
 China Animal Protein Market | 2026-2036
China Animal Protein Market Size, Share, and Industry Trends Forecast 2026-2036
China Animal Protein Market Outlook
The China animal protein sector is pivoting between premium branded cuts and undifferentiated commodity supply as urban consumers trade up while food manufacturers hunt for cost-optimized inputs. New Hope Liuhe leverages captive breeding and feed-milling capacity to control cost structures across pork and poultry. Haid Group anchors its position through aquaculture feed and protein systems integration. Bluestar Adisseo specializes in amino acid nutrition that differentiates protein yield economics for industrial buyers.
China animal protein encompasses muscle tissue, collagen fractions, and derived isolates from livestock and aquaculture species, processed through chilling, freezing, or enzymatic extraction to meet minimum protein content thresholds for human consumption and industrial formulation. Pork occupies the dominant volume position within product type segmentation, sustained by cultural consumption patterns and integrated hog farming infrastructure. Poultry registers the fastest structural expansion among protein categories, driven by shorter production cycles and lower feed conversion ratios that attract capital allocation. E-commerce channels within distribution channel segmentation are capturing disproportionate margin pools as direct-to-consumer cold-chain logistics mature beyond tier-one cities.
China's Ministry of Agriculture and Rural Affairs enforces livestock traceability protocols under national GB standards, while the Ministry of Ecology and Environment monitors manure treatment and methane discharge under dual carbon compliance timelines. SAMR oversees labeling integrity and food safety certification, tightening market access for unregistered processors. Stakeholders must monitor how provincial carbon intensity quotas reshape slaughterhouse location decisions and feed sourcing radii.
Market Dynamics
China's animal protein sector faces a structural squeeze between GB standards compliance costs and the dual carbon timeline, forcing processors to relocate slaughter capacity toward provinces with lower carbon intensity quotas while maintaining cold-chain access to Yangtze River Delta demand clusters.
Growth Catalysts
- Dual carbon policy enforcement:The Ministry of Ecology and Environment's methane discharge monitoring is accelerating manure-to-biogas infrastructure investment, converting compliance cost into energy revenue for integrated hog farms.
- Food service cold-chain expansion:Tier-one city operators are sourcing chilled premium cuts through direct supplier relationships, bypassing traditional wholesale layers and capturing margin previously lost to intermediaries.
- Poultry feed conversion economics:Shorter production cycles and lower feed conversion ratios relative to pork are redirecting capital toward broiler capacity in Shandong and Henan provinces.
Market Restraints
- Feed grain import dependency:Soybean and corn price volatility tied to Brazilian and US harvest conditions transmits directly to producer margins, with limited domestic substitution capacity.
- Slaughterhouse concentration in coastal provinces:Carbon intensity quotas are restricting new permits in Jiangsu and Zhejiang, forcing longer transport distances from interior breeding regions.
- African swine fever biocontainment:Persistent disease pressure requires permanent elevated biosecurity capex, structurally disadvantaging smallholder producers against integrated operations.
Strategic Opportunities
- Central province processing nodes:Hubei and Sichuan offer underdeveloped slaughter capacity with favorable carbon quotas and rail connectivity to coastal markets.
- E-commerce direct-to-consumer channels:Platform logistics now reach tier-two cities with 24-hour chilled delivery, opening premium branded cut access beyond Shanghai-Beijing-Guangzhou.
- Collagen isolate industrial applications:Enzymatic extraction technology is enabling pharmaceutical and cosmetic grade protein fractions, diversifying revenue beyond commodity muscle cuts.
Industry Challenges
- Veterinary epidemiology specialist scarcity:Regional disease surveillance and biocontainment protocol design require trained personnel that provincial agricultural colleges are not producing at sufficient scale.
- Legacy system integration with traceability mandates:Small and mid-scale processors face software and hardware retrofit costs to meet SAMR's real-time livestock tracking requirements.
- Cross-provincial permit harmonization:GB standard interpretation varies between provincial agriculture departments, creating compliance complexity for multi-site operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Animal Protein Market |
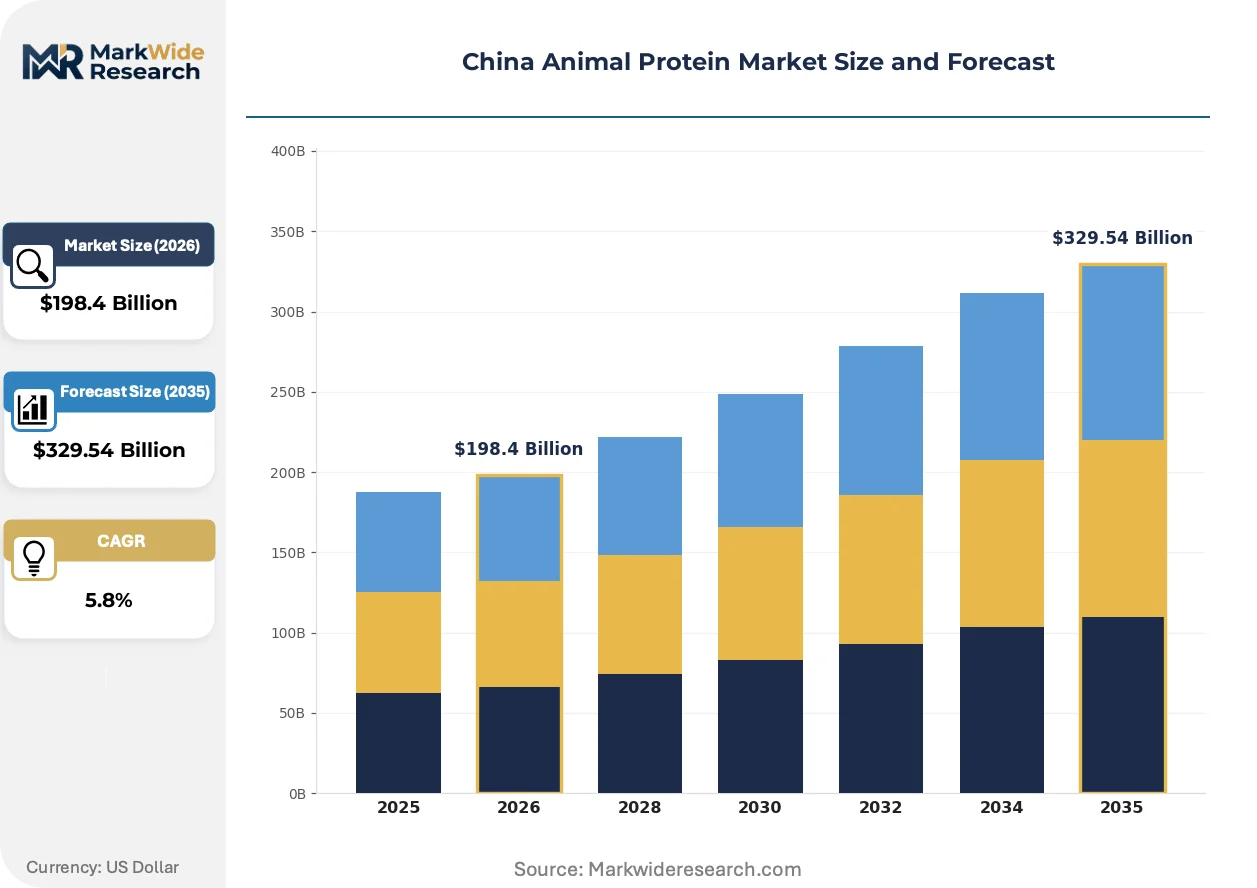
| Market Size in 2026 | $198.4 Billion |
| Market Size in 2035 | $329.54 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pork, Poultry, Beef, Seafood End User: Retail, Food Service, Industrial, Export Distribution Channel: Direct Sales, Wholesalers, E-commerce, Supermarkets Packaging Type: Bulk, Vacuum Sealed, Canned, Tray Packs |
| Companies Covered | Bluestar Adisseo, Glanbia PLC, Mengniu Dairy, Cargill, Arla Foods, Yili Group, Fonterra Co-operative Group, Haid Group, New Hope Liuhe, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Animal Protein Market Strategic Shifts
Automation and data integration are compressing production timelines while regulatory pressure is reshaping facility location economics across China's animal protein value chain.
Precision livestock monitoring systems incorporating computer vision and environmental sensors are consolidating control over mortality rates and feed conversion efficiency. Integrated pork and poultry operators in Hebei and Guangdong are deploying these systems at scale, replacing manual barn inspections with real-time alerts. The technology is consolidating competitive advantage toward capital-rich players capable of full-facility sensor deployment and data analytics staffing.
China's GB standards for livestock traceability now mandate individual animal identification and movement documentation from birth through slaughter. SAMR enforcement of these protocols is disqualifying unregistered processors from retail and food service channels. Small and mid-scale slaughterhouses in Shandong and Henan are responding by consolidating into larger certified facilities or exiting the market entirely.
Direct procurement relationships between protein processors and institutional food service operators are displacing traditional wholesale market transactions. Hotel and restaurant chains in the Yangtze River Delta are negotiating volume contracts with named suppliers, specifying breed, feed regimen, and cold-chain documentation. This pattern is most visible in Shanghai, where premium branded pork commands price premiums based on traceability certification and origin documentation.
China Animal Protein Market Segmentation
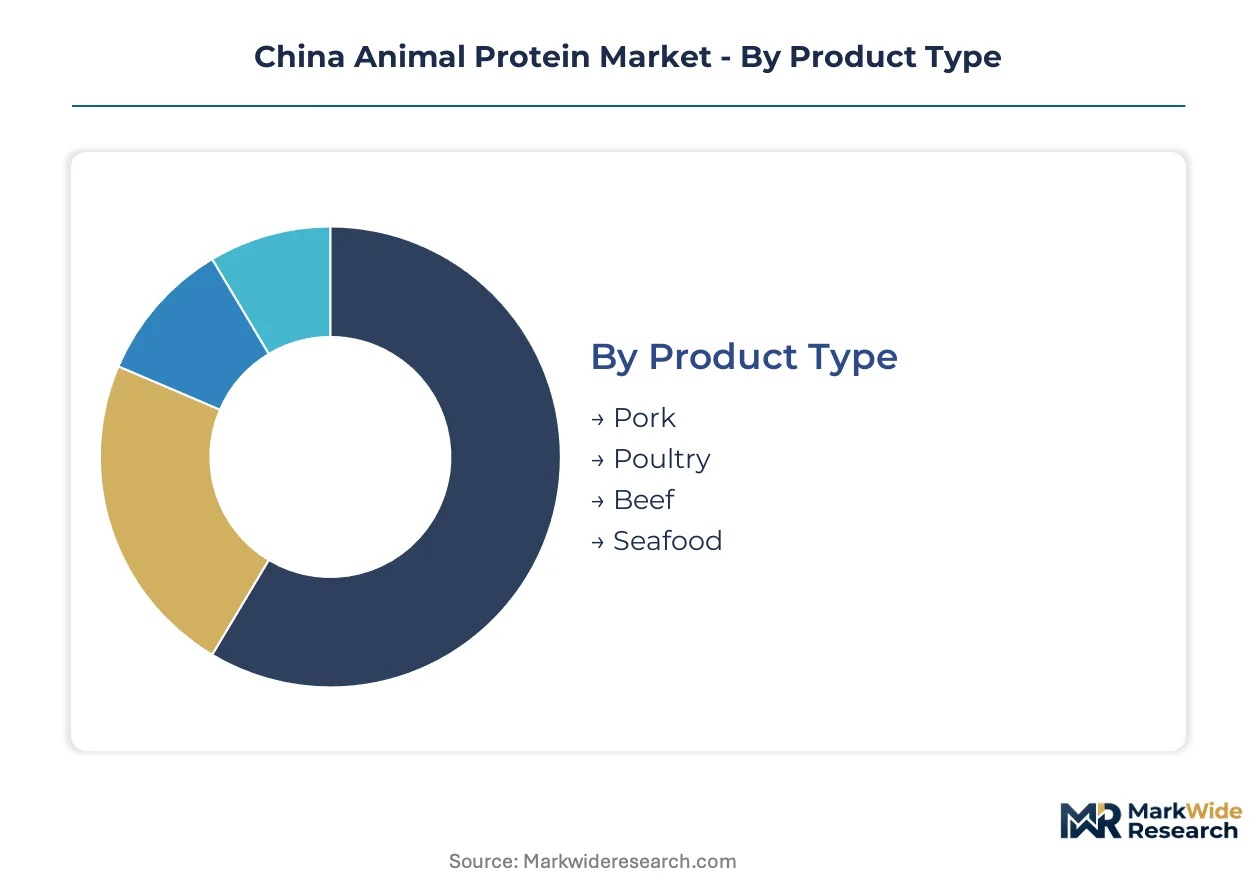
Segmentation in China's animal protein sector reveals how regulatory pressure and consumption upgrading split demand between commodity volume plays and premium traceable supply. Processors must align product specifications with channel-specific cold-chain capabilities and carbon compliance requirements.
Product Type:
Standalone protein categories dominate consumer-facing channels, while processed blends and isolates embed into industrial formulations and prepared foods.
- Pork:Muscle cuts and derived fractions from hog slaughter constitute the volume backbone, with chilled carcass delivery to Yangtze River Delta processors commanding premium positioning against frozen commodity supply. Cultural consumption patterns and integrated breeding infrastructure in Sichuan and Henan sustain this dominance despite carbon quota pressures on coastal slaughter capacity.
- Poultry:Broiler muscle tissue and mechanically separated meat offer shorter production cycles and superior feed conversion ratios that attract capital allocation toward Shandong and Henan expansion. SAMR traceability mandates favor integrated operators with captive hatchery-to-processing control over fragmented smallholder supply.
- Beef:Grass-fed and grain-finished cattle muscle from domestic herds and imported live animals serves hotpot and premium retail channels.
- Seafood:Finfish and shellfish protein from aquaculture and marine capture feeds both direct consumption and surimi processing.
Pork leads volumes today; poultry is gaining share fastest.
End User:
Customer type determines margin capture, with direct relationships to institutional buyers displacing wholesale intermediation.
- Retail:Branded packaged cuts through supermarket and e-commerce channels require individual animal traceability documentation and cold-chain integrity certification that SAMR enforces at point of sale.
- Food Service:Hotel and restaurant chains in Shanghai, Jiangsu, and Zhejiang negotiate direct volume contracts specifying breed, feed regimen, and carbon intensity documentation, bypassing traditional wholesale layers.
- Industrial:Protein isolates, hydrolysates, and collagen fractions supply food manufacturers and pharmaceutical formulators with enzymatic extraction specifications.
- Export:Quota-controlled shipments to Hong Kong, Macau, and select overseas markets face destination-country veterinary certification requirements.
Food service captures the steepest margin expansion; industrial applications show the fastest volume climb.
Distribution Channel:
Channel selection dictates cold-chain investment intensity and traceability system integration requirements.
- Direct Sales:Processor-to-institution relationships in tier-one cities specify 24-hour chilled delivery windows and real-time temperature logging that MEE carbon audits now review.
- Wholesalers:Traditional wet market intermediaries face SAMR registration pressure and are consolidating toward larger certified facilities in interior provinces.
- E-commerce:Platform logistics networks now reach tier-two cities with same-day chilled delivery, opening premium branded access beyond Beijing-Shanghai-Guangzhou.
- Supermarkets:Hypermarket and convenience store chains require batch-level traceability and packaging standardization that disadvantages unregistered processors.
Wholesalers still move the most tonnage; e-commerce posts the quickest expansion trajectory.
Packaging Type:
Packaging specification aligns with shelf-life requirements and channel cold-chain maturity.
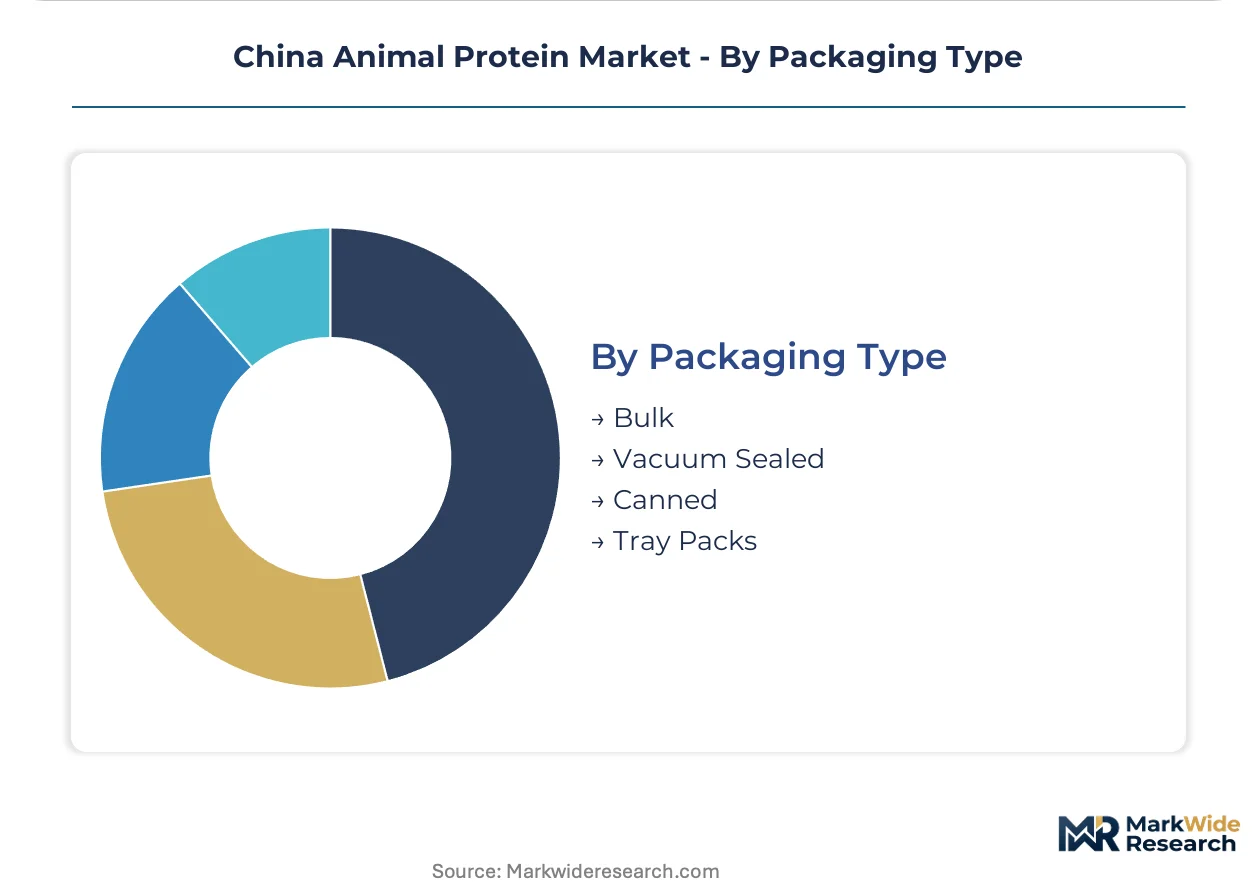
- Bulk:Carcass and primal cuts in unwrapped or minimally covered form supply food service central kitchens and industrial processors with immediate throughput needs.
- Vacuum Sealed:Modified atmosphere packaging extends retail shelf life and supports e-commerce delivery windows requiring 48-hour temperature maintenance.
- Canned:Retort-processed protein products serve emergency stockpiling, military supply, and rural distribution with ambient stability.
- Tray Packs:Overwrapped foam or fiber trays with absorbent pads dominate supermarket fresh meat counters with visibility-driven merchandising.
Bulk packaging handles the greatest volume; vacuum sealed formats are expanding most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Feed mill technicians and veterinary epidemiologists cluster along China's eastern seaboard and interior breeding corridors, anchoring regional capacity for integrated protein production.
Yangtze River Delta
Shanghai, Jiangsu, and Zhejiang provinces concentrate chilled premium cut demand from hotel and restaurant chains. SAMR traceability enforcement disqualifies unregistered processors from retail channels. Nanjing and Hangzhou host expanding cold-chain logistics hubs connecting interior breeding zones to coastal food service buyers.
Pearl River Delta
Guangdong province's hotpot and Cantonese cuisine traditions sustain robust beef and poultry consumption. MEE carbon intensity quotas restrict new slaughter permits in dense urban cores. Foshan and Dongguan processors are consolidating into larger certified facilities to meet dual carbon compliance timelines.
Sichuan-Chongqing
Integrated hog farming infrastructure in Sichuan province supplies pork muscle cuts to eastern markets. GB standards for livestock traceability mandate individual animal identification from birth through slaughter. Chengdu and Chongqing breeding operations are deploying precision monitoring systems to control mortality rates.
Shandong Peninsula
Shorter broiler production cycles attract capital allocation toward poultry capacity expansion. Feed grain import dependency transmits Brazilian and US harvest volatility directly to producer margins. Qingdao and Yantai processors leverage superior feed conversion economics to displace pork in institutional food service contracts.
Central China Corridor
Hubei and Henan provinces offer underdeveloped slaughter capacity with favorable carbon quotas and rail connectivity. African swine fever biocontainment requirements structurally disadvantage smallholder producers against integrated operations. Zhengzhou and Wuhan are emerging as processing nodes balancing compliance costs with market access.
China Animal Protein Market Competitive Environment
Capital-heavy producers compete with asset-light nutrition specialists across China's animal protein sector. The market structure tiers between integrated breeding-to-processing conglomerates and focused feed additive suppliers. Three archetypes dominate: captive breeding operators controlling cost structures, aquaculture feed integrators anchoring protein systems, and amino acid nutrition specialists differentiating industrial yield economics. Competitive moves center on backward integration into feed milling and strategic consolidation of slaughter capacity to meet SAMR traceability mandates.
Among integrated protein conglomerates, New Hope Liuhe and Haid Group exemplify the capital-intensive archetype with captive breeding and feed-milling control. Bluestar Adisseo occupies a position within the nutrition specialization tier, representing asset-light differentiation through amino acid technology. These three entities anchor the competitive map between volume-driven integration and premium-margin nutrition inputs.
| Leading Market Players |
|---|
| Bluestar Adisseo |
| Glanbia PLC |
| Mengniu Dairy |
| Cargill |
| Arla Foods |
| Yili Group |
| Fonterra Co-operative Group |
| Haid Group |
| New Hope Liuhe |
| Others |
Value Chain & Pricing Dynamics
Chicago Board of Trade corn and soybean futures transmit volatility directly through China's animal protein value chain, compressing margins at integrated hog farms while amplifying price spreads between commodity frozen cuts and chilled premium supply with full GB traceability documentation.
Pricing Analysis
Unbundled feed costs and bundled cold-chain logistics services split pricing structures across China's animal protein sector. Three-tier pricing structure across premium, standard, and economy levels separates SAMR-certified chilled cuts with individual animal traceability from frozen commodity supply and wet market unpackaged product. Price differentiation hinges on carbon intensity documentation and 24-hour delivery guarantees to Yangtze River Delta food service buyers. Cost compression in economy tiers is intensifying because Brazilian soybean harvest volatility feeds directly into domestic feed milling economics. Smallholder producers exhibit highest price sensitivity due to limited working capital buffers against input cost spikes.
Supply Chain Analysis
Single-source vulnerability sits with Brazilian and US feed grain exports that anchor China's soybean and corn procurement. Geographic supply concentration clusters in Brazil, the United States, and Argentina for oilseed inputs, while domestic breeding capacity concentrates in Sichuan, Henan, and Shandong provinces. Raw material dependencies rest on imported soybeans, domestic corn harvests, and amino acid premix formulations from Bluestar Adisseo. Supply chain risk centers on tariff exposure and ocean freight rate volatility for trans-Pacific grain shipments. Distribution runs through processor-direct relationships with tier-one city food service operators, bypassing traditional wholesale layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's animal protein sector functions as a regulatory compounder where SAMR traceability mandates and MEE dual carbon timelines continuously elevate compliance barriers that integrated operators convert into pricing power.
For Market Incumbents: To counter feed grain import dependency, New Hope Liuhe and Haid Group should deepen backward integration into domestic corn procurement networks in Northeast China while deploying precision livestock monitoring systems to compress feed conversion ratios. Captive breeding capacity expansion in Hubei and Sichuan provinces with favorable carbon quotas offers geographic diversification against coastal permit restrictions. SAMR certification investment for real-time traceability systems secures retail channel access disqualifying unregistered competitors. For New Entrants and Emerging Players: Underserved institutional buyers in tier-two cities with maturing e-commerce cold-chain infrastructure represent the most penetrable demand segment. Collagen isolate extraction for pharmaceutical and cosmetic applications offers white-space positioning beyond commodity muscle cuts with superior margin capture. Go-to-market execution should anchor on direct platform partnerships with JD Fresh and Missfresh for 24-hour chilled delivery capability. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale processors in Central China Corridor provinces possessing SAMR registration and rail connectivity to coastal markets but lacking capital for precision monitoring deployment. Long-term viability favors acquisition targets with integrated hatchery-to-processing control and manure-to-biogas infrastructure converting MEE compliance into energy revenue. The signal to watch is provincial carbon intensity quota tightening that accelerates slaughterhouse consolidation toward certified facilities.| Strategic Initiative | Industry Significance |
|---|---|
| Manure-to-Biogas Infrastructure Buildout | Converts MEE methane discharge compliance into captive energy revenue at integrated hog farms. |
| Precision Livestock Monitoring Deployment | Computer vision and sensor networks consolidate mortality control toward capital-rich operators in Hebei and Guangdong. |
| Central Province Processing Node Development | Hubei and Sichuan slaughter capacity expansion balances carbon quota advantages with Yangtze River Delta rail access. |
| E-Commerce Direct Channel Partnership | Platform logistics integration opens tier-two city premium cut access beyond traditional wholesale intermediation. |
| Collagen Isolate Extraction Capability | Enzymatic processing technology diversifies revenue streams beyond commodity muscle into pharmaceutical-grade fractions. |
Study Parameters
Direct dialogue with feed mill operations managers, SAMR regulatory affairs specialists, food service procurement directors at Yangtze River Delta hotel chains, and cold-chain logistics engineers grounded qualitative findings in operational reality. Secondary validation drew from Ministry of Agriculture and Rural Affairs livestock statistics, MEE environmental compliance disclosures, SAMR food safety bulletins, and China Customs feed grain import records. Bottom-up capacity modeling triangulated against top-down consumption surveys across the analysis window.
Segmented outputs by protein type, end-user channel, distribution format, and regional carbon quota cluster emerged from the quantitative framework. CAGRs were derived through regression analysis of historical production volumes against regulatory milestone implementation timelines and feed conversion efficiency improvement curves. Modeled inputs incorporated African swine fever biocontainment capex requirements and e-commerce cold-chain penetration rates by city tier throughout the forecast period.
Underlying measurement precision varies by segment; pork and poultry volume estimates carry tighter precision than emerging collagen isolate industrial applications due to longer commercialization histories. Forecasts reflect assumptions around SAMR enforcement consistency and dual carbon timeline adherence that provincial implementation variability could revise. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
North America Compound Feed Market
Agriculture and Agri Products
United Kingdom Animal Protein Market
Agriculture and Agri Products
Inulin Market
Agriculture and Agri Products
Honeysuckle Market
Agriculture and Agri Products
Organic Hemp Market
Agriculture and Agri Products
North America Eggs Market
Agriculture and Agri Products
Netherlands Cashew Market
Agriculture and Agri Products
Australia Floriculture Market
Agriculture and Agri Products
Apiculture Market
Agriculture and Agri Products
Europe Guar Market
Agriculture and Agri Products
Feed Protein Market
Agriculture and Agri Products
Saudi Arabia Poultry Meat Market
Agriculture and Agri Products
Colombia Agriculture Market
Agriculture and Agri Products
North America Aloe Vera Market
Agriculture and Agri Products
Organic Soybean Market
Agriculture and Agri Products
Elaeis Guineensis (Palm) Fruit Extract Market