
 Asia-Pacific Artificial Humus Market | 2026-2036
Asia-Pacific Artificial Humus Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Artificial Humus Market Insights
Subscription-based soil health monitoring is shifting how artificial humus vendors monetize relationships beyond one-time product sales. Humintech leverages digital agronomy platforms to sustain recurring revenue from Southeast Asian plantation operators. Novihum Technologies GmbH anchors its position through German-engineered production standards adapted for tropical soil conditions. Nutri-Tech Solutions Pty Ltd dominates Australian distribution through direct technical advisory channels that lock in long-term grower contracts.
Artificial humus denotes manufactured organic matter engineered from composted biomass, peat substitutes, or lignin-rich residues, typically containing 35-65% stable carbon compounds and mineral fractions designed to replicate natural topsoil structure. Its primary commercial purpose centers on restoring depleted soil organic carbon in intensive cropping systems while improving cation exchange capacity and water retention metrics. Granulated formulations command premium positioning in mechanized broadacre agriculture across Australia's wheat belt, whereas liquid variants capture expanding share in precision fertigation networks serving Vietnamese dragon fruit and Thai durian exporters. Powdered grades retain cost-driven volume in Indian government watershed programs where bulk procurement favors lower unit economics over handling convenience.
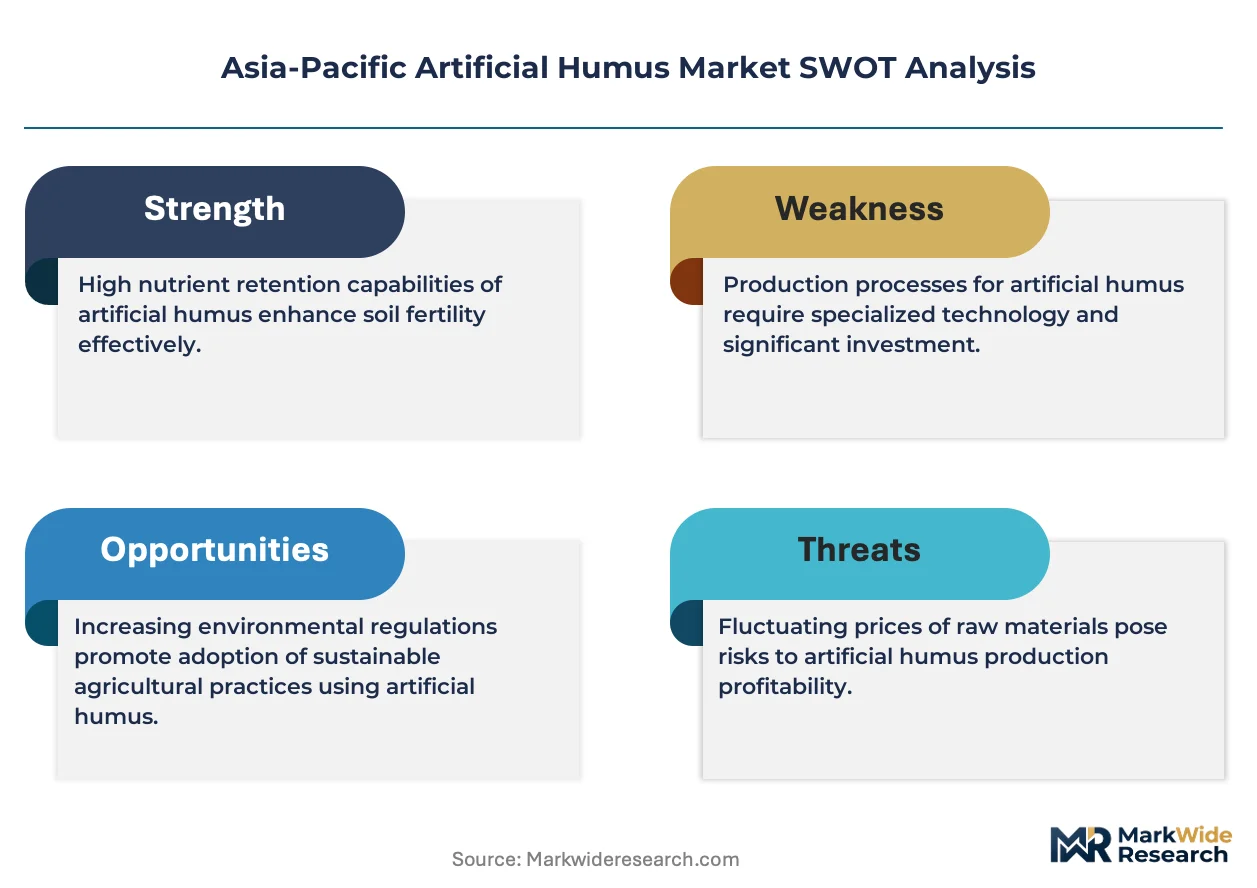
China's SAMR enforces GB standards for agricultural input labeling and heavy metal thresholds, while India's FSSAI and BIS jointly regulate organic substrate safety for food-crop applications. Japan's METI coordinates JIS certification pathways that constrain market entry for uncertified imported humus blends. Australia's TGA-equivalent agricultural chemical regulator maintains parallel bio-stimulant registration requirements that fragment compliance burdens. Stakeholders must monitor divergent national substance lists and carbon accounting methodologies as regional trade integration advances.
Market Dynamics
China's tightening GB standards for agricultural inputs are compressing import windows and forcing domestic manufacturers to accelerate carbon stability testing protocols. Vietnam and Indonesia are expanding organic farming cooperatives that now specify humus with verifiable mineral content thresholds.
Growth Catalysts
- Soil carbon mandates:China's dual carbon goals pressure provincial agriculture departments to restore depleted farmland organic matter. Provincial procurement programs in Hebei and Shandong specify artificial humus with certified carbon sequestration metrics.
- Horticulture intensification:India's Maharashtra and Punjab states drive bulk purchasing as commercial fruit and vegetable operations replace traditional manure with standardized soil amendments. State agricultural universities validate product efficacy for export-oriented grape and pomegranate growers.
- Precision fertigation expansion:Vietnamese dragon fruit and Thai durian exporters deploy liquid humus variants through automated irrigation networks. Plantation operators in the Mekong Delta measure return on soil health investments through yield-per-hectare tracking systems.
Market Restraints
- Lignin feedstock volatility:Paper mill residue supply fluctuates with packaging demand cycles. Manufacturers in Guangdong and Jiangsu face input cost swings that compress margin predictability.
- Import certification friction:Japan's METI-coordinated JIS pathways create six-to-nine month approval timelines for uncertified humus blends. European and Australian suppliers encounter repeated testing cycles for heavy metal thresholds.
- Peat substitute performance gaps:Natural peat retains superior water retention in controlled greenhouse trials. Dutch and Baltic suppliers leverage this technical advantage in premium horticulture segments across Australia and Japan.
Strategic Opportunities
- Subscription soil health monitoring:Digital agronomy platforms enable recurring revenue models beyond one-time product sales. Southeast Asian plantation operators pay annual fees for carbon tracking and amendment recommendations.
- Philippine coconut plantation rehabilitation:Typhoon-damaged soil in Davao and Quezon provinces requires systematic organic matter restoration. Government extension services lack capacity to supply adequate natural compost volumes.
- Australian bio-stimulant registration pathways:TGA-equivalent agricultural chemical regulations create first-mover advantages for compliant humus blends. Registered products access restricted distribution channels serving broadacre wheat and canola growers.
Industry Challenges
- Carbon accounting methodology divergence:China's MEE tracks soil carbon differently than Australia's Clean Energy Regulator. Multi-jurisdiction suppliers maintain parallel documentation systems that inflate compliance overhead.
- Technical advisory talent scarcity:Field agronomists capable of interpreting soil tests and prescribing amendment protocols command premium compensation. Plantation operators in Indonesia and Vietnam struggle to retain trained staff.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Artificial Humus Market |
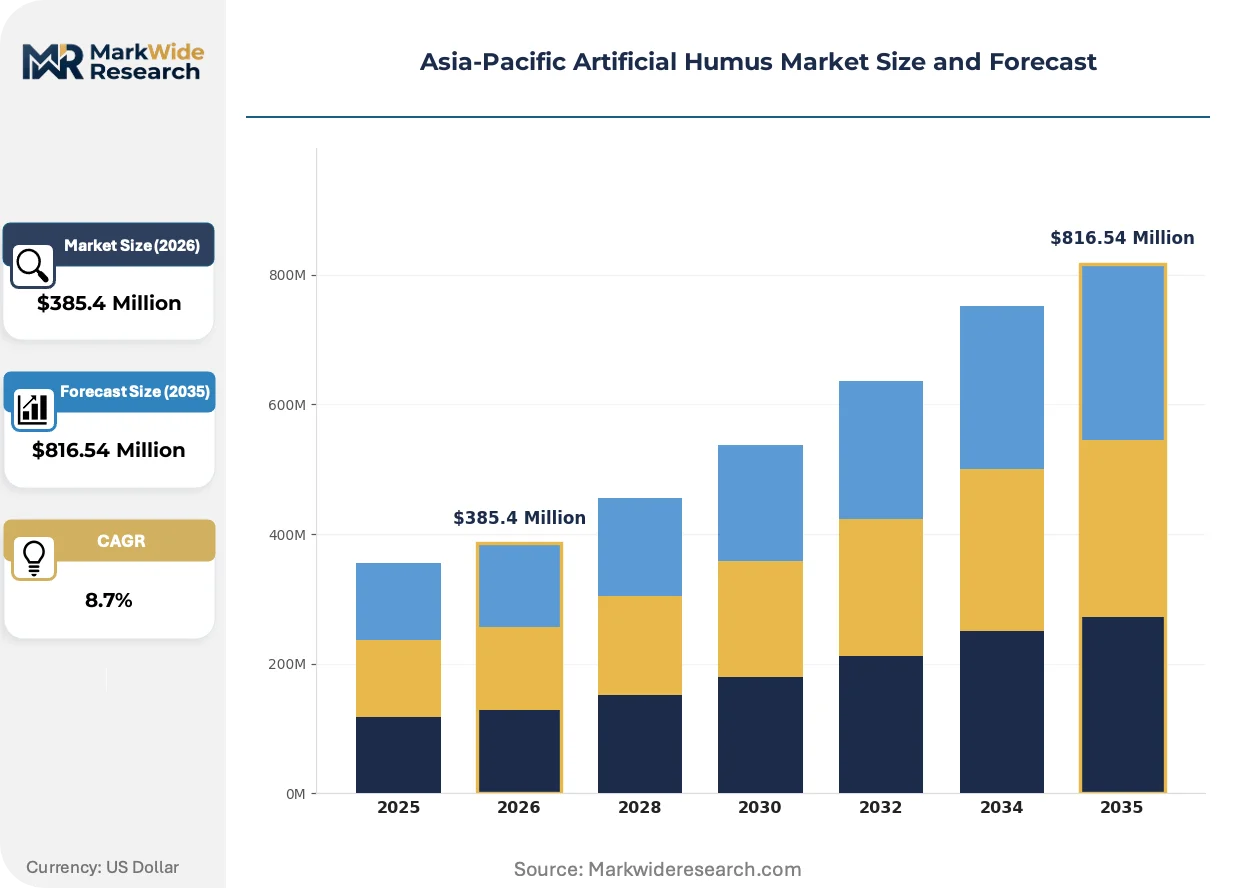
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $816.54 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granulated, Powdered, Liquid, Compressed Application: Agricultural Use, Horticulture, Environmental Restoration, Landscaping Customer Type: Farmers, Nurseries, Construction Firms, Government Agencies Distribution Channel: Online Retail, Direct Sales, Wholesale, Distributors |
| Companies Covered | Agbest Technology Co.,Ltd., Humintech, Novihum Technologies GmbH, Humusolver, The Fertrell Company, Ohio Earth Food, Nutri-Tech Solutions Pty Ltd, Organic Approach, LLC, Nature's Force Organics, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Artificial Humus Market Trends and Innovations
Manufacturing processes are converging with digital soil analytics to create feedback loops between production batches and field performance data. This integration is compressing product development cycles and reshaping how vendors demonstrate value to commercial growers.
Granulated formulations engineered for mechanized broadacre application are overtaking powdered grades in Australia's wheat belt. Broadacre operators in Western Australia and New South Wales prioritize handling efficiency and dust reduction during pneumatic spreading. This shift is compressing demand for lower-grade bulk products that dominated government watershed programs.
Japan's METI has tightened JIS certification pathways for imported organic substrates, extending testing protocols for heavy metal bioavailability. Manufacturers now pre-screen lignin sources through third-party laboratories before submitting formal applications. Australian and European suppliers face extended market entry timelines that favor domestic Japanese producers with established testing relationships.
Commercial buyers in Vietnam and Thailand now bundle soil amendment procurement with technical advisory contracts. Dragon fruit cooperatives in Long An province pay integrated fees covering product supply, application timing recommendations, and yield monitoring. This unbundles traditional distributor margins and concentrates purchasing authority with plantation management companies rather than input retailers.
Asia-Pacific Artificial Humus Market Segmentation
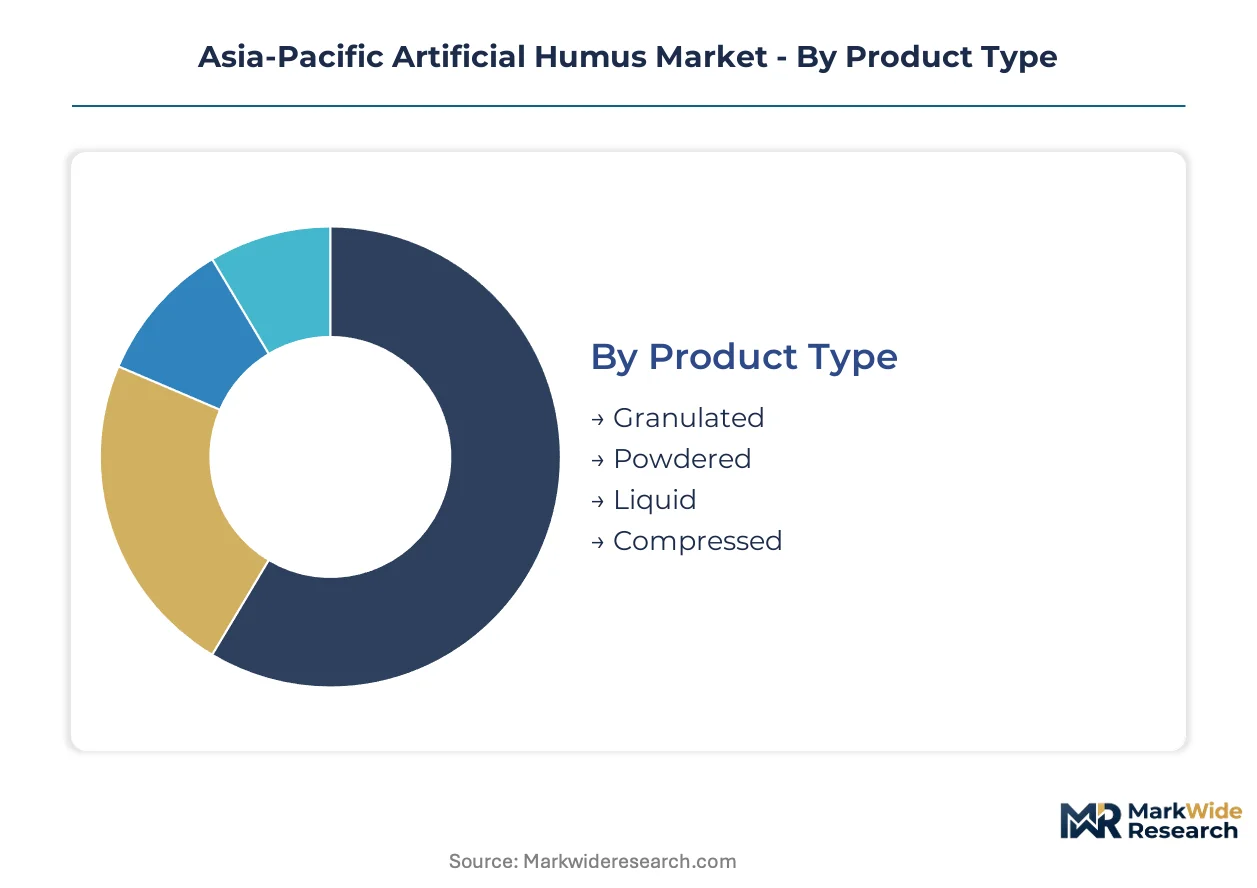
Artificial humus vendors configure product portfolios around handling logistics and application infrastructure. Segment boundaries reflect whether buyers operate mechanized spreading equipment, precision fertigation networks, or manual application systems.
Product Type:
Granulated and liquid formulations integrate directly into automated agricultural systems, while powdered and compressed grades serve standalone manual application contexts.
- Granulated:Spherical pellets engineered for pneumatic spreaders contain 40-55% stable carbon with controlled dissolution rates. Australian wheat belt operators in Western Australia and New South Wales specify this grade for dust-free handling during broadacre planting windows.
- Liquid:Suspension concentrates with 15-25% organic solids deploy through drip and micro-spray irrigation. Vietnamese dragon fruit cooperatives in Long An province and Thai durian exporters in Chanthaburi integrate liquid variants into fertigation schedules for root-zone precision.
- Powdered:Fine-ground lignin-rich material with 50-65% carbon content serves Indian government watershed programs in Maharashtra and Karnataka where bulk procurement prioritizes unit economics over handling convenience.
- Compressed:Dense blocks for slow-release soil amendment require manual incorporation. Landscaping contractors in Japanese urban greening projects and Philippine coconut plantation rehabilitation in Davao province utilize compressed forms for targeted spot application.
Volume placements concentrate in powdered grades for public procurement programs; the faster expansion belongs to liquid formulations serving precision agriculture networks.
Application:
End-use segments diverge by carbon restoration urgency and crop value intensity, with horticulture commanding premium positioning against environmental restoration's cost-constrained procurement.
- Horticulture:High-value fruit and vegetable operations in India's Maharashtra grape belt and Punjab pomegranate districts demand certified carbon sequestration metrics. State agricultural universities validate product efficacy for export-oriented growers facing residue compliance.
- Agricultural Use:Broadacre grain and oilseed producers across Australia's wheat belt and China's Hebei province specify granulated humus for soil organic matter restoration under provincial carbon mandates.
- Environmental Restoration:Typhoon-damaged coconut plantations in Philippine Quezon province and degraded watersheds in Indonesian Java require systematic organic matter rebuilding. Government extension services contract bulk supply where natural compost volumes prove inadequate.
- Landscaping:Urban greening projects in Japanese metropolitan areas and Australian municipal parks utilize compressed and granulated forms for aesthetic turf establishment with minimal maintenance requirements.
Revenue intensity peaks in horticulture applications; agricultural use segments scale fastest as China's dual carbon goals expand provincial procurement specifications.
Customer Type:
Procurement authority concentrates with entities controlling land access and technical advisory capacity, fragmenting traditional distributor relationships.
- Farmers:Commercial grain and horticulture operators in Vietnam's Mekong Delta and India's Punjab state negotiate direct supply contracts with yield-per-hectare performance guarantees.
- Nurseries:Propagation facilities in Thailand's Chiang Mai province and Japan's Chiba prefecture specify JIS-certified substrates for seedling establishment in controlled greenhouse environments.
- Construction Firms:Site rehabilitation contractors in Australian mining regions and Chinese infrastructure projects procure bulk amendments for topsoil replacement compliance.
- Government Agencies:Provincial agriculture departments in China's Shandong and Hebei provinces administer carbon restoration tenders with certified sequestration documentation requirements.
Contract volumes concentrate with government agencies; farmer-direct procurement is climbing the fastest as plantation management companies internalize input purchasing authority.
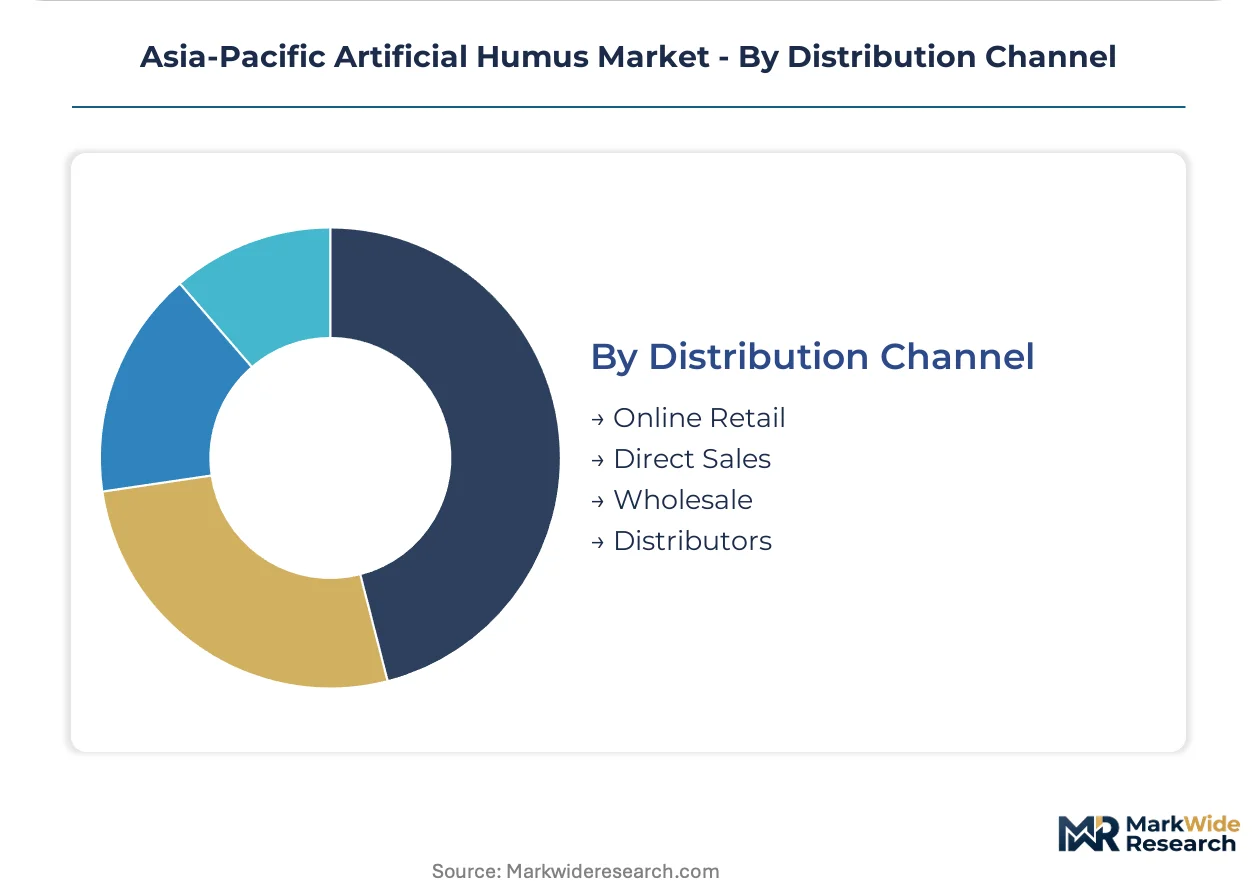
Distribution Channel:
Channel selection tracks buyer technical sophistication and shipment scale, with advisory bundling displacing transactional retail relationships.
- Direct Sales:Technical advisory contracts with Southeast Asian plantation operators bundle product supply, application timing protocols, and carbon tracking services. Humintech and Novihum Technologies anchor recurring revenue through direct agronomist relationships.
- Distributors:Regional agricultural input networks in Indonesia and Vietnam maintain inventory positions for smallholder farmers lacking technical staff. Distributor margins compress as plantation operators consolidate purchasing authority.
- Wholesale:Bulk procurement aggregators serve Indian government watershed programs and Chinese provincial carbon restoration tenders with standardized granulated and powdered grades.
- Online Retail:E-commerce platforms capture hobbyist and small nursery demand in Japanese urban centers and Australian metropolitan markets with certified organic substrate specifications.
Shipment volumes concentrate in wholesale channels for public procurement; direct sales channels gain share fastest through subscription-based soil health monitoring bundling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates manufacturing capacity for lignin-derived humus substrates while Australia and Southeast Asian markets absorb premium formulations. Production clusters in Guangdong and Jiangsu provinces feed provincial procurement programs and export channels simultaneously.
China
Hebei and Shandong provinces drive bulk procurement under dual carbon mandates that specify certified soil organic carbon restoration metrics. SAMR enforces GB standards for agricultural input labeling and heavy metal thresholds that compress import windows. Manufacturers in Guangdong province face input cost volatility from paper mill residue supply fluctuations tied to packaging demand cycles.
Australia
Broadacre wheat and canola growers across Western Australia and New South Wales specify granulated humus for dust-free pneumatic spreading during narrow planting windows. TGA-equivalent agricultural chemical regulations create registration barriers that favor compliant domestic and established international suppliers. Nutri-Tech Solutions anchors distribution through direct technical advisory channels that lock in long-term grower contracts with yield performance guarantees.
India
Maharashtra grape belt and Punjab pomegranate districts generate premium demand for certified carbon sequestration products validated by state agricultural universities. FSSAI and BIS jointly regulate organic substrate safety for food-crop applications with divergent documentation requirements. Karnataka government watershed programs procure powdered grades through bulk tenders that prioritize unit economics over handling convenience.
Vietnam
Dragon fruit cooperatives in Long An province deploy liquid humus variants through automated fertigation networks with integrated yield-per-hectare tracking. Organic farming cooperatives specify verifiable mineral content thresholds that displace generic manure alternatives. Mekong Delta plantation management companies consolidate purchasing authority and bundle technical advisory contracts with product supply agreements.
Japan
Metropolitan urban greening projects in Tokyo and Osaka utilize compressed and granulated forms for aesthetic turf establishment with minimal maintenance requirements. METI-coordinated JIS certification pathways extend testing protocols for heavy metal bioavailability to six-to-nine month timelines. Domestic producers with established laboratory relationships capture premium horticulture segments while European and Australian suppliers face repeated approval cycles.
Asia-Pacific Artificial Humus Market Competitive Landscape
Capital-heavy producers compete with asset-light formulation specialists across divergent technology pathways. The vendor base separates between integrated lignin processors with captive feedstock access and third-party blenders sourcing commoditized organic inputs. Three archetypes dominate: German-engineered precision manufacturers, Australian advisory-anchored distributors, and Asian plantation-integrated service providers. Competitive moves concentrate on direct agronomist relationships that displace traditional distributor margins and on pre-certification screening investments that compress regulatory approval timelines.
Within the precision-manufacturing tier, Novihum Technologies GmbH exemplifies German-engineered production standards adapted for tropical soil conditions. Humintech occupies a position representing digital agronomy platform integration that sustains recurring revenue from subscription-based soil health monitoring. Among advisory-anchored distributors, Nutri-Tech Solutions Pty Ltd sits within the technical relationship archetype that dominates Australian broadacre markets through direct grower contracts bundling product supply with application protocols.
| Leading Market Players |
|---|
| Agbest Technology Co.,Ltd. |
| Humintech |
| Novihum Technologies GmbH |
| Humusolver |
| The Fertrell Company |
| Ohio Earth Food |
| Nutri-Tech Solutions Pty Ltd |
| Organic Approach, LLC |
| Nature's Force Organics |
| Others |
Pricing and Supply Chain Analysis
China's dual carbon goals gate both qualified supply and premium-tier pricing access, as provincial procurement programs in Hebei and Shandong specify artificial humus with certified carbon sequestration metrics that only pre-qualified manufacturers can meet. This environmental mandate stratifies the market into certified premium suppliers commanding technical advisory bundling and uncertified commodity players competing on unit economics alone.
Pricing Analysis
Margin tightening in economy-tier powdered grades reflects paper mill residue supply fluctuations tied to packaging demand cycles in Guangdong and Jiangsu provinces. Three-tier pricing structure across premium, standard, and economy levels differentiates by certification grade and carbon stability testing depth. Cost-down pressure on liquid formulations accelerates because Vietnamese dragon fruit cooperatives negotiate integrated technical advisory contracts that unbundle traditional distributor markups. Government agencies in India and China exhibit lowest price sensitivity due to carbon mandate compliance requirements, while smallholder farmers in Indonesia remain most price-sensitive.
Supply Chain Analysis
Dual-sourcing requirements from Japanese METI and Australian TGA-equivalent regulators force buyers to qualify multiple lignin feedstock suppliers across China, Germany, and Australia simultaneously. Raw material dependencies center on paper mill lignin residues, composted biomass from agricultural waste streams, and peat substitute mineral fractions. Single-source vulnerability concentrates in Guangdong province manufacturers lacking diversified feedstock contracts. Distribution runs through technical advisory-anchored direct sales for plantation operators and wholesale aggregators for government watershed tenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where Japan's METI-coordinated JIS certification pathways create six-to-nine month approval timelines that function as a barrier-to-entry moat for pre-certified domestic and established international suppliers.
For Market Incumbents: Cement laboratory relationships with third-party testing facilities in Tokyo and Osaka to compress JIS approval cycles before European competitors establish equivalent partnerships. Deepen upstream control over lignin feedstock contracts in Jiangsu province to buffer against paper mill residue volatility that threatens margin predictability. For New Entrants and Emerging Players: Begin with Philippine coconut plantation rehabilitation in Davao and Quezon provinces, where typhoon-damaged soil lacks adequate natural compost supply from government extension services. Target environmental restoration applications with compressed humus blocks for spot application, leveraging lower certification friction than food-crop horticulture segments. For Investors and Strategic Acquirers: Subscription revenue inflection from Southeast Asian plantation operators is the leading indicator that digital agronomy platform integration creates sustainable recurring revenue models beyond transactional product sales. Prioritize asset-light formulation specialists with captive technical advisory talent over capital-heavy integrated processors. Watch for consolidation signals when field agronomist compensation premiums exceed fifteen percent annual escalation in Vietnam and Indonesia.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Certification Pre-Screening | Third-party laboratory partnerships compress JIS approval timelines from nine to four months for METI submissions. |
| Backward Integration into Lignin Supply | Captive paper mill residue contracts in Guangdong stabilize input costs against packaging demand cyclicality. |
| Technical Advisory Talent Acquisition | Field agronomist teams in Mekong Delta lock in plantation operator contracts with yield-per-hectare guarantees. |
| Digital Platform Integration | Subscription soil health monitoring sustains recurring revenue from Vietnamese dragon fruit cooperatives. |
| Provincial Procurement Pre-Qualification | Hebei and Shandong carbon restoration tenders require certified sequestration documentation that filters competitors. |
Research Methodology
Document review covered customs and trade data from China Customs and India's DGFT, complemented by interviews with plantation management executives in Vietnam's Mekong Delta, procurement officers at Maharashtra state agricultural universities, technical directors at Australian broadacre cooperatives, and regulatory affairs specialists navigating Japan's METI certification pathways. Secondary validation drew from SAMR GB standard filings, JIS certification registries, Australian TGA-equivalent agricultural chemical databases, and BIS organic substrate safety documentation. Bottom-up demand modeling from individual plantation operator procurement and top-down supply capacity analysis from lignin processor capacity announcements were triangulated.
Historical volume trajectories were cross-referenced against panel input from industry stakeholders to anchor growth assumptions across the projection horizon. Segmentation dimensions modeled include product formulation type, application intensity by crop value, customer procurement authority structure, and distribution channel technical sophistication. CAGRs were derived from slope analysis of certified carbon sequestration procurement volumes and provincial mandate implementation timelines. Forecast inputs incorporated lignin feedstock cost indices and plantation operator yield tracking system adoption rates.
Underlying measurement precision varies by segment; liquid formulation demand from precision fertigation networks carries tighter precision than powdered grade procurement from Indian government watershed programs where tender reporting lags operational deployment. Forecasts reflect assumptions around carbon accounting methodology convergence and plantation management company purchasing authority consolidation. Deviation in METI certification timeline extensions or sudden paper mill residue supply disruptions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Italy Animal Protein Market
Agriculture and Agri Products
Australia Compound Feed Market
Agriculture and Agri Products
Corn Co-Products Market
Agriculture and Agri Products
Global Warm Water Aquaculture Feed Market
Agriculture and Agri Products
GCC Poultry Meat Market
Agriculture and Agri Products
Spain Compound Feed Market
Agriculture and Agri Products
E-Commerce of Agricultural Products Market
Agriculture and Agri Products
Residential Organic Compost Market
Agriculture and Agri Products
United States Compound Feed Market
Agriculture and Agri Products
Thailand Compound Feed Market
Agriculture and Agri Products
Poultry and Eggs Market
Agriculture and Agri Products
Sugar Beet Market
Agriculture and Agri Products
Tunisia Agriculture Market
Agriculture and Agri Products
South America Feed Binders Market
Agriculture and Agri Products
Australia Animal Protein Market
Agriculture and Agri Products
India Compound Feed Market