
 Cattle Mineral Feeder Market | 2026-2036
Cattle Mineral Feeder Market Size, Share, and Industry Trends Forecast 2026-2036
Cattle Mineral Feeder Market Outlook
Polyethylene is pivoting into mineral feeder construction as ranchers reject rust-prone galvanized steel for UV-stabilized rotational-molded units that withstand freeze-thaw cycles without seam failure. Sioux Steel Company anchors its position through captive steel fabrication capacity serving the Corn Belt. Cargill Incorporated leverages its nutrition science division to bundle mineral formulations with proprietary feeder designs. Alltech, Inc. differentiates by embedding RFID-enabled intake monitors into tub feeder bases.
A cattle mineral feeder is a purpose-built dispensing vessel engineered to deliver free-choice trace minerals, macro-minerals, and vitamin premixes to grazing or confined cattle while excluding precipitation and limiting waste through restricted access geometry. Wall thickness typically ranges from 0.25 to 0.5 inches for rotational-molded polymer units, with load-bearing capacity calibrated to 1,200-pound bull pressure and 150-pound horn impact. Free choice feeders dominate volume sales due to their compatibility with loose mineral and weatherized block formulations. Tub feeders capture the fastest expansion as co-ops standardize on stackable, forklift-compatible designs for rotational grazing programs. Composite material feeders command premium positioning where fiberglass-reinforced polymer bridges the durability gap between commodity plastic and fabricated steel.
The USDA Animal and Plant Health Inspection Service enforces biosecurity protocols that influence feeder sanitation standards, while the EPA regulates zinc and copper runoff from mineral leaching into watersheds near concentrated animal feeding operations. State-level Department of Agriculture weights-and-measures offices inspect feeder calibration accuracy where minerals are sold by weight rather than by unit. Stakeholders must monitor evolving nutrient management plans that restrict mineral placement near riparian buffers.
Market Dynamics
Rotational molding of UV-stabilized polyethylene is displacing galvanized steel fabrication across the Great Plains feedlot corridor, compressing replacement cycles and altering regional supply chain economics for mineral feeder procurement.
Growth Catalysts
- USDA APHIS biosecurity protocols:Mandatory sanitation standards for confined cattle operations are accelerating feeder replacement schedules and favoring seamless polymer designs over welded steel seams that harbor pathogens.
- Precision nutrition adoption:Beef cattle operations in Nebraska and Kansas are deploying mineral intake monitoring systems that require feeder-integrated load cells and data ports, pulling hardware upgrades across the herd management sector.
- Freeze-thaw durability gap:Polyethylene's resistance to thermal cycling without seam failure is capturing share from steel in northern tier states where winter temperature swings exceed 80 degrees Fahrenheit annually.
Market Restraints
- Resin price volatility:Polyethylene feedstock costs tied to natural gas liquids pricing create margin compression for rotational molders serving price-sensitive ranch supply cooperatives.
- Fabrication concentration:Captive steel rolling capacity in the Corn Belt creates geographic supply asymmetry, limiting polymer feeder penetration where localized steel fabrication maintains cost advantages.
- Copper runoff restrictions:EPA watershed regulations near concentrated animal feeding operations are constraining mineral formulation flexibility, indirectly limiting feeder design freedom for high-leach formulations.
Strategic Opportunities
- RFID-enabled intake tracking:Convergence of livestock identification mandates with precision agriculture platforms is creating white space for feeder-embedded sensors that sync with herd management software.
- Rotational grazing standardization:Stackable tub designs compatible with forklift handling are penetrating cooperative procurement channels that service multi-pasture beef operations across the Mountain West.
- State nutrient management incentives:Department of Agriculture cost-share programs for riparian buffer compliance are subsidizing precision mineral placement hardware that reduces environmental leaching exposure.
Industry Challenges
- Load cell calibration expertise:Integration of weighing systems into polymer bases requires skill sets scarce among traditional livestock equipment distributors, forcing manufacturers to build direct service capabilities.
- Legacy steel replacement cycles:Extended durability of existing galvanized units in southern climates slows penetration velocity despite polymer advantages in freeze-thaw environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cattle Mineral Feeder Market |
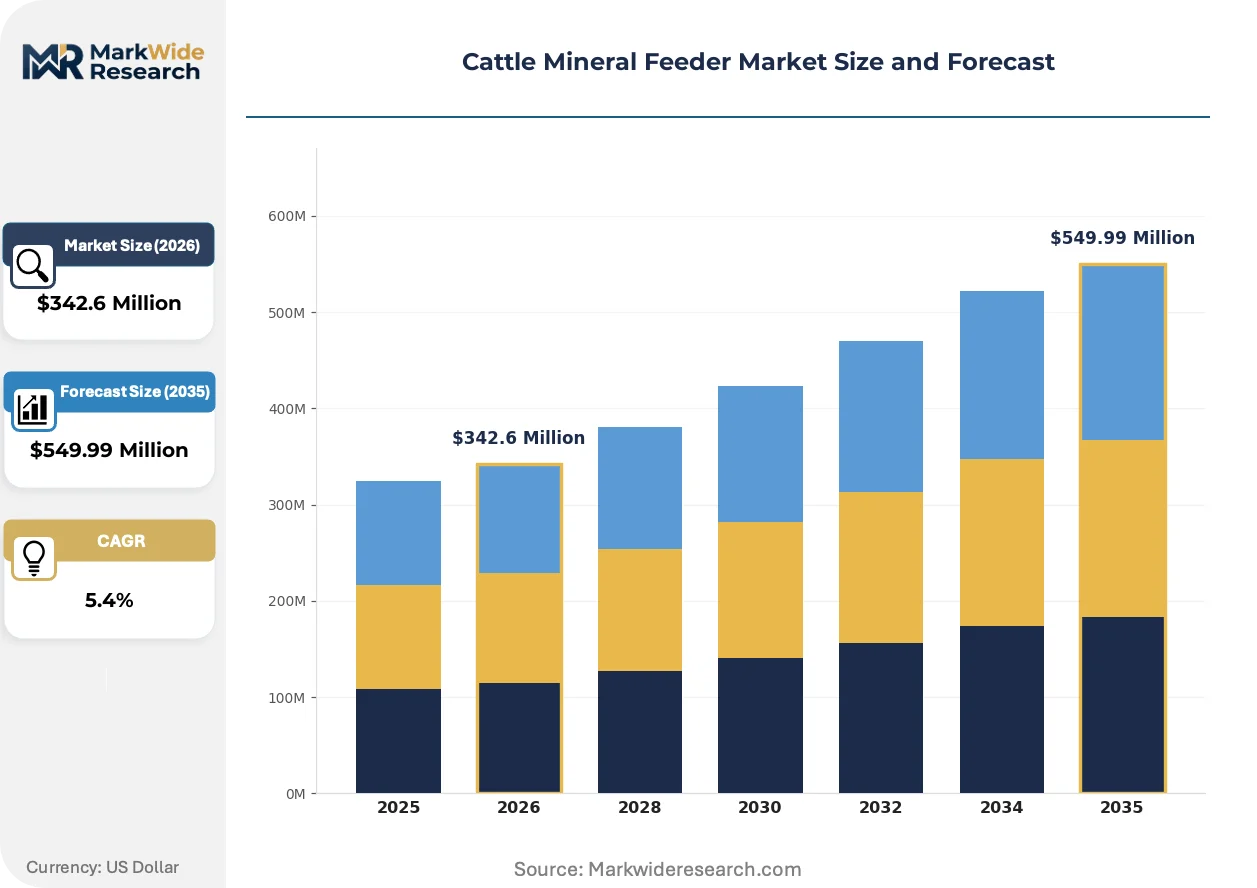
| Market Size in 2026 | $342.6 Million |
| Market Size in 2035 | $549.99 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Feeder, Block Feeder, Free Choice Feeder, Tub Feeder Material: Plastic, Metal, Wood, Composite End User: Dairy Farmers, Beef Farmers, Livestock Ranchers, Co-ops Distribution Channel: Online Retail, Agricultural Supply Stores, Wholesale Distributors, Direct Sales |
| Companies Covered | Land O'Lakes, Inc., AmeriAg, Sioux Steel Company, BASF SE, JFC Agri, Cargill Incorporated, Alltech, Inc., Archer Daniels Midland Company, Nutreco N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cattle Mineral Feeder Market Strategic Shifts
Feeder hardware is converging with livestock data infrastructure, transforming a passive dispensing vessel into an active node within precision herd management networks. Material science advances and regulatory pressure on environmental compliance are simultaneously reshaping design priorities.
Rotational-molded polyethylene is integrating impact-resistant rib geometries and UV stabilizer packages that extend service life beyond fifteen years in high-altitude solar exposure conditions. Large-scale feedlot operators in Texas and Oklahoma are specifying these units for replacement programs that prioritize reduced handling weight and elimination of corrosion-related downtime. The technology is integrating mineral delivery hardware with the broader shift toward automated cattle monitoring systems, compressing the addressable market for basic steel fabricators lacking polymer molding capacity.
EPA enforcement of zinc and copper runoff limits under the Clean Water Act is tightening mineral placement restrictions within riparian setbacks near concentrated animal feeding operations. Feedlot operators in the Platte River watershed are responding by relocating mineral stations to engineered pads with drainage containment, favoring portable tub designs over permanent steel installations. Cattle operations in Nebraska's Rainwater Basin are most affected, driving demand for repositionable feeders that accommodate seasonal wetland fluctuations without fixed concrete anchoring.
Cooperative procurement consolidation is compressing distributor margins and shifting specification authority from individual ranchers to centralized buying committees. Regional livestock supply cooperatives in the Dakotas are standardizing on stackable, forklift-compatible tub dimensions that optimize trailer cube utilization and reduce per-unit freight costs. This pattern is most visible across the Northern Plains where cooperative membership density exceeds sixty percent of commercial cow-calf operations, forcing independent equipment dealers to align with cooperative specification sheets or exit the feeder category entirely.
Cattle Mineral Feeder Market Segmentation
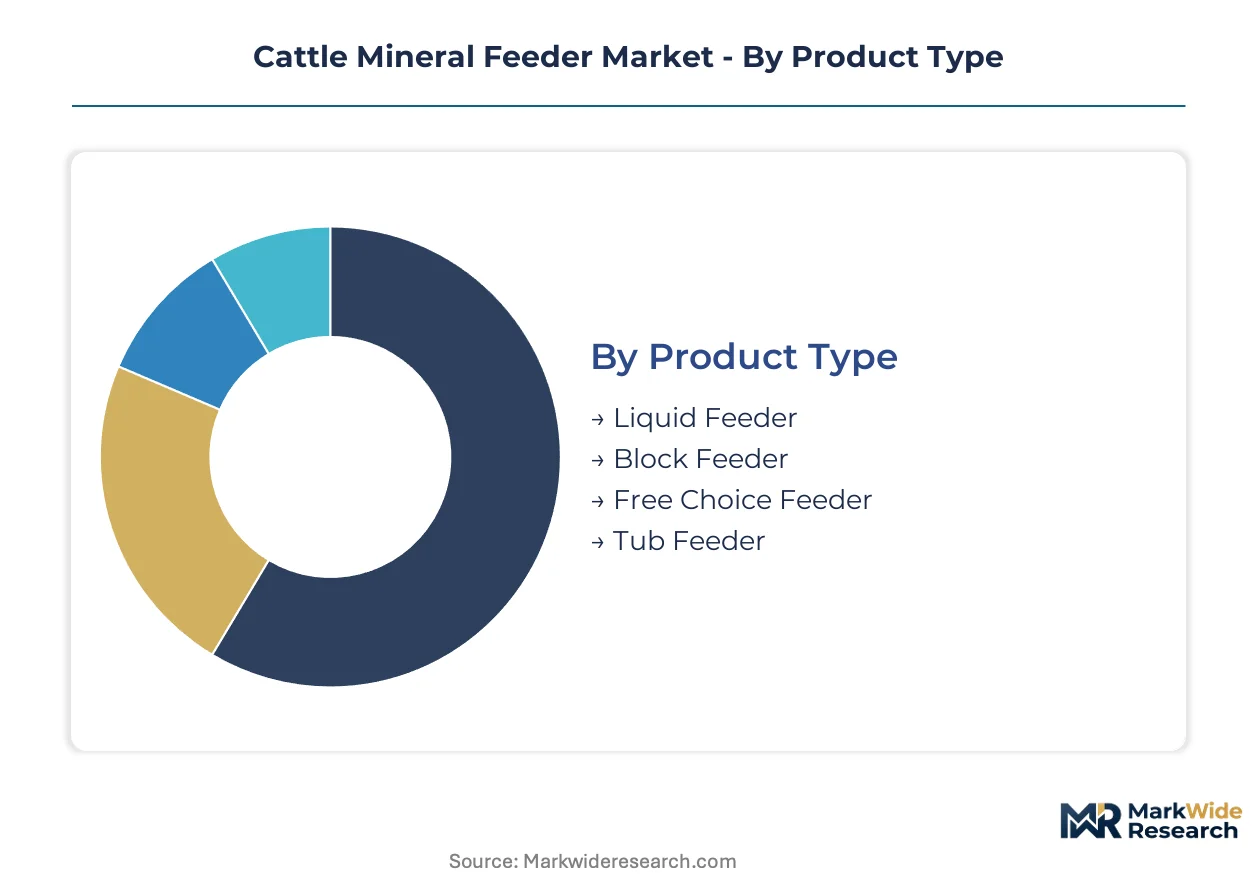
Cattle mineral feeder procurement splits across four distinct decision axes: product architecture, material durability, operational scale of the end user, and channel access. Each segmentation layer reveals divergent margin structures and replacement cycle dynamics that reshape vendor positioning.
Product Type:
Buyer selection hinges on mineral formulation compatibility and labor efficiency in high-headcount operations.
- Free Choice Feeder:Open-access vessels engineered for loose mineral and weatherized block dispensing dominate Great Plains feedlot procurement. Beef operations in Nebraska and Kansas specify these units for compatibility with precision intake monitoring systems that require unobstructed access geometry.
- Tub Feeder:Stackable rotational-molded designs with forklift pockets are climbing the fastest as Mountain West cooperatives standardize dimensions for rotational grazing logistics. Northern Plains ranchers prioritize these for seasonal pasture relocation without fixed infrastructure investment.
- Liquid Feeder:Pressurized dispensing systems for molasses-based mineral suspensions serve specialized dairy nutrition protocols requiring controlled intake rates.
- Block Feeder:Restricted-access hood designs minimize waste from compressed mineral blocks in exposed range conditions.
Volume sits with Free Choice Feeders; growth tilts toward Tub Feeders.
Material:
Total cost of ownership calculations now weight resin price volatility against steel fabrication geography.
- Plastic:UV-stabilized polyethylene rotational molding delivers 0.25-0.5 inch wall thickness calibrated to 1,200-pound bull pressure and 150-pound horn impact. Feedlot operators in Texas and Oklahoma specify these for elimination of corrosion-related downtime in high-humidity confinement.
- Metal:Galvanized steel fabrication retains cost advantage in Corn Belt regions with captive rolling capacity, though replacement cycles compress where USDA APHIS biosecurity protocols mandate seam sanitation.
- Composite:Fiberglass-reinforced polymer bridges durability gaps between commodity plastic and fabricated steel for premium positioning.
- Wood:Limited to heritage ranch aesthetic applications and temporary field installations with minimal capital allocation.
Procurement volume clusters with Plastic; specification authority is shifting fastest toward Composite in riparian buffer compliance scenarios.
End User:
Operational scale determines feeder durability specifications and data integration requirements.
- Beef Farmers:Large-scale feedlot operators in the Great Plains drive demand for RFID-enabled intake monitors and load cell integration. Herd managers prioritize precision nutrition hardware that syncs with herd management software platforms.
- Co-ops:Centralized buying committees across the Dakotas standardize stackable tub dimensions that optimize trailer cube utilization and reduce per-unit freight costs across multi-pasture member operations.
- Dairy Farmers:Confined operations emphasize biosecurity-compliant seamless designs for pathogen control in high-density housing.
- Livestock Ranchers:Mixed-species operations select versatile feeder geometries accommodating cattle, sheep, and goat mineral access.
Beef Farmers command the largest installed base; Co-ops are expanding most quickly through procurement consolidation.
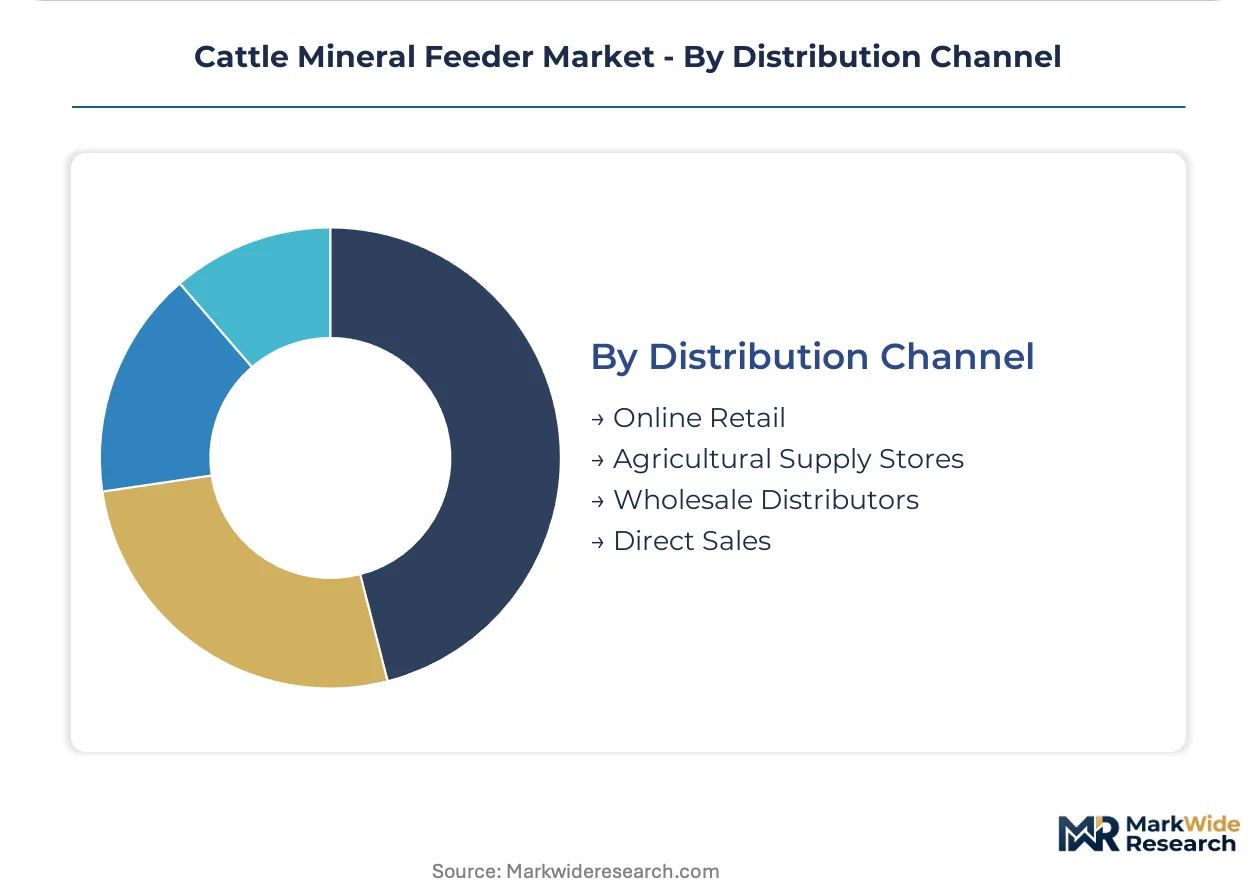
Distribution Channel:
Channel selection reflects geographic supply asymmetry and technical service requirements for precision hardware.
- Agricultural Supply Stores:Independent dealers in cooperative-dense regions align with standardized specification sheets or exit the category entirely. These outlets dominate replacement part availability and emergency procurement.
- Wholesale Distributors:Regional livestock supply networks leverage volume aggregation to compress manufacturer margins while controlling inventory positioning ahead of seasonal grazing shifts.
- Direct Sales:Manufacturers with load cell calibration expertise build direct service capabilities where traditional distributor skill scarcity impedes precision feeder deployment.
- Online Retail:E-commerce penetration remains limited to standardized commodity units without installation complexity or warranty service dependencies.
Transaction volume concentrates through Agricultural Supply Stores; channel control is migrating fastest toward Wholesale Distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Beef cattle operations concentrate demand across the Great Plains corridor of the United States, with feedlot density in Nebraska, Kansas, and Texas driving procurement volumes for mineral dispensing hardware.
United States
Great Plains feedlots in Nebraska and Kansas prioritize precision nutrition hardware with load cell integration for intake monitoring. USDA APHIS biosecurity protocols mandate seamless polymer designs over welded steel in confined operations. Sioux Steel Company anchors Corn Belt supply through captive fabrication capacity serving Iowa and Illinois ranch supply networks.
Brazil
Pastoral beef operations in Mato Grosso and Goiás states drive demand for weatherized mineral delivery systems in tropical exposure conditions. ANVISA regulates veterinary premix additives that flow through feeder hardware, affecting formulation compatibility standards. Campo Grande industrial clusters host rotational molding facilities supplying stackable tub designs for cooperative procurement channels.
Australia
Extensive grazing properties in Queensland and New South Wales specify UV-stabilized polyethylene units for high-altitude solar degradation resistance. The country's national agricultural regulator enforces biosecurity protocols for mineral station sanitation in multi-property enterprises. Toowoomba manufacturing hubs produce forklift-compatible designs for seasonal pasture relocation logistics.
Argentina
Pampas region feedlots deploy mineral feeders compatible with loose trace mineral formulations in corn-finishing operations. The national agricultural inspection service monitors mineral quality standards at point of dispensing equipment. Rosario industrial corridors concentrate polymer molding capacity serving Mercosur cooperative distribution networks.
Canada
Prairie Province cow-calf operations in Alberta and Saskatchewan prioritize freeze-thaw durability in mineral feeder procurement decisions. Health Canada regulates veterinary drug premixes that interact with feeder design specifications for controlled access. Lethbridge agricultural equipment clusters manufacture stackable configurations for rotational grazing programs across the Northern Plains.
Cattle Mineral Feeder Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with nutrition science conglomerates bundling mineral formulations with proprietary hardware designs while regional fabricators compete on replacement cycle economics. The vendor base organizes around three strategic archetypes: captive steel fabricators with Corn Belt rolling capacity, rotational molding specialists serving cooperative procurement channels, and integrated nutrition companies embedding data infrastructure into dispensing hardware. M&A activity concentrates among feed ingredient conglomerates acquiring precision hardware capabilities, while capacity expansion focuses on polymer molding installations in feedlot-dense corridors.
Among diversified nutrition conglomerates, Cargill Incorporated and Archer Daniels Midland Company exemplify the bundled-offering archetype that combines mineral science with dispensing hardware specifications. Sioux Steel Company represents the captive-fabrication model with geographic concentration in steel-rolling regions. These three entities anchor competitive positioning across distinct procurement channels: cooperative standardization programs, direct feedlot contracting, and regional agricultural supply networks.
| Leading Market Players |
|---|
| Land O'Lakes, Inc. |
| AmeriAg |
| Sioux Steel Company |
| BASF SE |
| JFC Agri |
| Cargill Incorporated |
| Alltech, Inc. |
| Archer Daniels Midland Company |
| Nutreco N.V. |
| Others |
Value Chain & Pricing Dynamics
Rotational-molding technician pools in the Great Lakes industrial corridor anchor labor-cost differentials that widen pricing-tier spreads between commodity polyethylene units and precision-integrated feeders with embedded load cells.
Pricing Analysis
Volume concentrates in standardized tub configurations while margins accrue to RFID-enabled precision feeders. Three-tier pricing structure across premium, standard, and economy levels separates composite-reinforced units with calibration services from basic rotational-molded commodity vessels. Pricing pressure stems from resin feedstock volatility tied to natural gas liquids benchmarks. Ranch supply cooperatives exhibit acute price sensitivity, whereas large-scale Nebraska and Kansas feedlots prioritize total cost of ownership over unit acquisition cost.
Supply Chain Analysis
Dual-sourcing requirements from Great Plains cooperative procurement committees mandate qualification of both polymer molders and steel fabricators, compressing single-source dependency risks. Manufacturing gravity centers on the United States Corn Belt, Canada Prairie Provinces, and Brazil Campo Grande industrial clusters. Feedstock dependencies encompass polyethylene resin, UV stabilizer packages, and zinc-coated steel sheet. Tariff exposure on Canadian steel shipments creates intermittent supply asymmetry. Distribution runs through agricultural supply cooperatives with captive logistics networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
USDA APHIS biosecurity protocols function as a cost-of-compliance moat, elevating sanitation-capable polymer molders while marginalizing welded steel fabricators lacking seamless construction expertise.
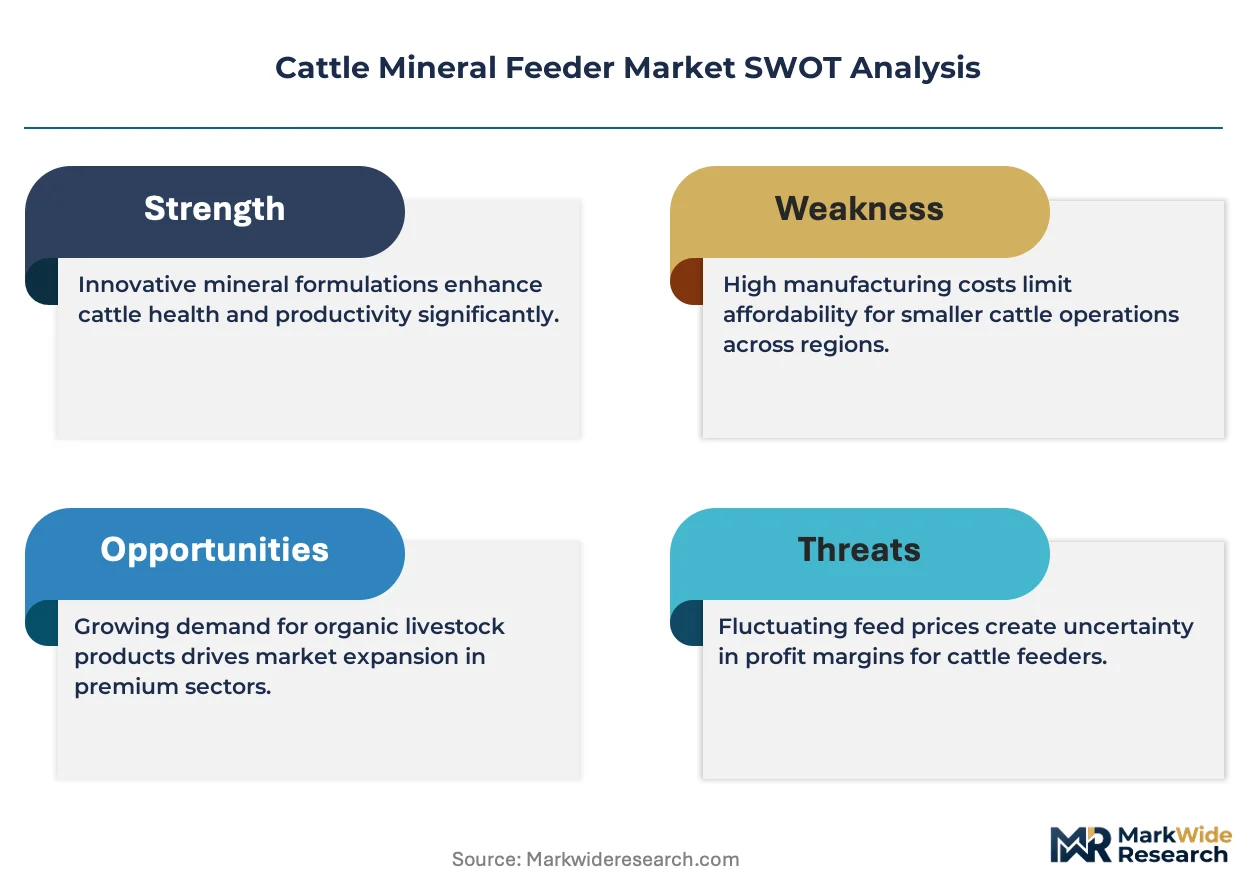
For Market Incumbents: Deepen captive rotational-molding capacity in feedlot-dense corridors to defend against nutrition-science conglomerates bundling mineral formulations with proprietary hardware. Prioritize backward integration into UV stabilizer compounding to hedge resin price volatility. Expand direct service capabilities for load cell calibration where distributor skill scarcity impedes precision feeder deployment. For New Entrants and Emerging Players: The mid-tier price-point gap between economy polyethylene tubs and premium composite-reinforced units opens white space for fiberglass-polymer hybrid designs targeting riparian buffer compliance scenarios. Mountain West cooperative standardization programs represent the most penetrable procurement channel. Pursue forklift-compatible dimensional certification through regional livestock supply networks to bypass entrenched dealer relationships. For Investors and Strategic Acquirers: Re-rating potential sits with rotational-molding specialists possessing embedded sensor integration capabilities given convergence of livestock identification mandates with precision agriculture platforms. Long-term viability favors vendors bridging hardware fabrication with data infrastructure deployment. Watch for EPA enforcement intensity in Platte River and Rainwater Basin watersheds as inflection indicator for repositionable feeder demand.| Strategic Initiative | Industry Significance |
|---|---|
| RFID Sensor Integration | Feeder-embedded intake monitors sync with Cargill and Alltech herd management software platforms. |
| Backward Integration into Resin Compounding | Captive UV stabilizer formulation hedges polyethylene feedstock volatility from natural gas liquids pricing. |
| Cooperative Procurement Certification | Standardized tub dimensions unlock Dakota and Nebraska cooperative buying committee specifications. |
| Riparian Buffer Compliance Positioning | Portable drainage-contained designs capture EPA-driven relocation demand in Nebraska wetland zones. |
| Direct Service Capability Buildout | Load cell calibration expertise bypasses traditional distributor technical limitations in precision hardware deployment. |
Study Parameters
Independent corroboration across feedlot operations managers, cooperative procurement directors, and rotational-molding plant engineers underwrites the qualitative findings. Primary fieldwork encompassed livestock equipment distributors, USDA APHIS compliance officers, and polymer resin procurement leads at Midwest molders. Secondary validation drew from EPA Clean Water Act enforcement records, state Department of Agriculture weights-and-measures inspection data, and agricultural supply cooperative annual reports. Bottom-up unit shipment tallies triangulated against top-down mineral consumption estimates across the analysis window.
Rate-of-change decomposition separated volume expansion from value migration across product architecture, material durability, operational scale, and channel access dimensions. Modeled segmentation encompassed free choice versus tub versus liquid feeder configurations, polyethylene versus steel versus composite material tiers, and beef feedlot versus cooperative versus dairy end-user categories. CAGRs derived from polynomial trend fitting to historical replacement cycles, calibrated against herd inventory projections and precision nutrition adoption curves. Forecast inputs incorporated resin price elasticity coefficients and biosecurity protocol expansion timelines.
Underlying measurement precision varies by segment; Great Plains feedlot procurement data carries tighter precision than scattered cow-calf operator estimates. Forecasts assume continued EPA enforcement trajectory and cooperative consolidation patterns. Deviation in USDA APHIS protocol stringency or natural gas liquids pricing volatility would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Livestock Management
Animal Artificial Insemination Market
Livestock Management
Equine Artificial Insemination Market
Livestock Management
United States Swine Feed Market
Livestock Management
Layer Feed Market
Livestock Management
Pig Feed Market
Livestock Management
South America Swine Feed Market
Livestock Management
Wild Birds Products Market
Livestock Management
Morocco Poultry Market
Livestock Management
Colombia Animal Feed Market
Livestock Management
Swine Artificial Insemination Market
Livestock Management
Poultry Concentrate Market
Livestock Management
Global Smart Ear Tags Market
Livestock Management
Animal Identification Market
Livestock Management
Cattle Head Catch Market
Livestock Management
Hominy Feed Market
Livestock Management
Poultry Health Market