
 United States Swine Feed Market | 2026-2036
United States Swine Feed Market Size, Share, and Industry Trends Forecast 2026-2036
United States Swine Feed Market Intelligence
Premium-grade swine nutrition specification is rotating through the United States swine feed channel as integrators tighten margin targets and export certification requirements stiffen. Cargill, Inc. leverages its grain origination network across Iowa and Illinois to secure cost-advantaged corn positions for captive feed production. BASF SE differentiates through micronutrient premix technology that addresses lysine optimization in grower rations. CHS Inc. anchors its position via cooperative ownership structures that lock in volume commitments from member pork producers.
Swine feed denotes formulated rations engineered to meet the nutritional requirements of domestic pigs across growth stages, typically comprising 60-75% corn, 15-25% soybean meal, and supplemented with amino acids, vitamins, and minerals to achieve target feed conversion ratios near 2.6:1. Its primary commercial purpose is to optimize weight gain efficiency while maintaining herd health metrics that satisfy processor audit standards. Pellet form commands structural preference among large-scale operations because pelleting reduces feed waste and improves nutrient digestibility compared to meal alternatives. Medicated feed categories face regulatory compression under antibiotic stewardship programs, while starter feed segments attract R&D investment focused on gut microbiome modulation.
The FDA Veterinary Feed Directive and USDA FSIS export certification requirements jointly constrain antibiotic inclusion levels and mandate documentation chains that elevate compliance costs for non-integrated producers. EPA nutrient management regulations in states with concentrated animal feeding operations further dictate manure-handling protocols that influence feed phosphorus formulation decisions. Stakeholders must monitor evolving state-level odor and water-quality restrictions that could force geographic relocation of finishing capacity and reshape regional feed demand patterns.
Market Dynamics
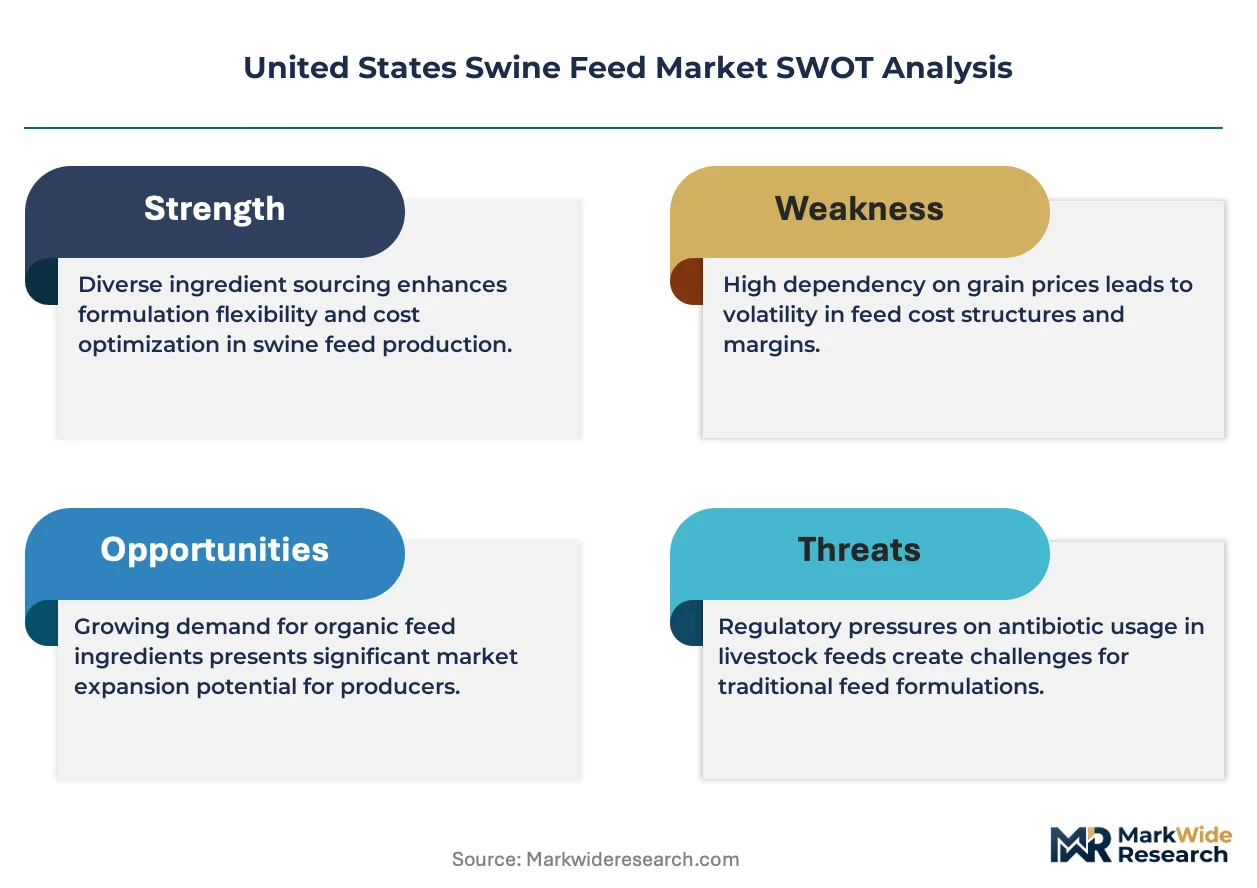
Consolidation among commercial pork processors is compressing feed supplier margins while simultaneously elevating traceability documentation requirements across the entire supply chain. This structural pressure forces feed manufacturers to absorb compliance costs or risk volume displacement to vertically integrated competitors with captive milling capacity.
Growth Catalysts
- Processor Traceability Mandates:Commercial pork processors now require lot-level documentation for antibiotic-free certification, pulling feed mills toward integrated quality management systems that satisfy export audit standards.
- Corn Belt Proximity Economics:Iowa and Illinois grain origination points enable cost-advantaged feed production through reduced transportation radius and just-in-time ingredient sourcing for finishing operations.
- FDA Veterinary Feed Directive:Restrictions on medically important antibiotics in feed are redirecting R&D investment toward gut microbiome modulation technologies and alternative growth promotion strategies.
Market Restraints
- Soybean Meal Price Volatility:Crush margin compression and export competition from China-bound shipments elevate input cost uncertainty for standard grower rations.
- Midwest Grain Handler Concentration:Four major elevator networks control origination logistics across the Corn Belt, limiting feed mill bargaining power during harvest windows.
- Phosphorus Formulation Constraints:EPA nutrient management regulations in Iowa, North Carolina, and Oklahoma restrict manure phosphorus application rates, forcing feed phosphorus reduction that can compromise growth performance metrics.
Strategic Opportunities
- Nebraska and Kansas Expansion Corridors:Underdeveloped finishing capacity in western Corn Belt states offers greenfield feed mill sites with lower regulatory density and available water rights.
- Precision Premix Technology:Real-time formulation adjustment based on individual barn microclimate data enables customized amino acid dosing that improves feed conversion ratios.
- USDA FSIS Export Certification Alignment:Feed mills achieving Hazard Analysis Critical Control Point validation for EU and Asian market access capture premium pricing from export-oriented integrators.
Industry Challenges
- Regulatory Documentation Burden:Veterinary Feed Directive record-keeping requirements demand specialized compliance personnel that smaller regional feed mills struggle to recruit and retain.
- Legacy Mill Retrofit Costs:Pelleting line upgrades to handle higher-inclusion alternative proteins require capital outlays that stretch payback periods beyond typical financing terms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Swine Feed Market |
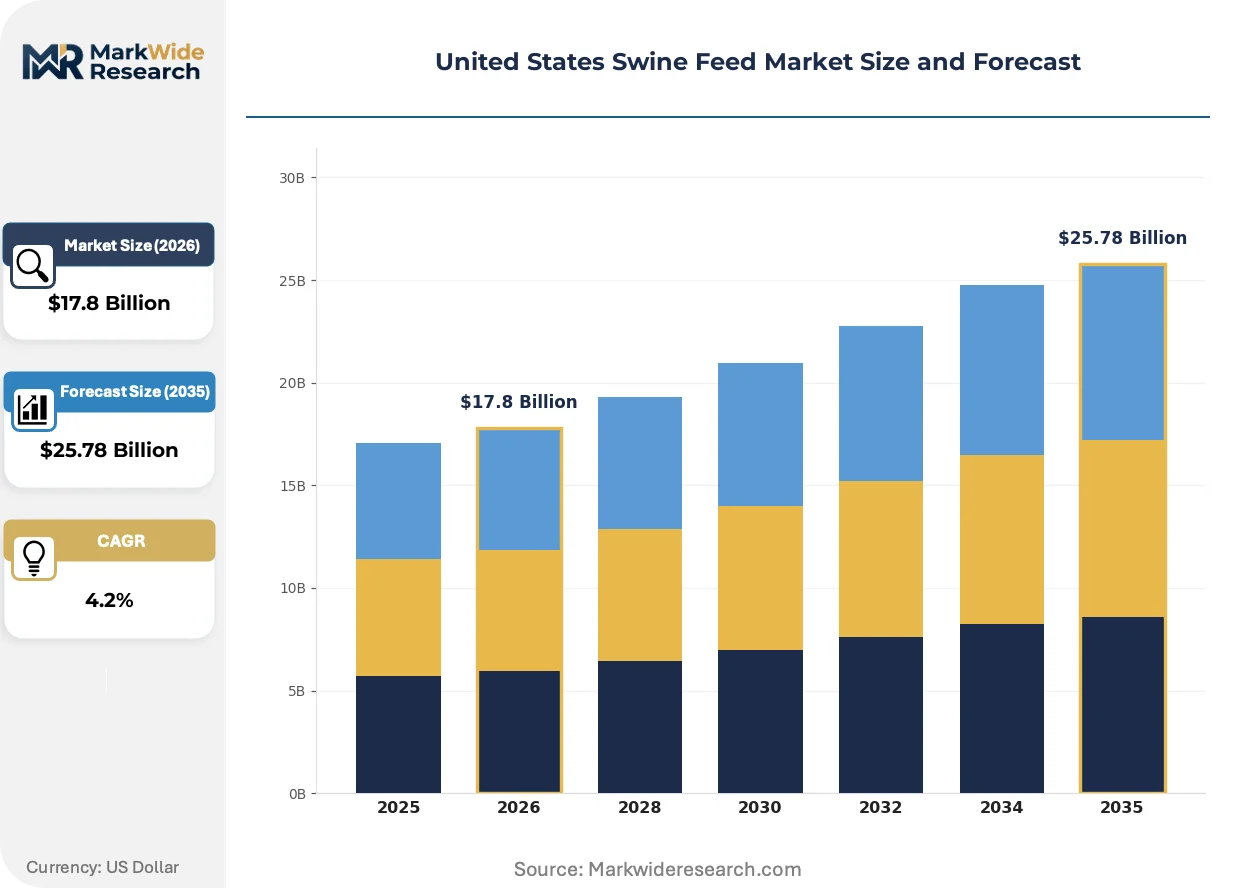
| Market Size in 2026 | $17.8 Billion |
| Market Size in 2035 | $25.78 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medicated Feed, Non-Medicated Feed, Starter Feed, Grower Feed Ingredient Type: Corn, Soybean Meal, Wheat, By-products Form: Pellets, Meal, Crumbles, Liquids Distribution Channel: Online Sales, Retail Stores, Direct Sales, Wholesalers |
| Companies Covered | Alltech, Inc., BASF SE, Cargill, Inc., KENT Nutrition Group, Novus International, Inc., Land O'Lakes, Inc., CHS Inc., J.D. Heiskell and Co., Archer Daniels Midland Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Swine Feed Market Strategic Shifts & Innovations
Digital feed formulation platforms and alternative protein sourcing strategies are restructuring how nutrition specifications propagate from genetic suppliers through to finishing barns. These innovations compress the traditional feed procurement cycle while elevating technical service intensity.
Enzyme-assisted digestion technology is bifurcating the grower feed segment between standard soybean meal formulations and reduced-crude-protein rations supplemented with synthetic amino acids and phytase. Large-scale integrators in Iowa and Minnesota are adopting these formulations at accelerating rates to meet processor antibiotic-free commitments. This technology is bifurcating competitive positioning between premix specialists with enzymatic expertise and commodity blenders lacking technical service depth.
The FDA's Veterinary Feed Directive continues tightening documentation chains for medically important antibiotics, compelling feed mills to implement electronic record systems that interface directly with veterinary prescription platforms. Industrial consequence includes elevated compliance staffing costs and accelerated consolidation among non-integrated regional mills. Smaller North Carolina and Oklahoma operations face disproportionate impact as they lack capital reserves for system upgrades.
Contracting models are rotating from spot ingredient purchasing toward indexed price agreements that lock in corn and soybean meal basis differentials six months forward. Large commercial processors and integrated systems are displacing traditional cash-market buying through these instruments. This shift is most visible across Iowa and Illinois where grain origination density supports liquid basis markets and reliable forward pricing infrastructure.
United States Swine Feed Market Segmentation
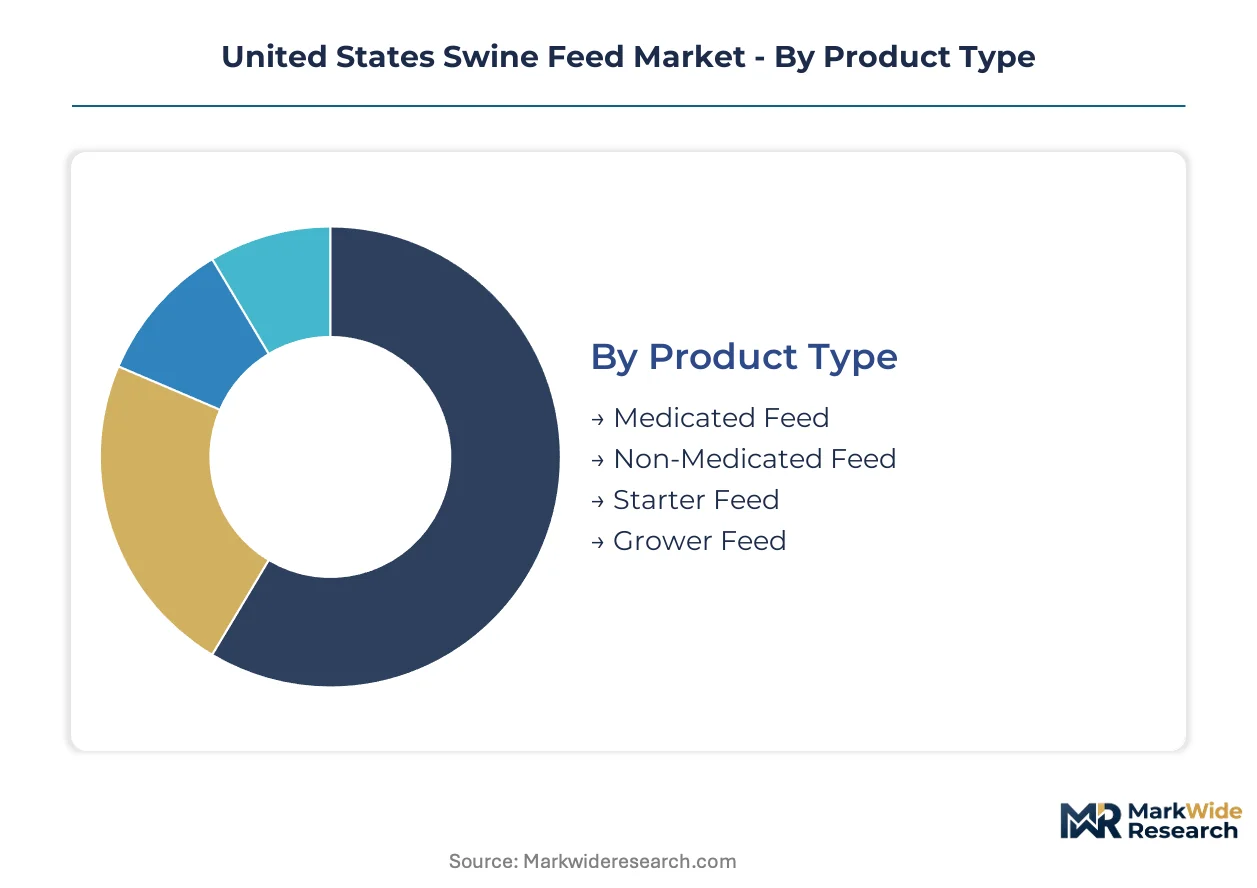
Feed manufacturers align product specifications with processor audit requirements and barn-level delivery economics. Channel mix varies sharply across segment categories, with large integrators favoring direct procurement while independent producers rely on retail and wholesale intermediaries.
Product Type:
Channel flow diverges sharply: medicated and starter feeds move predominantly through veterinary-linked direct sales, while grower and non-medicated categories concentrate in wholesale and retail channels serving independent finishers.
- Medicated Feed:Formulations containing FDA-regulated antibiotics require veterinary prescriptions under the Veterinary Feed Directive, restricting distribution to licensed feed mills with electronic documentation systems. Demand concentrates among mid-scale Iowa and Illinois operations lacking in-house nutrition teams, as these producers rely on medicated options to manage herd health metrics. Regulatory compression is redirecting R&D investment toward gut microbiome modulation alternatives.
- Starter Feed:High-protein rations engineered for nursery-phase pigs emphasize palatability and digestive enzyme supplementation to establish gut flora colonization. Nebraska and Kansas greenfield operations are expanding starter feed procurement most aggressively as they build sow farm and nursery capacity. This segment is climbing the fastest as antibiotic-free certification requirements stiffen.
- Non-Medicated Feed:Antibiotic-free formulations certified for export markets command premium pricing through processor-aligned channels.
- Grower Feed:Standard finishing rations optimized for feed conversion ratios near 2.6:1 dominate volume throughput in Corn Belt wholesale networks.
Grower feed dominates installed base. Starter feed is where expansion concentrates.
Ingredient Type:
Cost tier stratification separates commodity grain positions from value-added by-product formulations, with price sensitivity varying across integrated versus independent producer segments.
- Corn:Constitutes 60-75% of standard rations by weight, with origination proximity determining delivered cost competitiveness. Iowa and Illinois grain elevator networks supply captive feed mills at basis advantages unavailable to non-integrated competitors. Weather-driven yield volatility and ethanol plant competition for bushels create input cost uncertainty.
- Soybean Meal:Primary protein source providing lysine and other essential amino acids for muscle development. North Carolina and Oklahoma operations face elevated crush margin compression as export competition from China-bound shipments tightens domestic supply. Phytase supplementation is reducing inclusion rates in precision-formulated rations.
- Wheat:Substitute carbohydrate source during corn price spikes, common in Pacific Northwest feed formulations.
- By-products:Distillers dried grains and bakery meal offer cost-advantaged protein and energy in regional blending operations.
Corn dominates installed base. Soybean meal is where formulation innovation concentrates.
Form:
Volume scale and barn automation level dictate form selection, with large-scale operations driving structural preference toward mechanically handled formats.
- Pellets:Compacted feed forms reduce waste and improve nutrient digestibility through heat-treated starch gelatinization. Large-scale integrators in Minnesota and Iowa specify pellets exclusively for automated feeding systems in tunnel-ventilated finishing barns. Pelleting line capital requirements limit supply to major mill networks.
- Meal:Ground feed maintains cost advantage for smaller operations with manual handling systems and lower capital intensity.
- Crumbles:Intermediate particle size targets nursery-phase pigs transitioning from mash to pellet textures.
- Liquids:Molasses-based supplements and fat emulsions deliver energy density for high-performance genetic lines.
Pellets dominate installed base. Liquids are where precision nutrition investment concentrates.
Distribution Channel:
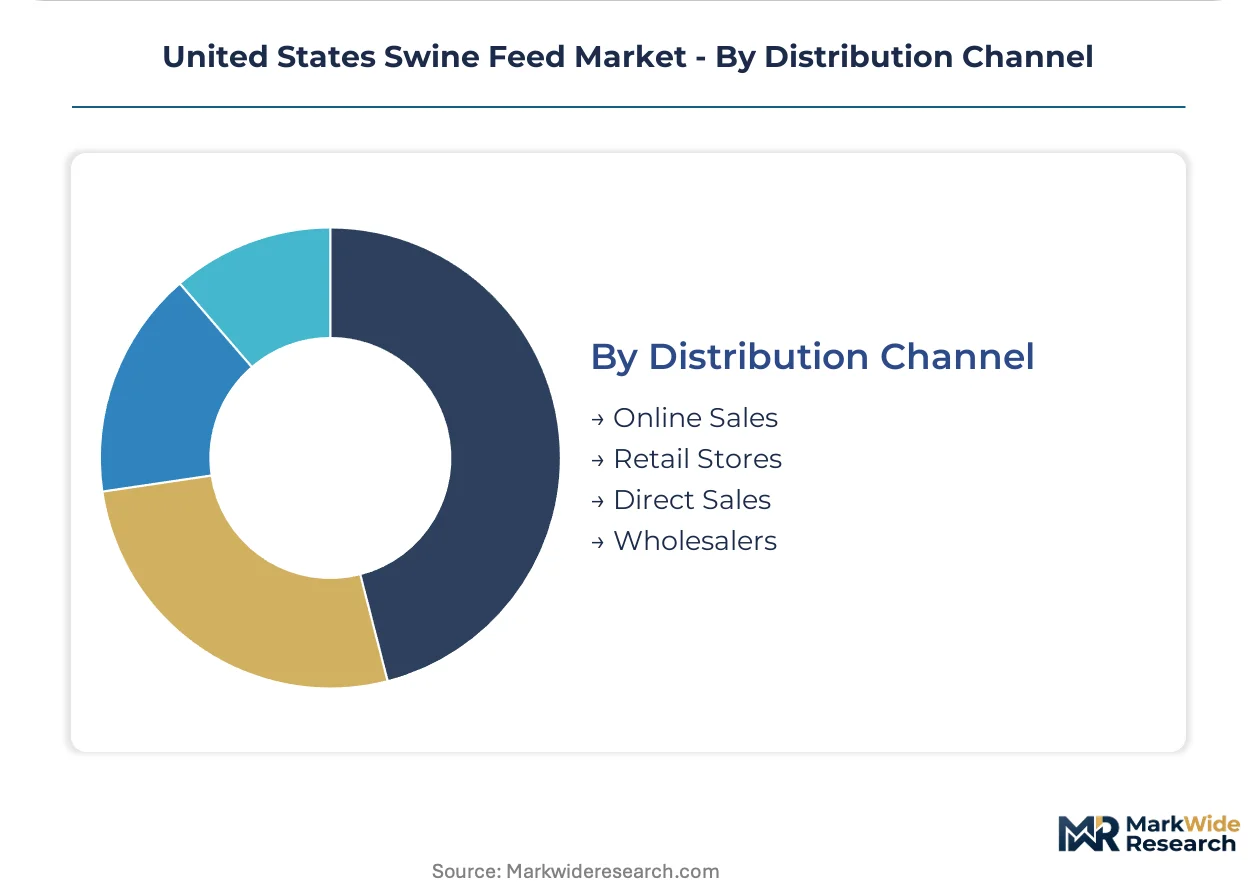
Customer type and procurement sophistication determine channel selection, with contract structure complexity varying across transaction mechanisms.
- Direct Sales:Long-term supply agreements link major feed manufacturers to integrated pork processors and large sow cooperatives. CHS Inc. and similar cooperative structures lock in volume commitments through member ownership, delivering just-in-time rations to finishing barns within 50-mile radius of mill locations. Electronic ordering platforms interface directly with barn management software.
- Wholesalers:Regional distributors aggregate volume from multiple mills to serve independent producers lacking direct procurement scale.
- Retail Stores:Farm supply cooperatives and independent dealers provide credit terms and technical service to smaller operations.
- Online Sales:Emerging channel for specialty premixes and micro-ingredients targeting niche antibiotic-free certification programs.
Direct sales dominate installed base. Online sales are where channel experimentation concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States runs a structural surplus in pork exports, with Corn Belt feed production capacity expanding to supply finishing operations that ship to Mexico and Asian markets. Regional feed demand patterns track processor consolidation and EPA nutrient management enforcement density.
Iowa
Integrated hog finishing and grain origination density makes Iowa the dominant feed consumption state, with operations clustering around Sioux City and Des Moines processing corridors. The EPA's concentrated animal feeding operation permitting requirements shape manure handling protocols that influence phosphorus formulation decisions. Northwest Iowa hosts the densest feed mill network, where cooperative and captive milling capacity serves Tyson Foods and JBS finishing barns within 50-mile radiuses.
Illinois
Central Illinois grain elevator networks supply cost-advantaged corn positions to feed mills concentrated around Peoria and Decatur processing hubs. The state's Nutrient Loss Reduction Strategy imposes watershed-level phosphorus loading caps that restrict manure application rates and force feed formulation adjustments. Western Illinois finishing capacity is expanding most aggressively as producers relocate from higher-regulation states.
North Carolina
The Cape Fear and Neuse River watersheds concentrate contract finishing operations serving Smithfield Foods processing plants, despite stricter EPA nutrient management enforcement than Midwest competitors. State-level moratoriums on new hog farm permits have frozen geographic expansion, forcing existing operations to intensify production. The Coastal Plain hosts legacy finishing capacity where smaller producers face disproportionate Veterinary Feed Directive compliance burdens.
Minnesota
Southern Minnesota sow farm and nursery capacity supports finishing operations that supply Hormel Foods and independent processors, with feed demand concentrated around Mankato and Worthington. The Minnesota Pollution Control Agency's feedlot rules govern manure storage and land application distances. The state's Red River Valley is attracting greenfield feed mill investment as producers expand antibiotic-free certification capacity for export markets.
Nebraska
Western Corn Belt expansion corridors in Nebraska offer lower regulatory density and available water rights that pull sow farm and finishing investment from saturated eastern markets. The Nebraska Department of Environment and Energy's livestock permitting framework enables faster project approval timelines than Iowa or Illinois. The Platte River Valley is emerging as a feed production growth zone where new mill capacity serves relocated finishing operations.
United States Swine Feed Market Key Industry Players
Concentration sits with grain-originating cooperatives and integrated agribusiness conglomerates that control captive milling capacity. Three tiers structure competitive positioning: multinational nutrition companies with premix technology, regional cooperative networks with member-locked volume, and independent blenders serving spot-market independents. Dominant competitive moves include backward integration into grain origination and strategic partnerships with processor-aligned integrators.
Among the multinational nutrition tier, BASF SE and Cargill, Inc. exemplify divergent strategic archetypes—BASF occupying the micronutrient premix specialization position while Cargill anchors the grain-origination-integrated feed manufacturing model. CHS Inc. represents the cooperative ownership structure that locks in volume commitments through member equity stakes. These three entities collectively illustrate how feed supply competitive advantage derives from either upstream grain control, technical service depth, or cooperative governance mechanisms.
| Leading Market Players |
|---|
| Alltech, Inc. |
| BASF SE |
| Cargill, Inc. |
| KENT Nutrition Group |
| Novus International, Inc. |
| Land O'Lakes, Inc. |
| CHS Inc. |
| J.D. Heiskell and Co. |
| Archer Daniels Midland Company |
| Others |
Cost & Logistics Intelligence
Synthetic amino acid substitution for soybean meal is redrawing procurement geography across the Corn Belt while compressing protein input costs for precision-formulated rations. This input shift simultaneously weakens crush margin exposure for Iowa and Illinois feed mills and elevates enzymatic premix suppliers into pricing gatekeeper roles.
Pricing Analysis
Commercial pork processors anchor contract pricing through indexed corn and soybean meal basis agreements that lock six-month forward differentials. Three-tier pricing structure across antibiotic-free certified, standard grower, and economy rations reflects certification grade and volume scale differentiation. Pricing pressure stems from processor consolidation forcing feed mills to absorb traceability compliance costs without pass-through mechanisms. Independent finishers in North Carolina and Oklahoma exhibit highest price sensitivity due to regulatory compliance burdens and smaller procurement scale.
Supply Chain Analysis
Just-in-time ingredient sourcing dominates Corn Belt feed manufacturing, with Iowa and Illinois grain elevator networks delivering corn within 24-hour windows to captive mill operations. Geographic supply concentration centers on the Midwest corn origination corridor, with secondary soybean meal dependencies drawing from Illinois and Indiana crush facilities. Supply chain risk hinges on single-source vulnerability among four major elevator networks controlling harvest logistics. Distribution runs through direct sales agreements linking cooperative mills to integrated finishing operations within 50-mile radiuses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The FDA Veterinary Feed Directive's antibiotic documentation mandates constitute a regulatory inflection that is accelerating digital feed formulation adoption and consolidating non-integrated regional mills. This disruption creates asymmetric opportunity for technology-enabled suppliers and cooperative structures with captive compliance infrastructure.
For Market Incumbents: Compound defensive positioning through backward integration into grain origination assets across Iowa and Illinois, securing basis advantages unavailable to commodity competitors. Accelerate HACCP validation investments for USDA FSIS export certification alignment to capture premium pricing from export-oriented integrators. The regulatory documentation burden threatens smaller regional mills with volume displacement. For New Entrants and Emerging Players: Anchor in Nebraska and Kansas expansion corridors where lower regulatory density and available water rights attract relocated sow farm and finishing investment. Target starter feed segments in greenfield nursery operations building antibiotic-free certification capacity. Deploy precision premix technology with real-time barn microclimate integration as differentiated go-to-market positioning against commodity blenders. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors cooperative ownership structures with member-locked volume and captive milling infrastructure. Long-term viability over the next decade hinges on feed mills achieving electronic veterinary prescription platform integration and export certification validation. Watch for FDA enforcement intensity on Veterinary Feed Directive compliance as the signal indicating acceleration of regional mill acquisition activity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Grain Origination | Cargill and CHS leverage Iowa elevator networks to secure cost-advantaged corn positions for captive feed production. |
| Precision Premix Technology Deployment | BASF's micronutrient formulations enable real-time amino acid dosing that improves feed conversion ratios for integrators. |
| Export Certification Alignment | HACCP validation for USDA FSIS requirements captures premium pricing from EU and Asian market-oriented pork processors. |
| Greenfield Mill Capacity Expansion | Nebraska Platte River Valley sites serve relocated finishing operations with faster permitting than Iowa or Illinois. |
| Electronic Documentation System Implementation | Veterinary Feed Directive compliance platforms interface directly with prescription systems to retain mid-scale producer volume. |
Research Approach
A standing panel of feed mill operations directors, veterinary nutrition specialists, pork processor procurement managers, and cooperative member relations executives provided ongoing calibration throughout the study period. Primary fieldwork combined structured interviews with secondary validation against USDA NASS crop production reports, EPA nutrient management filings, FDA Veterinary Feed Directive guidance documents, and Iowa State University extension economic analyses. Bottom-up volume modeling from state-level hog inventory data triangulated against top-down processor capacity assessments.
Consistency checks against USDA Economic Research Service livestock feed cost indices and Iowa Grain Company basis historicals validated projection outputs across the analysis window. Segmentation modeling incorporated product type, ingredient composition, physical form, and distribution channel dimensions with geographic regulatory cluster differentiation. CAGRs derived from trend extrapolation of corn-soybean meal price ratios, processor consolidation trajectories, and export certification adoption curves.
Material uncertainties — drought-induced corn yield volatility, EPA nutrient management enforcement intensity, and FDA antibiotic stewardship rule expansion — sit outside the modeled envelope. Forecasts reflect assumptions regarding continued processor traceability mandate tightening and stable export market access. Revision becomes warranted when Veterinary Feed Directive compliance cost thresholds trigger accelerated regional mill consolidation beyond baseline trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Livestock Management
Europe Swine Feed Market
Livestock Management
Roughage Feed Market
Livestock Management
Feed Management Software Market
Livestock Management
Europe Feed Binders Market
Livestock Management
Cattle Mineral Feeder Market
Livestock Management
North America Feed Binders Market
Livestock Management
Swine Feed Market
Livestock Management
Cattle Management Software Market
Livestock Management
Layer Breeding System Market
Livestock Management
Digital Livestock Farming Market
Livestock Management
China Swine Feed Market
Livestock Management
Hog Production and Pork Market
Livestock Management
Equine Artificial Insemination Market
Livestock Management
Smart Feeding Systems Market
Livestock Management
South America Ruminant Feed Market
Livestock Management
Africa Alfalfa Hay Market