
 South America Reactive Adhesives Market | 2026-2036
South America Reactive Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
South America Reactive Adhesives Market Analytics
Technical service subscriptions for adhesive application equipment is recalibrating how suppliers capture lifetime value from Brazilian and Argentine manufacturing clients. H.B. Fuller Company leverages its regional technical centers to anchor long-term maintenance contracts with automotive OEMs. Dow competes through direct silicone supply relationships with electronics assemblers in southern Brazil. Sika AG specializes in construction-sector bonding systems, dominating infrastructure project specifications across the Andean region.
Reactive adhesives are thermosetting polymer systems that cure through chemical reaction rather than solvent evaporation, typically achieving structural bond strengths exceeding 20 MPa through crosslinked polyurethane, epoxy, or acrylic chemistries. These formulations serve primary industrial purposes including permanent assembly of dissimilar substrates, vibration-dampening structural joints, and hermetic sealing in moisture-sensitive applications. Polyurethane adhesives lead volume consumption in South America due to flexibility and cure-speed adaptability across automotive and construction bonding lines. Epoxy segments command premium positioning in electronics laminating and high-strength coating applications where thermal resistance and dimensional stability determine specification. Acrylic formulations represent the fastest-expanding category in packaging sealing operations, driven by demand for UV-curable, low-odor systems in food-contact film applications.
ANVISA governs chemical substance registration and industrial hygiene standards for adhesive formulations manufactured or imported into Brazil. Argentina's Secretariat of Environment and Sustainable Development enforces volatile organic compound emission thresholds that shape product reformulation priorities for regional blending operations. REACH-equivalent regulatory convergence across Mercosur trading partners is forcing multinational suppliers to harmonize composition disclosure protocols. Stakeholders must monitor how forthcoming chemical inventory notification deadlines in Brazil and Argentina reshape import authorization pathways and local production requirements.
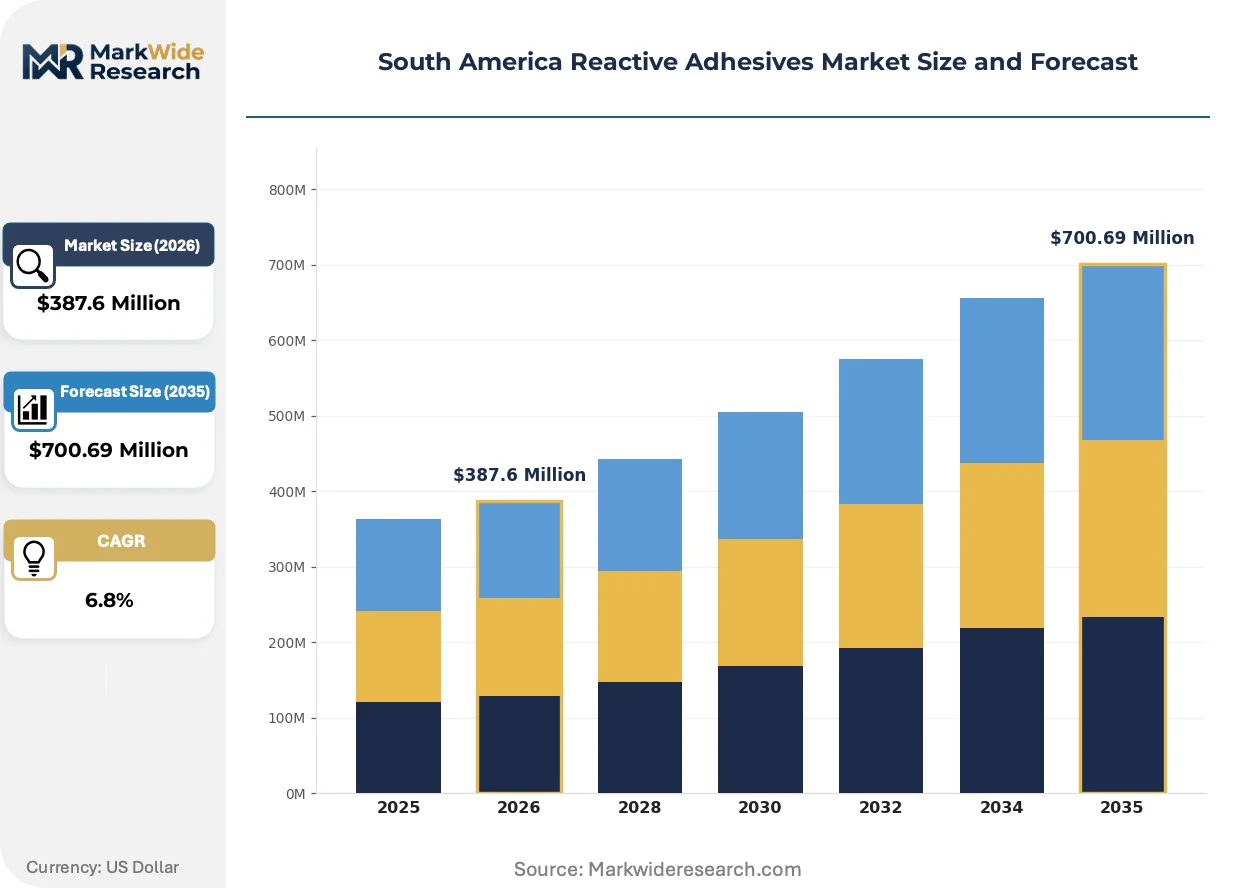
Market Dynamics
Automotive lightweighting mandates across Mercosur trading partners are forcing adhesive specification upgrades, as Brazilian OEMs replace mechanical fasteners with structural bonding systems to meet fuel-efficiency targets and crash-safety standards simultaneously.
Growth Catalysts
- ANVISA VOC compliance deadlines:Brazil's tightening volatile organic compound limits are accelerating reformulation investments toward solvent-free reactive systems in industrial coating operations.
- Wind blade manufacturing clusters:Argentine and Brazilian renewable energy equipment producers are specifying epoxy-urethane hybrid adhesives for turbine assembly lines in Córdoba and Rio Grande do Sul.
- Electronics laminating demand:Southern Brazil's printed circuit board fabricators are expanding consumption of thermally conductive epoxy adhesives for 5G infrastructure components.
Market Restraints
- Isocyanate feedstock volatility:Polyurethane adhesive margins compress when MDI and TDI prices spike, given Brazilian dependence on imported aromatic diisocyanates from Asian suppliers.
- Import authorization bottlenecks:Argentina's chemical inventory notification requirements delay new adhesive formulation launches by 12-18 months for non-Mercosur suppliers.
- Hot-melt pressure-sensitive substitution:Packaging converters in São Paulo are partially displacing reactive acrylics with EVA-based hot-melts in non-structural sealing applications.
Strategic Opportunities
- Chilean mining equipment maintenance:Copper and lithium extraction operators in Antofagasta represent an underpenetrated vertical for high-temperature epoxy repair adhesives in crusher and mill applications.
- UV-curable acrylic expansion:Food-contact film laminators across the region are retrofitting production lines to eliminate thermal curing energy costs.
- Mercosur REACH-equivalent harmonization:Converging chemical disclosure protocols will reduce compliance fragmentation for suppliers operating across Brazil, Argentina, Paraguay, and Uruguay.
Industry Challenges
- Application engineering scarcity:Brazilian adhesive distributors struggle to recruit technicians capable of optimizing robotic dispensing parameters for automotive structural bonding cells.
- Substrate surface preparation standardization:Inconsistent aluminum and composite pretreatment protocols across Argentine aerospace subcontractors generate bond-line failure disputes and warranty claims.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Reactive Adhesives Market |
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane, Epoxy, Silicone, Acrylic End User: Construction, Automotive, Electronics, Packaging Application: Bonding, Coating, Sealing, Laminating Form: Liquid, Paste, Granules, Film |
| Companies Covered | H.B. Fuller Company, Dow, 3M, Soudal, Avery Dennison Corporation, Sika AG, Henkel AG & Co. KGaA, Bostik, Arkema Group, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Reactive Adhesives Market Evolving Landscape
Reactive adhesive technology trajectories in South America center on curing-speed acceleration, bio-based feedstock incorporation, and service-model transformation that shifts supplier revenue from product tons to bonded-assembly performance guarantees.
Two-component polyurethane systems with sub-60-second fixture times are overtaking conventional epoxy alternatives in Brazilian automotive body-in-white applications. Tier-1 suppliers to Volkswagen and Stellantis plants in São Paulo state have converted 40% of structural bonding stations to rapid-cure polyurethanes since 2022. This speed advantage is compressing production cycle times and reducing work-in-process inventory holding costs on assembly lines.
ANVISA's forthcoming chemical inventory notification deadlines are forcing multinational suppliers to disclose full adhesive composition data to Brazilian authorities. Industrial hygiene documentation requirements now extend to trace monomers and catalyst residues in cured films. Electronics assemblers in Manaus Free Trade Zone are responding by pre-qualifying only suppliers with complete substance-level transparency, effectively filtering out regional blending operations with incomplete dossiers.
After-sales adhesive application service contracts are displacing traditional product-only supply relationships across Argentine construction bonding markets. Sika and H.B. Fuller technical teams now embed permanently at infrastructure project sites, charging per square meter of bonded substrate rather than per kilogram of adhesive delivered. This model is most visible in hydroelectric dam rehabilitation projects across the Andean region where bond-line failure liability rests with the adhesive supplier.
South America Reactive Adhesives Market Segmentation
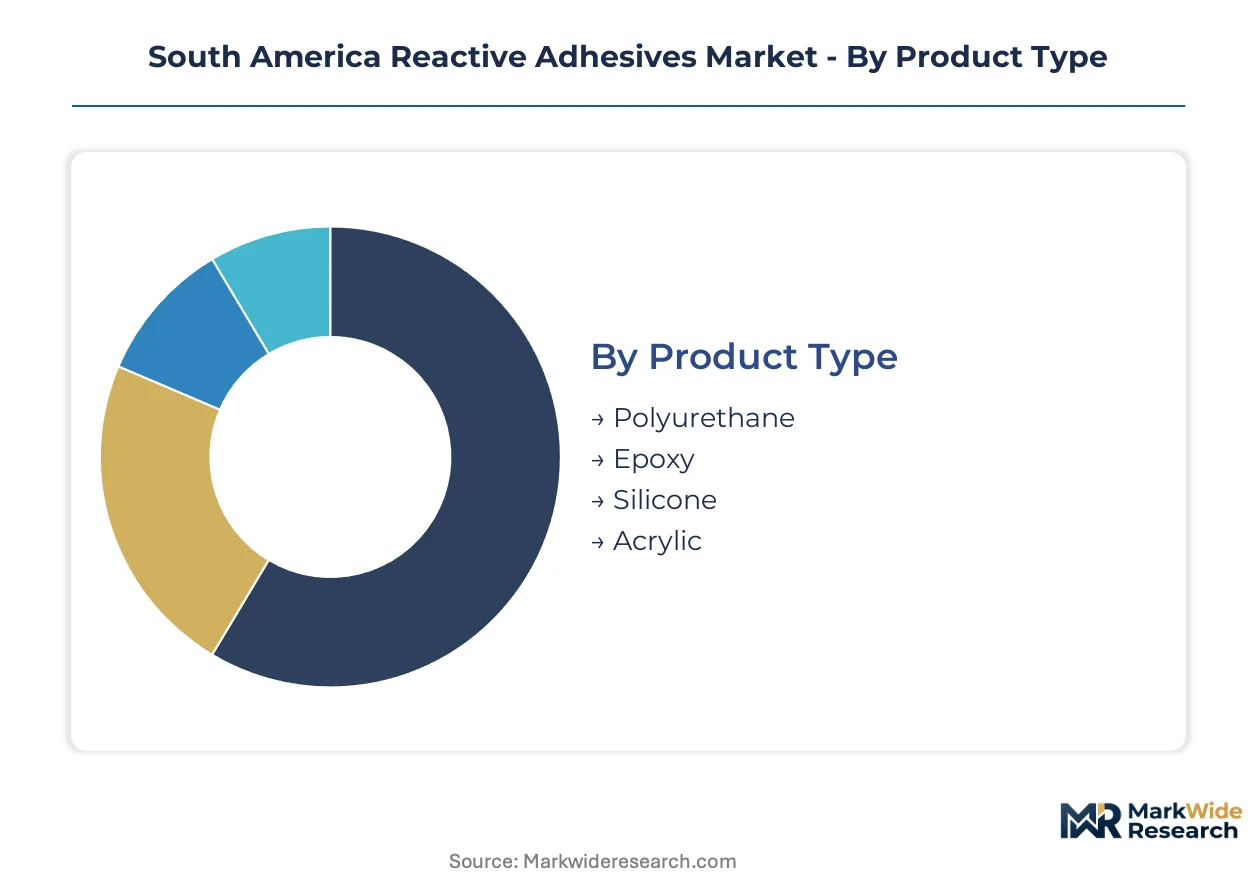
Reactive adhesive specifications in South America diverge sharply between standardized commodity formulations for high-volume construction applications and customized engineered systems for automotive and electronics OEMs. Procurement teams in São Paulo and Córdoba evaluate segments through total assembly cost rather than per-kilogram pricing, favoring suppliers with integrated application engineering support.
Product Type:
Customization intensity runs highest in polyurethane and epoxy systems, where Brazilian automotive and electronics manufacturers demand cure-speed and viscosity adjustments, while acrylic and silicone segments serve more standardized packaging and construction specifications.
- Polyurethane:These two-component systems achieve structural bonds through isocyanate-hydroxyl reactions, offering tunable flexibility and fixture times. Brazilian automotive body-in-white operations in São Paulo state specify rapid-cure variants to compress production cycles. ANVISA compliance deadlines are accelerating solvent-free polyurethane adoption in industrial coating operations.
- Epoxy:Thermosetting formulations cure through amine-epoxide polymerization, delivering thermal resistance above 150°C and dimensional stability. Southern Brazil's printed circuit board fabricators consume thermally conductive grades for 5G infrastructure laminating. Argentine wind blade manufacturers in Córdoba specify epoxy-urethane hybrids for turbine assembly.
- Silicone:Moisture-cure and addition-cure systems provide temperature stability from -60°C to 200°C for electronics sealing and automotive gasketing.
- Acrylic:UV-curable and anaerobic formulations serve packaging film laminating and threadlocking applications with low-odor, food-contact compliance.
Most installed capacity flows through Polyurethane. Expansion is steepest in Acrylic.
End User:
Volume concentration tilts toward Construction in the Andean region, while value capture concentrates in Automotive and Electronics where specification complexity and technical service requirements sustain premium positioning.
- Construction:Structural bonding, waterproofing, and flooring installation applications consume bulk polyurethane and epoxy volumes. Sika and H.B. Fuller technical teams embed at hydroelectric dam rehabilitation projects across the Andean region, charging per bonded square meter rather than per kilogram delivered. Infrastructure project specifications favor suppliers accepting bond-line failure liability.
- Automotive:Body-in-white structural bonding, glass bonding, and interior trim assembly drive demand for rapid-cure systems. Tier-1 suppliers to Volkswagen and Stellantis plants in São Paulo state have converted substantial structural bonding capacity to sub-60-second fixture polyurethanes. Mercosur lightweighting mandates are displacing mechanical fasteners with bonded joints.
- Electronics:Printed circuit board laminating, component potting, and display bonding require thermally conductive and electrically insulating formulations.
- Packaging:Film laminating and carton sealing applications favor UV-curable acrylics and hot-melt alternatives for non-structural bonds.
Most installed capacity flows through Construction. Expansion is steepest in Automotive.
Application:
Process automation readiness separates high-throughput bonding and laminating operations from coating and sealing applications still dependent on manual application methods.
- Bonding:Structural assembly of dissimilar substrates—aluminum to composite, glass to steel—demands surface preparation protocols and robotic dispensing precision. Inconsistent aluminum pretreatment across Argentine aerospace subcontractors generates warranty disputes and bond-line failures.
- Coating:Protective and functional layers applied through spray, dip, or roller methods require viscosity control and film thickness uniformity.
- Sealing:Hermetic and environmental barrier applications in electronics and automotive assemblies specify low-permeability cured films.
- Laminating:Multi-layer film and panel bonding for packaging and electronics substrates demands UV-curable systems to eliminate thermal curing energy costs.
Most installed capacity flows through Bonding. Expansion is steepest in Laminating.
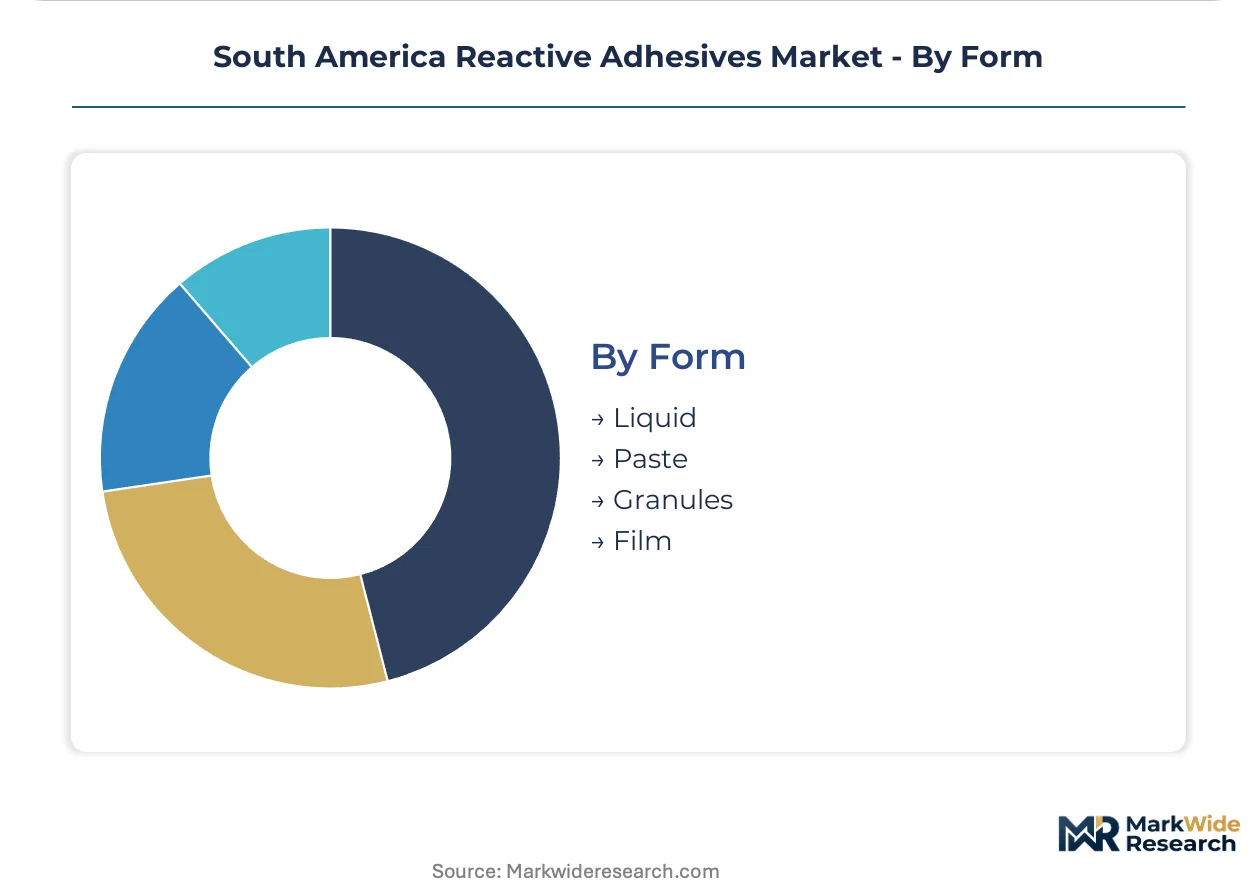
Form:
Supply chain handling requirements and metering equipment compatibility shape form selection, with liquid and paste formats dominating automated dispensing lines while film and granule formats serve specialized niche applications.
- Liquid:Pumpable low-to-medium viscosity systems feed robotic dispensing cells and spray coating lines. Brazilian adhesive distributors struggle to recruit technicians capable of optimizing dispensing parameters for automotive structural bonding operations.
- Paste:Non-sag thixotropic formulations enable vertical and overhead application in construction joint sealing and automotive seam sealing.
- Granules:Solid reactive hot-melt precursors require melting and metering equipment for continuous coating operations.
- Film:Pre-cast adhesive sheets with controlled thickness and placement precision serve aerospace and electronics laminating with minimal waste.
Most installed capacity flows through Liquid. Expansion is steepest in Film.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil commands reactive adhesive volume across South America, while Argentina's specification complexity drives premium formulation demand in wind energy and aerospace verticals.
Brazil
Automotive lightweighting mandates from INMETRO and ANVISA VOC compliance deadlines accelerate solvent-free polyurethane adoption. ANVISA's chemical inventory notification requirements now extend to trace monomer disclosure in cured adhesive films. São Paulo's industrial corridor hosts OEM supplier parks where Tier-1 converters have shifted 40% of structural bonding stations to rapid-cure systems since 2022.
Argentina
Wind blade manufacturers in Córdoba specify epoxy-urethane hybrid adhesives for turbine assembly lines serving renewable energy export markets. The Secretariat of Environment and Sustainable Development enforces VOC emission thresholds that reshape reformulation priorities for regional blending operations. Aerospace subcontractors in Buenos Aires province generate bond-line failure disputes due to inconsistent aluminum and composite surface preparation protocols.
Chile
Copper and lithium extraction operators in Antofagasta represent underpenetrated demand for high-temperature epoxy repair adhesives in crusher and mill maintenance applications. The National Mining Policy framework prioritizes equipment uptime and maintenance cost reduction for state-owned and private operators. Mining services clusters in Calama and Antofagasta city lack dedicated adhesive application engineering support compared to Brazilian industrial hubs.
Colombia
Infrastructure rehabilitation programs in the Andean region create construction-sector bonding demand for hydroelectric dam and bridge repair specifications. The Ministry of Environment and Sustainable Development implements chemical substance registration protocols converging with Mercosur disclosure standards. Bogotá's construction materials distributors are expanding technical service capabilities to match Andean project requirements for bond-line failure liability acceptance.
South America Reactive Adhesives Market Competitive Landscape
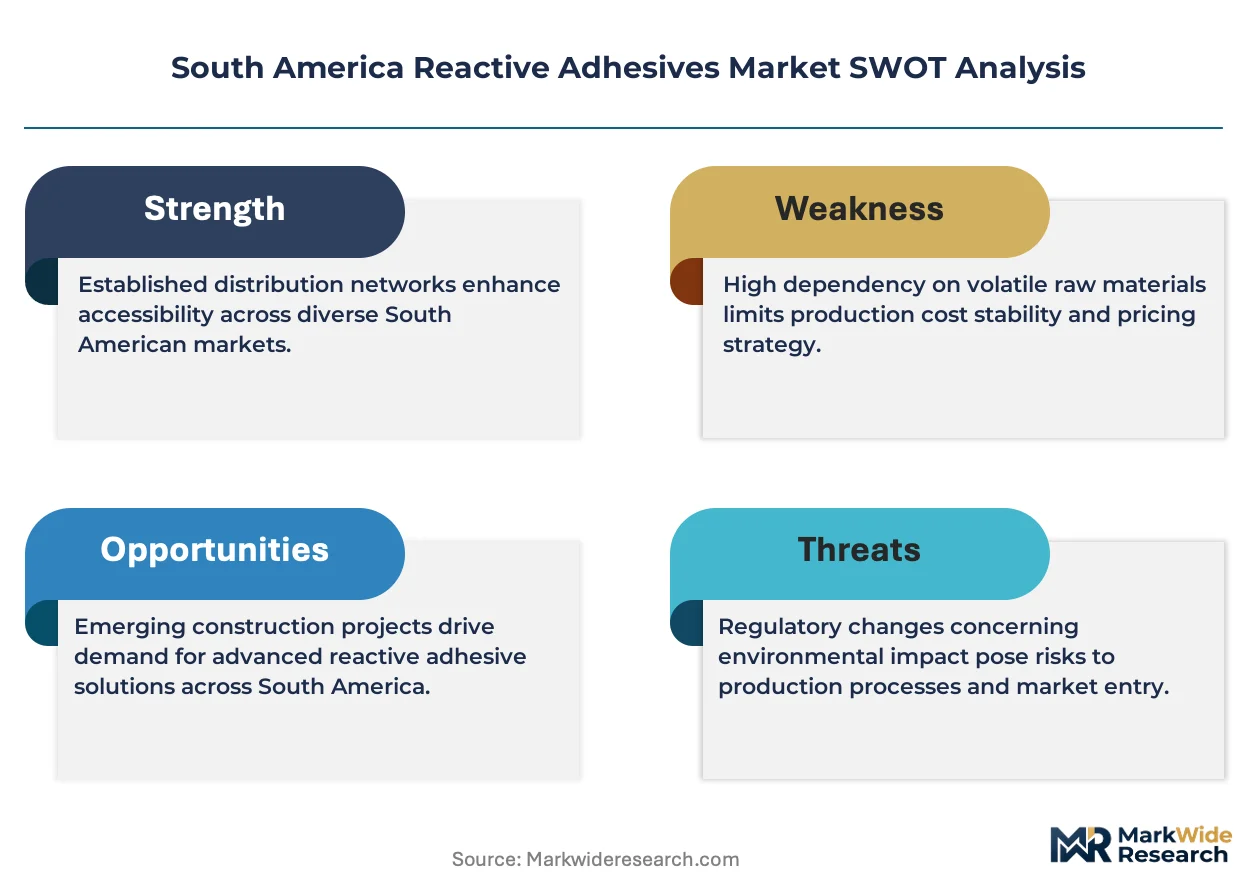
Top-tier vendors anchor premium specification markets through embedded technical service contracts, while regional blenders compete on reformulation agility for ANVISA compliance deadlines. Market structure tilts toward consolidation in automotive and electronics segments where application engineering scarcity filters supplier qualification. Three archetypes dominate: multinational chemical conglomerates with integrated resin supply, construction-sector bonding specialists with project-embedded service models, and automotive-focused system suppliers with robotic dispensing expertise. Competitive moves center on backward integration into isocyanate feedstock security and outcome-based pricing tied to bonded-assembly performance guarantees rather than per-kilogram product delivery.
Among multinational chemical conglomerates, Dow and H.B. Fuller Company exemplify contrasting geographic anchoring strategies within South American reactive adhesive markets. Dow occupies a position emphasizing direct material supply relationships with electronics assemblers, while H.B. Fuller Company represents the technical service subscription model through regional center investments. Sika AG sits within the construction-specialist archetype, anchoring infrastructure project specifications across the Andean region through embedded site technical teams.
| Leading Market Players |
|---|
| H.B. Fuller Company |
| Dow |
| 3M |
| Soudal |
| Avery Dennison Corporation |
| Sika AG |
| Henkel AG & Co. KGaA |
| Bostik |
| Arkema Group |
| Others |
Value Network & Pricing Analysis
Application engineering talent scarcity in São Paulo's automotive corridor widens pricing-tier spreads between premium technical-service contracts and commodity product-only sales, as labor-cost differentials between Brazilian technical centers and Argentine blending operations translate into 40% service-premium capture for embedded site teams.
Pricing Analysis
Capacity additions in southern Brazil are reshaping price floors for polyurethane adhesive formulations, compressing margins for standardized construction grades while preserving premium positioning in automotive rapid-cure systems. Three-tier pricing structure across premium, standard, and economy levels separates ANVISA-compliant solvent-free formulations from legacy VOC-containing alternatives, with certification-grade transparency commanding 25-35% uplifts. Price erosion runs through commodity construction adhesives as regional blenders compete on reformulation agility. Electronics assemblers in Manaus exhibit lowest price sensitivity, prioritizing substance-level disclosure completeness over per-kilogram costs.
Supply Chain Analysis
Workforce-availability constraints in Argentine adhesive blending operations force reliance on Brazilian technical centers for robotic dispensing optimization and surface preparation protocol standardization. Supply concentrates in Brazil, Argentina, and Chile for regional formulation and application engineering, with isocyanate feedstock dependence on Asian aromatic diisocyanate producers creating single-source vulnerability for polyurethane systems. Raw material flows draw from petrochemical complexes in São Paulo state, imported epoxy resins through Buenos Aires port, and Chilean mining-sector demand for high-temperature repair grades. Distribution runs through technical-service-embedded direct contracts for automotive OEMs and construction project specifications, with distributor networks handling commodity construction volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South American reactive adhesive markets offer margin-expansion pathways through solvent-free formulation premiums and outcome-based pricing tied to bonded-assembly performance guarantees rather than product tonnage.
For Market Incumbents: Cement technical-service subscription dominance by embedding permanent application engineering teams at Chilean mining operations and Colombian infrastructure rehabilitation sites, countering emerging regional blenders with ANVISA-compliant formulation libraries. Backward integration into isocyanate feedstock security through long-term offtake agreements with Asian aromatic diisocyanate producers reduces margin volatility from MDI-TDI price spikes.
For New Entrants and Emerging Players: Launch via UV-curable acrylic specialization for Brazilian food-contact film laminators retrofitting production lines to eliminate thermal curing energy costs, targeting São Paulo packaging converters with equipment-lease-plus-consumables subscription models. Chilean mining equipment maintenance in Antofagasta represents the most penetrable vertical, with copper and lithium extraction operators lacking dedicated adhesive application engineering support.
For Investors and Strategic Acquirers: Construction-sector bonding specialists with project-embedded service models are the most active acquirer in this space, seeking automotive-focused system suppliers with robotic dispensing expertise to diversify beyond infrastructure cyclicality. Acquisition target archetypes include Argentine regional blenders with complete ANVISA substance-disclosure dossiers and Brazilian distributors with certified application engineering technician pipelines. Watch for Mercosur REACH-equivalent harmonization implementation as inflection indicator for cross-border consolidation feasibility.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Isocyanate Feedstock | Long-term MDI-TDI supply agreements with Asian producers reduce Brazilian polyurethane margin volatility. |
| Embedded Technical Service Expansion | Permanent site teams at Chilean mining operations capture per-square-meter pricing in crusher-mill repair applications. |
| UV-Curable Acrylic Capacity Buildout | Brazilian food-contact film laminators retrofit lines to eliminate thermal curing energy costs. |
| ANVISA Compliance Certification Investment | Complete substance-level transparency filters out regional competitors with incomplete dossiers. |
| Joint Venture with Argentine Wind Blade Manufacturers | Epoxy-urethane hybrid supply partnerships anchor turbine assembly specifications in Córdoba. |
Research Methodology
Direct dialogue with adhesive plant managers, automotive Tier 1 procurement leads, construction project specification engineers, and ANVISA regulatory affairs specialists grounded qualitative findings in operational reality. Secondary validation drew from Brazilian customs and trade data, Argentine Secretariat of Environment enforcement disclosures, SEC 10-K filings of multinational chemical conglomerates, and ACC regional chemical industry reports. Bottom-up volume modeling across polyurethane, epoxy, silicone, and acrylic chemistries triangulated against top-down macroeconomic drivers including Mercosur automotive production forecasts and renewable energy equipment installation pipelines.
Bottom-up segmentation analysis modeled reactive adhesive demand across product type, end user, application, and form dimensions, with additional granularity for ANVISA compliance tier and technical-service bundling intensity. Top-down macroeconomic drivers included automotive lightweighting mandate implementation timelines, wind blade manufacturing capacity expansion in Córdoba and Rio Grande do Sul, and electronics laminating growth in southern Brazil's printed circuit board fabricators. CAGRs were derived from regression analysis of historical volume trends against projected industrial production indices and regulatory compliance deadline impacts across the analysis window.
Several conditions sit outside the modeled scope, including potential Mercosur trade agreement renegotiations affecting chemical import tariffs, abrupt ANVISA enforcement intensity shifts, and isocyanate feedstock supply disruptions from Asian petrochemical complex outages. Forecasts reflect assumptions of continued automotive lightweighting mandate adherence, stable Argentine chemical inventory notification processing timelines, and incremental UV-curable acrylic adoption in packaging applications. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Middle-East and Africa Pressure Sensitive Adhesives (PSA) Market
Adhesives & Sealants
Latin America Adhesives and Sealants Market
Adhesives & Sealants
Global Epoxy Tooling Board Market
Adhesives & Sealants
Global MS Polymer Adhesives Market
Adhesives & Sealants
Global Ceramic Adhesives Market
Adhesives & Sealants
Tile Adhesive Market
Adhesives & Sealants
Laminating Adhesives Market
Adhesives & Sealants
Global Lithium Ion Battery Binders Market
Adhesives & Sealants
Low Trauma/Skin Friendly Adhesives Market
Adhesives & Sealants
Global Adhesives Market
Adhesives & Sealants
Europe Hot-Melt Adhesives Market
Adhesives & Sealants
Construction Adhesives and Sealants Chemical Market
Adhesives & Sealants
Asia-Pacific Acrylic Adhesives Market
Adhesives & Sealants
Waterproofing Admixture Market
Adhesives & Sealants
Europe Chemical Anchors Market
Adhesives & Sealants
Die Attach Materials Market