
 South Africa Plastic Packaging Films Market | 2026-2036
South Africa Plastic Packaging Films Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Plastic Packaging Films Market Insights
Capital-intensity divergence between players is bifurcating the competitive landscape across South Africa's plastic packaging films sector. Mondi PLC leverages its integrated pulp-to-film operations in Richards Bay to sustain cost advantages in barrier film supply. Amcor Group GmbH anchors its position through specialized healthcare-grade sterilizable films, while Mpact Group competes via recycled-content polyethylene lines serving major South African retailers.
Plastic packaging films comprise extruded or cast polymer sheets, typically ranging from 12 to 150 microns in thickness, engineered for containment, preservation, and unitization of goods across supply chains. These substrates employ multi-layer coextrusion or surface coating to achieve oxygen transmission rates below 1 cc/m²/day for sensitive product categories. Stretch films dominate volume throughput in the industrial segment, reflecting palletization demand from South Africa's logistics-intensive mining and agricultural export sectors. Barrier films command premium positioning in food and healthcare applications, where ethylene vinyl alcohol copolymers and metallized polypropylene extend shelf stability against humidity and oxidation.
South Africa's National Regulator for Compulsory Specifications enforces polymer quality benchmarks under SABS standards, while the Department of Forestry, Fisheries and the Environment implements extended producer responsibility frameworks that mandate post-consumer collection targets for flexible packaging. The country's central bank monitors import parity pricing for resin feedstocks, indirectly shaping converter margins when rand volatility disrupts polyethylene import costs. Stakeholders must track regulatory enforcement timelines for recycled-content mandates and assess localized resin compounding investments that could redraw cost structures across the value chain.
Market Dynamics
South Africa's plastic packaging films sector is undergoing structural recalibration as extended producer responsibility regulations force converters to redesign material architectures and absorb collection infrastructure costs. The Department of Forestry, Fisheries and the Environment mandates are redirecting capital from capacity expansion toward recycling-compatible mono-material development.
Growth Catalysts
- Extended Producer Responsibility Regulations:The Department of Forestry, Fisheries and the Environment frameworks mandate post-consumer collection targets, compelling investment in recyclable film architectures and domestic recycling infrastructure.
- Food and Beverage Consumption:Rising packaged food demand across Gauteng and KwaZulu-Natal manufacturing corridors is expanding stretch film and barrier film volumes for palletization and shelf-life extension.
- Mono-Material Coextrusion:Advances in polyethylene-polypropylene compatible layer bonding are enabling full-film recyclability without performance degradation in oxygen barrier applications.
Market Restraints
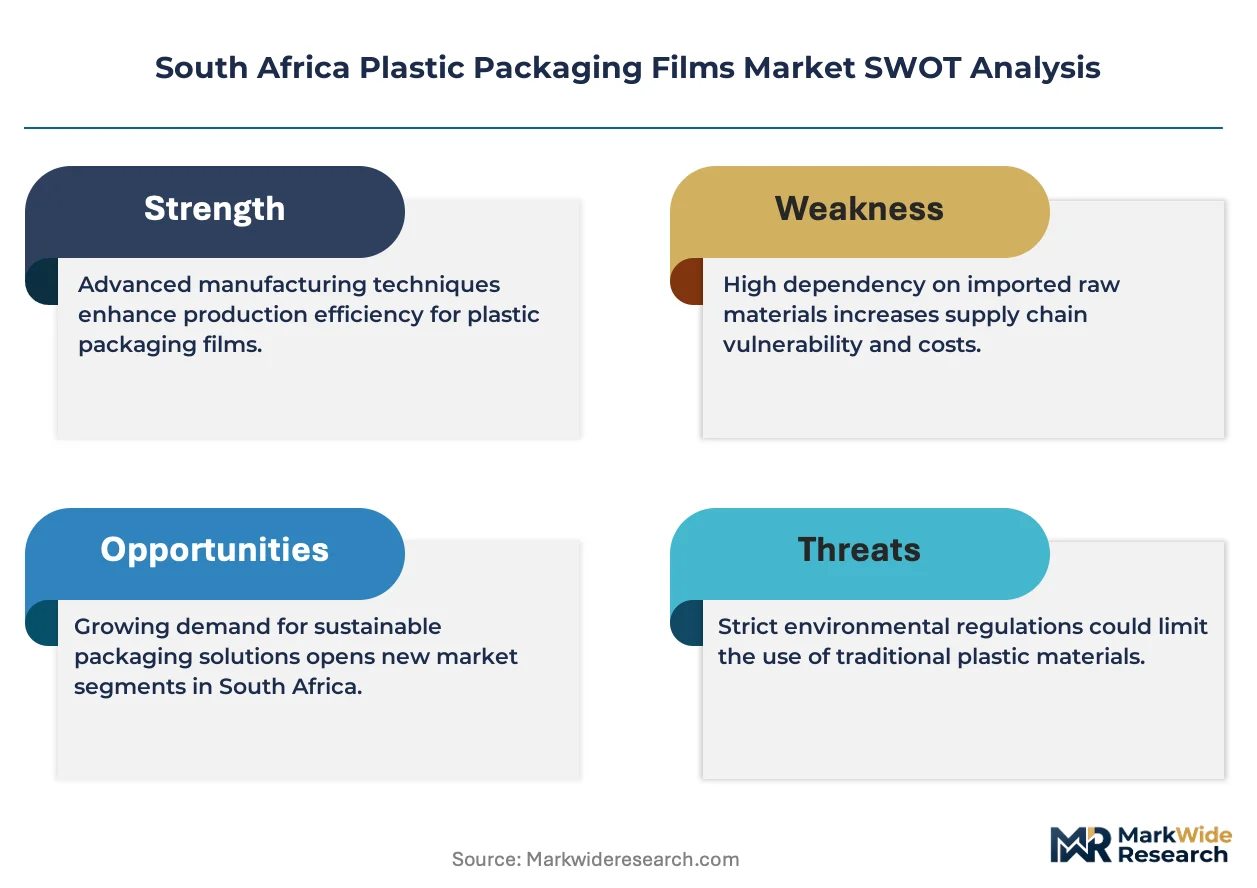
- Resin Import Parity Volatility:South African Reserve Bank monitoring of rand-denominated polyethylene import costs exposes converters to margin compression when currency weakness coincides with global resin price spikes.
- Mechanical Recycling Contamination Limits:Current South African sorting infrastructure cannot process multi-material laminates at scale, rendering historical barrier film investments stranded.
- Competing Rigid Packaging Substitution:Returnable glass bottle systems in premium beverage segments and fiber-based molded pulp in fresh produce are capturing share from flexible films.
Strategic Opportunities
- Chemical Recycling Infrastructure:Pyrolysis and depolymerization investments in the Durban-Richards Bay industrial corridor could unlock processing of contaminated flexible films currently rejected by mechanical recyclers.
- Healthcare Sterilizable Films:Specialized ethylene oxide and gamma-radiation compatible barrier films for pharmaceutical and medical device packaging remain underdeveloped relative to food-sector capacity.
- Digital Watermarking Integration:HolyGrail 2.0-compatible marker technologies enable automated sortation of food-contact films at municipal recovery facilities, improving post-consumer feedstock quality.
Industry Challenges
- Polymer Compounding Expertise Scarcity:Local shortage of technicians trained in recycled-content resin formulation and rheology control limits converter ability to meet mandated recycled-content thresholds.
- Retrofitting Coextrusion Lines:Existing seven-layer and nine-layer equipment requires substantial capital modification to process high percentages of post-consumer recycled polyethylene without gauge variability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Plastic Packaging Films Market |
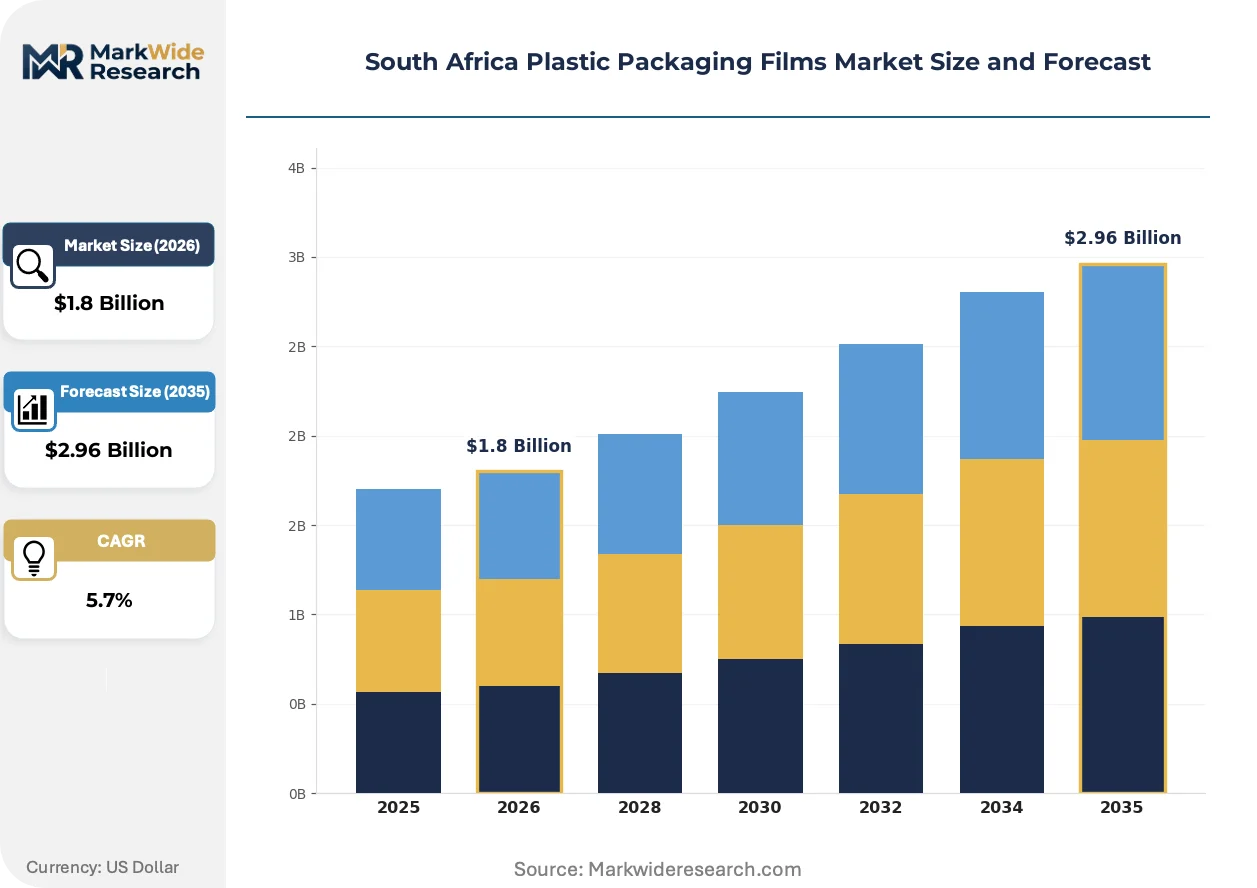
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stretch Films, Shrink Films, Barrier Films, Decorative Films Material: Polyethylene, Polypropylene, PVC, Biodegradable End User: Food & Beverage, Healthcare, Consumer Goods, Industrial Application: Retort Packaging, Shrink Wrapping, Vacuum Packaging, Surface Protection |
| Companies Covered | Berry Global Inc., AVPack Plastic Manufacturers, Amcor Group GmbH, Mpact Group, Nampak Ltd., RPC Astrapak Ltd., Constantia Flexibles Corporation, Mondi PLC, UFlex Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Plastic Packaging Films Market Trends and Innovations
Material science advances and regulatory compliance pressures are converging to reshape substrate selection and manufacturing processes across South African flexible packaging. Converter investment priorities are pivoting from throughput maximization toward circularity-compatible design.
Mono-material barrier architectures are fragmenting traditional multi-layer laminate dominance in South African food packaging. Retailers including Shoprite and Pick n Pay are accelerating specifications for polyethylene-only structures in fresh produce and bakery applications. This transition is fragmenting established supply relationships as converters without coextrusion modification capability lose preferred supplier status.
The Department of Forestry, Fisheries and the Environment's extended producer responsibility regulations are mandating post-consumer collection and recycling targets for flexible packaging producers. Compliance requires film producers to fund or operate collection infrastructure, reshaping cost structures and competitive positioning. Small and mid-sized converters without balance sheet capacity for vertical integration into recycling are consolidating or exiting.
Buyer concentration among South African retail chains is compressing supplier negotiation cycles and unbundling technical service from base film supply. Procurement teams at major retailers are implementing centralized category management for flexible packaging, replacing fragmented regional purchasing. This shift is most visible in the Johannesburg-Pretoria corridor where retail headquarters proximity enables direct converter relationships without distributor intermediation.
South Africa Plastic Packaging Films Market Segmentation
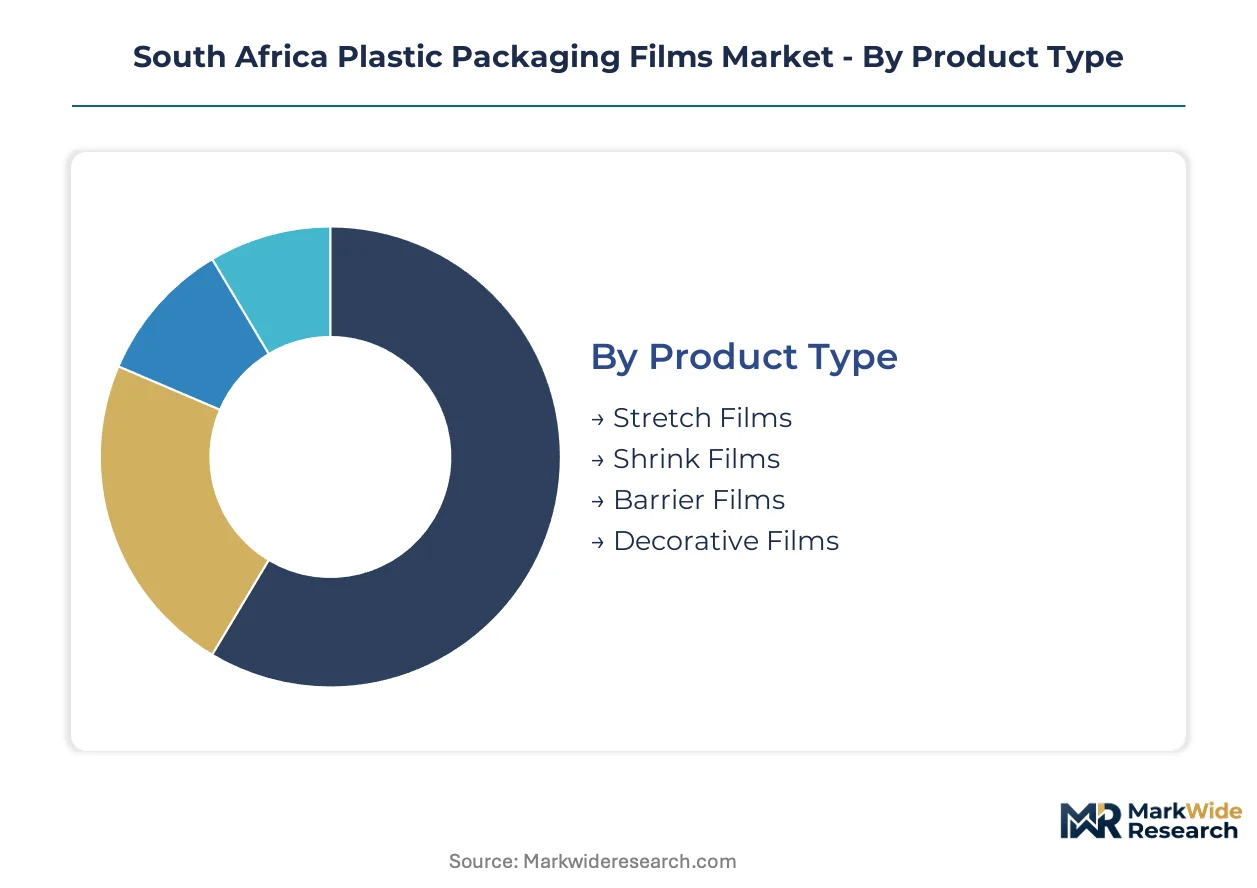
Segmentation in South Africa's plastic packaging films market reveals how converter capabilities and buyer requirements diverge across material specifications and end-use performance standards. Understanding these splits exposes where capital is concentrating and which substrate innovations are capturing procurement attention.
Product Type:
Channel flows differ sharply by product type, with stretch films moving primarily through industrial distributors serving logistics operators while barrier films route directly to food manufacturers under long-term supply agreements.
- Stretch Films:Linear low-density polyethylene formulations with 17-23 micron gauges dominate palletization applications. Demand concentrates in Johannesburg-Pretoria logistics corridors serving mining and agricultural export sectors where automated wrapping systems require consistent cling and puncture resistance.
- Barrier Films:Multi-layer coextrusions incorporating ethylene vinyl alcohol or metallized polypropylene achieve oxygen transmission rates below 1 cc/m²/day. Premium positioning in processed meat and cheese packaging drives specification by Shoprite and Pick n Pay private label suppliers.
- Shrink Films:Biaxially oriented polypropylene or polyethylene terephthalate glycol structures provide 40-70% shrinkage ratios for retail-ready multipacks.
- Decorative Films:Printed and metallized variants serve gift wrap and promotional packaging with shorter production runs.
By volume, stretch films lead. By growth pace, barrier films are climbing the fastest as shelf-life extension requirements intensify.
Material:
Cost tier stratification separates commodity polyethylene grades from specialty biodegradable alternatives, with converter investment capacity determining which material classes are accessible.
- Polyethylene:Low-density and linear low-density grades constitute the substrate backbone for 60% of flexible packaging output. Richards Bay resin compounding operations supply Gauteng converters with feedstock for stretch film and basic barrier applications.
- Polypropylene:Cast and oriented variants deliver higher temperature resistance for retort pouches and microwaveable structures. KwaZulu-Natal food processors specify biaxially oriented polypropylene for snack packaging clarity and moisture barrier performance.
- Biodegradable:Polylactic acid and starch-based blends address retailer sustainability mandates but face cost premiums of 40-60% over conventional polymers.
- PVC:Rigid and semi-rigid calendered films persist in pharmaceutical blister packs despite environmental scrutiny.
Polyethylene dominates tonnage throughput. Polypropylene is gaining share fastest in premium food packaging.
End User:
Customer type determines specification complexity, with healthcare and food sectors demanding certified barrier performance while industrial buyers prioritize unit cost and throughput reliability.
- Food & Beverage:Modified atmosphere packaging and vacuum structures extend shelf life for fresh produce, meat, and dairy distributed through Shoprite and Woolworths supply chains. Extended producer responsibility regulations mandate recyclable mono-material designs for private label programs.
- Healthcare:Sterilizable barrier films for medical devices and pharmaceutical packaging require ethylene oxide and gamma radiation compatibility. This segment commands 25-35% price premiums over food-grade equivalents.
- Consumer Goods:Printed laminates for personal care and household products emphasize shelf appeal and tamper evidence.
- Industrial:Heavy-duty polyethylene sheeting and construction-grade surface protection films serve mining equipment and building material suppliers.
Food and beverage generates the highest absolute volume. Healthcare is expanding most quickly as domestic pharmaceutical manufacturing scales.
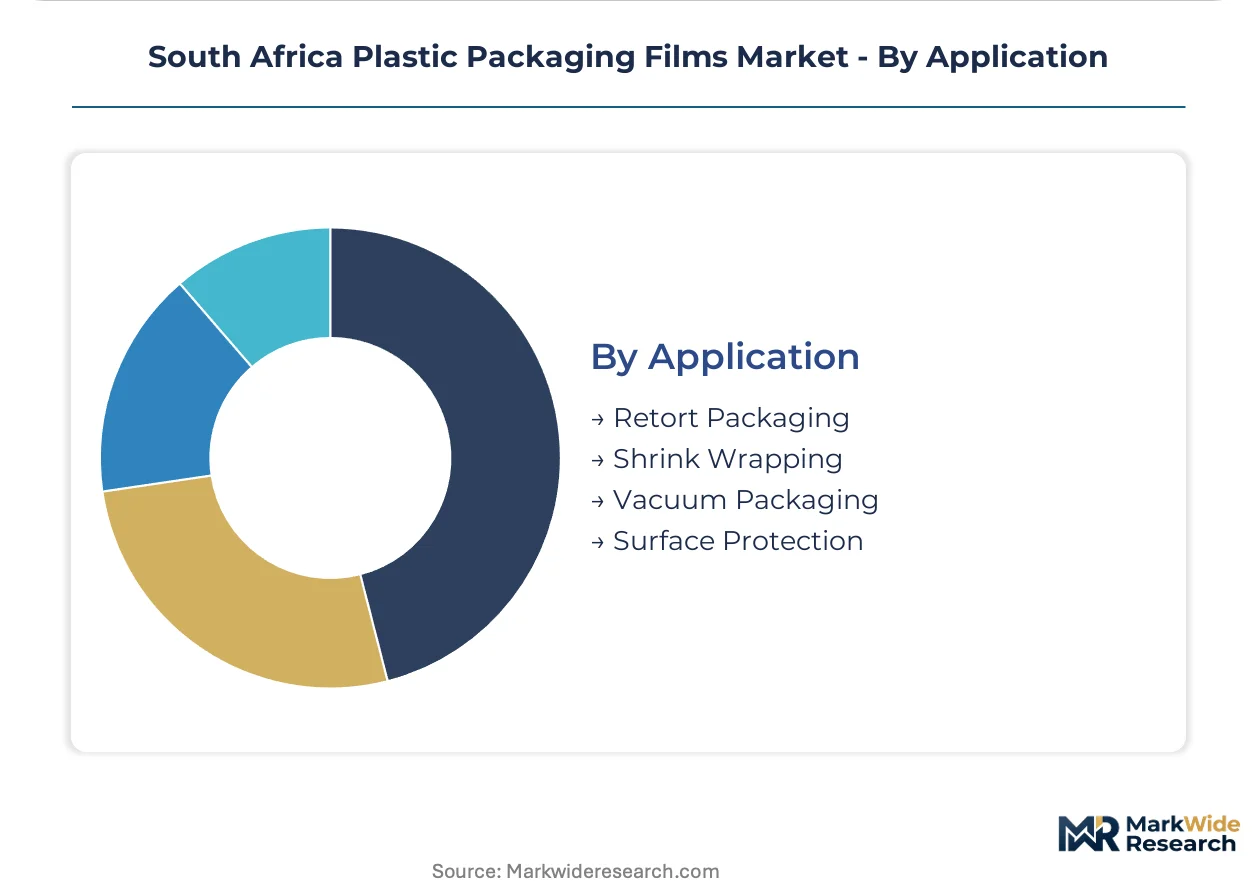
Application:
Application maturity varies, with shrink wrapping and surface protection representing established processes while retort-compatible flexible structures require advanced coextrusion expertise.
- Retort Packaging:Four-layer coextrusions withstand 121°C sterilization temperatures for ready-meal pouches. Local converter capability gaps force reliance on imported pre-made pouches for premium pet food and prepared meal segments.
- Vacuum Packaging:Thermoforming bottom webs and flexible top webs with controlled oxygen permeability preserve fresh meat and processed cheese. KwaZulu-Natal red meat processors drive specification for high-barrier nylon-polyethylene structures.
- Shrink Wrapping:Heat-activated films bundle multipacks for beverage and personal care distribution.
- Surface Protection:Temporary adhesive films guard automotive panels and appliance finishes during assembly and transit.
Shrink wrapping leads by installed equipment base. Retort packaging shows the steepest expansion trajectory as convenience food demand accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Africa's plastic packaging films trade flows reflect a net import position for specialized barrier substrates, while commodity-grade polyethylene films sustain domestic surplus. The Johannesburg-Pretoria corridor anchors converter capacity, with KwaZulu-Natal's Richards Bay complex supplying resin feedstock. Sub-regional specialization patterns concentrate high-performance film demand in Gauteng's retail headquarters cluster.
Gauteng Province
Stretch film consumption from mining logistics and agricultural export palletization drives volume demand. The Department of Forestry, Fisheries and the Environment enforces extended producer responsibility collection targets that converters must fund through packaging fees. Johannesburg-Pretoria industrial belt hosts the densest converter-to-retailer proximity, enabling direct supply relationships with Shoprite and Pick n Pay procurement centers.
KwaZulu-Natal
Barrier film specifications for processed meat and dairy packaging concentrate in Durban's food processing zone. Mondi PLC's Richards Bay integrated pulp-to-film complex supplies substrate to regional converters. The Durban-Richards Bay industrial corridor attracts chemical recycling infrastructure investment targeting contaminated flexible films rejected by mechanical recyclers.
Western Cape
Wine industry export packaging and fresh produce distribution sustain shrink film and modified atmosphere packaging demand. The Western Cape provincial government coordinates industrial symbiosis programs linking converter waste streams to recycling aggregators. Cape Town's port logistics infrastructure positions the region as a secondary distribution node for imported specialty films.
Eastern Cape
Automotive component manufacturing in Nelson Mandela Bay Metro generates surface protection film requirements for vehicle panel transit. The Eastern Cape Development Corporation incentivizes packaging sector investment through manufacturing competitiveness grants. Port Elizabeth's automotive export terminals drive specification for heavy-duty polyethylene sheeting in supply chain unitization.
South Africa Plastic Packaging Films Market Competitive Landscape
Concentration sits with diversified packaging conglomerates and regional film specialists. Three-tier structure separates integrated resin-to-film operators from converter-only specialists and import-dependent distributors. Strategic archetypes include backward-integrated pulp-based substrate producers, recycled-content polyethylene specialists, and healthcare-grade sterilizable film providers. Dominant competitive moves span coextrusion line retrofitting for mono-material compatibility and captive collection infrastructure buildout to satisfy extended producer responsibility mandates.
Among South Africa-based converters, Mpact Group and Nampak Ltd. occupy positions within the recycled-content and rigid-flexible hybrid segments respectively. Mondi PLC and Amcor Group GmbH anchor the integrated multinational tier. Berry Global Inc. represents the global diversified packaging archetype with regional presence through distribution partnerships. AVPack Plastic Manufacturers exemplifies mid-scale domestic specialists competing on converter service proximity to Gauteng retail headquarters.
| Leading Market Players |
|---|
| Berry Global Inc. |
| AVPack Plastic Manufacturers |
| Amcor Group GmbH |
| Mpact Group |
| Nampak Ltd. |
| RPC Astrapak Ltd. |
| Constantia Flexibles Corporation |
| Mondi PLC |
| UFlex Limited |
| Others |
Pricing and Supply Chain Analysis
Integrated resin-to-film operations in Richards Bay establish scale thresholds that smaller Gauteng converters cannot match, compressing price floors for commodity polyethylene grades while creating premium capture zones for barrier film specialists. The Department of Forestry, Fisheries and the Environment extended producer responsibility fees now embed collection infrastructure costs directly into converter pricing models, altering competitive positioning across substrate tiers.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake structure with volume-scale and certification-level differentiation driving spreads between standard and healthcare-grade films. Price differentiation stems from SABS compliance tier and vertical integration depth, with integrated producers commanding 15-20 point spreads over import-dependent distributors. Cost compression in stretch film tiers is intensifying because Shoprite and Pick n Pay procurement consolidation extracts volume concessions. Small-to-mid converters exhibit highest price sensitivity, while pharmaceutical sterilizable film buyers accept premiums for ethylene oxide compatibility.
Supply Chain Analysis
Just-in-time resin stocking dominates converter behavior given rand volatility exposure, though strategic polyethylene pellet stockpiling emerges among integrated operators with Richards Bay storage capacity. Supply concentrates in Saudi Arabia, Qatar, and the United States for high-density polyethylene feedstock, while domestic compounding draws from Richards Bay naphtha crackers and imported LLDPE. Raw material dependencies rest on ethylene monomer, metallocene catalysts, and EVOH barrier resins. Single-source vulnerability runs through Middle Eastern petrochemical export terminals. Distribution runs through Johannesburg-Pretoria industrial distributors for stretch films and direct converter relationships for barrier specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized polymer compounding expertise and chemical recycling infrastructure represent acute capability gaps that will determine which converters survive extended producer responsibility compliance mandates. Technical talent scarcity in recycled-content resin formulation is already forcing consolidation among mid-scale operators.
For Market Incumbents: Fortify backward integration into mechanical recycling infrastructure to capture post-consumer polyethylene feedstock before competitors lock supply agreements. Invest in coextrusion line retrofitting for mono-material compatibility to defend preferred supplier status against emerging recycled-content specialists. The Department of Forestry, Fisheries and the Environment collection target escalations threaten margin position for converters without captive recovery operations. For New Entrants and Emerging Players: Lead with healthcare sterilizable film capacity targeting domestic pharmaceutical manufacturing expansion, as this segment remains underdeveloped relative to food-sector saturation. Chemical recycling infrastructure in the Durban-Richards Bay corridor offers white-space entry with pyrolysis technology licensing from European technology providers. Direct technical service relationships with Gauteng pharmaceutical OEMs provide the most penetrable go-to-market angle. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors converters with installed coextrusion assets capable of mono-material barrier migration without greenfield capital deployment. Long-term viability hinges on regulatory compliance infrastructure ownership rather than throughput scale alone. Acquisition targets should exhibit established retailer-approved supplier status and demonstrated recycled-content formulation capability. The signal to watch is Department of Forestry, Fisheries and the Environment enforcement intensity for post-consumer collection targets.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Coextrusion Retrofit | Enables SABS-compliant recyclability for Shoprite and Pick n Pay private label specifications. |
| Chemical Recycling Infrastructure Buildout | Unlocks processing of contaminated flexible films rejected by Durban mechanical recyclers. |
| Healthcare Sterilizable Film Capacity Addition | Captures 25-35% price premiums from domestic pharmaceutical manufacturing expansion. |
| Captive Collection Infrastructure Integration | Satisfies extended producer responsibility mandates without third-party dependency. |
| Recycled-Content Resin Compounding Investment | Addresses polymer rheology expertise scarcity limiting converter compliance capability. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across converter technical directors, retail procurement managers at Shoprite and Pick n Pay, resin compounding plant managers, and Department of Forestry, Fisheries and the Environment regulatory officers. Secondary validation drew from SABS standards documentation, South African Reserve Bank import parity data, customs polyethylene trade records, and extended producer responsibility compliance filings. Bottom-up volume modeling triangulated against top-down resin consumption estimates from Richards Bay industrial sources.
Across the projection horizon, the analytical framework segmented by material substrate, end-use application, and geographic manufacturing corridor. Modeled dimensions included product type, material grade tier, and converter scale category. CAGRs derived from elasticity-adjusted demand projections across food and beverage consumption growth, healthcare manufacturing expansion, and mining logistics intensity. Industry-specific inputs incorporated rand-denominated resin import cost volatility and retailer sustainability specification timelines.
The analysis sits within stated boundaries; outcomes outside sustained rand stability or accelerated extended producer responsibility enforcement would require recalibration. Forecasts reflect documented assumptions regarding mono-material adoption rates and chemical recycling infrastructure commissioning. Revision becomes warranted when Department of Forestry, Fisheries and the Environment collection target stringency crosses thresholds that strand multi-layer laminate capacity investments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Philippines Plastics Market
Plastic Packaging
Malaysia and Thailand Thermoformed Plastic Market
Plastic Packaging
US Plastic Packaging Market
Plastic Packaging
HDPE Jug Market
Plastic Packaging
China Plastic Bottles Market
Plastic Packaging
PET Preforms Market
Plastic Packaging
Plastic Aerosol Packaging Market
Plastic Packaging
China Plastic Packaging Market
Plastic Packaging
Poland Plastic Packaging Tubes Market
Plastic Packaging
Plastic-Based Egg Packaging Market
Plastic Packaging
Polyethylene Corrugated Packaging Market
Plastic Packaging
Europe Plastic Packaging Market
Plastic Packaging
South Africa Flexible Packaging Market
Plastic Packaging
Blow Molded Plastic Bottles Market
Plastic Packaging
Global Micro Injection Molded Plastic Market
Plastic Packaging
Global Plastic Packaging Sacks Market