
 Industrial Radioactive Source Market | 2026-2036
Industrial Radioactive Source Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Radioactive Source Market Insights
Digital source monitoring and blockchain-enabled chain-of-custody tracking is reconfiguring how industrial radioactive sources are authenticated, transported, and retired across the supply chain. Thermo Fisher Scientific Inc. leverages its analytical instrument installed base to bundle source services with detection hardware. Eckert & Ziegler Strahlen- und Medizintechnik AG anchors European supply through vertically integrated isotope production and specialized logistics networks. QSA Global, Inc. competes in radiography services by controlling a dense North American branch network for source deployment and recovery.
Industrial radioactive sources are sealed capsules containing radionuclides such as cobalt-60, iridium-192, or americium-241, engineered to emit controlled gamma, beta, or neutron radiation for material interrogation, thickness gauging, and sterilization processes. The primary commercial purpose is to deliver non-destructive, high-penetration energy for quality assurance in manufacturing and infrastructure without consuming the source material. Radiography Sources command durable demand from pipeline and weld inspection contractors, while Calibration Sources concentrate margin pools through NIST-traceable certification requirements. Medical Isotopes represent the fastest-expanding category as diagnostic radioisotope shortages drive investment in cyclotron and reactor production capacity.
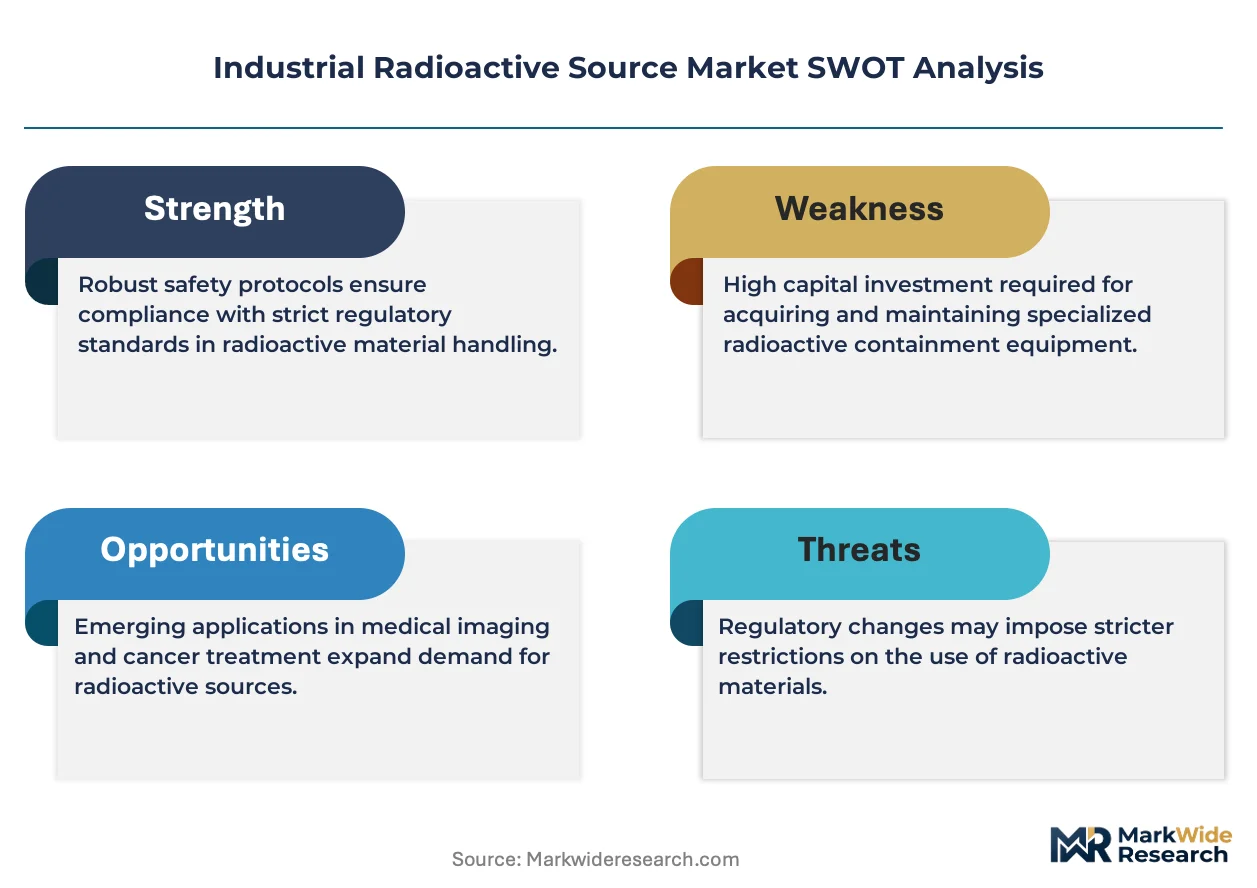
The IAEA Code of Conduct on the Safety and Security of Radioactive Sources shapes inventory accountability and cross-border transfer protocols for suppliers operating across multiple jurisdictions. EPA and NRC regulations in the United States mandate specific source encapsulation standards and disposal pathways that elevate compliance costs for market entrants. EAEA and national regulators across Europe enforce dual-use export controls that restrict technology transfer to certain end users. Stakeholders must weigh source substitution risks against the capital intensity of alternative technologies such as X-ray linear accelerators when planning long-term supply commitments.
Market Dynamics
Digital source authentication protocols and blockchain-enabled chain-of-custody systems are reconfiguring how sealed sources move through supply networks, compressing verification timelines and elevating compliance costs for facilities lacking integrated tracking infrastructure.
Growth Catalysts
- IAEA Code of Conduct mandates:Stricter inventory accountability requirements are compelling utilities and manufacturers to upgrade to certified sealed sources with embedded tamper-evident features.
- Pipeline integrity programs:Energy sector operators are expanding non-destructive testing deployments for weld inspection and corrosion monitoring across transmission infrastructure.
- Cyclotron capacity expansion:Diagnostic radioisotope shortages are driving investment in distributed production facilities to reduce supply chain concentration.
Market Restraints
- High-purity cobalt-60 supply concentration:Reactor-dependent production creates vulnerability to outages at limited irradiation facilities.
- NRC encapsulation standards:EPA-mandated disposal pathways and specific containment specifications elevate capital barriers for new market entrants.
- X-ray linear accelerator substitution:Non-isotope alternatives are capturing share in thickness gauging applications where penetration requirements permit.
Strategic Opportunities
- Southern Africa production hubs:Concentrated demand for industrial radiography sources remains underserved by regional manufacturing capacity.
- Medical isotope diversification:Therapeutic radioisotope applications are opening adjacent revenue streams beyond traditional industrial segments.
- Digital twin integration:Convergence of source monitoring systems with predictive maintenance platforms creates value-added service potential.
Industry Challenges
- Radiation safety officer certification timelines:Extended training requirements and examination backlogs constrain workforce scaling.
- Legacy source recovery logistics:Decommissioned capsule retrieval and transport coordination demand specialized handling infrastructure.
- Cross-border transfer documentation:Dual-use export control variations between jurisdictions create compliance complexity for multi-facility operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Radioactive Source Market |
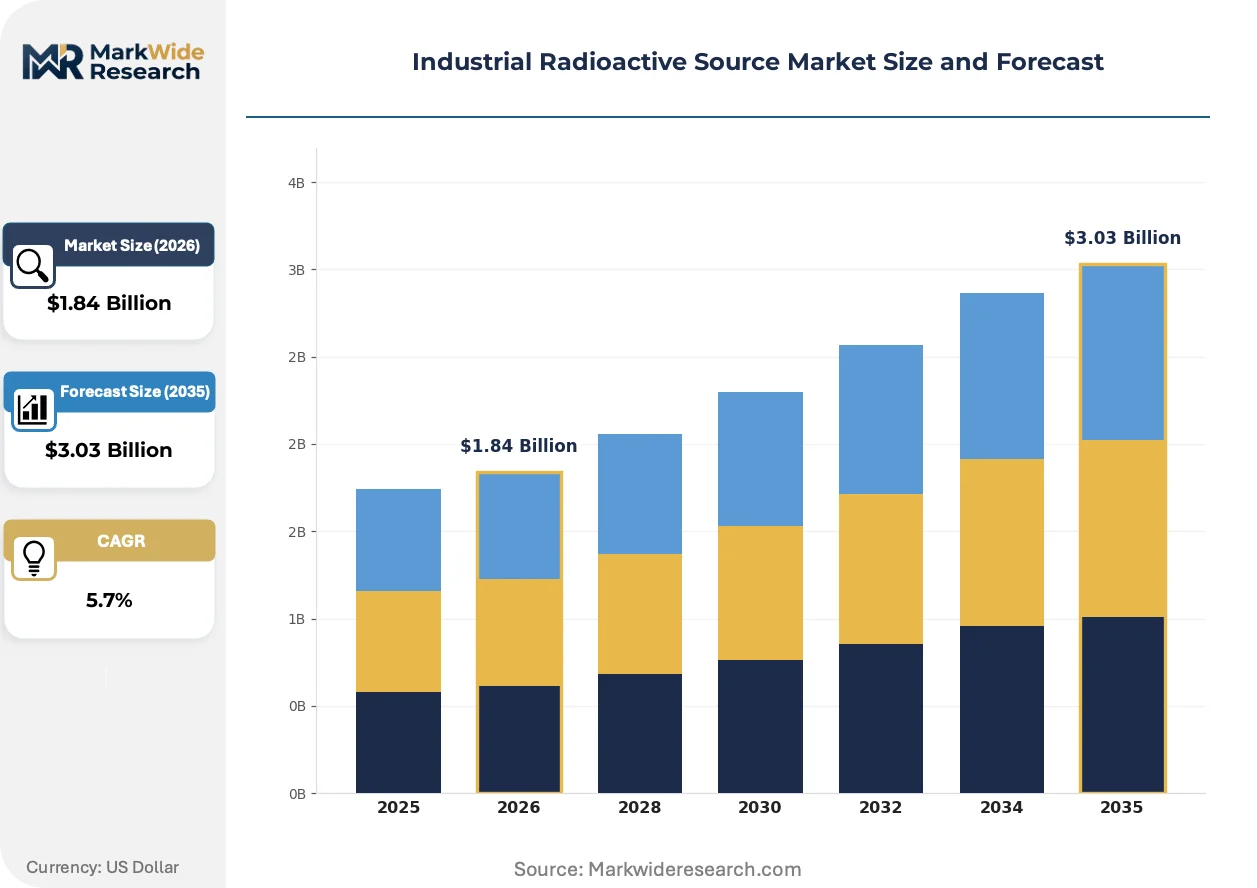
| Market Size in 2026 | $1.84 Billion |
| Market Size in 2035 | $3.03 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Gauges, Medical Isotopes, Radiography Sources, Calibration Sources Application: Nuclear Medicine, Radiological Testing, Material Inspection, Industrial Radiography End User: Research Institutions, Medical Facilities, Manufacturing Plants, Energy Sector Technology: Gamma Radiation, Alpha Radiation, Neutron Sources, Beta Radiation |
| Companies Covered | Thermo Fisher Scientific Inc., Eckert & Ziegler Strahlen- und Medizintechnik AG, QSA Global, Inc., Nordion (Canada) Inc., PerkinElmer, Inc., Berthold Technologies GmbH & Co. KG, NTP Radioisotopes SOC Ltd., China Isotope & Radiation Corporation, Mayak, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Radioactive Source Market Trends and Innovations
Authentication technologies and distributed production models are compressing traditional supply hierarchies while elevating transparency requirements across the sealed source lifecycle.
Blockchain-enabled provenance tracking is collapsing the information asymmetry that previously separated source manufacturers from end-user facilities. Pipeline inspection contractors and sterilization service providers are adopting distributed ledger verification for custody transfers. This transparency compression is eliminating intermediary authentication services and accelerating direct supplier-buyer relationships.
REACH substance registration requirements and EU dual-use export controls are tightening documentation standards for americium-241 and iridium-192 cross-border movements. Sealed source suppliers must now maintain substance volume tracking across the full product lifecycle. Medical isotope distributors are responding by consolidating European logistics networks under unified compliance management systems.
Service unbundling is fragmenting traditional source-supply contracts into discrete component transactions. End-users are separating hardware procurement, source loading, maintenance services, and disposal liability across specialized providers. This disaggregation is most pronounced in North American radiography services, where contractors now source capsules, equipment, and technician certification from independent vendors rather than integrated suppliers.
Industrial Radioactive Source Market Segmentation
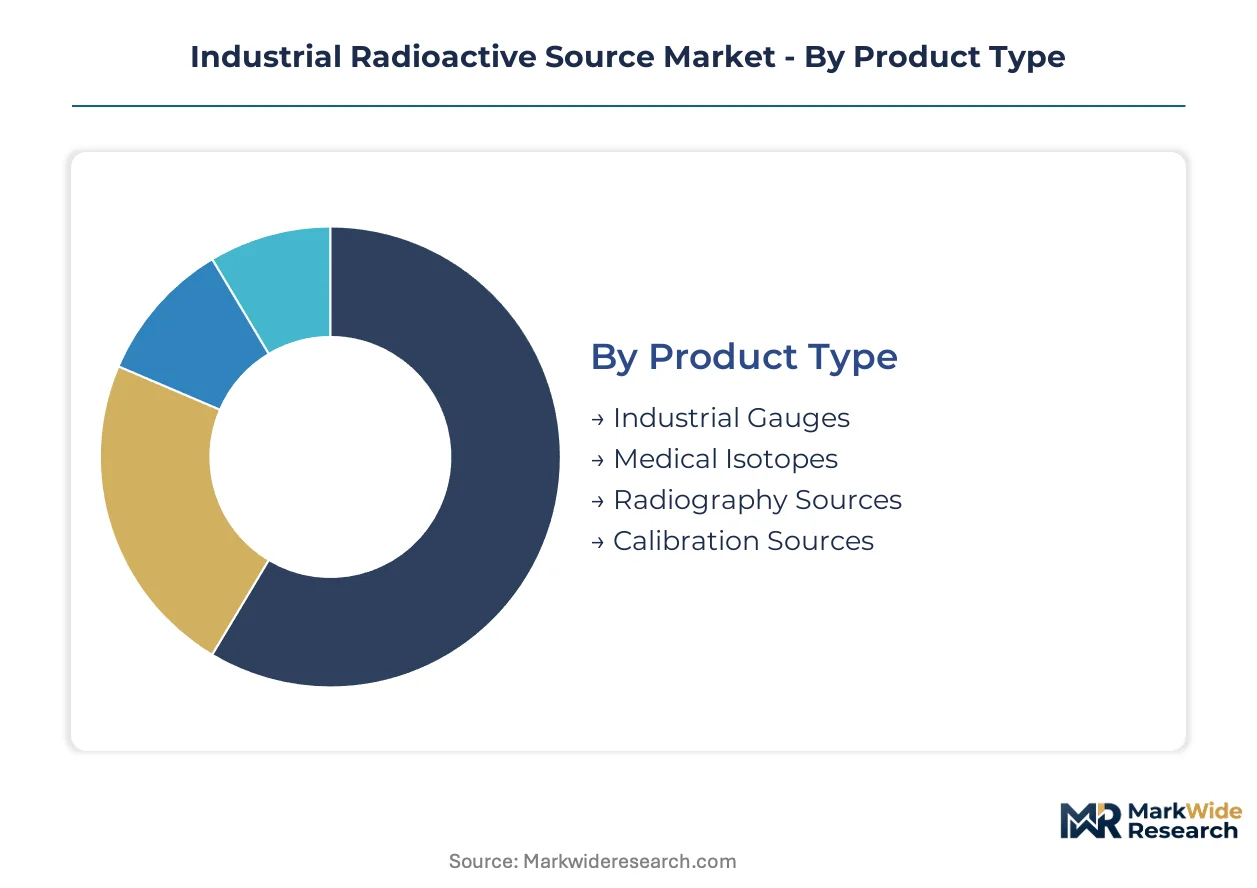
Industrial radioactive sources serve radically different technical requirements across sterilization, diagnostics, and non-destructive testing workflows. Segmentation clarity enables suppliers to match encapsulation specifications, activity levels, and regulatory certifications to precise end-use constraints without over-engineering.
Product Type:
Sealed source configurations range from high-activity cobalt-60 capsules for gamma sterilization to low-activity reference standards for calibration laboratories.
- Radiography Sources:Iridium-192 and cobalt-60 capsules engineered for gamma-ray penetration through steel welds and concrete structures. Pipeline contractors in the United States and refinery operators across the Gulf Coast deploy these sources for corrosion mapping and weld integrity verification under NRC-licensed protocols.
- Medical Isotopes:Diagnostic and therapeutic radionuclides including technetium-99m, iodine-131, and lutetium-177 produced via reactor or cyclotron irradiation. Hospital networks and specialized radiopharmacies are expanding procurement volumes as therapeutic radioisotope applications displace conventional chemotherapy in targeted oncology protocols.
- Industrial Gauges:Sealed americium-241 and cesium-137 sources for level detection, density measurement, and thickness gauging in continuous manufacturing lines.
- Calibration Sources:NIST-traceable reference standards with precisely certified activity levels for instrument validation and regulatory compliance documentation.
The dominant share belongs to Radiography Sources, while Medical Isotopes is closing the gap fastest.
Application:
Activity levels and shielding requirements vary by penetration depth and exposure duration demands.
- Industrial Radiography:Field-deployable gamma sources for weld inspection, pipeline corrosion assessment, and structural integrity verification in petrochemical infrastructure. Contractors across Texas, Louisiana, and Alberta coordinate source deployment through licensed service companies with mobile exposure devices.
- Nuclear Medicine:Diagnostic imaging and radiotherapy applications requiring pharmaceutical-grade radionuclide purity and sterile handling protocols. Cyclotron facilities in Belgium and the Netherlands are expanding molybdenum-99 alternative production to reduce supply chain concentration.
- Material Inspection:Non-destructive testing for aerospace components, castings, and composite materials using computed radiography and digital detector arrays.
- Radiological Testing:Environmental monitoring, contamination surveys, and personnel dosimetry calibration using certified reference sources.
Industrial Radiography commands the largest installed base, though Nuclear Medicine demonstrates the steepest expansion trajectory as therapeutic applications proliferate.
End User:
Procurement sophistication and compliance infrastructure vary sharply across facility types.
- Energy Sector:Pipeline operators, refinery maintenance divisions, and power generation utilities with dedicated radiation safety programs. Duke Energy and Southern California Edison maintain internal source inventories for heat exchanger tube inspection and pressure vessel certification cycles.
- Medical Facilities:Hospital nuclear medicine departments, cancer treatment centers, and specialized radiopharmacies requiring just-in-time isotope delivery. Mayo Clinic and MD Anderson operate captive cyclotron facilities to secure supply continuity for PET imaging programs.
- Manufacturing Plants:Steel mills, automotive assembly lines, and polymer processing facilities using fixed gauging systems for quality control.
- Research Institutions:National laboratories and university physics departments conducting materials science and detector development research.
Energy Sector facilities generate the highest source turnover volumes, while Medical Facilities are gaining procurement sophistication fastest.
Technology:
Radiation type determines shielding requirements, penetration capability, and regulatory classification.
- Gamma Radiation:High-energy photon emission from cobalt-60 and iridium-192 enabling deep material penetration for sterilization and radiography. Cobalt-60 sources from Ontario's Bruce Power reactor complex supply gamma sterilization facilities across North America and Europe.
- Neutron Sources:Californium-252 and americium-beryllium combinations for oil well logging, activation analysis, and reactor startup instrumentation. Schlumberger and Halliburton deploy these sources in downhole logging tools for formation evaluation in shale and sandstone reservoirs.
- Beta Radiation:Strontium-90 and promethium-147 sources for thin-film thickness gauging and static charge neutralization in paper and plastics manufacturing.
- Alpha Radiation:Americium-241 and polonium-210 for smoke detection ionization chambers and static elimination devices.
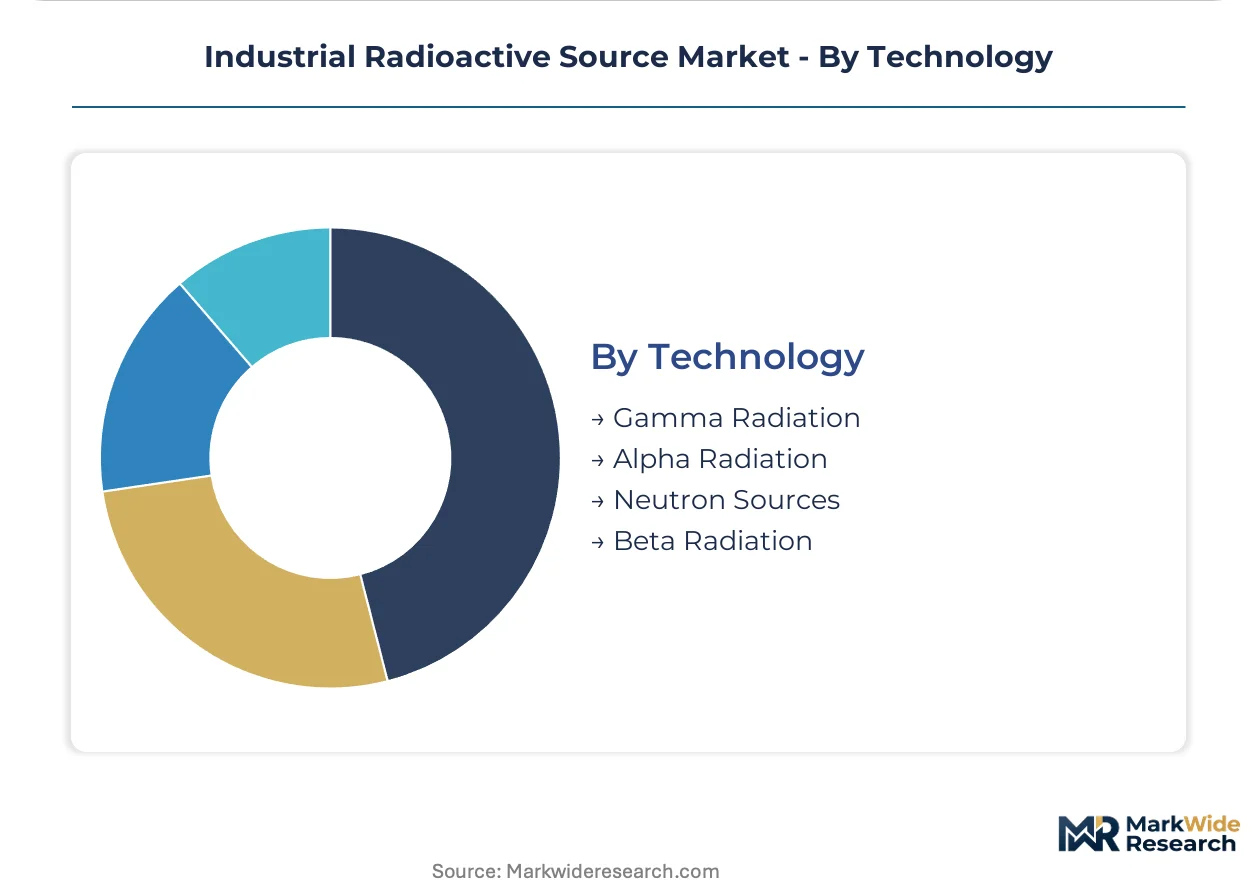
Gamma Radiation retains the dominant technology position, while Neutron Sources are climbing fastest as unconventional reservoir characterization demands intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South African reactor complexes supply iridium-192 and cobalt-60 capsules to pipeline inspection contractors across Texas, Alberta, and the North Sea. This trade corridor channels high-activity sealed sources from limited production nodes to dispersed radiography service networks.
United States
Gulf Coast refineries and Permian Basin pipeline operators deploy mobile gamma radiography units for weld integrity verification. NRC encapsulation standards and EPA-mandated disposal pathways elevate compliance costs for source handlers. Houston hosts the densest concentration of licensed radiography service companies coordinating source deployment across Texas, Louisiana, and Oklahoma energy infrastructure.
China
State-backed utilities expand non-destructive testing programs for nuclear power plant construction and pipeline networks. MIIT and MEE enforce dual-use export controls and source tracking protocols aligned with IAEA Code of Conduct. China Isotope & Radiation Corporation scales production capacity in Beijing and Shanghai to capture domestic and East Asian export demand.
Germany
Automotive manufacturers and chemical processors utilize fixed gauging systems for quality control in continuous production lines. ECHA REACH substance registration requirements tighten documentation standards for americium-241 and iridium-192 cross-border movements. The Rhine-Ruhr industrial corridor concentrates sealed source service providers serving steel mills and polymer processing facilities.
South Africa
NTP Radioisotopes SOC Ltd. operates reactor-based irradiation facilities supplying cobalt-60 and iridium-192 to radiography contractors across sub-Saharan Africa. The country's national nuclear regulator enforces IAEA-aligned inventory accountability for source export authorization. The Pelindaba nuclear complex anchors regional isotope production capacity serving underserved demand in mining and infrastructure inspection.
Canada
Bruce Power's Candu reactor complex supplies cobalt-60 capsules to gamma sterilization facilities across North America and Europe. Health Canada and PMRA enforce source encapsulation standards and transport documentation for cross-border transfers. Ontario's Chalk River region historically anchored isotope production, with distributed cyclotron capacity now expanding in Vancouver and Toronto for medical isotope diversification.
Industrial Radioactive Source Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three distinct tiers. Integrated analytical instrument manufacturers bundle source services with detection hardware, while isotope production specialists anchor supply through captive reactor or cyclotron capacity. Vertically integrated logistics operators control source deployment and recovery networks. Dominant competitive moves include capacity expansion at reactor irradiation facilities and strategic partnerships between source manufacturers and radiography service providers.
Among North American analytical instrument manufacturers, Thermo Fisher Scientific Inc. occupies a position representing the bundled-service archetype. German isotope production specialists Eckert & Ziegler Strahlen- und Medizintechnik AG exemplify the vertically integrated European supply model. South African reactor operator NTP Radioisotopes SOC Ltd. anchors regional production capacity for industrial radiography sources.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Eckert & Ziegler Strahlen- und Medizintechnik AG |
| QSA Global, Inc. |
| Nordion (Canada) Inc. |
| PerkinElmer, Inc. |
| Berthold Technologies GmbH & Co. KG |
| NTP Radioisotopes SOC Ltd. |
| China Isotope & Radiation Corporation |
| Mayak |
| Others |
Pricing and Supply Chain Analysis
Canadian reactor complexes at Bruce Power anchor cobalt-60 supply for gamma sterilization, concentrating margin capture downstream with radiography service providers who bundle source deployment with technician certification and regulatory compliance management.
Pricing Analysis
Prior-generation iridium-192 capsules trade at substantial discounts to next-generation embedded-authentication sources with tamper-evident features. Three-tier pricing structure across NIST-traceable calibration grade, industrial radiography standard, and bulk sterilization economy levels separates certification investment from basic activity supply. Cost compression in the economy tier intensifies because X-ray linear accelerator substitution erodes gauging applications. Pipeline contractors demonstrate highest price sensitivity due to project-based procurement cycles, while hospital networks accept premium positioning for diagnostic isotope reliability.
Supply Chain Analysis
EU dual-use export controls and IAEA Code of Conduct alignment restrict americium-241 and iridium-192 cross-border movements, forcing documentation rigor at every custody transfer. Production concentrates in Canada, South Africa, and Russia for cobalt-60 and iridium-192 irradiation, with China expanding cyclotron capacity for medical isotope diversification. Supply draws from high-purity cobalt metal feedstock, reactor irradiation slots, and specialized encapsulation foundries. Single-source vulnerability runs through limited reactor facilities subject to maintenance outages. Distribution runs through licensed logistics operators with mobile hot cell capabilities for field source exchange.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial radioactive sources sit in early-cycle expansion as therapeutic radioisotope applications displace conventional chemotherapy protocols and cyclotron capacity builds out distributed production networks.
For Market Incumbents: Entrench reactor slot access through long-term irradiation contracts and backward integration into cobalt metal supply. X-ray linear accelerator substitution threatens thickness gauging revenue pools, demanding defensive certification investment in embedded-authentication source features that regulators increasingly mandate. Channel control through captive radiography service networks preserves pricing power against unbundled competitors. For New Entrants and Emerging Players: Pursue Southern Africa production hub development where NTP Radioisotopes SOC Ltd. remains the sole regional supplier to mining and infrastructure inspection demand. Medical isotope distribution partnerships with hospital networks offer the most penetrable entry vector given diagnostic shortages and just-in-time delivery requirements. Go-to-market positioning should emphasize blockchain-enabled chain-of-custody verification that larger incumbents deploy slowly. For Investors and Strategic Acquirers: Capital is best deployed toward cyclotron-based medical isotope specialists with therapeutic pipeline diversification beyond technetium-99m. Long-term viability over the next decade hinges on regulatory capture through IAEA-aligned tracking infrastructure and reactor-independent production models. Watch cyclotron molybdenum-99 alternative production cost curves as the inflection signal for reactor-dependent source economics.| Strategic Initiative | Industry Significance |
|---|---|
| Reactor Capacity Expansion | Secures irradiation slots for cobalt-60 and iridium-192 amid supply concentration at Bruce Power and Pelindaba. |
| Blockchain Provenance Integration | Collapses authentication timelines for IAEA Code of Conduct compliance and eliminates intermediary verification services. |
| Medical Isotope Diversification | Opens lutetium-177 and actinium-225 revenue streams beyond industrial radiography as therapeutic applications proliferate. |
| Regional Logistics Consolidation | Unifies European distribution under REACH-aligned compliance management for americium-241 cross-border movements. |
| Digital Twin Service Bundling | Converges source monitoring with predictive maintenance platforms for gamma sterilization facility uptime optimization. |
Research Methodology
A standing panel of radiation safety officers, reactor operations managers, radiography service contractors, and hospital nuclear medicine directors provided ongoing calibration against secondary validation from NRC licensing databases, IAEA incident reports, EPA disposal records, and customs trade documentation. Bottom-up source deployment volumes triangulated against top-down isotope production capacity estimates.
Scenario-bracketing framed projections across the analysis window, modeling segmentation dimensions including radiation type, encapsulation specification, end-use application, and regional regulatory cluster. CAGRs derived from reactor outage probability distributions, cyclotron capacity buildout trajectories, and substitution elasticity parameters for X-ray linear accelerator penetration thresholds.
Sensitivities concentrate around reactor maintenance scheduling disruptions, export control enforcement intensification, and therapeutic isotope reimbursement policy shifts. Material shifts in IAEA Code of Conduct implementation timelines or major reactor facility decommissioning would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuclear Energy
Small Modular Reactor (SMR) Market
Nuclear Energy
Thorium Market
Nuclear Energy
South America Nuclear Reactor Construction Market
Nuclear Energy
Nuclear Powered Merchant Vessel Market
Nuclear Energy
Helium-3 Market
Nuclear Energy
Nuclear Power Market
Nuclear Energy
Nuclear Steam Generator Market
Nuclear Energy
Global Molten Salt Reactor Market
Nuclear Energy
France Nuclear Power Reactor Decommissioning Market
Nuclear Energy
Nuclear Spent Fuel Market
Nuclear Energy
North America Nuclear Power Plant and Equipment Market
Nuclear Energy
Global Thorium Reactor Market
Nuclear Energy
Middle-East and Africa Nuclear Power Plant Equipment Market
Nuclear Energy
Fusion Power Market
Nuclear Energy
Europe Nuclear Reactor Construction Market
Nuclear Energy
United States Nuclear Power Reactor Decommissioning Market