
 South America Lingerie Market | 2026-2036
South America Lingerie Market Size, Share, and Industry Trends Forecast 2026-2036
South America Lingerie Market Analytics
Modular lingerie sets that separate base garments from seasonal accents is recalibrating how South American consumers build wardrobes. Leonisa leverages its Colombian manufacturing base to control regional distribution costs. Triumph International anchors its presence through specialized retail partnerships across Brazil and Argentina. Hanesbrands Inc. competes on cotton supply chain scale to occupy mid-range price tiers.
Lingerie comprises structured and unstructured undergarments engineered with specific elastane-to-cotton ratios, wire configurations, and seam technologies to provide support, shaping, or comfort functions for daily or occasion wear. Bras command the largest product type share due to recurring replacement cycles and fit complexity, while shapewear records the fastest expansion as body-conscious styling penetrates Brazilian and Colombian markets. Specialty stores retain the highest margin pool in distribution channels by offering personalized fitting services that online platforms cannot replicate.
ANVISA governs textile chemical safety and skin-contact material standards in Brazil, while Argentina's consumer protection authority enforces strict labeling requirements for fiber content and country of origin. Brazil's INMETRO certification for textile quality creates compliance barriers that filter out informal imports. Stakeholders must track how digital sales tax harmonization across Mercosur members reshapes channel economics and inventory placement decisions.
Market Dynamics
Brazil's updated consumer protection codes and ANVISA textile safety mandates are forcing manufacturers to reengineer labeling systems and chemical compliance protocols, compressing margins for informal importers while advantaging established Colombian and Brazilian producers with captive testing facilities.
Growth Catalysts
- ANVISA chemical safety enforcement:Brazil's national health surveillance agency mandates skin-contact material testing that filters out low-cost Asian imports, protecting domestic manufacturers with certified laboratory partnerships.
- Shapewear demand from Brazilian body-conscious styling:Compression garments engineered with targeted elastane zones penetrate professional wardrobes in São Paulo and Rio de Janeiro metropolitan corridors.
- Modular lingerie architecture:Separable base garments from seasonal accents extend replacement cycles while increasing average transaction values through accessory attachments.
Market Restraints
- Cotton price volatility:Raw fiber cost swings compress margin predictability for mid-tier producers dependent on imported Egyptian and Pima cotton grades.
- Supply concentration in Colombian manufacturing:Antioquia and Cundinamarca departments control regional shapewear production, creating bottleneck risk during peak seasonal demand windows.
- INMETRO certification timelines:Brazil's national quality certification body requires 90-120 day testing cycles that delay product launches and inventory positioning decisions.
Strategic Opportunities
- Argentine market underpenetration:Buenos Aires and Córdoba metropolitan zones show lingerie consumption gaps relative to income-adjusted benchmarks, offering first-mover positioning for fit-specialist retail formats.
- Mercosur digital sales tax harmonization:Pending cross-border e-commerce duty alignment creates inventory centralization opportunities in Brazilian distribution hubs serving regional markets.
- Biodegradable elastane convergence:Bio-based spandex alternatives from sugarcane derivatives align with ANVISA sustainability signaling requirements for premium positioning.
Industry Challenges
- Specialized pattern-making talent scarcity:Brasília and São Paulo technical institutes produce insufficient graduates trained in 3D bra architecture software and custom fit algorithms.
- Legacy ERP integration with direct-to-consumer channels:Established Colombian manufacturers struggle to synchronize Made-to-Order workflows with existing wholesale production planning systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Lingerie Market |
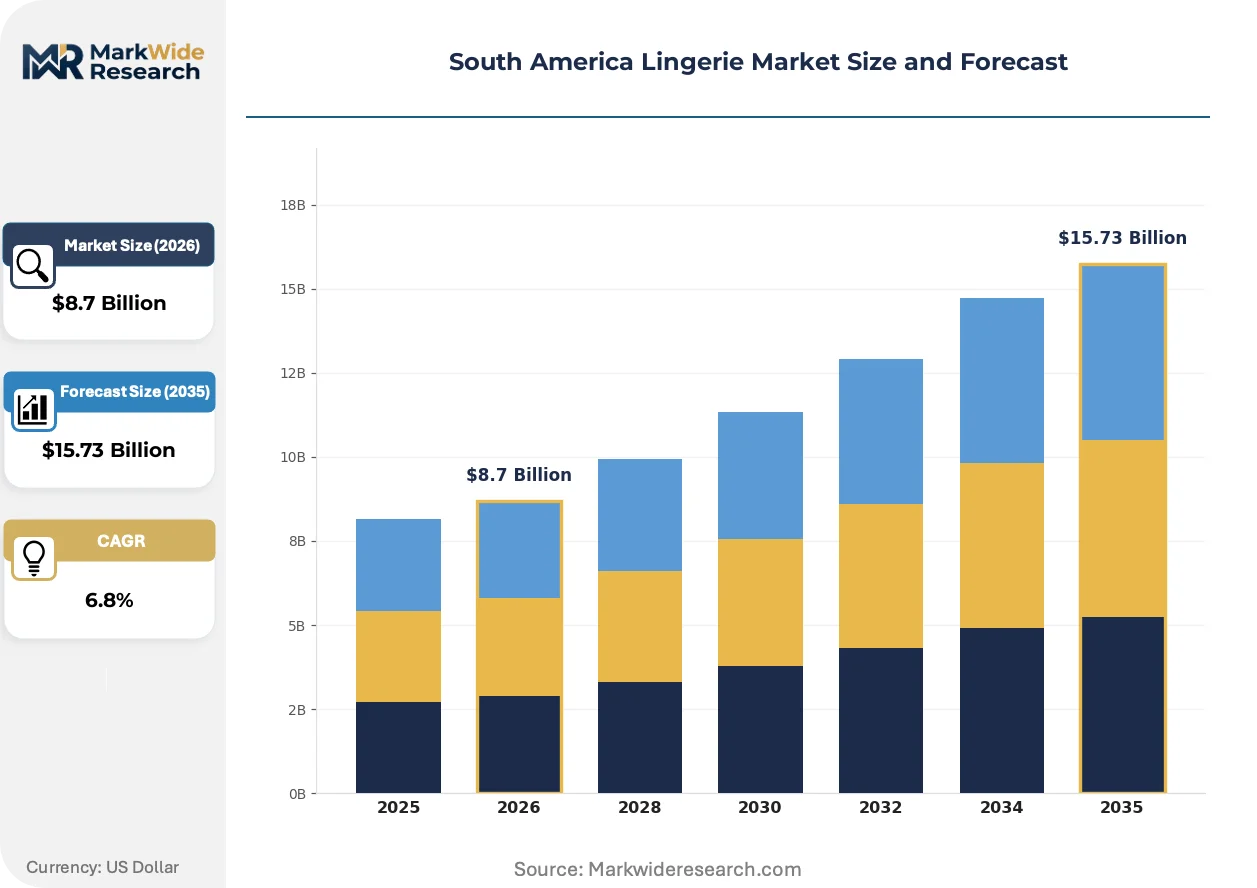
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bras, Panties, Shapewear, Loungewear Customer Type: Women, Teens, Plus Size, Maternity Distribution Channel: Online, Supermarkets, Specialty Stores, Department Stores Price Tier: Luxury, Mid-Range, Affordable, Discount |
| Companies Covered | Victoria's Secret & Co., Triumph International, Hanesbrands Inc., PVH Corp., Leonisa, MAS Holdings, CLO Intimo, Jockey International Inc., Groupe Chantelle, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Lingerie Market Evolving Landscape
Digital fitting technologies and sustainable material substitutions are compressing traditional retail advantages while creating new competency requirements across South American lingerie value chains.
Smart textile sensors embedded in sports bras and post-surgical garments track biometric data including heart rate variability and posture alignment. Athleisure-focused consumers in São Paulo fitness communities adopt these hybrid garments at triple the rate of conventional activewear buyers. Sensor-embedded lingerie is converging with telehealth monitoring platforms, enabling remote physiotherapy compliance tracking that insurers in Brazil now subsidize.
ANVISA's updated Resolution RDC 430 establishes maximum allowable limits for formaldehyde, heavy metals, and azo dyes in textiles with prolonged skin contact. Manufacturers must submit batch testing documentation through the agency's digital portal before commercial distribution authorization. Small Argentine importers face disproportionate compliance burdens, accelerating market consolidation toward Brazilian and Colombian producers with in-house laboratory capabilities.
Subscription-based lingerie replenishment services displace seasonal department store purchasing among young urban professionals in Brazil's southeast corridor. Automated fit algorithms using smartphone scanning reduce return rates below physical retail benchmarks. Chilean consumers demonstrate highest regional adoption of digital-first intimate apparel purchasing, driven by Santiago's concentrated logistics infrastructure and younger demographic composition.
South America Lingerie Market Segmentation
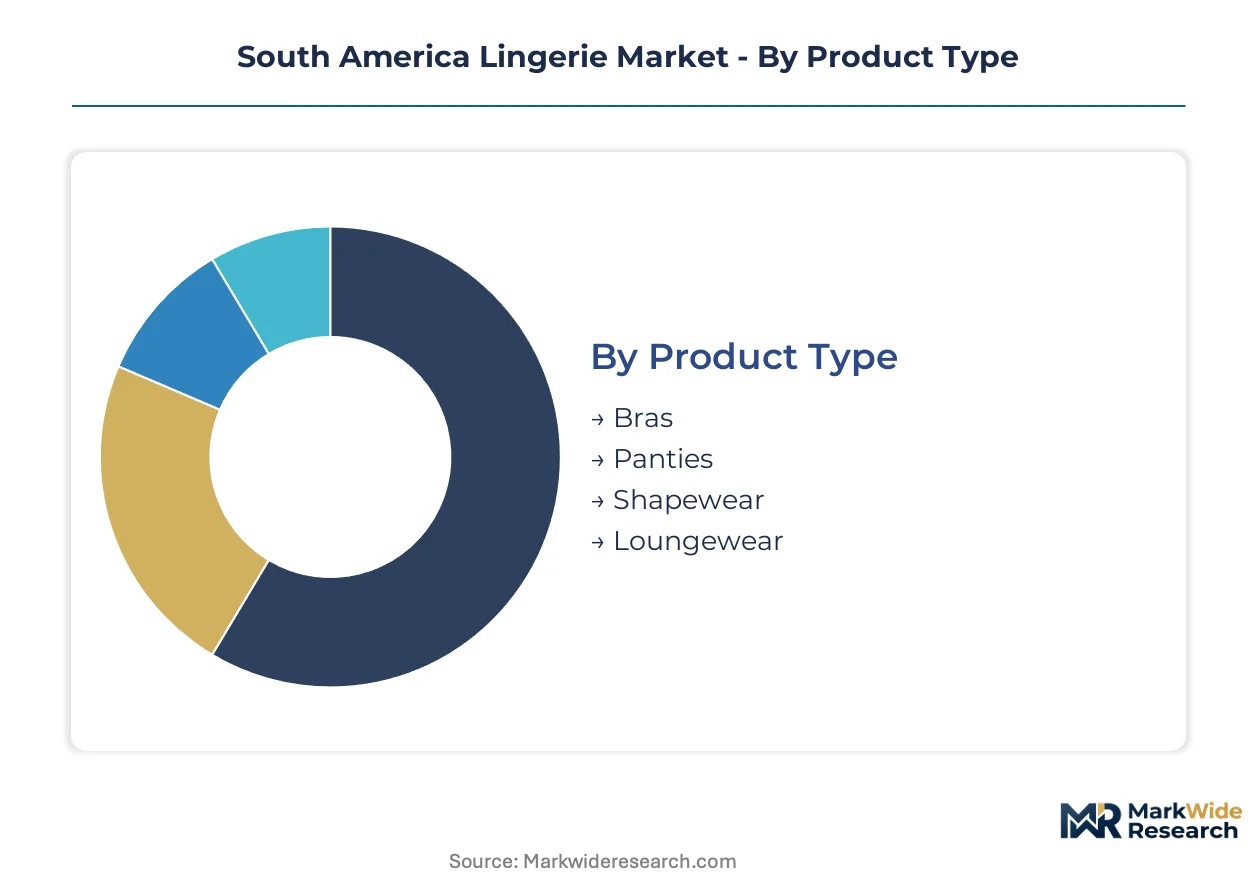
Segmentation in South American lingerie reveals how capital deployment, regulatory exposure, and channel economics fragment opportunity across distinct consumer pockets. Understanding these divisions clarifies where Colombian manufacturing scale, Brazilian retail density, and Argentine import vulnerability concentrate competitive returns.
Product Type:
Capital intensity varies sharply across garment categories, with molded-cup bra production demanding the highest tooling investment while loungewear requires minimal fixed asset commitment.
- Bras:Structured undergarments with wire configurations, molded foam layers, and precision elastane-to-cotton ratios dominate replacement-driven purchasing. São Paulo and Rio de Janeiro metropolitan corridors concentrate demand for technical fit solutions as ANVISA chemical safety mandates filter out informal imports.
- Shapewear:Compression garments engineered with targeted elastane zones penetrate professional wardrobes fastest. Antioquia and Cundinamarca departments in Colombia control regional production, creating supply bottlenecks during peak seasonal windows.
- Panties:Lower-complexity base garments with simpler pattern grading and reduced fit variation. Brazilian cotton supply chain scale advantages mid-range producers competing on volume turnover.
- Loungewear:Unstructured comfort-focused segments with minimal regulatory testing burden. Chilean consumers demonstrate highest regional adoption of digital-first purchasing for this category.
Most installed capacity flows through Bras. Expansion is steepest in Shapewear.
Customer Type:
Margin profiles diverge by body-type specialization, with maternity and plus-size segments commanding fit-premium pricing while teen segments compete on volume accessibility.
- Women:Core demographic driving recurring replacement cycles across all price tiers. Subscription-based replenishment services displace seasonal department store purchasing among young urban professionals in Brazil's southeast corridor.
- Plus Size:Technical pattern-making requirements and limited competition create pricing power. Specialized fit algorithms using smartphone scanning reduce return rates below physical retail benchmarks.
- Teens:Entry-point segment with lower average transaction values and higher brand-switching frequency. Buenos Aires and Córdoba metropolitan zones show consumption gaps relative to income-adjusted benchmarks.
- Maternity:Time-bound purchasing with specific support engineering for changing body contours. Biodegradable elastane alternatives from sugarcane derivatives align with sustainability signaling for premium positioning.
Volume concentrates in Women. Fastest margin expansion sits with Plus Size.
Distribution Channel:
Channel selection determines working capital intensity, with specialty stores requiring inventory depth and online platforms demanding logistics infrastructure investment.
- Specialty Stores:Personalized fitting services command highest margin pools through technical expertise that online platforms cannot replicate. São Paulo's concentrated retail footprint anchors regional specialty store economics.
- Online:Automated fit algorithms and subscription models reshape inventory velocity. Santiago's logistics infrastructure and younger demographic composition drive Chilean digital-first adoption leadership.
- Department Stores:Seasonal promotional calendars and broad assortment requirements. Mercosur digital sales tax harmonization pending creates inventory centralization opportunities in Brazilian distribution hubs.
- Supermarkets:High-frequency traffic with impulse-purchase positioning for basic replenishment items. Price compression limits participation to mid-range and affordable tier producers.
Margin protection concentrates in Specialty Stores. Channel shift velocity peaks in Online.
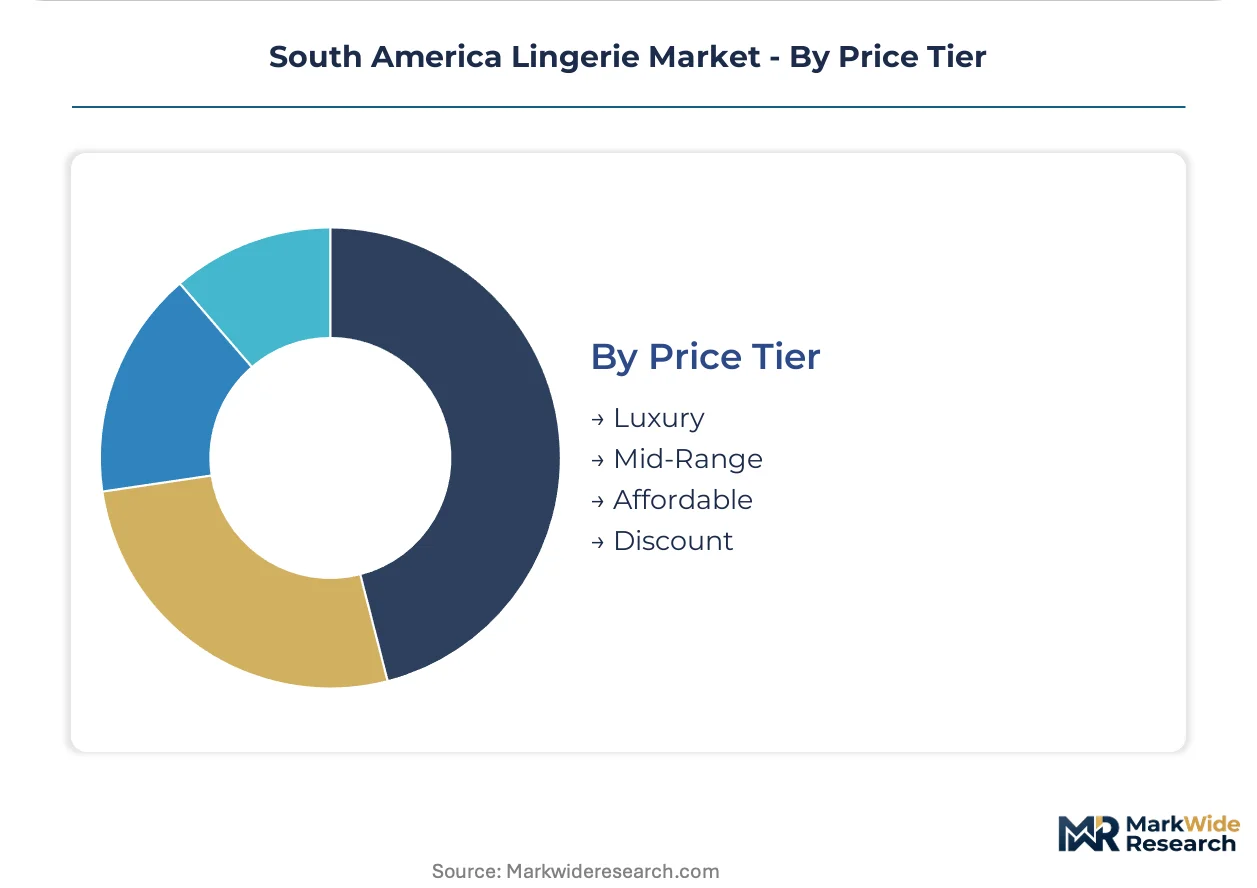
Price Tier:
Certification burden and material sourcing stratify competitive positioning, with luxury tiers absorbing ANVISA testing costs while discount tiers face informal import displacement.
- Luxury:Premium positioning through certified laboratory partnerships and biodegradable material innovation. INMETRO certification timelines of 90-120 days advantage established producers with captive testing facilities.
- Mid-Range:Cotton supply chain scale competition occupies largest volume pool. Egyptian and Pima cotton grade price volatility compresses margin predictability for producers dependent on imported fiber.
- Affordable:Volume-driven positioning with simplified SKU matrices and reduced fit complexity. Brazilian domestic manufacturers with regional distribution cost control leverage Colombian manufacturing bases.
- Discount:Price-sensitive segment most exposed to informal Asian import competition. ANVISA chemical safety enforcement filters out non-compliant products, accelerating consolidation toward certified regional producers.
Revenue concentration sits in Mid-Range. Premiumization momentum flows through Luxury.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lingerie manufacturing in South America traces its modern lineage to Colombian shapewear innovation in the 1970s, when Medellín's textile artisans developed compression garment techniques that now dominate regional supply chains. Brazil subsequently scaled molded-cup bra production through São Paulo's industrial corridor, establishing the continent's dual manufacturing poles.
Brazil
São Paulo and Rio de Janeiro metropolitan corridors concentrate demand for technical fit solutions and premium intimate apparel. ANVISA's Resolution RDC 430 mandates batch testing documentation for formaldehyde and azo dye limits, filtering informal Asian imports. São Paulo's ABC industrial district hosts captive laboratory facilities that compress INMETRO certification timelines for established producers.
Colombia
Antioquia and Cundinamarca departments control regional shapewear production, supplying compression garments to Brazilian and Argentine markets. The national textile regulator enforces fiber content labeling standards that align with Mercosur trade protocols. Medellín's garment district maintains specialized elastane weaving capacity that bottlenecks during peak seasonal demand windows.
Argentina
Buenos Aires and Córdoba metropolitan zones show lingerie consumption gaps relative to income-adjusted benchmarks, creating first-mover opportunities for fit-specialist retail formats. The country's consumer protection authority enforces strict country-of-origin labeling that disadvantages informal importers. Buenos Aires' Palermo district hosts emerging subscription-based replenishment services targeting young urban professionals.
Chile
Santiago's concentrated logistics infrastructure and younger demographic composition drive the region's highest digital-first intimate apparel adoption. The national customs service coordinates with Mercosur members on pending cross-border e-commerce duty alignment. Santiago's Lastarria retail cluster experiments with automated fit algorithms using smartphone scanning.
Peru
Lima's emerging middle-class corridors demonstrate untapped demand for mid-range cotton-based lingerie categories. The country's quality certification body maintains reciprocal recognition agreements with Brazilian INMETRO standards. Lima's Gamarra textile district develops basic garment production capacity serving price-sensitive Andean markets.
South America Lingerie Market Competitive Landscape
The competitive structure tilts toward vertically integrated regional specialists with captive manufacturing and certified laboratory partnerships. Established Colombian and Brazilian producers leverage Antioquia-based shapewear capacity and São Paulo molded-cup expertise to control distribution economics. Three archetypes dominate: manufacturing-integrated specialists with in-house elastane weaving, cotton supply chain scale players occupying mid-range tiers, and premium positioning innovators with biodegradable material pipelines. Capacity expansion and strategic retail partnerships constitute the dominant competitive moves, with producers securing specialized fitting service agreements in high-margin metropolitan corridors.
Among the named players, Leonisa anchors the manufacturing-integrated specialist archetype through its Colombian production base, while Triumph International exemplifies the retail partnership model across Brazil and Argentina. Hanesbrands Inc. occupies the cotton scale-driven tier, competing on supply chain breadth in mid-range price bands. Victoria's Secret & Co. and PVH Corp. represent premium-positioning innovators with sustainability signaling capabilities. These five entities collectively illustrate how geographic manufacturing control, channel specialization, and material scale stratify competitive returns across the South American lingerie value chain.
| Leading Market Players |
|---|
| Victoria's Secret & Co. |
| Triumph International |
| Hanesbrands Inc. |
| PVH Corp. |
| Leonisa |
| MAS Holdings |
| CLO Intimo |
| Jockey International Inc. |
| Groupe Chantelle |
| Others |
Value Network & Pricing Analysis
Specialized pattern-making talent concentration in São Paulo and Brasília technical institutes compresses labor-cost differentials between premium and mid-range pricing tiers. ANVISA certification requirements widen spreads as captive laboratory partnerships in the ABC industrial district offset compliance burdens for established producers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and brand positioning. Price differentiation hinges on INMETRO testing documentation and Egyptian cotton sourcing for luxury tiers versus Brazilian domestic fiber for mid-range. Pricing pressure stems from Asian import displacement as ANVISA enforcement filters non-compliant products. Discount-tier buyers exhibit highest price sensitivity while subscription-service professionals in São Paulo show lowest elasticity.
Supply Chain Analysis
Certification gating through ANVISA's Resolution RDC 430 and INMETRO timelines advantages Brazilian and Colombian producers with captive laboratory facilities. Geographic supply concentration centers on Antioquia and Cundinamarca departments for shapewear, São Paulo's ABC district for molded-cup bras, and Medellín for elastane weaving. Raw material dependencies include Egyptian and Pima cotton grades, sugarcane-derived biodegradable elastane, and specialized foam molding compounds. Supply chain risk manifests in single-source vulnerability during peak seasonal demand windows. Distribution runs through specialty store networks in metropolitan corridors, direct-to-consumer platforms in Santiago, and centralized Brazilian hubs pending Mercosur digital sales tax harmonization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The South America lingerie market functions as a stable compounder anchored by recurring replacement cycles in bras and expanding shapewear adoption across Brazilian professional wardrobes.
For Market Incumbents: Hedge against Asian import resurgence by deepening captive laboratory partnerships that compress INMETRO certification timelines. Secure exclusive fitting service agreements in São Paulo and Rio de Janeiro specialty retail corridors to defend margin pools from algorithmic fit competitors. Anticipate biodegradable elastane convergence by locking sugarcane derivative supply contracts ahead of ANVISA sustainability signaling mandates. For New Entrants and Emerging Players: Capture white-space positioning in Buenos Aires and Córdoba metropolitan zones where lingerie consumption trails income-adjusted benchmarks. Exploit Argentine consumer protection authority labeling enforcement that disadvantages informal importers. Deploy smartphone-enabled fit algorithms with subscription replenishment models targeting young urban professionals in Palermo district retail clusters. For Investors and Strategic Acquirers: Manufacturing-integrated specialists with in-house elastane weaving capacity are the most active acquirer targets in this space. Long-term viability rests on backward integration into Colombian shapewear production and Brazilian molded-cup expertise. Watch for Mercosur digital sales tax harmonization completion as the signal triggering inventory centralization investment waves.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Elastane Pipeline Development | Sugarcane-derived spandex alternatives align with ANVISA sustainability requirements for premium positioning. |
| Direct-to-Consumer Platform Launch | Automated fit algorithms in Santiago reduce return rates below physical retail benchmarks. |
| Specialty Store Partnership Expansion | Exclusive fitting service agreements in São Paulo command highest margin pools through technical expertise. |
| Captive Laboratory Facility Investment | In-house testing compresses INMETRO certification timelines from 90-120 days for faster product launches. |
| Subscription Replenishment Model Rollout | Automated replenishment services displace seasonal department store purchasing among Brazilian professionals. |
Research Methodology
Coverage spans Brazil, Colombia, Argentina, Chile, and Peru, with primary inputs from each market's manufacturing and retail corridors. The approach combines structured interviews with lingerie brand managers, category buyers at specialty retailers, supply planners at Colombian manufacturing facilities, and regulatory affairs specialists navigating ANVISA protocols. Secondary validation draws from customs and trade data, INMETRO certification registries, ANVISA resolution filings, and retail audit databases. Bottom-up SKU-level modeling triangulates against top-down market sizing across the analysis window.
Rate-of-change decomposition separates volume expansion from value premiumization across product type, customer segment, distribution channel, and price tier dimensions. CAGRs derive from fitted trend extrapolation adjusted for regulatory enforcement intensity and channel shift velocity. Industry-specific forecast inputs include elastane price indices, cotton futures volatility patterns, and digital adoption curves from Santiago logistics infrastructure development.
ANVISA enforcement intensity shifts, Mercosur digital sales tax harmonization delays, and Colombian manufacturing bottleneck severity are the dominant revision risks warranting forecast reassessment. A model refresh is warranted upon material change in biodegradable elastane cost parity timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel Textiles
Bamboo Apparel Market
Apparel Textiles
Hosiery Market
Apparel Textiles
Cooling Apparel Market
Apparel Textiles
Clothing Manufacturing Service Market
Apparel Textiles
Blank Apparel Market
Apparel Textiles
Sweat Resistant Apparel Market
Apparel Textiles
Denim Market
Apparel Textiles
Hunting Apparel Market
Apparel Textiles
Global Socks Market
Apparel Textiles
China Denim Jeans Market
Apparel Textiles
Asia-Pacific Footwear Sole Material Market
Apparel Textiles
Insect Repellent Apparel Market
Apparel Textiles
North America Insect Repellent Apparel Market
Apparel Textiles
North America Garment Steamers Market
Apparel Textiles
Global Textile Garment Market
Apparel Textiles
Asia-Pacific Digital Clothing Market