
 North America Insect Repellent Apparel Market | 2026-2036
North America Insect Repellent Apparel Market Size, Share, and Industry Trends Forecast 2026-2036
North America Insect Repellent Apparel Market Analytics
Specialty outdoor retail is reconfiguring how insect repellent apparel reaches end consumers, with dedicated storefronts and expert staff replacing general merchandise placements. Insect Shield LLC leverages its proprietary bonding technology to sustain licensing partnerships across multiple apparel brands. Columbia Sportswear anchors its market presence through integrated Omni-Shield product lines that compete on performance credentials rather than price alone. Patagonia differentiates through repairable construction and environmental accountability, occupying premium positioning that resists commoditization pressures.
North America insect repellent apparel comprises garments engineered with permethrin or botanical repellent compounds bonded to textile fibers during manufacturing or applied through post-treatment processes, achieving protection standards measured by EPA bioassay protocols against mosquito and tick bites. The primary commercial purpose centers on reducing vector-borne disease transmission risk during outdoor occupational and recreational exposure. T-Shirts and Pants command the largest volume share as foundational layering pieces, while Jackets capture higher unit margins through technical waterproof-breathable laminates that integrate repellency. Cotton and Polyester fabric types dominate current production, though Nylon and specialized Blends are gaining share in technical hiking and fishing applications where abrasion resistance and quick-dry performance justify premium positioning.
EPA regulates permethrin-treated garments under Federal Insecticide, Fungicide, and Rodenticide Act registration requirements, mandating efficacy testing and label claims that shape product development timelines and market access barriers. Health Canada enforces parallel PMRA standards for cross-border manufacturers, while state-level vector control programs in Texas and Florida supplement federal frameworks with localized public health messaging that stimulates seasonal demand spikes. Stakeholders must monitor evolving EPA registration renewal schedules and emerging botanical active ingredient pathways that could reshape formulation strategies without the synthetic compound regulatory burden.
Market Dynamics
EPA registration renewal timelines for permethrin-treated fabrics are compressing product development cycles while elevating compliance costs, forcing manufacturers to consolidate formulation R&D or exit the category entirely.
Growth Catalysts
- Vector-borne disease surveillance expansion:State health departments in Texas and Florida are amplifying tick-borne illness warnings, directly stimulating seasonal purchasing spikes for protective apparel among suburban gardeners and trail users.
- REACH-aligned botanical active ingredient pathways:ECHA's evolving stance on synthetic biocides is accelerating North American investment in plant-derived repellent compounds that bypass FIFRA registration burdens.
- Technical hiking segment concentration:Appalachian Trail thru-hikers and Pacific Crest Trail communities are normalizing permethrin-treated base layers as standard equipment, creating durable word-of-mouth demand.
Market Restraints
- Permethrin raw material concentration:Active ingredient supply chains cluster among Chinese agrochemical manufacturers, exposing North American finishers to tariff volatility and ocean freight disruptions.
- FIFRA efficacy testing timelines:EPA-mandated bioassay protocols extend product launch windows by 18-24 months, freezing capital in inventory before revenue recognition.
- Untreated technical apparel substitution:High-performance synthetic base layers from standard outdoor brands satisfy comfort requirements without repellency premiums, capturing price-sensitive consumers.
Strategic Opportunities
- Mexico outdoor tourism infrastructure:Copper Canyon and Baja California trail systems are attracting North American adventure operators seeking bulk uniform contracts with integrated vector protection.
- OSHA workplace safety integration:Landscaping and utility vegetation management crews present untapped occupational segments where employer-funded PPE programs could standardize repellent apparel.
- Direct-to-consumer subscription models:Seasonal replenishment of treated garments through curated outdoor boxes is bypassing traditional retail markup structures and capturing lifetime value.
Industry Challenges
- Textile bonding chemistry expertise scarcity:Formulation scientists capable of achieving wash-durable permethrin adhesion without fiber degradation command premium compensation, constraining scale-up capacity.
- Cross-border PMRA registration synchronization:Health Canada's parallel efficacy requirements for Canadian market access create documentation duplication that delays unified North American launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Insect Repellent Apparel Market |
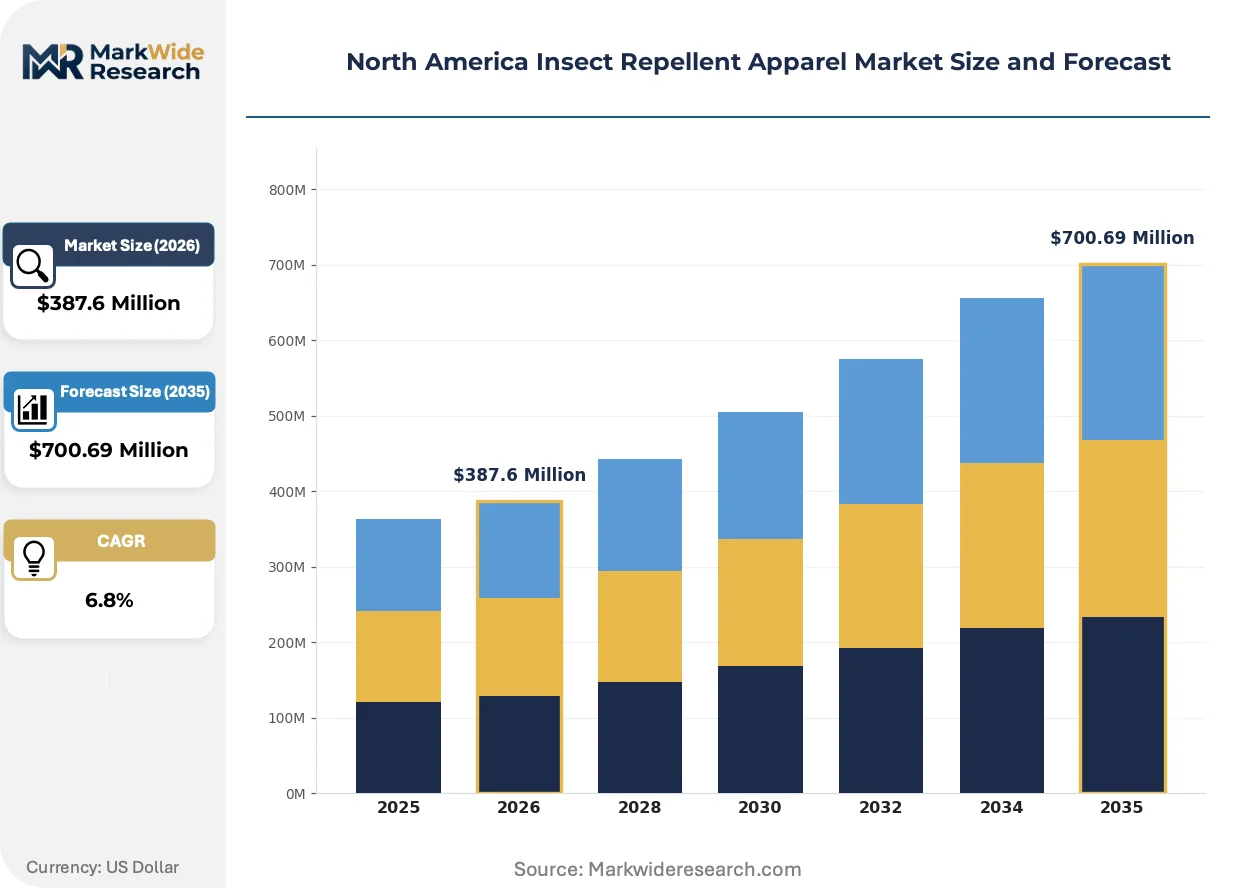
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: T-Shirts, Pants, Jackets, Hats Fabric Type: Cotton, Polyester, Nylon, Blends End Use: Outdoor Recreation, Camping, Fishing, Gardening Distribution Channel: Online Retail, Specialty Stores, Department Stores, Outlets |
| Companies Covered | Insect Shield LLC, ExOfficio, Craghoppers, Columbia Sportswear, Patagonia, L.L.Bean, The North Face, Outdoor Research, Rohan Designs, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Insect Repellent Apparel Market Evolving Landscape
Formulation chemistry and distribution architecture are undergoing parallel transformation as botanical alternatives challenge synthetic dominance and specialty retail reconfigures customer acquisition economics.
Microencapsulated essential oil blends derived from lemon eucalyptus and citronella are hybridizing with traditional textile finishing processes, enabling smaller batch production runs that appeal to boutique outdoor brands seeking EPA-compliant differentiation without permethrin's regulatory overhead. Boutique manufacturers in Colorado and Oregon are piloting these systems for fly-fishing waders and sun-protective shirts.
EPA's 2024 updated guidance on treated article exemptions is narrowing label claim permissibility for post-purchase spray applications while reinforcing registration requirements for factory-bonded repellency, advantaging established finishers with existing FIFRA clearances. California's Department of Pesticide Regulation is mirroring this stringency, creating a unified compliance bar across the largest state market.
Specialty outfitters are displacing mass-market sporting goods as the primary education channel, with trained staff demonstrating efficacy protocols and wash-care instructions that reduce product dissatisfaction and return rates. This shift concentrates in the Mountain West and Pacific Northwest where concentrated outdoor recreation cultures sustain standalone retail footprints against e-commerce pressure.
North America Insect Repellent Apparel Market Segmentation
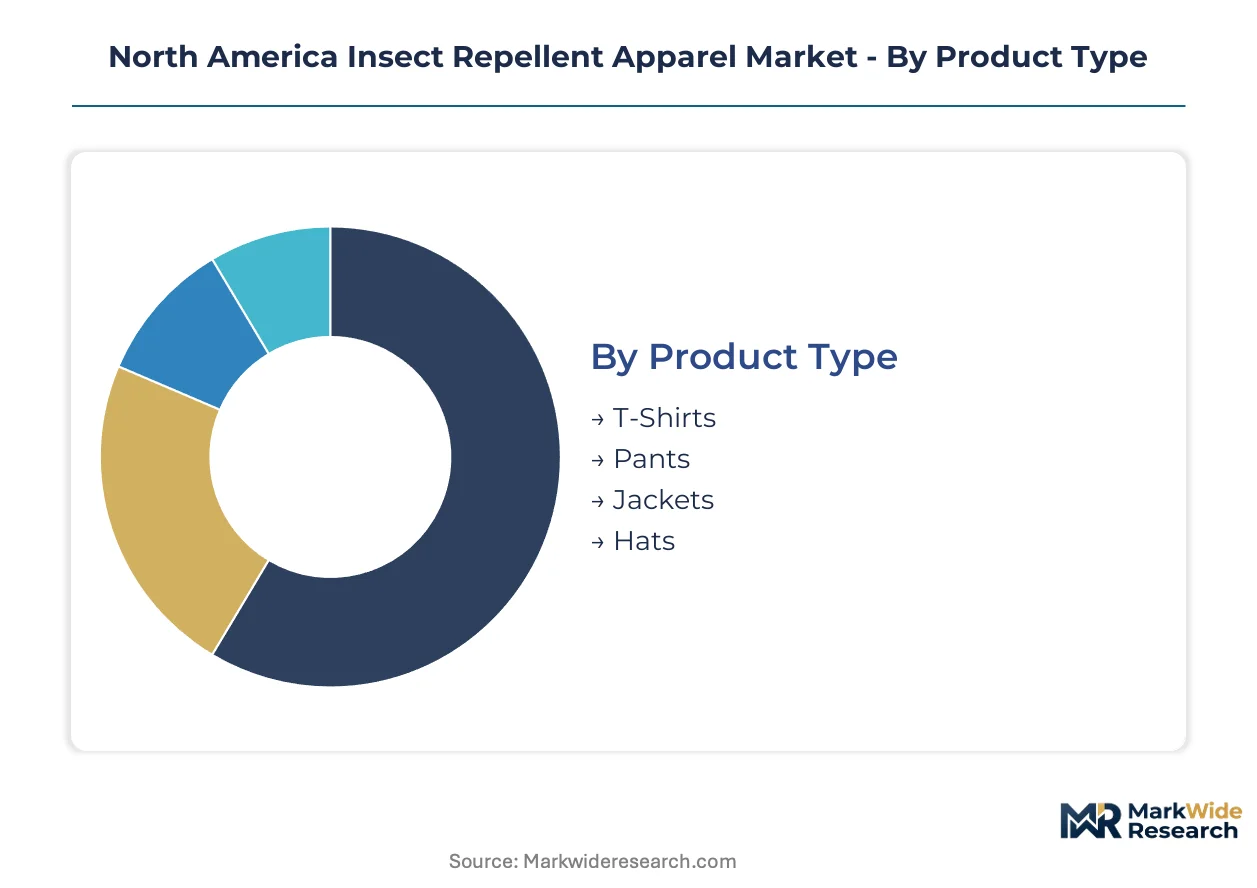
Segmentation in insect repellent apparel reveals distinct replacement cycles and margin structures that shape inventory planning and channel strategy. Understanding which garment categories turn over fastest versus which sustain multi-season use informs working capital allocation and promotional timing.
Product Type:
Replacement cycles vary dramatically across garment categories, with base layers requiring annual refresh while outerwear persists for multiple seasons.
- T-Shirts:Permethrin-bonded cotton and synthetic knits experience the shortest replacement cycles due to wash-frequency degradation and body-contact wear patterns. Demand clusters in Texas and Florida suburban markets where Health Canada and EPA messaging on tick-borne illness drives seasonal bulk purchasing ahead of spring gardening and summer trail use.
- Pants:Technical hiking trousers with integrated knee articulation and reinforced seat panels command higher per-unit economics and slower inventory turns. Appalachian Trail thru-hiker communities normalize treated base layers as standard equipment, creating durable word-of-mouth demand that sustains full-price sell-through outside promotional windows.
- Jackets:Waterproof-breathable laminates with bonded repellency occupy premium positioning with extended replacement horizons.
- Hats:Headwear with mesh ventilation and brim treatments serves specialized fly-fishing and desert hiking niches with intermittent purchase frequency.
T-Shirts dominate installed base. Pants is where expansion concentrates.
Fabric Type:
Material selection traces cost tiers from commodity synthetics to technical performance blends that justify price premiums through durability claims.
- Cotton:Natural fiber base layers with post-treatment permethrin bonding satisfy price-sensitive consumers in mass retail channels. Gardening segments in Florida and Texas prefer cotton for breathability during humid summer conditions, though wash durability lags synthetic alternatives.
- Polyester:Quick-dry synthetic knits and wovens anchor technical outdoor lines with superior wash-durable repellency adhesion. Pacific Northwest hiking communities drive polyester demand through moisture-management requirements during multi-day backpacking.
- Nylon:Abrasion-resistant face fabrics in fishing and climbing applications carry premium positioning.
- Blends:Cotton-polyester and nylon-spandex combinations optimize hand-feel and performance for boutique Colorado and Oregon manufacturers.
Polyester commands current volume leadership. Blends are climbing the fastest as technical specifications harden.
End Use:
Application context determines performance requirements, with occupational exposure and wilderness recreation demanding distinct efficacy standards and garment architectures.
- Outdoor Recreation:General trail use and day hiking represent the broadest addressable base with standardized EPA bioassay requirements. National park visitation in the United States sustains consistent purchasing through specialty retail education on proper wash-care protocols.
- Camping:Multi-day wilderness exposure elevates importance of wash-durable bonding chemistry and seam-sealed construction. Family camping segments in the Mountain West show seasonal concentration with pre-summer equipment preparation cycles.
- Fishing:Wading and bank-side applications prioritize quick-dry performance and abrasion resistance.
- Gardening:Suburban tick prevention drives replacement-heavy purchasing in southeastern United States markets.
Outdoor Recreation anchors current revenue. Camping is gaining share fastest as thru-hiking culture normalizes protective apparel.
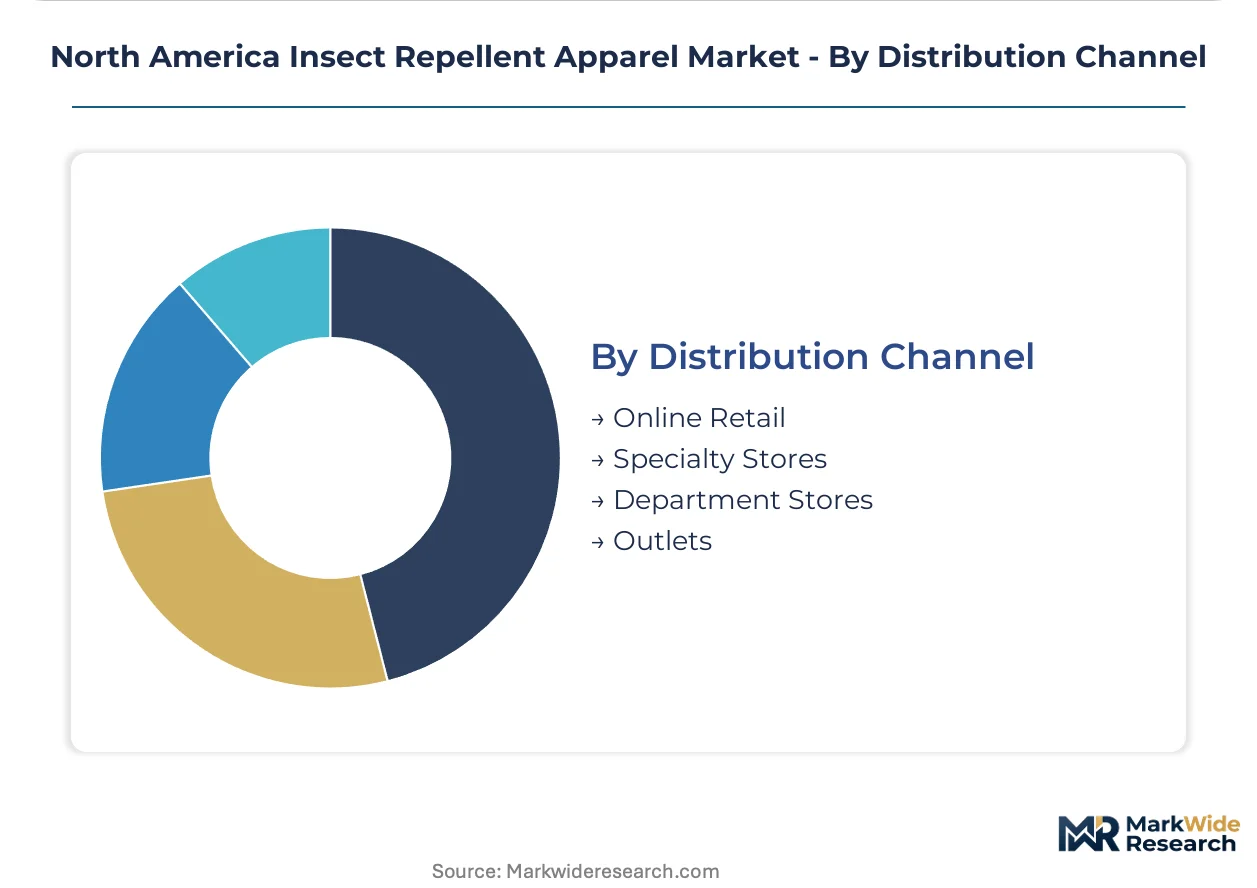
Distribution Channel:
Channel mix reflects customer education requirements, with complex products demanding trained staff and simple replenishment suited to digital fulfillment.
- Specialty Stores:Dedicated outdoor outfitters with trained staff demonstrate efficacy protocols and wash-care instructions that reduce return rates. Pacific Northwest and Mountain West concentrations sustain standalone retail footprints against e-commerce pressure through community embedding and trip-planning services.
- Online Retail:Direct-to-consumer platforms capture replenishment purchasing and subscription-model experimentation with seasonal box curation. Lower customer acquisition costs for replacement T-shirts and accessories offset higher return rates on fit-sensitive categories.
- Department Stores:General merchandise placements serve incidental purchasers with limited technical education.
- Outlets:Off-price channels move prior-season technical inventory with compressed margins.
Specialty Stores dominate premium positioning. Online Retail is where volume expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA registration requirements for permethrin-treated fabrics and Health Canada PMRA standards are elevating compliance costs while concentrating production among established finishers. State-level vector control programs in Texas and Florida supplement federal frameworks with localized public health messaging that stimulates seasonal demand spikes. Cross-border regulatory synchronization creates documentation burdens that delay unified North American launches.
United States
National park visitation and suburban gardening cultures sustain consistent purchasing across the Southeast and Mountain West. EPA mandates efficacy testing and label claims under FIFRA registration requirements that shape product development timelines. Appalachian Trail communities in Georgia and North Carolina normalize permethrin-treated base layers as standard equipment, creating durable word-of-mouth demand.
Canada
Health Canada enforces parallel PMRA standards for cross-border manufacturers, creating documentation duplication challenges. Provincial vector control programs in Ontario and British Columbia amplify tick-borne illness warnings that stimulate seasonal purchasing. Toronto and Vancouver outdoor retail clusters concentrate specialty outfitter footprints that educate consumers on wash-care protocols.
Mexico
Copper Canyon and Baja California trail systems attract North American adventure operators seeking bulk uniform contracts with integrated vector protection. Federal environmental regulations under SEMARNAT govern chemical treatment facilities operating near Mexico City and Monterrey industrial zones. Guadalajara and Nuevo León manufacturing clusters are piloting export-oriented finishing capacity for US brand licensees.
North America Insect Repellent Apparel Market Competitive Landscape
On the supply side, the industry is consolidating around established finishers with existing FIFRA clearances while boutique manufacturers experiment with botanical alternatives. Three strategic archetypes dominate: proprietary bonding technology licensors, integrated outdoor apparel brands with captive repellent product lines, and specialty outfitters curating third-party treated garments. Competitive moves concentrate on strategic partnerships for EPA registration sharing and portfolio diversification into adjacent protective categories.
Within the proprietary technology tier, Insect Shield LLC leverages its bonding expertise to sustain licensing partnerships across multiple apparel brands. Columbia Sportswear anchors integrated product line positioning through performance credentials rather than price competition. Patagonia occupies premium positioning that resists commoditization through repairable construction and environmental accountability frameworks.
| Leading Market Players |
|---|
| Insect Shield LLC |
| ExOfficio |
| Craghoppers |
| Columbia Sportswear |
| Patagonia |
| L.L.Bean |
| The North Face |
| Outdoor Research |
| Rohan Designs |
| Others |
Value Network & Pricing Analysis
Chinese agrochemical manufacturers cluster permethrin active ingredient production, anchoring cost structures for North American finishers while EPA registration requirements concentrate margin pools among established brands with existing FIFRA clearances. This upstream concentration forces downstream pricing stratification between registered premium tiers and unregistered economy alternatives.
Pricing Analysis
Volume-discount tiering separates enterprise uniform contracts from individual consumer purchases, with landscaping crews and adventure operators securing favorable unit economics against full retail markup. Certification grade under FIFRA registration and wash-durable bonding chemistry performance differentiate premium Columbia Sportswear and Patagonia positioning from mass-market cotton basics. Cost compression in economy cotton tiers intensifies as untreated technical apparel from standard outdoor brands captures price-sensitive trail users. Suburban gardeners in Texas and Florida exhibit highest price sensitivity, while Appalachian Trail thru-hikers prioritize performance credentials over unit cost.
Supply Chain Analysis
Permethrin feedstock production concentrates in China, with Indian chemical intermediates and US-based textile finishing completing the value chain. Active ingredient supply draws from agrochemical specialists, woven and knit fabrics from Vietnam and Bangladesh, and bonding chemistry from domestic specialty chemical formulators. Tariff exposure on Chinese permethrin imports creates margin volatility for finishers without long-term supply agreements. Distribution runs through specialty outdoor outfitters in the Mountain West and Pacific Northwest, supplemented by direct-to-consumer platforms for replenishment purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
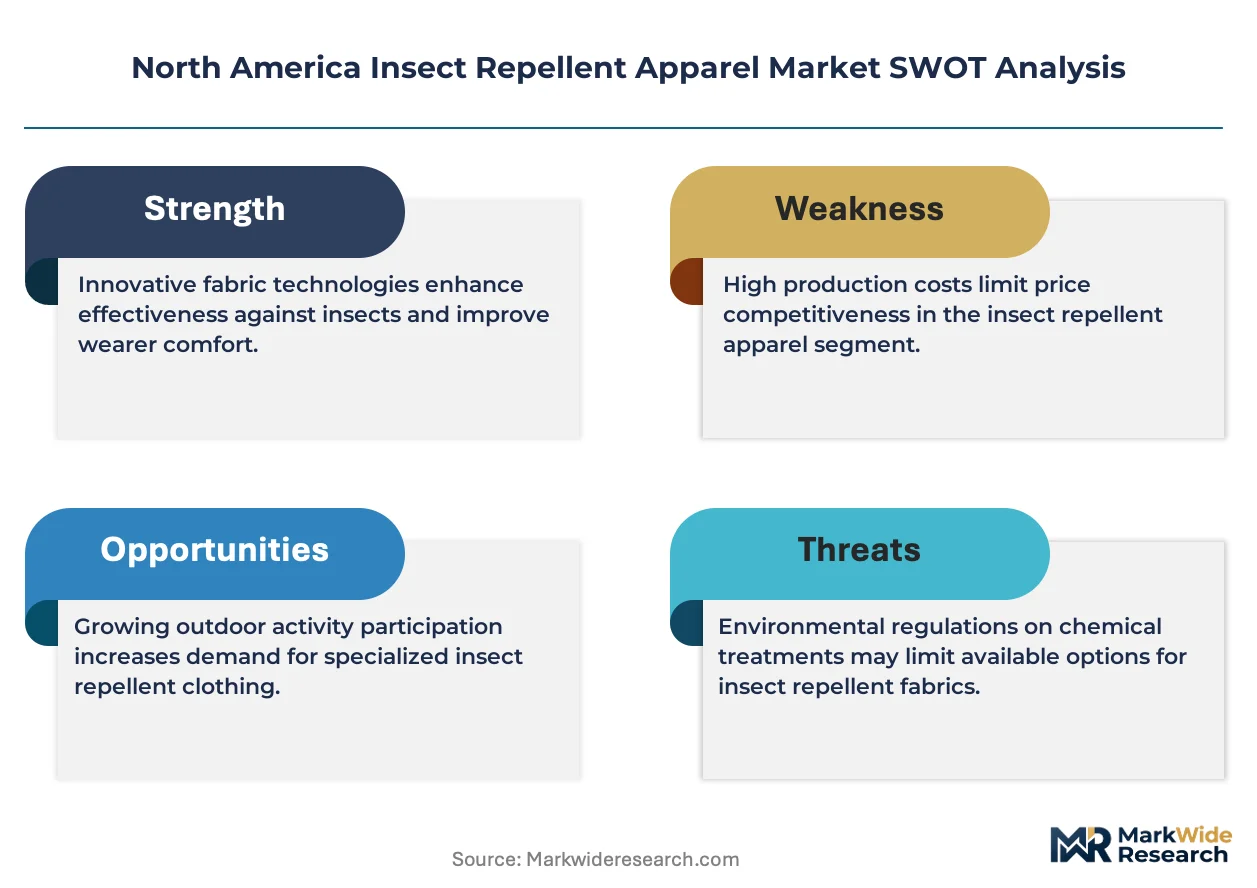
This market demands substitution defense against untreated high-performance synthetic base layers that satisfy comfort requirements without repellency premiums. Incumbents must navigate this threat through performance differentiation and channel control.
For Market Incumbents: Entrench market position by deepening captive supply of EPA-registered bonding chemistry and expanding proprietary licensing footprints across boutique outdoor brands. Prioritize certification investment in botanical active ingredient pathways that bypass FIFRA registration burdens as regulatory hedging against permethrin renewal compression.
For New Entrants and Emerging Players: OSHA-compliant employer-funded PPE programs for landscaping and utility vegetation management crews represent the most penetrable entry point, with bulk uniform contracts offering predictable revenue streams. Mexico outdoor tourism infrastructure in Copper Canyon and Baja California trail systems presents secondary white-space for adventure operator partnerships. Direct-to-consumer subscription models with seasonal replenishment curation provide the optimal go-to-market angle for bypassing established retail gatekeepers.
For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated finishers with existing FIFRA clearances and proprietary bonding technology portfolios, as regulatory barriers compound acquisition premiums over organic build timelines. Long-term viability hinges on botanical formulation diversification and cross-border Health Canada PMRA synchronization capabilities. Monitor EPA registration renewal schedules for permethrin-treated fabrics as the critical inflection signal for incumbent valuation compression or consolidation acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Botanical Active Ingredient R&D | Plant-derived repellent pathways bypass FIFRA registration burdens while satisfying REACH-aligned regulatory trajectories. |
| OSHA Workplace Safety Integration | Employer-funded PPE programs for landscaping crews expand addressable market beyond recreational consumer segments. |
| Direct-to-Consumer Subscription Launch | Seasonal replenishment models capture lifetime value while bypassing specialty retail markup structures. |
| Mexico Manufacturing Footprint Expansion | Guadalajara and Nuevo León clusters enable export-oriented finishing capacity for US brand licensees. |
| PMRA Registration Synchronization | Unified North American launch timelines reduce documentation duplication and accelerate Canadian market access. |
Research Methodology
Desk research of EPA registration databases, FIFRA label claim records, and Health Canada PMRA submission precedents preceded structured interviews with textile finishing plant managers, outdoor apparel brand product development directors, specialty retail buyers, and vector control program officers at state health departments. Secondary validation drew from customs trade data on permethrin imports, SEC filings of publicly traded outdoor apparel companies, and national park visitation statistics. Bottom-up unit economics modeling triangulated against top-down market sizing from regulatory filing volumes and retail channel audits.
Assumptions held fixed include EPA registration renewal timelines for permethrin-treated fabrics and prevailing tariff structures on Chinese active ingredient imports, while vector-borne disease surveillance intensity and botanical formulation efficacy were varied across sensitivity scenarios. Segmentation dimensions encompassed product type, fabric technology, end-use application context, and distribution channel concentration. CAGRs were derived from regression analysis of historical replacement cycle data and projected outdoor recreation participation trends, with Appalachian Trail thru-hiker equipment surveys and suburban gardening segment purchase pattern studies informing demand elasticity parameters.
Practitioners should monitor EPA guidance updates on treated article exemptions and emerging state-level vector control program funding levels for early signals of regulatory or demand trajectory revision. Cross-checking against Health Canada PMRA registration processing timelines and SEMARNAT environmental compliance enforcement patterns is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel Textiles
Smart Clothing Market
Apparel Textiles
Bamboo Apparel Market
Apparel Textiles
South America Lingerie Market
Apparel Textiles
Thailand Garment Industry Market
Apparel Textiles
Apparel Supply Chain Market
Apparel Textiles
Flame Retardant Apparel Market
Apparel Textiles
Clothing Manufacturing Service Market
Apparel Textiles
Cooling Apparel Market
Apparel Textiles
Middle East and Africa Textile Garment Market
Apparel Textiles
Rolle Market
Apparel Textiles
Global Textile Garment Market
Apparel Textiles
Head Scarves Market
Apparel Textiles
Global Socks Market
Apparel Textiles
North America Footwear Sole Material Market
Apparel Textiles
Hosiery Market
Apparel Textiles
Cleanroom Apparels Market