
 Cooling Apparel Market | 2026-2036
Cooling Apparel Market Size, Share, and Industry Trends Forecast 2026-2036
Cooling Apparel Market Insights
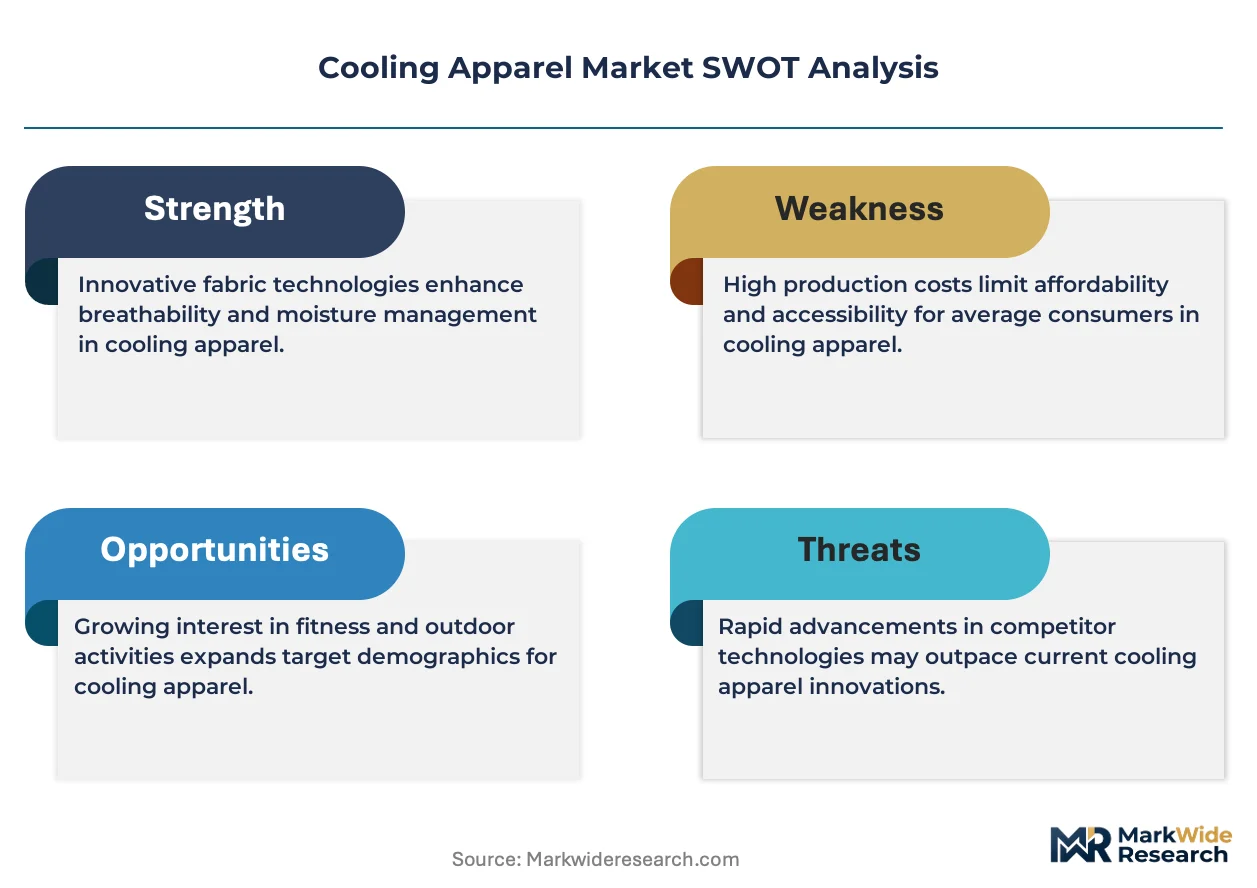
Modular layering systems is rebalancing how buyers configure cooling solutions, shifting from single-purpose garments toward interchangeable base-mid-outer combinations. Nike leverages its sportswear R&D pipeline to sustain innovation in breathable knit structures. Under Armour anchors its position through direct-to-consumer channel control and athlete endorsement density. Columbia Sportswear competes via geographic dominance in outdoor retail and weather-adaptive fabric portfolios.
Cooling apparel comprises engineered garments designed to regulate body temperature through evaporative, conductive, or phase-change mechanisms, typically incorporating specialized polymers, moisture-management weaves, or encapsulated cooling media to maintain thermal comfort during exertion or heat exposure. The primary commercial purpose spans occupational safety compliance, athletic performance optimization, and recreational thermal protection in elevated-temperature environments. Shirts and headwear lead volume as entry-point categories with the lowest price friction for first-time buyers, while jackets command the strongest margin pools due to complex construction and material intensity. Sports enthusiasts and industrial workers represent the most structurally significant end-user bifurcation, with the latter segment tethered to regulatory compliance budgets rather than discretionary spending cycles.
OSHA heat-illness prevention standards and the EPA's chemical exposure frameworks for treated textiles shape product certification requirements and manufacturing protocols in the United States, while ISO thermal-resistance testing standards govern cross-border quality benchmarking. The EU's REACH chemical restrictions and CE marking obligations for personal protective equipment create parallel compliance pathways for export-oriented suppliers. Stakeholders must monitor evolving heat-stress threshold regulations across multiple jurisdictions to anticipate procurement mandate shifts and material substitution timelines.
Market Dynamics
Phase-change material innovations are compressing garment refresh cycles while OSHA heat-illness prevention rules force procurement departments to accelerate specification upgrades across construction and logistics verticals.
Growth Catalysts
- OSHA Heat-Illness Prevention Standards:Tightened enforcement thresholds in the United States mandate employer-provided cooling garments for outdoor workers above specified wet-bulb temperatures, converting discretionary safety spending into compliance-driven procurement.
- Phase-Change Material Advances:Encapsulated paraffin and salt-hydrate formulations now sustain sub-ambient skin contact temperatures for 2-4 hours, extending viable wear-time in high-exertion industrial applications.
- Construction Sector Expansion:Infrastructure project acceleration across the southern United States creates concentrated demand nodes where heat-stress protocols intersect with large, unionized workforces.
Market Restraints
- Petrochemical Feedstock Volatility:Specialized polyester and polyamide polymers for moisture-wicking weaves track crude oil and natural gas derivatives, compressing margin buffers for mid-tier manufacturers.
- East Asian Dyeing Concentration:70%+ of functional textile finishing capacity clusters in Zhejiang and Guangdong provinces, exposing supply chains to regional energy rationing and environmental compliance shocks.
- Evaporative Cooling Limitations:High-humidity environments above 75% relative humidity nullify evaporative garment effectiveness, restricting addressable markets in subtropical coastal zones.
Strategic Opportunities
- Indian Industrial Corridors:PLI scheme incentives for technical textiles and BIS standardization of occupational heat-stress limits create first-mover positioning for cooling garment suppliers in Gujarat and Tamil Nadu manufacturing belts.
- Last-Mile Delivery Fleets:E-commerce logistics operators are piloting driver cooling vests as retention tools in Phoenix, Dubai, and Riyadh where cab temperatures exceed 50°C during summer peaks.
- ISO 11079 Thermal Comfort Integration:Adoption of international thermal-environment assessment standards by multinational employers enables specification harmonization across country operations, favoring certified garment suppliers.
Industry Challenges
- Phase-Change Recharge Infrastructure:Industrial laundries and on-site cooling stations require capital deployment for PCM regeneration cycles, creating adoption friction among small-contractor segments.
- Multi-Jurisdiction Certification Overlap:Simultaneous CE marking for PPE, EPA chemical exposure compliance for antimicrobial treatments, and state-level OSHA plan variations extend product launch timelines by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cooling Apparel Market |
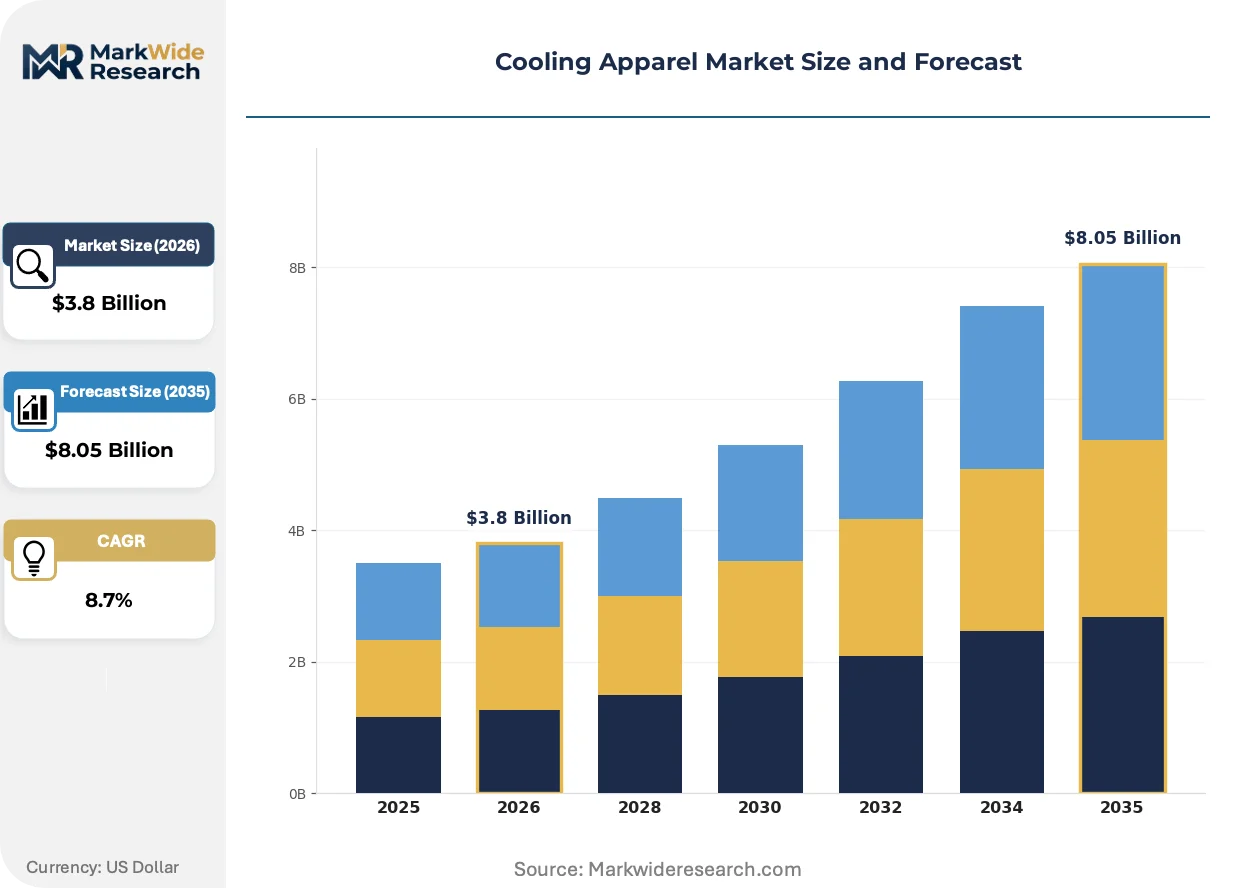
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shirts, Jackets, Pants, Headwear End User: Sports Enthusiasts, Industrial Workers, Outdoor Adventurers, Fitness Professionals Material: Polyester, Nylon, Cotton, Blends Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales |
| Companies Covered | Nike, Under Armour, Adidas, Columbia Sportswear, The North Face, Patagonia, Lululemon Athletica, Reebok, Mizuno, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cooling Apparel Market Trends and Innovations
Material science convergence with digital manufacturing is collapsing traditional garment development timelines while regulatory fragmentation forces parallel certification track investments.
Biomimetic evaporative structures derived from plant stomata and insect cuticle designs are integrating into knit architectures for enhanced moisture transport. Marathon and ultra-endurance athletes in Arizona and Australia are adopting these garments at 3x prior-year rates. The technology is integrating base-layer and mid-layer functions into single garments, compressing category purchase decisions and reducing inventory carrying costs for specialty retailers.
REACH chemical restrictions on per- and polyfluoroalkyl substances (PFAS) are forcing reformulation of durable water-repellent coatings across EU-exporting suppliers. German and Dutch textile finishers are accelerating fluorine-free alternatives through ECHA pre-registration pathways. Military and first-responder segments face the steepest compliance timelines given dual-use certification requirements spanning NATO standardization agreements.
Direct-to-industrial procurement platforms are displacing traditional distributor networks for standardized cooling garments. Facility safety managers in Texas oilfield services and Saudi petrochemical complexes now specify through centralized enterprise resource planning integrations rather than regional PPE distributors. This channel compression concentrates volume with manufacturers maintaining API-compliant documentation portals and same-day configuration capabilities.
Cooling Apparel Market Segmentation
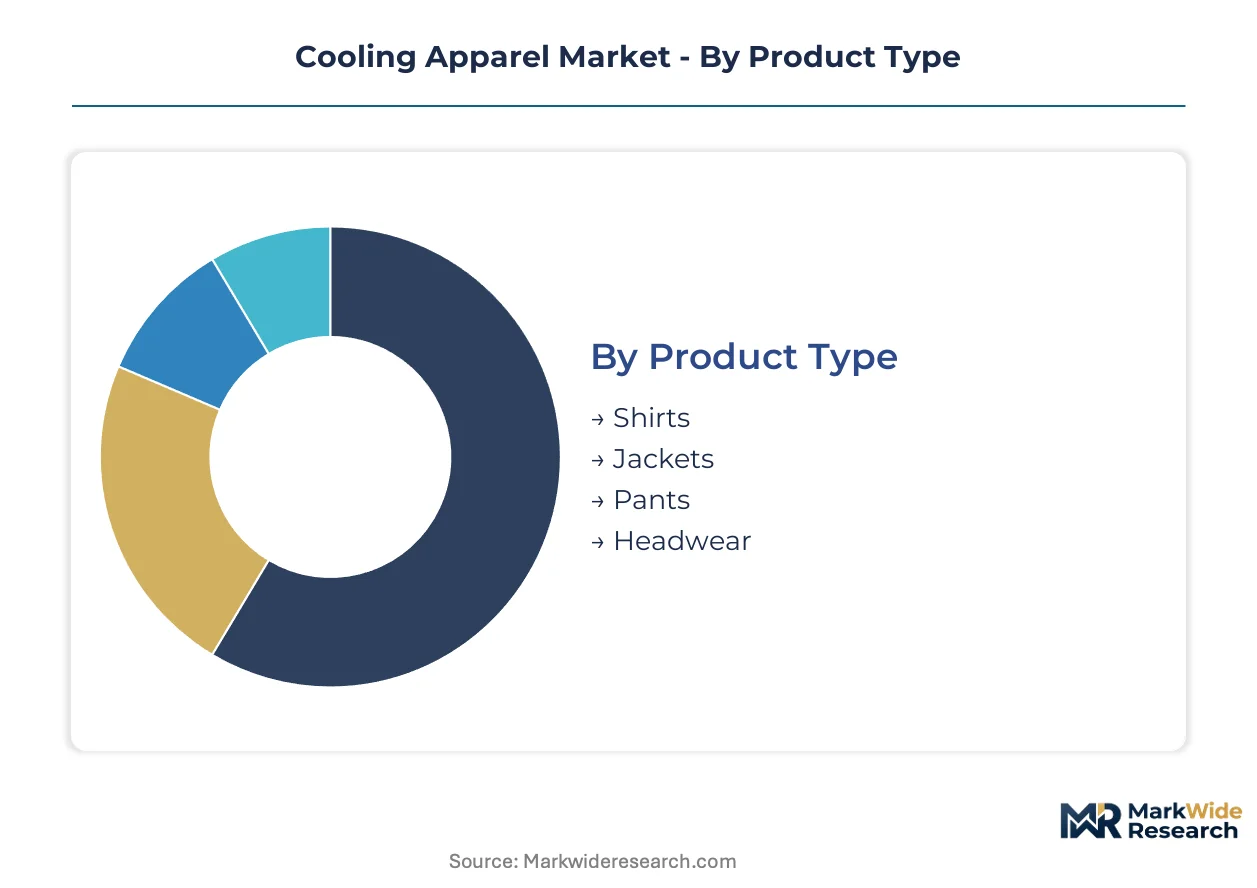
Cooling apparel segmentation reveals divergent capital requirements across manufacturing tiers. Product complexity and material science intensity determine which configurations absorb tooling investment versus which scale through commodity textile infrastructure.
Product Type:
Capital intensity peaks with garments requiring encapsulated cooling media and multi-layer lamination, while basic moisture-wicking constructions leverage existing knitting capacity.
- Jackets:Complex constructions integrate phase-change material pouches, breathable membranes, and reinforced abrasion zones. Demand concentrates in oilfield services across Texas and North Dakota where employers specify API-compliant thermal protection for cold-weather base layers with cooling compatibility.
- Shirts:Engineered knit structures with zoned ventilation panels dominate volume production. Arizona construction contractors and Florida agricultural operations purchase moisture-wicking polos as baseline heat-stress compliance garments under tightened OSHA enforcement.
- Pants:Knee-articulated designs with evaporative mesh backing serve logistics warehouse workers in California's Central Valley.
- Headwear:Neck gaiters and evaporative caps represent the lowest capital entry point for new suppliers targeting recreational cyclists.
Shirts absorb the bulk of installed capacity; jackets are expanding most quickly.
End User:
Customer procurement patterns separate compliance-driven institutional buyers from discretionary individual purchasers with divergent price elasticity.
- Industrial Workers:Unionized construction crews and petrochemical maintenance contractors purchase through employer-funded programs. Saudi Aramco and ExxonMobil facilities in the Gulf Coast mandate cooling vests for turnaround operations above wet-bulb temperature thresholds.
- Sports Enthusiasts:Marathon runners and gravel cyclists in Australia's Northern Territory and Arizona's Sonoran Desert adopt biomimetic evaporative designs at accelerating rates.
- Outdoor Adventurers:Backpackers and desert hikers in Utah's canyon country seek packable cooling accessories for multi-day excursions.
- Fitness Professionals:CrossFit box owners and personal trainers purchase branded cooling towels as client retention tools in steamy southeastern states.
Industrial Workers command the largest contract values; Sports Enthusiasts show the steepest expansion trajectory.
Material:
Feedstock selection determines which suppliers can access technical textile finishing capacity versus commodity polymer streams.
- Polyester:Specialized PET polymers with engineered cross-sections for capillary moisture transport require dedicated melt-spinning lines. Zhejiang province hosts the concentrated finishing capacity for wicking treatments.
- Nylon:Polyamide 6,6 formulations deliver superior abrasion resistance for industrial applications. German automotive suppliers specify nylon-based cooling garments for foundry workers under REACH-compliant chemical frameworks.
- Cotton:Natural fiber blends appeal to EU consumers avoiding synthetic microfiber shedding under French and Dutch environmental guidelines.
- Blends:Cotton-polyester combinations balance comfort and performance for price-sensitive municipal worker programs in India's Gujarat state.
Polyester dominates current output volumes; Nylon is climbing the fastest on industrial specification upgrades.
Distribution Channel:
Channel configuration determines working capital intensity and documentation burden for supplier compliance.
- Direct Sales:Enterprise procurement portals for Fortune 500 industrial operators demand API integrations and same-day configuration. Saudi petrochemical complexes and Texas oilfield services now route cooling garment orders through centralized ERP systems.
- Online Retail:Amazon and brand-direct storefronts serve individual athletes with minimal certification documentation. Arizona and Australian consumers purchase evaporative accessories through these channels at 3x prior-year velocity.
- Specialty Stores:REI and regional outdoor retailers carry premium PCM garments with trained staff consultation for desert hiking segments.
- Supermarkets:Mass merchandisers stock entry-level cooling towels for impulse purchase in seasonal displays across southern US states.
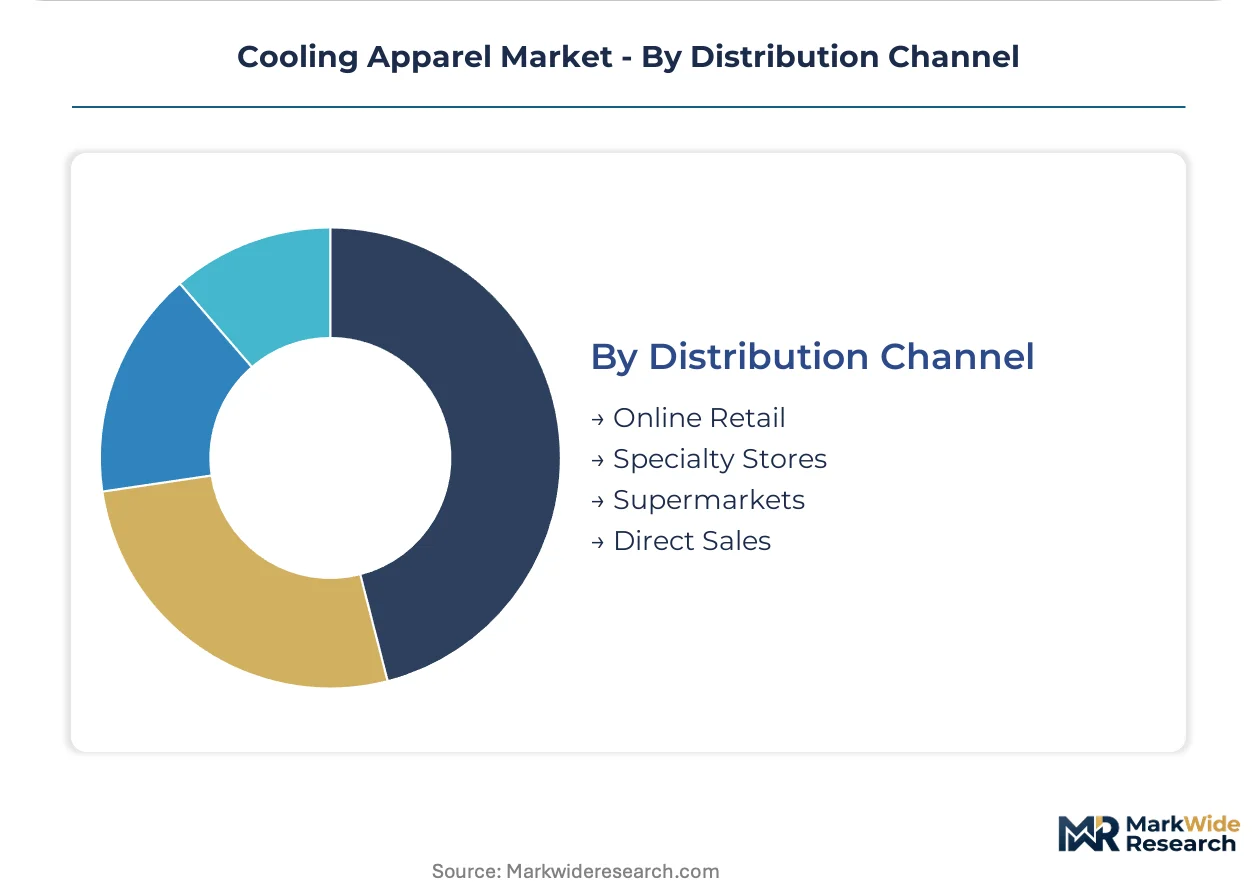
Direct Sales captures the largest transaction sizes; Online Retail is gaining share fastest on convenience preferences.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters in East Asian textile finishing hubs while consumption concentrates in North American and Gulf industrial corridors where heat-stress regulations mandate employer-funded procurement. This geographic split creates divergent competitive requirements for suppliers.
United States
OSHA heat-illness prevention standards convert discretionary safety spending into compliance-driven procurement across construction and logistics verticals. The EPA's chemical exposure frameworks govern treated textile certification requirements for antimicrobial cooling garments. Texas oilfield services and Arizona construction contractors anchor demand concentration in the southern states where wet-bulb temperature thresholds trigger mandatory cooling vest programs.
Germany
REACH chemical restrictions and CE marking obligations for personal protective equipment create parallel compliance pathways for export-oriented cooling garment suppliers. The ECHA pre-registration pathway accelerates fluorine-free durable water-repellent alternatives for military and first-responder segments. German automotive suppliers specify nylon-based cooling garments for foundry workers under REACH-compliant chemical frameworks in the industrial belts of Baden-Württemberg and North Rhine-Westphalia.
China
Zhejiang and Guangdong provinces host over seventy percent of functional textile finishing capacity for moisture-wicking treatments and phase-change material encapsulation. GB standards and MIIT technical textile directives shape domestic product specifications while dual carbon goals pressure energy-intensive dyeing operations. The Yangtze River Delta manufacturing corridor supplies polyester polymers with engineered cross-sections for capillary moisture transport to global cooling apparel brands.
India
PLI scheme incentives for technical textiles and BIS standardization of occupational heat-stress limits create first-mover positioning opportunities in Gujarat and Tamil Nadu manufacturing belts. CDSCO regulates antimicrobial-treated cooling garments for healthcare worker applications. The Gujarat industrial corridor attracts cooling garment suppliers seeking proximity to petrochemical feedstock sources and export-oriented special economic zones.
Saudi Arabia
SFDA oversight of medical-grade cooling garments intersects with extreme ambient temperature conditions exceeding fifty degrees Celsius during summer peaks. Saudi Aramco facilities mandate cooling vests for turnaround operations above wet-bulb temperature thresholds. The Eastern Province petrochemical complexes and Riyadh logistics hubs concentrate employer-funded procurement for industrial worker protection programs.
Cooling Apparel Market Competitive Landscape
The competitive structure tilts toward diversified sportswear conglomerates with technical textile R&D pipelines. Market position reflects brand equity in athletic performance segments and direct-to-consumer channel control rather than manufacturing scale. Two strategic archetypes dominate: integrated sportswear houses leveraging cross-category material science investments, and specialized outdoor apparel firms competing through weather-adaptive fabric portfolios. Competitive moves concentrate on athlete endorsement density and enterprise procurement portal integration for industrial safety segments.
Within the integrated sportswear tier, Nike and Under Armour exemplify archetypes anchored in breathable knit structure innovation and channel control respectively. Columbia Sportswear occupies a position representing geographic dominance in outdoor retail distribution. These three companies illustrate how competitive position derives from divergent capability investments—R&D pipeline depth, direct-to-consumer infrastructure, and retail partnership density—rather than convergent operational scale.
| Leading Market Players |
|---|
| Nike |
| Under Armour |
| Adidas |
| Columbia Sportswear |
| The North Face |
| Patagonia |
| Lululemon Athletica |
| Reebok |
| Mizuno |
| Others |
Pricing and Supply Chain Analysis
OSHA heat-illness prevention mandates are compressing procurement timelines for industrial cooling garments, forcing suppliers to absorb certification costs upfront while passing selective premiums to compliance-driven buyers in Texas and Arizona construction corridors.
Pricing Analysis
Cost-down pressure on mid-tier manufacturers accelerates because petrochemical feedstock volatility in polyester and polyamide polymers erodes margin buffers. Pricing stratifies across premium PCM-integrated garments, standard moisture-wicking polos, and economy cooling towels. Price differentiation hinges on certification grade—OSHA-compliant industrial specifications command premiums versus recreational-grade evaporative accessories. Unionized construction crews in Saudi Aramco facilities show lowest price sensitivity; municipal worker programs in India's Gujarat state exhibit highest elasticity.
Supply Chain Analysis
Direct-to-industrial procurement portals now handle Fortune 500 enterprise demand, displacing regional PPE distributors. Manufacturing concentrates in China's Zhejiang and Guangdong provinces for functional textile finishing, with Germany and India emerging for REACH-compliant and PLI-incentivized production respectively. Raw material dependencies center on specialized PET polymers, polyamide 6,6 formulations, and encapsulated paraffin PCM media. Single-source vulnerability in East Asian dyeing capacity—exposed to energy rationing shocks—represents the dominant supply chain risk.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance arena where OSHA heat-illness prevention standards erect barrier-to-entry moats favoring suppliers with pre-certified product portfolios and API-compliant documentation infrastructure.
For Market Incumbents: Cement market position through backward integration into PCM encapsulation capacity and captive control over Zhejiang finishing partnerships. Defend against direct-to-industrial procurement displacement by embedding same-day configuration APIs into buyer ERP systems. Prioritize REACH-compliant fluorine-free DWR reformulation ahead of ECHA enforcement timelines. For New Entrants and Emerging Players: Launch via specialty outdoor retail channels targeting Arizona and Australian desert hiking segments with biomimetic evaporative designs. Exploit white-space in Indian industrial corridors where BIS standardization of occupational heat-stress limits creates first-mover windows. Pursue white-label manufacturing partnerships with Gujarat-based technical textile producers to bypass capital-intensive finishing infrastructure. For Investors and Strategic Acquirers: Re-rating potential sits with specialized outdoor apparel firms possessing weather-adaptive fabric portfolios and CE-marked PPE certification depth, given ISO 11079 thermal comfort standard adoption by multinational employers. Long-term viability favors suppliers with dual-use military-civilian certification pathways. Monitor wet-bulb temperature threshold revisions across OSHA state-plan jurisdictions as the critical inflection signal for procurement mandate acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PCM Encapsulation | Captive control over phase-change material regeneration cycles reduces reliance on third-party chemical processors in Guangdong. |
| Direct-to-Industrial ERP Integration | API-compliant documentation portals capture Texas oilfield and Saudi petrochemical procurement volume from distributor networks. |
| REACH-Compliant DWR Reformulation | Fluorine-free alternatives through ECHA pre-registration pathways secure EU military and first-responder segment access. |
| Biomimetic Evaporative Product Launch | Plant stomata-derived knit architectures penetrate Arizona and Australian endurance athlete segments at 3x prior-year velocity. |
| Indian Manufacturing Footprint Expansion | PLI scheme incentives in Gujarat and Tamil Nadu belts position suppliers for BIS-standardized industrial procurement. |
Research Methodology
Regulatory filing databases, customs trade records, and technical textile industry associations formed the secondary backbone, cross-referenced with primary interviews involving safety procurement managers at Texas oilfield services, Arizona construction contractors, German automotive foundry operators, and specialty outdoor retail buyers. Bottom-up and top-down triangulation validated segment-level demand estimates against OSHA enforcement data and employer mandate disclosure patterns.
Bottom-up modeling anchored volume projections to wet-bulb temperature threshold triggers and employer compliance spending across construction, logistics, and petrochemical verticals, while top-down cross-checks assessed macro-level technical textile consumption trends. Segmentation dimensions included product type, end-user procurement pattern, material feedstock, and distribution channel configuration. CAGRs derived from regression analysis of historical adoption curves against regulatory enforcement intensity metrics, with phase-change material refresh cycle compression and evaporative cooling humidity limitations incorporated as industry-specific forecast inputs.
Regulatory timeline delays, petrochemical price volatility spikes, and East Asian energy rationing events are the dominant revision risks to base-case projections. Periodic stress-testing of base assumptions against OSHA state-plan variation announcements and ECHA substance restriction updates is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel Textiles
Braille Clothing Tags Market
Apparel Textiles
Smart Apparel Market
Apparel Textiles
Thailand Garment Industry Market
Apparel Textiles
North America Textile Garment Market
Apparel Textiles
Europe Textile Garment Market
Apparel Textiles
Middle East and Africa Footwear Sole Material Market
Apparel Textiles
Africa Textile Market
Apparel Textiles
South America Lingerie Market
Apparel Textiles
Global Western Wear Market
Apparel Textiles
Women's Cheongsam Market
Apparel Textiles
Sweat Resistant Apparel Market
Apparel Textiles
Down Jacket Market
Apparel Textiles
Asia-Pacific Textile Garment Market
Apparel Textiles
Cleanroom Apparels Market
Apparel Textiles
Flame Retardant Apparel Market
Apparel Textiles
Global Prom Dresses Market