
 China Denim Jeans Market | 2026-2036
China Denim Jeans Market Size, Share, and Industry Trends Forecast 2026-2036
China Denim Jeans Market Insights
A capital-intensity divergence between integrated mills and cut-make-trim operators is redrawing competitive boundaries in China's denim sector. Texhong Textile Group leverages captive yarn and fabric capacity to sustain margin control through upstream ownership. Black Peony (Group) Co., Ltd. anchors its position through specialized indigo dyeing infrastructure that smaller rivals cannot replicate. Dongguan Xiaofeiniu Garment Co., Ltd. (DiZNEW) competes via flexible batch production for domestic e-commerce labels.
China denim jeans denote cotton twill trousers with indigo-dyed warp threads, typically woven at 3×1 or 2×1 twill construction with fabric weights ranging from 10 to 14 ounces per square yard, serving as durable casual and semi-formal apparel. Skinny jeans and straight cut dominate unit volume among young adult and professional demographics, while stretch denim incorporating elastane blends commands premium positioning in urban retail channels. Selvedge denim maintains a niche but high-margin presence in specialty stores and online retail platforms targeting heritage-conscious consumers.
China's SAMR enforces GB 18401 national general safety technical code for textile products, while MEE implements wastewater discharge standards that constrain dyehouse operations in the Pearl River Delta. These frameworks elevate compliance costs for smaller finishers and accelerate consolidation toward enterprises with certified environmental management systems. Stakeholders must monitor evolving water-use quotas and chemical restriction lists that will determine which finishing technologies retain market access.
Market Dynamics
China's denim sector faces a structural squeeze between tightening MEE wastewater mandates in the Pearl River Delta and the capital requirements of laser finishing and ozone washing technologies that smaller finishers cannot fund.
Growth Catalysts
- GB 18401 Safety Compliance:SAMR enforcement of national textile safety codes drives certified producers to capture shelf space in domestic retail chains that reject uncertified imports.
- Laser Denim Finishing:Guangdong Province manufacturers adopt laser-based surface treatment to reduce water consumption and chemical discharge while accelerating style turnaround for e-commerce labels.
- Shanghai-Beijing Professional Casualization:Young adult professionals in these tier-one cities expand denim purchases as workplace dress codes relax, creating pull-through for mid-premium stretch selvedge lines.
Market Restraints
- Indigo Dye Input Volatility:Synthetic indigo prices fluctuate with petrochemical feedstock costs, squeezing margin at specialized dyehouses without captive chemical production.
- Pearl River Delta Supply Concentration:Finishing capacity clusters around Dongguan and Guangzhou, exposing the national supply base to simultaneous water-quota restrictions and regional climate disruptions.
- MEE Wastewater Standards:Discharge limits for chemical oxygen demand and heavy metals force dyehouses to install tertiary treatment or exit, accelerating consolidation toward capital-heavy operators.
Strategic Opportunities
- Western China Manufacturing Migration:Sichuan and Chongqing offer lower labor costs and less stringent water quotas for denim finishing, attracting cut-make-trim operators seeking margin relief.
- Closed-Loop Water Recycling:MEE incentives for zero-liquid-discharge systems create first-mover advantage for mills investing in membrane filtration and evaporative recovery infrastructure.
- Livestream Commerce Integration:Domestic e-commerce labels bypass traditional wholesale channels by partnering directly with flexible batch producers for made-to-order capsule releases.
Industry Challenges
- Laser Technician Scarcity:Guangdong manufacturers struggle to recruit operators capable of programming complex abrasion patterns for laser finishing equipment.
- GB Standard Certification Timelines:Testing laboratory backlogs delay product launches by 6-12 weeks, compressing seasonal windows for fast-fashion denim labels.
- Legacy Dyehouse Retrofit Costs:Conventional indigo rope-dyeing lines require multimillion-yuan capex to meet MEE effluent standards, stranding smaller finishers without access to green financing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Denim Jeans Market |
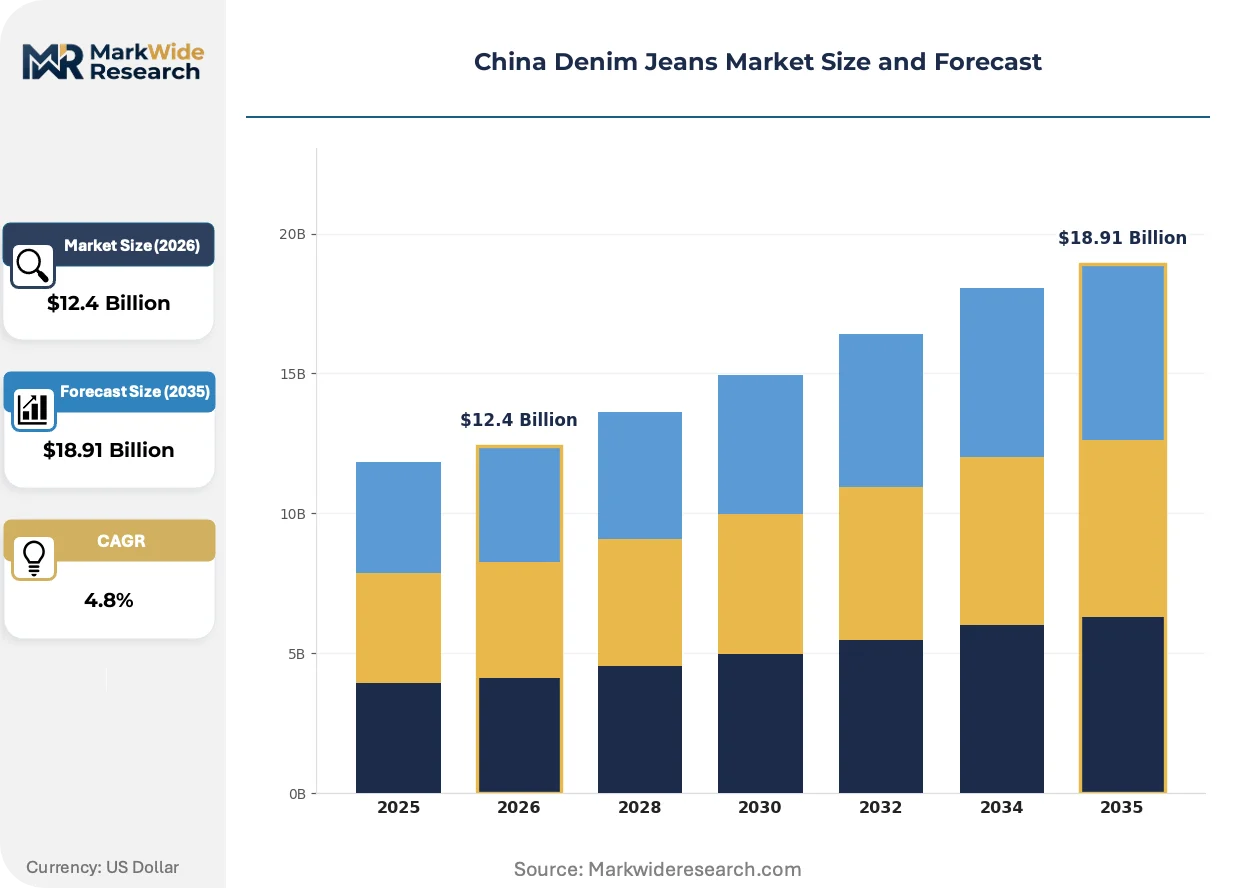
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $18.91 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skinny Jeans, Straight Cut, Bootcut, Relaxed Fit, Tapered, Flared Fabric Technology: Selvedge Denim, Stretch Denim, Organic Cotton Denim, Indigo Dye, Stonewashed, Bleached Consumer Demographic: Teens, Young Adults, Middle-aged, Seniors, Students, Professionals Distribution Channel: Online Retail, Department Stores, Specialty Stores, Outlet Malls, Pop-up Shops, E-commerce Platforms |
| Companies Covered | Henan Newasia Garment Co., Ltd. (INNBLAC), China-Jeans (Guangzhou Cunzhuang Clothing Co., Ltd.), TAL Apparel, Guangzhou Lepanchuang Garment Co., Ltd., Foshan Fly Jeans, Black Peony (Group) Co., Ltd., Dongguan Xiaofeiniu Garment Co., Ltd. (DiZNEW), QYOURECLO, Texhong Textile Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Denim Jeans Market Trends and Innovations
Laser and ozone-based finishing technologies are compressing traditional wet-process timelines while MEE regulatory pressure accelerates environmental hardware adoption across Guangdong manufacturing clusters.
Plasma and ozone surface treatments are supplanting potassium permanganate spray and stonewash methods that consume thousands of liters per garment. Guangzhou-based export manufacturers deploy these systems to meet EU buyer sustainability scorecards. The technology is supplanting conventional finishing capacity as water-recycling mandates render wet-process economics untenable for mid-scale operators.
MEE's 2023 amendments to wastewater discharge standards for the textile sector impose stricter limits on aniline derivatives and heavy metals in effluent. Dyehouses in the Pearl River Delta must install advanced oxidation or membrane bioreactor systems to retain operating licenses. Premium selvedge producers absorb compliance costs more readily than commodity denim finishers, widening the competitive gap between tiers.
Domestic e-commerce labels now contract directly with Dongguan cut-make-trim shops for micro-batch production, bypassing traditional wholesale fabric markets. Young adult consumers in Beijing and Shanghai discover styles through livestream sessions rather than physical retail. This channel compression concentrates demand volatility at the manufacturing tier, rewarding flexible batch producers with sub-two-week turnaround capability.
China Denim Jeans Market Segmentation
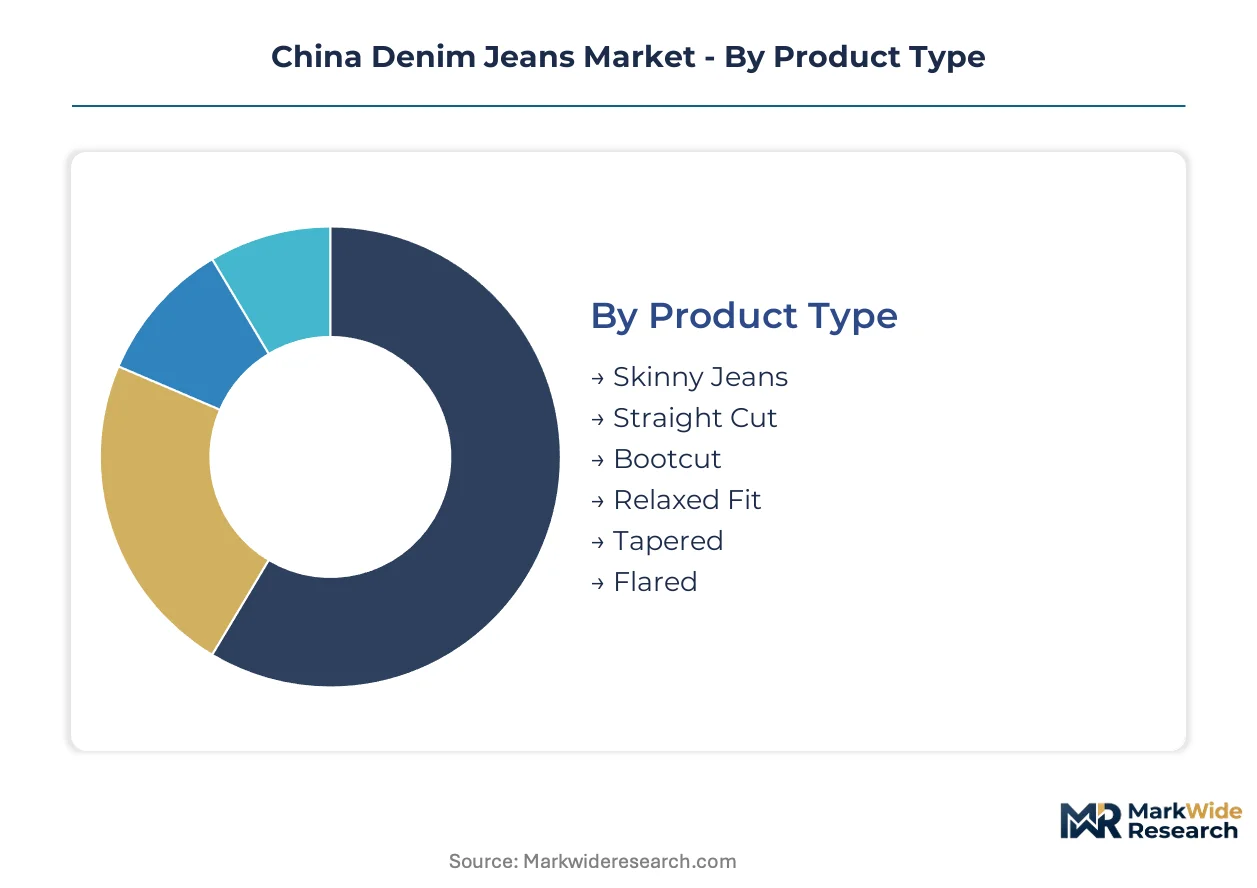
Channel fragmentation across livestream commerce and physical retail forces denim manufacturers to configure production lines for divergent batch sizes and turnaround speeds. Segmentation clarity enables mills to align laser finishing capacity with the velocity demands of each route to market.
Product Type:
Channel-mix patterns vary sharply across silhouettes, with e-commerce labels prioritizing skinny and straight cuts for rapid inventory turns while specialty stores anchor selvedge-driven tapered and bootcut lines.
- Skinny Jeans:Slim-fitting leg profile constructed with elastane-blend stretch denim for body-contouring fit. Young adult professionals in Shanghai and Beijing drive volume through workplace casualization, though MEE wastewater constraints on stretch fabric finishing elevate unit costs for smaller Guangdong finishers.
- Straight Cut:Uniform leg width from hip to ankle, traditionally woven at 3×1 twill with 12-14 oz fabric weights. Dongguan cut-make-trim operators produce straight cuts in micro-batches for domestic e-commerce labels seeking sub-two-week turnaround on capsule releases.
- Bootcut:Slight flare from knee to hem accommodating footwear, maintaining steady presence in department store channels serving middle-aged demographics.
- Relaxed Fit:Generous cut through thigh and seat, concentrated in outlet mall distribution targeting value-conscious consumers in inland provinces.
- Tapered:Narrowing leg profile from knee to ankle, gaining traction in specialty stores stocking premium selvedge lines for heritage-conscious buyers.
- Flared:Dramatic leg widening from knee downward, niche positioning in pop-up shops and trend-driven livestream drops.
By volume, straight cut leads. By growth pace, skinny jeans is climbing the fastest.
Fabric Technology:
Cost tier separation runs deepest here, with selvedge and organic cotton commanding 3-4x finishing costs over commodity stonewashed and bleached lines.
- Selvedge Denim:Shuttle-loomed fabric with self-finished edges, woven on narrow 30-inch looms at 14-16 oz weights. Specialty stores in Beijing and Shanghai stock selvedge lines from Black Peony's captive dyeing infrastructure, absorbing MEE compliance premiums that commodity finishers cannot match.
- Stretch Denim:Cotton-elastane blends incorporating 2-4% Lycra or Spandex for recovery and comfort. Young adult professionals drive demand through workplace casualization, though laser finishing complexity for stretch fabrics creates technician scarcity in Guangdong manufacturing clusters.
- Organic Cotton Denim:GOTS-certified fiber sourcing with restricted chemical inputs. E-commerce platforms targeting sustainability scorecards source organic lines from Sichuan and Chongqing mills migrating west for water quota relief.
- Indigo Dye:Synthetic indigo rope-dyeing on warp threads, the foundational technology facing petrochemical feedstock volatility.
- Stonewashed:Pumice stone abrasion creating vintage surface effects, water-intensive process declining under MEE discharge mandates.
- Bleached:Hypochlorite or potassium permanganate lightening, concentrated in budget channel production facing regulatory phase-out pressure.
By margin contribution, selvedge dominates. By volume scale, stretch denim leads expansion.
Consumer Demographic:
Application context shapes everything from fabric weight selection to finishing intensity, with professional wear demanding subtler treatments than student-oriented fashion lines.
- Young Adults:Primary volume engine across skinny and straight cuts, discovered through livestream commerce rather than physical retail. Beijing and Shanghai young professionals pull mid-premium stretch selvedge lines as workplace dress codes relax.
- Professionals:Workplace casualization expands denim acceptance into semi-formal contexts, favoring darker rinses and minimal distressing from certified GB 18401 producers.
- Teens:Trend-responsive segment driving pop-up shop and capsule release velocity, concentrated in online retail discovery patterns.
- Students:Price-sensitive demand funneled through e-commerce platforms and outlet mall channels, prioritizing volume over finishing complexity.
- Middle-aged:Department store and specialty store presence, gravitating toward relaxed fit and bootcut silhouettes with conservative wash treatments.
- Seniors:Smallest segment, served through established retail relationships with emphasis on comfort-oriented stretch constructions.
By current spend, young adults lead. By growth trajectory, professionals are gaining share fastest.
Distribution Channel:
Supply concentration in Dongguan and Guangzhou directly shapes channel economics, with laser-equipped finishers capturing e-commerce volume while conventional wet-process houses serve legacy retail.
- Online Retail:Direct-to-consumer platforms including Tmall, JD.com, and Douyin commerce, where livestream sessions now drive discovery. Micro-batch producers in Dongguan achieve sub-two-week turnaround for made-to-order capsule releases, bypassing traditional wholesale fabric markets.
- E-commerce Platforms:Aggregator marketplaces with fulfillment infrastructure, concentrating demand volatility at the manufacturing tier and rewarding flexible batch producers.
- Department Stores:Established retail chains in tier-one and tier-two cities, requiring GB 18401 certification for shelf access and rejecting uncertified imports.
- Specialty Stores:Curated denim boutiques in Shanghai and Beijing stocking premium selvedge and heritage lines, absorbing compliance cost premiums.
- Outlet Malls:Value-oriented channel for overstock and past-season inventory, concentrated in suburban locations serving price-sensitive demographics.
- Pop-up Shops:Temporary retail installations tied to influencer collaborations and limited drops, demanding extreme production flexibility from manufacturing partners.
By transaction volume, e-commerce platforms lead. By margin per unit, specialty stores are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium denim commands 40% higher unit economics in Shanghai than in inland manufacturing zones, while Guangdong's Pearl River Delta retains finishing capacity concentration despite tightening MEE water quotas. This pricing-power asymmetry is reshaping where brands locate value-capture versus cost-minimization functions.
Yangtze River Delta
Shanghai and Hangzhou young professionals drive mid-premium stretch selvedge consumption as workplace dress codes relax. SAMR enforces GB 18401 certification for retail shelf access, elevating compliance costs for uncertified imports. Suzhou-based finishers invest in laser equipment to serve e-commerce labels demanding sub-two-week turnaround on capsule releases.
Pearl River Delta
Guangzhou and Dongguan host China's densest denim manufacturing clusters, though MEE wastewater discharge limits force dyehouses toward tertiary treatment or exit. Water recycling mandates accelerate consolidation toward capital-heavy operators with certified environmental management systems. Black Peony's specialized indigo infrastructure anchors premium selvedge production in this zone.
Beijing-Tianjin-Hebei
Capital-region professionals expand casual workwear purchases, pulling darker rinses and minimal distressing from certified producers. Hebei Province's legacy textile towns face MEE air quality enforcement that constrains conventional finishing emissions. Tianjin port logistics support import-export denim trade serving northern retail channels.
Sichuan-Chongqing
Western migration offers lower labor costs and less stringent water quotas for cut-make-trim operators seeking margin relief. Chongqing's growing e-commerce fulfillment infrastructure connects micro-batch producers to domestic platforms. MEE incentives for zero-liquid-discharge systems attract membrane filtration investment from mills exiting Guangdong.
Shandong Peninsula
Qingdao and Weihai maintain cotton spinning heritage that feeds upstream denim fabric supply. Shandong's industrial water allocation policies remain more permissive than Pearl River Delta restrictions. Regional mills capture volume contracts from value-oriented e-commerce labels prioritizing cost over finishing complexity.
China Denim Jeans Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated mills controlling margin through captive yarn and fabric capacity while flexible batch operators capture e-commerce velocity. The market structures around three tiers: upstream-integrated producers with environmental certification, specialized finishers with dyeing infrastructure, and cut-make-trim shops serving micro-batch demand. Consolidation accelerates as MEE compliance costs strand smaller finishers without green financing access. Dominant competitive moves include backward integration into yarn production and geographic migration toward western water-quota relief.
Among integrated textile conglomerates, Texhong Textile Group occupies a position exemplifying upstream control through captive capacity, while Black Peony (Group) Co., Ltd. anchors the specialized dyeing tier with infrastructure smaller rivals cannot replicate. Dongguan Xiaofeiniu Garment Co., Ltd. (DiZNEW) represents flexible batch production archetype, serving domestic e-commerce labels with sub-two-week turnaround capability. These three patterns—integrated mill, specialized finisher, and agile manufacturer—capture the competitive vectors reshaping China's denim sector.
| Leading Market Players |
|---|
| Henan Newasia Garment Co., Ltd. (INNBLAC) |
| China-Jeans (Guangzhou Cunzhuang Clothing Co., Ltd.) |
| TAL Apparel |
| Guangzhou Lepanchuang Garment Co., Ltd. |
| Foshan Fly Jeans |
| Black Peony (Group) Co., Ltd. |
| Dongguan Xiaofeiniu Garment Co., Ltd. (DiZNEW) |
| QYOURECLO |
| Texhong Textile Group |
| Others |
Pricing and Supply Chain Analysis
Captive yarn and fabric capacity at integrated mills creates scale economies that smaller cut-make-trim operators cannot match, compressing price floors in commodity denim while elevating premiums for certified environmental compliance. MEE wastewater mandates in Guangdong concentrate finishing capacity among capital-heavy operators, allowing certified producers to capture shelf space in domestic retail chains that reject uncertified imports.
Pricing Analysis
The customization-premium spread separates made-to-order capsule releases from standard wholesale lines, with Dongguan micro-batch producers commanding 15-25% uplifts for sub-two-week turnaround. Three-tier pricing structure across premium selvedge, mid-market stretch, and economy stonewashed segments reflects GB 18401 certification status and laser finishing capability. Pricing pressure stems from synthetic indigo feedstock volatility and MEE compliance capex, squeezing margin at specialized dyehouses without captive chemical production. Students and inland value shoppers exhibit highest price sensitivity, while heritage-conscious buyers in Shanghai specialty stores absorb compliance premiums.
Supply Chain Analysis
Strategic stockpiling of indigo dye and stretch yarn dominates inventory strategy, as petrochemical feedstock volatility and elastane supply uncertainty reward forward coverage. Raw material sourcing draws from Xinjiang cotton spinning, synthetic indigo from petrochemical complexes, and elastane fiber from domestic chemical producers. Guangdong's Pearl River Delta hosts China's densest finishing clusters, exposing national supply to simultaneous water-quota restrictions and regional climate disruptions. Distribution runs through Dongguan cut-make-trim shops for e-commerce velocity, with certified mills serving department store chains requiring GB 18401 documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Livestream commerce integration is repositioning denim manufacturing as a platform-economy node, where flexible batch producers capture value through direct e-commerce label relationships rather than wholesale fabric market intermediation.
For Market Incumbents: Consolidate finishing capacity around laser and ozone infrastructure to defend margin against MEE wastewater mandates that strand conventional wet-process competitors. Acquire GB 18401-certified environmental management systems to lock in department store shelf access, while migrating cut-make-trim operations to Sichuan-Chongqing for water quota relief.
For New Entrants and Emerging Players: GB 18401 certification fast-track offers entry into domestic retail chains that reject uncertified imports, creating shelf space access unavailable to legacy exporters. Target organic cotton denim for sustainability scorecard-driven e-commerce platforms, leveraging western China's less stringent water quotas. Lead with closed-loop water recycling narratives to capture MEE incentive programs and green financing.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized finishers with captive dyeing infrastructure over commodity cut-make-trim operators facing margin compression. Long-term viability rests on environmental certification moats and laser finishing capability that smaller rivals cannot replicate. Watch MEE enforcement intensity in the Pearl River Delta as the signal for consolidation velocity and distressed asset availability.
| Strategic Initiative | Industry Significance |
|---|---|
| Laser Finishing Capacity Expansion | Reduces water consumption and chemical discharge while accelerating style turnaround for Dongguan e-commerce labels. |
| GB 18401 Certification Investment | Unlocks department store shelf access in tier-one cities where SAMR enforcement rejects uncertified imports. |
| Western Manufacturing Migration | Sichuan and Chongqing offer lower labor costs and less stringent MEE water quotas for margin relief. |
| Closed-Loop Water Recycling | MEE incentives for zero-liquid-discharge systems create first-mover advantage for membrane filtration investment. |
| Livestream Commerce Integration | Direct e-commerce label partnerships bypass wholesale fabric markets and concentrate demand volatility at flexible producers. |
Research Methodology
A standing panel of denim mill operations directors, e-commerce platform category managers, GB standards certification auditors, and MEE regional enforcement officers provided ongoing calibration across the study period. Primary fieldwork with Guangdong finishing operators and Shanghai retail buyers combined with secondary validation from SAMR regulatory filings, customs export records, and textile industry association capacity surveys. Bottom-up shipment data from Dongguan and Guangzhou manufacturing clusters triangulated against top-down consumption estimates from Beijing and Shanghai retail channels.
Consistency checks validated volume and value outputs against Pearl River Delta water-use permits and laser equipment installation records reported by Guangdong textile machinery distributors. Segmentation modeling spanned product type, fabric technology, consumer demographic, and distribution channel dimensions across the projection horizon. CAGRs derived from fitted growth curves incorporating MEE regulatory phase-in schedules and livestream commerce penetration trajectories.
Underlying assumptions cover MEE enforcement continuity, synthetic indigo supply stability, and livestream platform growth, with deviation risk concentrated in water-quota tightening velocity and cotton fiber cost trajectories. Revision becomes warranted when MEE discharge standard amendments or GB certification timeline changes cross implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel Textiles
Head Scarves Market
Apparel Textiles
Bamboo Apparel Market
Apparel Textiles
Uniform Market
Apparel Textiles
Clothing Manufacturing Service Market
Apparel Textiles
Embroidery Market
Apparel Textiles
Africa Textile Market
Apparel Textiles
Organic Baby Clothes Market
Apparel Textiles
Rain Apparel Market
Apparel Textiles
Global Prom Dresses Market
Apparel Textiles
Equestrian Apparel Market
Apparel Textiles
North America Insect Repellent Apparel Market
Apparel Textiles
Blank Apparel Market
Apparel Textiles
Stockings Market
Apparel Textiles
Asia-Pacific Footwear Sole Material Market
Apparel Textiles
Middle East and Africa Footwear Sole Material Market
Apparel Textiles
Zipper Market