
 Insect Repellent Apparel Market | 2026-2036
Insect Repellent Apparel Market Size, Share, and Industry Trends Forecast 2026-2036
Insect Repellent Apparel Market Outlook
Subscription-based re-treatment services is recalibrating how manufacturers monetize insect repellent apparel beyond the initial sale. Insect Shield LLC leverages its proprietary bonding technology to sustain recurring revenue through licensed treatment programs. ExOfficio LLC anchors its brand strength in travel-specialized channels with permethrin-integrated fabrics that compete on durability claims. Craghoppers Ltd differentiates through geographic dominance in European outdoor retail, where its NosiLife line occupies premium shelf positioning.
Insect repellent apparel denotes garments engineered with permethrin or bio-based compounds bonded to textile fibers at loadings typically between 0.52% and 0.67% by fabric weight, creating spatial protection zones that reduce arthropod bites for 70-plus launderings. These garments serve commercial and consumer markets requiring vector-borne disease mitigation without topical chemical application. Chemical Treated technology leads current volume owing to established EPA registrations and lower unit economics, while Bio-Based formulations represent the fastest-growing margin pool as botanical repellent systems gain regulatory preference in European markets. Pants and Shirts together dominate product type revenue, though Jackets command higher per-unit margins in specialized military and forestry procurement channels.
EPA registration under FIFRA governs permethrin-treated apparel sold in the United States, requiring efficacy data and labeling that shapes product development timelines and market access costs. REACH compliance in Europe restricts certain synthetic repellent chemistries, redirecting formulation investment toward bio-based alternatives that satisfy ECHA substance evaluation protocols. Stakeholders must monitor evolving state-level vector control mandates and emerging textile certification schemes to anticipate which treatment technologies will retain commercial viability across key regulatory jurisdictions.
Market Dynamics
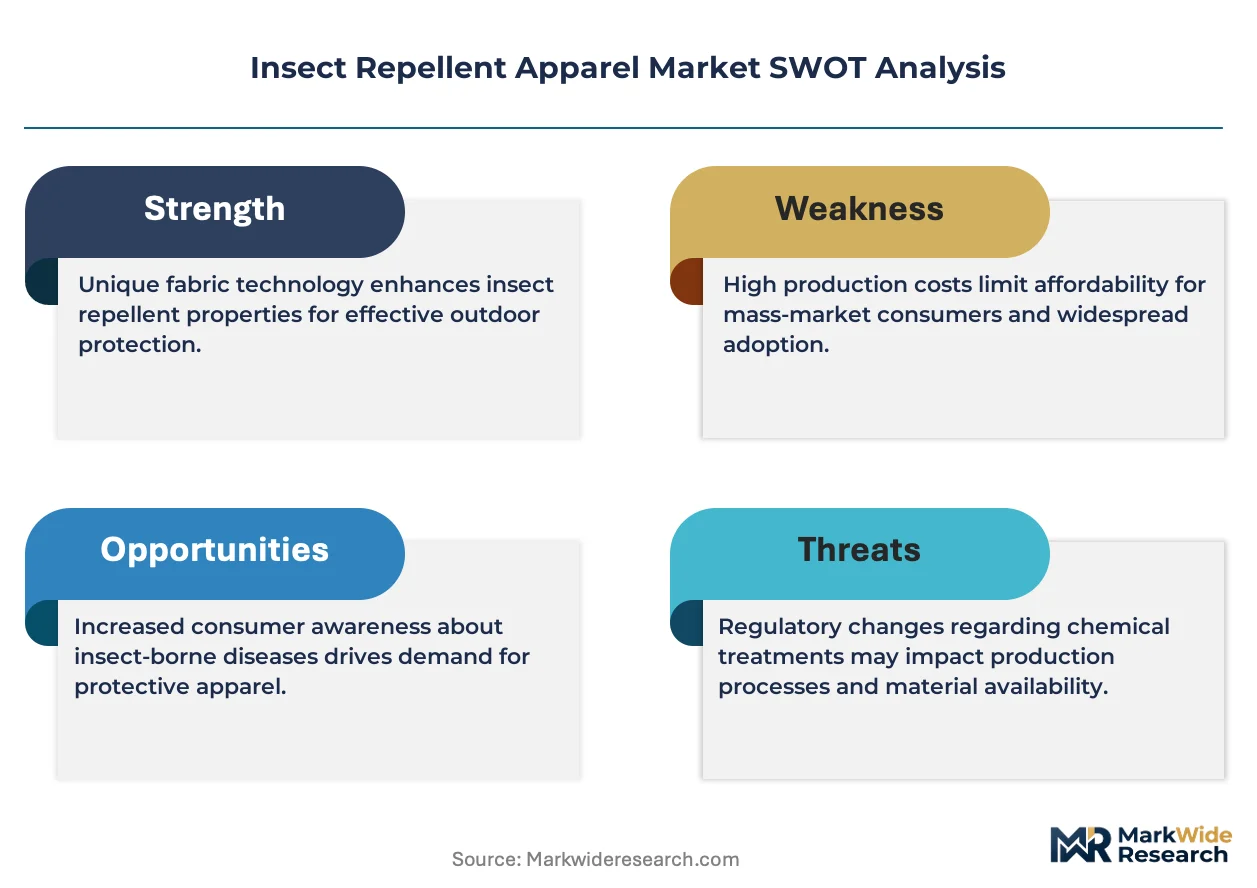
Permethrin-bonding chemistry advances and EPA registration tightening are compressing product development timelines while concentrating manufacturing among firms with captive treatment facilities. This structural pressure favors vertically integrated producers over contract-treatment dependent brands.
Growth Catalysts
- Lyme Disease Awareness Campaigns:US public health initiatives in endemic states elevate consumer willingness to pay protective premiums. Vector surveillance programs expand addressable demand beyond traditional outdoor recreation segments.
- REACH Restrictions on Synthetic Chemistries:European regulatory pressure redirects formulation investment toward botanical repellent systems. Bio-based alternatives capture regulatory preference and shelf positioning in EU outdoor retail channels.
- Permethrin Microencapsulation:Improved bonding technologies extend effective wash cycles from 25 to 70-plus launderings. Durability claims strengthen value propositions against disposable topical repellent alternatives.
Market Restraints
- Petrochemical Feedstock Volatility:Synthetic pyrethroid precursors fluctuate with crude oil derivatives, squeezing margin stability for chemical-treated garment producers.
- EPA FIFRA Registration Barriers:Efficacy data requirements and labeling compliance extend market access timelines for new entrants. Registration costs concentrate viable competition among established treatment licensors.
- Heat-Sensitive Application Limitations:Permethrin bonding degrades above standard home-drying temperatures. Consumer laundering errors accelerate efficacy decay and erode brand trust through inconsistent performance.
Strategic Opportunities
- Brazilian Vector Control Procurement:ANVISA regulatory pathways for dengue and Zika mitigation create institutional demand for treated workwear. Military and municipal forestry contracts remain underpenetrated by incumbent suppliers.
- Subscription Re-Treatment Services:Licensed treatment programs convert one-time apparel sales into recurring revenue streams. Post-purchase service models capture lifetime value from durability-conscious outdoor enthusiasts.
- Smart Textile Convergence:Integration of permethrin bonding with moisture-wicking and UV-blocking fiber technologies enables premium multi-functional positioning. Performance layering systems command price multiples in alpine and expedition segments.
Industry Challenges
- Textile Chemistry Talent Scarcity:Formulation expertise combining fiber engineering with pesticide efficacy testing remains concentrated among legacy treatment houses. Skills gaps constrain in-house R&D expansion.
- Cross-Jurisdictional Labeling Complexity:Divergent EPA, ECHA, and Health Canada PMRA disclosure requirements fragment packaging and marketing assets. Compliance overhead multiplies for brands pursuing multi-country distribution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Insect Repellent Apparel Market |
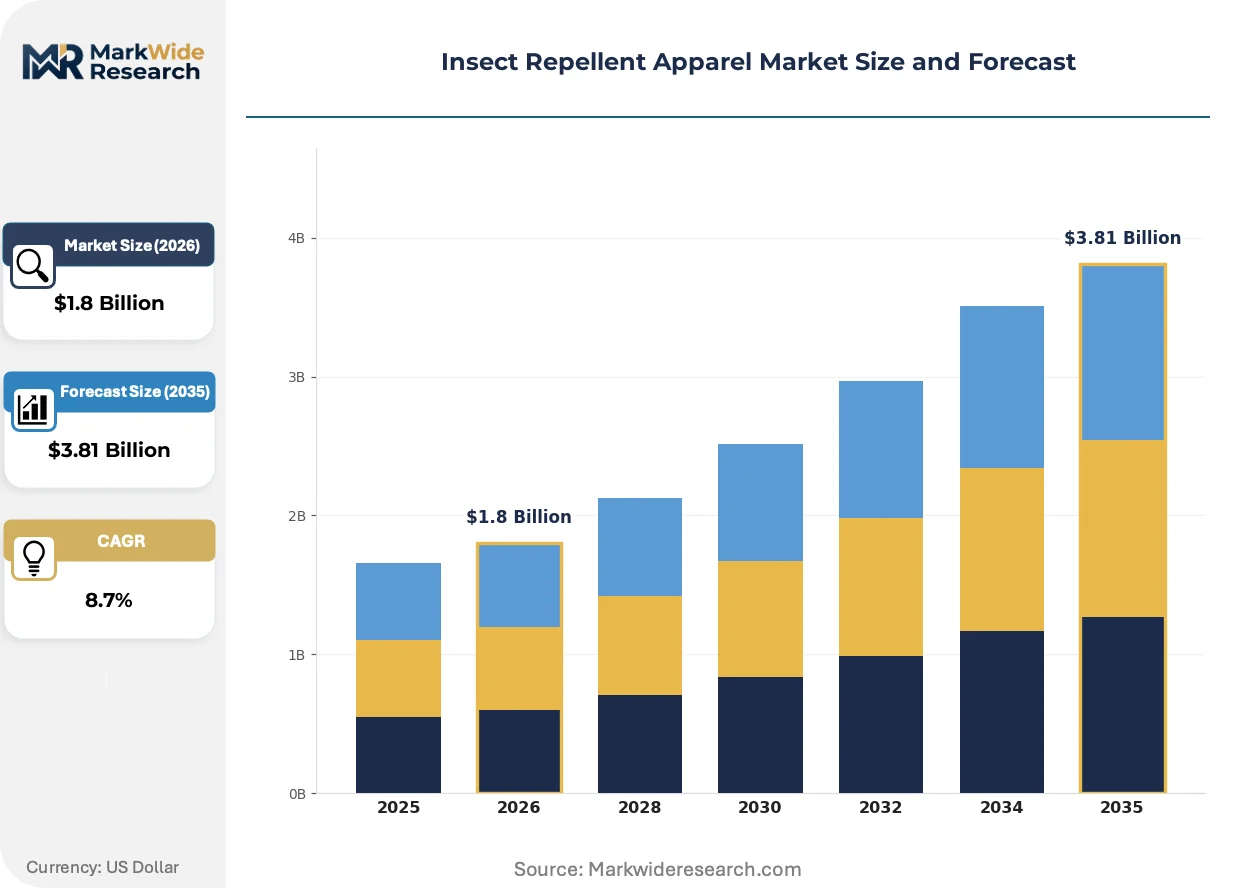
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pants, Shirts, Jackets, Socks Technology: Chemical Treated, Bio-Based, UV Protection, Mosquito Netting End User: Outdoor Enthusiasts, Travelers, Gardeners, Campers Distribution Channel: Retail Stores, Online Platforms, Direct Sales, Specialty Outlets |
| Companies Covered | Insect Shield LLC, ExOfficio LLC, Craghoppers Ltd, Burlington, Arcteryx, Nobitech, Royal Robbins LLC, The Orvis Company Inc, Tyndale USA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Insect Repellent Apparel Market Strategic Shifts
Formulation chemistry, regulatory compliance architecture, and post-purchase service models are simultaneously transforming how protective apparel is engineered, certified, and monetized. These shifts favor integrated manufacturers with captive technical capabilities.
Microencapsulated permethrin systems with controlled-release kinetics are overtaking surface-applied treatments in premium outdoor segments. Alpine outfitters and expedition suppliers specify bonded-chemistry garments for extended backcountry use without reapplication. This durability standard is compressing demand for topical repellent companion products and reshaping category margins toward integrated apparel solutions.
ECHA substance evaluation protocols under REACH are restricting specific synthetic pyrethroid analogues in EU member states. Formulators redirect R&D expenditure toward geraniol, citronellal, and other botanical repellent systems that satisfy ECHA biodegradability thresholds. Outdoor retail buyers in Germany, France, and Benelux markets now preference bio-based treated garments in sustainability-assortment planning.
After-sales re-treatment subscriptions are displacing single-transaction retail models in direct-to-consumer channels. Outdoor enthusiasts in US Rocky Mountain and Pacific Northwest clusters enroll in mail-in refresh programs to extend garment efficacy beyond factory bonding limits. This service attachment is most visible among permethrin-licensed brands with proprietary treatment networks and regional logistics infrastructure.
Insect Repellent Apparel Market Segmentation
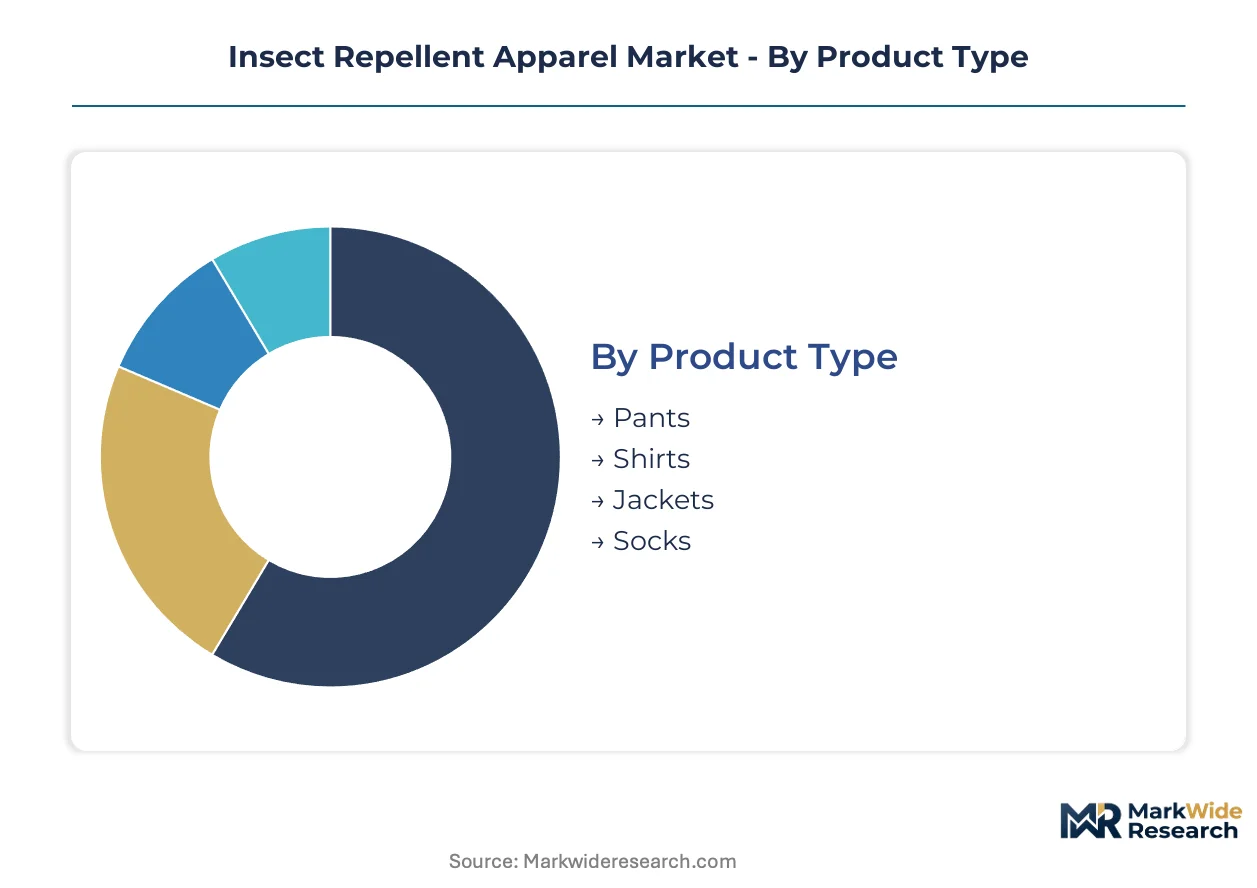
Product configuration in insect repellent apparel varies sharply between standardized mass-market offerings and technically specialized garments engineered for specific vector exposure scenarios. Treatment chemistry, garment architecture, and distribution channel each impose distinct customization requirements that reshape manufacturing economics and brand positioning.
Product Type:
Standardized silhouettes dominate volume production while specialized designs command technical premiums in professional and expedition segments.
- Pants:Permethrin-bonded trousers with reinforced knee panels and ankle gaiter compatibility anchor commercial volume in hiking and forestry applications. Demand concentrates in US Northeast and Upper Midwest states where Lyme disease surveillance programs elevate protective workwear procurement.
- Shirts:Long-sleeved button-down and pullover configurations with bonded collar and cuff treatments dominate travel-specialized retail. Outdoor enthusiasts in Rocky Mountain corridor states drive replacement cycles through seasonal expedition preparation.
- Jackets:Technical shell layers with integrated hood and hand-pocket treatments serve military and alpine expedition contracts requiring extended wear without laundering.
- Socks:Ankle and crew heights with permethrin-integrated yarn systems address tick exposure at lower extremities in gardening and casual outdoor use.
Most installed capacity flows through Pants and Shirts. Expansion is steepest in Jackets as military and alpine expedition procurement professionalizes.
Technology:
Regulatory jurisdiction determines which chemistries retain market access, fragmenting formulation strategies between EPA-governed and ECHA-regulated territories.
- Chemical Treated:Microencapsulated permethrin systems at 0.52-0.67% fabric weight loading deliver 70-plus wash durability through controlled-release kinetics. EPA FIFRA registration requirements concentrate viable supply among licensed treatment houses with established efficacy datasets.
- Bio-Based:Geraniol and citronellal formulations satisfy ECHA biodegradability thresholds under REACH substance evaluation protocols. German, French, and Benelux outdoor retail buyers now preference botanical systems in sustainability-assortment planning.
- UV Protection:Dual-function fiber treatments combining permethrin bonding with UPF-rated weaving command premium positioning in equatorial travel and desert expedition segments.
- Mosquito Netting:Headnet and sleeping enclosure configurations with permethrin-impregnated mesh address camping and humanitarian aid procurement in tropical vector zones.
Chemical Treated retains dominant production share. Bio-Based formulations are gaining share fastest as European regulatory pressure redirects R&D expenditure.
End User:
Activity intensity and vector exposure duration segment demand between recreational replacement purchasers and professional protective equipment buyers.
- Outdoor Enthusiasts:Hikers, hunters, and anglers in endemic Lyme and West Nile zones drive premium willingness-to-pay for extended-wash durability claims. Pacific Northwest and Appalachian Trail corridor clusters show highest subscription re-treatment enrollment.
- Travelers:Pre-trip preparation purchasers in urban centers favor packable, lightweight configurations for tropical and subtropical destinations. Airport-adjacent specialty retail and direct-to-consumer channels capture this segment.
- Gardeners:Residential landscaping and small-scale agriculture users prioritize lower price points with adequate tick protection for intermittent exposure.
- Campers:Family and group camping participants seek integrated protection across multi-garment systems for extended backcountry stays.
Outdoor Enthusiasts anchor volume throughput. Travelers show steepest trajectory as international tourism resumes and vector awareness campaigns expand.
Distribution Channel:
Channel selection determines margin capture and post-purchase service attachment potential for re-treatment revenue models.
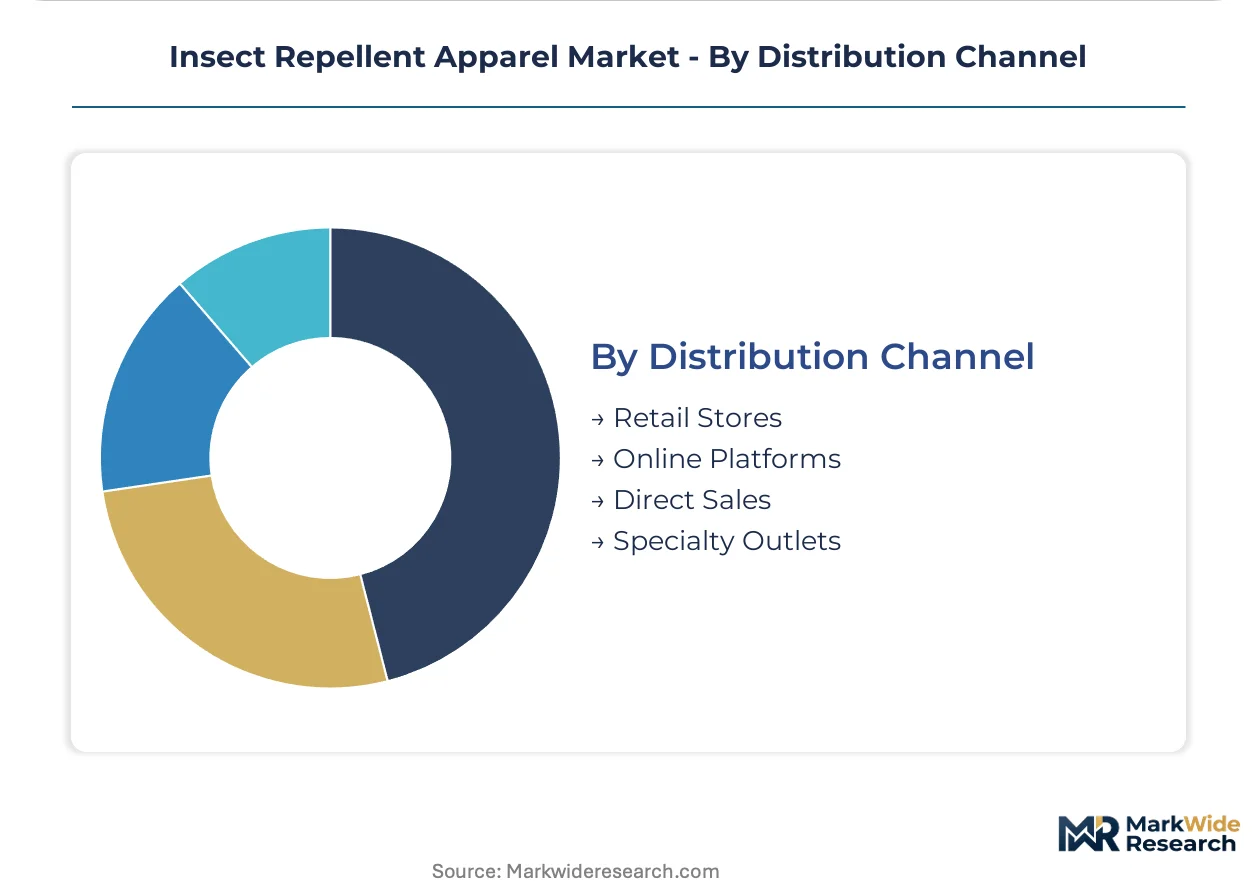
- Retail Stores:Outdoor specialty and big-box sporting goods locations enable tactile evaluation of fabric hand and treatment durability claims. Staff training on permethrin care instructions reduces consumer laundering errors that accelerate efficacy decay.
- Online Platforms:Direct-to-consumer and marketplace channels support subscription re-treatment enrollment and geographic reach beyond specialty retail footprints. Logistics infrastructure for mail-in refresh programs concentrates in US Rocky Mountain and Pacific Northwest clusters.
- Direct Sales:Institutional procurement for military, forestry, and municipal vector control contracts bypasses retail markup through licensed treatment house relationships.
- Specialty Outlets:Travel-specialized and expedition outfitters curate premium assortments with technical staff consultation for destination-specific vector risks.
Retail Stores process dominant transaction volume. Online Platforms are climbing the fastest as subscription service models convert one-time sales into recurring revenue streams.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumer willingness to pay protective premiums diverges sharply between the United States and Germany, where vector awareness campaigns and regulatory frameworks respectively reshape demand patterns. Brazil and Australia present contrasting procurement environments for institutional buyers, while Japan's aging outdoor demographic sustains niche premium positioning.
United States
Lyme disease surveillance programs in Connecticut and New York elevate protective workwear procurement among municipal forestry crews. EPA FIFRA registration requirements concentrate viable supply among licensed treatment houses with established efficacy datasets. Outdoor specialty retail clusters in Denver and Seattle anchor subscription re-treatment enrollment for permethrin-bonded garments.
Germany
ECHA substance evaluation protocols under REACH redirect formulation investment toward geraniol and citronellal botanical systems. Benelux outdoor retail buyers preference bio-based treated garments in sustainability-assortment planning. Munich and Hamburg specialty outfitters curate premium assortments with technical staff consultation for destination-specific vector risks.
Brazil
ANVISA regulatory pathways for dengue and Zika mitigation create institutional demand for treated workwear in municipal vector control programs. Military and forestry contracts in São Paulo and Minas Gerais remain underpenetrated by incumbent suppliers. Domestic textile processors seek licensing partnerships with established permethrin-bonding technology holders.
Australia
Ross River virus awareness campaigns in Queensland and New South Wales drive replacement cycles through seasonal expedition preparation. Health Australia's PMRA-aligned disclosure requirements fragment packaging assets for brands pursuing trans-Tasman distribution. Melbourne and Sydney direct-to-consumer channels support mail-in refresh programs for durability-conscious bushwalkers.
Japan
METI standards for functional textile labeling shape product development timelines for permethrin-integrated imports. Aging outdoor enthusiasts in the Kanto and Kansai regions sustain premium positioning for extended-wash durability claims. Osaka-based expedition outfitters specify bonded-chemistry garments for extended backcountry use without reapplication.
Insect Repellent Apparel Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with vertical integration favoring captive treatment facilities over outsourced bonding. The vendor base concentrates around licensed permethrin technology holders and European bio-based formulators. Two strategic archetypes dominate: integrated manufacturers with proprietary bonding capabilities, and brand licensors relying on contract treatment networks. Competitive moves center on subscription service model adoption and geographic expansion into underpenetrated institutional procurement channels.
Among US-based specialists, Insect Shield LLC and ExOfficio LLC occupy positions at opposite ends of the value chain archetype spectrum, with the former exemplifying technology-licensing scale and the latter representing travel-specialized brand positioning. Craghoppers Ltd anchors European geographic dominance through its UK-originated structure. These three entities collectively illustrate how regulatory jurisdiction and distribution channel selection determine margin capture potential in permethrin-treated and bio-based formulation segments.
| Leading Market Players |
|---|
| Insect Shield LLC |
| ExOfficio LLC |
| Craghoppers Ltd |
| Burlington |
| Arcteryx |
| Nobitech |
| Royal Robbins LLC |
| The Orvis Company Inc |
| Tyndale USA |
| Others |
Value Chain & Pricing Dynamics
Permethrin-bonding certification tiers split the market into EPA-registered premium garments and unlicensed commodity alternatives, with that bifurcation manifesting in both price positioning and sourcing configurations. Premium tier producers maintain captive treatment facilities in the United States and Vietnam to control bonding quality, while commodity players source from contract processors in Bangladesh and India where registration gaps permit lower-cost surface applications.
Pricing Analysis
Capacity additions in Vietnam and Bangladesh are reshaping price floors for standard chemical-treated garments as new bonding facilities come online. Three-tier pricing structure across premium EPA-registered, mid-tier private-label, and economy unlicensed levels reflects certification investment differentials. Cost compression in the economy tier is intensifying because synthetic pyrethroid feedstock volatility squeezes contract processors. Municipal forestry buyers show highest price sensitivity, while alpine expedition outfitters accept substantial premiums for extended-wash durability claims.
Supply Chain Analysis
Reverse logistics for subscription re-treatment services now anchor supply chain design, with mail-in refresh programs requiring regional collection hubs and bonded-chemistry refresh facilities. Manufacturing concentrates in Vietnam, Bangladesh, and the United States, with permethrin precursor sourcing tethered to Chinese and Indian petrochemical processors. Single-source vulnerability in EPA-licensed bonding technology creates bottleneck risk for brands without proprietary treatment partnerships. Distribution runs through outdoor specialty retail for tactile evaluation, supplemented by direct-to-consumer channels for service enrollment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where outdoor enthusiasts now demand 70-plus wash durability as table stakes, forcing margin compression on sub-standard offerings.
For Market Incumbents: Lock in proprietary bonding capacity through acquisition of licensed treatment houses before EPA registration barriers harden further. Deepen channel control by embedding staff training programs at outdoor specialty retail to reduce consumer laundering errors that erode brand trust. Defensive consolidation around captive R&D capabilities counters emerging bio-based formulators gaining European regulatory preference. For New Entrants and Emerging Players: Launch via direct-to-consumer subscription models to bypass incumbent retail shelf dominance and capture lifetime value through re-treatment enrollment. Brazilian municipal vector control contracts remain the most penetrable institutional segment, with ANVISA pathways creating first-mover advantages for treatment technology licensors willing to establish local bonding partnerships. For Investors and Strategic Acquirers: Asymmetric upside sits with vertically integrated specialists combining proprietary bonding chemistry with established subscription logistics infrastructure. Long-term viability hinges on regulatory moat sustainability across EPA and ECHA jurisdictions. Watch for ECHA substance evaluation protocol expansions that could accelerate synthetic pyrethroid restrictions and revalue bio-based formulation capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bonding Facilities | Captive EPA-licensed treatment capacity secures supply continuity against registration concentration. |
| Subscription Re-Treatment Service Launch | Mail-in refresh programs convert transactional apparel sales into recurring revenue streams. |
| Bio-Based Formulation R&D Expansion | Geraniol and citronellal systems satisfy ECHA biodegradability thresholds under REACH protocols. |
| Direct-to-Consumer Channel Buildout | Online platforms bypass retail markup and enable geographic reach beyond specialty store footprints. |
| Smart Textile Convergence Investment | Permethrin bonding combined with UPF-rated weaving commands premium in equatorial segments. |
Study Parameters
Bottom-up outdoor enthusiast and institutional procurement modeling reconciled against top-down treatment facility capacity tracking forms the analytical core. Primary interviews with EPA registration consultants, licensed bonding facility operators, outdoor specialty retail buyers, and municipal forestry procurement officers combined with secondary validation from EPA FIFRA registration databases, ECHA substance evaluation dossiers, and customs trade records. Triangulation across stakeholder inputs and documentary sources ensures segmentation integrity.
Input-output matrices map permethrin precursor flows through bonding facilities to finished garment output across product type, treatment chemistry, end-user activity intensity, and distribution channel dimensions. CAGRs derive from wash-cycle durability degradation curves and replacement frequency modeling throughout the projection horizon. Forecast inputs incorporate regulatory pathway timelines for bio-based formulation approvals and subscription service adoption elasticities.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt EPA registration requirement changes or ECHA pyrethroid analogue restrictions. Practitioners should monitor ANVISA regulatory pathway developments and ECHA substance evaluation protocol expansions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel Textiles
Blank Apparel Market
Apparel Textiles
Functional Apparel Market
Apparel Textiles
Maternity Wear Market
Apparel Textiles
Cleanroom Apparels Market
Apparel Textiles
North America Garment Steamers Market
Apparel Textiles
Women's Cheongsam Market
Apparel Textiles
Women's Jerseys, Sweatshirts and Pullovers Market
Apparel Textiles
Dye Sublimated Apparel Market
Apparel Textiles
Sweat Resistant Apparel Market
Apparel Textiles
Global Western Wear Market
Apparel Textiles
Asia Pacific Garment Steamers Market
Apparel Textiles
Welding Apparels Market
Apparel Textiles
Europe Textile Garment Market
Apparel Textiles
China Flame Retardant Apparel Market
Apparel Textiles
Japan Denim Jeans Market
Apparel Textiles
Cooling Apparel Market