

Sweat Resistant Apparel Market Size, Share, and Industry Trends Forecast 2026-2036
Sweat Resistant Apparel Market Insights
Southeast Asian textile producers is rebalancing capacity toward performance fabric mills as brand orders shift from commodity basics to engineered sportswear. Nike leverages vertical integration through proprietary Dri-FIT manufacturing partnerships across Vietnam and Indonesia. Under Armour sustains R&D intensity in Baltimore, anchoring its innovation pipeline in compression and temperature-regulation patents. Adidas competes through SPEEDFACTORY automation concepts and recycled ocean plastic supply chains that differentiate its sustainability positioning.
Sweat resistant apparel encompasses garments engineered with synthetic or treated natural fibers that transport moisture vapor away from skin surfaces, typically achieving evaporation rates exceeding standard cotton by factors of three to five through capillary action engineering. The primary commercial purpose centers on thermoregulation during exertion, reducing thermal stress and microbial accumulation in high-perspiration environments. Moisture wicking technology dominates volume production while antimicrobial finishes command premium positioning in medical and military procurement channels. Activewear as a product category captures the widest margin pools through direct-to-consumer pricing power, whereas workwear applications represent a maturing segment with slower innovation cycles.
FDA oversight of antimicrobial claims on textile surfaces constrains marketing language and substantiation requirements for treated garments sold in the United States. EPA registration mandates for biocidal coatings add compliance layers that smaller mills struggle to navigate, effectively raising barriers to premium segment entry. ISO 18184 antiviral textile testing protocols and OEKO-TEX Standard 100 certifications increasingly function as procurement prerequisites for European and North American retail buyers. Stakeholders must monitor evolving PFAS restrictions in water-repellent coatings across multiple jurisdictions, as these chemistry transitions will determine which suppliers retain access to performance-oriented defense and outdoor contracts.
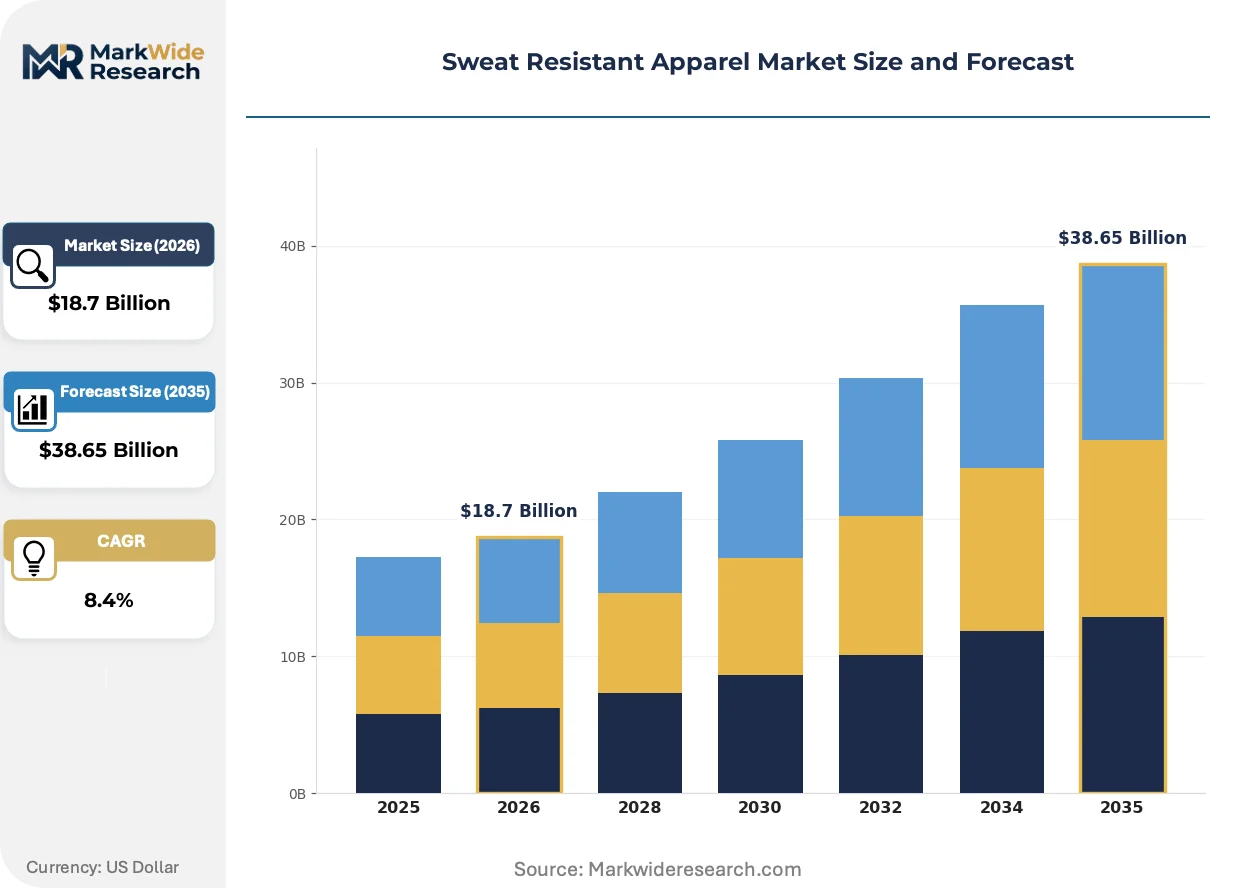
Market Dynamics
PFAS phaseout mandates across multiple jurisdictions are forcing chemistry transitions in durable water-repellent finishes, compressing supplier margins while opening procurement windows for fluorine-free alternatives.
Growth Catalysts
- Fitness sector expansion:Boutique studio chains and home gym equipment bundling are normalizing performance fabric expectations among casual exercisers previously served by cotton basics.
- EU Green Deal textile requirements:Mandatory recycled content thresholds and chemical disclosure rules are accelerating certified mill upgrades, advantaging early-compliant suppliers in procurement tenders.
- Antimicrobial medical procurement:ISO 18184 antiviral testing protocols are becoming standard in hospital linen contracts, expanding addressable market for treated performance garments.
Market Restraints
- Petrochemical feedstock volatility:Polyester and spandex input costs fluctuate with crude oil indices, compressing spinners' margin predictability on long-dated brand contracts.
- Southeast Asian mill concentration:Vietnam and Indonesia host disproportionate synthetic knit capacity, exposing order books to single-country logistics disruptions or trade policy shifts.
- Biocidal coating registration burdens:EPA registration timelines for antimicrobial finishes extend 18-24 months, freezing smaller mills out of premium medical and military channels.
Strategic Opportunities
- Indian domestic market penetration:Urban fitness culture in Mumbai, Bangalore, and Delhi remains underserved by organized performance apparel retail, presenting direct-to-consumer entry potential.
- Cellulosic-synthetic fiber blends:Lyocell-polyester interlock fabrics bridge sustainability credentials with wicking performance, opening positioning space between petroleum synthetics and untreated cotton.
- Workwear specification upgrades:Heat-stress regulations from OSHA are mandating moisture-management properties in industrial uniforms, converting a commodity segment into technical garment procurement.
Industry Challenges
- PFAS chemistry transition execution:Reformulating C6 and C8 fluorocarbon finishes to silicone or hydrocarbon alternatives requires 12-18 month validation cycles with brand partners.
- Performance testing standardization gaps:Inconsistent moisture-vapor transmission rate methodologies across AATCC, ISO, and JIS protocols create specification disputes between buyers and mills.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sweat Resistant Apparel Market Trends and Innovations
Material science advances and regulatory chemistry bans are converging to reshape how performance properties are engineered into textile substrates.
Biomimetic surface treatments derived from lotus-leaf microstructures are modularizing water-repellency construction. Outdoor and tactical buyers are piloting these finishes at small batch scale ahead of 2025-2026 procurement cycles. The approach enables property-specific layering onto base fabrics rather than reformulating entire yarn systems, compressing R&D timelines for specialized applications.
REACH restrictions on per- and polyfluoroalkyl substances are tightening discharge thresholds for textile finishing effluent. German and Dutch environmental agencies are enforcing stricter river basin compliance than minimum EU standards, forcing finish houses to install closed-loop water systems. Defense and first-responder garment contractors face specification freezes until fluorine-free alternatives achieve equivalent abrasion durability.
Direct-to-consumer subscription models for performance activewear are displacing seasonal wholesale purchasing among urban millennials. California and New York metro buyers increasingly expect monthly curated deliveries with fit-algorithm customization, compressing traditional retail markup structures. Brand logistics networks are reconfiguring around micro-fulfillment nodes rather than regional distribution centers.
Sweat Resistant Apparel Market Segmentation
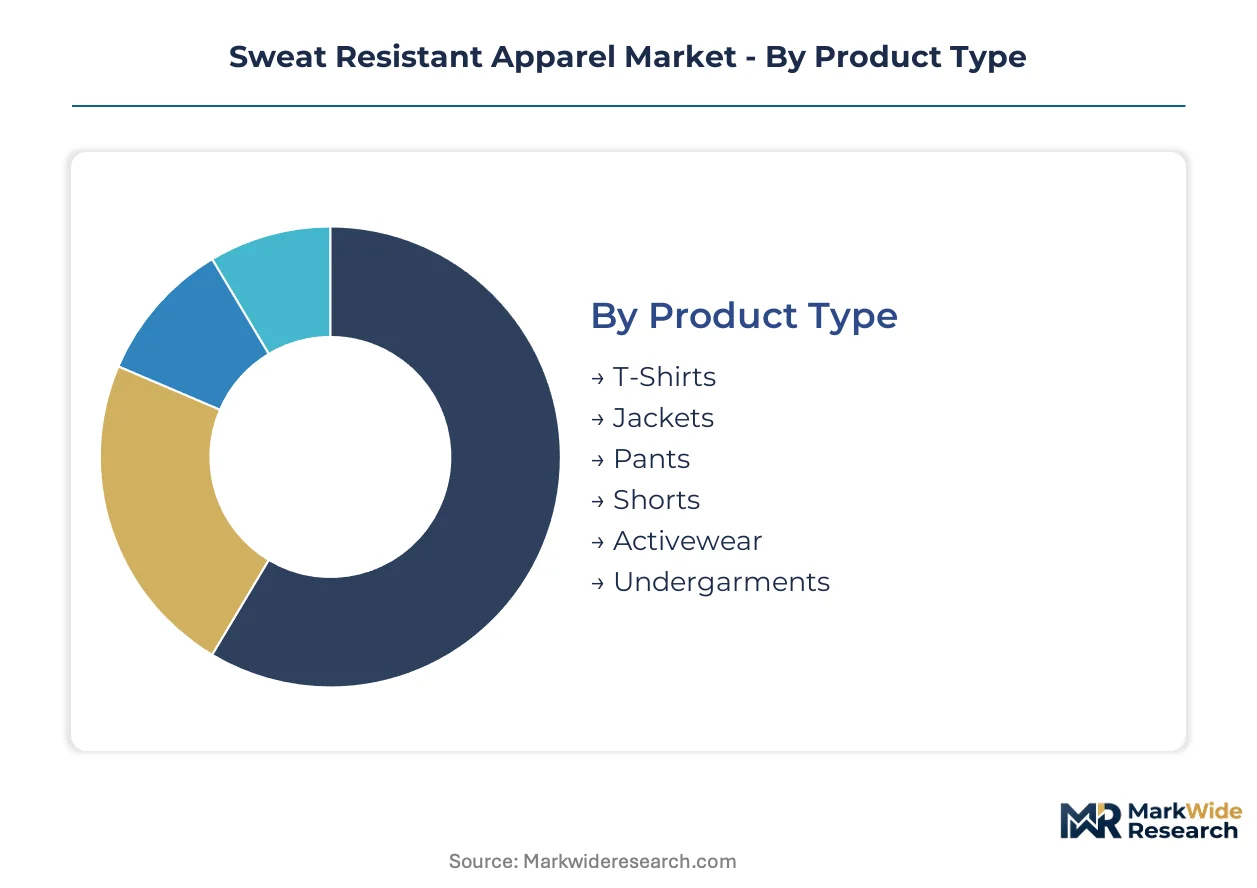
Sweat resistant apparel segmentation reveals divergent margin structures across product tiers. Technology differentiation and end-use specification intensity determine pricing power and procurement channel access.
Product Type:
Volume production concentrates in basic tops and bottoms, while premium positioning clusters in integrated activewear systems requiring multi-property engineering.
- Activewear:Integrated garment systems combine compression, moisture transport, and thermoregulation in single-piece construction. Demand clusters in California and New York metropolitan fitness studios where direct-to-consumer subscription models dominate procurement.
- T-Shirts:Polyester-cotton interlock and 100% synthetic knits represent the highest unit-volume category. Mass-market retail in United States coastal cities absorbs the majority of production, though margin compression from private-label competition constrains branded positioning.
- Jackets:Shell layers with breathable membranes serve outdoor recreation and tactical applications.
- Pants:Woven synthetics and softshell constructions address workwear and athletic training segments.
- Shorts:Lightweight knit constructions dominate running and court sports.
- Undergarments:Baselayer proximity to skin drives antimicrobial finish requirements and OEKO-TEX certification premiums.
Mature deployment sits with T-Shirts. Newer deployment is concentrated in Activewear.
Technology:
Property layering determines cost structure, with single-function treatments at commodity margins and multi-functional stacks commanding technical premiums.
- Moisture Wicking:Capillary-action engineering through yarn denier variation and fiber cross-section geometry moves perspiration vapor across fabric surfaces. Fitness applications in United States boutique studios represent the core demand concentration, with EPA-registered antimicrobial variants accessing medical procurement channels.
- Antimicrobial:Biocidal surface treatments suppress microbial accumulation in high-perspiration environments. FDA oversight of marketing claims and EPA registration timelines constrain supplier participation, concentrating supply among established finish houses with compliance infrastructure.
- Breathable Membranes:Microporous films and hydrophilic coatings enable vapor transmission while blocking liquid water penetration.
- Water-Repellent Coating:PFAS phaseout mandates are forcing chemistry transitions from C6 and C8 fluorocarbons to silicone and hydrocarbon alternatives.
- Quick Dry:Accelerated evaporation through fiber selection and fabric construction supports travel and tropical climate applications.
- UV Protection:UPF-rated constructions address outdoor recreation and occupational sun exposure requirements.
Technology adoption runs deepest in Moisture Wicking. Steepest expansion trajectory belongs to Antimicrobial as ISO 18184 certification becomes standard in hospital linen contracts.
Application:
Performance specification intensity varies sharply across use cases, from aesthetic moisture management to life-safety thermoregulation.
- Sports:Competition-grade garments require moisture wicking combined with compression and aerodynamic surface engineering. United States collegiate athletics and professional team procurement drive specification intensity, with seasonal uniform cycles creating predictable demand patterns.
- Workwear:OSHA heat-stress regulations are mandating moisture-management properties in industrial uniforms, converting commodity procurement to technical garment specification. Construction and utility sectors in Texas and Florida represent early adoption concentration.
- Fitness:Boutique studio chains and home gym equipment bundling normalize performance fabric expectations among casual exercisers.
- Outdoor Recreation:Multi-layer systems require property-specific engineering across shell, insulation, and base layers.
- Military:Defense procurement mandates durability and flame resistance alongside moisture management, with specification freezes pending PFAS-free water-repellency validation.
- Casual Wear:Aesthetic moisture-wicking properties serve everyday comfort without performance certification requirements.
Established penetration characterizes Sports. Regulatory conversion is reshaping Workwear fastest.
End User:
User sophistication and procurement authority determine specification complexity and channel access.
- Athletes:Elite and professional competitors demand garment systems validated through biometric performance testing. United States Olympic training centers and professional franchise equipment managers drive co-development partnerships with technical apparel brands.
- Defense Personnel:Military procurement operates through defense logistics agencies with multi-year contract cycles and stringent durability requirements. Specification freezes on water-repellent finishes are delaying program transitions to fluorine-free alternatives.
- Fitness Enthusiasts:Recreational exercisers represent the volume expansion segment as boutique studio culture normalizes performance fabric expectations.
- Outdoor Professionals:Guides, rangers, and field researchers require multi-day wear durability and environmental protection.
- Corporate Sector Workers:Industrial uniform programs are upgrading to heat-stress-compliant moisture management under OSHA regulatory pressure.
- Students:School athletic programs and physical education requirements represent price-sensitive volume demand.
Institutional procurement maturity sits with Defense Personnel. Volume expansion concentrates in Fitness Enthusiasts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polyester and spandex feedstock concentration along the US Gulf Coast and in East Asian petrochemical corridors anchors geographic production patterns for performance fabric manufacturing.
United States
Fitness studio chains in Los Angeles and New York Metro normalize technical fabric expectations among casual exercisers. EPA registration mandates for antimicrobial finishes constrain smaller mill participation in medical procurement. North Carolina's textile belt hosts synthetic knit capacity serving collegiate athletics and boutique activewear brands.
Germany
REACH enforcement on PFAS discharge thresholds drives chemistry transitions in durable water-repellent finishes. The country's environmental agencies enforce stricter river basin compliance than minimum EU standards. Bavaria's technical textile clusters are installing closed-loop water systems to maintain defense contractor access.
Vietnam
Synthetic knit capacity expansion serves brand orders shifting from commodity basics to engineered sportswear. The country's national environmental regulator is tightening effluent standards for textile finishing operations. Ho Chi Minh City industrial zones host Dri-FIT manufacturing partnerships that anchor regional production networks.
India
Urban fitness culture in Mumbai and Bangalore remains underserved by organized performance apparel retail. Bureau of Indian Standards certification requirements are evolving for technical textile imports. Tamil Nadu's spinning mills are rebalancing capacity toward performance fabric production as export orders shift.
Indonesia
Export-oriented synthetic knit manufacturing serves North American and European brand procurement. The country's environmental ministry is implementing stricter wastewater discharge monitoring for textile finishers. Java's industrial corridors concentrate capacity vulnerable to single-country logistics disruptions.
Sweat Resistant Apparel Market Competitive Landscape
Global majors compete with regional champions across technology licensing and manufacturing scale. The vendor base stratifies into three tiers: integrated sportswear conglomerates with captive R&D, specialized performance fabric mills, and private-label contractors serving mass retail. Two strategic archetypes dominate: vertically integrated brands controlling proprietary fiber-to-garment pipelines, and technology licensors monetizing patented finishes across multiple manufacturing partners. Competitive moves concentrate on chemistry transition partnerships and direct-to-consumer channel buildouts.
Within the integrated brand tier, Nike and Adidas exemplify divergent approaches to supply chain control. Under Armour anchors innovation investment in compression and thermoregulation patents. These three entities represent the primary competitive anchors shaping procurement standards and technology licensing terms across the performance apparel value chain.
| Leading Market Players |
|---|
| Nike |
| Adidas |
| Under Armour |
| Lululemon Athletica |
| Columbia Sportswear |
| Hanesbrands |
| Patagonia |
| Puma |
| Decathlon |
| Others |
Pricing and Supply Chain Analysis
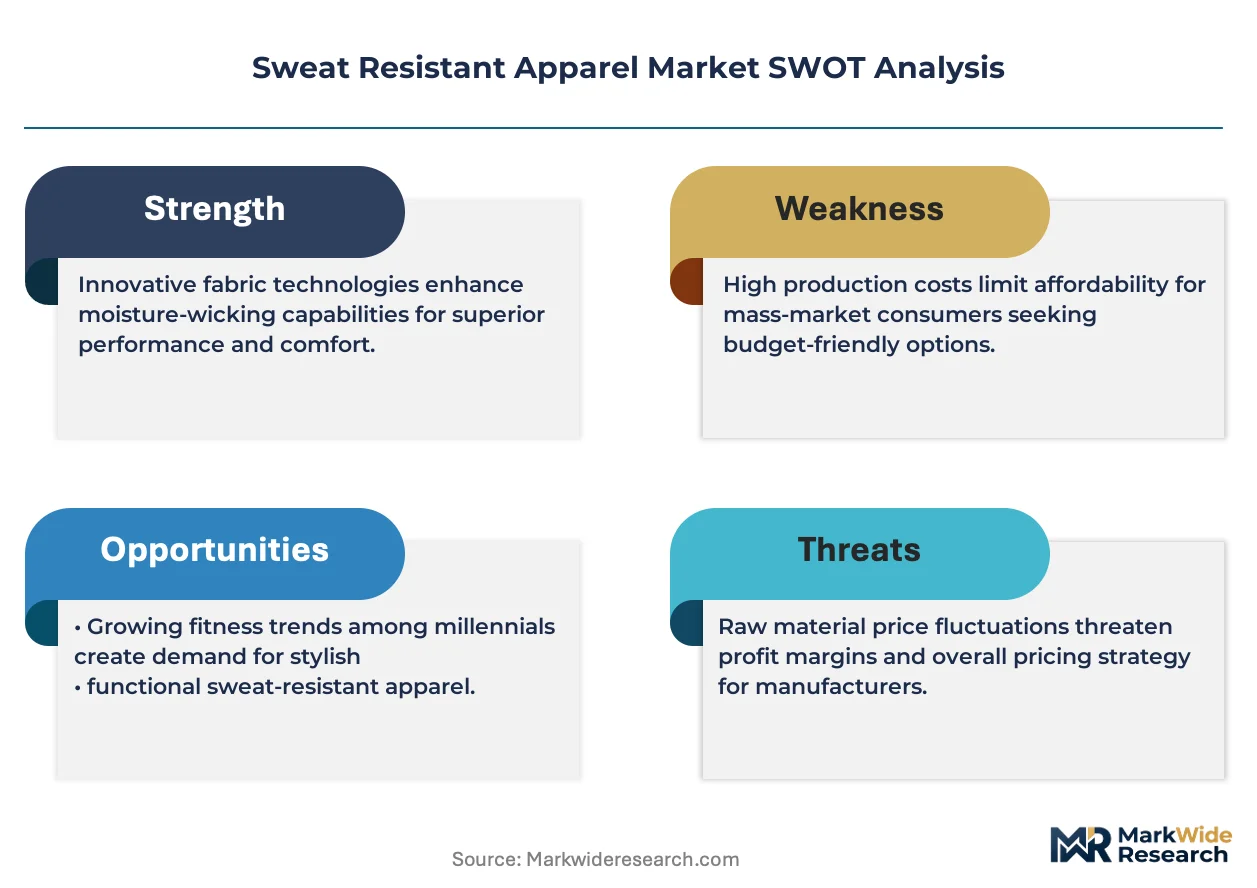
Captive control over proprietary fiber-to-garment pipelines anchors Nike's supply position and pricing power through Dri-FIT manufacturing partnerships in Vietnam and Indonesia. This integration insulates branded activewear from commodity margin compression while forcing private-label competitors to absorb polyester feedstock volatility on spot markets.
Pricing Analysis
Warranty-backed performance guarantees separate premium activewear from unbundled mass-market basics. Three-tier pricing structure across premium, standard, and economy levels reflects OEKO-TEX certification grade and EPA-registered antimicrobial finish status. Cost compression in economy polyester-cotton blends is intensifying because private-label retail consolidation concentrates buyer leverage. Students and school athletic programs exhibit highest price sensitivity; defense logistics agencies and hospital procurement committees show lowest.
Supply Chain Analysis
Single-source vulnerability sits with Vietnam's synthetic knit capacity concentration in Ho Chi Minh City industrial zones. Feedstock draws from US Gulf Coast and East Asian petrochemical corridors; finished fabric relies on Indonesian and Tamil Nadu spinning mills. Tariff exposure on US-bound shipments from Southeast Asia creates margin unpredictability. Distribution runs through brand-controlled micro-fulfillment nodes serving direct-to-consumer subscription channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA registration timelines for antimicrobial finishes function as a cost-of-compliance moat, freezing smaller mills out of premium medical and military procurement channels for 18-24 months. This regulatory barrier rewards early-compliant suppliers with locked-in contract access.
For Market Incumbents: Deepen backward integration into proprietary yarn engineering to defend against fluorine-free chemistry transition delays. Expand captive lyocell-polyester blend capacity in Tamil Nadu before REACH restrictions harden. Prioritize ISO 18184 certification maintenance as hospital linen contracts convert to antiviral standards. For New Entrants and Emerging Players: Capture white-space in Mumbai and Bangalore urban fitness retail through direct-to-consumer subscription models with algorithmic fit customization. Target workwear specification upgrades under OSHA heat-stress mandates in Texas and Florida construction corridors. Lead with cellulosic-synthetic blends positioned between petroleum synthetics and untreated cotton. For Investors and Strategic Acquirers: Exit pathways concentrate in technology licensing to mid-tier mills lacking EPA compliance infrastructure. Long-term viability favors finish houses with validated fluorine-free water-repellency portfolios. Watch for defense procurement specification unfreezes as C6 alternative durability benchmarks clear.| Strategic Initiative | Industry Significance |
|---|---|
| Fluorine-Free Chemistry Transition | REACH compliance unlocks European defense and outdoor procurement contracts. |
| Direct-to-Consumer Subscription Launch | California and New York metro millennials displace seasonal wholesale purchasing. |
| ISO 18184 Certification Investment | Antiviral textile validation opens hospital linen procurement channels. |
| Lyocell-Polyester Capacity Expansion | Sustainability credentials bridge petroleum synthetics and untreated cotton positioning. |
| Micro-Fulfillment Network Buildout | Urban logistics reconfiguration supports curated monthly delivery expectations. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for triangulation with primary interviews. Conversations with textile mill technical directors, brand supply chain managers, EPA compliance consultants, and hospital procurement officers informed operational assumptions. FDA guidance documents, OEKO-TEX certification databases, and Bureau of Indian Standards technical textile import records provided secondary validation. Bottom-up mill capacity estimates and top-down brand revenue allocations were cross-referenced.
Segment-level modeling addressed product type, technology stack, application intensity, and end-user sophistication across the projection horizon. CAGRs were derived from volume trajectory analysis against feedstock cost indices and regulatory implementation schedules. Lyocell fiber supply elasticity and PFAS phaseout compliance timelines served as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to REACH enforcement severity and defense procurement specification unfreeze timing. Forecasts reflect documented assumptions about chemistry transition validation cycles and boutique studio chain expansion rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.