
 Denim Market | 2026-2036
Denim Market Size, Share, and Industry Trends Forecast 2026-2036
Denim Market Analysis
Market Dynamics
Bangladesh is reconfiguring denim manufacturing capacity through backward integration into yarn spinning and finishing facilities. Levi Strauss & Co. leverages its direct-to-consumer channel expansion to sustain pricing power in premium segments. Arvind Limited anchors South Asian supply through integrated cotton-to-garment operations. ISKO competes on technical fabric innovation with proprietary stretch and recovery technologies.
Technical Definition and Segment Structure
Denim is a rugged cotton twill textile woven with a colored warp yarn and white weft yarn, typically weighing 12–14 ounces per square yard and distinguished by its diagonal ribbing created through a 3x1 or 2x1 twill weave structure. The fabric's primary commercial purpose centers on durable apparel construction where abrasion resistance and structural integrity withstand repeated mechanical stress and washing cycles. Jeans within the product type category occupy the dominant margin pool as the mature volume anchor, while jackets and shorts represent faster-growing segments driven by seasonal fashion cycling and casualization trends. Stretch fabric types command premium positioning through elastane integration that expands mobility applications beyond traditional workwear into performance-oriented casual segments.
Regulatory Environment
ECHA REACH restrictions on azo dyes and formaldehyde-based resins reshape European denim finishing requirements, forcing reformulation of wash and treatment chemistries. The EU Green Deal's textile sustainability mandates accelerate water recycling investments and restrict sandblasting operations across contracted manufacturing networks. Stakeholders must monitor evolving chemical disclosure thresholds and traceability requirements that determine market access across major consumption regions.
Market Dynamics
EU Green Deal chemical restrictions are forcing denim finishers to rebuild wash chemistry portfolios and water recycling infrastructure, compressing margins for non-compliant suppliers while rewarding early reformulators with preferential retail access.
Growth Catalysts
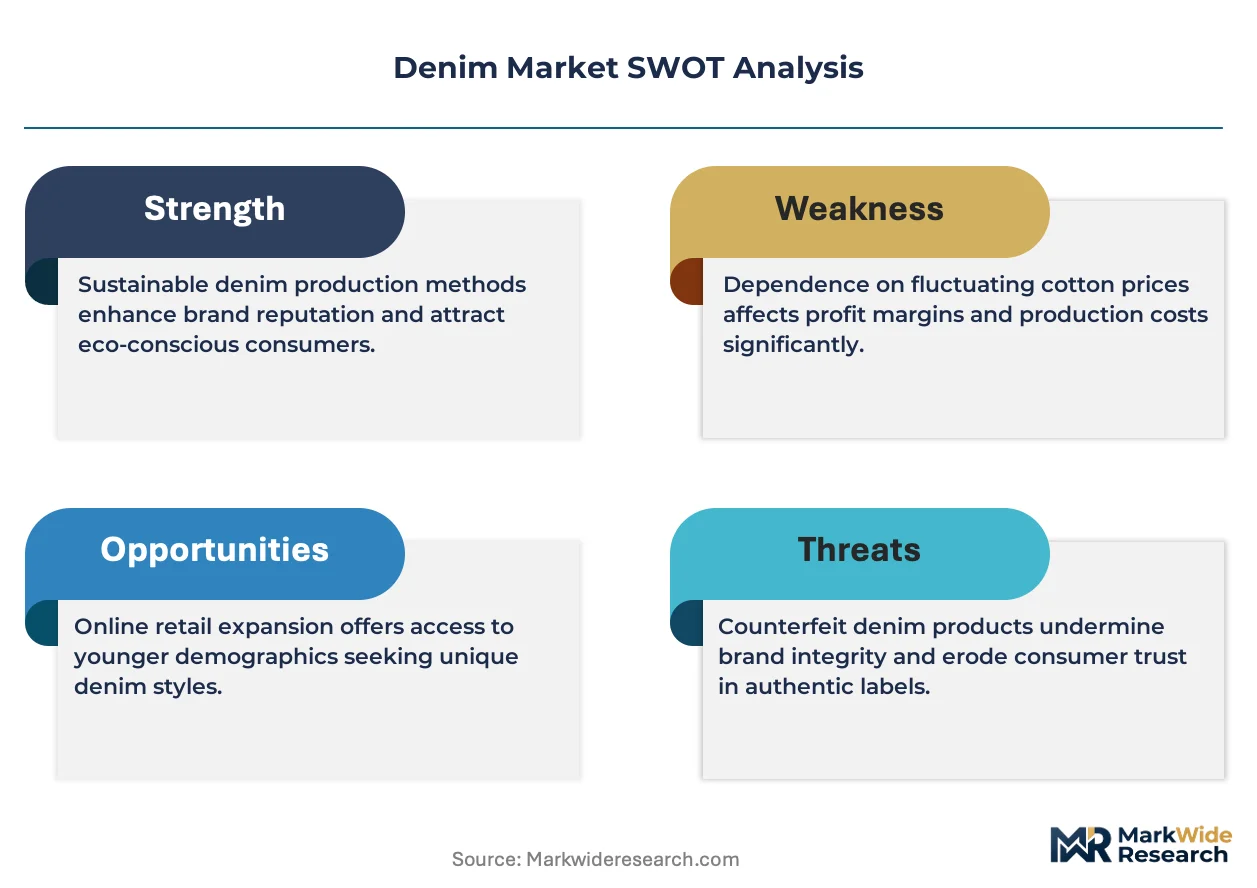
- ECHA REACH dye reformulation:European azo dye bans accelerate adoption of bio-based indigo alternatives and enzyme-based finishing, creating first-mover advantages for certified suppliers.
- Athleisure-wear crossover demand:United States consumers prioritize stretch denim with recovery properties, expanding elastane integration into premium casual segments beyond traditional workwear applications.
- Bangladesh backward integration:Captive yarn spinning and finishing capacity reduces import dependency and shortens lead times for European fast-fashion contracts.
Market Restraints
- Cotton price volatility:Weather-driven supply disruptions and speculative trading in ICE cotton futures transmit cost shocks directly to fabric margins.
- Water stress in South Asian basins:Groundwater depletion around Dhaka and Karachi forces reliance on expensive municipal supply or recycled water capital expenditure.
- Technical limitations in bio-stretch:Current bio-based elastane alternatives fail to match petroleum-derived Lycra recovery rates above 40% stretch thresholds.
Strategic Opportunities
- EU Green Deal textile sustainability mandates:Mandatory extended producer responsibility schemes create revenue streams for take-back and fiber-to-fiber recycling services.
- Blockchain traceability integration:Converging distributed ledger technology with chemical testing protocols enables premium pricing for verified supply chain transparency.
- Direct-to-consumer channel expansion:Bypassing wholesale markups allows margin capture and first-party data collection for predictive inventory positioning.
Industry Challenges
- Finishing chemist talent scarcity:Reformulation expertise for enzyme-based and laser-based wash effects remains concentrated among a narrow specialist cohort.
- Legacy ERP integration friction:Water monitoring and chemical inventory systems require costly middleware to connect with existing enterprise platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Denim Market |
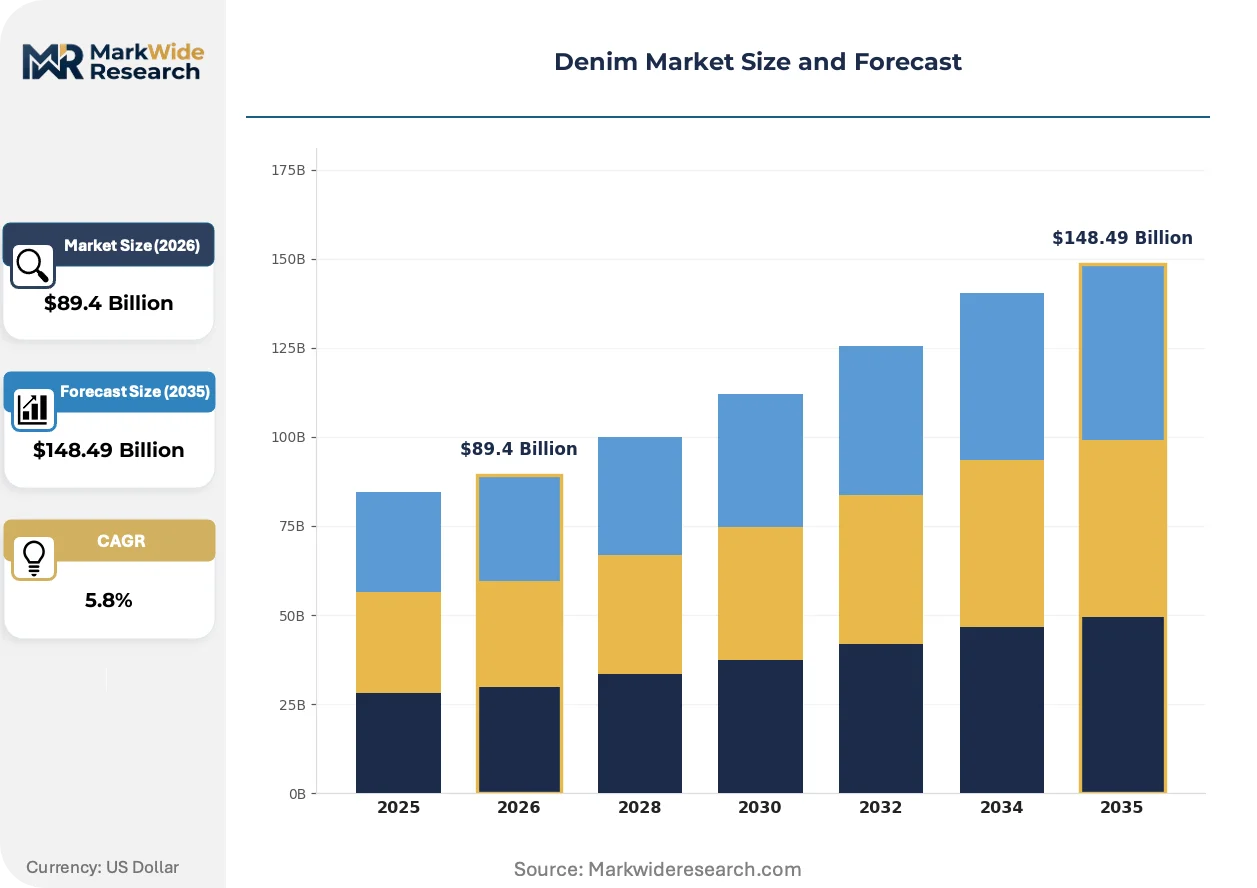
| Market Size in 2026 | $89.4 Billion |
| Market Size in 2035 | $148.49 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Jeans, Jackets, Shorts, Skirts Fabric Type: Cotton, Stretch, Organic, Blended End User: Men, Women, Children, Unisex Distribution Channel: Online, Retail, Wholesale, Boutique |
| Companies Covered | Grupo Denim, Blue Age Denim, Levi Strauss & Co., Kaihara, Nien Hsing Textile Co., Arvind Limited, Changhong Garment Co., Ltd., DiZNEW Factory, ISKO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Denim Market Emerging Trajectories
Laser finishing technology is compressing traditional wash chemistry volumes while regulatory pressure and demand fragmentation pull supply chains toward modular, low-water production architectures.
Digital laser surface treatment is digitizing manual abrasion and whiskering processes previously performed by chemical washes or hand-sanding. Premium denim brands in Japan and Italy adopt these systems to reduce water consumption below 5 liters per garment. This shift is digitizing quality control protocols and enabling single-piece customization at scale.
ECHA REACH restrictions on formaldehyde-based resins and azo dyes force European finishers to validate alternative cross-linking chemistries and natural indigo sources. Compliance timelines compress to 18-24 months for existing product lines. Women's fashion denim in Germany and France bears the highest reformulation burden as retailers enforce chemical disclosure thresholds ahead of legal mandates.
Buyers now demand outcome-based transparency certificates rather than generic sustainability claims, compressing trust cycles between brands and manufacturing partners. Direct-to-consumer channels in the United States bypass traditional wholesale gatekeepers, shifting margin capture upstream. This pattern is most visible in Los Angeles and New York metro areas where vertically integrated studios offer 72-hour turnaround on small-batch custom fits.
Denim Market Segmentation
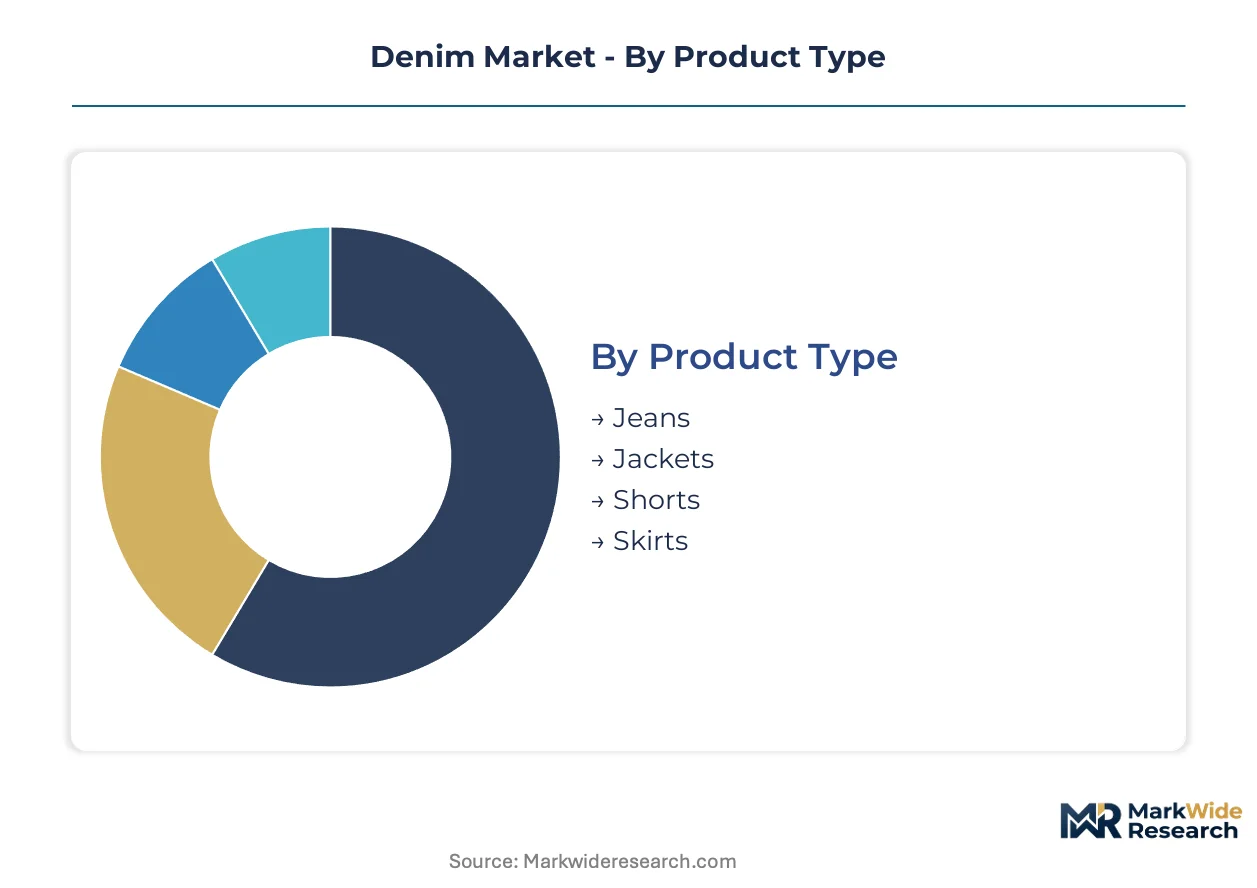
Denim segmentation reveals divergent margin profiles across product lifecycles, where seasonal fashion velocity in outerwear contrasts with the replenishment economics of core bottoms. Understanding these turnover differentials enables inventory positioning that matches capital deployment to cash conversion speed.
Product Type:
Cycle times vary dramatically: jeans turn on predictable replenishment calendars while jackets and shorts ride seasonal fashion waves with compressed selling windows.
- Jeans:The foundational 12–14 ounce cotton twill construction dominates unit economics through standardized sizing and repeat purchase patterns. United States mass-market retailers rely on denim bottoms for traffic generation, though athleisure crossover styles now command premium shelf space in Los Angeles and New York metro areas.
- Jackets:Trucker and chore coat silhouettes experience accelerated fashion cycling as seasonal layering trends shift. European fast-fashion contracts from Germany and France prioritize quick-turn jacket programs that exploit shorter lead times from Bangladesh integrated manufacturers.
- Shorts:Seasonal demand concentrates in warm-climate markets with narrow selling windows requiring precise inventory timing.
- Skirts:Fashion-forward silhouettes serve trend-responsive segments with higher markdown risk but margin upside on hits.
Jeans anchors the volume base while jackets gains share at the steepest rate.
Fabric Type:
Raw material tiers separate performance specifications from commodity positioning, with elastane integration and certification premiums defining margin stratification.
- Cotton:Conventional 100% cotton constructions remain the cost benchmark for entry-level price tiers. ICE futures volatility transmits directly to fabric margins, forcing Bangladesh spinners to hedge exposure or absorb short-term shocks.
- Stretch:Elastane blends typically integrating 2–5% Lycra or petroleum-derived spandex enable mobility applications that expand beyond workwear into performance casual segments. United States consumers prioritize recovery properties above 40% stretch thresholds where bio-based alternatives currently fail.
- Organic:Third-party certified cotton commands sourcing premiums from European retailers responding to EU Green Deal disclosure mandates.
- Blended:Tencel, hemp, and recycled fiber mixes address sustainability positioning with variable performance trade-offs.
Cotton maintains the deepest volume footprint while stretch climbs the fastest on athleisure crossover demand.
End User:
Demographic targeting aligns product development cycles with distinct purchasing behaviors and fit complexity requirements.
- Women:Fashion denim adoption accelerates as EU Green Deal chemical restrictions force reformulation of wash and treatment chemistries. German and French retailers enforce disclosure thresholds ahead of legal mandates, concentrating compliance burden in this segment.
- Men:Core replenishment patterns dominate with slower fashion cycling and standardized fits that reduce return rates.
- Children:Growth-out replacement cycles create predictable demand with lower per-unit price points and durability emphasis.
- Unisex:Gender-neutral silhouettes expand addressable market through simplified SKU architectures.
Women's fashion denim generates the highest reformulation investment while unisex offerings expand most quickly on streamlined operations.
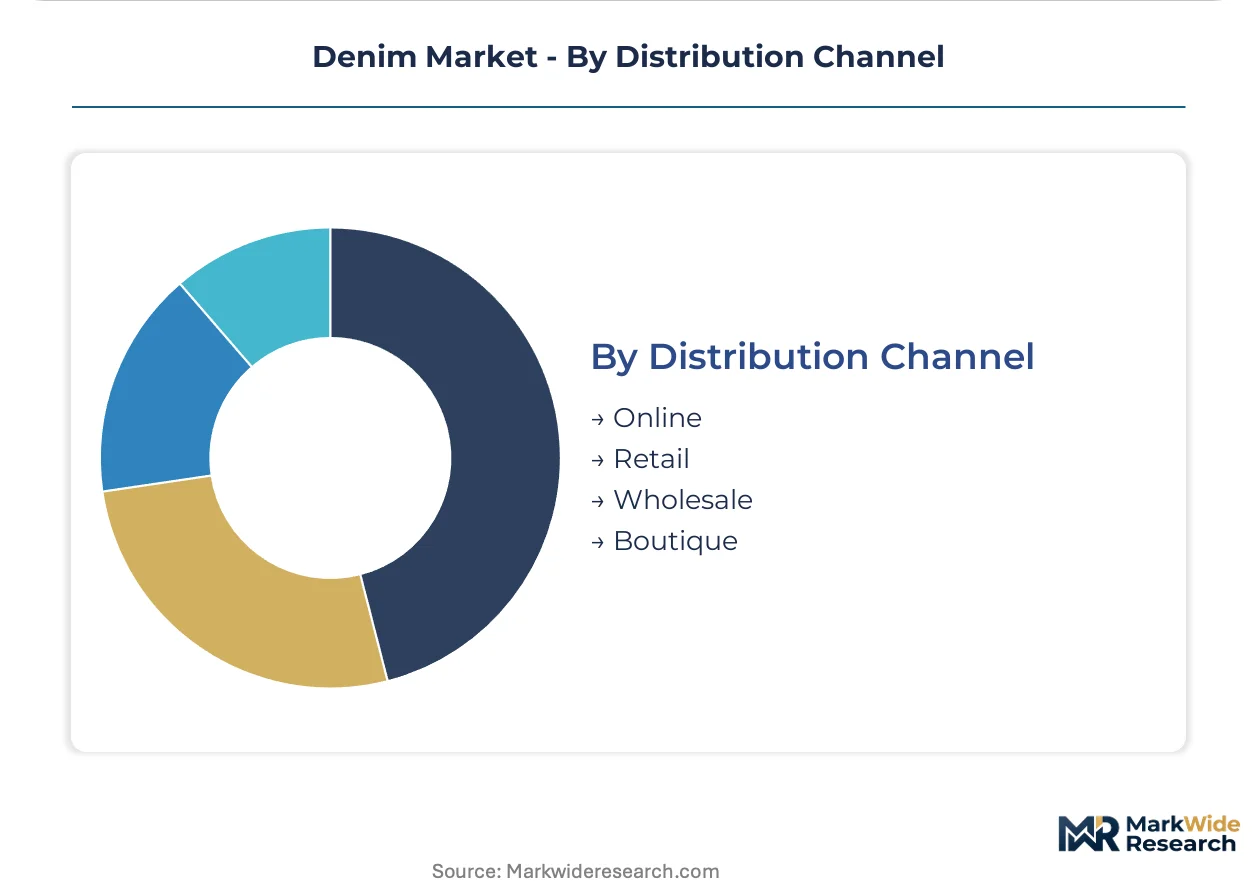
Distribution Channel:
Channel economics determine margin capture potential and data ownership, with direct relationships displacing wholesale intermediaries in premium positioning.
- Online:Direct-to-consumer expansion enables first-party data collection and predictive inventory positioning. Los Angeles and New York vertically integrated studios leverage 72-hour turnaround capabilities on small-batch custom fits.
- Retail:Flagship and department store presence sustains brand authority with higher fixed cost burdens.
- Wholesale:Third-party retail partnerships sacrifice margin for reach, concentrating volume in mass-market price tiers.
- Boutique:Curated independent accounts serve discovery-oriented consumers with higher full-price realization.
Online channels capture margin expansion while boutique access builds brand heat fastest among trend-forward segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Chittagong Port's container throughput underwrites Bangladesh's denim export dominance, connecting spinning mills in Gazipur to European fast-fashion buyers through direct vessel calls. This maritime infrastructure compresses lead times against competing Asian supply bases.
United States
Athleisure crossover styles drive elastane integration above 40% stretch thresholds in Los Angeles and New York metro areas. EPA wastewater discharge standards constrain finishing operations in California's Central Valley. Vertically integrated studios in downtown Los Angeles offer 72-hour turnaround on small-batch custom fits, capturing direct-to-consumer margins.
Germany
EU Green Deal chemical disclosure mandates concentrate reformulation investment in women's fashion denim. ECHA REACH azo dye bans accelerate bio-based indigo adoption in North Rhine-Westphalia's finishing cluster. The ChemCologne network near Leverkusen supplies enzyme-based wash chemistries to compliant suppliers.
Bangladesh
Backward integration into captive yarn spinning reduces cotton import dependency for Dhaka-based manufacturers. The central bank's export refinancing scheme subsidizes working capital for Green Deal compliance investments. Gazipur's integrated textile parks cluster spinning, weaving, and finishing within 50-kilometer radii.
Italy
Premium heritage positioning sustains margin capture in Veneto's Prosecco denim belt. ECHA restrictions on formaldehyde-based resins force reformulation of traditional rigid denim finishes. Prato's regenerated fiber processors supply recycled cotton blends to certified sustainable lines.
Japan
Kaihara's Okayama Prefecture operations anchor selvedge denim prestige for domestic and export markets. METI's Green Transformation bonds finance water recycling infrastructure at legacy finishing sites. Kojima's Jeans Street retail cluster concentrates brand flagship presence and tourist foot traffic.
Denim Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream on technical fabric innovation. The vendor base stratifies between scale-driven commodity suppliers and premium-tier heritage houses. Three archetypes dominate: integrated cotton-to-garment operators, technical stretch innovators, and direct-to-consumer brand platforms. Capacity expansion and chemical compliance certification constitute the primary competitive vectors.
Among heritage-brand platforms, Levi Strauss & Co. occupies a position exemplifying direct-to-consumer channel leverage. Technical fabric specialists include ISKO, which sits within the stretch innovation tier. Integrated supply operators find representation in Arvind Limited, anchoring South Asian captive production archetypes. These three patterns illustrate the structural segmentation between brand margin capture, material science differentiation, and manufacturing scale.
| Leading Market Players |
|---|
| Grupo Denim |
| Blue Age Denim |
| Levi Strauss & Co. |
| Kaihara |
| Nien Hsing Textile Co. |
| Arvind Limited |
| Changhong Garment Co., Ltd. |
| DiZNEW Factory |
| ISKO |
| Others |
Supply Flow & Price Mechanics
The Chittagong Port's container throughput cost dynamics compress lead times for Bangladeshi spinners while amplifying price differentiation between European fast-fashion contracts and premium heritage buyers in Italy and Japan. This maritime corridor's efficiency concentrates supply-side power among integrated manufacturers capable of absorbing ECHA REACH compliance costs, forcing non-compliant finishers toward economy-tier pricing or exit.
Pricing Analysis
Volume-discount tiering structures separate premium selvedge lines certified for EU Green Deal compliance from standard stretch denim serving United States athleisure demand and economy-grade commodity cotton for mass-market replenishment. Price differentiation hinges on certification grade and elastane integration level, with stretch recovery above 40% thresholds commanding sustained premiums. Cost compression in the economy tier is intensifying because Bangladeshi spinners absorb ICE cotton futures volatility to defend contract renewals. Mass-market retailers exhibit highest price sensitivity, while Japanese heritage buyers and European sustainability-focused boutiques show lowest sensitivity.
Supply Chain Analysis
Upstream cotton feedstock draws from United States, Brazil, and Indian growing regions before concentrating in Bangladesh, Vietnam, and China's spinning and garment assembly operations. Raw material dependencies center on ICE cotton futures, petroleum-derived elastane, and bio-based indigo alternatives. Supply chain risk rests on water stress in South Asian basins forcing municipal supply reliance or recycled water capital expenditure. Distribution runs through direct-to-consumer channels in Los Angeles and New York, European fast-fashion buying offices in Germany and France, and heritage retail clusters in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards players who control scarce reformulation expertise for enzyme-based and laser-based wash effects, as ECHA REACH timelines compress to 18-24 months and certified chemist talent concentrates among narrow specialist cohorts.
For Market Incumbents: Build certification moats around ECHA REACH-compliant finishing chemistries and blockchain-integrated traceability systems. Levi Strauss & Co.'s direct-to-consumer channel expansion and ISKO's proprietary stretch recovery technologies illustrate defensive positioning against bio-based elastane disruptors. Incumbents should deepen backward integration into captive yarn spinning in Gazipur textile parks to shorten lead times for European fast-fashion contracts. For New Entrants and Emerging Players: Geographic underpenetration in laser finishing technology across South Asian supply bases offers white-space entry for capital-light equipment-as-a-service models. Target mid-tier United States brands seeking water consumption below 5 liters per garment without premium Italian equipment costs. A go-to-market angle pairing laser system leasing with certified chemist training programs addresses the talent scarcity blocking adoption. For Investors and Strategic Acquirers: Technical fabric innovators with proprietary stretch and recovery patents represent the acquisition target archetype most exposed to valuation expansion as bio-based elastane alternatives fail 40% stretch thresholds. Long-term viability favors players integrating digital laser finishing with predictive inventory positioning through first-party data capture. Watch for inflection when ECHA REACH disclosure thresholds tighten ahead of legal mandates, forcing accelerated compliance investment.| Strategic Initiative | Industry Significance |
|---|---|
| Laser Finishing Technology Deployment | Reduces water consumption below 5 liters per garment for ECHA REACH compliance in European markets. |
| Backward Integration into Yarn Spinning | Captive cotton-to-garment operations in Gazipur reduce import dependency and shorten lead times. |
| Blockchain Traceability Integration | Enables premium pricing for verified supply chain transparency demanded by German and French retailers. |
| Direct-to-Consumer Channel Expansion | Los Angeles and New York studios capture margin and first-party data for predictive inventory positioning. |
| Bio-Based Indigo Sourcing | Addresses ECHA REACH azo dye bans ahead of compliance timelines for women's fashion denim in Europe. |
Methodological Framework
The analysis maps stretch fabric innovation, laser finishing adoption, and EU Green Deal compliance pathways, each validated through finishing chemists, denim brand sourcing directors, and Bangladeshi textile park operators. Primary interviews with enzyme-based wash chemistry suppliers, European fast-fashion procurement leads, and United States vertically integrated studio founders combined with secondary validation from ECHA regulatory filings, ICE cotton futures data, and Chittagong Port throughput statistics. Bottom-up unit economics across product types and top-down market sizing triangulate volume and value estimates.
Assumption sets held ECHA REACH enforcement timelines and cotton price volatility patterns within observed ranges while varying athleisure crossover penetration rates and laser finishing adoption curves across the projection horizon. Segmentation dimensions modeled include product type lifecycle velocity, fabric type performance tier, end-user demographic purchasing behavior, and distribution channel margin capture structure. CAGRs derive from historical volume trajectories adjusted for regulatory inflection points and technology substitution elasticities, with elastane integration rates and water recycling capital expenditure serving as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by bio-based elastane innovators or laser equipment manufacturers would shift outcomes beyond modeled ranges. Cross-checking against ICE cotton futures forward curves and ECHA pre-registration disclosure databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel Textiles
Maternity Leggings Market
Apparel Textiles
Global Maternity Innerwear Market
Apparel Textiles
North America Garment Steamers Market
Apparel Textiles
Waterproof Fabrics for Sports Apparel Market
Apparel Textiles
Africa Textile Market
Apparel Textiles
Women's Jerseys, Sweatshirts and Pullovers Market
Apparel Textiles
Uniform Market
Apparel Textiles
North America Footwear Sole Material Market
Apparel Textiles
Global Prom Dresses Market
Apparel Textiles
Asia Pacific Garment Steamers Market
Apparel Textiles
North America Textile Garment Market
Apparel Textiles
Smart Clothing Market
Apparel Textiles
School Uniform Market
Apparel Textiles
Zipper Market
Apparel Textiles
Hunting Apparel Market
Apparel Textiles
Maternity Wear Market