
 Bamboo Apparel Market | 2026-2036
Bamboo Apparel Market Size, Share, and Industry Trends Forecast 2026-2036
Bamboo Apparel Market Outlook
The gap between mechanical and chemical bamboo fiber processing is narrowing as closed-loop solvent recovery systems reduce environmental footprints and production costs. Cariloha, Inc. anchors its competitive position through vertical control over bamboo sourcing from plantations in the Sichuan province. Ettitude Holdings, Inc. differentiates via proprietary CleanBamboo fabric technology that eliminates harsh chemicals from viscose production. Tasc Performance specializes in performance-oriented bamboo blends targeting athletic and outdoor segments with enhanced durability standards.
Bamboo apparel encompasses garments manufactured from fibers derived from the bamboo plant, typically processed through mechanical crushing and natural enzyme retting or chemical viscose methods yielding cellulosic textiles with inherent antibacterial and UV-resistant properties. Bamboo viscose dominates fabric type volumes due to established supply chains and silk-like drape characteristics preferred in women's dresses and premium underwear, while organic bamboo commands margin premiums in specialty retail channels. Online retail represents the fastest-growing distribution channel, driven by direct-to-consumer brands leveraging sustainability storytelling and subscription replenishment models for core basics.
The US Federal Trade Commission enforces textile labeling standards that distinguish mechanically processed bamboo from chemically derived rayon, shaping how brands communicate material origins to consumers. REACH regulations in Europe restrict certain chemicals in viscose production, pushing manufacturers toward certified closed-loop processes or mechanical alternatives. China's GB standards for textile safety and the National Development and Reform Commission's dual carbon goals influence domestic processing upgrades and export compliance costs. Stakeholders must monitor evolving certification schemes and traceability requirements as regulatory fragmentation across major markets intensifies compliance complexity.
Market Dynamics
The EU Green Deal's textile sustainability mandates are compressing certification timelines and forcing upstream investment in closed-loop solvent recovery systems across bamboo viscose production networks.
Growth Catalysts
- EU Green Deal textile mandates:The regulation's biodegradable material requirements are pulling brands toward certified bamboo fiber sourcing to maintain EU market access.
- Moisture-wicking performance demand:Women's activewear manufacturers are specifying bamboo blends for thermoregulating base layers that outperform synthetic alternatives in consumer trials.
- Sichuan plantation clusters:China's integrated bamboo fiber processing infrastructure is reducing raw material transit costs for downstream apparel manufacturers serving North American and Asian markets.
Market Restraints
- Caustic soda input volatility:Chemical viscose production remains exposed to sodium hydroxide price swings that compress processor margins during energy market disruptions.
- FTC labeling enforcement:The US regulator's strict distinction between mechanical bamboo and rayon creates compliance friction for brands using chemical processing methods.
- Organic cotton substitution:Established organic cotton supply chains with lower price premiums threaten bamboo's positioning in mid-market basics segments.
Strategic Opportunities
- REACH-compliant closed-loop expansion:European processors investing in certified solvent recovery systems can capture premium positioning as ECHA restrictions tighten on conventional viscose chemicals.
- Subscription replenishment models:Direct-to-consumer channels for core basics are bypassing wholesale markups and building recurring revenue streams.
- Mechanical-enzyme retting convergence:Combining traditional crushing methods with modern enzymatic treatments is opening performance applications previously reserved for chemical viscose.
Industry Challenges
- Closed-loop certification timelines:OEKO-TEX and GOTS verification processes for new processing facilities extend 18-24 months, delaying market entry.
- Traceability system integration:Blockchain and DNA tagging technologies require capital deployment that mid-tier processors struggle to finance without strategic partnerships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bamboo Apparel Market |
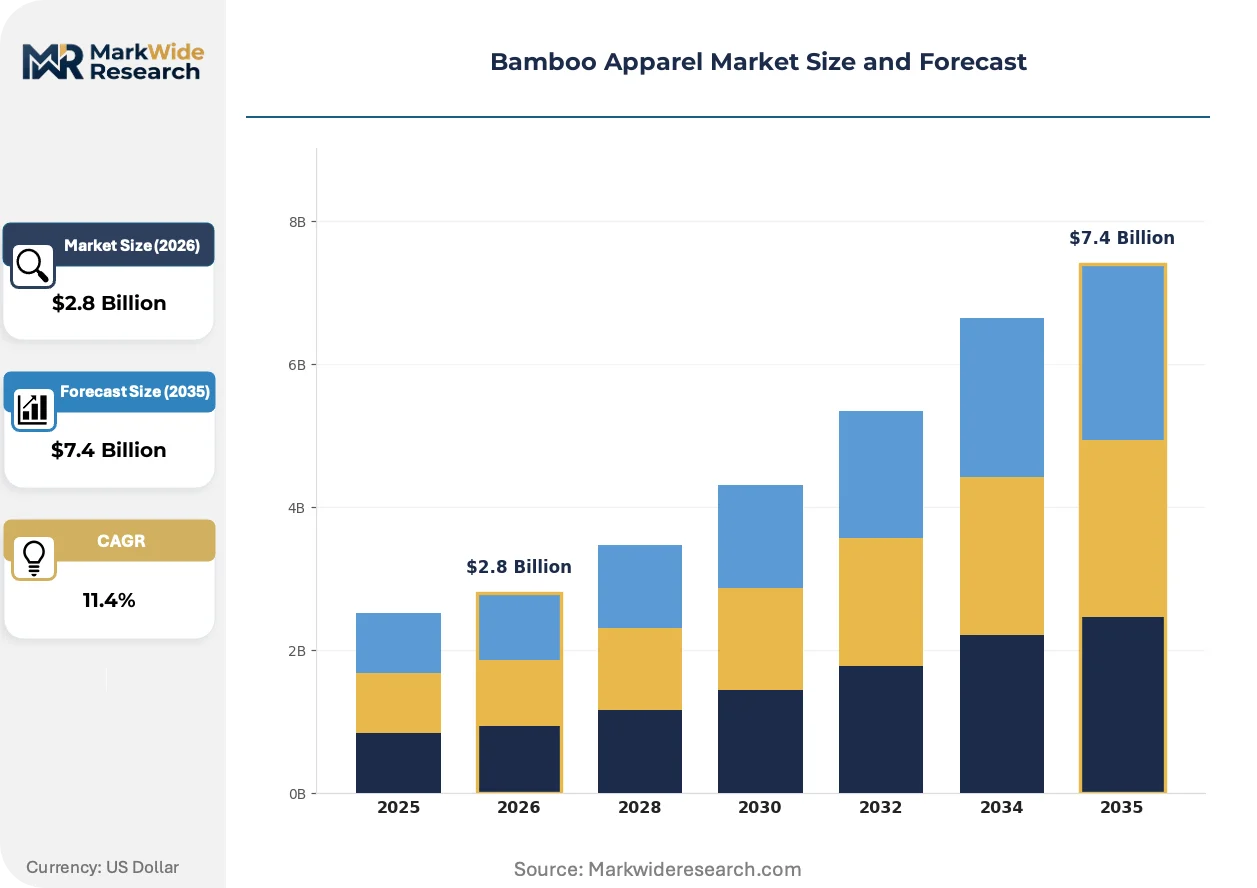
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: T-Shirts, Dresses, Activewear, Underwear End User: Men, Women, Children, Unisex Fabric Type: Bamboo Viscose, Bamboo Lycra, Bamboo Cotton Blend, Organic Bamboo Distribution Channel: Online Retail, Specialty Stores, Department Stores, Direct Sales |
| Companies Covered | Terrera, Royal Apparel Inc., Ettitude Holdings, Inc., Cariloha, Inc., Cozy Earth, LLC, Tasc Performance, Hara The Label Pty Ltd, Blue Canoe, Spun Bamboo LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bamboo Apparel Market Strategic Shifts
Processing technology and distribution architecture are undergoing simultaneous transformation as sustainability verification becomes a competitive differentiator rather than a compliance checkbox.
Closed-loop solvent recovery systems are migrating from pilot installations to commercial-scale deployment across viscose production facilities. European processors adopting these systems are securing preferential supply contracts with sustainability-focused retailers. The technology is migrating from niche certification premiums toward baseline market access requirements as REACH enforcement intensifies.
REACH chemical restrictions are forcing reformulation of traditional viscose production inputs across European manufacturing zones. Processors are accelerating capital deployment into alternative solvent systems ahead of 2025-2027 regulatory phase-outs. Women's premium underwear and dress segments are absorbing the highest compliance costs while pushing suppliers toward mechanical fiber alternatives.
Direct-to-consumer subscription models for core basics are displacing traditional wholesale replenishment cycles among digitally native brands. These brands are capturing full margin stacks while building proprietary customer data assets. China and the US represent the primary geographies where this channel shift is compressing traditional retail intermediation.
Bamboo Apparel Market Segmentation
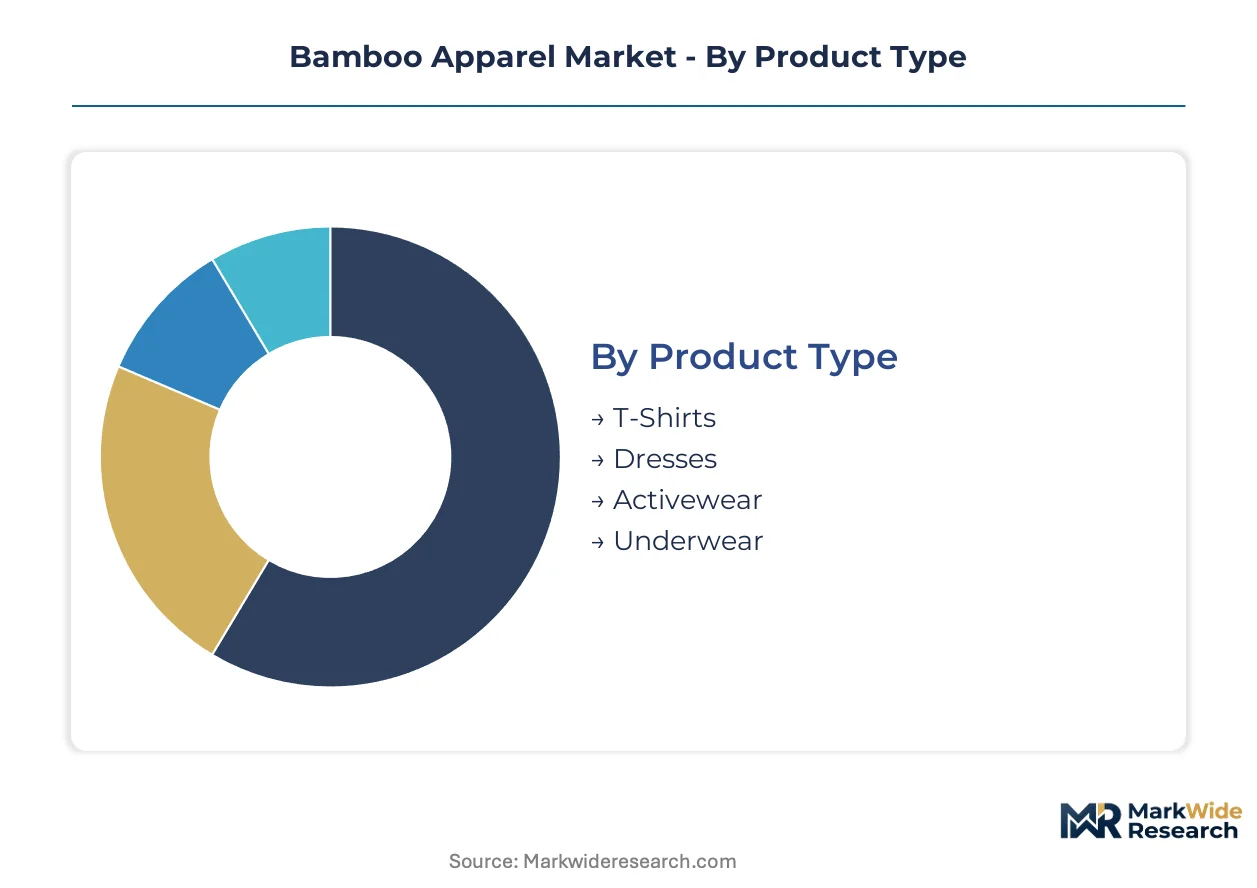
Bamboo apparel segmentation reveals how fiber processing methods and distribution architectures create distinct competitive arenas. Each dimension carries implications for margin structure, certification requirements, and customer acquisition costs.
Product Type:
Cost tier stratification across garment categories determines raw material specifications and margin capture potential.
- Activewear:High-performance bamboo blends with enhanced moisture-wicking and thermoregulating properties command premium positioning. Women's fitness segments in China and North America are absorbing volume as synthetic alternatives face microplastic scrutiny.
- Underwear:Seamless construction and antibacterial fiber properties address hygiene-sensitive applications. Direct-to-consumer replenishment models are concentrating demand for core basics in the US and EU markets.
- T-Shirts:Standard-weight bamboo viscose knits serve entry-level sustainability positioning with lower certification thresholds.
- Dresses:Fluid drape characteristics of bamboo viscose dominate formal and casual categories, with EU retailers specifying REACH-compliant closed-loop sourcing.
Activewear holds installed capacity. Underwear is rotating up the share rankings.
End User:
Customer type differentiation shapes sizing complexity, color palette breadth, and marketing channel selection.
- Women:The largest addressable base spanning activewear, loungewear, and premium underwear categories. Moisture-wicking base layers and UV-protective outdoor garments are driving specification upgrades in Chinese manufacturing clusters.
- Men:Concentrated in performance basics and outdoor segments with simpler SKU requirements and higher repeat purchase rates.
- Children:Hypoallergenic positioning and soft hand-feel requirements dominate, with EU safety standards (EN 71, OEKO-TEX Standard 100) governing chemical residue limits.
- Unisex:Simplified sizing and neutral colorways reduce inventory risk for digitally native brands pursuing subscription replenishment models.
Women's segments anchor current revenue. Children's categories are expanding most quickly as parental safety consciousness intensifies.
Fabric Type:
Material composition determines processing capital intensity, certification pathway, and end-market accessibility.
- Bamboo Viscose:Chemically processed cellulosic fiber with silk-like drape and established supply chains. REACH restrictions on carbon disulfide are forcing European processors toward closed-loop solvent recovery investments.
- Organic Bamboo:Mechanically processed or certified organic chemical methods command margin premiums in specialty retail. GOTS and OEKO-TEX MADE IN GREEN verification extends 18-24 months, delaying market entry for new suppliers.
- Bamboo Lycra:Stretch performance blends target athletic applications with enhanced recovery properties.
- Bamboo Cotton Blend:Cost-optimized intermediate positioning bridges pure bamboo and conventional cotton price points.
Bamboo viscose maintains dominant capacity share. Organic bamboo is gaining share fastest as EU Green Deal compliance hardens.
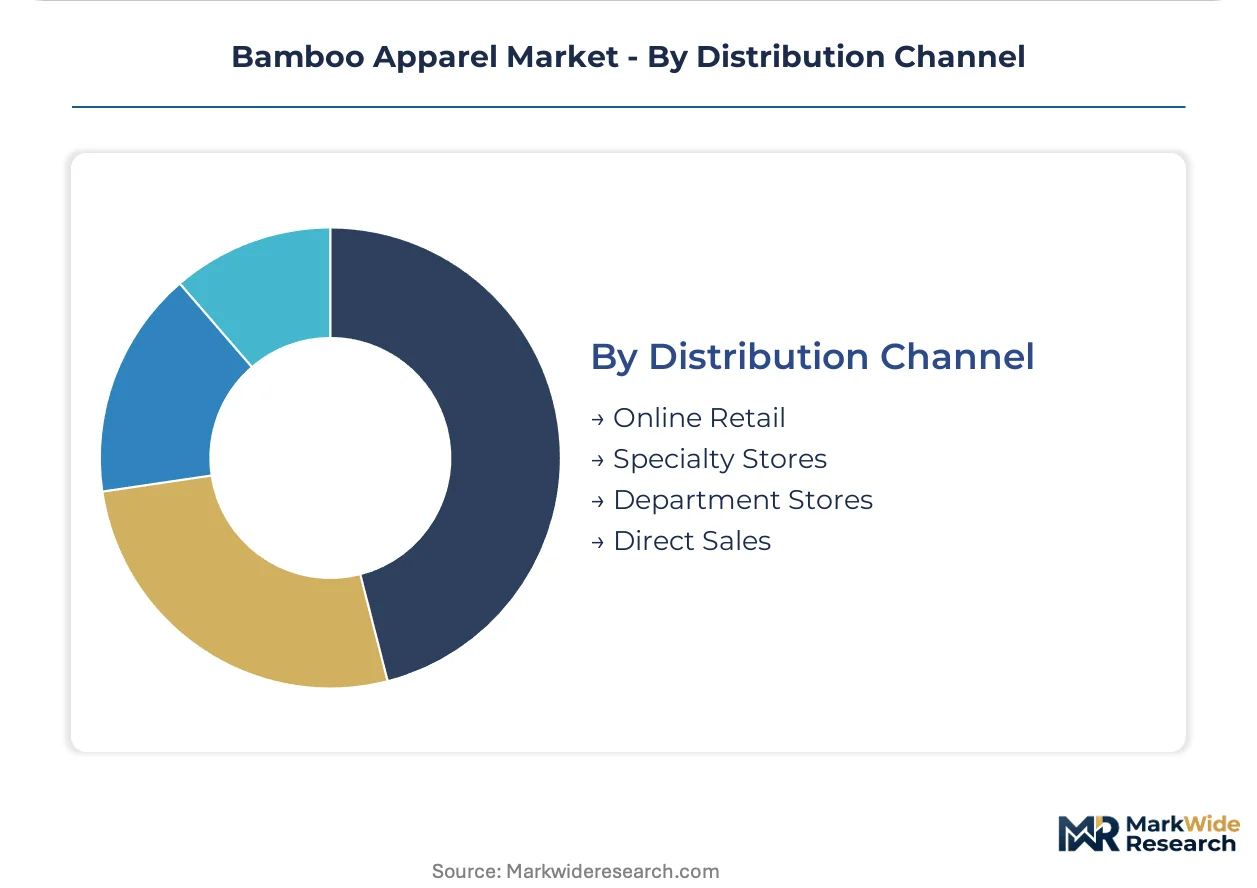
Distribution Channel:
Channel architecture governs margin retention, customer data ownership, and inventory velocity.
- Online Retail:Direct-to-consumer platforms bypass wholesale markups and enable subscription replenishment for core basics. Chinese and US markets exhibit the steepest channel shift toward digital-native brands.
- Specialty Stores:Curated sustainability storytelling and tactile evaluation support premium pricing for certified organic grades.
- Department Stores:Consolidated purchasing power demands volume commitments and standardized SKU matrices, favoring established bamboo viscose suppliers.
- Direct Sales:Pop-up installations and brand-owned physical touchpoints test markets before permanent retail commitments.
Department stores retain legacy volume. Online retail is climbing the fastest as customer acquisition costs stabilize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Direct-to-consumer brands concentrate procurement decisions in China, the United States, Germany, and Japan, with each geography presenting distinct certification requirements and channel access conditions.
China
Women's activewear manufacturers source bamboo viscose from Sichuan province processing clusters. GB textile safety standards and the National Development and Reform Commission's dual carbon goals drive domestic facility upgrades. Chengdu-based integrated mills supply raw fiber to downstream apparel manufacturers serving North American export markets.
United States
Subscription replenishment models for core basics concentrate demand among digitally native brands. The FTC enforces strict textile labeling distinctions between mechanical bamboo and chemically derived rayon. California and New York Metro area headquarters control brand positioning and customer acquisition strategies.
Germany
REACH chemical restrictions force reformulation of traditional viscose production inputs. ECHA enforcement timelines push processors toward closed-loop solvent recovery investments. Bavaria and North Rhine-Westphalia host specialty retailers curating certified organic bamboo grades for EU consumers.
Japan
Performance-oriented bamboo blends target athletic applications with enhanced durability standards. METI guidelines influence sustainable textile procurement across domestic retail channels. Osaka-based trading houses coordinate import logistics for Southeast Asian manufacturing partners.
United Kingdom
Loungewear segments absorb REACH-compliant closed-loop sourcing premiums from EU suppliers. London and Southeast England headquarters manage direct-to-consumer platform operations. Midlands distribution centers handle fulfillment for subscription replenishment models targeting EU market access.
Bamboo Apparel Market Competitive Environment
Channel-controlling players compete with product-specialist players across a market structure that fragments between vertically integrated plantation operators and digitally native brand builders. Three archetypes dominate: Sichuan-based upstream controllers with captive fiber supply, proprietary fabric technology licensors, and performance-apparel specialists with athletic segment focus. Competitive moves concentrate on backward integration into plantation assets and direct-to-consumer platform expansion.
Within the proprietary technology tier, Ettitude Holdings, Inc. and Cariloha, Inc. exemplify divergent approaches to supply chain positioning. Tasc Performance occupies a position representing the performance-specialist archetype. These three entities anchor the competitive landscape without exhausting its structural variation.
| Leading Market Players |
|---|
| Terrera |
| Royal Apparel Inc. |
| Ettitude Holdings, Inc. |
| Cariloha, Inc. |
| Cozy Earth, LLC |
| Tasc Performance |
| Hara The Label Pty Ltd |
| Blue Canoe |
| Spun Bamboo LLC |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in closed-loop viscose processing facilities across Germany and Austria is compressing margins for REACH-compliant bamboo fiber while simultaneously elevating pricing power for certified European suppliers serving premium EU apparel brands.
Pricing Analysis
Cost-plus contracts with sodium hydroxide indexation dominate chemical viscose procurement agreements between Sichuan processors and North American apparel brands. Pricing stratifies across GOTS-certified organic grades, standard closed-loop viscose, and conventional rayon alternatives based on certification tier and solvent recovery technology. Cost compression in mid-market bamboo cotton blends is intensifying because organic cotton supply expansion narrows the premium gap. Fast-fashion private labels exhibit highest price sensitivity, while specialty retailers curating sustainable assortments absorb certification premiums with minimal volume elasticity.
Supply Chain Analysis
Upstream Moso bamboo feedstock cultivation concentrates in Sichuan, Zhejiang, and Fujian provinces where plantation-to-processor distances minimize transit spoilage. Raw material sourcing draws from enzymatic retting facilities, carbon disulfide-based viscose plants, and mechanical crushing operations with divergent capital requirements. Single-source vulnerability persists for European brands dependent on Chengdu-clustered integrated mills lacking qualified alternative suppliers. Distribution runs through direct-to-consumer platforms, specialty retail partnerships, and consolidated department store purchasing with divergent margin retention profiles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Profitable scaling in bamboo apparel hinges on scarce closed-loop certification expertise and captive plantation access, with these capabilities concentrated among upstream-integrated operators rather than pure brand plays.
For Market Incumbents: Entrench market position through backward integration into Sichuan plantation assets and accelerated OEKO-TEX MADE IN GREEN certification timelines ahead of ECHA solvent restrictions. Organic cotton substitution in mid-market basics represents the primary demand threat requiring premium tier elevation. Closed-loop capacity addition in Austria or Germany secures EU market access as REACH enforcement tightens. For New Entrants and Emerging Players: Establish a beachhead in children's hypoallergenic segments where parental safety consciousness drives rapid share gain and certification barriers remain surmountable. Women's premium underwear in the US direct-to-consumer channel offers the most penetrable white space with subscription replenishment models enabling recurring revenue capture. Position around mechanical-enzyme retting technology to bypass chemical viscose regulatory exposure entirely. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among digitally native brands with subscription replenishment models for core basics, suggesting superior cash flow quality versus wholesale-dependent operators. Long-term viability across the projection horizon favors processors with certified closed-loop infrastructure and vertical plantation control. Watch OEKO-TEX and GOTS certification backlog durations as the inflection signal for supply-constrained pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Loop Certification Investment | REACH-compliant solvent recovery systems secure preferential supply contracts with EU retailers ahead of ECHA phase-outs. |
| Direct-to-Consumer Platform Launch | Subscription replenishment models for underwear and loungewear capture full margin stacks and proprietary customer data assets. |
| Plantation Backward Integration | Sichuan-based Moso bamboo cultivation control insulates raw material costs from transit volatility and quality inconsistency. |
| Mechanical-Enzyme Retting Scale-Up | Combining traditional crushing with enzymatic treatments opens performance applications without carbon disulfide regulatory exposure. |
| Premium Tier Brand Extension | GOTS-certified organic bamboo positioning captures margin premiums in specialty retail channels with tactile evaluation requirements. |
Study Parameters
Initial hypotheses were tested against primary input from bamboo fiber processing plant managers, sustainability certification auditors, apparel brand procurement directors, and specialty retail category buyers and refined through secondary validation against customs trade records, OEKO-TEX and GOTS certification databases, FTC textile labeling enforcement actions, and EU ECHA regulatory filings. Bottom-up fiber production estimates and top-down apparel consumption modeling were triangulated to reconcile volume figures.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation dimensions spanning fabric processing method, distribution channel architecture, end-user category, and regional regulatory cluster. CAGRs were derived from installed capacity trajectories, certification timeline projections, and channel shift velocity assumptions. Forecast inputs incorporated Sichuan plantation yield trends and EU Green Deal implementation pacing.
Macroeconomic conditions sit as an overlay; deviation in consumer discretionary spending indices, caustic soda energy-linked pricing, or euro-dollar exchange rates would shift the trajectory. Forecasts reflect documented assumptions regarding certification adoption curves and regulatory enforcement intensity. Cross-checking against customs export data from China's National Bureau of Statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel Textiles
Apparel Supply Chain Market
Apparel Textiles
Asia Pacific Garment Steamers Market
Apparel Textiles
Equestrian Apparel Market
Apparel Textiles
Thailand Garment Industry Market
Apparel Textiles
Functional Apparel Market
Apparel Textiles
Maternity Wear Market
Apparel Textiles
China Denim Jeans Market
Apparel Textiles
TIC for Apparel Market
Apparel Textiles
Women's Cheongsam Market
Apparel Textiles
Asia-Pacific Digital Clothing Market
Apparel Textiles
Smart Apparel Market
Apparel Textiles
Asia-Pacific Footwear Sole Material Market
Apparel Textiles
China Flame Retardant Apparel Market
Apparel Textiles
Middle East and Africa Textile Garment Market
Apparel Textiles
Smart Clothing Market
Apparel Textiles
Hunting Apparel Market