
 North America Garment Steamers Market | 2026-2036
North America Garment Steamers Market Size, Share, and Industry Trends Forecast 2026-2036
North America Garment Steamers Market Insights
Online retail is fragmenting as a primary sales channel for garment steamers, with direct-to-consumer platforms and marketplace aggregators pulling volume from traditional big-box partnerships. Conair Corporation leverages its established brand presence to sustain shelf space across multi-channel environments. Midea Group Co., Ltd anchors production scale through in-house manufacturing of heating elements and boiler assemblies. Panasonic Holdings Corporation differentiates via vertical control over semiconductor-grade temperature sensors.
North America garment steamers are electromechanical appliances that convert water to pressurized steam through resistive heating elements rated typically between 1000 and 1800 watts, delivering de-wrinkling and sanitizing functions for textiles without direct fabric contact. Handheld steamers occupy the highest volume tier among product types due to apartment-dwelling demographics and space-constrained storage norms. Commercial steamers command concentrated margin pools within the end-user dimension, as professional cleaners and hotel housekeeping departments prioritize duty-cycle durability over unit price.
UL safety certification and FCC electromagnetic compliance govern product access across the United States, while Health Canada and CSA Group standards regulate Canadian market entry. These frameworks elevate design costs for new entrants but reinforce incumbent advantages for firms with established testing protocols. Stakeholders must monitor evolving state-level appliance efficiency mandates and hospitality sustainability procurement criteria to anticipate specification shifts.
Market Dynamics
EPA energy-efficiency guidelines and state-level appliance standards are compressing wattage tolerances for resistive heating elements, forcing manufacturers to redesign boiler assemblies without sacrificing steam pressure output. This regulatory compression intersects with boutique hotel procurement cycles that now embed sustainability criteria into commercial-grade equipment tenders.
Growth Catalysts
- EPA Energy-Efficiency Guidelines:Federal appliance standards are mandating lower-wattage heating element designs that reduce operational costs for hospitality end-users across the United States.
- Boutique Hotel Procurement:Independent hospitality chains in the United States and Canada are expanding commercial-grade steaming equipment orders to meet guest-facing garment care expectations.
- Urban Residential Density:Apartment-dwelling demographics in the United States Northeast corridor are driving handheld steamer volume through space-constrained storage requirements.
Market Restraints
- Copper and Nickel Input Volatility:Resistive heating element manufacturing depends on commodity metal prices that fluctuate with global mining output, compressing margin predictability for boiler assembly producers.
- Testing Protocol Concentration:UL safety certification and FCC electromagnetic compliance requirements elevate fixed costs for new entrants, reinforcing incumbent advantages among established testing protocol holders.
- Substitute Garment Care Methods:Traditional ironing equipment and professional dry-cleaning services retain cost advantages for consumers with low utilization frequency.
Strategic Opportunities
- Canadian Hospitality Expansion:Underpenetrated resort markets in British Columbia and Quebec present white space for commercial-grade steaming equipment deployment.
- Smart Home Integration:Convergence of semiconductor-grade temperature sensors with connected appliance platforms enables predictive maintenance and usage analytics for premium residential segments.
- Direct-to-Consumer Platforms:Marketplace aggregators and brand-owned e-commerce channels are displacing traditional big-box partnerships, reducing slotting fee burdens and capturing margin.
Industry Challenges
- Multi-Jurisdictional Certification Timelines:Simultaneous UL, FCC, Health Canada, and CSA Group approval processes extend product launch windows by 8-14 months for cross-border distribution.
- Legacy Inventory Integration:Commercial housekeeping departments require backward compatibility with existing steamer accessory ecosystems, limiting rapid specification upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Garment Steamers Market |
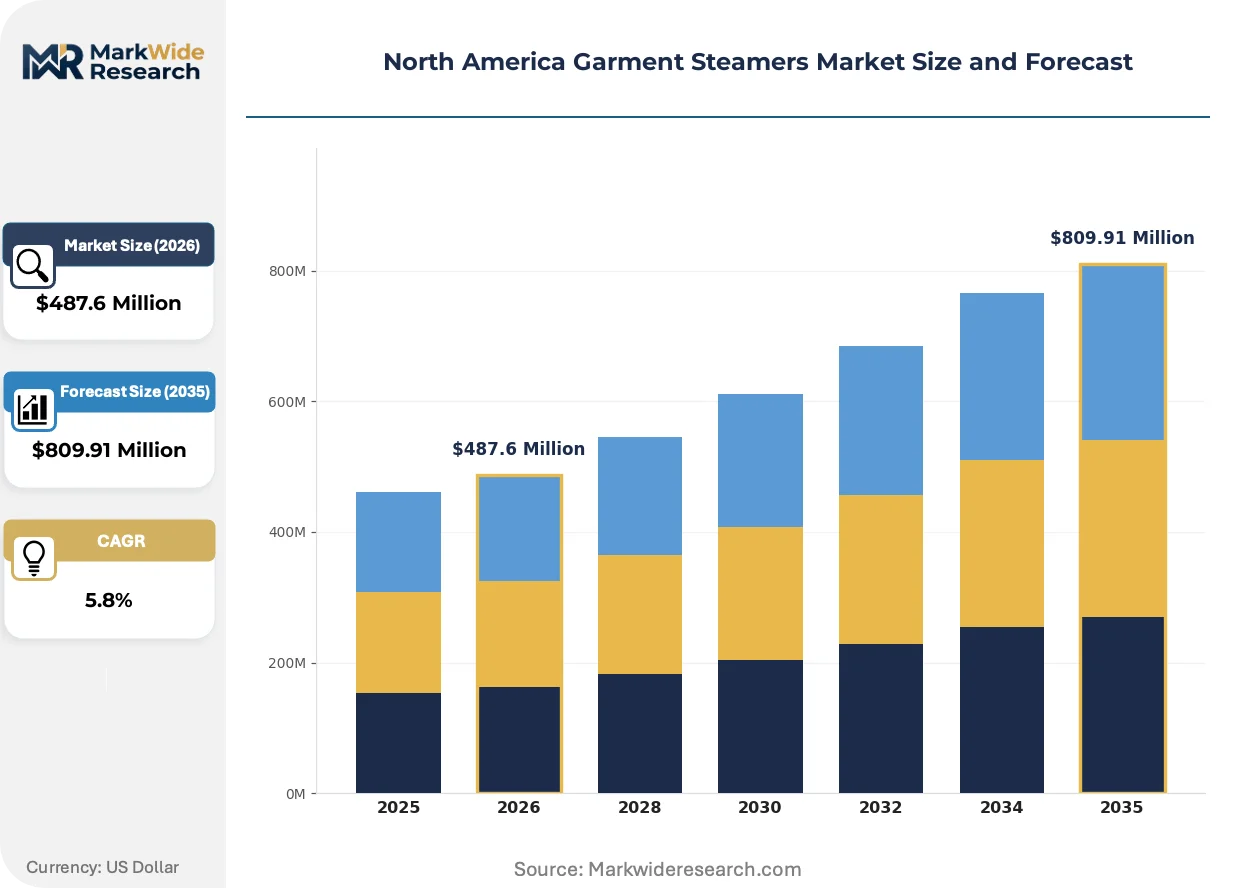
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $809.91 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Steamers, Standing Steamers, Travel Steamers, Commercial Steamers End User: Home Users, Professional Cleaners, Retail Stores, Hotels Power Rating: 500-1000 Watts, 1001-1500 Watts, 1501-2000 Watts, Above 2000 Watts Sales Channel: Online Retail, Offline Retail, Wholesale Distribution, Direct Sales |
| Companies Covered | Midea Group Co., Ltd, Conair Corporation, Haier Smart Home Co., Ltd, Rowenta, Jiffy Steamer Company LLC, Koninklijke Philips N.V., Panasonic Holdings Corporation, AB Electrolux, Groupe SEB, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Garment Steamers Market Trends and Innovations
Garment steamer engineering is migrating toward precision thermal management systems that replace analog thermostats with digital feedback loops. This shift is compressing the performance gap between handheld and commercial units while opening new specification tiers.
Resistive heating element technology is migrating from standardized nichrome wire configurations to composite alloy formulations with faster thermal response curves. Boutique hotel engineering departments are piloting these elements in 24-hour housekeeping cycles. The structural consequence is that duty-cycle durability is migrating from a premium-tier feature to a baseline expectation across mid-market commercial contracts.
State-level appliance efficiency mandates in California, New York, and Massachusetts are tightening standby power limits for plug-in garment care devices. These regulations are forcing boiler assembly redesigns that prioritize rapid heat-up over sustained temperature maintenance. Handheld steamer manufacturers serving the United States Northeast corridor are responding with segmented heating zones that activate only during active steaming intervals.
Buyer concentration among hospitality procurement consortia is consolidating vendor relationships into multi-year framework agreements with embedded sustainability scoring. Independent hotel operators are losing negotiating leverage against these pooled purchasing entities. This pattern is most visible in the United States, where third-party facility management companies now control specification decisions for approximately one-third of branded hotel properties.
North America Garment Steamers Market Segmentation
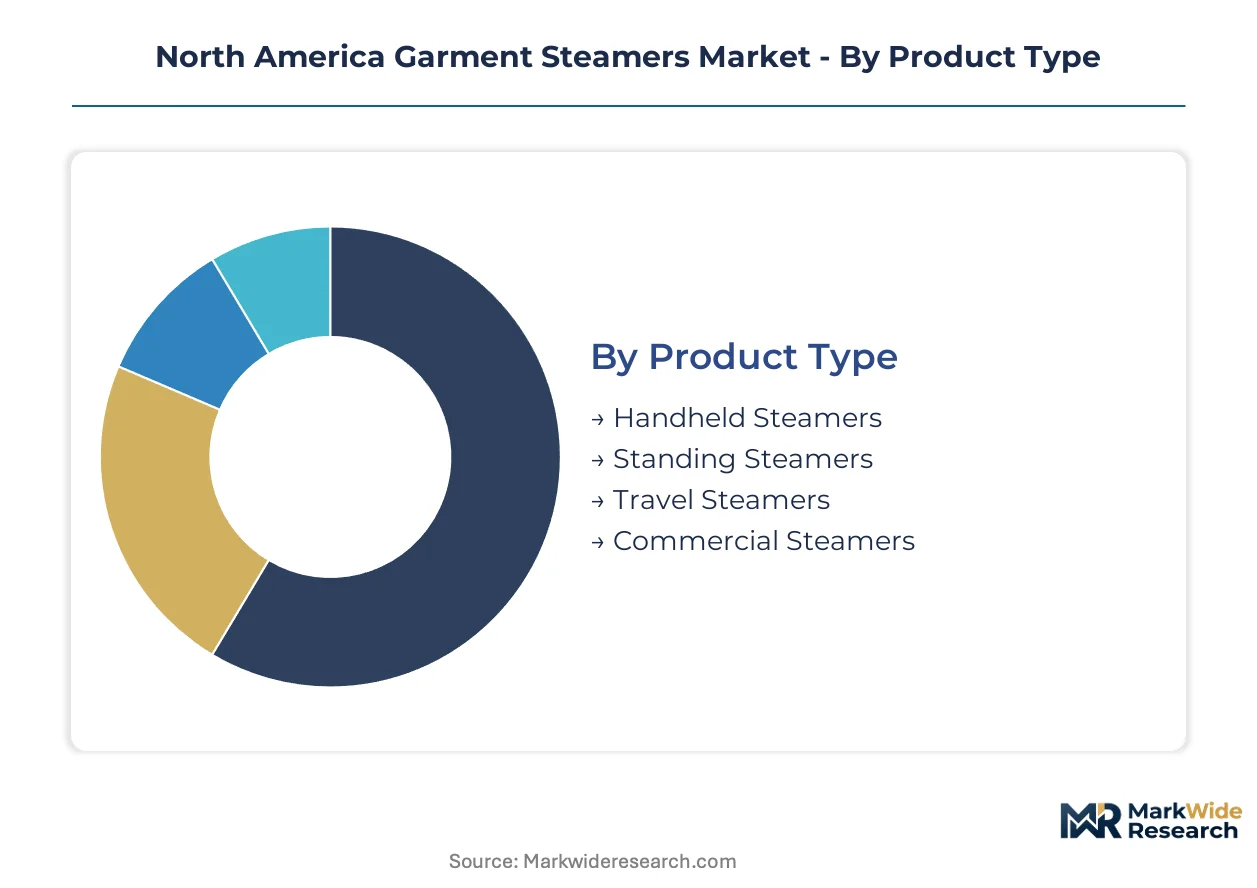
Product differentiation across North America garment steamers follows distinct usage patterns shaped by residential density, commercial duty cycles, and procurement channel evolution. Segment boundaries are hardening as EPA efficiency mandates and hospitality sustainability criteria force specification divergence between consumer and commercial tiers.
Product Type:
Cost tier stratification separates portable residential units from capital-intensive commercial systems with divergent margin structures and replacement cycles.
- Handheld Steamers:Compact electromechanical units with 1000-1800 watt resistive heating elements and sub-200ml water reservoirs. Apartment-dwelling demographics in the United States Northeast corridor drive volume through space-constrained storage requirements and intermittent usage patterns.
- Commercial Steamers:High-duty-cycle equipment with stainless steel boiler assemblies and continuous-fill water systems rated for 8-24 hour operation intervals. Boutique hotel procurement consortia across the United States and Canada specify these units for guest-facing garment care services.
- Standing Steamers:Vertical-format residential appliances with telescoping poles and integrated hanger systems. Mid-market households in suburban Canadian markets favor these for dedicated laundry room installation.
- Travel Steamers:Dual-voltage compact units with collapsible water chambers designed for international voltage compatibility. Leisure travel recovery patterns influence replacement demand timing.
Commercial Steamers holds installed capacity. Handheld Steamers is rotating up the share rankings.
End User:
Application context determines specification rigor, with hospitality and professional cleaning segments imposing durability standards that consumer tiers rarely require.
- Hotels:Housekeeping departments at branded properties and independent boutiques across the United States and Canada deploy commercial-grade steaming equipment for in-room garment care amenities. Third-party facility management companies now control specification decisions for approximately one-third of these properties.
- Professional Cleaners:Independent garment care services and franchise operations require equipment with rapid heat-up cycles and mineral-scale resistance for high-throughput environments.
- Home Users:Residential consumers prioritize storage footprint and countertop compatibility over duty-cycle specifications. California, New York, and Massachusetts state-level appliance efficiency mandates constrain standby power limits for this segment.
- Retail Stores:Apparel merchants utilize steaming equipment for floor-ready presentation of wrinkle-prone textiles. Seasonal hiring patterns create lumpy procurement cycles.
Hotels command specification authority. Professional Cleaners is expanding most quickly.
Power Rating:
Volume concentration clusters in mid-wattage bands where EPA guidelines and practical steam output requirements achieve regulatory compliance without performance sacrifice.
- 1001-1500 Watts:The dominant residential specification tier balancing heat-up speed against circuit capacity constraints in older United States apartment electrical infrastructure. Handheld and standing steamer formats concentrate here.
- 1501-2000 Watts:Commercial-grade equipment specifications for hotel housekeeping and professional cleaning operations requiring sustained steam output. EPA energy-efficiency guidelines are compressing design tolerances in this band.
- 500-1000 Watts:Entry-level handheld and travel steamer configurations prioritizing portability over de-wrinkling velocity. Canadian and United States border-state consumers show higher price sensitivity here.
- Above 2000 Watts:Specialized industrial applications and premium commercial installations with dedicated electrical circuits. Limited penetration outside institutional laundry facilities.
1001-1500 Watts holds installed capacity. 1501-2000 Watts is climbing the fastest.
Sales Channel:
Customer type migration from big-box retail toward direct digital engagement is restructuring margin capture and brand relationship economics.
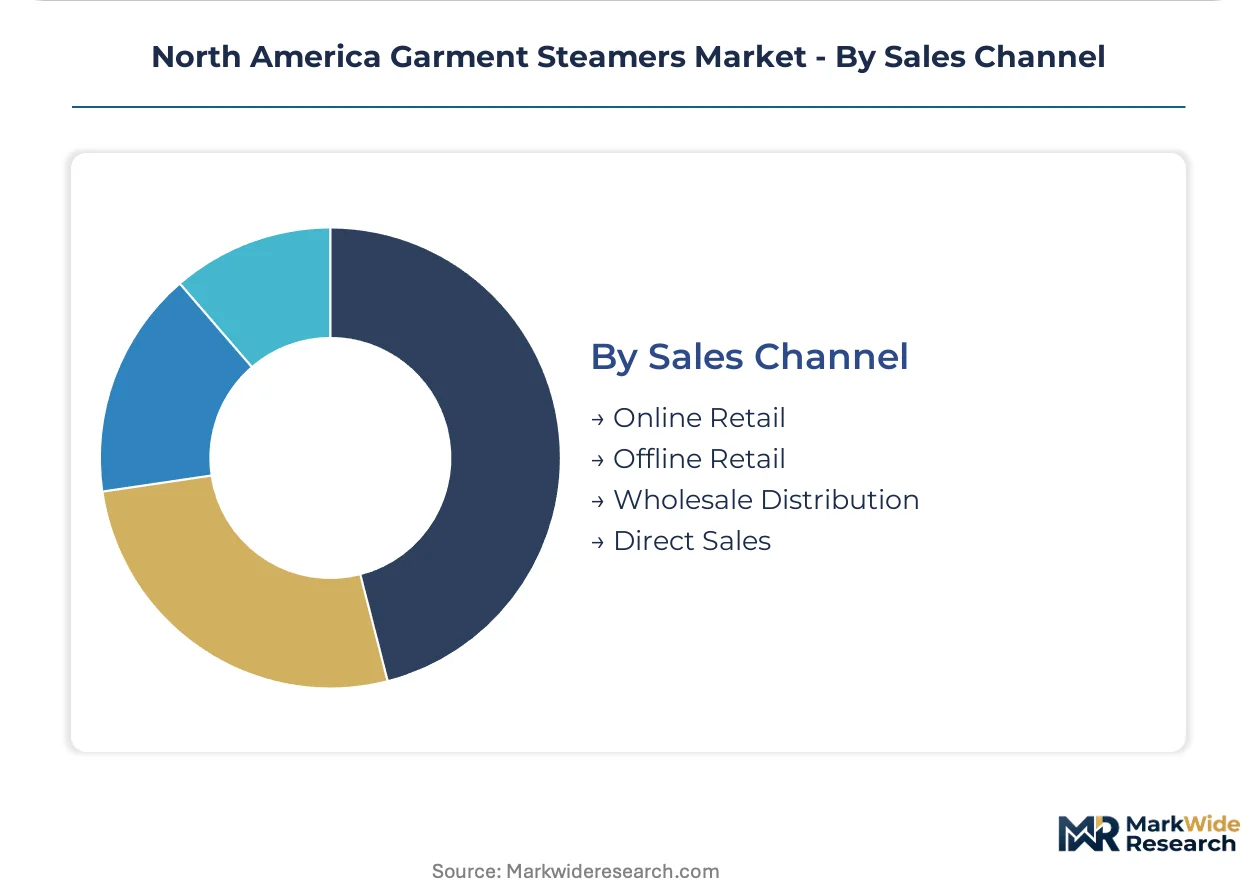
- Online Retail:Marketplace aggregators and brand-owned e-commerce platforms are displacing traditional big-box partnerships, reducing slotting fee burdens while enabling usage analytics collection for premium segments.
- Offline Retail:Multi-channel shelf space at mass merchants and specialty appliance retailers sustains brand visibility for consumer segments with tactile purchase preferences.
- Wholesale Distribution:Hospitality procurement consortia and facility management companies source commercial-grade equipment through specialized B2B distributors with embedded service networks.
- Direct Sales:Manufacturer field representatives engage hotel engineering departments and professional cleaning operations for specification-influencing technical demonstrations.
Offline Retail holds installed capacity. Online Retail is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian hospitality procurement commands premium pricing for commercial-grade steaming equipment, while Mexican manufacturing clusters absorb cost-sensitive handheld volume through maquiladora assembly networks. This asymmetry concentrates margin capture in northern markets and unit production in border-adjacent facilities.
United States
EPA energy-efficiency guidelines and state-level appliance standards in California, New York, and Massachusetts compress wattage tolerances for resistive heating elements. The FCC governs electromagnetic compliance for plug-in garment care devices. Boutique hotel procurement consortia in the Northeast corridor specify commercial-grade equipment for guest-facing amenities.
Canada
Health Canada and CSA Group standards regulate market entry for garment steamers, elevating design costs for cross-border distribution. Provincial efficiency mandates in British Columbia and Quebec align with federal sustainability procurement criteria. Underpenetrated resort markets in these provinces present deployment opportunities for commercial-grade steaming equipment.
Mexico
Maquiladora assembly networks in Nuevo León and Baja California produce cost-optimized handheld steamers for re-export to the United States. The country's national standards body certifies electrical safety for domestic appliance sales. Border-state manufacturing clusters leverage duty-advantaged logistics to supply price-sensitive consumer segments.
North America Garment Steamers Market Competitive Landscape
Scale-driven manufacturers and specialization-focused fabricators split the market along duty-cycle durability and price-band vectors. The structure tilts toward consolidated procurement relationships in commercial tiers and fragmented brand competition in residential handheld segments. Appliance conglomerates with captive heating-element production anchor one archetype; boutique engineering houses with hospitality service networks occupy another. Dominant competitive moves include backward integration into boiler assembly manufacturing and multi-year framework agreements with hospitality procurement consortia.
Within the scale-driven tier, Midea Group Co., Ltd and Haier Smart Home Co., Ltd represent Chinese appliance conglomerates with in-house production capabilities. Conair Corporation anchors the North American brand-architecture archetype through multi-channel shelf presence. Panasonic Holdings Corporation exemplifies the precision-component pathway with semiconductor-grade temperature sensor integration.
| Leading Market Players |
|---|
| Midea Group Co., Ltd |
| Conair Corporation |
| Haier Smart Home Co., Ltd |
| Rowenta |
| Jiffy Steamer Company LLC |
| Koninklijke Philips N.V. |
| Panasonic Holdings Corporation |
| AB Electrolux |
| Groupe SEB |
| Others |
Pricing and Supply Chain Analysis
Port of Long Beach freight corridors absorb fuel surcharge volatility that concentrates margin pressure on Mexican maquiladora producers while amplifying price differentiation between EPA-certified commercial tiers and uncertified economy imports. This logistics chokepoint funnels cost compression toward handheld steamer assemblers in Nuevo León and Baja California, forcing upstream boiler component suppliers to absorb tariff exposure or surrender shelf space.
Pricing Analysis
The customization-premium spread separates configured-to-order commercial steamers with CSA Group and UL safety certifications from standard handheld units sold through marketplace aggregators. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and after-sales service bundling, with boutique hotel procurement consortia least sensitive and border-state residential consumers most responsive to unit price. Cost compression in the economy tier intensifies because maquiladora assemblers face copper and nickel input volatility without contract hedging.
Supply Chain Analysis
Export-control regimes on semiconductor-grade temperature sensors limit flows from Japanese precision-component manufacturers to North American appliance assemblers, constraining smart home integration roadmaps. China, Mexico, and Vietnam anchor supply concentration for resistive heating elements, boiler assemblies, and plastic injection-molded housings. Distribution runs through hospitality procurement consortia for commercial tiers and direct-to-consumer platforms for residential segments, with single-source vulnerability in nichrome wire supply from Zhejiang Province producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North America garment steamers constitute a high-growth disruption as EPA energy-efficiency guidelines and state-level appliance standards in California, New York, and Massachusetts force boiler assembly redesigns that obsolete legacy inventory. This regulatory inflection compresses replacement cycles and privileges incumbents with established testing protocols.
For Market Incumbents: Harden certification护城河 through accelerated Health Canada and CSA Group approval pipelines that extend product launch windows for challengers. Deepen backward integration into composite alloy heating element production to offset copper and nickel commodity volatility, while embedding predictive maintenance software into premium residential tiers to capture smart home integration premiums.
For New Entrants and Emerging Players: Underpenetrated resort markets in British Columbia and Quebec represent the most penetrable entry point for commercial-grade steaming equipment, bypassing consolidated United States hospitality procurement consortia. Direct-to-consumer platforms enable bypass of slotting fee burdens at big-box retailers, with sustainability-scored product positioning aligning with Canadian federal procurement criteria.
For Investors and Strategic Acquirers: Boutique engineering houses with embedded hospitality service networks and captive boiler assembly manufacturing capabilities offer the strongest acquisition target archetype for long-term viability across a 5-10 year window. Monitor EPA standby power limit enforcement intensity in Massachusetts and New York as the signal indicating specification upgrade urgency and replacement demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heating Elements | Midea Group and Haier Smart Home anchor margin control through captive nichrome wire and composite alloy production. |
| Multi-Year Framework Agreements | Third-party facility management companies consolidate vendor relationships with embedded sustainability scoring for one-third of branded hotel properties. |
| Smart Home Platform Integration | Panasonic Holdings leverages semiconductor-grade temperature sensors for predictive maintenance and usage analytics capture. |
| Direct-to-Consumer Channel Expansion | Conair Corporation reduces slotting fee burdens while capturing margin through brand-owned e-commerce and marketplace aggregators. |
| Canadian Hospitality Market Entry | Underpenetrated resort markets in British Columbia and Quebec offer white space deployment for commercial-grade steaming equipment. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with hotel engineering directors, procurement leads at hospitality consortia, appliance retail category managers, and boiler assembly manufacturing engineers; and secondary validation through EPA appliance efficiency filings, Health Canada and CSA Group certification databases, customs records for copper and nickel imports, and SEC 10-K disclosures from listed appliance conglomerates. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions.
Forecast inputs included resistive heating element wattage compression trajectories under state-level mandates, boutique hotel expansion pipelines in the United States Northeast corridor and Canadian resort provinces, and online retail channel share migration patterns. Segmentation dimensions spanned product type, end user, power rating, and sales channel, with CAGRs derived from regression analysis against historical replacement cycles and regulatory compliance deadlines. Copper and nickel commodity price volatility curves and hospitality capital expenditure intentions shaped scenario weightings.
Macroeconomic conditions sit as an overlay; deviation in hospitality construction lending rates and cross-border tariff regimes would shift the trajectory. Forecasts reflect documented assumptions regarding EPA enforcement consistency and maquiladora labor cost stability. Material shifts in United States-Canada-Mexico trade agreement provisions or California standby power mandate acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel Textiles
Maternity Leggings Market
Apparel Textiles
North America Footwear Sole Material Market
Apparel Textiles
Bamboo Apparel Market
Apparel Textiles
Stockings Market
Apparel Textiles
Rolle Market
Apparel Textiles
OEM Clothing Manufacturer Service Market
Apparel Textiles
Smart Clothing Market
Apparel Textiles
Smart Apparel Market
Apparel Textiles
South America Lingerie Market
Apparel Textiles
Africa Textile Market
Apparel Textiles
Head Scarves Market
Apparel Textiles
Automotive Textiles Market
Apparel Textiles
Middle East and Africa Textile Garment Market
Apparel Textiles
Knitwear Market
Apparel Textiles
Cosplay Clothing Market
Apparel Textiles
Organic Baby Clothes Market