
 Global Socks Market | 2026-2036
Global Socks Market Size, Share, and Industry Trends Forecast 2026-2036
Global Socks Market Outlook
EU REACH chemical restrictions is rebalancing material sourcing requirements across the Global Socks Market, forcing reformulation of synthetic blends and dye processes. Nike Inc. leverages vertical integration in textile innovation to control fiber-to-finish quality. Adidas AG anchors its position through R&D intensity in moisture-wicking knit architectures. Hanesbrands Inc. sustains manufacturing scale across multi-channel distribution networks.
Socks are close-fitting knitted garments engineered from cotton, wool, nylon, or polyester blends, typically constructed with elasticized cuffs, reinforced heels, and seamless toes for friction reduction during prolonged wear; they function as moisture-management interfaces between foot and footwear in athletic, occupational, and casual contexts. Crew socks and ankle socks occupy the largest volume positions due to universal casual and athletic applicability, while no-show socks represent the fastest-expanding category as minimalist footwear trends reshape consumer preferences. Material segmentation shows cotton retaining dominant share in everyday basics, though polyester and wool blends command premium positioning in performance and thermal applications.
FDA textile contact standards, EU REACH substance restrictions, and China's GB national standards collectively govern fiber safety labeling, chemical residue limits, and product claims across major supply corridors. These frameworks elevate compliance costs for synthetic dye houses but create market access advantages for certified organic and recycled-material suppliers. Stakeholders must monitor evolving chemical restriction schedules and certification reciprocity agreements to anticipate sourcing disruptions and premium positioning opportunities.
Market Dynamics
EU REACH chemical restrictions are forcing fiber-to-finish reformulation across sock manufacturing, eliminating legacy dye processes and certifying organic cotton and recycled polyester as baseline compliance inputs rather than premium positioning tools.
Growth Catalysts
- Performance Apparel Demand:Athletic wear brands are expanding sock assortments as sportswear consumption accelerates in China and domestic supply chains mature to capture local demand.
- REACH Compliance Migration:Certified organic cotton and recycled polyester inputs are gaining mandatory status under tightening chemical residue limits across European supply corridors.
- Moisture-Wicking Knit Architectures:R&D intensity in technical yarn engineering is elevating functional specifications for athletic and occupational end-uses.
Market Restraints
- Petrochemical Input Volatility:Polyester and nylon staple fiber prices fluctuate with crude oil derivatives, compressing margin buffers for synthetic-blend manufacturers.
- Dye House Concentration:Compliance-capable synthetic dyeing capacity clusters in Zhejiang and Guangdong provinces, creating single-point vulnerability for Western brands.
- Natural Fiber Substitution Ceiling:Wool and cotton blends face performance limitations in extreme moisture-management applications where technical synthetics retain functional superiority.
Strategic Opportunities
- India Domestic Market Penetration:PLI scheme incentives for technical textiles and rising organized retail footprint create white space for branded performance sock lines.
- Direct-to-Consumer Channel Expansion:Subscription-based replenishment models bypass wholesale margin compression and capture recurring revenue from athletic and diabetic sock segments.
- EU Green Deal Alignment:CSRD reporting requirements and circular economy action plans reward transparent recycled-content supply chains with preferential retail placement.
Industry Challenges
- Certification Timeline Compression:OEKO-TEX and GOTS multi-stage auditing creates six-to-nine month qualification delays for new supplier onboarding.
- Seamless Toe Integration Complexity:Technical knit engineering talent scarcity constrains capacity expansion for friction-reduction architectures in performance lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Socks Market |
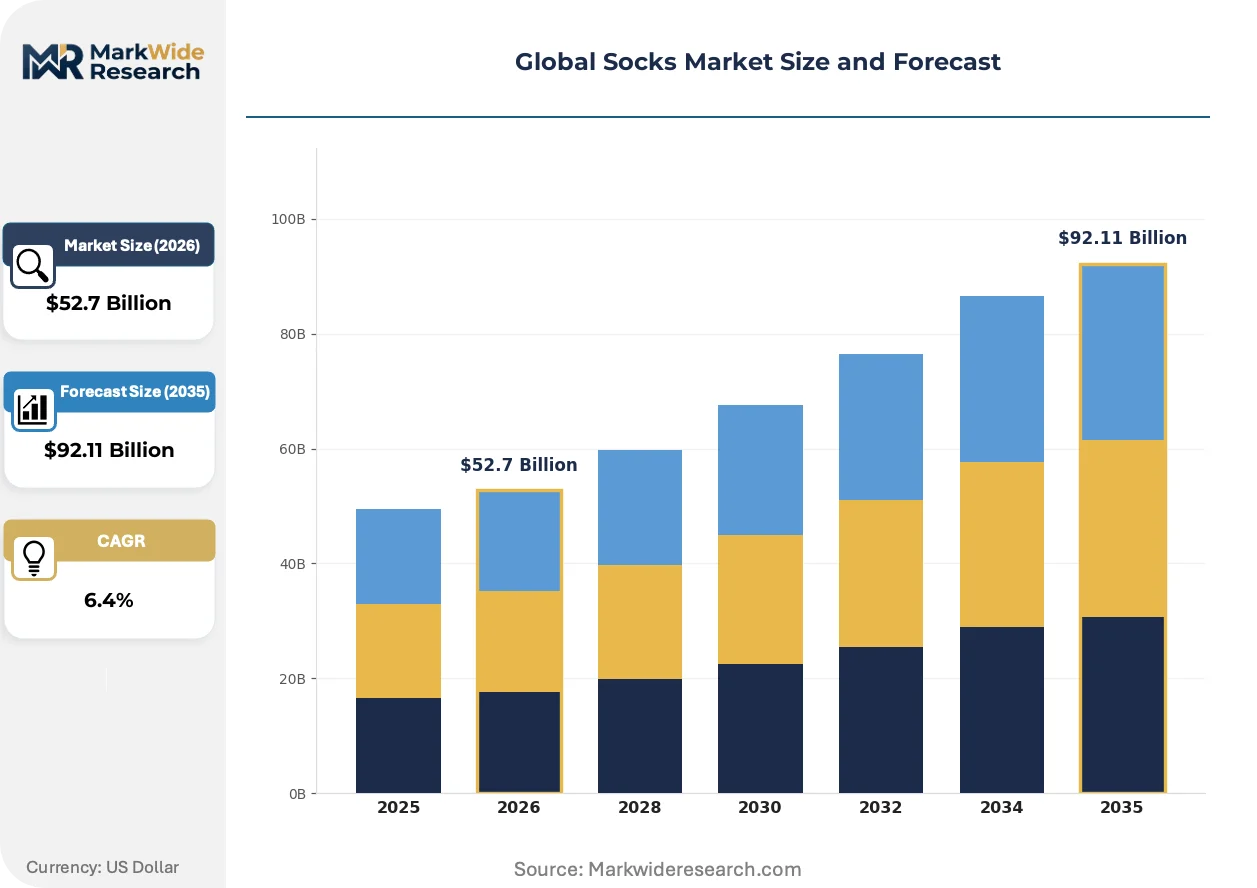
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $92.11 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ankle Socks, Crew Socks, Knee-high Socks, No-show Socks Material: Cotton, Wool, Nylon, Polyester End User: Men, Women, Children, Unisex Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Department Stores |
| Companies Covered | Nike Inc., Adidas AG, Hanesbrands Inc., Puma SE, Gildan Activewear Inc., Under Armour Inc., Renfro Corporation, ASICS Corporation, Gold Toe-Moretz LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Socks Market Strategic Shifts
Material science convergence with digital manufacturing is collapsing traditional lead times and enabling mass-customization at scale, while regulatory chemical phase-outs are rewriting baseline input specifications across all price tiers.
3D-knit seamless construction is rewriting how athletic socks integrate zoned compression and ventilation channels without post-knit assembly. Marathon and trail-running communities are adopting these architectures fastest, demanding anatomical left-right differentiation. The technology is compressing SKU proliferation costs and enabling small-batch colorway experimentation.
EU REACH substance restriction schedules are eliminating azo dyes and formaldehyde-based finishing agents from European-bound production lines. Dye houses in Portugal and Turkey are capturing reformulation service contracts as Asian suppliers face compliance recertification backlogs. Organic cotton and dope-dyed recycled polyester are becoming default inputs for brands serving EU retail channels.
Minimalist footwear adoption is fragmenting casual sock demand into ultra-low-profile no-show and hidden-liner categories. Specialty running retailers and direct brands are displacing department store hosiery sections as primary purchase points for technical casual socks. This rotation is most visible in urban coastal markets across the United States and Western Europe where sneaker culture dominates casual dress norms.
Global Socks Market Segmentation
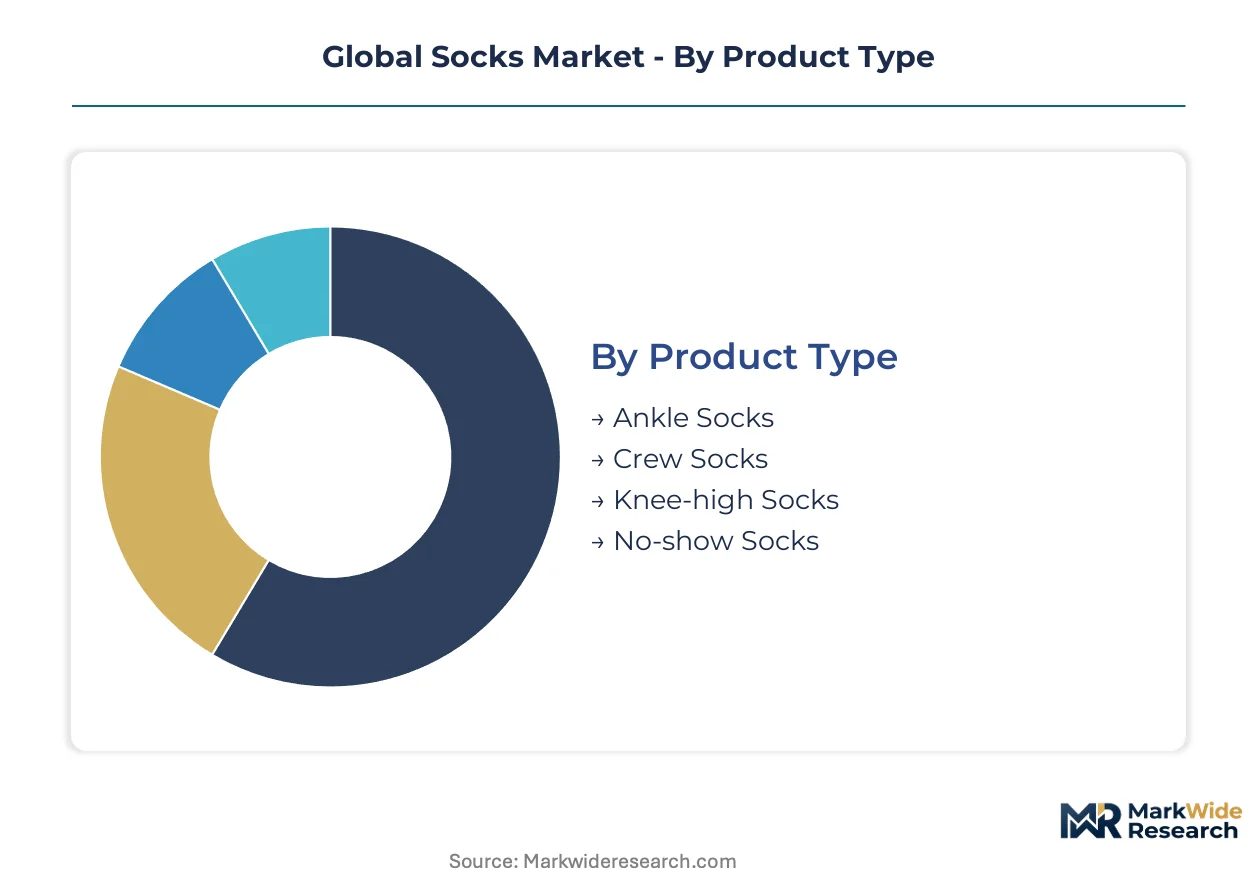
Sock manufacturers configure production lines around length specifications and fiber inputs that dictate knitting machinery, dye chemistry, and finishing protocols. Each segmentation dimension carries distinct margin profiles and compliance obligations that reshape supplier selection and channel strategy.
Product Type:
Knitting equipment specialization clusters around length categories, with seamless toe machines and zoned compression capabilities concentrating in crew and ankle formats.
- Crew Socks:Mid-calf construction with reinforced heels and cushioned soles dominates athletic and occupational procurement. Demand concentrates in United States team sports and German industrial safety channels where moisture-wicking specifications are mandatory.
- Ankle Socks:Quarter-length cut with elasticized arch support serves universal casual and light athletic use. Volume concentrates in Chinese domestic retail and Indian urban markets as sneaker penetration deepens.
- No-show Socks:Ultra-low-profile hidden liners with silicone heel grips.
- Knee-high Socks:Extended shaft construction for compression therapy and formal dress applications.
Crew socks absorb the bulk of installed capacity; no-show socks are expanding most quickly.
Material:
Fiber selection determines dye house partnerships, REACH compliance pathways, and end-use performance ceilings across price tiers.
- Cotton:Staple fiber from conventional or certified organic sources forms the baseline for everyday basics. Sourcing concentrates in India and Turkey as EU-bound production shifts from conventional to GOTS-certified spinning capacity.
- Polyester:Petrochemical-derived filament and staple engineered for moisture transport and durability. Demand clusters in Chinese athletic manufacturing and Vietnamese export processing zones serving performance apparel brands.
- Wool:Merino and synthetic-wool blends for thermal regulation.
- Nylon:Polyamide staple for reinforcement and sheer hosiery applications.
Cotton dominates volume throughput; polyester is climbing the fastest on athletic demand and recycled-content certification.
End User:
Gendered sizing grids and anatomical engineering requirements split design teams and pattern libraries across distinct customer cohorts.
- Men:Larger foot form factors with wider heel cups and extended cuff heights. Volume concentrates in United States big-box retail and German mail-order channels where multipack economics drive replenishment cycles.
- Women:Narrower lasts with fashion-forward colorway sensitivity and seasonal pattern turnover. Demand clusters in Japanese department stores and French specialty retailers where coordination with footwear trends dictates assortment depth.
- Children:Rapid size turnover with safety-focused fiber specifications.
- Unisex:Simplified sizing with neutral aesthetics for bulk institutional procurement.
Men's sizing absorbs the bulk of installed capacity; women's technical casual lines are gaining share fastest.
Distribution Channel:
Channel selection determines margin structure, return rates, and inventory velocity with distinct operational footprints for digital versus physical fulfillment.
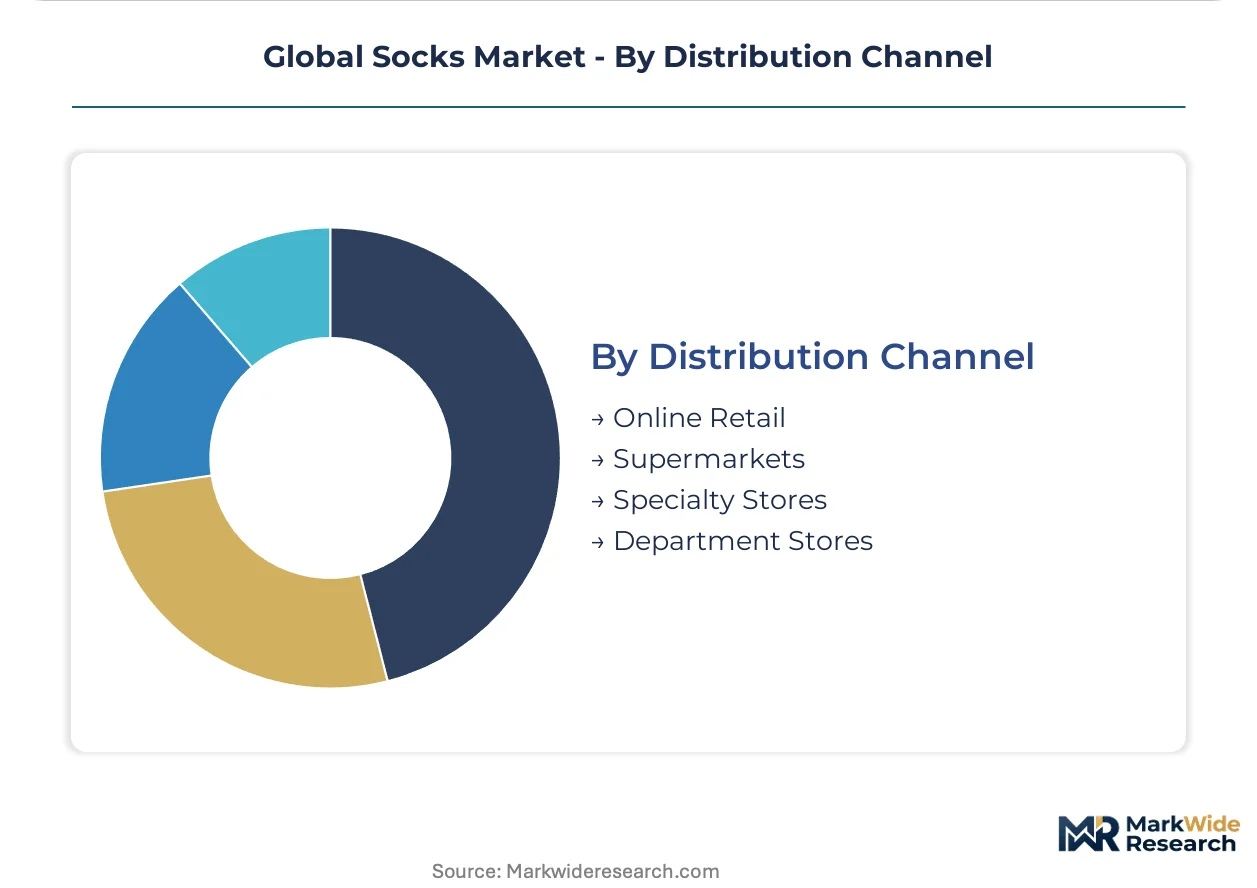
- Online Retail:Direct-to-consumer and marketplace platforms with subscription replenishment models. Volume concentrates in United States coastal metros and United Kingdom urban centers where same-day delivery infrastructure supports impulse replenishment.
- Specialty Stores:Running, outdoor, and diabetic-focused retailers with trained fitting staff. Demand clusters in Australian coastal cities and Swiss alpine towns where technical specification conversations drive premium conversion.
- Supermarkets:High-velocity multipack basics with compressed margins.
- Department Stores:Declining footprint for hosiery sections amid apparel consolidation.
Online retail absorbs the bulk of growth investment; specialty stores are expanding most quickly in performance segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Zhejiang and Guangdong provinces concentrate dye house capacity serving European-bound production, while India's PLI scheme for technical textiles redirects investment toward domestic spinning clusters.
United States
Team sports procurement and big-box retail multipack economics drive crew sock volume. FDA textile contact standards govern fiber safety labeling for imports. North Carolina's hosiery belt around Burlington and Hickory maintains knitting machinery density for athletic and diabetic sock lines.
China
Domestic sportswear consumption and sneaker culture penetration accelerate ankle and no-show demand. GB national standards on fiber safety and chemical residue limits tighten compliance timelines. Zhejiang province dye houses in Shaoxing and Jiaxing face REACH recertification backlogs as azo dye phase-outs take effect.
Germany
Industrial safety channels mandate moisture-wicking specifications for occupational crew socks. ECHA REACH substance restrictions eliminate formaldehyde-based finishing agents from European-bound supply chains. North Rhine-Westphalia's technical textile R&D clusters around Mönchengladbach advance seamless toe integration for performance lines.
India
Organized retail footprint expansion and rising sneaker penetration create white space for branded performance lines. PLI scheme incentives for technical textiles attract spinning capacity investment. Tamil Nadu's GOTS-certified organic cotton spinning around Tiruppur shifts toward EU-compliant export production.
Turkey
Proximity to European retail channels and reformulation service capabilities capture dye house migration from Asia. EU Green Deal circular economy action plans reward transparent recycled-content supply chains. Istanbul and Bursa industrial zones consolidate GOTS-certified finishing capacity for organic cotton sock exports.
Global Socks Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Athletic wear conglomerates leverage textile innovation scale against hosiery specialists emphasizing diabetic and compression niches. Three archetypes dominate: vertically integrated sportswear giants controlling fiber-to-finish quality, regional knitting specialists serving private-label contracts, and direct-to-consumer challengers exploiting subscription replenishment models. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with dye house compliance certification emerging as a bottleneck resource.
Within the sportswear conglomerate tier, Nike Inc. and Adidas AG exemplify backward integration into textile innovation, while Hanesbrands Inc. occupies a position emphasizing manufacturing scale across multi-channel distribution networks. These three entities represent divergent strategic postures: captive fiber development, R&D intensity in knit architectures, and operational scale efficiency respectively.
| Leading Market Players |
|---|
| Nike Inc. |
| Adidas AG |
| Hanesbrands Inc. |
| Puma SE |
| Gildan Activewear Inc. |
| Under Armour Inc. |
| Renfro Corporation |
| ASICS Corporation |
| Gold Toe-Moretz LLC |
| Others |
Value Chain & Pricing Dynamics
EU REACH chemical restrictions gate both qualified supply access and premium-tier pricing power, as dye house recertification backlogs in Zhejiang province force brands toward compliant Portuguese and Turkish alternatives that command margin premiums. This regulatory filter reshapes procurement economics across all volume tiers.
Pricing Analysis
Lead-time compression commands measurable premiums in athletic sock procurement, with 3D-knit seamless construction lines extracting price advantages over conventional post-knit assembly. Pricing stratifies across GOTS-certified organic inputs, REACH-compliant synthetic blends, and conventional undifferentiated basics. Cost compression in economy multipacks is intensifying as polyester staple prices fluctuate with crude derivatives. Mass-market retailers exhibit acute price sensitivity, while specialty running retailers absorb premiums for anatomical left-right differentiation and zoned compression architectures.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Hamburg anchor European replenishment, with hub-and-spoke patterns extending to specialty running retailers and direct-to-consumer fulfillment nodes. Manufacturing concentrates in China, Vietnam, and Turkey, with spinning capacity drawing from Indian GOTS-certified cotton clusters and Chinese petrochemical filament plants. Single-source vulnerability concentrates in Zhejiang dye houses facing azo dye phase-outs. Distribution runs through brand-owned direct channels, wholesale sporting goods networks, and subscription-based replenishment platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around compliance-capable supply chains, with REACH recertification timelines forcing sub-scale dye houses and undifferentiated private-label knitters toward exit or acquisition.
For Market Incumbents: Extend backward integration into GOTS-certified spinning capacity in Tamil Nadu and Bursa to secure fiber-to-finish traceability for EU retail placement. Lock in reformulation service contracts with Portuguese dye houses before Asian competitors clear compliance backlogs. This defends margin position against direct-to-consumer challengers exploiting subscription replenishment economics. For New Entrants and Emerging Players: EU Green Deal circular economy action plans in Europe open a window for transparent recycled-content supply chains to capture preferential retail placement. Target India's organized retail expansion in Mumbai and Bangalore for branded performance lines. Enter through diabetic and compression niches where trained fitting staff requirements create incumbent blind spots. For Investors and Strategic Acquirers: Dye house compliance certification bottlenecks are the leading indicator that technical knit engineering talent scarcity will constrain capacity expansion for seamless toe architectures. The 5-10 year viability window favors acquisition of mid-scale GOTS-certified finishers with established EU brand relationships. Watch for OEKO-TEX multi-stage auditing delays as the signal for supply-constrained pricing power shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Spinning | GOTS-certified organic cotton capacity in Tiruppur secures EU market access under tightening chemical residue limits. |
| Direct-to-Consumer Channel Launch | Subscription replenishment models bypass wholesale margin compression in diabetic and athletic sock segments. |
| 3D-Knit Seamless Capacity Expansion | Zoned compression and ventilation architectures capture marathon and trail-running community demand fastest. |
| Reformulation Service Partnerships | Turkish and Portuguese dye houses capture migration from Asian suppliers facing REACH recertification backlogs. |
| Recycled-Content Supply Chain Certification | CSRD reporting requirements reward transparent recycled polyester inputs with preferential retail placement. |
Study Parameters
Document review covered customs and trade databases, SEC 10-K filings, and OEKO-TEX certification registries, complemented by interviews with supply chain directors at athletic wear brands, procurement leads at European retailers, technical textile R&D heads, and dye house compliance officers. Secondary validation drew from EU ECHA substance restriction schedules, China GB national standards documentation, and India PLI scheme technical textile incentive circulars. Bottom-up capacity modeling triangulated against top-down consumption estimates across the analysis window.
Segment-level value and volume trajectories emerged from disaggregated modeling across product type, material composition, end-user demographic, and distribution channel dimensions. CAGRs were derived from fitted growth curves anchored to observed fiber input demand and channel shift patterns. Key inputs included polyester staple price indices, GOTS-certified cotton spinning capacity expansion timelines, and REACH compliance recertification completion rates.
The model assumes a particular technology adoption path for 3D-knit seamless construction; alternative pathways for conventional post-knit assembly retention would alter the outlook for SKU proliferation costs and small-batch experimentation economics. Forecasts reflect documented assumptions regarding dye house concentration and certification timeline compression. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel Textiles
Dye Sublimated Apparel Market
Apparel Textiles
Organic Baby Clothes Market
Apparel Textiles
China Denim Jeans Market
Apparel Textiles
Global Maternity Innerwear Market
Apparel Textiles
North America Footwear Sole Material Market
Apparel Textiles
OEM Clothing Manufacturer Service Market
Apparel Textiles
Down Jacket Market
Apparel Textiles
Embroidery Market
Apparel Textiles
Rain Apparel Market
Apparel Textiles
Cosplay Clothing Market
Apparel Textiles
Equestrian Apparel Market
Apparel Textiles
Uniform Market
Apparel Textiles
Braille Clothing Tags Market
Apparel Textiles
Middle East and Africa Textile Garment Market
Apparel Textiles
Hunting Apparel Market
Apparel Textiles
North America Textile Garment Market