
 Blank Apparel Market | 2026-2036
Blank Apparel Market Size, Share, and Industry Trends Forecast 2026-2036
Blank Apparel Market Analytics
Bangladesh's export processing zones is narrowing the lead time gap for bulk knit orders. Next Level Apparel leverages its Los Angeles-based vertical manufacturing to sustain rapid replenishment cycles. Royal Apparel anchors its position through organic cotton specialization and domestic cut-and-sew operations.
Blank apparel denotes undecorated garments—typically 100% cotton or cotton-poly blends between 150-200 GSM—produced for downstream customization via screen printing, embroidery, or heat transfer. These items serve as the substrate for branded merchandise, corporate uniforms, and promotional campaigns. T-shirts and hoodies dominate volume, with cotton blends capturing the largest margin pool due to their balance of printability and cost. Bamboo fibers represent the fastest-growing material segment as sustainability requirements tighten across European procurement channels.
FDA textile labeling rules, EPA discharge standards for dye houses, and REACH chemical restrictions in Europe collectively elevate compliance costs for offshore suppliers. California's Proposition 65 enforcement adds state-level exposure for brands distributing into the US West Coast. Stakeholders must monitor how carbon border adjustments and extended producer responsibility schemes redirect sourcing decisions before committing to long-term supplier contracts.
Market Dynamics
E-commerce platforms are compressing order minimums and accelerating replenishment cycles, forcing blank apparel suppliers to reconfigure inventory positioning around screen printing shops and custom decoration houses that now expect 48-72 hour fulfillment.
Growth Catalysts
- REACH chemical transparency mandates:European procurement channels now require full material disclosure, creating competitive separation for suppliers with certified supply chains and accelerating adoption of organic and recycled fiber programs.
- Cut-and-sew automation:Bangladesh's garment manufacturing zones are deploying automated spreading and cutting systems that reduce bulk knit order lead times from 90 days to 45 days.
- Heat transfer vinyl compatibility:Polyester-cotton blends optimized for dye-sublimation and HTV decoration are capturing volume from traditional 100% cotton as decoration shops diversify their equipment footprints.
Market Restraints
- Cotton price volatility:Weather-driven supply shocks in Texas and Maharashtra create margin compression for undifferentiated commodity knits without forward-contract hedging programs.
- Single-geo dye house concentration:Pakistan's Punjab province hosts 60% of South Asia's reactive dyeing capacity for cotton fleece, exposing buyers to energy rationing and effluent enforcement disruptions.
- Water-based ink curing limitations:Screen printers face throughput constraints on dark garments compared to plastisol systems, restricting migration to lower-VOC formulations despite EPA discharge standards.
Strategic Opportunities
- Direct-to-garment readiness:Ring-spun cotton jersey engineered for DTG pretreatment compatibility commands 15-20% premiums as online customizers bypass screen setup costs for short runs.
- Bamboo fiber certification pipelines:OEKO-TEX and GOTS-certified bamboo viscose programs unlock access to Scandinavian corporate uniform tenders with mandated renewable content floors.
- Micro-fulfillment partnerships:Blank suppliers are placing satellite inventory within Amazon's MFN network and Shopify Fulfillment Network nodes to capture same-day decoration demand in Texas, Ohio, and Pennsylvania.
Industry Challenges
- Color matching across dye lots:Screen printing shops require Pantone-certified consistency for corporate reorders, yet offshore suppliers struggle with metamerism control under varying water chemistries.
- California Proposition 65 defense costs:Brands distributing into Los Angeles and San Francisco face private enforcement actions over phthalate content in plastisol-printed garments, requiring legal reserves and reformulation verification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blank Apparel Market |
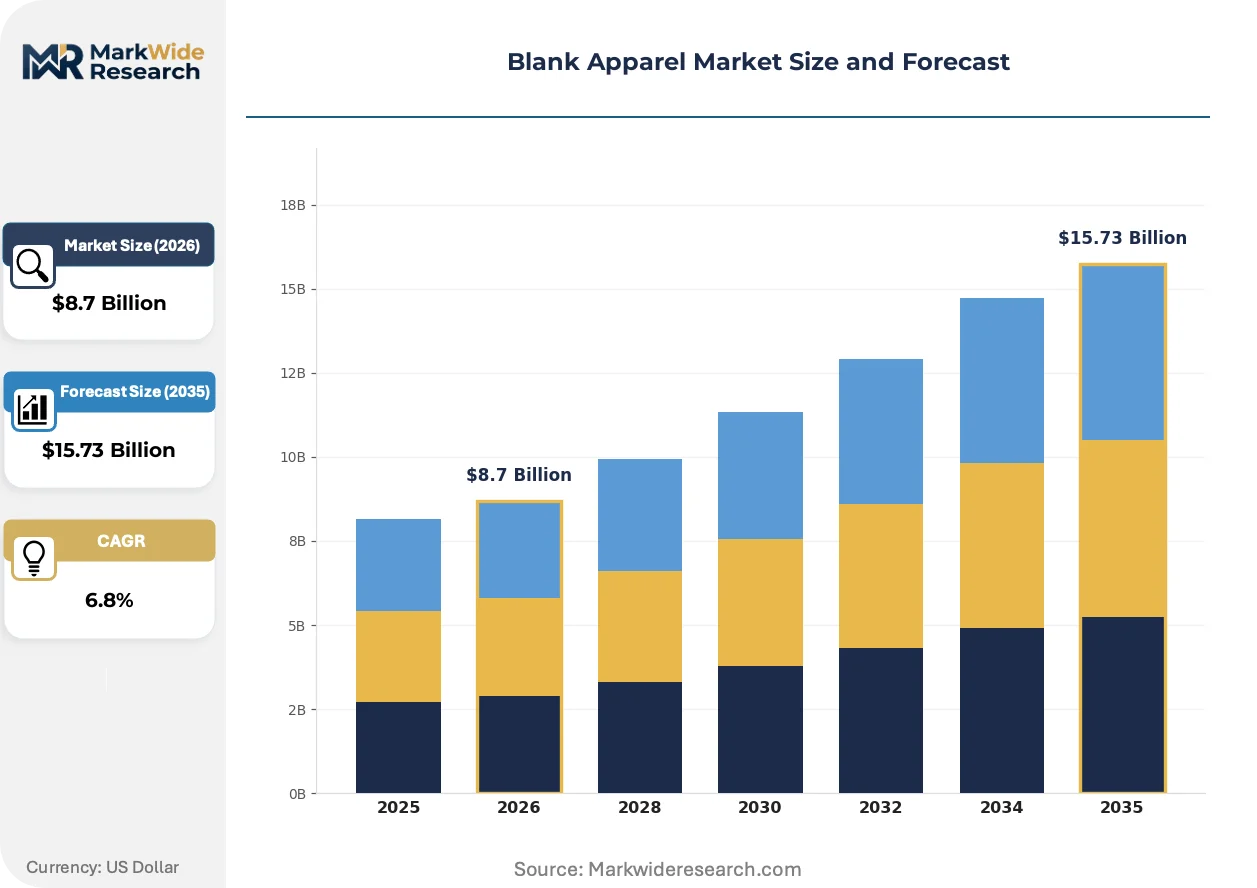
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: T-Shirts, Hoodies, Sweatshirts, Caps Material: Cotton, Polyester, Blends, Bamboo Distribution Channel: Online Retail, Wholesale, Direct Sales, Resellers End User: Retailers, Print Shops, Promotional Brands, Manufacturers |
| Companies Covered | Next Level Apparel, Zega Apparel, Los Angeles Apparel, YC Apparels, Hoodie Manufacturer, Royal Apparel, Lefty Production Co., Affix Apparel, Rays Creations, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blank Apparel Market Evolving Landscape
Digital decoration technologies and fiber chemistry advances are converging to redefine what constitutes a "print-ready" substrate, shifting supplier R&D investments from basic weight and shrinkage control to surface energy optimization and pretreatment compatibility.
Recycled cotton-mechanical polyester blends are hybridizing the performance characteristics of synthetic and natural fibers. Screen printing shops in Texas and North Carolina are trialing these fabrics for athletic and outdoor applications where moisture management conflicts with sustainability commitments. The hybridizing effect allows suppliers to maintain single-SKU inventory positions while serving previously incompatible end-use requirements.
EU Green Deal carbon border adjustment mechanisms are triggering supply chain reconfigurations before full implementation. Bangladeshi and Vietnamese exporters are accelerating renewable energy certificates and Scope 3 accounting to preserve access to German and Dutch buying offices. Medium-weight fleece and French terry categories face the steepest compliance cost escalations due to energy-intensive knitting and finishing stages.
Corporate buyers are consolidating vendor lists around suppliers offering decoration-as-a-service rather than pure wholesale blanks. Marketing services companies and promotional distributors in the US Midwest are outsourcing inventory ownership to vertically integrated providers who manage both substrate supply and applied decoration. This behavioral shift concentrates volume with Los Angeles-based and Central American suppliers capable of 72-hour decorated delivery to Chicago, Atlanta, and Dallas distribution points.
Blank Apparel Market Segmentation
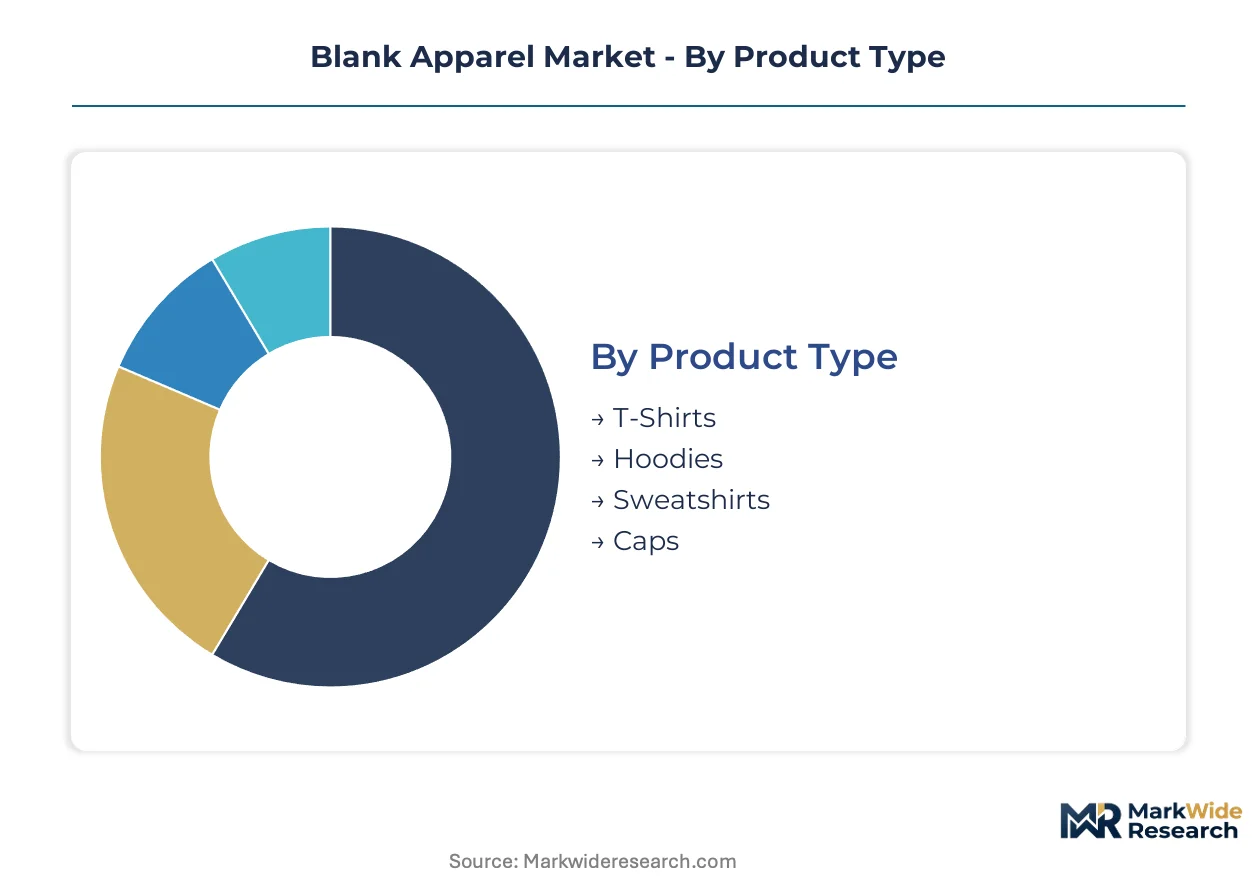
Blank apparel suppliers configure their service models around how intensively customers require technical support and replenishment responsiveness. Segmentation reveals where margin pools concentrate and which combinations of product, material, and channel capture the highest lifetime value from decoration shops and brand owners.
Product Type:
After-sales intensity varies sharply across garment categories, with bulk replenishment programs and color consistency guarantees driving supplier resource allocation.
- T-Shirts:Ring-spun cotton jersey between 150-180 GSM dominates procurement volumes from screen printing shops. Bangladesh's export processing zones and Los Angeles-based vertical manufacturers compete on 48-hour replenishment cycles for white and black base stocks.
- Hoodies:Cotton-poly fleece at 280-320 GSM requires precise shrinkage control and surface preparation for plastisol and water-based inks. European promotional brands prioritize OEKO-TEX-certified suppliers to satisfy REACH transparency mandates.
- Sweatshirts:Crewneck and quarter-zip constructions serve corporate uniform programs with longer production runs but lower SKU proliferation than T-shirts.
- Caps:Structured and unstructured headwear demands specialized embroidery backing and panel engineering, concentrating supply among dedicated accessories manufacturers.
By volume, T-Shirts leads. By growth pace, Hoodies is ahead.
Material:
Cost tier positioning separates commodity suppliers from certified specialty programs that command sustained premiums.
- Cotton:Combed and carded varieties between 150-200 GSM anchor the commodity segment. Texas and Maharashtra weather patterns inject price volatility that unhedged buyers absorb directly.
- Polyester:Performance microfiber constructions serve athletic and outdoor end-uses where moisture-wicking properties override sustainability preferences.
- Blends:Cotton-poly and tri-blend fabrics balance printability with durability, capturing volume from print shops diversifying across screen printing, DTG, and heat transfer decoration methods.
- Bamboo:Viscose derived from bamboo pulp offers the steepest expansion trajectory as Scandinavian corporate uniform tenders mandate renewable content floors and OEKO-TEX or GOTS certification.
By volume, Cotton leads. By margin expansion, Bamboo is ahead.
Distribution Channel:
Customer type determines fulfillment architecture, with e-commerce platforms forcing inventory repositioning toward micro-fulfillment nodes.
- Online Retail:Amazon MFN and Shopify Fulfillment Network partnerships enable same-day decorated delivery from satellite inventory positions in Texas, Ohio, and Pennsylvania.
- Wholesale:Traditional bulk distribution to screen printing shops and promotional distributors concentrates in Los Angeles and Central American supply points serving Chicago, Atlanta, and Dallas.
- Direct Sales:Vertically integrated suppliers offering decoration-as-a-service bypass distributor markups by managing both substrate supply and applied customization.
- Resellers:Independent sales organizations extend geographic coverage for mid-tier suppliers lacking owned distribution infrastructure.
By transaction volume, Wholesale leads. By strategic priority, Online Retail is ahead.
End User:
Application maturity shapes supplier development roadmaps, with emerging decoration technologies creating new substrate performance requirements.
- Retailers:Branded merchandise programs demand Pantone-certified color consistency and rapid replenishment to minimize stockouts during promotional campaigns.
- Print Shops:Screen printing, DTG, and heat transfer operations require surface energy optimization and pretreatment compatibility, driving R&D investment toward ring-spun cotton jersey engineered for digital decoration.
- Promotional Brands:Marketing services companies consolidate vendor lists around vertically integrated providers capable of 72-hour decorated delivery.
- Manufacturers:Cut-and-sew houses and private label programs source undecorated blanks for downstream branding, prioritizing Bangladeshi suppliers with automated spreading and cutting systems.
By volume concentration, Print Shops leads. By vendor consolidation momentum, Promotional Brands is ahead.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bangladesh's export processing zones host the densest concentration of cut-and-sew capacity, with automated spreading systems compressing bulk knit lead times. Los Angeles-based vertical manufacturers sustain rapid replenishment through in-house dyeing and finishing. European procurement channels drive certification requirements that reshape supplier selection across all regions.
United States
Screen printing shops in Texas and North Carolina drive substrate demand for DTG-compatible ring-spun cotton. EPA discharge standards for dye houses elevate compliance costs for imported blanks. Los Angeles anchors domestic vertical manufacturing, with Next Level Apparel and Los Angeles Apparel operating integrated dye-cut-sew facilities serving 48-hour replenishment cycles.
Germany
Corporate uniform tenders in Bavaria and North Rhine-Westphalia mandate OEKO-TEX and GOTS certification for renewable content. EU Green Deal carbon border adjustments trigger supplier reconfigurations before full implementation. The country's national textile regulator enforces REACH chemical transparency, creating competitive separation for certified Bangladeshi and Portuguese suppliers.
Bangladesh
Export processing zones in Dhaka and Chittagong deploy automated cutting systems that halve bulk order lead times. The country's central bank facilitates renewable energy certificate programs to preserve EU market access. Garment manufacturing clusters concentrate reactive dyeing capacity, though energy rationing in Punjab-adjacent zones exposes supply vulnerabilities.
Vietnam
Cut-and-sew houses in Ho Chi Minh City and Hanoi serve Japanese and South Korean promotional brands with shorter runs than Bangladesh. The Ministry of Industry and Trade accelerates Scope 3 accounting adoption to preempt carbon border adjustment impacts. Da Nang emerging as a secondary hub for French terry and fleece categories facing steepest compliance cost escalations.
India
Maharashtra and Gujarat cotton belt volatility injects price instability into commodity knit supply. BIS textile labeling rules intersect with state-level effluent enforcement in Tiruppur's dyeing cluster. The country's national environmental regulator tightens discharge standards, pushing suppliers toward zero-liquid-discharge systems or Central American alternatives.
Blank Apparel Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in fiber and fabric supply. The blank apparel market structures around three tiers: Los Angeles-based vertical manufacturers with in-house decoration, Bangladeshi scale producers with automated cut-and-sew, and regional micro-fulfillment specialists. Consolidation concentrates among vertically integrated providers offering decoration-as-a-service. Capacity expansion and certification pipeline investments dominate competitive moves as buyers consolidate vendor lists.
Among Los Angeles-based fabricators, Next Level Apparel, Los Angeles Apparel, and Royal Apparel exemplify the vertical integration archetype. These entities occupy positions spanning substrate supply through applied decoration, enabling 72-hour delivery to Chicago, Atlanta, and Dallas distribution points. Their geographic concentration reflects proximity to screen printing shops and promotional distributors demanding rapid replenishment. Royal Apparel represents organic cotton specialization within this tier, while Next Level Apparel anchors rapid replenishment through captive dyeing and finishing. Los Angeles Apparel sits within the same manufacturing corridor, serving corporate uniform and branded merchandise programs with Pantone-certified consistency.
| Leading Market Players |
|---|
| Next Level Apparel |
| Zega Apparel |
| Los Angeles Apparel |
| YC Apparels |
| Hoodie Manufacturer |
| Royal Apparel |
| Lefty Production Co. |
| Affix Apparel |
| Rays Creations |
| Others |
Value Network & Pricing Analysis
Pakistan's Punjab dye house concentration determines both the spread between premium-certified and commodity-tier blanks and the geographic routing of supply chains serving European and North American buyers. Buyers face pricing volatility when energy rationing disrupts reactive dyeing capacity, forcing rapid supplier switching and freight cost absorption.
Pricing Analysis
REACH chemical transparency mandates dictate the pricing tier structure across European procurement channels. Three-tier pricing stratifies across OEKO-TEX-certified organic programs, standard combed cotton, and uncarded commodity knits. Certification grade and volume scale drive price differentiation, with ring-spun DTG-compatible jersey commanding premiums. Cost compression in commodity tiers intensifies because Bangladeshi automation expands supply. Small screen printing shops show highest price sensitivity; corporate uniform programs demonstrate lowest.
Supply Chain Analysis
Texas and Maharashtra cotton belt volatility feeds raw material instability into downstream knit pricing. Bangladesh, Vietnam, and India anchor cut-and-sew capacity, drawing from cotton futures markets, polyester chip supply, and bamboo pulp imports. Single-source dependency on Pakistan's reactive dyeing clusters creates vulnerability to effluent enforcement and energy rationing. Distribution runs through Los Angeles-based vertical manufacturers for rapid replenishment and Central American transshipment points for bulk wholesale.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Decoration-as-a-service layers expand faster than undecorated substrate sales, creating recurring revenue pools for suppliers managing inventory ownership and applied customization. The attach rate of fulfillment services now exceeds hardware margins in customer lifetime value calculations.
For Market Incumbents: Entrench position through captive dyeing capacity and GOTS certification pipelines that emerging Bangladeshi competitors cannot replicate quickly. Automate spreading and cutting systems to compress replenishment cycles below 48 hours. Defend against Los Angeles-based vertical manufacturers by securing Amazon MFN and Shopify Fulfillment Network node placements. For New Entrants and Emerging Players: Establish a beachhead in bamboo fiber certification programs serving Scandinavian corporate uniform tenders with mandated renewable content floors. Target DTG-ready ring-spun cotton jersey for online customizers bypassing screen setup costs. Lead with OEKO-TEX and GOTS credentials to unlock procurement channels closed to commodity suppliers. For Investors and Strategic Acquirers: Los Angeles-based fabricators with in-house decoration capabilities and Central American satellite capacity represent the most defensible acquisition archetype. Long-term viability hinges on backward integration into dyeing and finishing rather than pure cut-and-sew assembly. Watch carbon border adjustment implementation pace as the inflection signal for supply chain reconfiguration urgency.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Pipeline Investment | GOTS and OEKO-TEX credentials unlock EU Green Deal-compliant procurement channels in Germany and Netherlands. |
| Micro-Fulfillment Partnership | Satellite inventory placement within Amazon MFN nodes captures same-day decoration demand in Texas and Ohio. |
| Automation Deployment | Automated spreading systems in Bangladesh halve bulk knit lead times against Pakistani dye house bottlenecks. |
| Backward Integration | Captive dyeing and finishing in Los Angeles sustains 48-hour replenishment cycles for screen printing shops. |
| Material Innovation | Recycled cotton-mechanical polyester blends serve athletic applications where moisture management conflicts with sustainability commitments. |
Research Methodology
The analysis maps ring-spun cotton jersey, cotton-poly fleece, bamboo viscose, and polyester microfiber segments, each validated through procurement managers at promotional distributors, technical directors at screen printing shops, sustainability officers at corporate uniform programs, and logistics coordinators at e-commerce fulfillment networks. Primary interviews with these stakeholders combined with secondary validation from customs records, EPA discharge compliance filings, REACH registration databases, and OEKO-TEX certification registries. Bottom-up volume estimates and top-down market sizing triangulate across data streams.
Assumptions held fixed include current tariff structures, REACH chemical transparency enforcement levels, and carbon border adjustment implementation timelines; variables stress-tested include cotton price volatility, energy rationing severity in South Asian dye clusters, and DTG equipment adoption rates. The analytical framework models product type, material certification tier, distribution channel, and end-user application across the projection horizon. CAGRs derive from segment-level growth rate reconciliation against macroeconomic drivers. Forecast inputs include Bangladeshi automation deployment schedules and EU renewable energy certificate program participation rates.
Stress conditions across cotton supply shocks, dye house regulatory enforcement, and e-commerce platform fulfillment requirements were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions and risk factors including Proposition 65 litigation exposure and Scope 3 accounting adoption pace. Cross-checking against OEKO-TEX and GOTS certification database growth trajectories is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel Textiles
Cosplay Clothing Market
Apparel Textiles
Japan Denim Jeans Market
Apparel Textiles
Asia-Pacific Footwear Sole Material Market
Apparel Textiles
Hunting Apparel Market
Apparel Textiles
Automotive Textiles Market
Apparel Textiles
OEM Clothing Manufacturer Service Market
Apparel Textiles
Clothing Manufacturing Service Market
Apparel Textiles
Thailand Garment Industry Market
Apparel Textiles
Denim Market
Apparel Textiles
Uniform Market
Apparel Textiles
North America Footwear Sole Material Market
Apparel Textiles
Flame Retardant Apparel Market
Apparel Textiles
Maternity Wear Market
Apparel Textiles
Middle East and Africa Textile Garment Market
Apparel Textiles
Bridal Gowns Market
Apparel Textiles
Equestrian Apparel Market