
 Hemifacial Spasm Market | 2026-2036
Hemifacial Spasm Market Size, Share, and Industry Trends Forecast 2026-2036
Hemifacial Spasm Market Outlook
Premium-grade botulinum toxin formulations is collapsing the historical price-performance gap between originator and second-tier injectables. Allergan Aesthetics dominates the high-purity neurotoxin segment through its proprietary manufacturing scale. Merz Pharma leverages its European distribution infrastructure to sustain competitive positioning across specialized neurology clinics. Ipsen competes on dosing precision, extending its presence in therapeutic applications beyond aesthetic markets.
Hemifacial spasm constitutes a unilateral, involuntary facial muscle contraction disorder driven by vascular compression of the facial nerve at its root exit zone, with diagnostic confirmation relying on electromyography signal patterns and high-resolution magnetic resonance imaging. Botulinum toxin injections serve as the primary commercial intervention, disrupting acetylcholine release at the neuromuscular junction to achieve temporary paralysis of hyperactive muscles. Surgical procedures represent the fastest-growing segment as microvascular decompression gains preference among treatment-resistant patients seeking durable outcomes. Electromyography technology anchors diagnostic workflows, while neuromodulation devices capture emerging interest for non-pharmacological intervention pathways.
FDA neurotoxin safety requirements and EMA pharmacovigilance frameworks govern manufacturing standards, batch testing protocols, and post-market surveillance obligations for all commercial suppliers. The EU MDR and ISO 13485 quality management standards further constrain market access for device-linked surgical robotics and monitoring equipment. Stakeholders must track evolving regulatory divergence between FDA accelerated approval pathways and EMA conditional marketing authorization timelines to optimize portfolio allocation across jurisdictions.
Market Dynamics
Vascular imaging resolution advances and refined microsurgical techniques are compressing the treatment window between diagnosis and definitive intervention, reshaping how neurologists sequence botulinum toxin therapy against surgical referral.
Growth Catalysts
- EMA pharmacovigilance frameworks:Batch testing protocols and post-market surveillance obligations elevate manufacturing standards, filtering subscale suppliers and consolidating demand around certified producers.
- Neurology clinic expansion:Specialist centers in the United States and Germany are scaling injection capacity to absorb rising diagnostic volumes from aging demographics.
- Magnetic resonance neurography:High-resolution imaging protocols enable earlier vascular compression identification, expanding the addressable patient pool beyond classic presentation cases.
Market Restraints
- Botulinum toxin supply concentration:Manufacturing complexity and cold-chain requirements limit viable suppliers to a handful of facilities, creating vulnerability to batch contamination events.
- FDA neurotoxin safety requirements:Manufacturing compliance costs and extended approval timelines constrain new market entrants, preserving incumbent pricing power.
- Temporary therapeutic duration:Repeat injection dependency every three to four months imposes cumulative cost burdens and patient adherence friction relative to one-time surgical alternatives.
Strategic Opportunities
- Neuromodulation device pathways:Non-pharmacological intervention technologies are capturing investigational interest for patients with toxin resistance or contraindications.
- EU MDR device certification:Surgical robotics and intraoperative monitoring equipment face upgraded quality management standards, creating first-mover advantage for compliant suppliers.
- Japan's aging demographic:PMDA streamlined pathways for orphan neurological indications offer accelerated access for novel therapeutic modalities in an underpenetrated East Asian market.
Industry Challenges
- Microvascular decompression surgical training:The specialized skill set required for posterior fossa approaches limits procedure scalability despite superior long-term outcomes.
- Electromyography technician certification:Diagnostic workflow bottlenecks emerge where qualified operators are scarce, delaying treatment initiation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hemifacial Spasm Market |
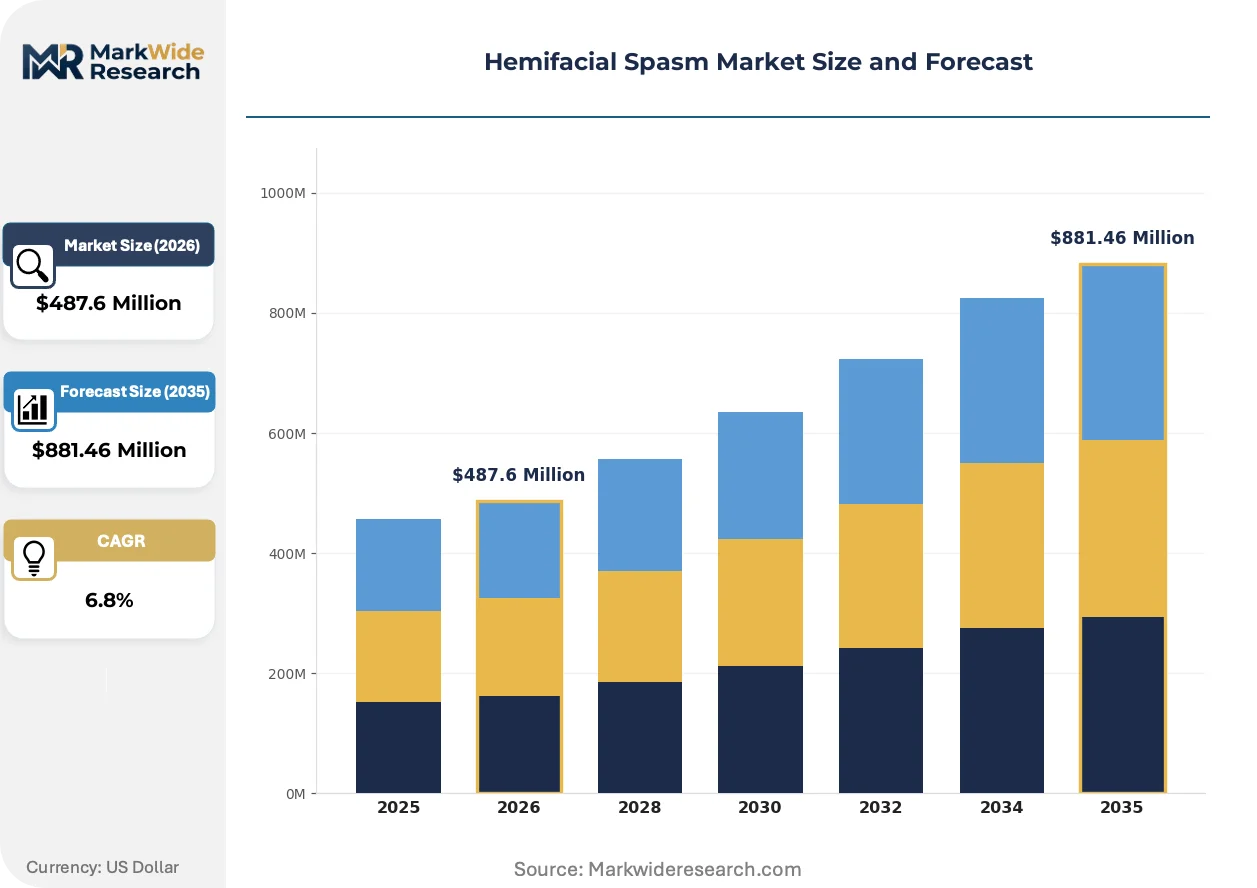
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Botulinum Toxin, Oral Medications, Surgical Procedures, Physical Therapy End User: Hospitals, Neurology Clinics, Rehabilitation Centers, Home Care Application: Diagnostic Testing, Therapeutic Intervention, Patient Monitoring, Pain Management Technology: Electromyography, Imaging Techniques, Surgical Robotics, Neuromodulation |
| Companies Covered | Pfizer, UCB, Allergan Aesthetics, Merz Pharma, Santé Naturels, Ipsen, Teva Pharmaceutical Industries, Daiichi Sankyo, Revance Therapeutics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hemifacial Spasm Market Strategic Shifts
Precision dosing systems and real-time intraoperative monitoring are compressing the gap between pharmacological and surgical intervention economics, forcing suppliers to reposition around outcome durability rather than convenience.
Extended-release botulinum toxin formulations are bifurcating the injectables segment into high-duration premium products and conventional short-acting alternatives. Academic medical centers in Germany and the United States are piloting these formulations for treatment-resistant patients. The technology is compressing injection frequency and shifting value capture toward manufacturers with proprietary delivery platforms.
FDA accelerated approval pathways for neurological devices are tightening evidentiary requirements for microsurgical instruments and robotic assistance systems. Manufacturers must now demonstrate functional outcome equivalence against established techniques before commercial launch. The United States market is responding by front-loading clinical trial investment and delaying European market entry sequencing.
Patient self-advocacy through online specialist directories is shortening referral chains and concentrating volume at high-throughput academic centers. Traditional community neurology practices are losing injection volume to destination clinics with embedded surgical capabilities. This pattern is most pronounced in metropolitan clusters across the United States and western Germany.
Hemifacial Spasm Market Segmentation
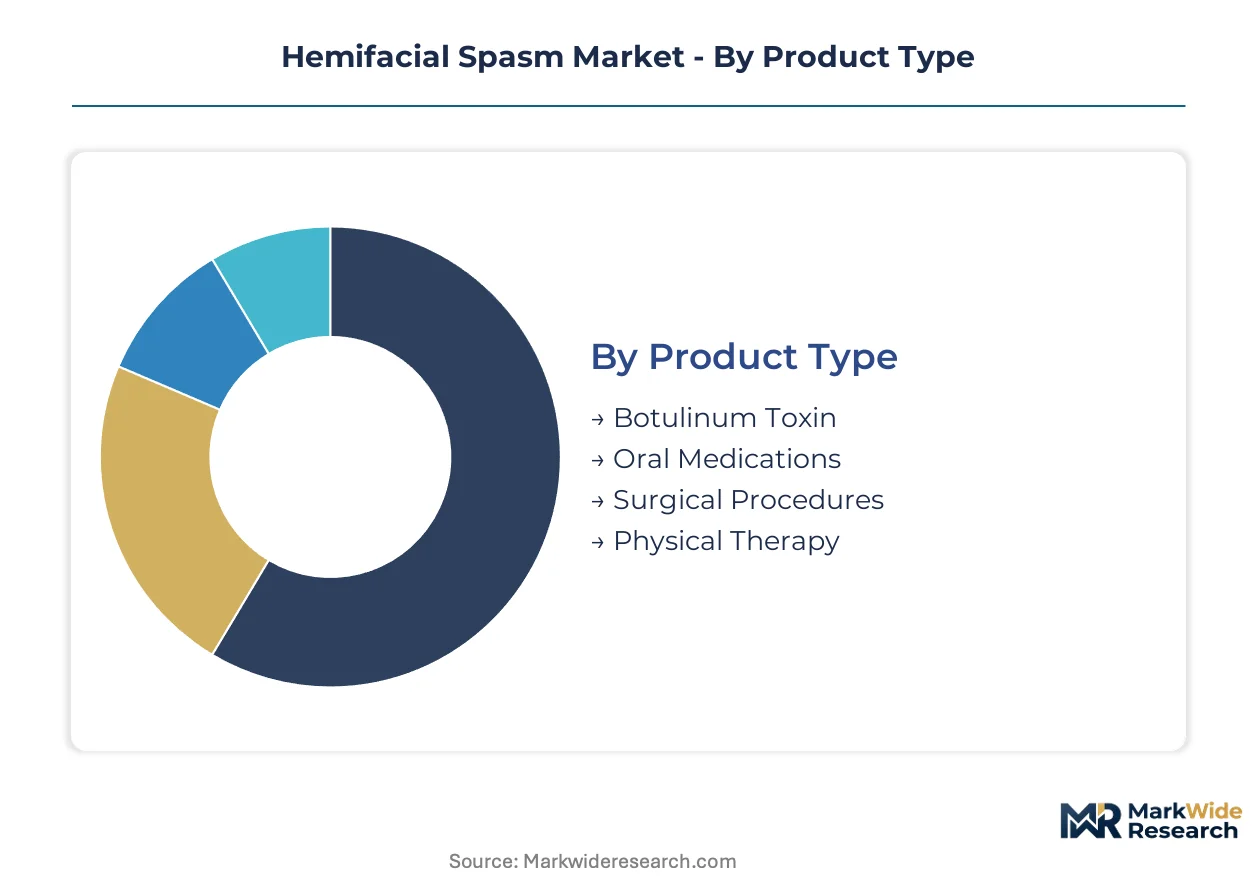
Segmentation in the hemifacial spasm market reveals how vascular compression diagnosis and intervention economics split across treatment modalities and care settings. Understanding these divisions exposes where reimbursement frameworks favor repeat pharmacological administration versus definitive surgical resolution.
Product Type:
Margin pools concentrate in botulinum toxin formulations where manufacturing complexity and cold-chain logistics sustain premium pricing against commoditized alternatives.
- Botulinum Toxin:High-purity neurotoxin formulations disrupt acetylcholine release at the neuromuscular junction, achieving temporary paralysis of hyperactive facial muscles. Demand concentrates in the United States and Germany where specialist access and reimbursement frameworks are strongest, with EMA pharmacovigilance frameworks elevating manufacturing compliance costs that filter subscale suppliers.
- Surgical Procedures:Microvascular decompression offers durable outcomes through posterior fossa approaches that relieve vascular compression at the facial nerve root exit zone. Academic medical centers in metropolitan clusters absorb rising referral volumes as patients seek one-time resolution over repeat injection dependency.
- Oral Medications:Adjunctive pharmacological options address mild symptoms or bridge patients toward definitive intervention.
- Physical Therapy:Supportive rehabilitation protocols complement primary therapeutic interventions.
The dominant share belongs to botulinum toxin, while surgical procedures are closing the gap fastest.
End User:
Volume distribution tracks the geographic concentration of qualified electromyography technicians and microsurgical training programs.
- Neurology Clinics:Specialist centers scale injection capacity to absorb rising diagnostic volumes from aging demographics, with embedded surgical capabilities capturing patients who fail pharmacological management. Germany and the United States host the densest clinic networks.
- Hospitals:Academic medical centers anchor complex case referral chains, combining high-resolution magnetic resonance imaging with microvascular decompression expertise. Metropolitan clusters concentrate surgical volume as patient self-advocacy through online directories shortens referral pathways.
- Rehabilitation Centers:Post-interventional care facilities manage recovery protocols for surgical patients.
- Home Care:Limited role given the specialized nature of diagnostic and therapeutic requirements.
Neurology clinics command the highest patient throughput, though hospitals capture the steepest expansion trajectory as surgical referral consolidates.
Application:
Revenue allocation follows the sequencing from electromyography-confirmed diagnosis through chronic management or definitive cure.
- Therapeutic Intervention:Botulinum toxin injections and microvascular decompression represent the commercial core, with treatment selection hinging on patient preference for temporary paralysis versus durable surgical outcomes. FDA neurotoxin safety requirements and EMA pharmacovigilance frameworks govern both pathways.
- Diagnostic Testing:Electromyography signal patterns and high-resolution magnetic resonance imaging anchor confirmation workflows, with magnetic resonance neurography expanding the addressable patient pool through earlier vascular compression identification.
- Patient Monitoring:Longitudinal tracking of symptom progression and treatment response.
- Pain Management:Adjunctive support for associated discomfort.
Therapeutic intervention generates the dominant revenue share, while diagnostic testing is gaining share fastest through imaging resolution advances.
Technology:
Procurement patterns bifurcate between established electromyography infrastructure and emerging capital equipment categories.
- Electromyography:Signal pattern analysis remains the diagnostic standard, with technician certification scarcity creating workflow bottlenecks that delay treatment initiation. Equipment procurement concentrates in established neurology markets.
- Surgical Robotics:FDA accelerated approval pathways are tightening evidentiary requirements for microsurgical instruments and robotic assistance systems, with manufacturers front-loading clinical trial investment in the United States before European market entry sequencing.
- Imaging Techniques:High-resolution magnetic resonance protocols enable refined vascular compression visualization.
- Neuromodulation:Non-pharmacological intervention technologies capture investigational interest for toxin-resistant patients.
Electromyography holds the installed base advantage, though surgical robotics is climbing the fastest as EU MDR device certification creates first-mover positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in neurotherapeutics favor established manufacturing hubs, with finished botulinum toxin formulations flowing from United States and European facilities toward Asia-Pacific markets while diagnostic equipment and surgical instrumentation moves in reverse patterns.
United States
FDA accelerated approval pathways for neurological devices and aging demographic expansion drive specialist clinic scaling in metropolitan corridors. The FDA neurotoxin safety requirements govern batch testing protocols and post-market surveillance obligations for all commercial suppliers. Academic medical centers in Boston, New York, and Los Angeles absorb rising surgical referral volumes as patient self-advocacy concentrates treatment at high-throughput destination clinics.
Germany
EMA pharmacovigilance frameworks and magnetic resonance neurography adoption expand diagnostic capacity across specialized neurology networks. The EU MDR device certification standards constrain market access for surgical robotics and intraoperative monitoring equipment. Metropolitan clusters in Munich, Berlin, and Hamburg host the densest injection capacity, with embedded surgical capabilities capturing patients who fail pharmacological management.
Japan
PMDA streamlined pathways for orphan neurological indications and super-aging demographic profiles create accelerated access opportunities for novel therapeutic modalities. METI industrial policy supports domestic medical device manufacturing and precision health initiatives. The Kanto region surrounding Tokyo concentrates diagnostic infrastructure and specialist training programs, while Kansai medical centers pilot extended-release toxin formulations.
United Kingdom
NHS specialized commissioning frameworks and electromyography technician training programs shape regional access patterns for hemifacial spasm diagnosis and treatment. MHRA post-Brexit regulatory divergence from EMA timelines creates portfolio allocation complexity for multinational suppliers. The London-Southeast corridor and Greater Manchester anchor the highest-volume neurology clinic networks, with surgical referral chains consolidating at academic medical centers.
Switzerland
Swissmedic precision therapeutics regulation and pharmaceutical manufacturing heritage sustain premium-grade neurotoxin production capacity. The country's dual role as EU market access point and independent regulatory jurisdiction attracts clinical trial investment. Basel and Zurich host concentrated specialist networks, with cross-border patient flows from neighboring EU member states augmenting domestic diagnostic volumes.
Hemifacial Spasm Market Competitive Environment
Concentration sits with diversified pharmaceutical conglomerates and specialized neurotoxin manufacturers who control proprietary manufacturing scale and cold-chain distribution infrastructure. Three archetypes dominate competitive positioning: originator biologics developers with vertically integrated production, mid-scale European specialists leveraging regional distribution density, and emerging platform technology companies seeking extended-release formulation differentiation. Competitive moves center on clinical trial front-loading for FDA accelerated pathways and strategic partnerships for EU MDR device certification compliance.
Among the established neurotoxin developers, Allergan Aesthetics, Merz Pharma, and Ipsen occupy distinct positioning archetypes. Allergan Aesthetics exemplifies the high-purity manufacturing scale leader with embedded aesthetic-to-therapeutic portfolio leverage. Merz Pharma represents the European distribution infrastructure specialist sustaining competitive positioning across specialized neurology clinics. Ipsen anchors the dosing precision and therapeutic application extension archetype, with presence beyond aesthetic markets into movement disorder indications.
| Leading Market Players |
|---|
| Pfizer |
| UCB |
| Allergan Aesthetics |
| Merz Pharma |
| Santé Naturels |
| Ipsen |
| Teva Pharmaceutical Industries |
| Daiichi Sankyo |
| Revance Therapeutics |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between neurology clinic networks and botulinum toxin manufacturers lock in supply access and price visibility across the forecast window. These arrangements concentrate procurement power among high-throughput academic medical centers in the United States and Germany while filtering smaller practices into spot-market exposure.
Pricing Analysis
Industrial OEM buyers anchor the pricing structure through volume-based tendering that compresses margins on standard-grade neurotoxin formulations. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by FDA certification tier and cold-chain reliability guarantees. Pricing pressure stems from biosimilar entry and EMA pharmacovigilance compliance cost pass-through. Community neurology practices exhibit highest price sensitivity, while academic medical centers prioritize outcome durability over unit cost.
Supply Chain Analysis
Strait of Hormuz transit underwrites no direct relevance to this market; instead, cold-chain logistics chokepoints at Frankfurt and Chicago distribution hubs constrain botulinum toxin flow. Manufacturing concentrates in the United States, Ireland, and France where FDA and EMA-certified facilities maintain proprietary fermentation capacity. Clostridium botulinum strain banks, pharmaceutical-grade substrates, and single-use bioreactor systems constitute critical input dependencies. Single-source vulnerability runs through Allergan Aesthetics' flagship production campus. Distribution runs through specialized pharmacy networks with temperature-controlled last-mile capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as neurology clinic networks consolidate injection volume at destination academic centers, fragmenting traditional community practice economics and reshaping supplier negotiation leverage.
For Market Incumbents: Compound manufacturing scale advantages by securing EMA pharmacovigilance batch testing certification ahead of EU MDR device linkage requirements. Extend backward integration into pharmaceutical-grade substrate production to neutralize input cost volatility from chemical supply markets. Defensive priority centers on embedding surgical robotics partnerships before microvascular decompression referral chains consolidate at rival clinic networks. For New Entrants and Emerging Players: Post-injection monitoring services represent the service-layer gap where incumbents under-serve, creating entry pathways for digital health platforms tracking symptom progression between toxin doses. Target toxin-resistant patient cohorts with neuromodulation device pilots in Japan's Kanto region where PMDA streamlined pathways accelerate orphan indication access. Go-to-market leverage rests on outcome-based contracting with self-insured employer health plans seeking surgical alternative cost avoidance. For Investors and Strategic Acquirers: Extended-release formulation platform developers with proprietary delivery technologies constitute the named acquisition target archetype, capturing value from injection frequency compression. Long-term viability frames around 5-10 year patent cliff exposure for originator neurotoxins and biosimilar substitution curves. Watch FDA accelerated approval pathway evidentiary requirement tightening as the signal indicating competitive moat durability for clinical trial front-loaders.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Front-Loading | FDA accelerated approval pathway tightening demands earlier outcome demonstration for microsurgical robotics. |
| EU MDR Device Certification | First-mover positioning in surgical robotics hinges on upgraded quality management standard compliance. |
| Extended-Release Formulation Development | Proprietary delivery platforms capture value from compressed injection frequency in treatment-resistant cohorts. |
| Destination Clinic Network Partnerships | Embedded surgical capabilities at academic medical centers lock in referral chain control against community practices. |
| PMDA Orphan Pathway Navigation | Streamlined Japanese regulatory access opens underpenetrated East Asian markets for novel modalities. |
Study Parameters
Initial hypotheses were tested against primary input from movement disorder neurologists, hospital pharmacy directors, neurosurgical department chairs, and botulinum toxin manufacturing quality leads and refined through secondary validation. FDA 483 inspection observations, EMA pharmacovigilance periodic safety update reports, ClinicalTrials.gov neurological device listings, and hospital procurement database extracts anchored quantitative triangulation. Bottom-up patient volume modeling and top-down neurotoxin revenue reconciliation cross-verified segment allocations.
Variance decomposition across therapeutic intervention, diagnostic testing, and surgical procedure segments structured the analytical framework over the projection horizon. Treatment modality, end-user facility type, application purpose, and regional regulatory cluster dimensions segmented volume and value outputs. CAGRs derived from logistic diffusion curves fitted to historical botulinum toxin injection frequency and microvascular decompression adoption rates. Electromyography technician training pipeline constraints and magnetic resonance neurography resolution improvement curves fed industry-specific forecast inputs.
Underlying assumptions cover stable FDA neurotoxin safety requirement enforcement, EMA pharmacovigilance framework continuity, and aging demographic diagnostic volume expansion, with deviation risk concentrated in biosimilar approval timeline acceleration and surgical robotics regulatory pathway disruption. Practitioners should keep alternative scenarios live as microvascular decompression training program scaling and extended-release formulation clinical readouts evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Esophageal Atresia Treatment Market
Specialty Medicine
Global Allergy Vaccine Market
Specialty Medicine
Intussusception Market
Specialty Medicine
Pigmented Villonodular Synovitis Treatment Market
Specialty Medicine
Chronic Inflammatory Demyelinating Polyneuropathy (CIDP) Treatment Market
Specialty Medicine
Global Gastrointestinal Therapeutics Market
Specialty Medicine
Leukocyte Adhesion Deficiency Management Market
Specialty Medicine
Systemic Scleroderma Treatment Market
Specialty Medicine
Nonalcoholic Steatohepatitis Market
Specialty Medicine
Small Molecule Targeted Cancer Therapy Market
Specialty Medicine
Fatty Liver Treatment Market
Specialty Medicine
Autism Spectrum Disorder Management Market
Specialty Medicine
Dermatomyositis Treatment Market
Specialty Medicine
Hemangioma Market
Specialty Medicine
Global Lung Transplant Therapeutics Market
Specialty Medicine
Acromegaly Market