
 Cystic Fibrosis Transmembrane Conductance Regulator (CFTR) Market | 2026-2036
Cystic Fibrosis Transmembrane Conductance Regulator (CFTR) Market Size, Share, and Industry Trends Forecast 2026-2036
Cystic Fibrosis Transmembrane Conductance Regulator (CFTR) Market Outlook
Asset-light licensing partnerships between biotech innovators and large pharmaceutical distributors is reconfiguring competitive dynamics in CFTR therapeutics. Vertex Pharmaceuticals leverages its vertical integration across discovery, clinical development, and commercialization to sustain pricing power in the modulator space. AbbVie Inc. anchors its position through specialized rare-disease commercial infrastructure that controls access to prescriber networks. Sionna Therapeutics competes by concentrating R&D investment on next-generation correctors with differentiated binding mechanisms.
Cystic Fibrosis Transmembrane Conductance Regulator proteins are chloride ion channels encoded by the CFTR gene, with dysfunction causing defective mucociliary clearance across epithelial surfaces; CFTR modulators restore channel gating, trafficking, or conductance through pharmacological intervention. The ivacaftor and elexacaftor product classes dominate current revenue pools due to established efficacy in gating and trafficking mutations respectively. Oral delivery mode leads volume distribution, though inhalation formulations are gaining development priority for direct lung epithelium targeting. Hospital end users capture the largest patient initiation share, while home care channels are expanding for maintenance therapy administration.
FDA orphan drug designations and EMA priority medicines pathways shape development economics by granting market exclusivity and protocol assistance for CFTR-directed therapies. The FDA's accelerated approval framework permits surrogate endpoint-based authorization, compressing time-to-market for novel modulator combinations. Reimbursement negotiations with national health technology assessment bodies in Germany, France, and England determine accessible patient populations across European markets. Stakeholders must monitor emerging gene therapy and mRNA correction platforms that could displace small-molecule modulator paradigms before patent cliff exposures materialize.
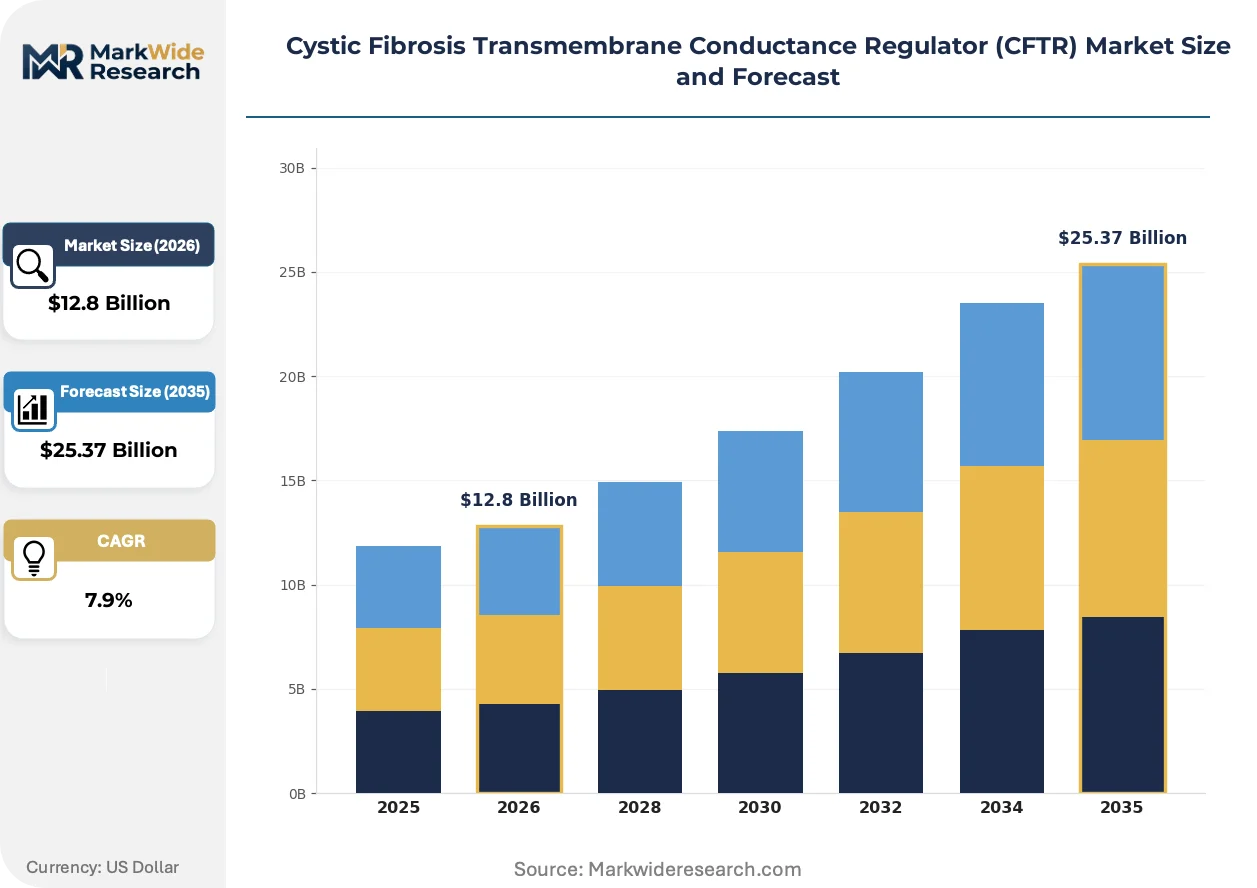
Market Dynamics
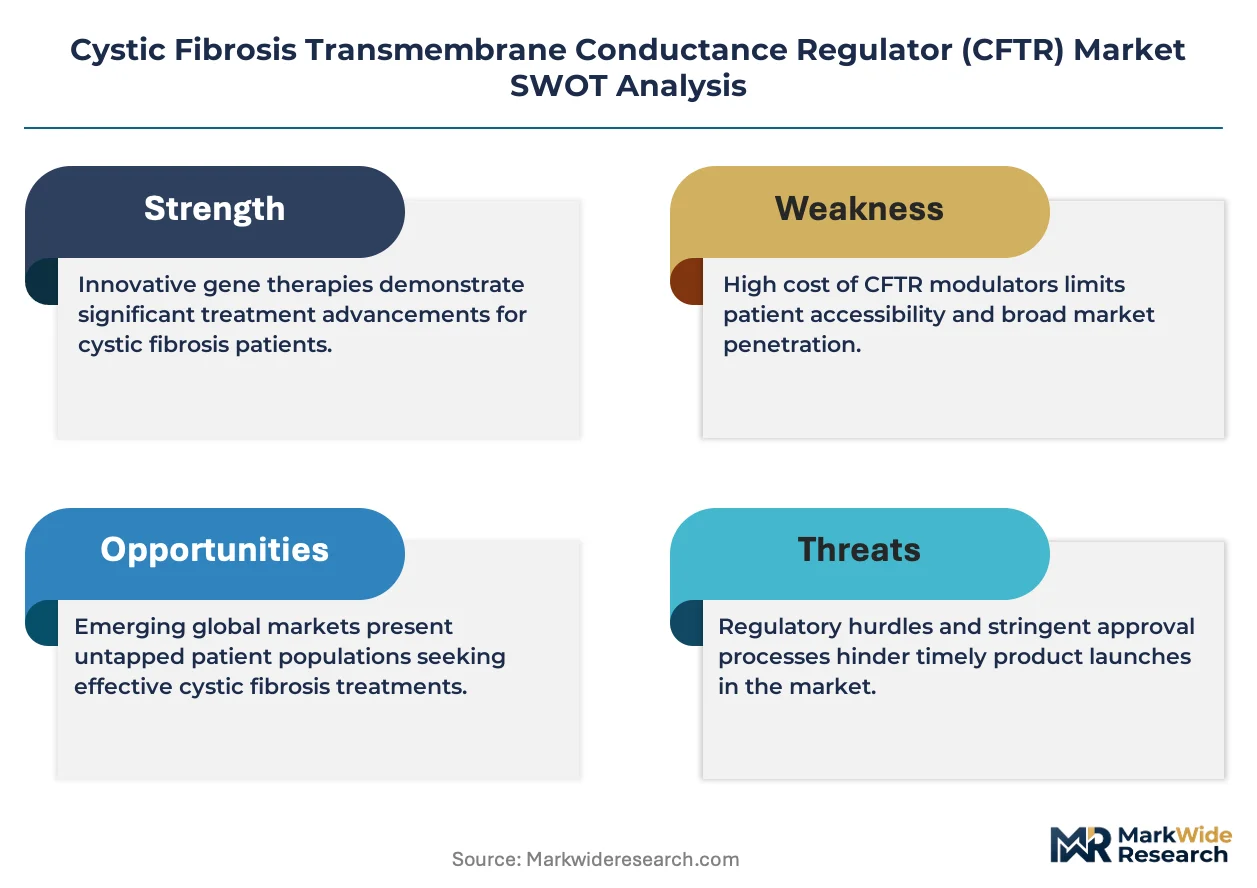
The CFTR therapeutics market is restructuring around accelerated FDA orphan drug pathways that compress development timelines from discovery to commercial launch, concentrating revenue capture among vertically integrated developers with captive rare-disease commercial infrastructure.
Growth Catalysts
- EMA Priority Medicines Pathway:European regulators grant protocol assistance and accelerated assessment for CFTR-directed therapies, reducing time-to-market for novel modulator combinations seeking EU authorization.
- Hospital-based pulmonology expansion:Specialist care infrastructure in the United States is scaling rapid diagnostic-to-treatment pipelines, compressing patient initiation timelines for modulator therapies.
- Surrogate endpoint frameworks:The FDA permits sweat chloride reduction as a validated biomarker for accelerated approval, enabling smaller trial designs and faster regulatory decisions for corrector-investigational drug combinations.
Market Restraints
- Reimbursement concentration risk:Germany's G-BA and England's NICE impose cost-effectiveness thresholds that restrict accessible patient populations for triple-combination therapies, fragmenting European market penetration.
- Input cost volatility:Active pharmaceutical ingredient synthesis for CFTR correctors requires specialized chiral chemistry capabilities concentrated in Swiss and German contract manufacturers, exposing supply chains to capacity constraints.
- Gene therapy substitution threat:CRISPR-based CFTR correction platforms and mRNA delivery systems in Phase I/II trials threaten to displace small-molecule modulator paradigms before patent expirations materialize.
Strategic Opportunities
- Underpenetrated pediatric segments:France and Italy maintain lower diagnosis-to-treatment ratios for adolescent CF patients compared to Nordic markets, creating white space for age-appropriate formulation development.
- Direct-to-patient distribution:Home care channels for maintenance therapy administration are expanding beyond hospital-centric models, enabling pharmacy benefit manager partnerships and patient adherence programs.
- Inhalation formulation convergence:Nebulized delivery systems combining CFTR modulators with mucolytic agents are gaining priority in development pipelines, targeting direct lung epithelium penetration.
Industry Challenges
- Regulatory chemistry, manufacturing and controls expertise:The specialized skill set required for CFTR modulator quality control and batch consistency testing faces acute scarcity, extending validation timelines for new manufacturing sites.
- Legacy diagnostic infrastructure integration:Genotyping laboratories in secondary care settings require capital-intensive upgrades to next-generation sequencing platforms capable of identifying rare CFTR mutations eligible for targeted therapies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cystic Fibrosis Transmembrane Conductance Regulator (CFTR) Market |
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $25.37 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ivacaftor, Lumacaftor, Tezacaftor, Elexacaftor Delivery Mode: Oral, Inhalation, Injectable, Topical End User: Hospitals, Clinics, Home Care, Pharmacies Therapy Area: Pulmonology, Pediatrics, Gastroenterology, Genetics |
| Companies Covered | Vertex Pharmaceuticals, AbbVie Inc., Novartis AG, Gilead Sciences, AstraZeneca, Bayer AG, Sionna Therapeutics, Genentech Inc., ReCode Therapeutics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cystic Fibrosis Transmembrane Conductance Regulator (CFTR) Market Strategic Shifts
Computational drug discovery platforms are compressing lead optimization cycles for CFTR modulators, while regulatory science advances and patient advocacy pressure are reshaping how rare disease therapeutics reach market authorization.
Structure-guided molecular design is virtualizing traditional high-throughput screening workflows for next-generation CFTR correctors. Biotech innovators deploy cryo-electron microscopy and artificial intelligence-driven binding prediction to identify allosteric sites distinct from Vertex's established pharmacophores. Hospital-based research consortia in Boston and San Diego are piloting these platforms for patient-derived organoid screening, collapsing preclinical validation timelines from years to months.
REACH registration requirements for novel chemical entities are forcing reformulation strategies for inhalation-grade CFTR modulators. The European Chemicals Agency's nanomaterial characterization mandates impose additional toxicology burdens on liposomal and polymeric delivery systems. Developers are responding by establishing dedicated regulatory affairs functions in Brussels to navigate substance volume threshold calculations and exposure scenario modeling.
Patient advocacy organizations are consolidating purchasing influence through specialized pharmacy networks that bypass traditional hospital procurement. The Cystic Fibrosis Foundation's Path to a Cure initiative channels research funding toward gene therapy developers, redirecting prescriber attention from incremental modulator improvements to curative modalities. This behavioral shift concentrates most visibly in the United States, where foundation-supported care centers coordinate treatment decisions with commercial access programs.
Cystic Fibrosis Transmembrane Conductance Regulator (CFTR) Market Segmentation
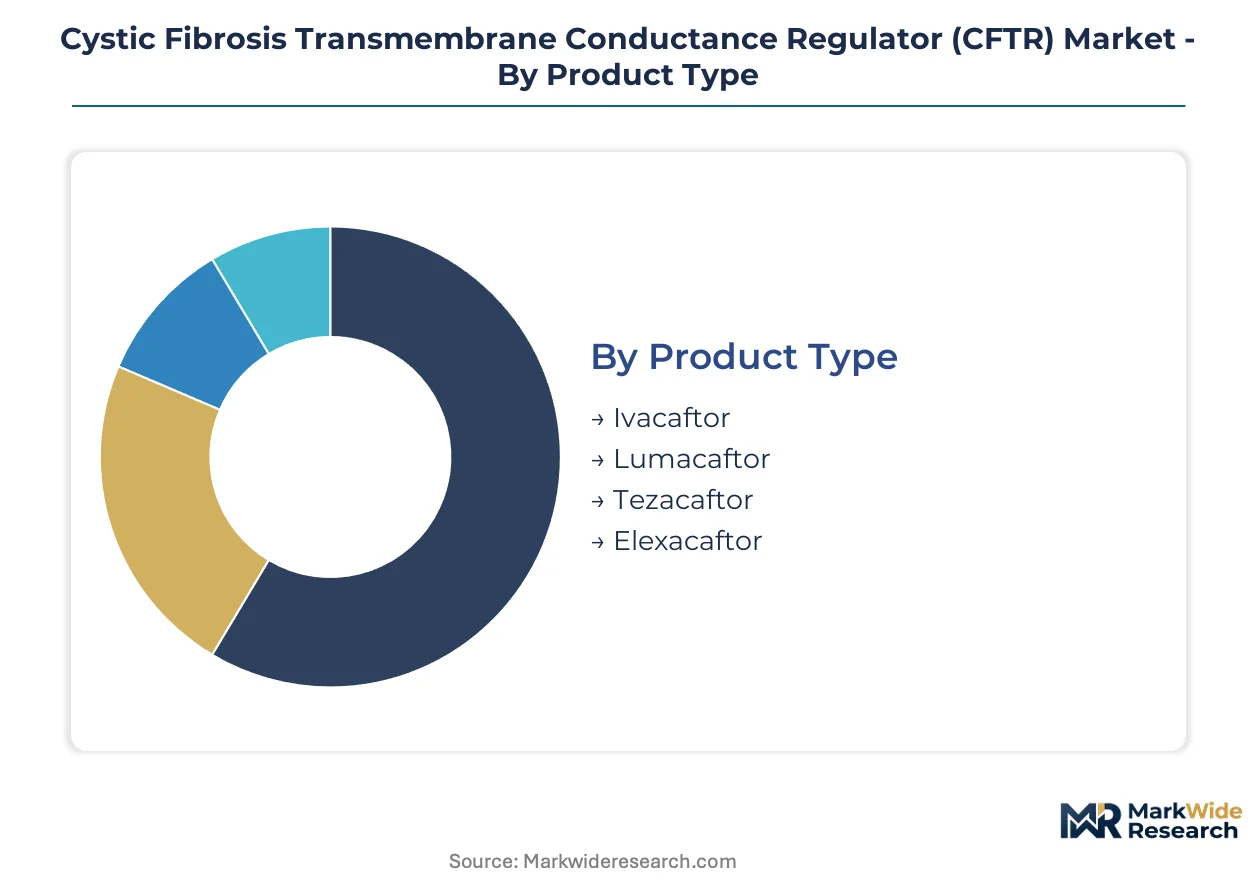
CFTR modulator segmentation reveals how formulation science, administration convenience, and care setting economics intersect to determine accessible patient populations. Distinct product classes target mutation-specific channel defects, while delivery innovation and end-user channel expansion reshape competitive boundaries.
Product Type:
Cost tier differentiation separates established single-agent therapies from premium triple-combination regimens, with pricing power concentrated among mutation-specific portfolios.
- Ivacaftor:Potentiator compounds restore gating function in G551D and other Class III mutations through direct channel activation. Demand concentrates in the United States among patients with responsive genotypes, constrained by narrow eligibility criteria and high list pricing that triggers pharmacy benefit manager prior authorization protocols.
- Elexacaftor:Next-generation corrector components enable triple-combination therapy for F508del homozygous patients, the largest addressable mutation population. United States specialist centers capture the majority of initiations, driven by FDA orphan drug exclusivity and compressed diagnostic-to-treatment timelines in academic medical center networks.
- Lumacaftor:First-generation corrector with established efficacy in F508del combinations, now positioned for cost-sensitive markets and formulary tier management.
- Tezacaftor:Improved corrector pharmacokinetics supporting dual and triple therapy, with particular relevance for heterozygous F508del populations requiring tailored combination approaches.
Ivacaftor commands the established base. The steepest expansion runs through Elexacaftor.
Delivery Mode:
Application convenience drives adherence economics, with oral formulations dominating maintenance therapy and inhalation systems gaining priority for direct epithelial targeting.
- Oral:Tablet and granule formulations enable daily self-administration, supporting high adherence rates in adolescent and adult populations. United States home care channels capture volume leadership, facilitated by specialty pharmacy distribution and patient support programs that reduce discontinuation risk.
- Inhalation:Nebulized and dry-powder delivery achieves direct lung deposition, addressing mucus penetration barriers that limit systemic bioavailability. Development pipelines in Boston and Basel prioritize this modality for next-generation correctors, targeting improved epithelial exposure with reduced systemic exposure.
- Injectable:Subcutaneous and intravenous routes reserved for acute exacerbation settings and gene therapy adjunct protocols.
- Topical:Nasal and dermal applications for localized CFTR-related conditions, including chronic rhinosinusitis and sweat gland dysfunction.
Oral administration retains volume leadership. Inhalation systems are climbing the fastest toward regulatory submission.
End User:
Customer type concentration reflects care complexity, with hospital-based specialists controlling initiation decisions and home channels expanding for maintenance.
- Hospitals:Academic medical centers and children's hospitals house specialized CF care teams with genotype interpretation expertise and clinical trial access. United States centers accredited by the Cystic Fibrosis Foundation capture the majority of modulator initiations, leveraging embedded pharmacy services to navigate prior authorization requirements.
- Home Care:Specialty nursing and infusion services enable maintenance therapy administration outside institutional settings, reducing infection exposure for immunocompromised patients. Germany and France are expanding reimbursement for home-based monitoring, creating channel diversification opportunities.
- Clinics:Community pulmonology practices handle stable patient follow-up and prescription renewal.
- Pharmacies:Retail and specialty pharmacy networks manage refill logistics and adherence packaging.
Hospitals anchor the initiation pathway. Home care is gaining share fastest as maintenance protocols mature.
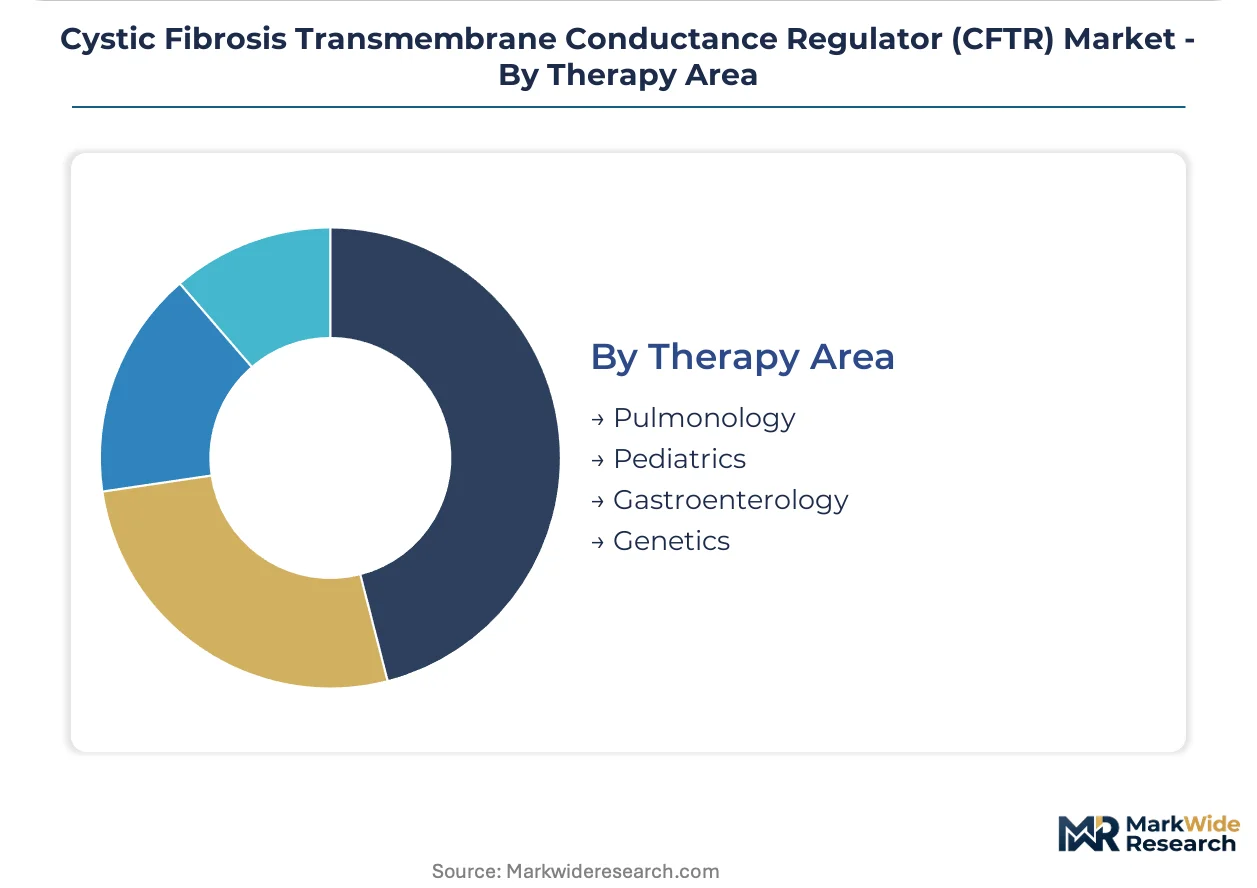
Therapy Area:
Maturity gradients separate well-established pulmonology indications from emerging gastrointestinal and genetic medicine applications.
- Pulmonology:Lung-targeted modulator therapy represents the commercial core, with forced expiratory volume and pulmonary exacerbation rate as primary endpoints. United States pulmonology departments in Philadelphia, Denver, and Seattle lead real-world evidence generation through integrated electronic health record networks.
- Genetics:Personalized medicine approaches using next-generation sequencing to match mutation profiles with optimal modulator combinations. European reference laboratories in Leuven and Copenhagen are scaling diagnostic throughput, expanding treatable population identification.
- Pediatrics:Age-appropriate formulations and early intervention protocols for disease modification prior to irreversible lung damage.
- Gastroenterology:Pancreatic enzyme replacement adjuncts and emerging CFTR-directed therapies for intestinal manifestations.
Pulmonology holds the revenue base. Genetics-enabled personalization is expanding most quickly into clinical practice.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialist care centers and reimbursement frameworks determine where CFTR modulator demand materializes. Vertically integrated developers capture revenue in markets with established rare-disease commercial infrastructure. Regulatory pathway efficiency varies sharply by jurisdiction.
United States
The Cystic Fibrosis Foundation accredits over 130 care centers that control patient access to modulator therapies. FDA orphan drug exclusivity and accelerated approval frameworks compress time-to-market for novel combinations. Boston and San Diego anchor clinical trial density, with Massachusetts General Hospital and UC San Diego leading real-world evidence generation for next-generation correctors.
Germany
G-BA cost-effectiveness assessments determine reimbursement eligibility for triple-combination therapies, creating access friction for premium-priced regimens. The country's statutory health insurance system mandates health technology assessment prior to national listing. Heidelberg and Berlin concentrate genotyping laboratory capacity, with European reference networks scaling diagnostic throughput for rare mutation identification.
United Kingdom
NICE single technology appraisals impose cost-per-QALY thresholds that restrict patient populations for high-cost modulator combinations. NHS England's specialized commissioning framework centralizes treatment initiation in designated cystic fibrosis centers. Manchester and London house the largest adult CF populations, with Royal Brompton Hospital driving longitudinal outcomes research.
France
ANSM early access programs and HAS transparency committee evaluations shape market access timelines for innovative CFTR-directed therapies. The country's reference pricing system creates spillover effects across EU markets. Paris and Lyon maintain the highest diagnosis-to-treatment ratios, though adolescent penetration lags Nordic benchmarks.
Switzerland
Swissmedic authorization procedures and compulsory health insurance coverage decisions determine commercial viability for premium orphan drugs. The country's contract manufacturing base supplies active pharmaceutical ingredients for corrector synthesis, with Basel and Zurich hosting specialized chiral chemistry capabilities. University Hospital Zurich anchors pediatric clinical research for age-appropriate formulations.
Cystic Fibrosis Transmembrane Conductance Regulator (CFTR) Market Competitive Environment
Channel-controlling players compete with product-specialist players for prescriber access and patient initiation control. The market structure concentrates around vertically integrated rare-disease developers with captive commercial infrastructure and specialized biotech innovators pursuing differentiated binding mechanisms. Two strategic archetypes dominate: full-stack developers controlling discovery-through-distribution value chains, and platform-focused correctors targeting pharmacophore white space. Competitive moves center on diagnostic partnership expansion and formulation science differentiation for direct lung targeting.
Among full-stack developers, Vertex Pharmaceuticals exemplifies vertical control over the modulator value chain, while AbbVie Inc. occupies a position anchored in rare-disease commercial infrastructure. Sionna Therapeutics represents the specialized corrector archetype, concentrating R&D investment on next-generation mechanisms distinct from established pharmacophores. These three anchors illustrate how competitive positioning stratifies between channel dominance and scientific differentiation.
| Leading Market Players |
|---|
| Vertex Pharmaceuticals |
| AbbVie Inc. |
| Novartis AG |
| Gilead Sciences |
| AstraZeneca |
| Bayer AG |
| Sionna Therapeutics |
| Genentech Inc. |
| ReCode Therapeutics |
| Others |
Value Chain & Pricing Dynamics
Basel and Zurich anchor the global supply of chiral chemistry capabilities for CFTR corrector synthesis, where specialized contract manufacturing capacity constraints translate directly into pricing power for developers controlling captive production assets. Vertex Pharmaceuticals leverages this geographic concentration to sustain premium positioning for triple-combination therapies, while smaller innovators face input cost volatility from Swiss and German API manufacturers.
Pricing Analysis
Certification level creates the primary spread between FDA-orphan-designated triple-combination regimens and legacy dual-therapy alternatives. Three-tier pricing structure across premium, standard, and economy levels stratifies by mutation eligibility and treatment line, with F508del homozygous populations commanding highest reimbursement. Cost compression in first-generation correctors intensifies as pharmacy benefit managers impose prior authorization protocols. Pediatric formulations show highest price sensitivity due to weight-based dosing economics and formulary tier placement.
Supply Chain Analysis
Tariff exposure between Switzerland and the United States dominates risk calculus for CFTR modulator developers dependent on Basel-based chiral synthesis. Active pharmaceutical ingredient production draws from Switzerland, Germany, and India, with specialized heterocyclic chemistry capabilities concentrated in Basel and Ludwigshafen. Single-source vulnerability runs through Swiss contract manufacturers holding proprietary crystallization protocols. Distribution runs through specialty pharmacy networks accredited by the Cystic Fibrosis Foundation, bypassing traditional hospital procurement for maintenance therapy.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The CFTR therapeutics market rewards developers commanding scarce regulatory chemistry expertise and rare-disease commercial infrastructure, while gene therapy platforms threaten to obsolete small-molecule investments before patent expirations.
For Market Incumbents: Entrench diagnostic-to-treatment control through embedded pharmacy services in Cystic Fibrosis Foundation-accredited centers, countering gene therapy substitution threats with longitudinal real-world evidence generation. Deepen backward integration into chiral API synthesis to insulate margins from Swiss contract manufacturing capacity constraints. Prioritize pediatric formulation development to capture age-appropriate exclusivity windows.
For New Entrants and Emerging Players: Underpenetrated adolescent populations in France and Italy represent the most penetrable entry point for next-generation correctors with differentiated binding mechanisms. Direct-to-patient distribution partnerships with specialty pharmacy networks bypass hospital-centric procurement bottlenecks. Target inhalation formulation convergence as the fastest regulatory pathway to clinical differentiation.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors platform-correctors with distinct pharmacophores over incremental modulator improvements. Long-term viability hinges on patent runway extension through formulation innovation and geographic expansion. Watch CRISPR-based CFTR correction platform readouts as the critical inflection signal for small-molecule displacement risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA accelerated approval compresses timelines for corrector combinations using sweat chloride surrogate endpoints. |
| Manufacturing Scale-Up | Specialized chiral chemistry capacity expansion in Basel reduces API supply bottlenecks for triple-therapy production. |
| Pipeline Diversification | Gene therapy and mRNA correction platforms hedge against small-molecule patent cliff exposures. |
| Hospital System Partnership | Cystic Fibrosis Foundation care center accreditation controls patient initiation and formulary placement. |
| Reimbursement Strategy | NICE and G-BA health technology assessment navigation determines accessible European patient populations. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers. Secondary validation drew from FDA orphan drug designations, EMA priority medicines pathways, ClinicalTrials.gov entries, and formulary database audits. Bottom-up patient population modeling and top-down revenue triangulation anchored market size estimation.
Calibration against historical approval timelines and reimbursement decision patterns shaped the analytical framework across the projection horizon. Segmentation dimensions included product type, delivery mode, end user, and therapy area, with mutation-specific eligibility criteria as a cross-cutting stratifier. CAGRs were derived from epidemiological prevalence projections and treatment penetration curves, incorporating payer access dynamics and competitive launch sequencing.
Macroeconomic conditions sit as an overlay; deviation in statutory health insurance reimbursement rates or rare-disease funding allocations would shift the trajectory. Forecasts reflect assumptions about regulatory pathway efficiency and gene therapy clinical progress that warrant continuous reassessment. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Oral Cancer Treatment Market
Specialty Medicine
Autism Spectrum Disorder Management Market
Specialty Medicine
Generalized Anxiety Disorder (GAD) Market
Specialty Medicine
Focal Segmental Glomerulosclerosis (FSGS) Treatment Market
Specialty Medicine
Systemic Scleroderma Treatment Market
Specialty Medicine
Cervical Cancer Therapeutics Market
Specialty Medicine
Epilepsy Treatment Market
Specialty Medicine
Neuroendocrine Carcinoma Treatment Market
Specialty Medicine
Hemorrhagic Stroke Treatment Market
Specialty Medicine
Buruli Ulcer Treatment Market
Specialty Medicine
Piriformis Syndrome Treatment Market
Specialty Medicine
Mucinoses Management Market
Specialty Medicine
Nerve Entrapment Syndrome Therapeutics Market
Specialty Medicine
Brugada Syndrome Market
Specialty Medicine
Parathyroid Disorders Market
Specialty Medicine
Cerebral Vein Thrombosis Treatment Market