
 Intelligent Pigging Services Market | 2026-2036
Intelligent Pigging Services Market Size, Share, and Industry Trends Forecast 2026-2036
Intelligent Pigging Services Market Outlook
The power generation sector is broadening its reliance on intelligent pigging as hydrogen blending and carbon capture pipelines expand. Baker Hughes Company leverages its electromagnetic technology portfolio across onshore and offshore delivery modes. T.D. Williamson sustains its position through specialized cleaning and inline inspection tool development. NDT Global differentiates via high-resolution ultrasonic crack detection capabilities for critical sour gas lines.
Intelligent pigging services deploy instrumented devices through pressurized pipelines to detect metal loss, cracks, and geometric anomalies using magnetic flux leakage, ultrasonic, electromagnetic, or acoustic sensor arrays. These services enable operators to assess wall thickness, identify corrosion patterns, and map dent profiles without interrupting product flow. Magnetic flux leakage technology occupies the largest service volume due to mature tool availability and lower per-kilometer deployment cost. Ultrasonic inspection represents the fastest-expanding segment, driven by demand for crack detection precision in high-strength steel lines. Inline inspection commands the dominant share of value pools, while data acquisition services are deepening as operators integrate real-time analytics platforms.
PHMSA integrity management rules in the United States, the EU Pipeline Safety Directive, and ISO 13847 welding standards collectively shape tool certification requirements and inspection frequency mandates. Compliance with these frameworks determines market access for service providers and drives replacement cycles for legacy magnetic flux leakage systems. Stakeholders must monitor evolving hydrogen infrastructure codes and their implications for sensor calibration standards and tool compatibility.
Market Dynamics
Aging pipeline infrastructure across North America and Europe is forcing midstream operators to accelerate inline inspection cycles while hydrogen blending mandates require recalibration of existing electromagnetic and ultrasonic sensor arrays for embrittlement-sensitive materials.
Growth Catalysts
- PHMSA Integrity Management Rules:United States operators must complete baseline assessments on high-consequence areas every seven years, creating recurring demand for magnetic flux leakage and ultrasonic tool deployment cycles.
- Hydrogen Pipeline Infrastructure:European utilities are repurposing natural gas networks for hydrogen transport, requiring specialized crack detection protocols and new calibration standards for existing intelligent pigging fleets.
- Offshore Decommissioning Delays:Extended operational life of subsea pipelines in the North Sea and Gulf of Mexico necessitates more frequent geometric anomaly mapping and corrosion monitoring through tethered inspection tools.
Market Restraints
- High-Strength Steel Compatibility Gaps:Existing magnetic flux leakage tools face signal attenuation challenges when inspecting X80 and X100 grade pipelines, limiting service addressability in newer transmission corridors.
- Specialized Technician Scarcity:Data interpretation from multi-sensor arrays requires certified analysts with combined expertise in non-destructive testing and pipeline integrity engineering, constraining service provider capacity expansion.
- Bi-Directional Launcher Retrofit Costs:Legacy pipeline systems lacking pig trap infrastructure require substantial capital investment to enable intelligent pigging access, particularly in remote gathering networks.
Strategic Opportunities
- Carbon Capture Transport Networks:CO2 pipeline operators in the United States and Canada require corrosion monitoring adapted to supercritical fluid conditions, opening specialized service niches for ultrasonic wall-thickness measurement providers.
- Real-Time Data Telemetry:Integration of fiber-optic cable piggyback systems with electromagnetic inspection tools enables immediate anomaly alerting, reducing response latency for critical sour gas lines.
- India Pipeline Safety Directives:The Petroleum and Natural Gas Regulatory Board is mandating systematic integrity assessments on aging cross-country pipelines, creating first-mover advantages for certified international service providers.
Industry Challenges
- Multi-Vendor Data Harmonization:Operators running sequential inspections from different service providers face incompatible data formats and coordinate reference systems, complicating longitudinal corrosion trend analysis.
- Sensor Calibration Drift:Electromagnetic tool performance degrades in high-temperature heavy crude environments, requiring frequent in-field verification against reference standards that disrupt inspection scheduling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intelligent Pigging Services Market |
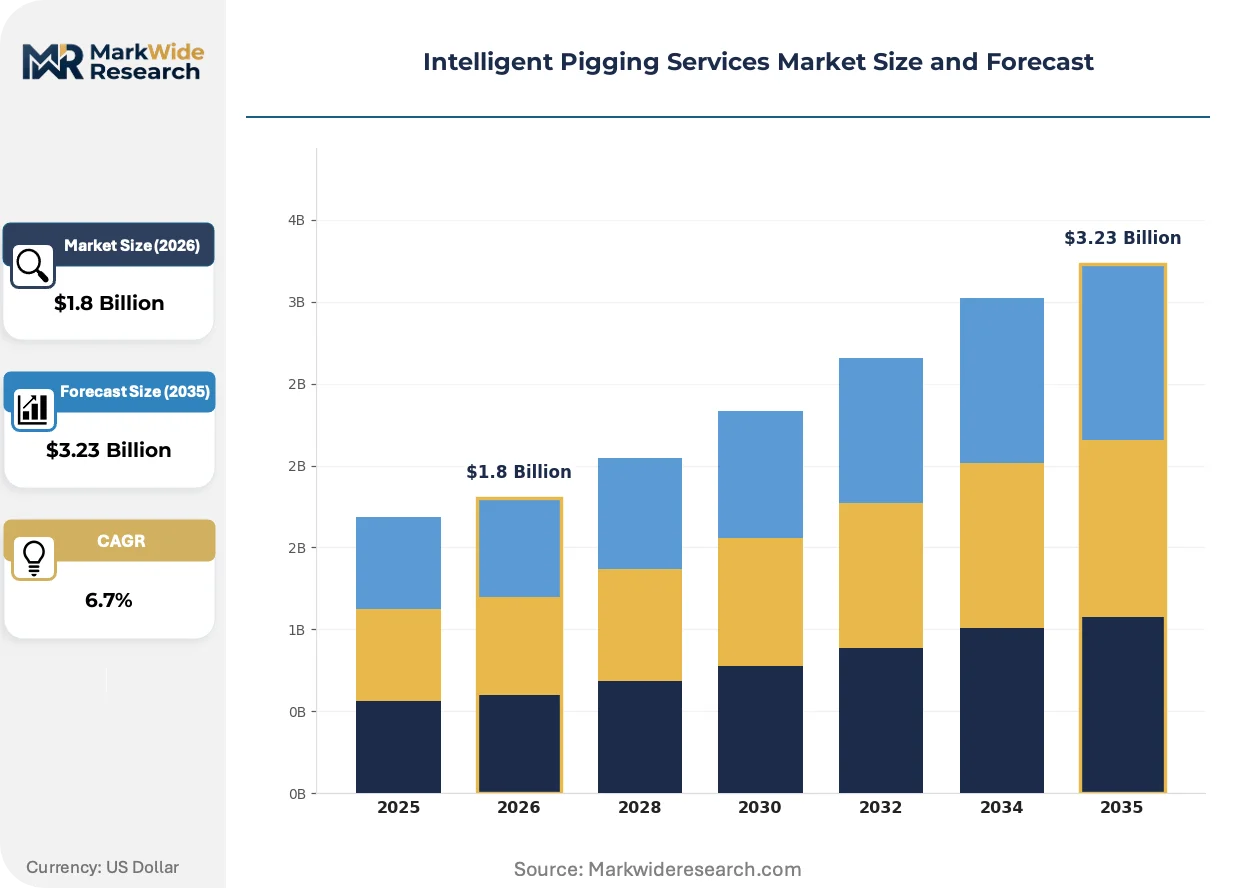
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Inline Inspection, Cleaning, Data Acquisition, Corrosion Monitoring Industry Vertical: Oil & Gas, Water & Wastewater, Chemical Processing, Power Generation Delivery Mode: Onshore, Offshore, Remote Monitoring, Centralized Services Technology: Electromagnetic, Ultrasonic, Magnetic Flux Leakage, Acoustic |
| Companies Covered | ROSEN Group, Baker Hughes Company, T.D. Williamson, NDT Global, Applus+, SGS SA, Enduro Pipeline Services, Pipeline Integrity International, LIN SCAN, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intelligent Pigging Services Market Strategic Shifts
Sensor fusion architectures and autonomous navigation capabilities are compressing inspection timelines while elevating detection precision for crack-like anomalies in challenging pipeline geometries.
Tri-axial magnetic flux leakage sensor arrays with integrated inertial measurement units are electrifying defect characterization capabilities for spiral weld anomalies and axial cracking in seam-welded lines. Offshore operators in the Gulf of Mexico and North Sea are deploying these enhanced tools for unpiggable pipeline sections previously requiring costly excavation or direct assessment. The technology is compressing the trade-off between inspection speed and anomaly resolution that has historically constrained operational scheduling windows.
The EU Pipeline Safety Directive's 2024 amendments mandate traceable calibration records and third-party tool verification for all high-consequence area inspections, elevating certification burdens for service providers. German and Dutch regulators are enforcing these provisions through unannounced field audits of inspection data quality and tool maintenance logs. Midstream operators are responding by consolidating vendor relationships with certified providers holding multiple national accreditations.
Integrated service contracts bundling inspection execution with integrity management software subscriptions are displacing transactional per-kilometer pricing in mature pipeline corridors. Major United States midstream operators now demand predictive analytics dashboards and remaining-life calculations as standard deliverables alongside raw inspection data. This bundling is most advanced in the Permian Basin and Appalachia shale plays where operator consolidation has concentrated procurement authority with fewer buyers.
Intelligent Pigging Services Market Segmentation
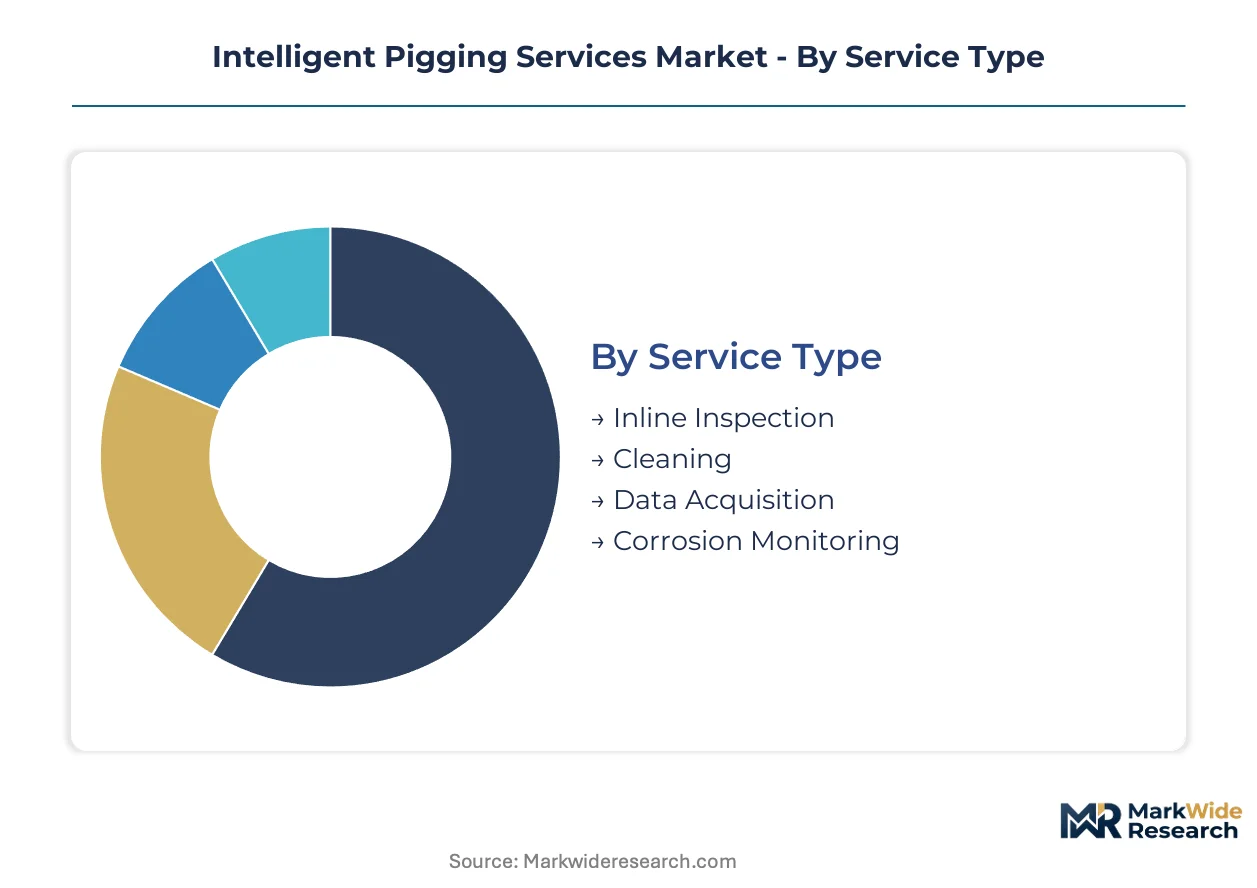
Intelligent pigging services fragment across four distinct axes that determine tool selection, deployment economics, and operator procurement patterns. Technology specifications dictate sensor array configurations, while delivery mode constraints shape logistics and scheduling windows. Service type and industry vertical classifications further refine contract structures and compliance requirements.
Technology:
Sensor modality selection determines detection resolution, material compatibility, and calibration protocols for pressurized pipeline inspection.
- Magnetic Flux Leakage:Tri-axial sensor arrays detect volumetric metal loss and general corrosion patterns through magnetization of pipe wall steel. PHMSA baseline assessment mandates in the United States sustain recurring demand cycles for this mature technology in high-consequence area networks.
- Ultrasonic:High-resolution pulse-echo and phased-array configurations enable crack detection precision and wall-thickness measurement in high-strength steel lines. European hydrogen pipeline repurposing initiatives are accelerating calibration investments for embrittlement-sensitive material inspection.
- Electromagnetic:Eddy-current and remote-field sensing modalities assess near-surface anomalies without direct fluid coupling requirements. Offshore operators in the Gulf of Mexico deploy these tools for unpiggable sections where conventional launcher access is restricted.
- Acoustic:Passive and active acoustic monitoring detects leak signatures and third-party interference events through pipeline wall vibration analysis. Water and wastewater utilities favor this modality for non-metallic pipe materials where magnetic methods prove ineffective.
Mature deployment sits with magnetic flux leakage systems. Newer deployment is concentrated in ultrasonic configurations for crack-sensitive hydrogen infrastructure.
Service Type:
Contract scope ranges from discrete tool runs to integrated integrity management subscriptions with predictive analytics deliverables.
- Inline Inspection:Instrumented pig deployment for geometric mapping, metal loss quantification, and anomaly location referencing using inertial measurement units. Midstream operators in the Permian Basin and Appalachia shale corridors bundle these services with remaining-life calculation software.
- Cleaning:Progressive-density foam, brush, and scraper pig sequences remove wax, scale, and debris to prepare lines for inspection tool passage. Pre-inspection cleaning mandates from German and Dutch regulators under EU Pipeline Safety Directive amendments elevate service frequency in North Sea corridors.
- Data Acquisition:Raw sensor signal capture with coordinate referencing and initial quality verification before analyst interpretation. Real-time telemetry integration through fiber-optic piggyback systems is compressing response latency for critical sour gas lines.
- Corrosion Monitoring:Longitudinal trend analysis combining sequential inspection datasets to model degradation rates and predict intervention timing. Carbon capture transport operators require adapted protocols for supercritical CO2 conditions in United States and Canadian pipeline networks.
Revenue concentration favors inline inspection contracts. Subscription bundling is expanding fastest in corrosion monitoring with integrated software platforms.
Delivery Mode:
Physical deployment constraints determine crew mobilization costs, tool tethering requirements, and scheduling flexibility.
- Onshore:Standard launcher and receiver trap configurations enable routine pigging access across transmission and distribution networks. Bi-directional trap retrofits for legacy gathering systems in remote locations impose capital barriers to service addressability.
- Offshore:Subsea deployment through platform-based traps or tethered inspection tools for pipeline sections lacking surface infrastructure. Extended North Sea and Gulf of Mexico decommissioning timelines sustain demand for geometric anomaly mapping in aging subsea corridors.
- Remote Monitoring:Continuous sensor telemetry and anomaly alerting without full inspection tool mobilization. Fiber-optic integration with electromagnetic tools enables immediate response protocols for critical infrastructure segments.
- Centralized Services:Hub-and-spoke logistics models consolidating tool maintenance, calibration, and data processing at regional facilities. Vendor consolidation trends among United States midstream operators favor providers with multi-national accreditation portfolios.
Volume leadership remains with onshore deployment. Offshore applications command premium pricing tiers due to specialized tooling and crew certification requirements.
Industry Vertical:
End-use specifications dictate fluid compatibility, pressure-temperature ratings, and regulatory compliance frameworks.
- Oil & Gas:Crude oil, natural gas, and refined product pipelines requiring systematic integrity assessment under PHMSA and EU Pipeline Safety Directive mandates. Hydrogen blending infrastructure in European networks demands recalibrated crack detection protocols.
- Water & Wastewater:Potable water transmission and sewage force mains with corrosion monitoring focused on cement-mortar lining degradation and microbially induced corrosion. Municipal procurement patterns favor lowest-cost compliant bids over technology differentiation.
- Chemical Processing:Specialized product and feedstock lines with material compatibility constraints for aggressive chemistries. Inspection scheduling must accommodate batch campaign interruptions and clean-in-place verification cycles.
- Power Generation:Hydrogen transport and carbon capture pipelines emerging from utility decarbonization commitments. Baker Hughes Company and NDT Global are positioning electromagnetic and ultrasonic portfolios for emerging hydrogen infrastructure codes.
Contract value concentrates in oil and gas verticals. Power generation applications are climbing the fastest as hydrogen and CO2 pipeline networks expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Permian Basin tax-advantaged drilling zones concentrate pipeline construction activity, drawing intelligent pigging service providers to establish calibration facilities and regional headquarters near Midland-Odessa infrastructure corridors.
United States
PHMSA baseline assessment mandates drive recurring seven-year inspection cycles across high-consequence area networks spanning Texas, Louisiana, and Oklahoma. The Gulf Coast petrochemical corridor sustains the densest concentration of magnetic flux leakage and ultrasonic tool deployments, with Houston serving as the primary logistics hub for offshore Gulf of Mexico mobilizations.
Germany
The Ruhr industrial belt and North Sea pipeline corridors require systematic integrity assessments under EU Pipeline Safety Directive amendments mandating traceable calibration records. German regulators enforce these provisions through unannounced field audits, elevating certification burdens for service providers operating across the Emsland hydrogen repurposing initiatives and Bavarian chemical processing networks.
India
Petroleum and Natural Gas Regulatory Board mandates on aging cross-country pipelines create first-mover opportunities for certified international providers entering the Mumbai-Delhi industrial corridor. Gujarat's Jamnagar refining complex and the Hazira-Bijaipur-Jagdishpur pipeline network concentrate demand for inline inspection tool deployment and data interpretation services.
United Kingdom
Extended North Sea decommissioning timelines sustain demand for geometric anomaly mapping through Aberdeen-based service providers. The Oil and Gas Authority's stewardship expectations compel operators to accelerate inspection frequencies on aging subsea infrastructure, with Scottish clusters serving as the primary mobilization point for tethered inspection tool deployments.
Canada
Alberta's oil sands gathering networks and British Columbia's natural gas transmission corridors require specialized protocols for heavy crude and sour gas conditions. The Canada Energy Regulator's damage prevention regulations shape inspection frequency mandates across the Trans Mountain pipeline corridor and Coastal GasLink construction zones.
Intelligent Pigging Services Market Competitive Environment
Top-tier vendors anchor technology leadership through multi-sensor platform development, while mid-tier specialists concentrate on regional calibration services and data interpretation subscriptions. The vendor base stratifies across three functional tiers: integrated energy technology conglomerates with electromagnetic and ultrasonic portfolios; specialized inline inspection contractors with tool fabrication capabilities; and regional service brokers bundling third-party analytics with field execution. Consolidation pressures favor providers holding multiple national accreditations, particularly as EU and Indian regulators tighten certification requirements. Portfolio diversification into hydrogen-compatible sensor arrays and real-time telemetry integration represents the dominant competitive vector.
Among energy-technology conglomerates, Baker Hughes Company and T.D. Williamson exemplify the integrated service model spanning tool manufacturing through integrity management software subscriptions. NDT Global occupies a specialist position emphasizing high-resolution ultrasonic crack detection capabilities for critical sour gas applications. These three anchors illustrate the competitive tension between scale-driven bundled offerings and precision-focused technology differentiation in mature pipeline corridors.
| Leading Market Players |
|---|
| ROSEN Group |
| Baker Hughes Company |
| T.D. Williamson |
| NDT Global |
| Applus+ |
| SGS SA |
| Enduro Pipeline Services |
| Pipeline Integrity International |
| LIN SCAN |
| Others |
Value Chain & Pricing Dynamics
Certified pipeline integrity analysts concentrated in the United States Gulf Coast and North Sea corridors command wage premiums that compress service-provider margins and widen spreads between premium-certified and standard-tier inspection contracts. Labor-cost differentials between these specialized technician pools and emerging calibration hubs in India directly shape three-tier pricing structures across the market.
Pricing Analysis
Short lead-time premiums for emergency inspection mobilizations command 40-60% markups over scheduled deployments, while spot-market tool availability discounts appear during seasonal maintenance windows. Contract structures stratify across premium multi-year integrity management subscriptions, standard per-kilometer inline inspection rates, and economy-tier cleaning-only services. Price differentiation hinges on PHMSA certification tier and real-time telemetry bundling. Cost compression in the standard tier intensifies as regional service brokers consolidate procurement authority. Municipal water utilities exhibit the highest price sensitivity, while offshore operators in the Gulf of Mexico demonstrate minimal elasticity for certified subsea deployments.
Supply Chain Analysis
High-resolution ultrasonic transducer supply rests on German and Japanese precision sensor manufacturers, with magnetic flux leakage magnet assemblies drawing from Chinese and South Korean steel foundries. Specialized inertial measurement units source from United States and Israeli defense-aerospace suppliers. Raw material dependencies span rare-earth magnet alloys, piezoelectric ceramics, and fiber-optic telemetry cables. Single-source vulnerability concentrates in tri-axial magnetic sensor arrays from two dominant European producers. Distribution runs through Houston and Aberdeen logistics hubs serving regional pipeline corridors, with centralized calibration facilities in Rotterdam and Singapore anchoring Asia-Pacific service networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as tool manufacturers acquire data analytics platforms to capture recurring software subscription revenue. Backward integration into captive sensor production represents the dominant upstream lever players are pursuing.
For Market Incumbents: Anticipate margin compression from regional service brokers bundling third-party analytics with discounted field execution. Defend position by consolidating multi-national PHMSA and EU Pipeline Safety Directive accreditations into unified certification portfolios. Accelerate in-house production of hydrogen-compatible sensor arrays to reduce dependency on external transducer suppliers. For New Entrants and Emerging Players: The Petroleum and Natural Gas Regulatory Board mandates in India open a window for certified international providers to establish first-mover positions in the Mumbai-Delhi industrial corridor. Target carbon capture transport operators in Alberta and Texas requiring adapted ultrasonic protocols for supercritical CO2 conditions. Pursue white-label data interpretation partnerships with established tool manufacturers lacking analyst capacity. For Investors and Strategic Acquirers: Re-rating potential sits with mid-tier specialists holding dual electromagnetic and ultrasonic capabilities given hydrogen infrastructure code finalization. Long-term viability favors providers with integrated software platforms and recurring revenue exposure over transactional inspection contractors. Monitor German and Dutch regulatory audit intensity as an inflection indicator for certification-premium sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Platform Development | Tri-axial magnetic arrays with integrated IMUs elevate detection precision for spiral weld anomalies in seam-welded lines. |
| Hydrogen Compatibility Certification | Recalibrated crack detection protocols unlock European natural gas network repurposing initiatives under amended EU codes. |
| Real-Time Telemetry Integration | Fiber-optic piggyback systems with electromagnetic tools compress response latency for critical sour gas infrastructure. |
| Regional Calibration Hub Expansion | Centralized facilities in Rotterdam and Singapore reduce mobilization costs for Asia-Pacific and North Sea corridors. |
| Predictive Analytics Subscription Bundling | Remaining-life calculation software displaces per-kilometer pricing in Permian Basin and Appalachia shale plays. |
Study Parameters
Document review covered PHMSA incident databases, EU Pipeline Safety Directive amendments, and ISO 13847 welding standards, complemented by interviews with pipeline integrity managers at United States midstream operators, inline inspection tool engineers at electromagnetic technology providers, and procurement leads at North Sea offshore consortia. Secondary validation drew from Canada Energy Regulator filings, Petroleum and Natural Gas Regulatory Board circulars, and industry association maintenance logs. Bottom-up segmentation modeling triangulated against top-down energy infrastructure capex forecasts.
Historical inspection frequency patterns cross-referenced against regulatory panel input on mandate enforcement intensity shaped the analytical framework across the analysis window. Segmentation dimensions modeled include sensor modality, service type contract scope, delivery mode constraints, and industry vertical specifications. CAGRs derived from pipeline mileage expansion projections, integrity management rule compliance cycles, and hydrogen infrastructure deployment timelines.
Caveats apply where PHMSA rulemaking on hydrogen blending standards or EU tool verification audit protocols could materially shift the outlook. Forecasts reflect assumptions regarding technician training pipeline throughput and rare-earth magnet supply continuity. A small set of named triggers—German unannounced field audit intensity, Indian regulatory accreditation timelines, and ultrasonic transducer import restrictions—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Underreamers Market
Oil & Gas
Offshore Oil and Gas Paints and Coatings Market
Oil & Gas
India Natural Gas Market
Oil & Gas
Oil and Gas Nuclear Magnetic Resonance Market
Oil & Gas
Asia-Pacific Oilfield Auxiliary Rental Equipment Market
Oil & Gas
Saudi Arabia Liner Hanger System Market
Oil & Gas
Oilwell Completion Tools Market
Oil & Gas
Asia-Pacific Digital Oilfield Market
Oil & Gas
Logging While Drilling (LWD) Market
Oil & Gas
Connected Oil and Gas Market
Oil & Gas
Crude Oil Desalter Market
Oil & Gas
Drilling Fluids Market
Oil & Gas
Injection Well Market
Oil & Gas
Floating Skimmer Market
Oil & Gas
Oriented Perforating System Market
Oil & Gas
Africa Oil Refining Market