
 Egypt Oil and Gas Market | 2026-2036
Egypt Oil and Gas Market Size, Share, and Industry Trends Forecast 2026-2036
Egypt Oil and Gas Market Analysis
Market Context
Offshore concession licensing is reshaping how international operators access Egypt's Mediterranean gas provinces. Eni leverages its Zohr field infrastructure to sustain development drilling across adjacent blocks. BP anchors deepwater exploration through partnership structures with Egyptian General Petroleum Corporation. Apache competes in the Western Desert through tight gas development and established pipeline connections.
Technical Definition and Segment Structure
Egypt oil and gas encompasses hydrocarbon exploration, production, processing, and distribution systems spanning onshore basins and offshore Mediterranean waters, with reservoirs typically requiring seismic imaging and directional drilling at depths exceeding 3,000 meters to reach productive formations. The upstream application dominates current investment flows as operators target undeveloped Mediterranean reserves. Enhanced oil recovery technology leads growth potential within mature onshore fields where natural drive mechanisms have depleted. Distribution services occupy established margin pools through pipeline networks serving Cairo-Alexandria industrial corridors.
Regulatory Framework
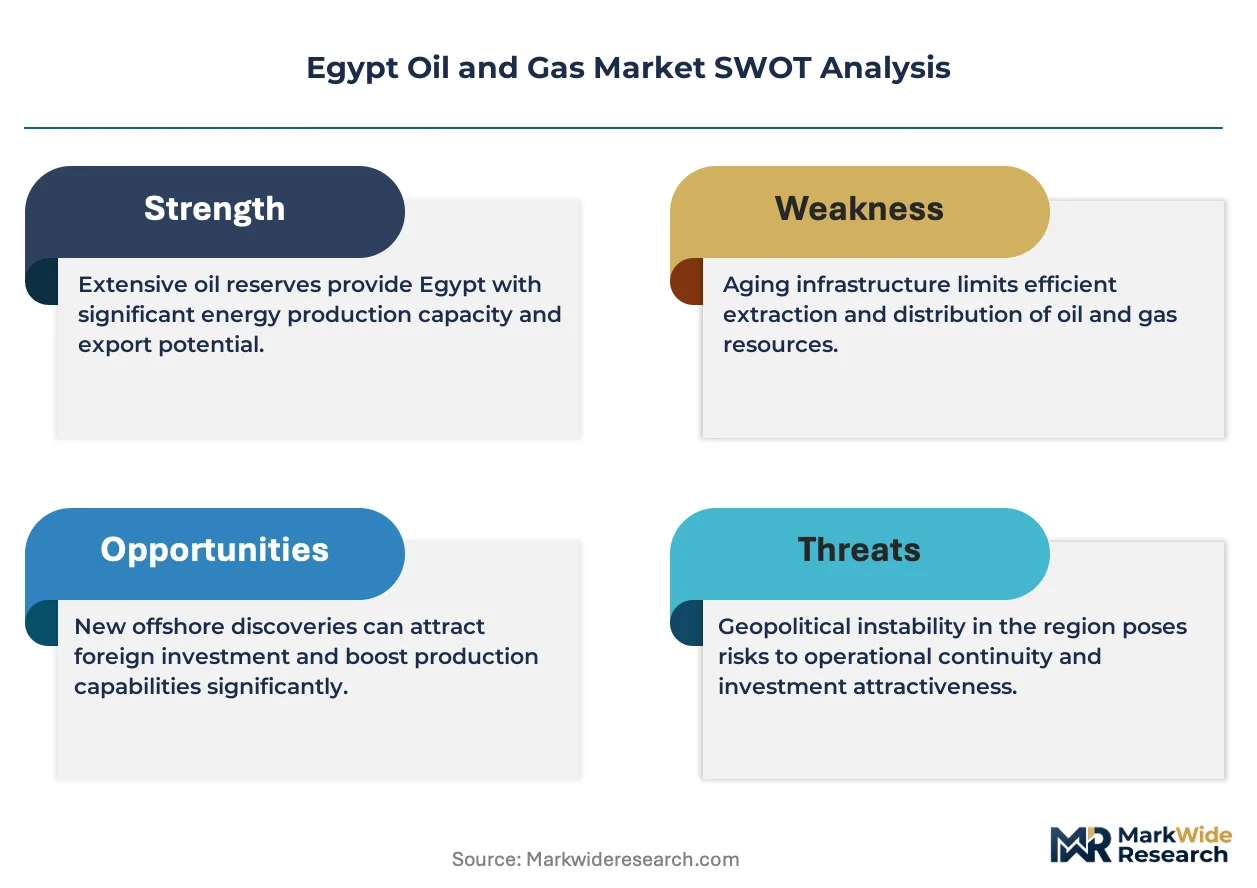
Egyptian General Petroleum Corporation and the Ministry of Petroleum coordinate concession terms, while environmental compliance follows frameworks aligned with ISO standards and national air quality directives. These regulatory structures shape drilling permit timelines, local content requirements, and emission thresholds for offshore platforms. Stakeholders must monitor licensing round terms and domestic gas pricing formulas that determine project economics.
Market Dynamics
Offshore Mediterranean licensing rounds are redrawing concession boundaries as international operators compete for access to deepwater gas provinces, with the Petroleum Ministry's accelerated block releases compressing traditional exploration timelines.
Growth Catalysts
- Mediterranean Block Licensing:The Petroleum Ministry's accelerated concession rounds are opening access to undeveloped offshore gas provinces. International operators are securing exploration rights in frontier blocks adjacent to producing fields.
- Power Generation Utilities:Egyptian electricity producers are expanding natural gas offtake volumes to stabilize grid operations. This demand concentration supports production commitments from Nile Delta and Western Desert corridors.
- Enhanced Recovery Technology:Mature onshore fields are deploying advanced extraction methods to sustain output from depleted reservoirs. Directional drilling and seismic imaging are improving recovery rates in established production zones.
Market Restraints
- Domestic Gas Pricing Formulas:Egyptian General Petroleum Corporation's administered price structures compress project economics for new field developments. Operators face margin pressure when global benchmarks diverge from local contract rates.
- Deepwater Technical Complexity:Mediterranean reservoirs at depths exceeding 3,000 meters require specialized drilling rigs and subsea infrastructure. Equipment availability constraints and technical service scarcity limit development pace.
- Local Content Requirements:Concession terms mandate minimum Egyptian workforce participation and domestic supplier procurement. Compliance timelines extend project planning cycles and raise operational coordination costs.
Strategic Opportunities
- Western Desert Tight Gas:Unconventional formations in Egypt's western production corridor remain underdeveloped relative to Mediterranean offshore focus. Operators with established pipeline connections can expand tight gas extraction using existing infrastructure.
- Cairo-Alexandria Industrial Corridor:Petrochemical and manufacturing clusters along this axis are absorbing incremental gas supply for process heat and feedstock. Direct pipeline connections to concentrated demand pools improve offtake certainty.
- Environmental Compliance Alignment:ISO-standard frameworks and national air quality directives are creating certification premiums for low-emission production methods. Early adopters of emission-threshold compliance gain preferential licensing consideration.
Industry Challenges
- Subsea Engineering Talent:Deepwater Mediterranean development requires specialized expertise in high-pressure reservoir management and subsea installation. Egyptian technical universities produce limited graduates in these niche disciplines.
- Legacy Infrastructure Integration:New offshore platforms must connect to existing processing and pipeline networks originally designed for shallower conventional fields. Retrofit requirements add capital intensity to greenfield developments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Egypt Oil and Gas Market |
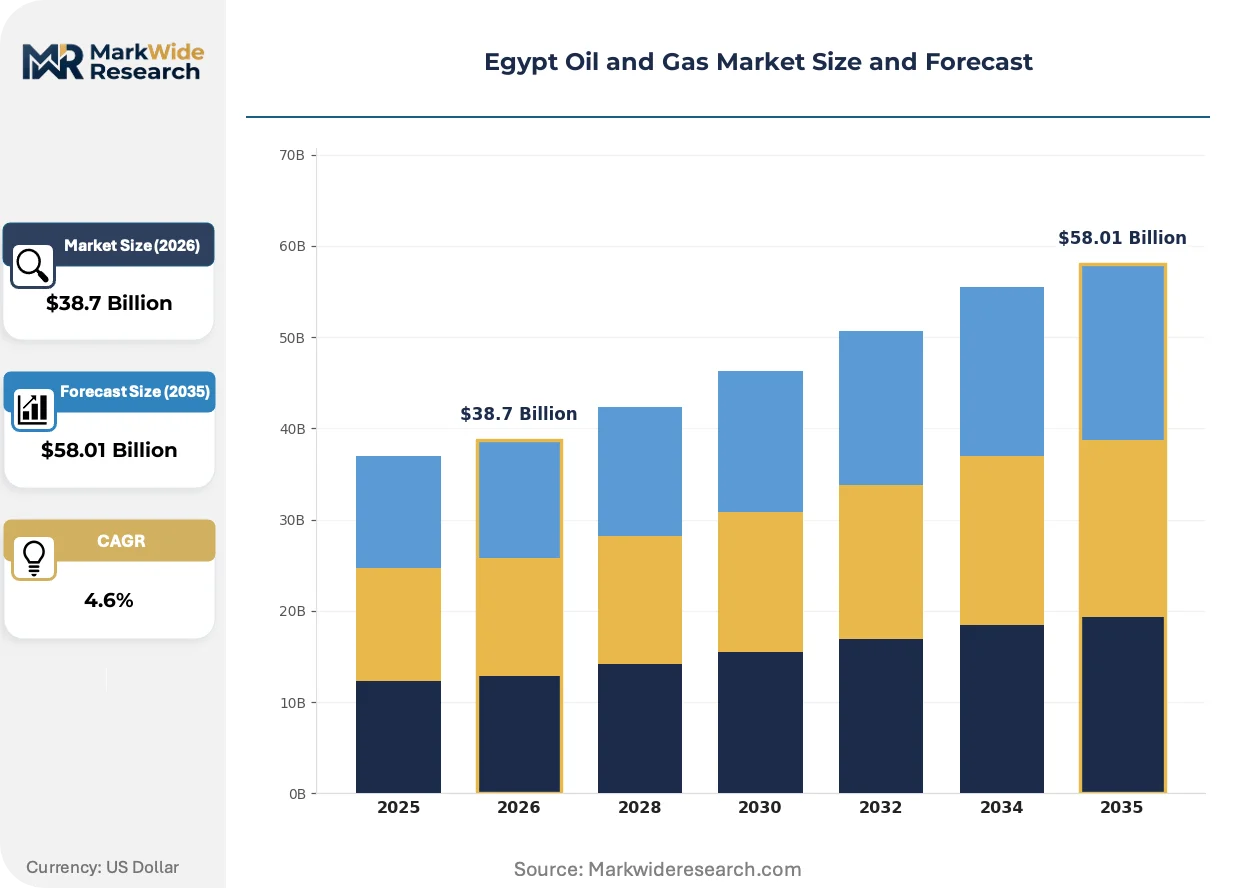
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $58.01 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Exploration, Production, Refining, Distribution Technology: Drilling, Enhanced Oil Recovery, Seismic Imaging, Automation Application: Upstream, Midstream, Downstream, LNG End User: Industrials, Power Plants, Chemical Manufacturers, Others |
| Companies Covered | TotalEnergies, Egyptian General Petroleum Corporation, BP, Apache, Eni, ExxonMobil, Chevron, KUFPEC, Shell, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Egypt Oil and Gas Market Emerging Trajectories
Digital reservoir characterization and automated drilling systems are compressing exploration-to-production cycles across Egyptian offshore concessions, while regulatory frameworks evolve to accommodate frontier development.
Directional drilling technology is migrating from conventional onshore applications to deepwater Mediterranean environments. Offshore operators are adopting extended-reach drilling systems to access multiple reservoir targets from single platform locations. This migration from jack-up rigs to floating production units is enabling development of scattered gas accumulations previously deemed uneconomic.
Egyptian General Petroleum Corporation has tightened environmental compliance protocols for offshore platforms, aligning emission thresholds with ISO 14001 standards and Mediterranean marine protection directives. Operators must now submit detailed spill-response plans and continuous monitoring systems before drilling permits issue. Deepwater exploration segments face the steepest compliance burden, with Mediterranean blocks requiring enhanced baseline environmental assessments.
Industrial gas buyers in the Cairo-Alexandria corridor are consolidating procurement through long-term supply agreements with minimum volume commitments. This concentration is displacing spot-market transactions and forcing distributors to offer integrated logistics and storage services. Petrochemical complexes along the Suez Canal axis are driving this shift, seeking price predictability for multi-year expansion programs.
Egypt Oil and Gas Market Segmentation
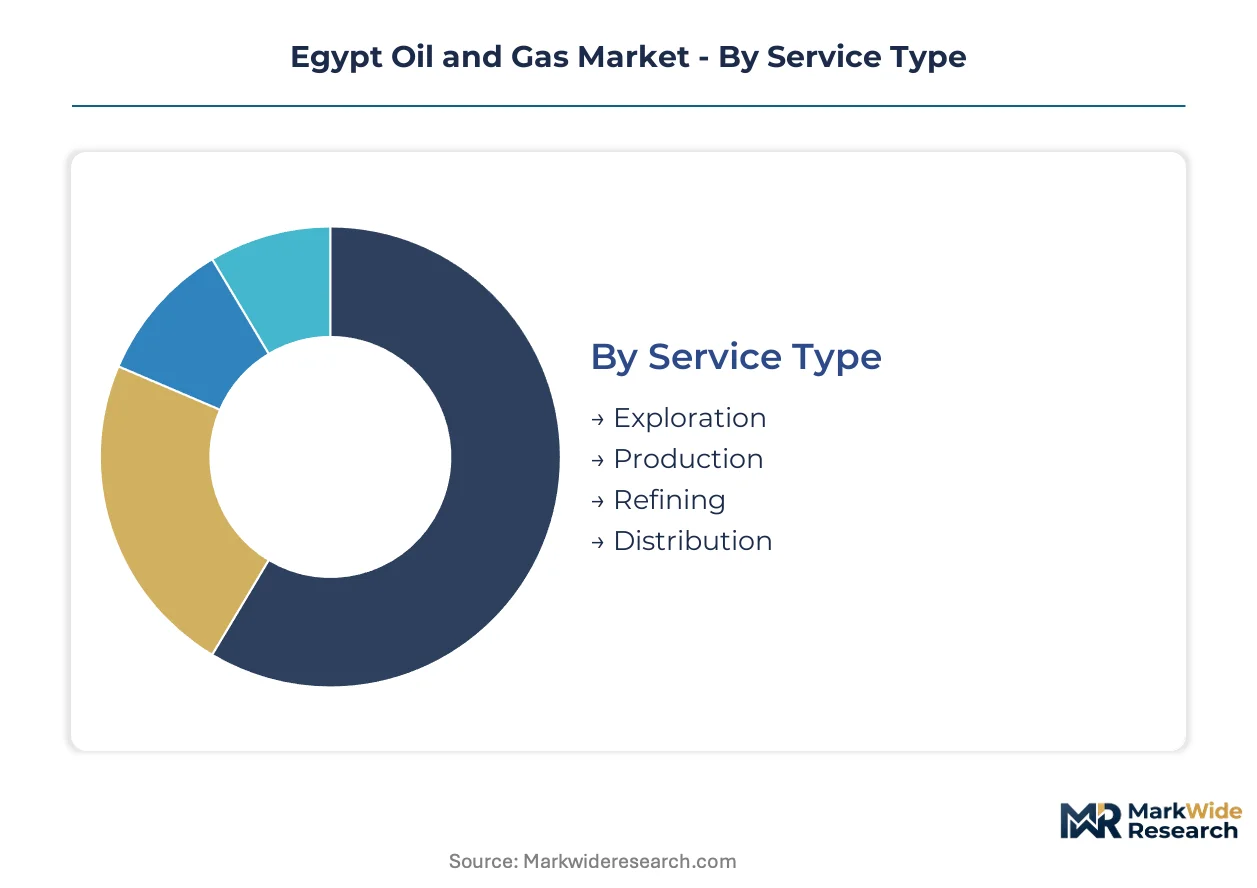
Egypt's hydrocarbon value chain fragments across distinct operational layers, each commanding specialized capital deployment and regulatory engagement. Understanding these segment boundaries clarifies where Egyptian General Petroleum Corporation concentrates licensing leverage versus where international operators retain technical autonomy.
Service Type:
Mature production services dominate revenue pools while frontier exploration commands premium contract terms.
- Exploration:Seismic surveying and wildcat drilling target undeveloped Mediterranean blocks and Western Desert frontiers. Egyptian General Petroleum Corporation's accelerated concession rounds are compressing traditional exploration timelines as international operators compete for deepwater access.
- Production:Reservoir management and extraction operations span Zohr field infrastructure, Western Desert tight gas corridors, and mature Nile Delta concessions. Power generation utilities in Cairo-Alexandria industrial zones anchor offtake commitments that sustain production economics.
- Refining:Crude processing and product upgrading serve domestic fuel specifications and petrochemical feedstock requirements. Refining capacity concentrates around Suez Canal axis facilities with pipeline connections to Red Sea terminals.
- Distribution:Pipeline networks and storage terminals link production zones to concentrated demand pools. Cairo-Alexandria industrial corridor absorbs the majority of transported volumes through dedicated high-pressure trunk lines.
Production retains volume leadership; exploration holds the steepest expansion curve.
Technology:
Cost tier stratification separates commoditized drilling services from premium recovery technologies requiring specialized engineering partnerships.
- Drilling:Directional and extended-reach systems access multiple reservoir targets from single platform locations. Mediterranean deepwater developments at depths exceeding 3,000 meters require floating production units and specialized high-pressure equipment.
- Enhanced Oil Recovery:Advanced extraction methods including gas injection and thermal stimulation sustain output from depleted onshore reservoirs. Mature Western Desert fields deploy these technologies to offset natural production decline.
- Seismic Imaging:3D and 4D subsurface characterization guides exploration targeting and reservoir optimization. Processing algorithms interpret complex Mediterranean geology where salt formations obscure conventional survey methods.
- Automation:Digital monitoring and automated drilling systems compress exploration-to-production cycles. Offshore platforms integrate continuous emission monitoring to satisfy Egyptian General Petroleum Corporation's tightened environmental compliance protocols.
Drilling commands the largest installed base; automation is climbing the fastest.
Application:
Customer type concentration varies sharply across the value chain, with upstream catering to international operators and downstream serving state-linked offtakers.
- Upstream:Exploration and production activities targeting hydrocarbon extraction from subsurface reservoirs. Mediterranean offshore blocks and Western Desert onshore concessions constitute the primary investment focus under current licensing terms.
- Midstream:Transportation and storage infrastructure connecting production zones to processing facilities and export terminals. Pipeline networks serving the Nile Delta and Suez Canal corridor carry the majority of domestic gas volumes.
- Downstream:Refining, marketing, and petrochemical processing of crude oil and natural gas liquids. Industrial clusters along the Cairo-Alexandria axis absorb refined products for manufacturing process heat and chemical synthesis.
- LNG:Liquefaction and regasification infrastructure for natural gas export and import flexibility. Egyptian LNG terminals provide swing supply capacity to regional Mediterranean markets.
Upstream retains volume leadership; LNG holds the steepest expansion curve.
End User:
Margin structure differs across customer categories, with power plants securing administered pricing and chemical manufacturers negotiating long-term supply agreements.
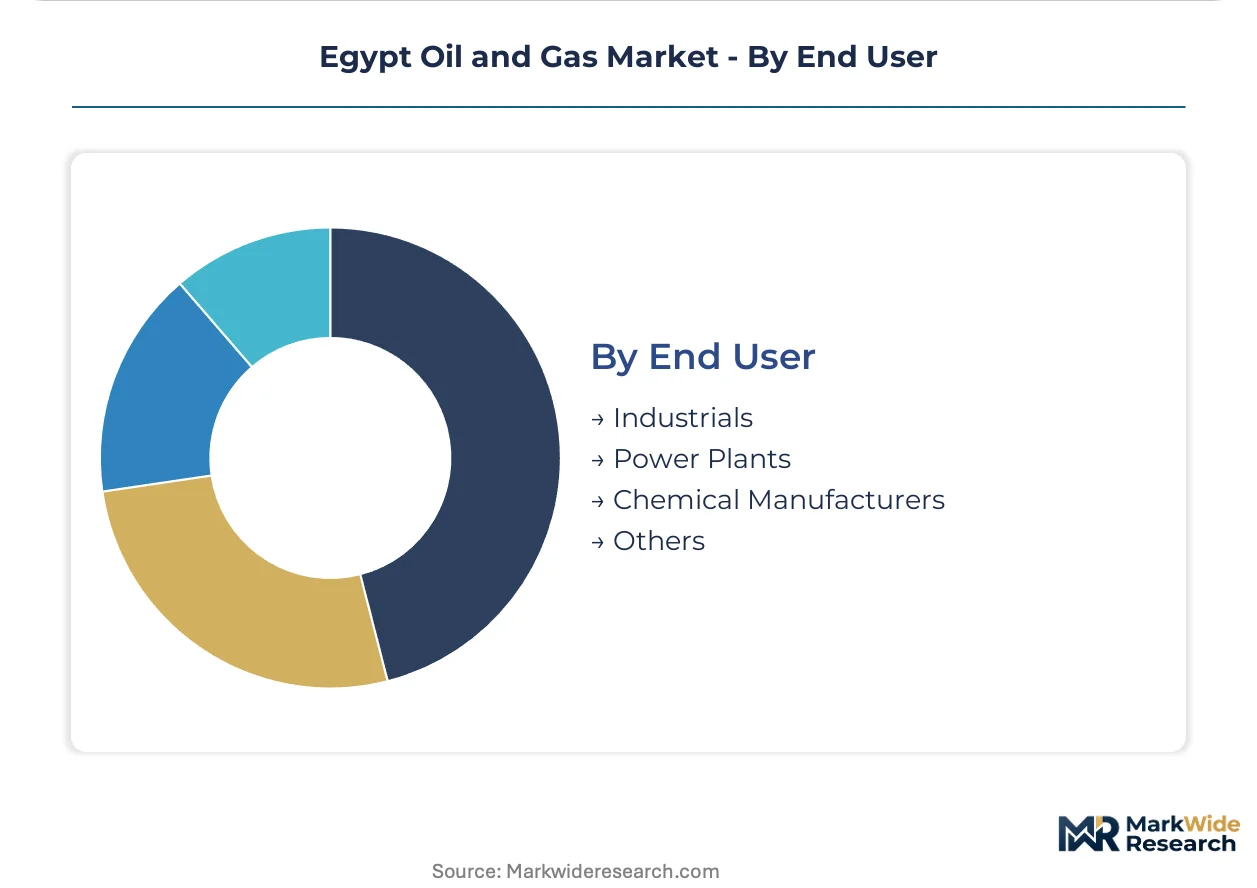
- Industrials:Manufacturing facilities consuming natural gas for process heat, mechanical power, and onsite generation. Textile, cement, and steel producers in the Delta region represent concentrated demand pockets with pipeline access.
- Power Plants:Electricity generation utilities expanding gas-fired capacity to stabilize grid operations. Egyptian Electricity Holding Company procurement drives the majority of domestic gas offtake volume growth.
- Chemical Manufacturers:Petrochemical complexes requiring feedstock gas for ammonia, methanol, and olefin production. Suez Canal Economic Zone developments are consolidating multi-year supply agreements with minimum volume commitments.
- Others:Residential, commercial, and transportation sector consumption through compressed natural gas and piped distribution networks. Urban centers in Greater Cairo and Alexandria account for the bulk of non-industrial demand.
Power plants retain volume leadership; chemical manufacturers hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Sumed Pipeline anchors Egypt's hydrocarbon corridor, transporting crude from the Red Sea to Mediterranean terminals while the Zohr gas field infrastructure underwrites offshore development in the Nile Delta basin.
Nile Delta
Power generation utilities and petrochemical complexes drive gas offtake demand across this northern corridor. Egyptian General Petroleum Corporation's administered pricing formulas shape procurement economics for industrial buyers. Port Said and Damietta host LNG export terminals serving regional Mediterranean markets.
Western Desert
Tight gas formations and mature oilfields sustain production through enhanced recovery methods in this onshore province. Apache Corporation operates established pipeline networks connecting wells to processing facilities. Mersa Matruh serves as the logistical hub for equipment staging and workforce deployment.
Suez Canal Economic Zone
Refining and petrochemical investments concentrate along this axis, absorbing natural gas for process heat and chemical synthesis. The Petroleum Ministry's special economic zone incentives accelerate project timelines for integrated complexes. Ain Sokhna hosts the majority of new capacity additions under construction.
Mediterranean Offshore
Deepwater exploration targets gas reservoirs at depths exceeding 3,000 meters across licensed concession blocks. Eni leverages existing Zohr field infrastructure to sustain development drilling in adjacent acreage. Alexandria maintains subsea engineering capabilities and supply base operations for offshore campaigns.
Red Sea Coast
Import terminals and storage facilities provide supply flexibility for domestic consumption and re-export arrangements. Sumed Pipeline operations require continuous maintenance and security coordination. Safaga and Hurghada support offshore logistics for southern Red Sea exploration permits.
Egypt Oil and Gas Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream supplying discrete technical services. Egyptian General Petroleum Corporation anchors state-controlled concessions while international operators compete for Mediterranean block access. Three archetypes define competitive positioning: national oil companies holding concession authority, integrated majors deploying capital at scale, and independent specialists targeting niche formations. Consolidation through farm-in agreements and joint venture structures accelerates as operators share deepwater development risk.
Among European-headquartered majors, Eni and BP occupy positions as archetypal platform integrators leveraging existing infrastructure for adjacent block development. Apache Corporation exemplifies the independent specialist model, concentrating tight gas extraction in the Western Desert through established pipeline connections. Egyptian General Petroleum Corporation anchors the national oil company tier, coordinating concession terms and domestic offtake arrangements across all producing provinces.
| Leading Market Players |
|---|
| TotalEnergies |
| Egyptian General Petroleum Corporation |
| BP |
| Apache |
| Eni |
| ExxonMobil |
| Chevron |
| KUFPEC |
| Shell |
| Others |
Supply Flow & Price Mechanics
Commodity price volatility in global LNG benchmarks determines both contract-tier spreads and supply chain configuration across Egyptian gas procurement. Egyptian General Petroleum Corporation's administered pricing formulas tether domestic offtake rates to international spot indices, compressing margins for operators when global benchmarks spike while insulating industrial buyers from volatility.
Pricing Analysis
Volume-discount tiering structures dominate gas supply contracts across the Cairo-Alexandria industrial corridor. Egyptian Electricity Holding Company secures administered rates through multi-year offtake agreements with minimum volume commitments, while petrochemical complexes negotiate feedstock pricing tied to international ammonia and methanol benchmarks. Price differentiation hinges on contract duration and delivery reliability guarantees rather than quality grades. Cost compression in spot-market tiers is intensifying because industrial buyers are consolidating procurement through direct pipeline connections, bypassing intermediaries. Chemical manufacturers exhibit highest price sensitivity due to feedstock cost exposure, whereas power plants tolerate premium pricing for grid stability assurance.
Supply Chain Analysis
Export-control regimes on subsea drilling technology from the United States and European Union constrain equipment flows into Mediterranean deepwater developments. Egypt's offshore supply chain draws from specialized fabricators in Italy, Norway, and South Korea for high-pressure blowout preventers and subsea trees. Raw material dependencies center on specialty steel alloys, high-performance elastomers, and advanced electronics for downhole measurement systems. Single-source vulnerability concentrates in subsea engineering talent pools, where Mediterranean basin expertise remains limited to a handful of contractor firms. Distribution runs through Alexandria's port facilities and Mersa Matruh logistics hubs for Western Desert campaigns.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Egypt's oil and gas sector represents an early-cycle expansion story anchored by Mediterranean licensing rounds accelerating frontier block access. Unconventional tight gas penetration in the Western Desert remains below technical potential, creating whitespace for infrastructure-led development.
For Market Incumbents: Pre-empt competitive encroachment by securing farm-in positions on adjacent Mediterranean blocks before rival operators establish infrastructure footprints. Deepen backward integration into subsea engineering capabilities through partnerships with Egyptian technical universities to offset talent scarcity. Prioritize environmental compliance certification under ISO 14001 frameworks to secure preferential licensing consideration from the Petroleum Ministry.
For New Entrants and Emerging Players: Pursue tight gas extraction opportunities in the Western Desert where Apache Corporation's pipeline networks reduce greenfield infrastructure requirements. Target petrochemical feedstock supply agreements in the Suez Canal Economic Zone, where minimum volume commitments provide offtake certainty. Lead with integrated logistics and storage service offerings to differentiate from commodity gas traders.
For Investors and Strategic Acquirers: The market sits at a licensing-acceleration phase that favors operators with established Mediterranean infrastructure and Egyptian General Petroleum Corporation relationships. Long-term viability hinges on portfolio exposure to both frontier offshore exploration and mature field enhanced recovery. Acquisition targets should demonstrate subsea execution capability or tight gas extraction expertise. Watch Mediterranean drilling permit issuance velocity as the inflection signal for capital deployment timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Mediterranean Block Farm-In Agreement | Shares deepwater development risk while leveraging Zohr field infrastructure for adjacent acreage. |
| Western Desert Tight Gas Capacity Expansion | Utilizes existing Apache pipeline networks to accelerate unconventional production timelines. |
| ISO 14001 Environmental Certification Program | Secures preferential licensing consideration from Egyptian General Petroleum Corporation for offshore permits. |
| Cairo-Alexandria Industrial Corridor Supply Contract | Locks in multi-year offtake commitments with Egyptian Electricity Holding Company procurement. |
| Subsea Engineering Talent Partnership | Addresses critical capability scarcity through Egyptian technical university curriculum development. |
Methodological Framework
The analysis maps upstream exploration, midstream transportation, downstream refining, and LNG infrastructure segments, each validated through petroleum ministry officials, international operator development executives, Egyptian General Petroleum Corporation planning officers, and subsea engineering contractors. Primary fieldwork combined structured interviews with secondary validation across EIA country analysis briefs, IEA natural gas market reports, Egyptian Ministry of Petroleum licensing round disclosures, and Suez Canal Economic Zone investment bulletins. Bottom-up project economics modeling triangulated against top-down sector expenditure forecasts.
Assumption sets held regulatory licensing velocity and domestic gas pricing formulas constant while varying international LNG benchmark trajectories and subsea equipment availability across the projection horizon. Segmentation dimensions modeled include service type, technology tier, application layer, and end-user category. CAGRs were derived from production volume build-ups and capital expenditure schedules across licensed concession blocks. Forecast inputs incorporated Mediterranean drilling success rates and Western Desert tight gas recovery factors.
Sensitivities concentrate around Petroleum Ministry licensing round frequency, Egyptian General Petroleum Corporation pricing formula adjustments, and subsea rig day-rate movements. Forecasts reflect documented assumptions on concession term stability and domestic demand growth trajectories. Material shifts in Mediterranean maritime boundary disputes or European Union technology export restrictions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Asia-Pacific Liner Hanger System Market
Oil & Gas
Asia-Pacific LNG Bunkering Market
Oil & Gas
Subsea Manifolds Market
Oil & Gas
Colombia Oil and Gas Midstream Market
Oil & Gas
Middle-East and Africa Liner Hanger System Market
Oil & Gas
Riserless Light Well Intervention Market
Oil & Gas
Europe Hydraulic Fracturing Market
Oil & Gas
Oil and Gas Fabrication Market
Oil & Gas
Republic of Congo Oil and Gas Market
Oil & Gas
Russia Oilfield Services Market
Oil & Gas
Mud Mixers Market
Oil & Gas
SCADA Oil and Gas Market
Oil & Gas
Middle-East Oil and Gas Line Pipe Market
Oil & Gas
Oil and Gas Infrastructure Market
Oil & Gas
Kazakhstan Oil and Gas Downstream Market
Oil & Gas
Coiled Tubing System Market