
 Oil and Gas Nuclear Magnetic Resonance Market | 2026-2036
Oil and Gas Nuclear Magnetic Resonance Market Size, Share, and Industry Trends Forecast 2026-2036
Oil and Gas Nuclear Magnetic Resonance Market Analytics
Multi-source procurement for NMR logging tools is hardening across North American shale operators. Weatherford International plc leverages its integrated drilling and evaluation portfolio to sustain long-term service contracts with supermajors. Baker Hughes Company anchors its position through in-house manufacturing of high-temperature spectrometer components. Schlumberger Limited competes by extending its digital platform connectivity into real-time NMR data streams.
Oil and Gas Nuclear Magnetic Resonance refers to spectroscopic instrumentation that applies pulsed radiofrequency energy to hydrogen nuclei in subsurface rock formations, measuring relaxation times to quantify fluid-filled porosity, permeability, and hydrocarbon composition at reservoir temperatures exceeding 175°C. The technology serves the petroleum industry by reducing uncertainty in reserve estimates and optimizing completion designs in low-permeability formations. Equipment categories dominate capital deployment, as downhole spectrometer probes require specialized pressure housings and high-gradient magnets that command premium pricing. Software segments exhibit the fastest structural expansion, driven by cloud-based inversion algorithms that transform raw decay curves into actionable petrophysical models. Time-Domain technology retains the largest installed base, though Hybrid systems are displacing conventional platforms in deepwater environments where signal-to-noise constraints intensify.
EPA methane emissions regulations and BSEE well integrity standards in the United States mandate validated formation evaluation methods that NMR logging satisfies through direct fluid typing without radioactive sources. The EU Green Deal's carbon border adjustment mechanisms push European oil producers toward precision reservoir management that minimizes unnecessary drilling. Stakeholders must monitor how evolving environmental compliance frameworks in multiple jurisdictions reshape capital allocation between exploration and reservoir optimization technologies.
Market Dynamics
Hybrid time-frequency domain sensors are compressing deployment timelines for unconventional shale operators while fragmenting competitive advantage away from legacy tool manufacturers with pure time-domain architectures.
Growth Catalysts
- EPA methane emissions regulations:Direct fluid typing without radioactive sources satisfies validated formation evaluation mandates, accelerating NMR logging substitution for conventional neutron-density tools in Permian Basin operations.
- Multi-well pad drilling intensity:Real-time porosity mapping reduces rig standby costs during horizontal completion design in West Texas and southeastern New Mexico unconventional plays.
- Cloud-based inversion algorithms:Software segments transform raw decay curves into actionable petrophysical models, compressing interpretation cycles from days to hours for upstream reservoir engineers.
Market Restraints
- High-temperature magnet supply concentration:Specialized pressure housings and high-gradient magnets for downhole spectrometer probes depend on limited North American and European precision manufacturing capacity.
- Deepwater signal-to-noise constraints:Conventional time-domain platforms face technical limitations in high-pressure, high-temperature formations exceeding 175°C reservoir conditions.
- Radioactive source substitution lag:Regulatory friction from BSEE well integrity standards creates compliance complexity for operators transitioning fully away from chemical source-based logging.
Strategic Opportunities
- Carbon border adjustment mechanisms:EU Green Deal incentives push European oil producers toward precision reservoir management that minimizes unnecessary drilling and associated scope 3 emissions.
- Digital platform connectivity:Real-time NMR data streams integrated with drilling automation systems create service differentiation for integrated oilfield service providers.
- Offshore Brazil pre-salt formations:Underpenetrated deepwater basins with complex carbonate reservoirs present white space for hybrid sensor deployment where signal resolution advantages compound.
Industry Challenges
- Petrophysicist specialization gap:Interpretation of T1-T2 relaxation spectra requires scarce cross-trained professionals fluent in both rock physics and electromagnetic theory.
- Legacy well log integration:Compatibility protocols for merging NMR outputs with decades of neutron-density archives create data governance complexity for supermajor reservoir databases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oil and Gas Nuclear Magnetic Resonance Market |
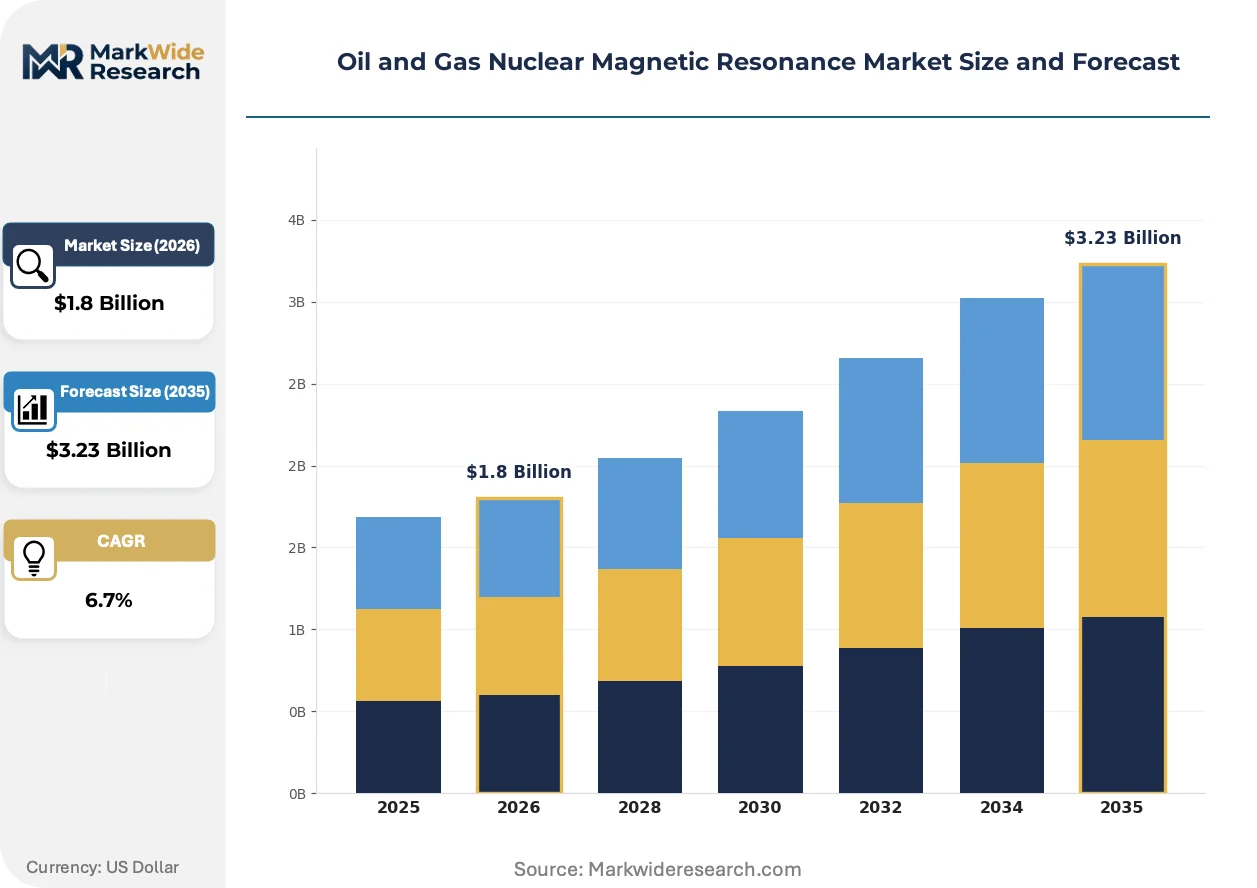
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analyzers, Equipment, Accessories, Software Technology: Time-Domain, Frequency-Domain, Hybrid, Advanced Imaging End User: Oil Producers, Gas Companies, Research Institutions, Service Providers Application: Reservoir Characterization, Fluid Analysis, Monitoring, Exploration |
| Companies Covered | Weatherford International plc, CNPC Logging Co., Ltd., Schlumberger Limited, Qteq Pty Ltd, Vista Clara Inc, Halliburton Company, Scientific Drilling International, Mount Sopris Instruments Inc., Baker Hughes Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oil and Gas Nuclear Magnetic Resonance Market Evolving Landscape
Sensor fusion architectures and computational inversion advances are restructuring how formation evaluation data moves from acquisition to decision, compressing the interval between raw measurement and completion design.
Hybrid time-frequency domain sensors is integrating pulsed radiofrequency encoding with continuous-wave detection to resolve both fast-diffusing bound fluids and slow-diffusing free hydrocarbons in single acquisition passes. Unconventional shale operators in the Permian Basin are adopting these platforms at replacement-cycle pace as conventional tool retirements accelerate. The technology is integrating previously separate logging runs, reducing rig time and enabling same-day completion decisions that were previously impossible.
REACH substance restrictions and EU Green Deal carbon border adjustments are forcing European operators to document formation evaluation precision as part of emissions intensity calculations for imported crude. Industrial consequence includes mandatory third-party validation of reserve estimates that NMR direct fluid typing satisfies without radioactive source transport complications. Offshore Norway and UK North Sea assets are responding by specifying NMR-inclusive logging programs in drilling contracts to preempt regulatory audit risk.
Integrated service contracting is consolidating previously fragmented logging, interpretation, and completion design responsibilities under single-vendor accountability structures. Independent shale operators are displacing multi-vendor coordination models with bundled NMR-to-perforation workflows that compress cycle times. This pattern is most visible in West Texas where private equity-backed producers prioritize capital velocity over equipment ownership.
Oil and Gas Nuclear Magnetic Resonance Market Segmentation
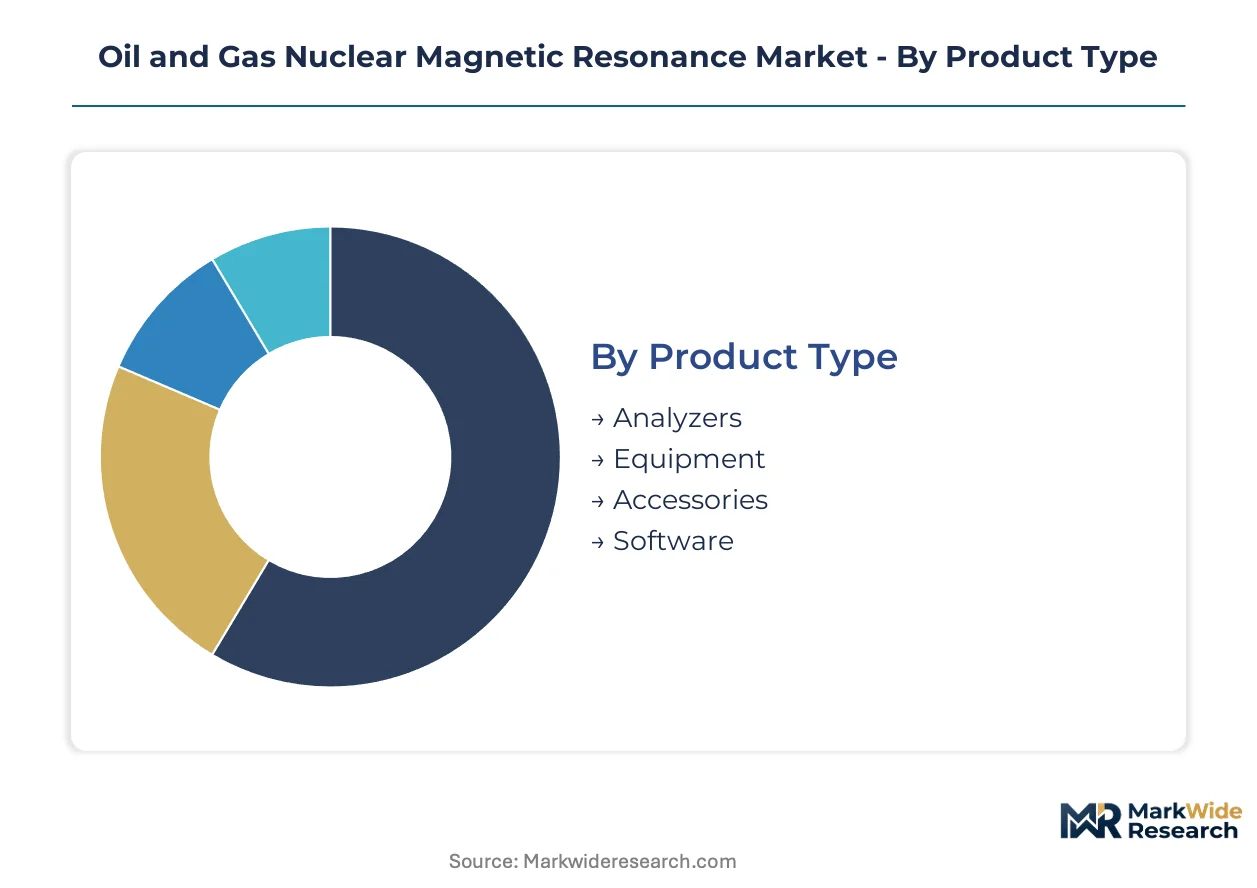
NMR market segmentation reveals how capital flows diverge between hardware-heavy equipment procurement and software-driven interpretation services. Understanding these splits helps vendors align R&D budgets with where purchasing decisions actually concentrate across upstream, midstream, and research-oriented buyers.
Product Type:
Replacement-cycle dynamics favor integrated platforms over component purchases as operators seek to reduce vendor coordination overhead.
- Equipment:Downhole spectrometer probes with specialized pressure housings and high-gradient magnets command premium capital allocation. Permian Basin operators deploy these for real-time porosity mapping during multi-well pad drilling, compressing formation evaluation timelines.
- Software:Cloud-based inversion algorithms transform raw T1-T2 decay curves into actionable petrophysical models. Upstream reservoir engineers in West Texas and southeastern New Mexico use these tools to cut interpretation cycles from days to hours.
- Analyzers:Laboratory-grade benchtop systems support core sample validation for reserve estimate auditing.
- Accessories:Replacement magnet assemblies and RF coil modules sustain extended tool lifecycles in high-temperature reservoirs.
Volume placements concentrate in Equipment; the faster expansion belongs to Software.
Technology:
Cost tiering separates legacy time-domain installations from next-generation hybrid platforms commanding 40-60% deployment premiums.
- Hybrid:Pulsed radiofrequency encoding combined with continuous-wave detection resolves both fast-diffusing bound fluids and slow-diffusing free hydrocarbons in single acquisition passes. Deepwater pre-salt formations offshore Brazil drive adoption where signal-to-noise constraints intensify.
- Time-Domain:Conventional pulsed-NMR architectures retain the largest installed base across mature conventional fields. Technical limitations above 175°C reservoir conditions accelerate replacement demand in high-pressure formations.
- Frequency-Domain:Continuous-wave detection suits laboratory core analysis with superior spectral resolution for fluid typing.
- Advanced Imaging:Multi-dimensional relaxation mapping enables 3D saturation profiling for enhanced oil recovery optimization.
Installed base dominance sits with Time-Domain; Hybrid platforms are climbing the fastest as unconventional shale operators accelerate replacement cycles.
End User:
Customer-type fragmentation splits procurement between capital-constrained independents and integrated supermajors with captive service capabilities.
- Service Providers:Integrated logging companies bundle NMR acquisition with interpretation and completion design under single-vendor accountability structures. Private equity-backed producers in West Texas prioritize these compressed workflows.
- Oil Producers:Supermajors and national oil companies deploy NMR logging for reserve validation under EPA methane emissions regulations and BSEE well integrity standards.
- Gas Companies:Unconventional gas operators use permeability mapping to optimize hydraulic fracture staging in low-permeability formations.
- Research Institutions:University consortia and national laboratories advance T1-T2 interpretation algorithms for next-generation sensor architectures.
Procurement volume aggregates through Service Providers; Oil Producers drive the steepest technology upgrade trajectory as regulatory compliance tightens.
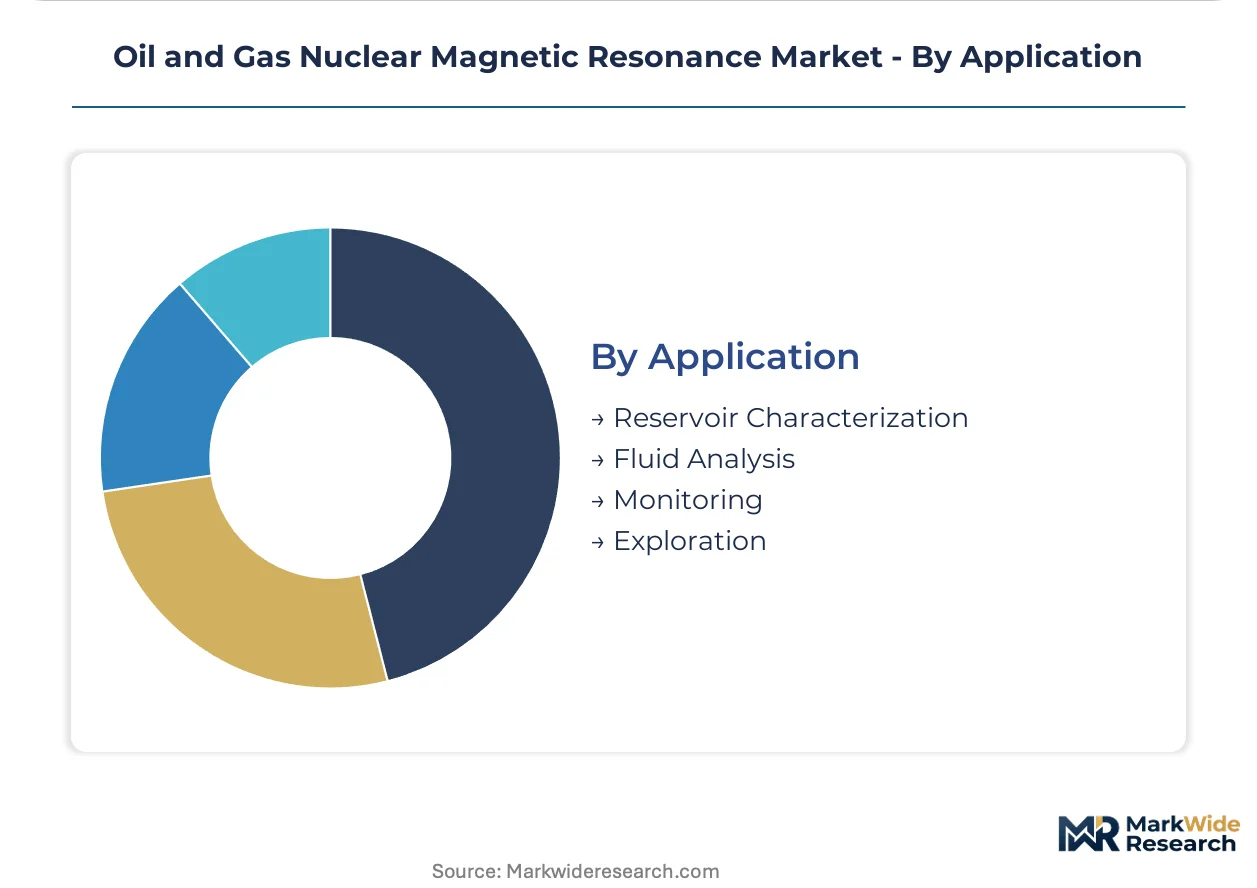
Application:
Application maturity varies from established reservoir characterization workflows to emerging real-time monitoring deployments with unproven ROI documentation.
- Reservoir Characterization:Porosity and permeability quantification for reserve estimation represents the foundational NMR use case. EPA and BSEE regulations mandate validated formation evaluation methods that direct fluid typing satisfies without radioactive source complications.
- Fluid Analysis:Hydrocarbon composition discrimination enables completion optimization in heterogeneous unconventional plays. EU Green Deal carbon border adjustments push European operators toward precision reservoir management applications.
- Monitoring:Time-lapse saturation tracking supports enhanced oil recovery project surveillance.
- Exploration:Wildcat drilling programs use rapid formation evaluation to reduce dry hole risk in frontier basins.
Revenue concentration remains in Reservoir Characterization; Fluid Analysis applications are expanding most quickly as completion design automation advances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Upstream operators in the United States concentrate half of worldwide NMR logging deployment, with the Permian Basin driving replacement-cycle demand for hybrid sensor platforms.
United States
Multi-well pad drilling in West Texas and southeastern New Mexico compresses formation evaluation timelines for unconventional shale producers. EPA methane emissions regulations and BSEE well integrity standards mandate validated logging methods that direct fluid typing satisfies. The Permian Basin anchors domestic demand as private equity-backed operators prioritize capital velocity through bundled NMR-to-perforation workflows.
Brazil
Pre-salt carbonate formations offshore drive adoption of hybrid time-frequency domain sensors where signal-to-noise constraints intensify at extreme depths. ANVISA and environmental licensing requirements from the national petroleum regulator shape equipment import protocols for deepwater operations. The Santos Basin concentration of floating production facilities creates white space for integrated logging service contracts.
Norway
North Sea asset operators specify NMR-inclusive logging programs to preempt regulatory audit risk under EU Green Deal carbon border adjustment mechanisms. REACH substance restrictions eliminate radioactive source transport complications for offshore drilling campaigns. Stavanger and Bergen clusters host service provider engineering centers supporting subsea formation evaluation technology.
China
Tarim Basin and Sichuan shale gas operators expand NMR adoption for tight-gas permeability mapping under national energy security directives. MIIT industrial standards and GB certification requirements govern downhole equipment manufacturing partnerships. State-backed exploration programs in the Ordos Basin accelerate procurement of high-temperature spectrometer probes.
Saudi Arabia
Unconventional gas targets in the Jafurah Basin drive demand for real-time porosity mapping during horizontal drilling campaigns. The national petroleum regulator mandates formation evaluation precision for reserve certification in upstream concession agreements. Dhahran-based research centers collaborate with international service providers on next-generation sensor validation.
Oil and Gas Nuclear Magnetic Resonance Market Competitive Landscape
Integrated service contracting dominates the current landscape as operators displace multi-vendor coordination models with bundled accountability structures. The vendor base concentrates around three strategic tiers: diversified oilfield service conglomerates with captive manufacturing, specialized logging technology firms with sensor fusion expertise, and national oil company affiliates with protected domestic markets. Technology licensing agreements and backward integration into high-temperature magnet supply represent the primary competitive vectors.
Among diversified service providers, Weatherford International plc, Schlumberger Limited, and Baker Hughes Company exemplify the integrated tier where digital platform connectivity and in-house component manufacturing anchor competitive positioning. These entities occupy positions defined by long-term supermajor contracts and real-time data stream integration capabilities. Specialized operators including Halliburton Company and Qteq Pty Ltd represent the technology-focused segment where hybrid sensor architectures and regional service density differentiate market presence.
| Leading Market Players |
|---|
| Weatherford International plc |
| CNPC Logging Co., Ltd. |
| Schlumberger Limited |
| Qteq Pty Ltd |
| Vista Clara Inc |
| Halliburton Company |
| Scientific Drilling International |
| Mount Sopris Instruments Inc. |
| Baker Hughes Company |
| Others |
Value Network & Pricing Analysis
Performance-grade bifurcation between hybrid time-frequency sensors and conventional time-domain platforms manifests in both capital deployment premiums and magnet supply chain concentration. Equipment procurement for deepwater pre-salt formations commands substantial pricing power from limited North American and European precision manufacturing capacity, while software segments compete on cloud-based inversion velocity rather than hardware margins.
Pricing Analysis
Volume placements concentrate in transactional equipment sales while margin expansion belongs to subscription-based software tiers. Three-tier pricing structure across premium hybrid sensors, standard time-domain tools, and economy-grade refurbished probes reflects certification grade and temperature rating differentiation. Pricing pressure stems from private equity-backed shale operators prioritizing capital velocity over equipment ownership in West Texas. Independent operators exhibit highest price sensitivity; supermajors with captive service capabilities demonstrate lowest sensitivity to per-tool premiums.
Supply Chain Analysis
Freight costs for specialized pressure housings and high-gradient magnets escalate with each routing through Houston and Stavanger logistics hubs. Manufacturing concentration in the United States, Germany, and Norway draws from rare earth magnet feedstocks and precision RF coil winding capabilities. Single-source vulnerability characterizes high-temperature magnet assemblies where qualified suppliers number fewer than five globally. Distribution runs through integrated oilfield service providers who bundle acquisition with interpretation under long-term contracting structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA methane emissions regulations and BSEE well integrity standards erect substantial compliance barriers that favor incumbents with validated formation evaluation workflows and radioactive source substitution expertise.
For Market Incumbents: Cement long-term service contracts by extending digital platform connectivity into real-time NMR data streams that compress interpretation cycles. Threat from specialized sensor fusion firms demands backward integration into high-temperature magnet supply to defend manufacturing autonomy. Priority lever rests with hybrid technology R&D investment targeting deepwater pre-salt signal-to-noise constraints. For New Entrants and Emerging Players: Begin with laboratory-grade benchtop analyzer segments where capital barriers remain lowest and customer acquisition costs favor regional service density. White space concentrates in offshore Brazil pre-salt formations where ANVISA import protocols and floating production facility logistics create incumbent coordination friction. Go-to-market angle emphasizes third-party reserve estimate validation for EU Green Deal carbon border adjustment compliance. For Investors and Strategic Acquirers: Re-rating potential sits with specialized logging technology firms given hybrid sensor architecture differentiation and replacement-cycle acceleration in Permian Basin multi-well pad drilling. Long-term viability frames around precision reservoir management as emissions intensity calculations permeate drilling contract specifications. Acquisition target archetype combines sensor fusion expertise with established regional service infrastructure. Signal to watch: EPA enforcement intensity around validated formation evaluation mandates.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Sensor Platform Development | Integrates time-frequency encoding to resolve bound and free fluids in single acquisition passes for pre-salt formations. |
| Cloud-Based Inversion Algorithm Investment | Compresses petrophysical interpretation from days to hours for upstream reservoir engineers in unconventional shale basins. |
| High-Temperature Magnet Supply Integration | Reduces single-source vulnerability for downhole spectrometer probes exceeding 175°C reservoir conditions. |
| Digital Platform Connectivity Extension | Links real-time NMR data streams with drilling automation systems for same-day completion decisions. |
| EU Green Deal Compliance Positioning | Documents formation evaluation precision for carbon border adjustment mechanisms affecting North Sea asset valuations. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs while structured interviews with petrophysicists, drilling engineers, reservoir characterization leads, and oilfield service procurement officers provided primary validation. Bottom-up triangulation against top-down macroeconomic indicators incorporated EPA enforcement databases, BSEE well integrity reports, ANVISA import protocols, and EU ETS emissions trading records. Cross-referencing between equipment shipment manifests and software licensing disclosures verified segment-level revenue allocation.
Granularity-level modeling distinguished equipment, software, analyzer, and accessory product types alongside hybrid, time-domain, frequency-domain, and advanced imaging technology tiers. End-user segmentation captured service providers, oil producers, gas companies, and research institutions across reservoir characterization, fluid analysis, monitoring, and exploration applications. CAGRs derived from replacement-cycle velocity in unconventional shale basins and regulatory compliance-driven upgrade trajectories in offshore jurisdictions. Forecast inputs incorporated multi-well pad drilling intensity metrics and deepwater pre-salt development timelines.
Underlying measurement precision varies by segment; software and equipment categories carry tighter precision than emerging monitoring applications with unproven ROI documentation. Forecasts reflect assumptions around EPA methane regulation enforcement continuity and hybrid sensor cost reduction curves. Stakeholders should weight assumptions against their own operating context and regulatory jurisdiction exposure.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Egypt Natural Gas Market
Oil & Gas
Canada Oil and Gas Upstream Market
Oil & Gas
Indonesia Oilfield Equipment Rental Services Market
Oil & Gas
Well Stimulation Vessels Market
Oil & Gas
Nigeria Oil and Gas Midstream Market
Oil & Gas
Leak Detection for Oil & Gas Market
Oil & Gas
Europe Coiled Tubing Market
Oil & Gas
Containment and Handling Drilling Waste Management Market
Oil & Gas
Smart Oilfield Market
Oil & Gas
Chad Oil and Gas Upstream Market
Oil & Gas
Global Oilfield Stimulation Chemicals Market
Oil & Gas
Global Fracking Fluids and Chemicals Market
Oil & Gas
Fracking Fluid Market
Oil & Gas
Oil and Gas Electrification Market
Oil & Gas
Europe Natural Gas Market
Oil & Gas
United Kingdom Oil and Gas Midstream Market