
 Smart Pipeline Pigging Market | 2026-2036
Smart Pipeline Pigging Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Pipeline Pigging Market Insights
Modular inspection service bundling is pivoting buyer choice away from standalone tool sales toward integrated integrity-as-a-service contracts. Baker Hughes Company leverages its upstream-to-midstream equipment portfolio to anchor long-term pigging agreements across North American infrastructure. ROSEN Group competes through specialized electromagnetic sensor arrays that dominate high-resolution crack detection in sour gas lines. T.D. Williamson sustains manufacturing scale in custom launcher and receiver fabrication, giving it channel control over retrofit projects on legacy pipeline systems.
Smart pipeline pigging refers to the deployment of instrumented inline devices propelled by product flow to perform non-destructive evaluation of pipeline wall condition, typically incorporating magnetic flux leakage sensors operating at axial resolutions below 5 millimeters or ultrasonic transducer rings achieving thickness measurement precision of ±0.1 millimeter. These systems serve the primary industrial purpose of detecting metal loss, cracking, and geometric deformation before catastrophic failure occurs in hydrocarbon and water transport networks. Intelligent pigs command the highest value tier within the product type dimension due to their multi-sensor fusion architectures and real-time data telemetry capabilities, while ultrasonic technology leads the technology dimension for crack-sizing accuracy in liquid lines. Cleaning pigs represent the most mature segment with thinner margins, though demand for combined cleaning-plus-inspection configurations is expanding the addressable scope for integrated service providers.
The US Department of Transportation's Pipeline and Hazardous Materials Safety Administration enforces integrity management rules under 49 CFR Part 195 that mandate regular inline inspection of high-consequence areas, directly shaping procurement cycles and tool specification requirements for operators. The EU's F-Gas Regulation and national methane reduction frameworks in Germany and the Netherlands are tightening leak detection standards that extend to pipeline maintenance protocols including pre- and post-pigging verification. Stakeholders must monitor how evolving carbon accounting rules and methane intensity benchmarks reshape the economic justification for predictive versus preventive pigging schedules across their asset portfolios.
Market Dynamics
Pipeline integrity mandates from the US Department of Transportation are compressing inspection intervals across North American midstream networks, forcing operators to convert from reactive maintenance schedules toward continuous monitoring architectures.
Growth Catalysts
- PHMSA Integrity Management Rules:The US DOT's 49 CFR Part 195 enforcement mandates inline inspection of high-consequence areas, creating recurring procurement cycles for smart pigging services across interstate transmission lines.
- Permian Basin Infrastructure Density:Concentrated pipeline construction in West Texas and southeastern New Mexico generates sustained demand for crack-detection pigs in corrosive sour gas service.
- Electromagnetic Sensor Fusion:Multi-technology pigs combining magnetic flux leakage with ultrasonic transducers now detect sub-millimeter crack initiation, expanding addressable inspection scope into previously uninspectable pipeline segments.
Market Restraints
- Specialized Alloy Input Costs:Tool body fabrication relies on high-grade stainless steel and rare-earth magnetic materials, exposing manufacturers to commodity volatility and extended lead times.
- German Equipment Supplier Concentration:Precision sensor arrays and telemetry electronics concentrate among a narrow base of Bavarian and Baden-Württemberg component vendors, creating single-source vulnerability.
- Bi-Directional Launch Constraints:Legacy pipeline systems lacking receiver valve configurations cannot accommodate standard smart pigs without capital-intensive station modifications.
Strategic Opportunities
- Alberta Oil Sands Expansion:Canadian thermal production growth requires new diluent pipeline corridors where inspection-as-a-service contracts can anchor multi-year vendor relationships.
- Methane Intensity Benchmarking:The EU's F-Gas Regulation and emerging carbon accounting frameworks create economic justification for predictive pigging schedules tied to leak-rate verification requirements.
- AI-Enabled Defect Classification:Machine learning algorithms trained on historical inline inspection data are reducing false-call rates, enabling faster turnaround between field runs and maintenance decisions.
Industry Challenges
- Ultrasonic Transducer Calibration Expertise:Qualified technicians capable of maintaining ±0.1 millimeter thickness measurement precision remain scarce in secondary US pipeline corridors outside the Gulf Coast.
- Legacy SCADA Integration:Real-time telemetry pigs face protocol compatibility barriers when interfacing with decades-old control systems prevalent in Appalachian gathering networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Pipeline Pigging Market |
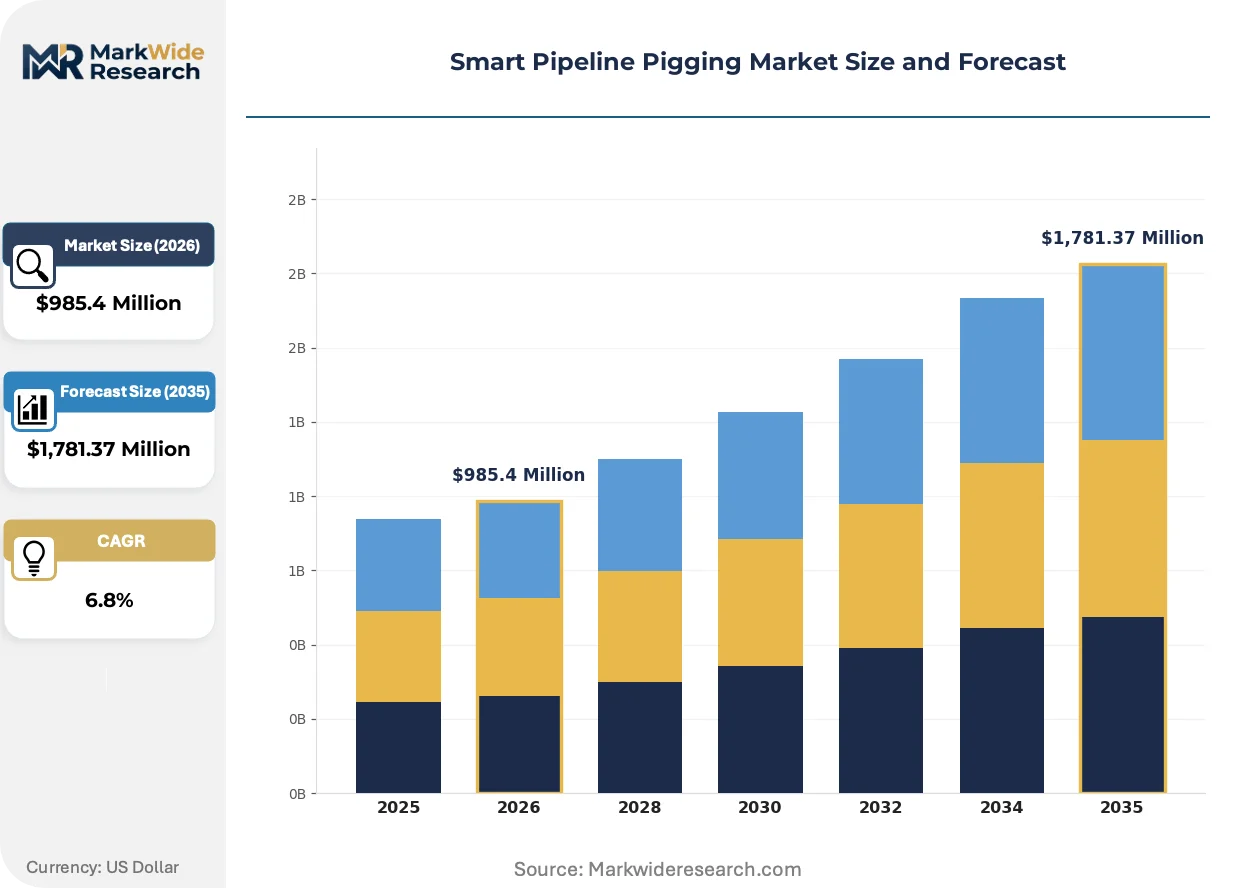
| Market Size in 2026 | $985.4 Million |
| Market Size in 2035 | $1,781.37 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intelligent Pigs, Utility Pigs, Inspection Pigs, Cleaning Pigs Technology: Ultrasonic, Magnetic, Electromagnetic, Mechanical End User: Oil & Gas Companies, Water Utilities, Industrial Manufacturers, Waste Management Application: Corrosion Detection, Thickness Measurement, Cleaning Operations, Flow Assurance |
| Companies Covered | Baker Hughes Company, ROSEN Group, T.D. Williamson, NDT Global, Enduro Pipeline Services, SGS SA, Pigtek Ltd., Dexon Technology, Applus+, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Pipeline Pigging Market Trends and Innovations
Sensor miniaturization and edge computing are collapsing the latency between defect detection and maintenance response, compressing the traditional weeks-long analysis cycle into hours.
Ultrasonic phased-array transducer rings now achieve circumferential coverage with single-pass resolution below two millimeters, enabling crack-sizing accuracy previously requiring multiple tool runs. Midstream operators in liquid hydrocarbon service are adopting these configurations for baseline surveys of new construction. Conventional magnetic flux leakage tools are overtaking legacy radiographic methods for wall-thickness mapping in non-piggable pipeline segments.
The EU's F-Gas Regulation tightens verification standards for pre- and post-maintenance leak rates, extending to pipeline segments previously exempt from formal inspection protocols. Operators must now document integrity status through traceable inline inspection records rather than pressure-test certificates alone. German and Dutch transmission system operators are accelerating procurement of combined cleaning-plus-detection pigs to satisfy both maintenance and regulatory documentation requirements in single deployments.
Service bundling now dominates buyer preference, with standalone tool purchases declining relative to integrated integrity contracts covering analysis, remediation planning, and regulatory filing support. This shift compresses vendor margins on hardware while expanding recurring revenue from data interpretation and engineering advisory. The Permian Basin and Alberta oil sands exhibit the most pronounced migration toward outcome-based service structures.
Smart Pipeline Pigging Market Segmentation
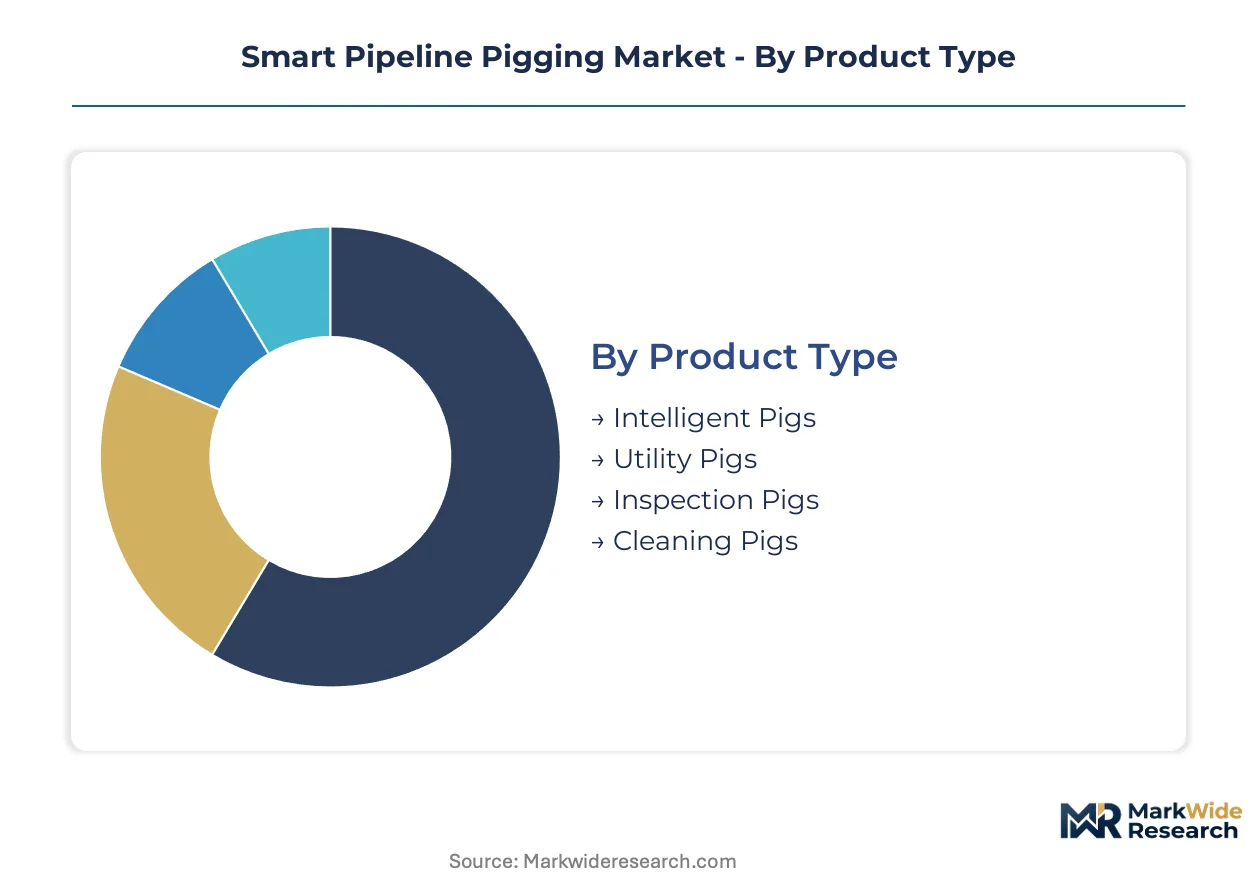
Segmentation in smart pipeline pigging reveals how capital allocation, technical complexity, and regulatory pressure concentrate across distinct equipment tiers and service models. Understanding these divisions clarifies where vendors earn sustainable margins versus where commoditization erodes pricing power.
Product Type:
Capital intensity escalates sharply from basic cleaning tools toward multi-sensor intelligent platforms requiring precision machining and embedded telemetry systems.
- Intelligent Pigs:These systems integrate magnetic flux leakage arrays, ultrasonic transducer rings, and real-time data transmission modules to deliver sub-millimeter defect resolution. Demand clusters in high-consequence areas of the Permian Basin where sour gas corrosion mandates continuous wall-condition monitoring. PHMSA enforcement of 49 CFR Part 195 inspection intervals sustains procurement velocity for these premium-tier units.
- Inspection Pigs:Single-technology platforms—either electromagnetic or ultrasonic—target specific defect modalities without the sensor fusion of intelligent configurations. Midstream operators in the Gulf Coast corridor deploy these for routine metal-loss surveys where crack detection remains secondary. Capital requirements run roughly half those of intelligent pigs, expanding addressability to smaller independent operators.
- Cleaning Pigs:Brush, blade, and cup configurations remove wax, scale, and debris without instrumentation. These mature products compete on manufacturing scale and material durability rather than sensor sophistication.
- Utility Pigs:Hybrid designs combining limited gauging capability with cleaning functions serve batching and separation duties in multiproduct pipelines. Demand tracks liquid hydrocarbon throughput volumes rather than integrity mandates.
Intelligent pigs absorb the bulk of installed capacity; inspection pigs are expanding most quickly as operators segment their tool fleets by defect type.
Technology:
Technical performance thresholds and calibration complexity separate premium sensing modalities from established mechanical methods.
- Ultrasonic:Phased-array transducer rings achieve ±0.1 millimeter thickness measurement precision through direct wall-contact pulse-echo timing. Liquid hydrocarbon lines in the Gulf Coast corridor favor this technology for crack-sizing accuracy that magnetic methods cannot replicate. German and Dutch transmission operators specify ultrasonic configurations to satisfy EU F-Gas Regulation leak-rate verification protocols.
- Electromagnetic:Sensor fusion architectures combining eddy current and remote field technologies excel in gas lines where ultrasonic coupling proves unreliable. Sour gas gathering systems in West Texas and southeastern New Mexico represent concentrated demand nodes. Bavarian component suppliers dominate precision sensor fabrication, creating supply concentration risk.
- Magnetic:Conventional magnetic flux leakage tools map general metal loss without the crack-resolution of electromagnetic arrays. These platforms retain cost advantages for baseline corrosion surveys in water and crude service.
- Mechanical:Gauging pigs with calibrated aluminum or polyurethane discs detect geometric deformation and severe metal loss through physical interference. No electronic components reduce capital cost and maintenance burden for routine cleaning verification.
Ultrasonic platforms command the steepest expansion trajectory in liquid service; electromagnetic arrays dominate gas-line procurement cycles.
End User:
Procurement sophistication and contract scale vary dramatically across infrastructure ownership models and regulatory exposure.
- Oil & Gas Companies:Integrated majors and large midstream operators negotiate multi-year integrity-as-a-service agreements bundling tool deployment, data analysis, and regulatory filing support. These buyers specify sensor performance thresholds and demand real-time telemetry integration with SCADA architectures.
- Water Utilities:Municipal and regional water authorities deploy cleaning and basic inspection pigs to maintain flow capacity in aging distribution networks. Capital constraints favor utility-grade platforms over intelligent configurations.
- Industrial Manufacturers:Petrochemical complexes and refining operations use specialized pigs for internal process piping where external inspection remains impractical. Demand concentrates in turnaround maintenance windows rather than continuous programs.
- Waste Management:Hazardous liquid and slurry transport operators face emerging integrity requirements but exhibit lower procurement sophistication than hydrocarbon midstreamers.
Oil and gas operators absorb the bulk of installed capacity; water utilities are expanding most quickly as municipal infrastructure ages and regulatory attention extends beyond hydrocarbon networks.
Application:
Functional purpose determines sensor specification, deployment frequency, and the economic threshold for intelligent versus basic tool selection.
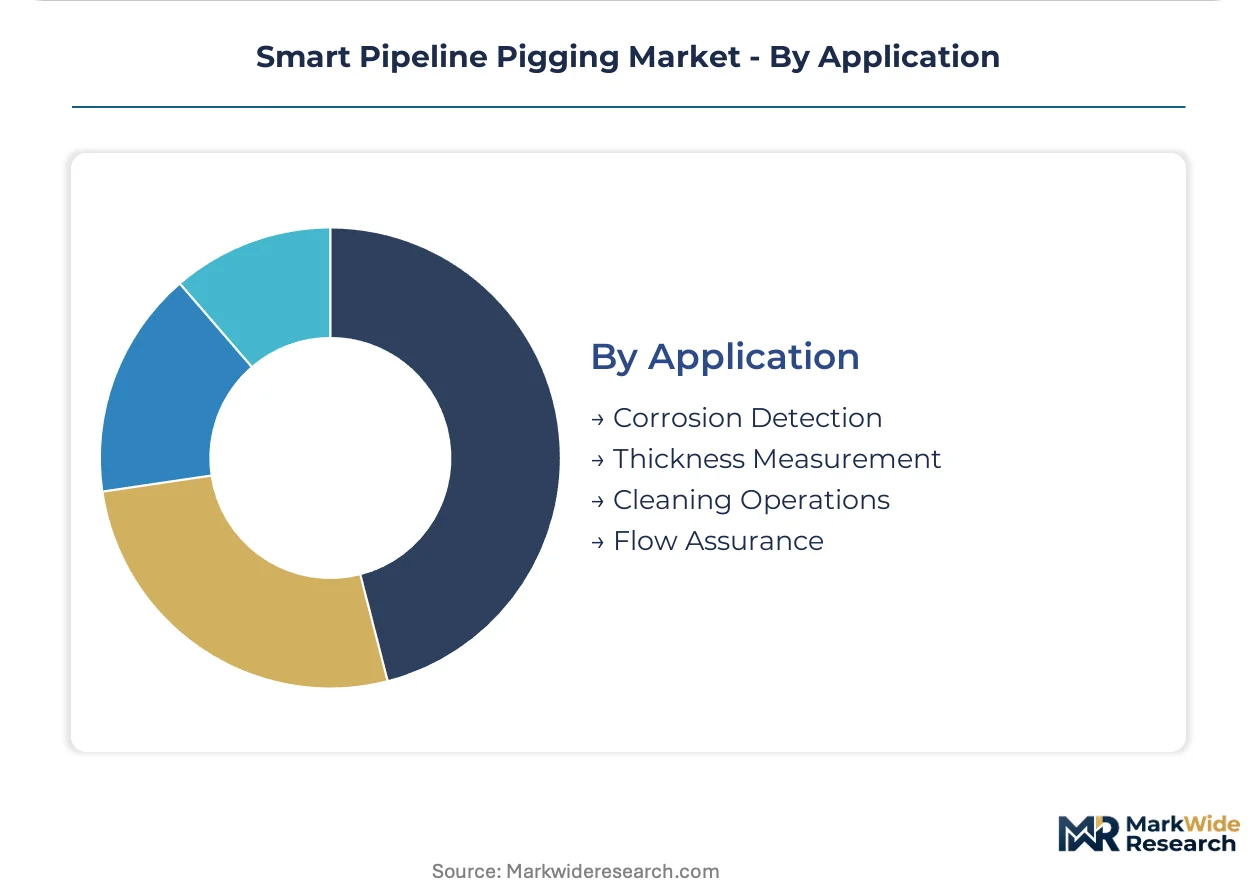
- Corrosion Detection:Metal-loss mapping drives the highest-value inspection contracts, requiring either high-resolution magnetic flux leakage or ultrasonic coverage. Sour gas lines in corrosive West Texas formations sustain premium pricing for crack-detection capabilities.
- Thickness Measurement:Ultrasonic direct-measurement applications in liquid hydrocarbon service demand calibration expertise that concentrates among Gulf Coast technical service providers. Precision requirements exceed magnetic method capabilities.
- Cleaning Operations:Wax and scale removal in crude oil and multiphase lines represents high-volume, lower-margin activity where tool durability matters more than sensor performance.
- Flow Assurance:Hydrate inhibition and liquid holdup management in subsea and cold-climate pipelines require specialized chemical-injection pigs and gel-pig configurations distinct from inspection platforms.
Corrosion detection absorbs the bulk of installed capacity; thickness measurement is expanding most quickly as baseline surveys of new construction adopt ultrasonic standards.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pipeline integrity equipment production concentrates in German industrial clusters while consumption gravity shifts toward North American shale corridors and North Sea decommissioning programs. Equipment fabricators in Bavaria and Baden-Württemberg supply precision sensor arrays to operators facing compressed inspection cycles.
United States
PHMSA enforcement of 49 CFR Part 195 mandates recurring inline inspection across high-consequence areas spanning interstate transmission networks. The Permian Basin in West Texas and southeastern New Mexico generates concentrated procurement for crack-detection pigs in corrosive sour gas service. Appalachian gathering systems in Pennsylvania and Ohio face SCADA integration barriers for real-time telemetry deployments.
Germany
Bavarian component vendors dominate precision electromagnetic sensor fabrication for global pigging OEMs. The F-Gas Regulation and national methane reduction frameworks tighten pre- and post-maintenance leak verification standards for transmission operators. Industrial concentration in Stuttgart and Munich sustains rare-earth magnetic material processing for high-resolution transducer arrays.
Canada
Alberta oil sands expansion requires new diluent pipeline corridors where inspection-as-a-service contracts anchor multi-year vendor relationships. Provincial regulators align with federal integrity management expectations for thermal production infrastructure. Calgary-based technical service providers concentrate ultrasonic calibration expertise for heavy crude applications.
Netherlands
National methane intensity benchmarks reshape economic justification for predictive versus preventive pigging schedules across Groningen and Rotterdam corridor assets. The F-Gas Regulation extends to pipeline segments previously exempt from formal inspection protocols. Combined cleaning-plus-detection pig procurement accelerates to satisfy maintenance and regulatory documentation in single deployments.
United Kingdom
North Sea decommissioning programs and aging onshore infrastructure drive integrity spending across Scottish and English transmission networks. The Health and Safety Executive maintains pressure equipment inspection standards that reference inline inspection records. Aberdeen service clusters specialize in subsea pigging logistics for offshore pipeline systems.
Smart Pipeline Pigging Market Competitive Landscape
The competitive structure tilts toward integrated service bundling over standalone equipment sales. Tier-one vendors anchor multi-year integrity contracts covering tool deployment, data interpretation, and regulatory filing support. Mid-scale fabricators compete on custom launcher and receiver fabrication for retrofit projects. Dominant competitive moves include strategic partnerships with midstream operators and geographic expansion through regional service hubs.
Among North American-based energy technology conglomerates, Baker Hughes Company exemplifies the integrated portfolio archetype spanning upstream through midstream equipment. German specialist ROSEN Group occupies a position within the precision sensor tier, while T.D. Williamson represents the manufacturing-scale archetype in pipeline station fabrication. These three anchors illustrate how vendor positioning diverges between outcome-based service contracts and capital equipment supply.
| Leading Market Players |
|---|
| Baker Hughes Company |
| ROSEN Group |
| T.D. Williamson |
| NDT Global |
| Enduro Pipeline Services |
| SGS SA |
| Pigtek Ltd. |
| Dexon Technology |
| Applus+ |
| Others |
Pricing and Supply Chain Analysis
Integrated midstream operators in the Permian Basin and Gulf Coast corridor anchor procurement scale, compressing vendor margins through multi-year integrity-as-a-service contracts that bundle hardware deployment with data interpretation and regulatory filing support. This buyer concentration shifts pricing power toward outcome-based structures where tool suppliers sacrifice upfront equipment margins for recurring engineering advisory revenue.
Pricing Analysis
Margin tightening in intelligent pig configurations reflects rare-earth magnetic material cost volatility and extended calibration lead times for ultrasonic transducer arrays. Three-tier pricing structure across premium intelligent platforms, standard inspection units, and economy cleaning tools stratifies by sensor fusion complexity and real-time telemetry capability. Cost-down pressure accelerates because German component suppliers command single-source positions in precision electromagnetic sensor fabrication. Independent operators in secondary US pipeline corridors exhibit highest price sensitivity, while integrated majors absorb premium pricing for PHMSA-compliant crack-detection capabilities.
Supply Chain Analysis
Single-source vulnerability sits with Bavarian and Baden-Württemberg precision sensor vendors, concentrating high-resolution transducer array production in southern German industrial clusters. Tool body fabrication draws from US and Japanese high-grade stainless steel mills, while rare-earth magnetic materials hinge on Chinese and Australian extraction and processing networks. Tariff exposure on sensor electronics creates procurement risk for North American OEMs assembling intelligent pig platforms. Distribution runs through regional service hubs in Houston, Calgary, and Aberdeen that coordinate field deployment logistics with midstream operator maintenance windows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into precision sensor fabrication and captive telemetry electronics production is accelerating as vendors seek margin defense against German component supplier concentration and rare-earth material cost volatility.
For Market Incumbents: Lock in long-term offtake agreements with rare-earth processors and Bavarian sensor suppliers to secure input cost predictability. Deepen backward integration into electromagnetic array fabrication to reduce dependency on single-source German vendors. Channel control over custom launcher and receiver retrofit projects on legacy pipeline systems defends pricing power against emerging fabrication competitors. For New Entrants and Emerging Players: AI-enabled defect classification algorithms offer technology-first entry into data interpretation services where established vendors retain hardware dominance. White-space targets include ultrasonic calibration services in Appalachian gathering networks outside Gulf Coast technical service clusters. Municipal water utilities present penetrable demand for utility-grade cleaning and basic inspection platforms with lower capital barriers than intelligent pig manufacturing. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional service providers with established SCADA integration capabilities in North American shale corridors. Long-term viability centers on vendors capturing recurring revenue from integrity-as-a-service contracts rather than transactional equipment sales. Monitor PHMSA enforcement intensity and EU methane intensity benchmarking as inflection indicators for predictive pigging schedule acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Fabrication | Captive production of electromagnetic arrays reduces dependency on Bavarian suppliers and stabilizes input costs. |
| Integrity-as-a-Service Contract Expansion | Bundled offerings covering deployment, analysis, and regulatory filing anchor multi-year revenue streams with Permian operators. |
| AI-Enabled Defect Classification Investment | Machine learning reduces false-call rates and compresses turnaround between field runs and maintenance decisions. |
| Regional Service Hub Establishment | Calgary and Aberdeen logistics centers position vendors for Alberta oil sands and North Sea decommissioning procurement cycles. |
| Ultrasonic Calibration Capability Buildout | Technical service expansion into secondary US corridors addresses qualified technician scarcity outside Gulf Coast clusters. |
Research Methodology
Independent corroboration across midstream integrity managers, PHMSA regulatory specialists, and German sensor component engineers underwrites the qualitative findings. Primary interviews with pipeline maintenance directors, inline inspection service procurement leads, and electromagnetic transducer R&D heads combined with secondary validation from DOT enforcement records, EU F-Gas Regulation implementation guidance, and Bavarian industrial cluster trade data. Bottom-up segmentation modeling and top-down market sizing triangulate volume and value estimates.
Comparable-period anchoring to historical integrity management spending patterns and inspection interval compression trends shapes the projection framework. Segmentation dimensions span product type, technology modality, end-user sophistication tier, and application purpose across the modeling period. CAGRs derive from equipment deployment velocity, regulatory mandate expansion rates, and service contract renewal patterns. Forecast inputs incorporate PHMSA enforcement intensity trajectories and EU methane reduction benchmark adoption curves.
Several conditions sit outside the modeled scope, including sudden commodity price shocks affecting rare-earth magnetic materials, unanticipated regulatory interval relaxations, and breakthrough non-piggable inspection technologies. Forecasts reflect documented assumptions regarding continued sour gas corrosion severity in West Texas formations and sustained German supplier concentration in precision sensor arrays. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Chad Oil and Gas Market
Oil & Gas
North America Completion Equipment and Services Market
Oil & Gas
Pipeline Pigging Services Market
Oil & Gas
Mexico Wireline Services Market
Oil & Gas
Middle-East Enhanced Oil Recovery Market
Oil & Gas
Africa Drilling and Completion Fluids Market
Oil & Gas
Africa Oil Refining Market
Oil & Gas
Clear Brine Fluids Market
Oil & Gas
Latin America AI in Oil and Gas Market
Oil & Gas
Oilfield Rotary Table Market
Oil & Gas
Oil Tank Rotating Stacker Market
Oil & Gas
Sidetracking Market
Oil & Gas
Iron Ore Mining Market
Oil & Gas
North America Perforating Gun Market
Oil & Gas
Middle East and Africa Coiled Tubing Market
Oil & Gas
Nigeria Oil and Gas Market