
 Aqueous Flare Meter Market | 2026-2036
Aqueous Flare Meter Market Size, Share, and Industry Trends Forecast 2026-2036
Aqueous Flare Meter Market Outlook
Market Context with Strategic Players
The buyer base for aqueous flare metering systems is broadening as independent shale producers and midstream water-handling facilities enter the procurement pool alongside integrated majors. Emerson Electric Co. leverages its automation platform to bundle flare meters with distributed control systems for refinery clients. Endress+Hauser Group sustains strong positioning through calibration laboratories that anchor long-term service contracts. ABB Ltd competes on integrated digital twin offerings that pair meter hardware with predictive analytics software.
Technical Definition and Structural Segments
An aqueous flare meter is an instrumentation device designed to measure hydrocarbon content, flow rate, and pressure in water-laden flare gas streams, typically operating at temperatures from minus forty to two hundred degrees Celsius with corrosion-resistant wetted materials for saline environments. Its primary industrial purpose is environmental compliance monitoring and flare gas recovery optimization at facilities handling produced water or aqueous chemical effluent. Multi-phase meters command the dominant revenue share due to complex wellstream characterization needs in offshore oil and gas installations, while ultrasonic technology segments are gaining traction fastest as non-intrusive designs reduce maintenance downtime in sour service conditions. Portable meter demand is accelerating in chemical manufacturing where temporary process validation and EPA audit response create episodic procurement cycles distinct from capital-intensive permanent installations.
Regulatory Frame and Forward-Looking Close
The EPA enforces Quad Oa standards that mandate continuous flare gas monitoring at onshore oil and gas facilities, directly shaping meter specification requirements for accuracy and data logging capability. OSHA process safety management rules and BSEE offshore safety regulations further constrain equipment selection through intrinsic safety certifications and material traceability documentation. Stakeholders must monitor evolving methane emission protocols and state-level air quality mandates to anticipate specification shifts that could obsolete installed meter populations or trigger replacement waves.
Market Dynamics
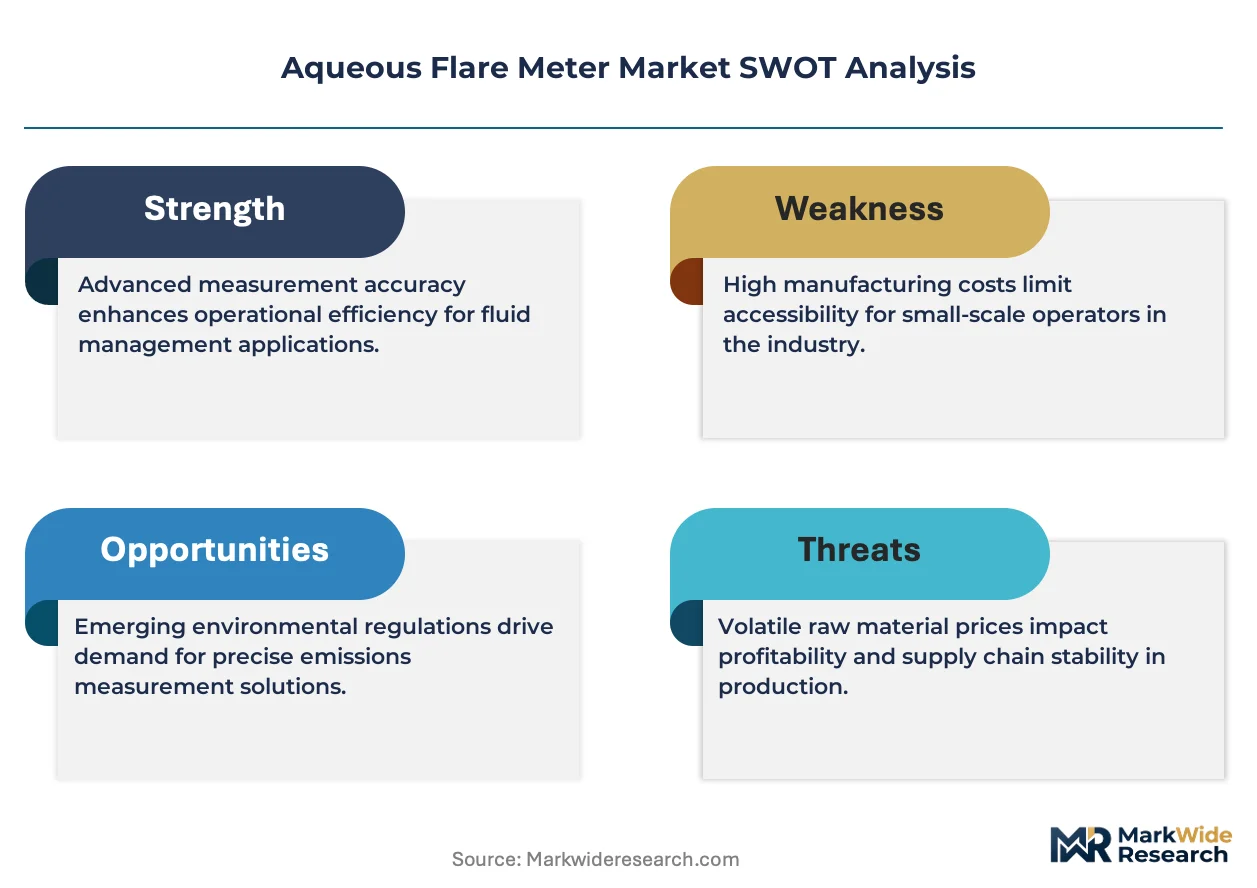
EPA Quad Oa enforcement is compressing replacement cycles for aqueous flare meters as operators face escalating penalties for non-compliant monitoring systems at onshore oil and gas facilities.
Growth Catalysts
- Offshore platform retrofits:Aging Gulf of Mexico infrastructure requires meter upgrades to handle high-salinity produced water streams and meet BSEE safety documentation mandates.
- EPA Clean Air Act tightening:Continuous monitoring requirements for methane and volatile organic compounds force operators to deploy multi-phase meters with enhanced data logging capabilities.
- Midstream water-handling expansion:Independent shale producers building centralized produced water treatment facilities create new procurement demand for portable validation meters.
Market Restraints
- Hastelloy and titanium input costs:Corrosion-resistant wetted materials for sour service applications face price volatility from constrained specialty alloy supply chains.
- Calibration infrastructure concentration:Certified flow laboratories cluster along the Texas-Louisiana refining corridor, creating service access gaps for Permian Basin operators.
- Ultrasonic signal attenuation limits:High gas void fraction in certain wellstream conditions degrades measurement accuracy below EPA-mandated thresholds.
Strategic Opportunities
- Permian Basin produced water recycling:Texas and New Mexico operators building closed-loop systems need meters for real-time hydrocarbon detection in reuse streams.
- Digital twin convergence:Integration of meter hardware with predictive analytics platforms enables remote diagnostics and reduces offshore platform maintenance visits.
- California CARB methane protocols:State-level air quality mandates ahead of federal standards create early-adopter demand for next-generation monitoring systems.
Industry Challenges
- Intrinsic safety certification timelines:ATEX and IECEx approvals for explosion-proof designs in hazardous areas extend product launch schedules by 8-14 months.
- Legacy system integration:Retrofitting smart meters into existing distributed control architectures at mature refineries requires custom protocol gateways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aqueous Flare Meter Market |
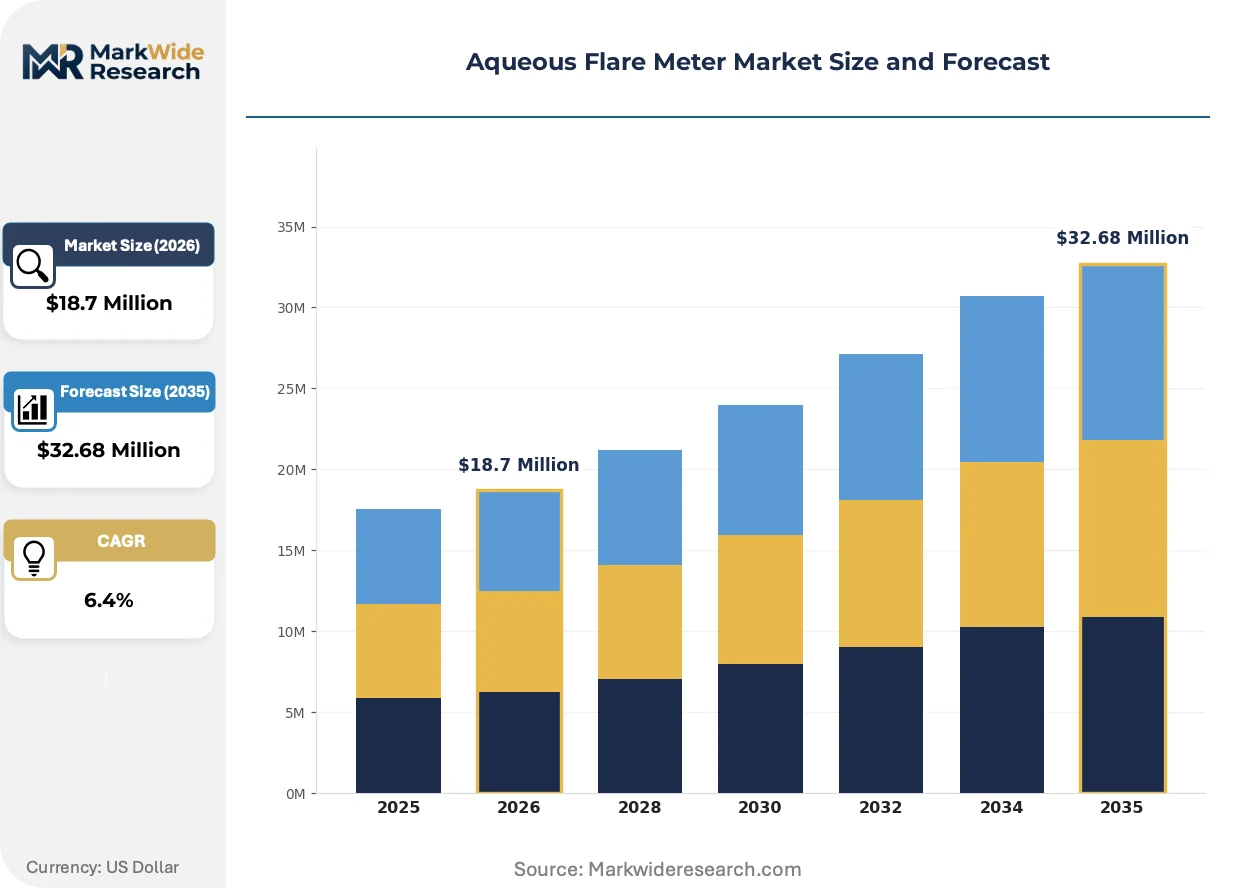
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $32.68 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Phase Meters, Multi-Phase Meters, Portable Meters, Fixed Meters Technology: Ultrasonic, Electromagnetic, Coriolis, Thermal End User: Oil & Gas, Wastewater Treatment, Chemical Manufacturing, Power Generation Installation Type: Onshore, Offshore, Permanent, Temporary |
| Companies Covered | Emerson Electric Co., Endress+Hauser Group, ABB Ltd, Yokogawa Electric Corporation, Siemens AG, Schneider Electric SE, Baker Hughes Company, KROHNE Group, Kowa American Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aqueous Flare Meter Market Strategic Shifts
Non-intrusive sensing architectures and cloud-connected diagnostics are transforming how operators maintain compliance and optimize flare gas recovery across water-handling facilities.
Clamp-on ultrasonic transducer arrays with time-of-flight correlation algorithms is rewriting maintenance economics for sour service applications. Offshore platform operators in the Gulf of Mexico are adopting these designs to eliminate process shutdowns for meter removal and recalibration. The shift is compressing total cost-of-ownership calculations and displacing insertion-style meters in high-H2S environments.
EPA's proposed methane emissions performance standards for new and existing sources are tightening allowable uncertainty bands for flare gas volumetric measurement. This regulatory pressure is forcing meter specification upgrades at onshore oil and gas facilities ahead of formal compliance deadlines. Multi-phase meter vendors are responding with enhanced gamma-ray densitometry integration to handle wider gas-liquid ratio variations.
Service contract unbundling is fragmenting traditional vendor-customer relationships in the chemical manufacturing sector. End-users are separating hardware procurement from calibration and data analytics subscriptions, creating openings for specialized service providers. This pattern is most pronounced along the Texas Gulf Coast where temporary process validation needs drive episodic meter rentals rather than capital purchases.
Aqueous Flare Meter Market Segmentation
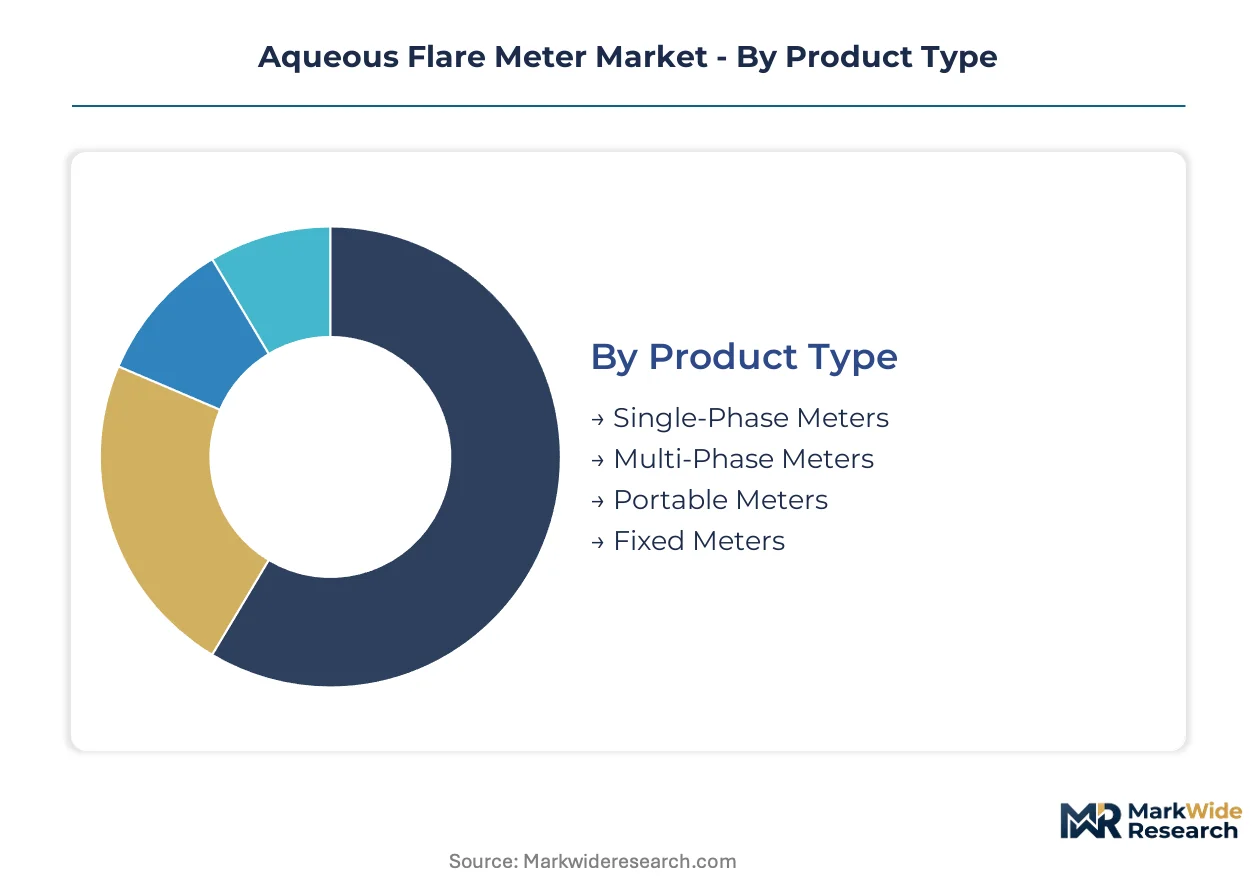
Segmentation in aqueous flare metering reflects divergent technical requirements across sour service conditions, regulatory stringency, and capital deployment cycles. Equipment specifications vary sharply between permanent offshore installations and temporary validation deployments.
Product Type:
Technology sophistication and measurement complexity define the product hierarchy, with phase-handling capability as the central specification axis.
- Multi-Phase Meters:These systems simultaneously characterize gas-liquid ratios, hydrocarbon composition, and flow dynamics in produced water streams. Offshore Gulf of Mexico platforms deploy these for continuous flare gas recovery optimization where EPA Quad Oa mandates precision across variable wellstream conditions.
- Portable Meters:Battery-powered validation units enable episodic audit response and temporary process characterization without permanent capital commitment. Independent shale operators in the Permian Basin rent these for EPA compliance spot-checks at centralized water-handling facilities.
- Single-Phase Meters:Simpler instruments isolate either gas or liquid measurement for standardized process streams with consistent composition profiles.
- Fixed Meters:Hardened permanent installations integrate into distributed control architectures at refineries and chemical plants with 15-20 year service lifecycles.
Multi-phase meters lead on scale; portable meters lead on momentum.
Technology:
Measurement physics and maintenance economics separate the technology tiers, with non-intrusive designs commanding premium positioning.
- Ultrasonic:Clamp-on transducer arrays with time-of-flight correlation eliminate process shutdowns for recalibration. Gulf of Mexico operators favor these for sour service where H2S exposure degrades wetted materials in insertion-style alternatives.
- Coriolis:Direct mass flow measurement with density compensation handles wide gas-liquid ratio variations in complex wellstreams. Offshore installations specify these where BSEE documentation mandates material traceability and intrinsic safety certification.
- Electromagnetic:Faraday's law-based volumetric measurement suits conductive aqueous streams with consistent salinity profiles at onshore treatment facilities.
- Thermal:Heat-transfer principles enable low-flow sensitivity for leak detection and flare minimization applications in chemical manufacturing.
Ultrasonic technology is expanding most quickly; Coriolis maintains the deepest installed base.
End User:
Regulatory exposure and water-handling intensity concentrate demand across energy and process industries.
- Oil & Gas:Upstream producers and midstream operators face the most stringent methane monitoring mandates. EPA Quad Oa enforcement compresses replacement cycles for non-compliant systems at onshore facilities while BSEE rules govern offshore platform specifications.
- Chemical Manufacturing:Batch process variability and episodic effluent characterization create rental-heavy procurement patterns. Texas Gulf Coast clusters separate hardware purchases from calibration subscriptions.
- Wastewater Treatment:Municipal and industrial facilities deploy meters for hydrocarbon detection in influent streams prior to biological treatment stages.
- Power Generation:Combined cycle plants monitor aqueous blowdown and cooling tower discharge for VOC content under Clean Air Act permits.
Oil and gas dominates volume; chemical manufacturing shows the steepest expansion trajectory.
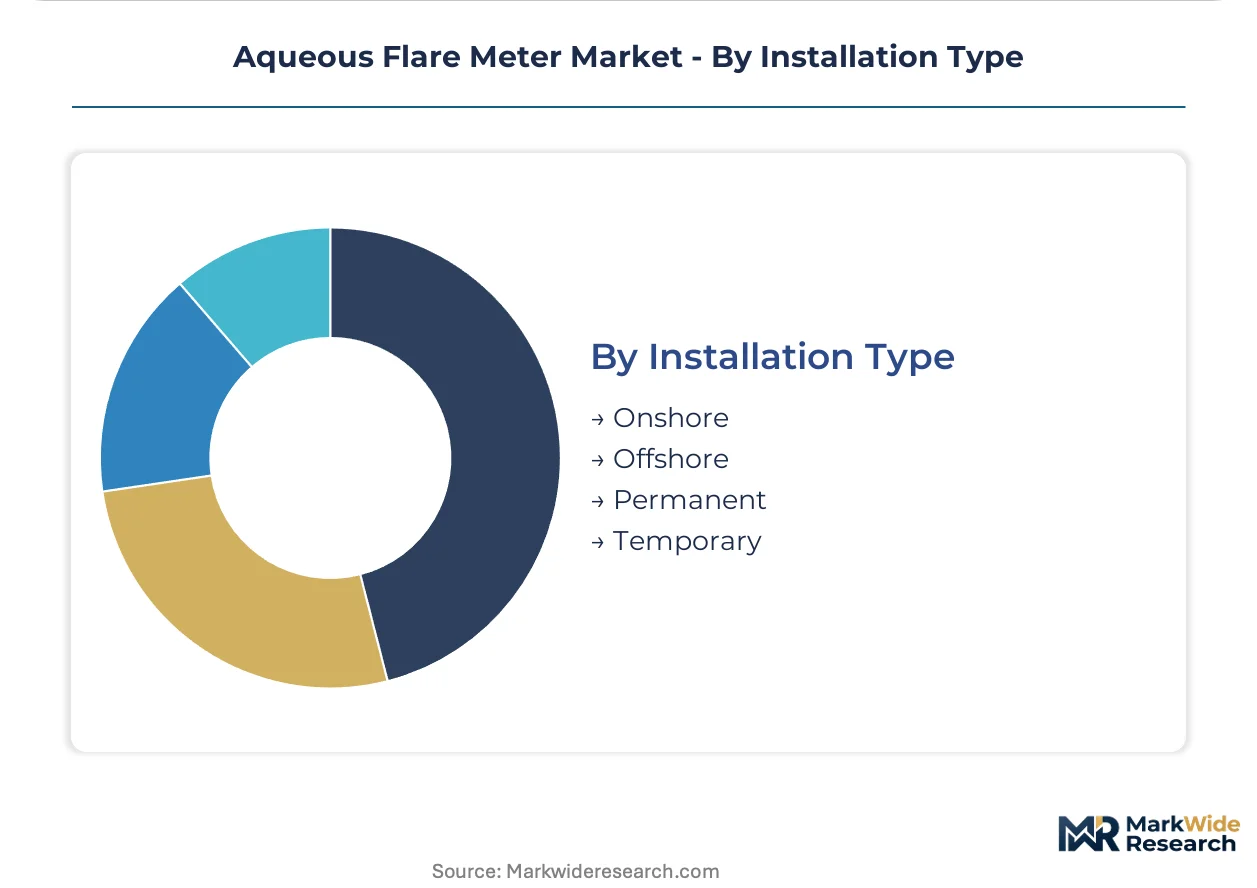
Installation Type:
Physical environment and deployment duration shape specification requirements and service access economics.
- Offshore:Platform-mounted systems endure salt spray, vibration, and limited maintenance windows. BSEE safety documentation and ATEX certification requirements extend procurement lead times.
- Onshore:Refinery and treatment facility installations benefit from proximate calibration infrastructure along the Texas-Louisiana corridor.
- Permanent:Capital-intensive deployments with 20-year amortization horizons demand predictive maintenance integration and digital twin compatibility.
- Temporary:Rental units for turnaround inspections, EPA audit response, and pilot-scale process validation.
Offshore installations command the highest unit values; temporary deployments are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates aqueous flare meter demand through Gulf Coast refining clusters, while Norway's North Sea offshore sector drives premium specifications for sour service applications. Regulatory divergence between EPA methane mandates and EU industrial emissions frameworks creates distinct procurement patterns across Atlantic markets.
United States
Offshore platform retrofits in the Gulf of Mexico and Permian Basin produced water recycling projects dominate procurement volumes. EPA Quad Oa enforcement compresses replacement cycles for non-compliant monitoring systems at onshore oil and gas facilities. The Texas-Louisiana refining corridor anchors calibration infrastructure concentration, though service access gaps persist for Permian Basin operators.
Norway
North Sea offshore installations specify corrosion-resistant meters for high-H2S wellstream conditions in mature oil fields. The country's national petroleum regulator enforces stringent material traceability documentation through BSEE-aligned safety protocols. Stavanger and Bergen host engineering clusters where operators pilot next-generation ultrasonic designs for platform deployment.
Germany
Chemical manufacturing complexes along the Rhine-Ruhr corridor generate rental-heavy demand for portable validation meters during turnaround inspections. EU REACH regulations constrain wetted material selection for aqueous flare systems handling complex effluent streams. BASF and Bayer facility clusters near Ludwigshafen and Leverkusen drive episodic procurement for EPA audit response support.
Brazil
Pre-salt offshore development in the Santos Basin requires multi-phase meters capable of handling extreme gas-liquid ratio variations. The country's national petroleum regulator, ANP, mandates continuous flare monitoring at floating production facilities. Rio de Janeiro engineering centers coordinate specification alignment between operator procurement teams and international meter vendors.
Saudi Arabia
Gas processing expansion at Jubail and Yanbu industrial cities creates demand for fixed installations integrating with distributed control architectures. The national hydrocarbon regulator enforces flare minimization protocols aligned with Saudi Vision 2030 sustainability targets. Eastern Province clusters concentrate procurement decision-making for offshore Arabian Gulf platform retrofits.
Aqueous Flare Meter Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across technology tiers in the aqueous flare meter market. Emerson Electric Co., ABB Ltd, and Siemens AG anchor the diversified tier with automation platform bundling capabilities, while Endress+Hauser Group and KROHNE Group occupy specialist positions through calibration service anchoring. Market structure tilts toward consolidation at the premium tier where intrinsic safety certification requirements create barriers. Dominant competitive moves include strategic partnerships for digital twin integration and geographic expansion through certified flow laboratory replication.
Within the diversified industrial automation tier, Emerson Electric Co. and ABB Ltd exemplify platform-centric positioning that bundles flare meter hardware with distributed control systems and predictive analytics software. Endress+Hauser Group represents the specialist archetype through calibration laboratory networks that anchor long-term service contracts and recurring revenue streams. Yokogawa Electric Corporation occupies a position bridging both tiers with regional strength in Asia-Pacific offshore markets. KROHNE Group and Baker Hughes Company sit within the energy-focused specialist segment where sour service expertise and material science capabilities differentiate positioning.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| Endress+Hauser Group |
| ABB Ltd |
| Yokogawa Electric Corporation |
| Siemens AG |
| Schneider Electric SE |
| Baker Hughes Company |
| KROHNE Group |
| Kowa American Corporation |
| Others |
Value Chain & Pricing Dynamics
Integrated Gulf Coast refiners and Permian Basin shale operators concentrate procurement volumes, anchoring contract-based long-term offtake agreements that bundle hardware with multi-year calibration service subscriptions.
Pricing Analysis
Capacity additions in Germany and Japan are reshaping price floors for Coriolis meter assemblies. Three-tier pricing structure across premium, standard, and economy levels separates ATEX-certified offshore platforms from onshore chemical rental units. Price differentiation hinges on intrinsic safety certification grade and geographic delivery cost to remote Permian Basin facilities. Cost compression in the portable meter tier is intensifying because independent shale producers unbundle service contracts. Midstream water-handling facilities show highest price sensitivity; offshore platform operators show lowest.
Supply Chain Analysis
Single-source vulnerability sits with Japanese specialty alloy foundries supplying Hastelloy C-276 wetted components. Manufacturing concentrates in Germany, the United States, and Japan for precision Coriolis tube assemblies and ultrasonic transducer arrays. Raw material dependencies include titanium sponge, gamma-ray densitometry sources, and high-temperature ceramic insulators. Tariff exposure on Chinese rare earth magnets for electromagnetic meter coils threatens cost stability. Distribution runs through authorized instrumentation distributors with factory-trained service technicians.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The aqueous flare meter market functions as a regulatory compounder where EPA Quad Oa methane enforcement creates replacement-driven demand independent of commodity price cycles.
For Market Incumbents: Anchor market position through backward integration into specialty alloy casting for sour service wetted materials. Defend against ultrasonic specialist entrants by accelerating ATEX certification timelines for next-generation clamp-on designs. Prioritize calibration laboratory replication in the Permian Basin to close service access gaps threatening long-term contract renewals. For New Entrants and Emerging Players: Enter via portable validation meter rentals for Texas Gulf Coast chemical turnaround inspections. Target underpenetrated produced water recycling facilities in New Mexico where real-time hydrocarbon detection specifications remain unsettled. Pursue white-label partnerships with midstream water-handling facility engineering procurement and construction contractors as the fastest channel to operator specification lists. For Investors and Strategic Acquirers: Industrial automation conglomerates seeking sensor portfolio completeness are the most active acquirer in this space. Five-to-ten year viability rests on digital twin integration capabilities rather than hardware manufacturing scale. Acquisition target archetype: ultrasonic technology specialists with existing BSEE safety documentation and Gulf of Mexico operator relationships. Signal to watch: California CARB methane protocol adoption rates as leading indicator for next-generation specification shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Laboratory Expansion | Permian Basin service infrastructure closes geographic gaps threatening incumbent contract renewals. |
| Ultrasonic Transducer Array Development | Non-intrusive designs displace insertion meters in high-H2S Gulf of Mexico sour service conditions. |
| Digital Twin Platform Integration | Predictive analytics bundling with meter hardware captures recurring software subscription revenue streams. |
| Specialty Alloy Backward Integration | In-house Hastelloy casting insulates margin pressure from volatile titanium and nickel supply chains. |
| Portable Meter Rental Service Launch | Episodic chemical manufacturing demand in Texas Gulf Coast creates asset-light revenue without capital intensity. |
Study Parameters
Bottom-up oil and gas operator modeling reconciled against top-down instrumentation vendor shipment tracking forms the analytical core. Primary interviews with refinery maintenance directors, midstream water-handling facility engineers, EPA compliance officers, calibration laboratory technicians, and distributed control system integrators were validated against secondary sources including EPA enforcement action databases, BSEE safety incident reports, SEC 10-K filings from listed automation vendors, and customs trade data for specialty alloy imports. Triangulation between procurement-side demand signals and supply-side production volumes ensures consistency across market sizing estimates.
Historical trendline analysis of replacement cycle patterns and regulatory compliance deadline clustering informed the projection framework. Segmentation dimensions modeled include product type, measurement technology, end-use industry, and installation environment across the projection horizon. CAGRs were derived from weighted scenario analysis incorporating EPA enforcement intensity variations and offshore platform decommissioning schedules. Industry-specific forecast inputs include produced water volume projections from Permian Basin drilling activity and methane emission reduction targets from operator sustainability disclosures.
Inputs from EPA enforcement databases and BSEE safety documentation were available through the study window; gaps in real-time vendor shipment data introduce uncertainty bands around technology segment splits. Forecasts reflect assumptions about regulatory timeline adherence and specialty alloy price stability. Specific risk factors that could revise projections include delayed Quad Oa enforcement, accelerated ultrasonic signal processing breakthroughs, or Gulf of Mexico hurricane disruption to offshore maintenance schedules. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Digital Twin in Oil and Gas Market
Oil & Gas
East Africa Oil and Gas Market
Oil & Gas
Asia-Pacific AI in Oil and Gas Market
Oil & Gas
Global Oilfield Stimulation Chemicals Market
Oil & Gas
Saudi Arabia Drilling Services Market
Oil & Gas
South America LNG Bunkering Market
Oil & Gas
Iraq Oil and Gas Market
Oil & Gas
GCC Natural Gas Market
Oil & Gas
South Korea Oil and Gas Market
Oil & Gas
Thermal Spray Coating for Oil and Gas Market
Oil & Gas
Leak Detection for Oil & Gas Market
Oil & Gas
Bunker Liners Market
Oil & Gas
Floating Liquefied Natural Gas (FLNG) Terminals Market
Oil & Gas
Oil and Gas Separator Market
Oil & Gas
Oil and Gas Infrastructure Market
Oil & Gas
Global Seismic Survey Market