
 Middle-East Oilfield Services Market | 2026-2036
Middle-East Oilfield Services Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East Oilfield Services Market Outlook
National oil companies are reorganizing procurement priorities around in-country value and digital integration, shifting contract awards away from pure cost-based selection. Schlumberger Limited leverages integrated drilling and evaluation portfolios to anchor long-term framework agreements with Saudi Aramco. Halliburton Company sustains dominance in completion technologies across Kuwait and Qatar through localized manufacturing partnerships. Baker Hughes Co differentiates via turbomachinery and artificial lift systems tailored to high-sour gas conditions in the UAE.
Middle-East oilfield services encompass the technical labor, equipment, and engineered systems required to drill, complete, maintain, and enhance hydrocarbon production from subsurface reservoirs, spanning well depths from 3,000 to over 25,000 feet with bottom-hole temperatures regularly exceeding 150°C. Drilling services command the largest revenue pool due to sustained rig demand for offshore gas development, while digital oilfield technology represents the fastest-expanding segment as operators deploy real-time monitoring and predictive analytics to optimize artificial lift performance and reduce non-productive time. Completion services concentrate margin in complex multi-stage hydraulic fracturing for tight gas formations, particularly in Saudi Arabia's unconventional Jafurah basin.
Saudi Arabia's IKTVA program and the UAE's ADNOC In-Country Value framework reshape contractor eligibility by mandating local workforce development and domestic supply chain spending. The country's national petroleum regulator and environmental authority enforce well integrity standards and flaring reduction targets that elevate demand for well intervention and emissions monitoring services. Stakeholders must monitor how localization thresholds and carbon intensity benchmarks redefine competitive positioning for international service providers seeking access to Gulf NOC tender programs.
Market Dynamics
Saudi Arabia's IKTVA localization mandates and ADNOC's In-Country Value framework are restructuring contractor eligibility, forcing international service providers to reconfigure supply chains and workforce composition to maintain access to Gulf NOC tender programs.
Growth Catalysts
- Jafurah Unconventional Development:Saudi Aramco's tight gas expansion requires multi-stage hydraulic fracturing and advanced completion technologies, pulling specialized service capacity into the Kingdom.
- Offshore Gas Redevelopment:ADNOC's Upper Zakum and sour gas field upgrades demand high-specification drilling rigs and corrosion-resistant completion systems.
- Digital Oilfield Mandates:Real-time production optimization platforms are reducing non-productive time across mature onshore basins in Kuwait and Qatar.
Market Restraints
- Steel Alloy Input Volatility:Premium OCTG and specialty metallurgy costs fluctuate with nickel and chromium pricing, compressing drilling contractor margins on fixed-price frameworks.
- Specialized Labor Concentration:Directional drilling and well intervention expertise clusters in Houston and Aberdeen, creating mobility bottlenecks for rapid project ramp-ups.
- Well Integrity Standards:Saudi Arabia's national petroleum regulator enforces casing pressure testing protocols that extend rig mobilization timelines.
Strategic Opportunities
- Oman Gas Expansion:BP's Khazzan tight gas development and PDO's enhanced oil recovery programs offer under-tapped demand for artificial lift and water injection services.
- Hydrogen-Ready Infrastructure:Blue hydrogen pilot projects in the UAE require modified wellhead equipment and CO2 injection expertise transferable from EOR experience.
- Local Manufacturing Partnerships:IKTVA's domestic spending thresholds incentivize joint ventures for pressure pumping equipment assembly in Dammam industrial zones.
Industry Challenges
- Directional Drilling Talent Gap:Geosteering and rotary steerable system operation skills outpace regional training pipeline output, forcing reliance on expatriate rotations.
- Legacy SCADA Integration:Digital oilfield platforms must interface with decades-old wellsite control architectures, complicating real-time data standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East Oilfield Services Market |
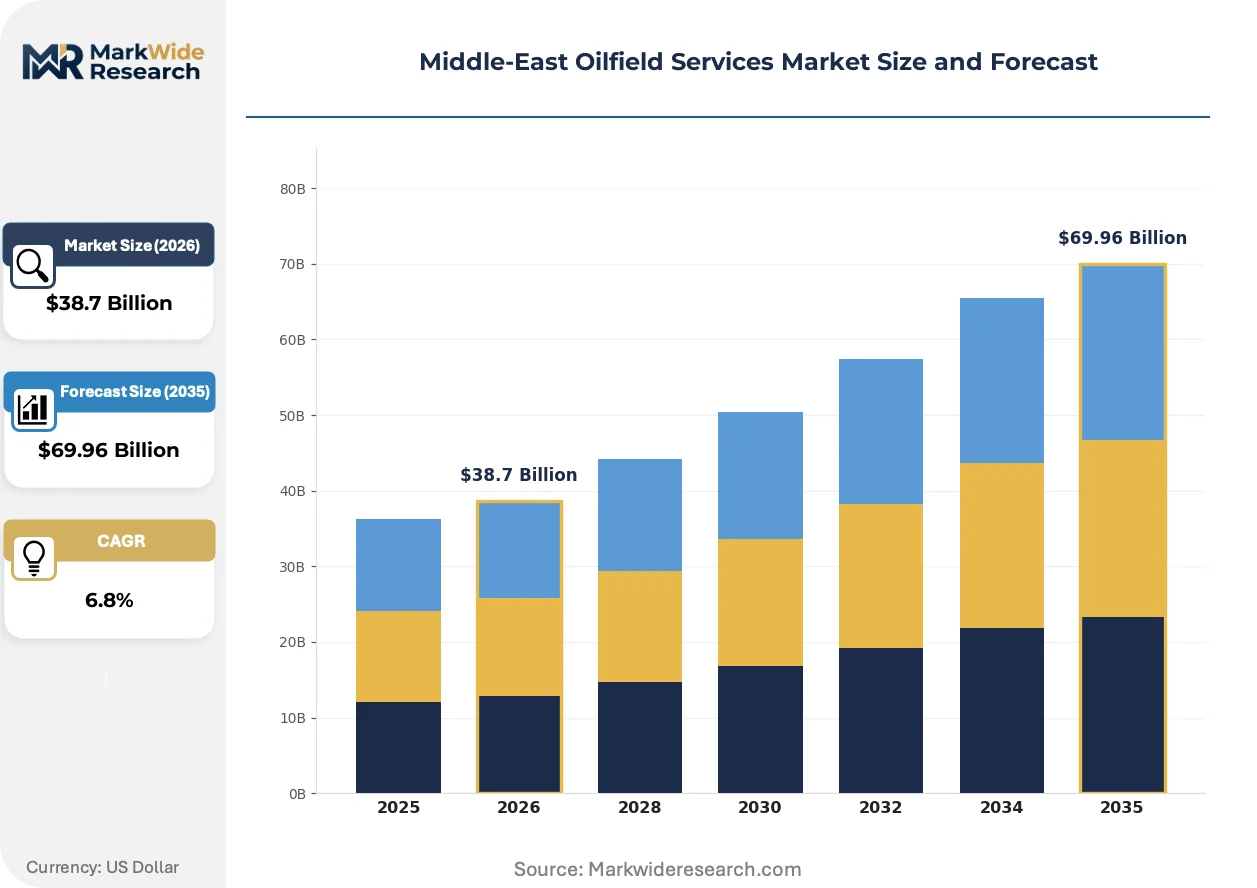
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Drilling, Completion, Production, Well Services Technology: Conventional, Digital Oilfield, Enhanced Oil Recovery, Artificial Lift End User: National Oil Companies, Independent Operators, Service Providers, Multi-National Corporations Application: Offshore, Onshore, Shale, Heavy Oil |
| Companies Covered | Weatherford International PLC, Anton Oilfield Services (Group) Ltd, Schlumberger Limited, ADNOC Drilling, National Energy Services Reunited Corp, Halliburton Company, Welltec A/S, Swire Oilfield Services Ltd, Baker Hughes Co, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East Oilfield Services Market Strategic Shifts
Automation and predictive analytics are redefining how reservoir performance is managed, while regulatory pressure on emissions and localization accelerates technology refresh cycles across contractor portfolios.
Automated drilling systems are bifurcating the rig fleet into high-specification units capable of continuous optimization and legacy mechanical rigs facing accelerated retirement. National oil companies in Saudi Arabia and the UAE are prioritizing intelligent drilling packages on new offshore tenders. This technology compression is consolidating day-rate premiums around automation-enabled performance guarantees rather than equipment age.
Saudi Arabia's environmental authority enforces flaring reduction targets that elevate demand for closed-loop mud systems and vapor recovery units. Operators must deploy continuous emissions monitoring to maintain production licenses. The regulation most affects mature onshore fields in the Kingdom's Eastern Province, where service providers are retrofitting legacy facilities with methane detection networks.
Performance-based contracting is displacing traditional day-rate structures in offshore drilling procurement. Contractors assume reservoir outcome risk through integrated service packages covering drilling, completion, and initial production. This model concentrates most visibly in ADNOC's offshore redevelopment tenders, where operators seek guaranteed production delivery rather than discrete service execution.
Middle-East Oilfield Services Market Segmentation
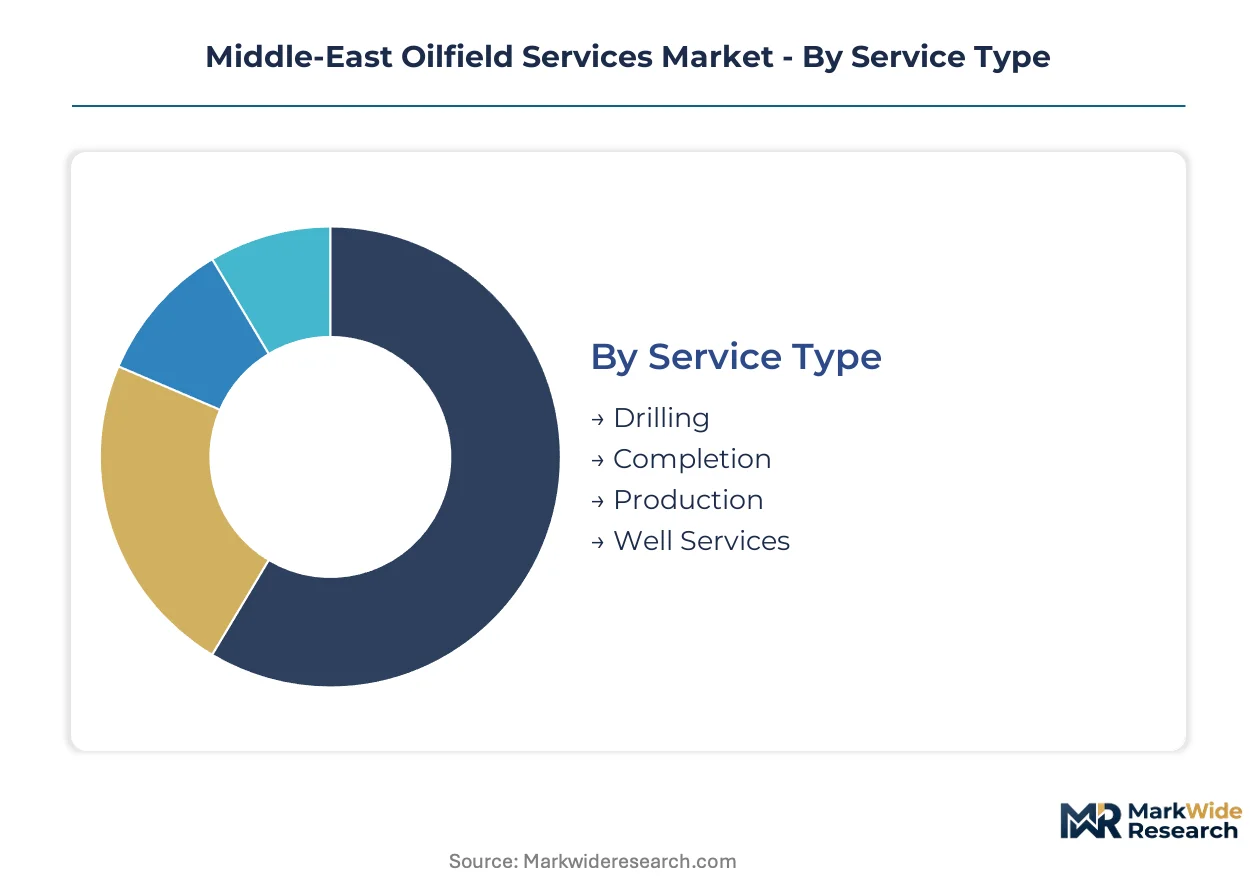
Service differentiation in Middle-East oilfield procurement reflects divergent regulatory pressures across Saudi Arabia, the UAE, and Kuwait. National oil companies weight contract awards toward segments demonstrating compliance with localization mandates and emissions benchmarks.
Service Type:
Saudi Arabia's national petroleum regulator and environmental authority enforce distinct well integrity and flaring standards that elevate technical requirements for specific service categories.
- Drilling:High-specification rigs equipped with automated pipe handling and real-time pressure monitoring dominate offshore gas tenders in the UAE. ADNOC's Upper Zakum redevelopment demands corrosion-resistant metallurgy for sour gas conditions, compressing contractor qualification pools.
- Completion:Multi-stage hydraulic fracturing packages command premium positioning in Saudi Arabia's Jafurah tight gas development. IKTVA localization thresholds force international providers to assemble pressure pumping equipment within Dammam industrial zones to maintain tender eligibility.
- Production:Artificial lift optimization and surface facility maintenance concentrate in Kuwait's mature Burgan field operations.
- Well Services:Intervention, workover, and plug-and-abandonment activities respond to Saudi Arabia's casing pressure testing protocols.
Established volume favors Drilling; emerging adoption favors Completion.
Technology:
Cost tier differentiation separates legacy mechanical systems from digitally integrated platforms commanding performance guarantees.
- Conventional:Mechanical drilling rigs and standard artificial lift systems serve marginal onshore fields in Oman and Bahrain where capital constraints limit technology refresh cycles.
- Digital Oilfield:Real-time production optimization platforms deploy predictive analytics to reduce non-productive time across Qatar's mature North Field operations. Integration with legacy SCADA architectures remains the primary deployment bottleneck.
- Enhanced Oil Recovery:Thermal and chemical EOR methods target heavy oil formations in Kuwait's Ratqa field and Oman's Mukhaizna development.
- Artificial Lift:Electric submersible pumps and gas lift systems optimize production from high-temperature, high-sour gas wells in the UAE's Shah field.
Conventional systems retain installed base dominance; Digital Oilfield climbs the fastest on new tender requirements.
End User:
Customer type determines procurement sophistication, with national oil companies driving integrated service packaging.
- National Oil Companies:Saudi Aramco, ADNOC, and KPC anchor regional demand through multi-year framework agreements. IKTVA and In-Country Value mandates restructure supplier eligibility around domestic workforce ratios and local supply chain spending.
- Independent Operators:Smaller producers in Oman and Bahrain pursue discrete service contracts with shorter cycle times and lower localization thresholds.
- Service Providers:Subcontractor tiers execute specialized directional drilling and well intervention under prime contractor management.
- Multi-National Corporations:IOCs with production-sharing contracts in Qatar and Iraq operate under distinct procurement protocols from NOC direct hires.
National Oil Companies concentrate contract value; Independent Operators create entry points for specialized technology providers.
Application:
Geology and water depth dictate equipment specifications and contractor capability requirements across the Gulf.
- Offshore:High-specification jackup and platform rigs serve ADNOC's Upper Zakum and Saudi Aramco's Manifa developments. Sour gas corrosion challenges elevate metallurgy standards for subsea completion systems.
- Onshore:Mature basins in Kuwait's Burgan field and Saudi Arabia's Ghawar require continuous well intervention and artificial lift optimization to sustain plateau production.
- Shale:Saudi Arabia's Jafurah basin represents the region's primary unconventional focus, demanding multi-stage fracturing and horizontal drilling expertise.
- Heavy Oil:Steam-assisted gravity drainage and thermal EOR methods target high-viscosity reserves in Kuwait and Oman.
Onshore operations retain the deepest contractor footprint; Shale applications attract the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Service exports from Dammam and Abu Dhabi flow toward offshore gas developments across the Gulf, with procurement patterns diverging sharply between Saudi Arabia's localization mandates and the UAE's performance-based contracting frameworks.
Saudi Arabia
Jafurah tight gas development and offshore Manifa expansion anchor service demand. The national petroleum regulator enforces casing pressure testing protocols under IKTVA localization mandates. Dammam industrial zones concentrate pressure pumping equipment assembly to meet domestic spending thresholds.
United Arab Emirates
Upper Zakum offshore redevelopment and Shah sour gas field upgrades drive high-specification rig demand. ADNOC's In-Country Value framework restructures supplier eligibility around workforce ratios. Abu Dhabi serves as the procurement hub for corrosion-resistant completion systems.
Kuwait
Burgan field artificial lift optimization and Ratqa heavy oil thermal EOR sustain mature basin service intensity. The national oil company maintains multi-year framework agreements with strict local content requirements. Ahmadi district clusters well intervention contractors serving plateau production maintenance.
Oman
Khazzan tight gas development and PDO enhanced oil recovery programs generate demand for water injection and artificial lift services. Petroleum Development Oman operates under distinct procurement protocols favoring long-cycle partnerships. Muscat coordinates subcontractor tiers for directional drilling mobilization.
Qatar
North Field gas expansion sustains completion and drilling service commitments through offshore platform development. QatarEnergy pursues integrated service packaging for reservoir outcome guarantees. Ras Laffan industrial city hosts contractor logistics for high-temperature wellsite operations.
Middle-East Oilfield Services Market Competitive Environment
Listed leaders compete with private specialists across technology integration and localization compliance, creating a tiered structure where scale advantages concentrate in framework agreements with national oil companies. The vendor base separates into three strategic archetypes: integrated service providers bundling drilling through production, specialized technology vendors targeting unconventional or sour gas applications, and regional contractors leveraging domestic workforce quotas. Consolidation pressures favor M&A activity around digital oilfield capabilities, while capacity expansion concentrates in Dammam and Abu Dhabi industrial zones to satisfy IKTVA and In-Country Value spending mandates.
Within the integrated service tier, Schlumberger Limited and Halliburton Company occupy positions exemplifying long-term framework anchoring with Saudi Aramco and regional NOCs. Baker Hughes Co represents the specialized technology archetype through turbomachinery and artificial lift positioning. Among regional contractors, ADNOC Drilling exemplifies state-affiliated scale advantages under Abu Dhabi's localization mandates. Weatherford International PLC sits within the well intervention and completion specialist tier serving mature basin redevelopment across Kuwait and Qatar.
| Leading Market Players |
|---|
| Weatherford International PLC |
| Anton Oilfield Services (Group) Ltd |
| Schlumberger Limited |
| ADNOC Drilling |
| National Energy Services Reunited Corp |
| Halliburton Company |
| Welltec A/S |
| Swire Oilfield Services Ltd |
| Baker Hughes Co |
| Others |
Value Chain & Pricing Dynamics
Saudi Arabia's IKTVA certification regime gates tender eligibility while simultaneously stratifying contractor pricing power, compressing international providers who lack domestic assembly capacity while elevating joint-venture premiums. This regulatory filter reshapes how service tiers are priced across the Gulf.
Pricing Analysis
Next-generation automated drilling packages command day-rate premiums against legacy mechanical rigs facing accelerated retirement, while conventional systems compete on marginal cost. Price differentiation rests on localization compliance scores and digital integration depth. Cost compression in standard drilling tiers intensifies as fixed-price frameworks absorb steel alloy volatility. National oil companies exhibit lowest price sensitivity for sour-gas-qualified completion systems; independent operators in Oman and Bahrain drive hardest bargain on conventional well services.
Supply Chain Analysis
Strategic stockpiling of premium OCTG and specialty metallurgy dominates contractor inventory strategy against just-in-time approaches for standard consumables. Manufacturing concentrates in the United States, Germany, and Japan for high-specification drilling equipment and corrosion-resistant alloys. Raw material dependencies center on nickel, chromium, and high-grade steel feedstocks. Single-source vulnerability runs through specialized directional drilling component suppliers. Distribution feeds from Dammam and Abu Dhabi industrial zones into offshore project logistics hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geosteering expertise and rotary steerable system operation skills outpace regional training pipeline output, creating persistent capability gaps that reshape competitive access for contractors across Saudi Arabia and the UAE.
For Market Incumbents: Fortify framework agreement anchoring with Saudi Aramco and ADNOC through accelerated IKTVA compliance investments in Dammam assembly capacity. Deepen backward integration into pressure pumping equipment manufacturing to defend margin position against emerging Chinese competitors. Prioritize digital oilfield certification pathways that exceed national petroleum regulator baseline requirements. For New Entrants and Emerging Players: Well intervention service gaps in Kuwait's mature Burgan field operations present under-served white-space where incumbents prioritize offshore gas premiums. Target Oman's Khazzan tight gas development for artificial lift specialization with lower localization thresholds than Saudi tenders. Pursue partnership-first go-to-market with established regional contractors to bypass prime contractor qualification barriers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across digital oilfield platform development as real-time analytics capabilities separate viable contractors from commodity service providers. Long-term viability favors integrated service providers with proven framework agreement histories and captive technology pipelines. Acquisition target archetype: specialized sour gas completion technology vendors with ADNOC qualification history. Signal to watch: IKTVA enforcement intensity against international provider joint-venture structures.| Strategic Initiative | Industry Significance |
|---|---|
| Localization Joint Venture Formation | IKTVA-compliant partnerships unlock Saudi Aramco tender eligibility for international pressure pumping specialists. |
| Digital Oilfield Platform Integration | Real-time SCADA interoperability differentiates contractors in ADNOC's performance-based offshore procurement. |
| Sour Gas Metallurgy Certification | Corrosion-resistant completion system qualification expands addressable market into UAE Shah field upgrades. |
| Regional Training Academy Investment | Domestic geosteering talent pipelines reduce expatriate rotation costs and accelerate rig mobilization timelines. |
| Backward Integration into OCTG Supply | Captive steel alloy sourcing insulates drilling margins from nickel and chromium price volatility. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with drilling operations directors, procurement leads at national oil companies, EPC contractors, and well intervention specialists; and secondary validation against customs trade data, national petroleum regulator filings, IEA Middle-East upstream investment reports, and contractor SEC disclosures. Bottom-up service segment sizing triangulated against top-down NOC capital expenditure patterns.
Across the projection horizon, the analytical framework modeled demand across service type, technology tier, end-user procurement sophistication, and application geology. CAGRs derived from rig count trajectories, well completion intensity benchmarks, and localization spending enforcement curves. Forecast inputs incorporated Saudi Aramco's Jafurah development pace and ADNOC's Upper Zakum redevelopment timeline.
Underlying assumptions cover sustained oil price bands supporting unconventional gas economics, with deviation risk concentrated in IKTVA enforcement intensity and steel alloy cost trajectories. Revision becomes warranted when national oil company localization thresholds cross compliance feasibility thresholds for mid-tier international contractors.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Oil and Gas Separator Market
Oil & Gas
Russia Oil and Gas EPC Market
Oil & Gas
Rotary Steerable System Market
Oil & Gas
Casing and Cementation Hardware Market
Oil & Gas
Wireline Logging Services Market
Oil & Gas
Romania Oil and Gas Upstream Market
Oil & Gas
Indonesia Oil and Gas Midstream Market
Oil & Gas
LAMEA Oilfield Auxiliary Rental Equipment Market
Oil & Gas
Asia-Pacific Small-Scale LNG Market
Oil & Gas
Land Drilling Rig Market
Oil & Gas
Hydraulic Fracturing Market
Oil & Gas
Subsea Manifolds Market
Oil & Gas
Open Hole Logging Services Market
Oil & Gas
Intelligent Well Completion Market
Oil & Gas
Europe Oilfield Equipment Rental Services Market
Oil & Gas
Expandable Liner Hanger System Market