
 Electrochromic Glass for Construction Market | 2026-2036
Electrochromic Glass for Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Electrochromic Glass for Construction Market Foresight
Commercial property developers is collapsing as the dominant buyer archetype while residential architects gain specification authority for electrochromic installations. SageGlass leverages its solid-state technology leadership to anchor high-rise facade projects across North America. View, Inc. competes through vertically integrated manufacturing that controls ion conductor deposition and final glass lamination. Gentex Corporation extends its automotive electrochromic expertise into commercial construction channels.
Electrochromic glass for construction consists of multi-layer laminated assemblies incorporating tungsten oxide or nickel oxide electrochromic films, lithium ion conductors, and transparent conductive oxide coatings that modulate visible light transmission and solar heat gain when voltage is applied. The technology serves primarily to reduce HVAC loads and artificial lighting requirements in enclosed structures. Switchable product variants dominate current specification volumes while photovoltaic-integrated electrochromic panels represent the fastest-growing structural segment due to combined energy generation and dynamic shading functionality. Application demand concentrates in commercial buildings where facade retrofits and new construction command premium pricing, whereas residential structures remain a developing margin pool constrained by installed cost sensitivity.
The EU Green Deal and REACH chemical compliance frameworks mandate reduced embodied carbon in building materials while the EPA Energy Star program and ASHRAE standards in the United States establish performance baselines that dynamic glazing satisfies. China's GB standards and dual carbon goals from MEE further accelerate electrochromic adoption in public and commercial construction. Stakeholders must monitor evolving certification requirements for circular material content and ion conductor chemistries as regulatory scope expands beyond operational energy into full lifecycle building impacts.
Market Dynamics
Energy code ratcheting across major construction markets is forcing dynamic glazing specification into standard practice rather than premium positioning, compressing the decision window for facade material selection.
Growth Catalysts
- EU Green Deal building performance mandates:Operational energy limits in commercial construction now require solar heat gain modulation that only electrochromic assemblies satisfy.
- Tungsten oxide film deposition advances:Sputtering process improvements have reduced switching latency to under three minutes, enabling specification for occupied spaces.
- China's dual carbon policy enforcement:MEE inspection protocols for public buildings now penalize excessive HVAC loads that static glazing generates.
Market Restraints
- Lithium carbonate price volatility:Ion conductor raw material swings of forty percent annually destabilize electrochromic laminate cost structures.
- Transparent conductive oxide supply concentration:Indium tin oxide sputtering targets originate from three dominant East Asian refiners, creating single-source vulnerability.
- REACH chemical registration complexity:Novel nickel oxide formulations face eighteen-month authorization timelines that freeze product iteration cycles.
Strategic Opportunities
- Residential retrofits in Germany:KfW efficiency subsidies now cover dynamic glazing upgrades for multi-family housing stock built before 1990.
- Photovoltaic-electrochromic convergence:BIPV facade systems that generate power while modulating transmission are capturing specification in net-zero commercial projects.
- Direct-to-developer digital specification platforms:Facade design software integration allows real-time electrochromic performance simulation during schematic design phases.
Industry Challenges
- Thin-film electrochemist talent scarcity:The specialized workforce for multi-layer deposition and ionic conductor optimization remains concentrated in automotive and display industries.
- ASTM E2141-21 certification duration:Cyclic durability testing requires fourteen months of accelerated aging before commercial approval.
- Legacy building management system integration:BACnet protocol translation for electrochromic voltage control demands custom middleware development per project.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electrochromic Glass for Construction Market |
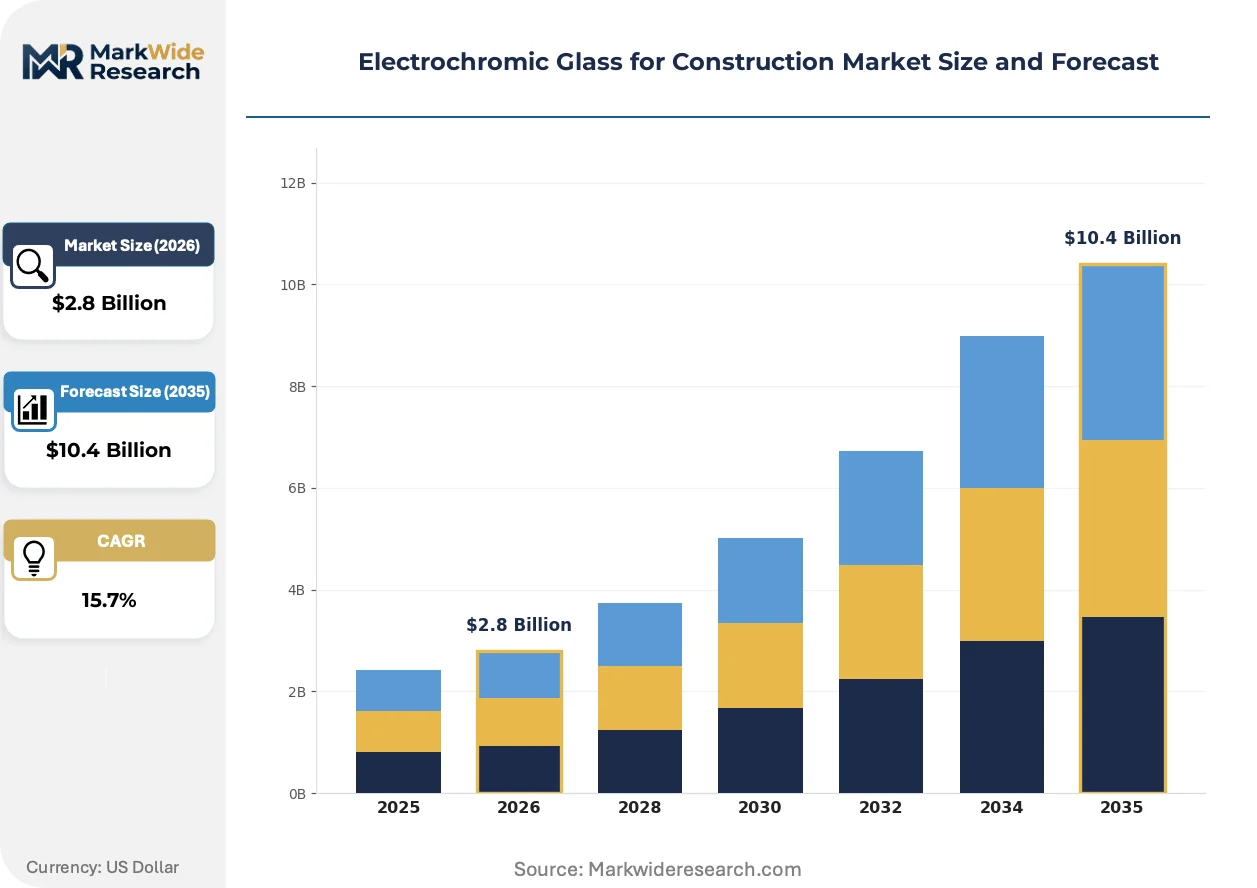
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $10.4 Billion |
| CAGR (2026 – 2036) | 15.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Switchable, Self-Tinting, Thermochromic, Photovoltaic Application: Commercial Buildings, Residential Structures, Facades, Skylights Technology: Solid-State, Liquid-Crystal, Polymer-Based, Nano-Material End User: Architects, Builders, Contractors, Property Developers |
| Companies Covered | View, Inc., SageGlass, Gentex Corporation, ChromoGenics, AGC Inc., PPG Industries, Saint-Gobain, Halio Inc., Gauzy Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electrochromic Glass for Construction Market Shifts & Advancements
Electrochromic technology is migrating from discrete facade components toward integrated building envelope systems that combine generation, modulation, and sensing functions in unified assemblies.
Solid-state lithium ion conductors are supplanting liquid electrolyte architectures in electrochromic laminates. Commercial developers in the United States specify solid-state variants for high-rise projects where leakage risk carries liability exposure. The shift is compressing warranty terms for legacy liquid-electrolyte suppliers and redirecting R&D budgets toward ceramic ion conductor development.
REACH Annex XIV authorization requirements for nickel compounds are tightening substitution timelines for electrochromic manufacturers. The regulation forces reformulation of cathodic electrochromic layers toward tungsten oxide dominance or organic hybrid alternatives. German facade engineering firms are accelerating material qualification programs to maintain specification eligibility for EU public procurement.
Performance-based facade procurement contracts are displacing traditional material-specification purchasing in commercial construction. Developers now contract for guaranteed HVAC load reduction rather than glazing product delivery, transferring operational risk to electrochromic system integrators. This model concentrates in California and New York where utility incentive structures reward verified energy outcomes over installed equipment capacity.
Electrochromic Glass for Construction Market Segmentation
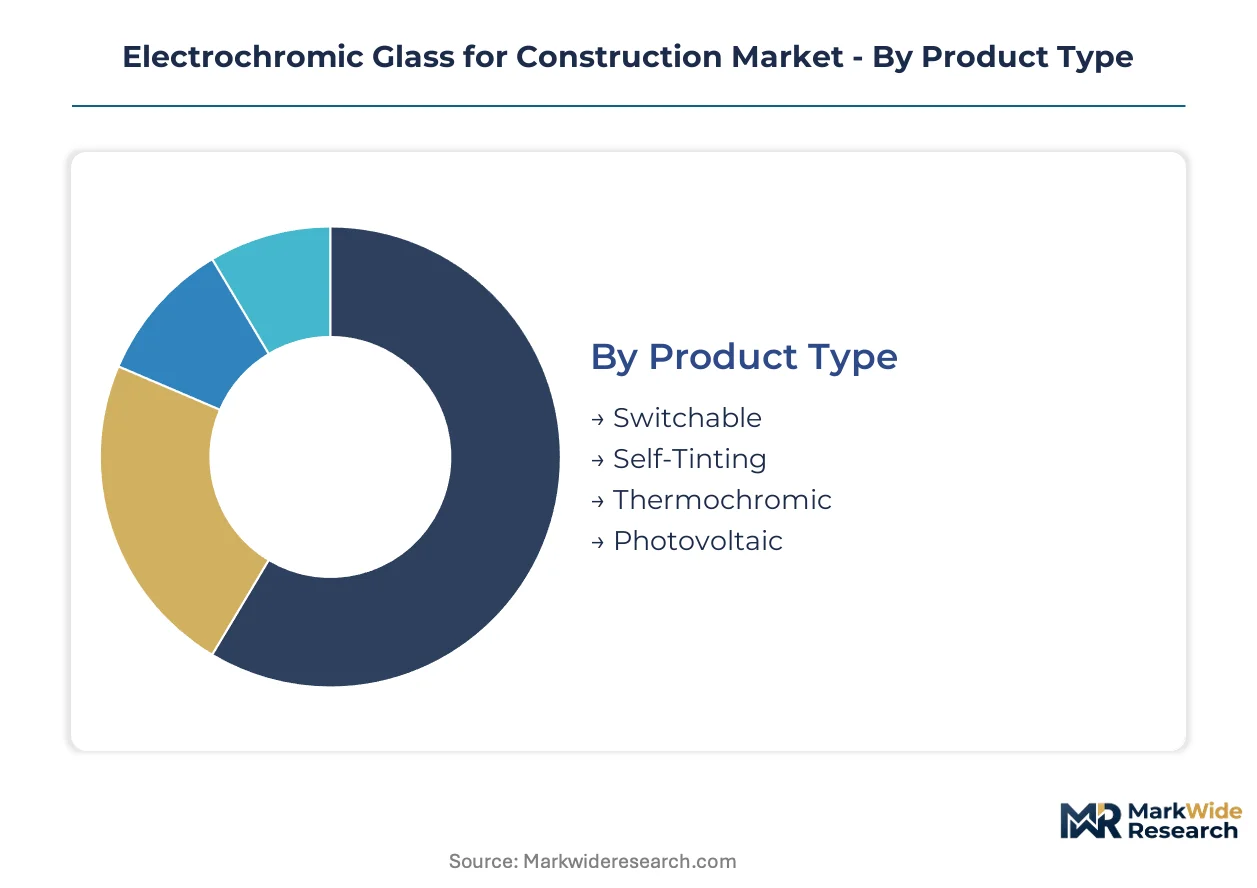
Electrochromic glass segmentation reveals where substitution pressure from static glazing and dynamic shading alternatives reshapes competitive boundaries. Category boundaries increasingly blur as photovoltaic integration and solid-state architectures create hybrid product definitions.
Product Type:
Switchable variants face intensifying substitution pressure from electrochromic alternatives that eliminate manual control dependencies.
- Switchable:Multi-layer laminated assemblies with tungsten oxide films and lithium ion conductors enable manual or automated tint modulation via applied voltage. Demand concentrates in United States commercial high-rises where ASHRAE 90.1 compliance mandates solar heat gain coefficient modulation that static glazing cannot achieve.
- Self-Tinting:Passive electrochromic systems respond to ambient light without electrical input, incorporating photochromic additives within electrochromic thin-film stacks. German facade engineering firms specify these for KfW-subsidized residential retrofits where wiring infrastructure is cost-prohibitive.
- Thermochromic:Temperature-responsive vanadium dioxide coatings switch opacity based on thermal thresholds rather than electrical signals.
- Photovoltaic:BIPV-integrated assemblies combine perovskite or silicon thin-film generation with electrochromic modulation layers.
Switchable products anchor the volume base while Photovoltaic segments gain share at the steepest rate.
Application:
Cost tier stratification separates premium facade specifications from price-sensitive residential penetration attempts.
- Commercial Buildings:Curtain wall and atrium installations command premium pricing for HVAC load reduction verification. China's MEE dual carbon enforcement drives public building procurement in Beijing and Shanghai where operational energy limits are binding.
- Facades:Exterior envelope systems integrate electrochromic glass with structural silicone glazing and thermal breaks. California Title 24 compliance deadlines compress specification timelines for new construction in Los Angeles and San Francisco metropolitan corridors.
- Residential Structures:Single-family and multi-family housing applications remain constrained by installed cost premiums over conventional low-E glazing.
- Skylights:Overhead glazing applications leverage electrochromic modulation for daylight harvesting and glare control.
Commercial Buildings dominate current revenue while Facades expand most quickly as building envelope integration deepens.
Technology:
Supply concentration in ceramic ion conductor manufacturing favors solid-state architectures over liquid-dependent alternatives.
- Solid-State:Ceramic lithium conductors replace liquid electrolytes, eliminating leakage risk and enabling extended warranty terms. United States developers specify these for liability-sensitive high-rise projects where facade access for maintenance is restricted.
- Liquid-Crystal:PDLC suspensions modulate opacity through electrical orientation of nematic crystals in polymer matrices. Hospitality and healthcare segments in Germany adopt these for privacy glazing where complete opacity switching supersedes gradual tint modulation.
- Polymer-Based:Conductive polymer electrochromes offer deposition flexibility on flexible substrates.
- Nano-Material:Tungsten oxide nanoparticle and graphene-enhanced conductors enable faster switching kinetics.
Solid-State technology captures the margin premium while Nano-Material formulations climb the fastest toward commercial qualification.
End User:
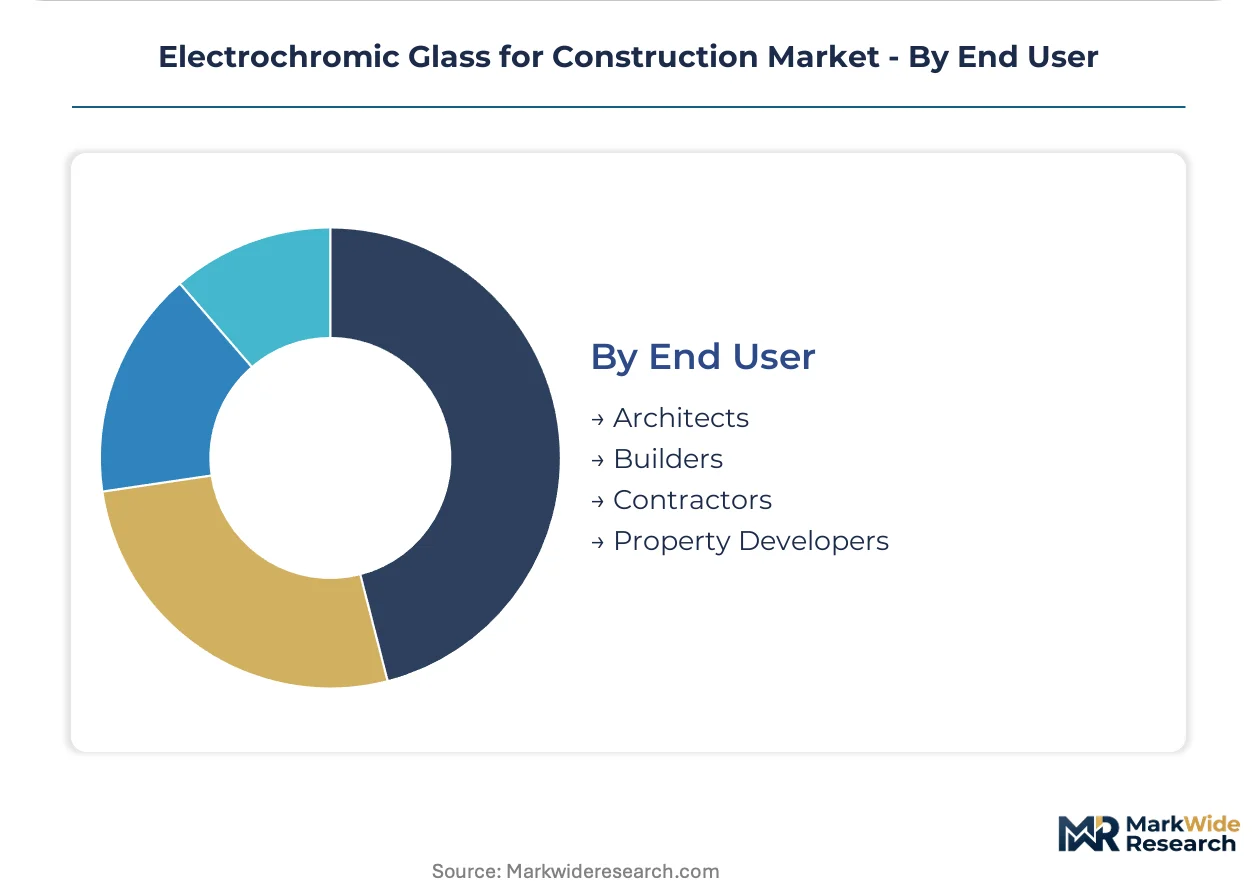
Customer type fragmentation reflects divergent specification authority between design-phase architects and procurement-phase developers.
- Property Developers:Commercial real estate owners and REITs contract for performance-based facade outcomes rather than material specifications. New York and California developers now procure guaranteed HVAC load reductions, transferring operational risk to electrochromic system integrators.
- Architects:Design professionals specify electrochromic glazing during schematic design phases using integrated facade simulation software. German engineering firms accelerate material qualification programs to maintain EU public procurement eligibility under REACH Annex XIV.
- Builders:General contractors execute electrochromic installation with specialized glazing subcontractors.
- Contractors:Facade-specific installers manage field integration with building management systems and BACnet protocol translation.
Property Developers control the largest specification volume while Architects gain influence fastest through digital design tool integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German facade engineering firms export electrochromic glass laminates to commercial developers in the United States and China, establishing the primary trade-flow corridor for premium dynamic glazing assemblies.
United States
California Title 24 compliance deadlines and New York Local Law 97 carbon caps drive specification in Los Angeles and New York metropolitan corridors. The EPA Energy Star program establishes performance baselines that electrochromic assemblies satisfy. High-rise facade projects in San Francisco and Manhattan command premium pricing for HVAC load reduction verification.
Germany
KfW efficiency subsidies now cover dynamic glazing upgrades for multi-family housing stock built before 1990. REACH Annex XIV authorization requirements for nickel compounds force reformulation of cathodic electrochromic layers. Berlin and Munich engineering firms accelerate material qualification programs to maintain EU public procurement eligibility.
China
MEE dual carbon policy enforcement penalizes excessive HVAC loads that static glazing generates in public buildings. GB standards establish operational energy limits that only dynamic glazing satisfies. Beijing and Shanghai deploy large-scale smart building projects with electrochromic facades in government and commercial construction.
Japan
METI building efficiency standards mandate solar heat gain modulation in new commercial construction. JIS certification requirements for construction materials create compliance pathways for imported electrochromic laminates. Tokyo and Osaka metropolitan areas concentrate specification authority among design-phase architects.
United Arab Emirates
Dubai Building Code revisions mandate dynamic shading for glass curtain walls in commercial towers above 15 stories. MOHAP construction material safety protocols regulate ion conductor chemistries in facade assemblies. Dubai Design District and Abu Dhabi Central Business District anchor specification volume for premium electrochromic installations.
Electrochromic Glass for Construction Market Competitive Landscape
Listed leaders compete with private specialists across technology architecture and vertical integration depth. The vendor base spans three tiers: solid-state technology originators, vertically integrated glass fabricators, and automotive crossover specialists. Consolidation pressure concentrates among liquid-electrolyte suppliers facing warranty compression. Dominant competitive moves include backward integration into ion conductor manufacturing and strategic partnerships with facade engineering firms.
Among North American technology originators, View, Inc. and SageGlass exemplify the solid-state architecture tier. Gentex Corporation represents automotive crossover specialists extending electrochromic expertise into commercial channels. These three occupy positions across the technology spectrum from sputtering process control to final glass lamination integration.
| Leading Market Players |
|---|
| View, Inc. |
| SageGlass |
| Gentex Corporation |
| ChromoGenics |
| AGC Inc. |
| PPG Industries |
| Saint-Gobain |
| Halio Inc. |
| Gauzy Ltd. |
| Others |
Supply & Pricing Matrix
Solid-state lithium ion conductors replacing liquid electrolyte architectures are redrawing procurement geography toward East Asian ceramic suppliers while compressing warranty premiums for legacy laminate producers. This substitution dynamic concentrates pricing power with sputtering target manufacturers in China, Japan, and South Korea, forcing electrochromic fabricators to absorb ion conductor cost volatility or pass through to developers.
Pricing Analysis
Current-generation solid-state electrochromic laminates command substantial premiums over liquid-electrolyte predecessors, while photovoltaic-integrated panels occupy the highest tier. Three-tier pricing structure across premium solid-state, standard liquid-electrolyte, and economy thermochromic alternatives reflects certification grade differentiation and warranty term length. Cost compression in standard liquid-electrolyte tiers is intensifying because REACH Annex XIV compliance timelines are accelerating R&D recapture demands. Residential developers exhibit the highest price sensitivity, whereas United States commercial high-rise developers prioritize liability reduction over unit economics.
Supply Chain Analysis
Strategic stockpiling of indium tin oxide sputtering targets dominates procurement behavior among electrochromic laminate manufacturers facing supply uncertainty. Raw material dependencies center on lithium carbonate from Chile and Australia, tungsten oxide from China and Vietnam, and transparent conductive oxides from East Asian refiners. Single-source vulnerability in ITO target manufacturing creates acute exposure to export restriction scenarios. Distribution runs through facade engineering firms that integrate electrochromic assemblies into curtain wall systems for commercial developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electrochromic glass for construction operates as a substitution defense market where static low-E glazing and dynamic external shading systems threaten specification share. Incumbents must navigate this substitute pressure while solidifying technology differentiation.
For Market Incumbents: Secure captive supply of ceramic ion conductors through backward integration or long-term offtake agreements with East Asian refiners. Accelerate ASTM E2141-21 certification pipelines for nickel oxide alternatives ahead of REACH Annex XIV authorization deadlines. Liquid-electrolyte suppliers face warranty compression that demands rapid product architecture migration. For New Entrants and Emerging Players: Differentiate on photovoltaic-electrochromic convergence for net-zero commercial projects where BIPV specification authority is consolidating. Target Germany's KfW-subsidized residential retrofit segment where self-tinting architectures bypass wiring infrastructure barriers. Direct-to-developer digital specification platforms offer the most penetrable go-to-market channel. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors solid-state specialists with certified ceramic conductor supply. Long-term viability rests on regulatory compliance durability across EU, United States, and Chinese chemical frameworks. Acquisition targets should demonstrate REACH-ready material qualification programs and established facade engineering firm partnerships. The signal to watch is MEE enforcement intensity for public building operational energy limits in Beijing and Shanghai.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ion Conductor Manufacturing | Captive lithium ceramic supply from East Asian refiners insulates margin from carbonate volatility. |
| REACH-Compliant Material Qualification Program | German engineering firms require Annex XIV-ready nickel oxide alternatives for EU public procurement eligibility. |
| Photovoltaic-Electrochromic Product Convergence | Perovskite-integrated BIPV assemblies capture net-zero commercial project specification authority. |
| Direct-to-Developer Digital Platform Launch | Facade design software integration enables real-time performance simulation during schematic phases. |
| Strategic Partnership with Facade Engineering Firms | Curtain wall integrators control specification gatekeeping for United States high-rise developments. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with electrochromic technology executives, facade engineering directors, commercial property developers, and building code compliance officers; and secondary validation through EPA Energy Star program filings, ECHA REACH registration databases, MEE dual carbon enforcement protocols, and ASHRAE 90.1 standard documentation. Bottom-up triangulation across laminate production volumes and top-down validation against construction permit data for electrochromic-specified projects anchored market sizing.
Across the projection horizon, the analytical framework modeled electrochromic glass demand through segmentation dimensions spanning product architecture, application envelope, technology generation, and end-user specification authority. CAGRs were derived from regression analysis of historical specification velocity against regulatory compliance deadline clustering. Industry-specific forecast inputs incorporated KfW subsidy allocation trajectories and Title 24 compliance timeline density in California metropolitan corridors.
The analysis sits within stated boundaries; outcomes outside sustained enforcement of EU Green Deal building performance mandates, China's dual carbon policy, and United States energy code ratcheting would require recalibration. Forecasts reflect assumptions regarding lithium carbonate supply stability and REACH authorization timeline adherence. Revision becomes warranted when MEE inspection protocol intensity or indium tin oxide export restriction severity crosses thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Facade Anchor Systems Market
Building & Construction Materials
Railing Market
Building & Construction Materials
Customized Shopfitting Materials Market
Building & Construction Materials
Thailand Construction Chemicals Market
Building & Construction Materials
North America Wood Based Panel Market
Building & Construction Materials
North America Concrete Cellulose Fiber Reinforcement Market
Building & Construction Materials
US Residential and Commercial Roofing Materials Market
Building & Construction Materials
Chain Link Fencing Market
Building & Construction Materials
USA and Canada Pre-Painted Steel Roofing and Cladding Market
Building & Construction Materials
Ball Iron Rods Market
Building & Construction Materials
Europe Particle Board Market
Building & Construction Materials
GCC Ceramic Tiles Market
Building & Construction Materials
Africa Vinyl Windows Market
Building & Construction Materials
Construction Elastomers Market
Building & Construction Materials
Australia Industrial Insulation Market
Building & Construction Materials
Non-Residential Polished Concrete Market