
 Roofing Tiles Market | 2026-2036
Roofing Tiles Market Size, Share, and Industry Trends Forecast 2026-2036
Roofing Tiles Market Analysis
Residential retrofit buyers are rotating toward impact-rated and cool-roof-certified tile systems as insurance underwriting tightens in coastal counties. Wienerberger AG leverages its European clay sourcing network to sustain cost discipline across Atlantic freight lanes. Westlake Royal Building Products anchors North American distribution through pro-dealer and direct-to-contractor channels. Verea Clay Tile specializes in handmade Mediterranean profiles that command premium positioning in custom home segments.
Roofing tiles are rigid surfacing elements, typically fired clay, cast concrete, or natural slate, designed to overlap and channel precipitation while providing thermal mass and fire resistance rated up to Class A. Their primary commercial purpose is to protect structural envelopes across multi-decade service lives while enabling architectural differentiation through profile, color, and texture variation. Concrete tiles dominate volume in new residential construction across the southwestern United States due to lower installed cost per square and adaptability to S-tile and flat profiles. Metal tiles, particularly stone-coated steel, represent the fastest-growing product category as DECRA Roofing Systems and MCA Clay Roof Tile compete on lightweight retrofit compatibility and hail resistance. Clay retains margin concentration in heritage restoration and high-end custom segments where material authenticity commands specification loyalty.
The EPA's ENERGY STAR roof products program and cool roof credits in California Title 24 shape product development priorities, while Florida's Miami-Dade County product approval protocols and Texas Department of Insurance windborne debris certifications govern market access for coastal applications. Etex Group and Standard Industries navigate multi-jurisdictional code books through centralized testing and regional specification teams. Stakeholders must monitor how evolving insurance risk models and municipal resilience bonds redirect capital toward performant roofing assemblies versus conventional replacement cycles.
Market Dynamics
Building code stringency in hurricane-prone coastal zones is compressing replacement cycles and redirecting specification authority from homeowners toward insurance underwriters and municipal resilience officers.
Growth Catalysts
- Impact-Rated Certification Mandates:Florida's Miami-Dade County product approval protocols and Texas Department of Insurance windborne debris certifications are disqualifying conventional tile systems from coastal retrofit eligibility.
- Cool Roof Incentive Structures:California Title 24 cool roof credits and EPA ENERGY STAR roof products program specifications are tilting new construction specifications toward reflective surface treatments.
- Stormwater Management Compliance:EPA municipal separate storm sewer system mandates are elevating permeable tile assemblies in commercial and institutional flat-roof applications.
Market Restraints
- Atlantic Freight Cost Volatility:European clay sourcing networks face bunker fuel surcharge instability and Panama Canal capacity constraints that compress margin on imported ceramic products.
- Lightweight Substitute Displacement:Stone-coated steel tile systems are capturing retrofit volume in hail-prone interior markets where structural load limits restrict traditional concrete and clay installation.
- Installation Labor Scarcity:Specialized mortar-set and foam-adhesive application techniques require certified contractor networks that concentrate in legacy Sun Belt construction markets.
Strategic Opportunities
- Municipal Resilience Bond Financing:Florida and Texas county-level catastrophe preparedness programs are creating dedicated funding streams for Class A fire-rated and impact-resistant roof replacements in designated vulnerability zones.
- Direct-to-Contractor Digital Platforms:Pro-dealer channel bypass models are emerging in Texas and Arizona metropolitan markets where builder procurement teams seek specification-grade product access without distributor markup.
- Photovoltaic Integration Compatibility:Tile-integrated solar mounting systems are opening specification pathways in California custom home segments where aesthetic concealment of renewable infrastructure commands premium positioning.
Industry Challenges
- Multi-Jurisdictional Certification Timelines:Florida Product Approval, Texas Department of Insurance, and California State Fire Marshal listings require parallel testing protocols that extend market entry lead times by 18-24 months.
- Raw Material Sourcing Reconfiguration:Domestic clay body reformulation to reduce dependence on specific European kaolin deposits demands capital-intensive kiln recalibration and firing curve redevelopment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Roofing Tiles Market |
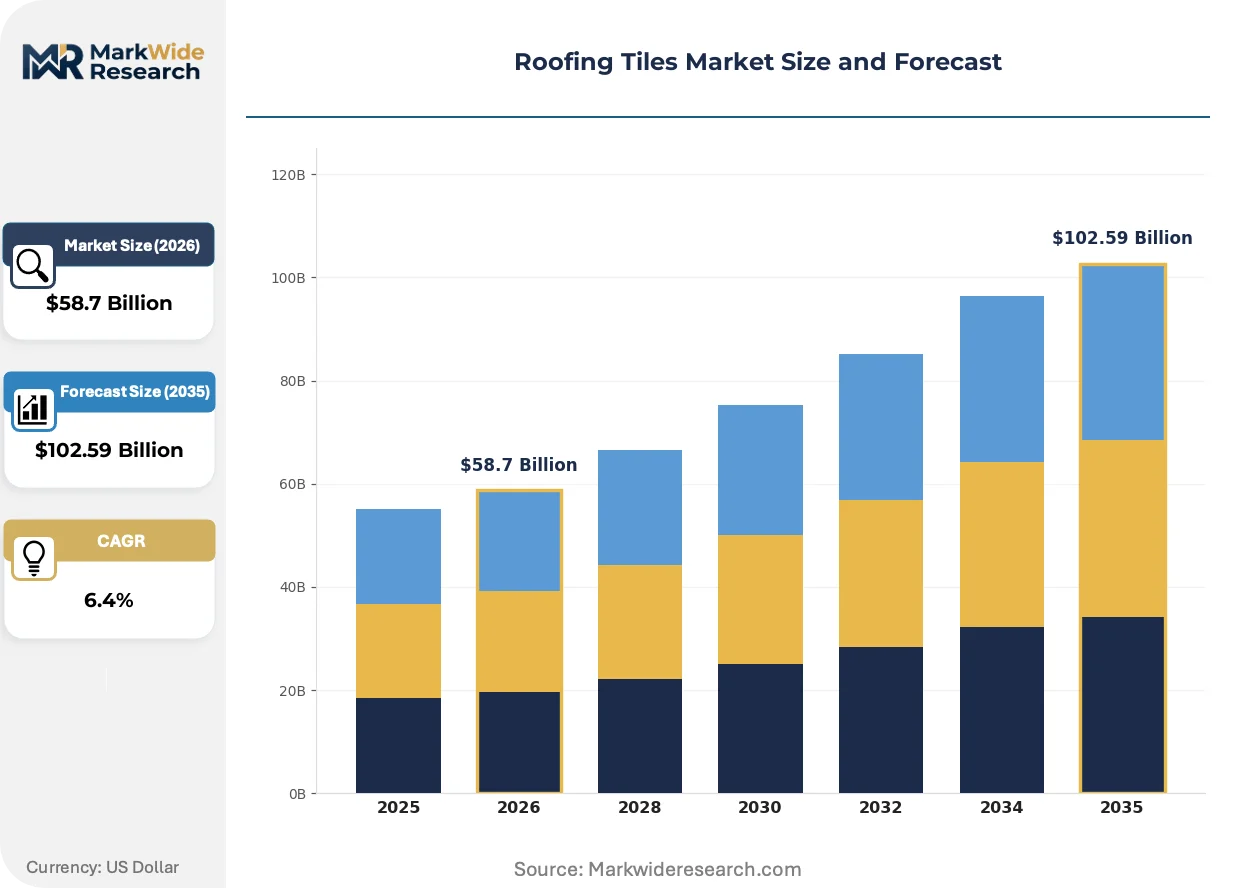
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $102.59 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ceramic, Concrete, Slate, Metal Installation Method: Direct Lay, Batten System, Standing Seam, Interlocking End User: Residential, Commercial, Industrial, Agricultural Material: Clay, Fiber Cement, Asphalt, Synthetic |
| Companies Covered | Westlake Royal Building Products, Verea Clay Tile, Wienerberger AG, DECRA Roofing Systems, Inc., MCA Clay Roof Tile, Standard Industries Inc. (BMI Group), Crown Roof Tiles, Marley, Etex Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Roofing Tiles Market Emerging Trajectories
Specification authority is migrating from aesthetic preference toward performance certification as insurance underwriting and municipal code enforcement tighten eligibility criteria for coastal and wildland-urban interface zones.
Cool roof surface technology is bifurcating the specification landscape. Infrared-reflective pigment systems and ventilated batten configurations now dominate California and Arizona new construction. Custom home architects in Florida coastal counties are specifying these systems to meet Title 24-equivalent performance thresholds. The technology is bifurcating margin concentration between commodity concrete tile producers and specialized coating applicators who control surface treatment intellectual property.
EPA stormwater management mandates are reshaping commercial flat-roof specifications. Permeable tile assemblies with integrated drainage matrices now qualify for municipal green infrastructure credits in Florida and Texas jurisdictions with combined sewer overflow mitigation obligations. Institutional buyers in these markets are prioritizing products with documented runoff coefficient performance.
Retrofit buyer behavior is rotating toward insurance-driven replacement cycles. Florida and Texas coastal homeowners are selecting impact-rated systems based on premium discount eligibility rather than aesthetic preference. Pro-dealer networks in these markets are retraining sales staff to navigate underwriting documentation requirements alongside traditional color and profile selection.
Roofing Tiles Market Segmentation
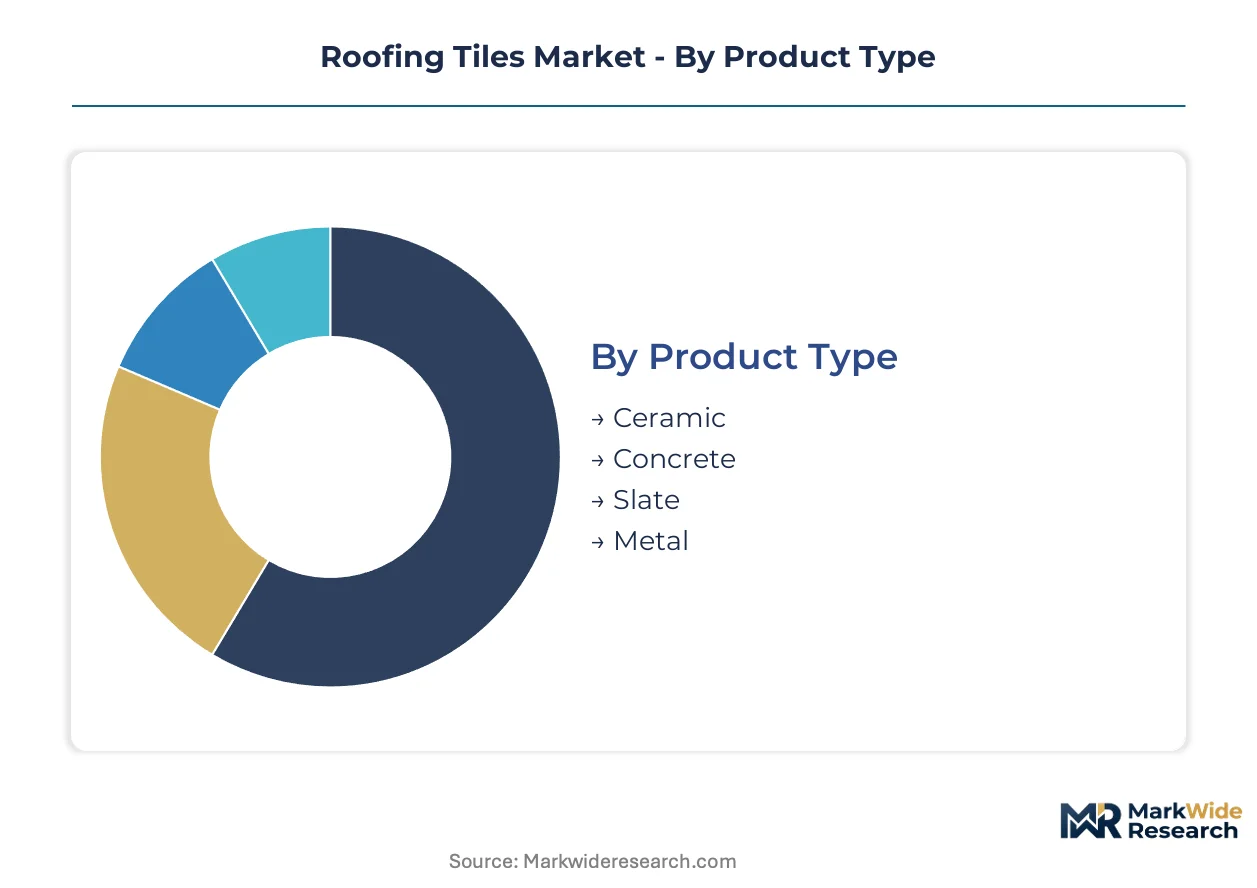
Segmentation in roofing tiles determines specification pathways, certification requirements, and margin capture across divergent building codes and insurance underwriting regimes. Product material and installation method classifications dictate which contractor networks and distribution channels manufacturers must cultivate.
Product Type:
Substitution pressure from lightweight alternatives and synthetic composites is reshaping volume distribution across traditional ceramic and concrete dominance.
- Ceramic:Fired clay tiles deliver Class A fire ratings and century-long service life in coastal Mediterranean and Spanish Colonial architectural specifications. Demand concentrates in Florida custom home segments where Miami-Dade County impact certification and heritage authenticity command simultaneous specification loyalty.
- Concrete:Cast mineral-aggregate tiles dominate new residential volume across southwestern United States sub-markets due to lower installed cost per square and adaptability to S-tile, flat, and shake profiles. California Title 24 cool roof compliance drives specification toward concrete substrates with infrared-reflective surface treatments.
- Slate:Natural metamorphic stone tiles serve heritage restoration and high-end institutional segments where material authenticity and dimensional stability justify premium positioning.
- Metal:Stone-coated steel and aluminum tiles represent the fastest-climbing category as hail resistance and structural load compatibility open retrofit pathways in interior markets.
Concrete anchors the volume base while metal gains share at the steepest rate.
Installation Method:
Cost tier differentiation separates premium engineered systems from commodity direct-to-deck applications in residential retrofit versus new construction procurement.
- Direct Lay:Mechanically fastened tiles applied directly to roof deck sheathing minimize material cost and labor hours in tract home production. Texas and Arizona builder procurement teams specify direct lay for velocity-driven subdivision construction where code minimums govern.
- Batten System:Elevated counter-batten configurations create ventilated air gaps that enhance thermal performance and moisture management in humid subtropical zones. Florida coastal counties mandate batten systems for impact-rated tile assemblies to achieve Miami-Dade County product approval.
- Standing Seam:Concealed-fastener metal tile profiles deliver weathertight performance in steep-slope commercial and institutional applications.
- Interlocking:Self-sealing edge profiles reduce installation labor certification requirements and accelerate project timelines in agricultural and light commercial segments.
Direct lay commands the highest shipment volume while batten systems expand most quickly in code-stringent coastal jurisdictions.
End User:
Application-specific performance requirements segment the market across fire rating, wind uplift, and insurance certification priorities.
- Residential:Single-family and multifamily construction drives specification diversity from economy concrete to premium clay and metal systems. Retrofit activity in Florida and Texas hurricane corridors rotates toward impact-rated assemblies as underwriters tighten eligibility criteria.
- Commercial:Flat and low-slope institutional roofing elevates permeable tile assemblies with integrated drainage matrices for EPA stormwater management compliance.
- Industrial:Heavy manufacturing and warehouse facilities prioritize structural load capacity and chemical resistance in specification.
- Agricultural:Barn and outbuilding applications favor cost-optimized direct-lay concrete and interlocking metal systems.
Residential anchors the volume base while commercial specification climbs fastest on green infrastructure credit eligibility.
Material:
Supply concentration and sourcing geography determine margin stability across natural versus engineered material categories.
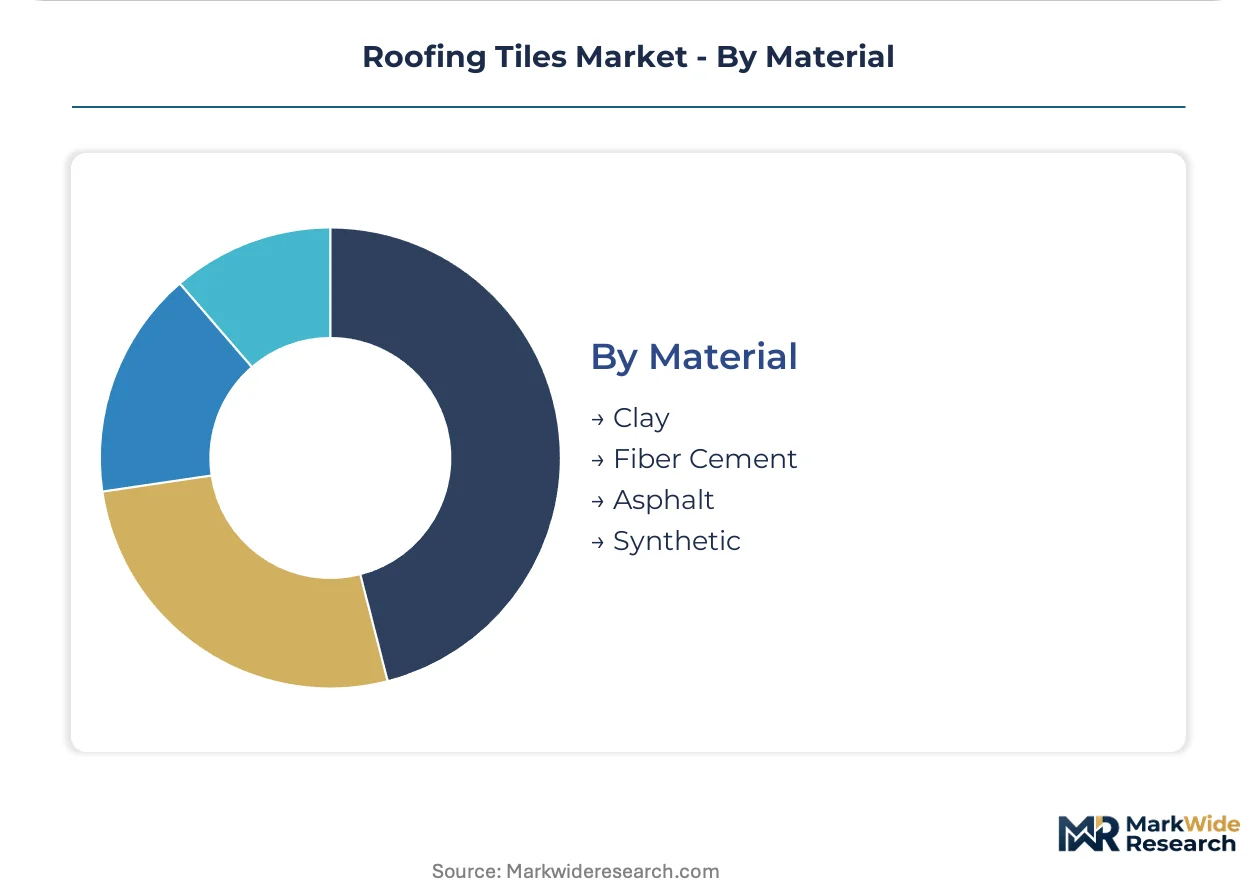
- Clay:Natural kaolin-based ceramic bodies sustain premium positioning in heritage and custom segments. European sourcing networks face Atlantic freight volatility and Panama Canal capacity constraints that compress margin on imported products.
- Fiber Cement:Cellulose-reinforced cementitious composites offer intermediate weight and cost positioning between clay and concrete. California wildland-urban interface zones specify fiber cement for Class A fire rating compliance.
- Asphalt:Saturated organic and fiberglass mat shingles retain economy positioning in reroofing markets where first cost dominates procurement.
- Synthetic:Polymer-composite and recycled-rubber tiles deliver lightweight retrofit compatibility and impact resistance in hail-prone interior markets.
Clay sustains the premium tier while synthetic materials capture the steepest expansion trajectory on retrofit structural load compatibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Residential retrofit buyers in hurricane-prone coastal zones dominate procurement volume. Insurance underwriters and municipal resilience officers now control specification authority in these markets. Building code stringency concentrates demand in jurisdictions where premium discounts intersect with certification mandates.
United States
Florida, Texas, and California sub-markets absorb the majority of impact-rated and cool-roof tile shipments. The EPA's ENERGY STAR roof products program and California Title 24 cool roof credits reshape product development priorities. Miami-Dade County product approval protocols govern market access for coastal applications in South Florida.
Germany
Heritage restoration and high-performance building envelope specifications sustain demand for premium clay systems. The EU Green Deal and national energy efficiency standards accelerate cool roof and ventilated assembly adoption. Industrial clusters in Bavaria and North Rhine-Westphalia concentrate specialty coating applicators who control surface treatment intellectual property.
China
Urban residential construction and infrastructure resilience programs drive concrete tile volume in coastal provinces. GB standards and MIIT building material regulations govern fire rating and structural load requirements. Manufacturing concentration in Shandong and Guangdong provinces supplies domestic and export markets with S-tile and flat profiles.
India
Rapid urbanization and affordable housing schemes expand concrete tile penetration in southwestern and southern states. BIS certification requirements and state-level disaster management codes elevate wind uplift and impact resistance specifications. Industrial corridors in Gujarat and Maharashtra host domestic producers serving tier-2 and tier-3 city construction.
Australia
Bushfire-prone zone construction and cyclone-rated building codes concentrate demand in Queensland and New South Wales. The country's national building regulator mandates Class A fire ratings and windborne debris resistance in designated vulnerability zones. Sydney and Melbourne metropolitan markets prioritize cool roof performance for thermal compliance.
Roofing Tiles Market Vendor Landscape
Player mix skews toward integrated building material conglomerates with multi-jurisdictional certification capabilities. The vendor base concentrates around manufacturers with captive clay sourcing networks and established pro-dealer distribution infrastructure. Two strategic archetypes dominate: European heritage specialists leveraging Mediterranean authenticity premiums, and North American scale players optimizing direct-to-contractor channel efficiency. Competitive moves center on portfolio diversification into lightweight metal alternatives and geographic expansion through centralized testing facilities.
Among European heritage specialists, Wienerberger AG and Verea Clay Tile occupy positions anchored by Mediterranean sourcing networks and handmade profile authenticity. Westlake Royal Building Products exemplifies the North American scale archetype with pro-dealer and direct-to-contractor channel dominance. DECRA Roofing Systems, Inc. represents the metal tile specialization vector, competing on lightweight retrofit compatibility.
| Leading Market Players |
|---|
| Westlake Royal Building Products |
| Verea Clay Tile |
| Wienerberger AG |
| DECRA Roofing Systems, Inc. |
| MCA Clay Roof Tile |
| Standard Industries Inc. (BMI Group) |
| Crown Roof Tiles |
| Marley |
| Etex Group |
| Others |
Supply Flow & Price Mechanics
Stone-coated steel tile displacement of traditional concrete and clay systems simultaneously redraws supply geography toward East Asian metal-coating clusters and compresses pricing power in legacy ceramic supply networks. This substitution dynamic forces European clay producers to absorb Atlantic freight volatility while North American concrete manufacturers defend share through infrared-reflective surface treatment premiums.
Pricing Analysis
Long-term offtake contracts with bunker fuel indexation dominate European clay tile imports, insulating Wienerberger AG and Verea Clay Tile from spot freight spikes while locking margin exposure to Rotterdam-Savannah lane volatility. Three-tier pricing structure across impact-rated premium, Title 24-compliant standard, and economy direct-lay concrete separates Miami-Dade certified products from Arizona tract-home specifications. Cost compression in ceramic tiers is intensifying because Panama Canal capacity constraints extend inventory cycles. Production homebuilders in Texas and Arizona exhibit highest price sensitivity, while Florida coastal retrofit buyers prioritize insurance discount eligibility over first cost.
Supply Chain Analysis
Spain and Italy anchor Mediterranean clay body production for heritage-grade ceramic tiles, while China and Vietnam concentrate stone-coated steel substrate manufacturing for lightweight retrofit systems. Domestic concrete tile production draws from regional sand and cement supply basins in California, Texas, and Florida to minimize outbound freight exposure. Single-source vulnerability concentrates in European kaolin deposits for premium clay formulations, prompting Wienerberger AG to recalibrate kiln firing curves for domestic clay body alternatives. Distribution runs through pro-dealer networks in Sun Belt metropolitan markets, with direct-to-contractor platforms emerging in Phoenix and Dallas-Fort Worth.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Roofing tile procurement is approaching a platform-economics inflection as tile-integrated solar mounting systems and municipal resilience bond platforms create interoperability standards between roofing assemblies and distributed energy infrastructure.
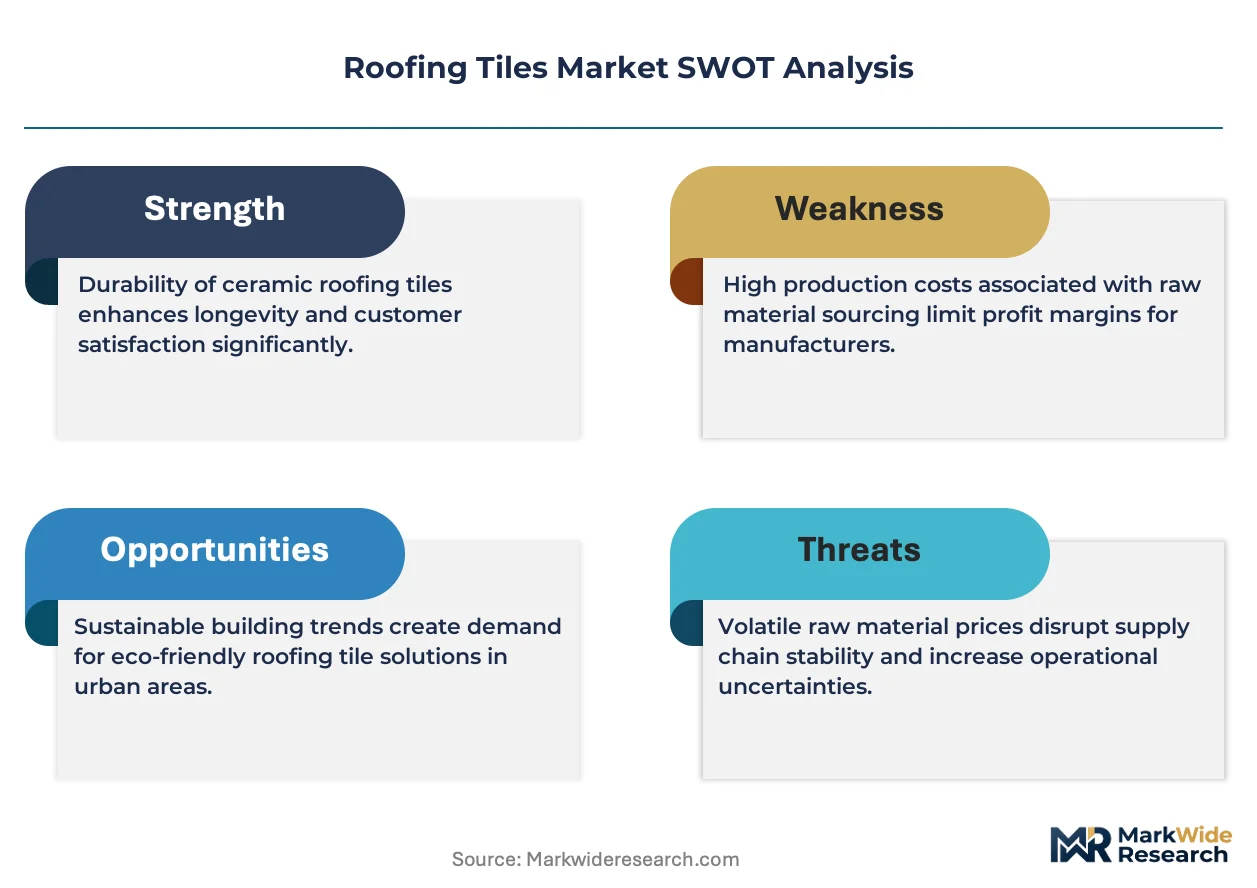
For Market Incumbents: Secure Miami-Dade County product approval and Texas Department of Insurance windborne debris certification as defensive moats against stone-coated steel substitution in coastal retrofit markets. Backward integration into captive clay sourcing or regional sand mining insulates margin from Atlantic freight volatility and construction aggregate spot pricing. Channel control through exclusive pro-dealer relationships in Florida and Texas concentrates specification authority against direct-to-contractor platform entrants. For New Entrants and Emerging Players: Anchor in California custom home segments where photovoltaic integration compatibility commands aesthetic concealment premiums unavailable to commodity concrete producers. The most penetrable white space sits in municipal resilience bond-funded Class A fire-rated replacements in Florida vulnerability zones, where incumbent certification backlogs create 18-24 month entry windows. A go-to-market angle pairing cool roof surface treatment intellectual property with direct digital specification tools bypasses legacy distributor markups. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap metal tile specialists with established UL 2218 impact ratings and lightweight structural load compatibility for hail-prone interior retrofit markets. Long-term viability across the analysis window hinges on positioning for insurance underwriting convergence with building code enforcement in coastal counties. The signal to watch as inflection indicator is Florida Office of Insurance Regulation premium discount schedule revisions that accelerate or decelerate impact-rated system payback periods.| Strategic Initiative | Industry Significance |
|---|---|
| Impact-Rated Certification Investment | Miami-Dade County product approval unlocks Florida coastal retrofit eligibility and insurance discount pathways. |
| Cool Roof Surface Treatment Development | California Title 24 compliance and EPA ENERGY STAR qualification tilt new construction specifications toward reflective systems. |
| Direct-to-Contractor Platform Launch | Phoenix and Dallas-Fort Worth metropolitan bypass models capture builder procurement teams seeking specification-grade access. |
| Photovoltaic Integration Partnership | Tile-integrated solar mounting compatibility opens California custom home segments where aesthetic concealment commands premium positioning. |
| Regional Clay Body Reformulation | Domestic kaolin alternative development reduces Atlantic freight exposure and Panama Canal capacity constraint vulnerability. |
Methodological Framework
Operator-level perspectives from roofing tile plant managers, pro-dealer distribution principals, municipal building code officials, insurance underwriters in Florida and Texas, and custom home architects anchored the qualitative base. Secondary validation drew from EPA ENERGY STAR product listings, Miami-Dade County product approval databases, California Title 24 compliance certifications, and customs records for Atlantic ceramic tile imports. Bottom-up shipment data triangulated against top-down construction permit analysis across the analysis window.
Sensitivity analysis tested volume and value outputs against variable assumptions for Atlantic freight rate trajectories, insurance premium discount schedule revisions, and municipal resilience bond issuance velocity across the projection horizon. Segmentation dimensions modeled include product material, installation method, end-use application, and regional regulatory cluster. CAGRs derived from regression analysis of historical shipment data against construction permit forecasts and retrofit replacement cycle assumptions. Industry-specific forecast inputs incorporated Florida Product Approval backlog durations and California cool roof credit utilization rates.
Material uncertainties — bunker fuel surcharge volatility, Panama Canal capacity constraints, and insurance risk model recalibrations — sit outside the modeled envelope. Forecasts reflect assumptions regarding sustained building code stringency in hurricane-prone coastal zones and continued EPA stormwater management mandate enforcement. Recalibration cycles align with material shifts in Florida Office of Insurance Regulation premium schedules and Texas Department of Insurance certification requirement updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Composite Insulated Panels Market
Building & Construction Materials
Global Awning Market
Building & Construction Materials
North America Prefab Wood Building Market
Building & Construction Materials
Prestressed Concrete (PC) Wire and Strand Market
Building & Construction Materials
Roofing Underlay Market
Building & Construction Materials
Black Bricks Market
Building & Construction Materials
GRC Conduit Fittings Market
Building & Construction Materials
Concrete Protective Liners Market
Building & Construction Materials
Global Sandwich Panels Market
Building & Construction Materials
North America Gutter Guards Market
Building & Construction Materials
North America Luxury Vinyl Tile (LVT) Market
Building & Construction Materials
Roofing Underlayment Market
Building & Construction Materials
Concrete Formwork System Market
Building & Construction Materials
US Terracotta Cladding Market
Building & Construction Materials
North America Concrete Sealer Market
Building & Construction Materials
Girdle Plates Market