
 Global Steel Wire Rod Market | 2026-2036
Global Steel Wire Rod Market Size, Share, and Industry Trends Forecast 2026-2036
Global Steel Wire Rod Market Foresight
Buyer concentration among tier-one automotive cable harness manufacturers is recalibrating procurement volumes toward long-term offtake agreements with integrated steel producers. ArcelorMittal leverages its European and Brazilian rolling capacity to secure multi-year supply contracts with European automotive OEMs. Nippon Steel Corporation anchors its competitive position through proprietary controlled-cooling technology for tire cord-grade wire rod. China Baowu Steel Group Corporation dominates domestic high-volume supply through backward integration into captive billet production.
Steel wire rod consists of semi-finished long steel products, typically 5.5 to 42 millimeters in diameter, hot-rolled from continuously cast billets and subsequently drawn or rolled into wire, strand, or fastener stock for structural and mechanical applications. Continuous casting technology yields superior internal soundness and dimensional consistency compared to traditional ingot routes, reducing downstream breakage during cold drawing operations. Hot rolled product types command the largest volume share due to their role as feedstock for construction mesh and concrete reinforcement, while galvanized wire rod captures premium margin pools from corrosion-resistant fencing and utility cable applications. Cold drawing technology segments attract specialized demand from spring makers requiring precise tensile strength tolerances.
The US EPA enforces stringent particulate emissions thresholds at integrated minimills, compelling producers to upgrade rolling mill fume extraction systems. China's MEE implements dual carbon monitoring protocols that tie production quotas to verified emissions intensity per ton of wire rod shipped. India's BIS mandates IS 1786 certification for thermomechanically treated wire rod used in seismic-zone construction, creating non-tariff barriers for uncertified imports. Stakeholders must monitor how divergent carbon-border adjustment mechanisms reshape cost-competitive sourcing corridors before committing to regional capacity expansions.
Market Dynamics
Automotive cable harness manufacturers are consolidating procurement around long-term offtake agreements with integrated steel producers, compressing spot market liquidity and elevating contract discipline as the dominant market-shaping force.
Growth Catalysts
- Automotive electrification mandates:European OEMs require high-carbon wire rod grades for battery tray reinforcement and motor winding applications, pulling volume toward certified suppliers.
- MEE dual carbon protocols:China's emissions intensity quotas per ton shipped are accelerating retrofit investments in electric induction heating at rolling mills, expanding low-carbon wire rod availability.
- Seismic construction codes:India's BIS IS 1786 certification requirements for thermomechanically treated wire rod are mandating quality upgrades across the western industrial corridor from Gujarat through Maharashtra.
Market Restraints
- Scrap price volatility:Electric arc furnace operators face margin compression when ferrous scrap costs spike, constraining production flexibility at minimills serving construction mesh segments.
- Integrated mill concentration:Backward-integrated producers in East Asia control captive billet supply, limiting independent wire rod mills' access to competitively priced feedstock.
- Aluminum substitution in automotive:Lightweighting programs in European passenger vehicle platforms are displacing steel wire rod in select cable harness and structural applications.
Strategic Opportunities
- India greenfield capacity:POSCO and ArcelorMittal investments in Maharashtra and Gujarat create localized supply hubs for western industrial corridor demand concentration.
- Galvanized premium segments:Corrosion-resistant fencing and utility cable applications command margin premiums over standard hot-rolled construction feedstock.
- Controlled-cooling technology licensing:Proprietary metallurgical processes for tire cord-grade wire rod represent defensible IP positions for technology holders.
Industry Challenges
- Metallurgical technician scarcity:Precision cold drawing operations for spring makers require specialized tensile strength calibration expertise that outpaces vocational training pipeline output.
- Emissions retrofit capex cycles:US EPA particulate thresholds and China's MEE monitoring protocols demand simultaneous fume extraction and induction heating investments, straining balance sheets.
- Cross-border certification reciprocity:Divergent carbon-border adjustment mechanisms create compliance fragmentation for exporters serving multiple regulatory jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Steel Wire Rod Market |
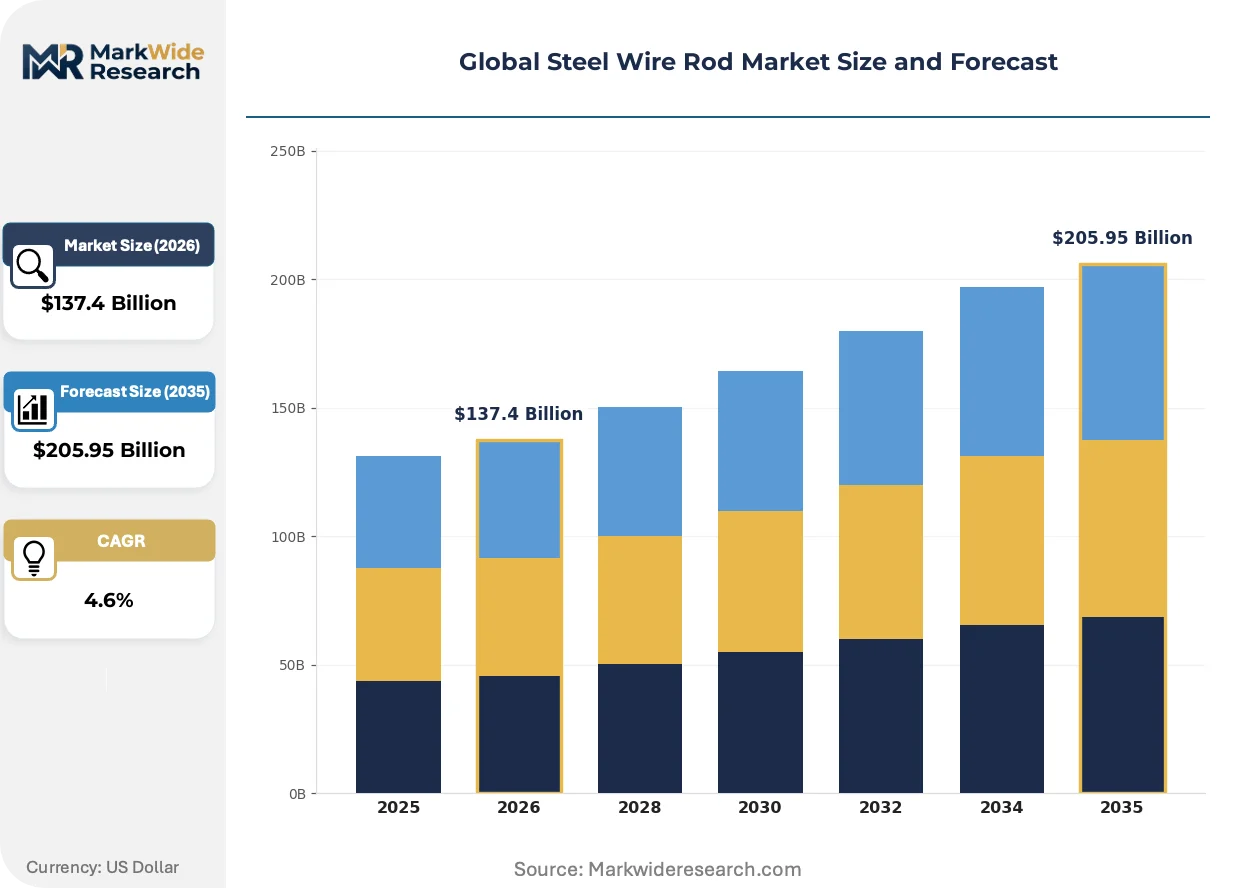
| Market Size in 2026 | $137.4 Billion |
| Market Size in 2035 | $205.95 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hot Rolled, Cold Rolled, Galvanized, Stainless, Alloy Steel End Use Industry: Construction, Electrical Equipment, Wire Rope Manufacturers, Fastener Makers, Spring Makers Technology: Continuous Casting, Billet Casting, Induction Heating, Hot Rolling, Cold Drawing Distribution Channel: Direct Sales, Distributors, Online Platforms, Wholesale Suppliers, Exporters |
| Companies Covered | ArcelorMittal, Nippon Steel Corporation, JFE Steel Corporation, Tata Steel, POSCO, United States Steel Corporation, Kobe Steel, China Baowu Steel Group Corporation, Steel Authority of India Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Steel Wire Rod Market Shifts & Advancements
Continuous casting technology is displacing traditional ingot routes as the dominant metallurgical foundation, while regulatory emissions frameworks and procurement consolidation are compressing supplier diversity across the value chain.
Electric induction heating systems are absorbing capital allocation at integrated rolling mills undergoing decarbonization retrofits. Automotive OEMs and tier-one cable harness manufacturers specify these lower-emission wire rod grades in multi-year supply contracts. The technology is absorbing margin pressure from carbon-border adjustments by preemptively reducing emissions intensity per ton.
China's MEE implements verified emissions intensity quotas tied directly to production permits, compelling integrated mills to document carbon output per wire rod shipment. Brazilian and European rolling capacity faces parallel pressure from EU Green Deal carbon-border adjustment mechanisms. Tire cord-grade and high-carbon automotive segments absorb the steepest compliance costs, accelerating consolidation toward backward-integrated producers with captive clean energy.
Buyer concentration among tier-one automotive cable harness manufacturers is compressing supplier rosters toward long-term offtake agreements with integrated steel producers. Spot market liquidity for standard construction mesh grades is thinning as procurement teams prioritize supply security over price optimization. European automotive OEMs and India's western industrial corridor demonstrate the most pronounced contract discipline, with multi-year agreements displacing quarterly tendering cycles.
Global Steel Wire Rod Market Segmentation
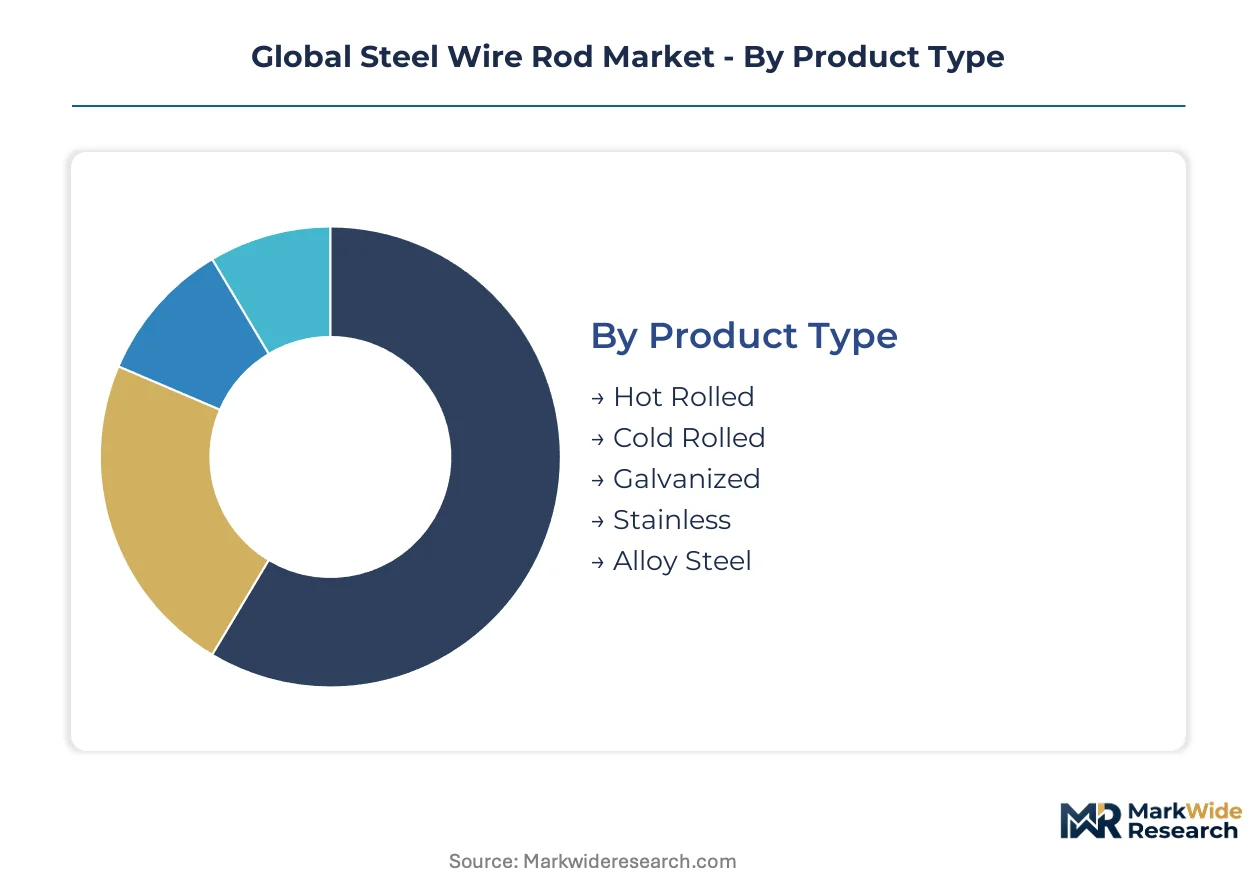
Steel wire rod segmentation reveals how metallurgical specifications and procurement channels fragment value capture across construction, automotive, and industrial end-uses. Each category exposes different pressure points: product type determines margin structure, end-use dictates volume scale, technology governs emissions compliance, and distribution shapes working capital intensity.
Product Type:
Customization intensity spans from commodity hot-rolled grades to specification-locked stainless and alloy variants requiring metallurgical certification.
- Hot Rolled:Semi-finished wire rod produced directly from continuously cast billets without subsequent cold reduction, serving as primary feedstock for concrete reinforcement mesh and construction-grade wire. Demand concentrates in India's western industrial corridor from Gujarat through Maharashtra, where POSCO and ArcelorMittal greenfield investments target seismic-certified construction projects under BIS IS 1786 mandates.
- Cold Rolled:Wire rod subjected to precision cold reduction after hot rolling, delivering tighter dimensional tolerances and enhanced surface finish for fastener and spring applications. Procurement from tier-one automotive cable harness manufacturers is consolidating around long-term offtake agreements with integrated mills possessing captive billet supply.
- Galvanized:Zinc-coated wire rod providing corrosion resistance for fencing, utility cables, and marine applications.
- Stainless:Chromium-alloyed grades resisting oxidation in chemical processing and food equipment environments.
- Alloy Steel:Engineering grades with controlled carbon and manganese content for high-strength tire cord and suspension spring wire.
Leading the category by volume: Hot Rolled. Expanding most quickly: Galvanized premium grades for corrosion-resistant infrastructure.
End Use Industry:
Volume concentration tracks construction cycles, while value concentration follows automotive electrification and precision mechanical component demand.
- Construction:Reinforcing bar and mesh production for concrete structures, bridges, and seismic-resistant buildings. India's BIS mandates thermomechanically treated certification for seismic zones, compressing supplier rosters toward integrated mills with verified metallurgical testing capabilities.
- Electrical Equipment:Motor windings, transformer cores, and battery tray reinforcement for electrified vehicle platforms. European OEMs specify high-carbon grades in multi-year supply contracts, pulling procurement toward ArcelorMittal's European and Brazilian rolling capacity.
- Wire Rope Manufacturers:Strand and cable production for lifting, mining, and marine mooring applications.
- Fastener Makers:Bolt, screw, and rivet stock requiring consistent cold-heading performance.
- Spring Makers:Precision coil and leaf spring wire demanding tight tensile strength tolerances calibrated through controlled-cooling technology.
Construction commands absolute tonnage. Electrical Equipment generates the steepest margin expansion trajectory.
Technology:
Capital intensity and emissions exposure separate legacy casting routes from retrofit induction heating systems absorbing decarbonization investment.
- Continuous Casting:Direct solidification of liquid steel into billet form yielding superior internal soundness and dimensional consistency versus ingot routes. China's MEE dual carbon protocols tie production quotas to verified emissions intensity per ton shipped, favoring mills with integrated continuous casting and electric arc furnace feedstock.
- Induction Heating:Electric-powered billet reheating replacing fossil fuel-fired furnaces at rolling mills. Retrofit installations are accelerating under EU Green Deal carbon-border adjustment mechanisms and China's emissions intensity monitoring.
- Billet Casting:Traditional mold-based solidification routes still serving legacy integrated mill configurations.
- Hot Rolling:High-temperature deformation processing establishing base wire rod dimensions and metallurgical properties.
- Cold Drawing:Precision reduction operations requiring specialized tensile strength calibration expertise for spring and tire cord grades.
Continuous Casting dominates installed capacity. Induction Heating captures the fastest retrofit spending.
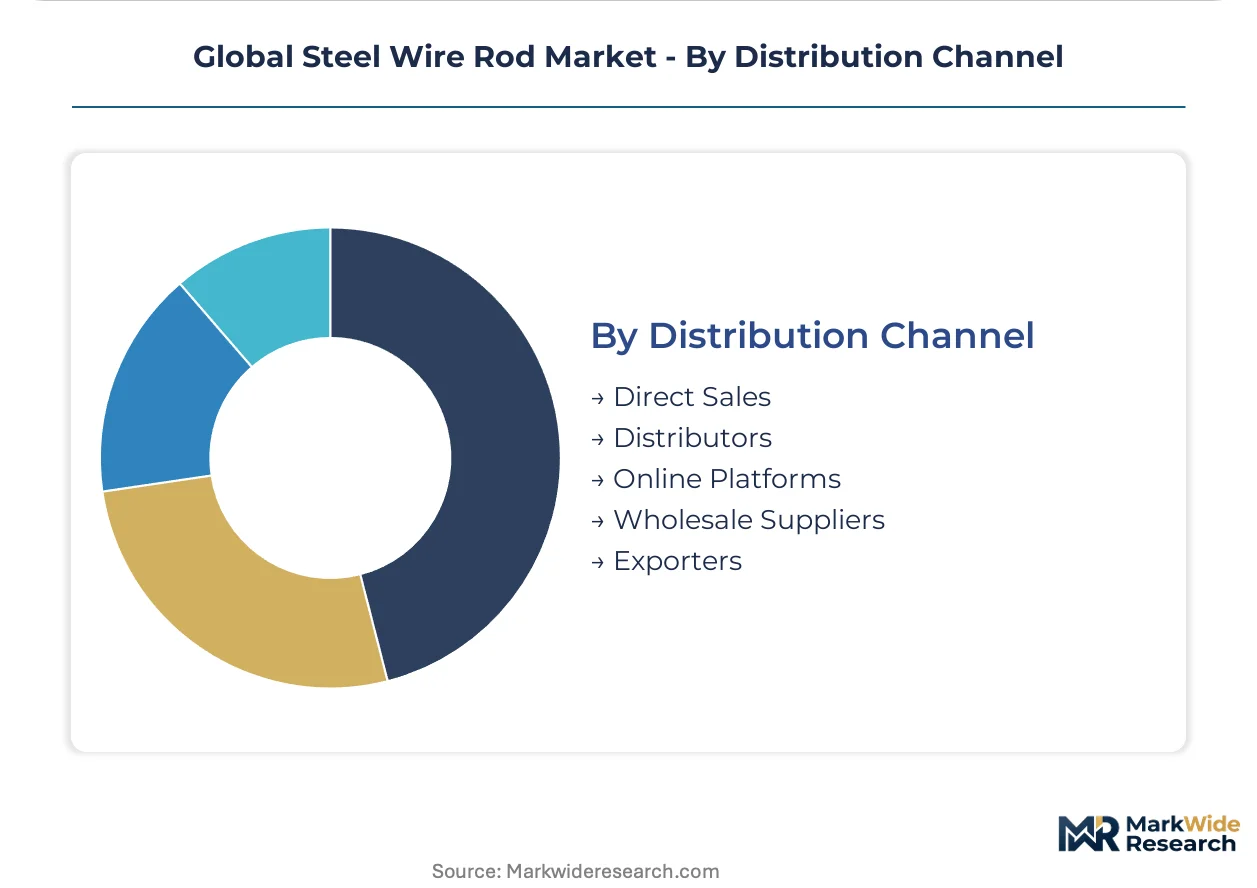
Distribution Channel:
Channel selection reflects buyer scale, certification requirements, and inventory risk allocation between producers and intermediaries.
- Direct Sales:Mill-to-customer contracts governing high-volume automotive and construction procurement with embedded quality verification. Tier-one cable harness manufacturers leverage direct relationships with integrated producers to secure multi-year offtake agreements displacing quarterly tendering.
- Distributors:Regional stockholding intermediaries serving fragmented construction mesh and fencing fabricators with smaller order quantities.
- Online Platforms:Digital procurement channels emerging for standard grades with transparent certification documentation.
- Wholesale Suppliers:Volume aggregators consolidating spot market liquidity for uncertified construction feedstock.
- Exporters:Cross-border traders navigating divergent carbon-border adjustment mechanisms and BIS IS 1786 reciprocity requirements.
Direct Sales commands contract value. Distributors maintain broadest geographic penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive cable harness procurement is concentrating in long-term contracts across Germany, China, India, the United States, and Brazil, with each market shaped by distinct emissions frameworks and construction certification regimes.
China
MEE dual carbon protocols tie wire rod production quotas to verified emissions intensity per ton shipped, compelling integrated mills to retrofit rolling mills with electric induction heating. Backward-integrated producers with captive billet supply dominate high-volume segments. Industrial demand clusters in the Yangtze River Delta and Pearl River Delta, where steel groups serve construction mesh and automotive feedstock requirements under tightening environmental monitoring.
India
BIS mandates IS 1786 certification for thermomechanically treated wire rod in seismic zones, creating non-tariff barriers for uncertified imports. POSCO and ArcelorMittal advance greenfield investments across Maharashtra and Gujarat to capture western industrial corridor demand. Mumbai-Pune and Ahmedabad-Vadodara clusters anchor this capacity expansion for seismic-certified construction projects.
Germany
EU Green Deal carbon-border adjustment mechanisms pressure rolling capacity to document emissions intensity for tire cord-grade and high-carbon automotive segments. ArcelorMittal leverages European rolling assets to secure multi-year supply contracts with automotive OEMs. The Ruhr industrial region and Bavarian manufacturing belt concentrate precision cold drawing operations for spring and fastener applications.
United States
EPA particulate emissions thresholds at integrated minimills compel fume extraction system upgrades, elevating compliance costs for construction mesh producers. Electric arc furnace operators face margin compression when ferrous scrap costs spike. Gulf Coast and Great Lakes industrial corridors host the primary wire rod rolling capacity serving domestic automotive and construction demand.
Brazil
EU carbon-border adjustments expose Brazilian wire rod exports to compliance documentation requirements for European automotive supply chains. ArcelorMittal deploys Brazilian rolling capacity to serve European OEM procurement consolidation. São Paulo state and Minas Gerais anchor integrated steel production with access to iron ore feedstock and coastal export logistics.
Global Steel Wire Rod Market Competitive Landscape
East Asian producers anchor one tier through backward integration into captive billet supply; European and Indian specialists hold contract-driven positions in automotive and seismic-certified construction segments. The vendor base stratifies across three tiers: integrated multinationals with global rolling capacity, regional champions serving domestic certification requirements, and independent mills dependent on spot billet markets. Strategic archetypes include emissions-compliant integrated producers, technology licensors of controlled-cooling processes, and regional construction specialists. Competitive moves center on multi-year offtake agreement capture and rolling mill decarbonization retrofits.
Within the integrated multinational tier, ArcelorMittal, Nippon Steel Corporation, and China Baowu Steel Group Corporation occupy positions reflecting distinct geographic and technological anchoring. ArcelorMittal represents the contract-consolidation archetype through European and Brazilian rolling capacity aligned with automotive OEM procurement. Nippon Steel Corporation exemplifies technology-driven positioning through proprietary controlled-cooling capabilities for tire cord-grade specifications. China Baowu Steel Group Corporation anchors the high-volume domestic supply archetype through backward integration into captive billet production under MEE emissions monitoring protocols.
| Leading Market Players |
|---|
| ArcelorMittal |
| Nippon Steel Corporation |
| JFE Steel Corporation |
| Tata Steel |
| POSCO |
| United States Steel Corporation |
| Kobe Steel |
| China Baowu Steel Group Corporation |
| Steel Authority of India Limited |
| Others |
Supply & Pricing Matrix
Ferrous scrap price indices on the US Gulf Coast cascade through electric arc furnace economics into three distinct pricing tiers for wire rod shipments. Hot-rolled construction grades absorb the steepest cost compression when scrap spikes, while certified automotive and seismic-grade segments command contract premiums that insulate integrated mills from spot volatility.
Pricing Analysis
Volume concentrates in commodity hot-rolled feedstock for construction mesh, while margin pools accrue to galvanized and cold-rolled precision grades. Price differentiation hinges on BIS IS 1786 seismic certification for Indian construction and MEE emissions intensity documentation for Chinese exports. Pricing pressure stems from aluminum substitution in European automotive cable harness applications. Spot-market buyers in uncertified construction segments exhibit acute price sensitivity, whereas tier-one automotive cable harness manufacturers prioritize supply security over unit cost optimization in multi-year offtake negotiations.
Supply Chain Analysis
Certification gating through BIS IS 1786, MEE dual carbon protocols, and EU Green Deal carbon-border adjustments fragments supplier rosters and elevates compliance costs for cross-border shipments. Geographic supply concentration centers on China, India, and Germany, with Brazilian rolling capacity serving European automotive demand. Raw material dependencies span high-grade iron ore fines, ferrous scrap, and zinc for galvanizing operations. Single-source vulnerability concentrates in captive billet supply controlled by backward-integrated East Asian producers. Distribution runs through direct mill-to-customer contracts for automotive and seismic-certified grades, with regional distributors handling fragmented construction mesh demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a supply-constrained environment where metallurgical technician scarcity and emissions retrofit capex cycles prop pricing for certified grades. Capacity bottlenecks at precision cold drawing operations for spring and tire cord applications sustain margin premiums for qualified suppliers.
For Market Incumbents: Anticipate consolidation pressure from aluminum substitution in European automotive platforms by deepening controlled-cooling technology licensing revenue streams. Secure captive billet supply through upstream integration or long-term offtake agreements to defend against scrap price volatility. Prioritize MEE-compliant electric induction heating retrofits to maintain Chinese production quota access. For New Entrants and Emerging Players: Enter via India's western industrial corridor, where POSCO and ArcelorMittal greenfield investments validate demand concentration but leave service gaps for specialized seismic-certified processing. Target thermomechanically treated wire rod segments requiring IS 1786 certification that integrated mills underserve. Pursue toll-processing arrangements with established rolling mills to bypass captive billet barriers. For Investors and Strategic Acquirers: Distressed-cycle entries favor controlled-cooling technology holders in Germany and Japan, where proprietary tire cord-grade processes command licensing premiums through the projection horizon. Long-term viability hinges on emissions-compliant capacity with verified carbon intensity documentation. Monitor EU carbon-border adjustment implementation timelines as the critical inflection signal for European supply chain restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Billet Supply | China Baowu Steel Group Corporation's captive production insulates against feedstock cost spikes and quota restrictions. |
| Electric Induction Heating Retrofit | ArcelorMittal's European rolling mill upgrades preempt EU Green Deal carbon-border compliance costs for automotive contracts. |
| Controlled-Cooling Technology Licensing | Nippon Steel Corporation's proprietary tire cord-grade processes generate defensible IP revenue from precision spring manufacturers. |
| Seismic Certification Investment | Tata Steel's IS 1786 compliance investments capture western India construction demand from Gujarat through Maharashtra. |
| Long-term Offtake Agreement Capture | POSCO's Maharashtra greenfield capacity anchors multi-year supply relationships with tier-one automotive cable harness manufacturers. |
Research Methodology
Multi-period observation of ferrous scrap price indices, MEE emissions intensity quotas, and BIS certification enforcement patterns anchored the trend analysis, supplemented by interviews with rolling mill operations directors, automotive cable harness procurement leads, seismic construction project engineers, and zinc coating specialists. Secondary validation drew from customs trade data, EPA enforcement disclosures, EU ETS carbon price series, and SEC filings of integrated steel producers. Bottom-up capacity modeling and top-down demand triangulation from construction and automotive end-use databases cross-verified volume estimates.
Input-output matrices mapped billet-to-wire rod conversion yields, emissions intensity per ton shipped, and certification cost burdens across product grade tiers over the projection horizon. Segmentation dimensions encompassed metallurgical specification, end-use industry, processing technology, and distribution channel. CAGRs derived from elasticity-adjusted demand curves incorporating electrification content per vehicle and seismic code adoption trajectories. Forecast inputs included scrap-to-billet price spreads, MEE quota allocation schedules, and EU carbon-border adjustment phase-in assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt aluminum substitution acceleration or MEE quota contraction scenarios. Model assumptions reflect documented regulatory trajectories without anticipating unannounced policy shifts. A model refresh is warranted upon material change in EU carbon-border adjustment implementation timelines or BIS IS 1786 reciprocity negotiations with ASEAN suppliers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Industrial Thermal Insulation Market
Building & Construction Materials
North America Particle Board Market
Building & Construction Materials
Asia-Pacific Construction Adhesives Market
Building & Construction Materials
Skirting Board Market
Building & Construction Materials
Building Insulation Market
Building & Construction Materials
Temporary Storage Buildings Market
Building & Construction Materials
Global Shotcrete/Sprayed Concrete Market
Building & Construction Materials
Outside Door Handle Market
Building & Construction Materials
United Kingdom Prefab Wood Buildings Market
Building & Construction Materials
External Wall Insulation Board Market
Building & Construction Materials
Geogrid Market
Building & Construction Materials
Global Concrete Surface Retarders Market
Building & Construction Materials
Tower Bolt Market
Building & Construction Materials
North America Non-Residential Polished Concrete Market
Building & Construction Materials
PVC Window Market
Building & Construction Materials
Italy Ceramic Tiles Market