
 South America Fungicide Market | 2026-2036
South America Fungicide Market Size, Share, and Industry Trends Forecast 2026-2036
South America Fungicide Market Insights
ANVISA's re-registration requirements under Resolution RDC 294/2019 is rotating the competitive landscape toward manufacturers with dedicated toxicology and residue chemistry capabilities. Syngenta Group leverages its integrated seed-and-crop-protection platform to sustain channel dominance across Brazilian soybean belts. BASF SE anchors its position through backward integration into active ingredient synthesis, while Bayer AG competes via biological-and-chemical fungicide combination portfolios.
Fungicides are biocidal compounds formulated to inhibit or kill fungal pathogens affecting agricultural crops, typically containing active ingredients such as azoles that disrupt ergosterol biosynthesis in fungal cell membranes. Their primary commercial purpose centers on yield protection in broad-acre and specialty crop systems where fungal epidemics can destroy harvest value within days. Strobilurins occupy the premium tier in Brazilian soybean applications due to their systemic mobility and resistance management utility, while triazoles represent the volume backbone across cereals and oilseeds where cost efficiency governs procurement. Soil treatment formulations are gaining structural share in no-till systems prevalent across Argentina's Pampas, displacing foliar-only programs with early-season protection embedded at planting.
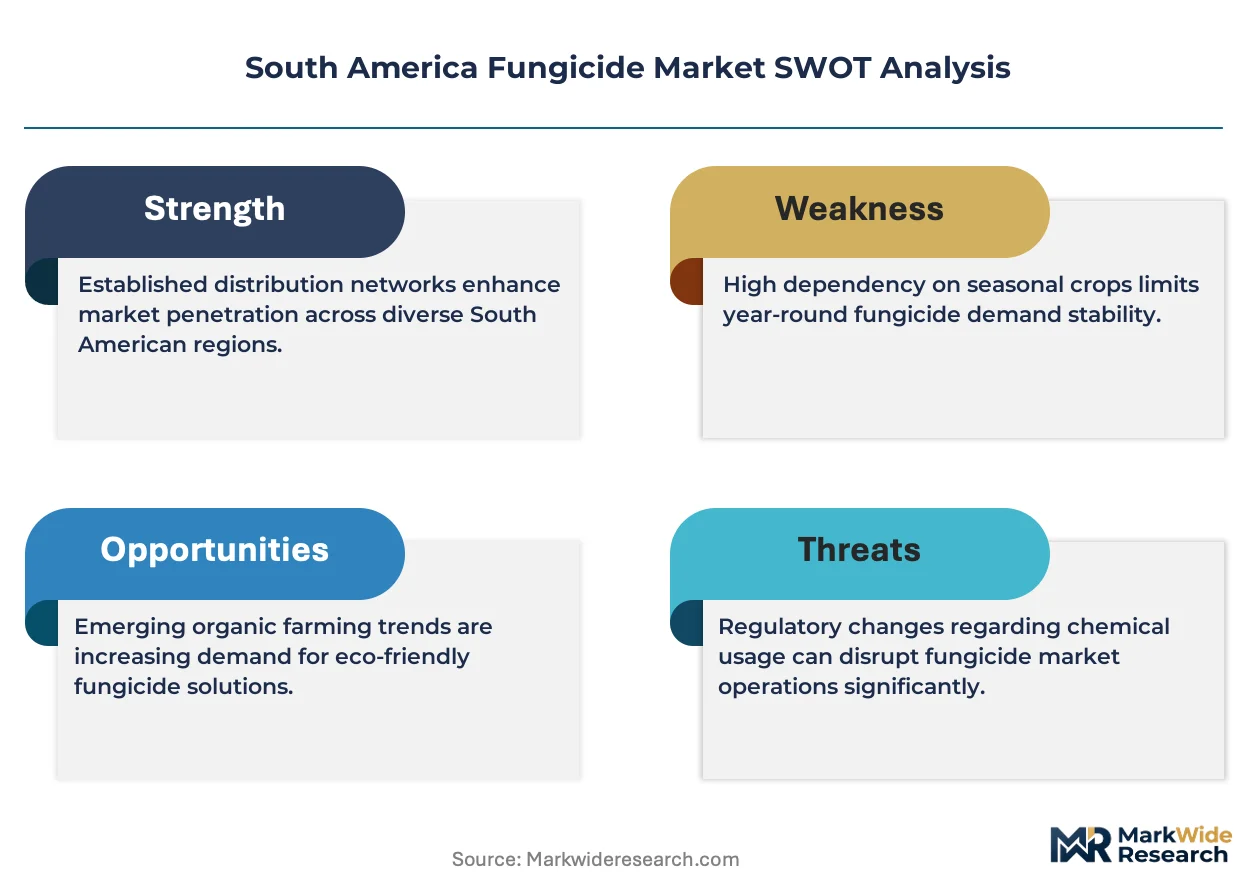
ANVISA's residue tolerance protocols and Brazil's Ministry of Agriculture MAPA registration timelines shape product development pipelines, forcing reformulation investments before patent cliffs erode margins. Argentina's SENASA import-equivalence rules and Chile's SAG phytosanitary certification create fragmented market access conditions that favor registrants with dedicated South American regulatory affairs teams. Stakeholders must monitor the convergence of biological fungicide efficacy data with ANVISA's accelerated novel-mode-of-action review pathway, as this interface will determine which technology portfolios capture replacement demand from phased-out chemistries.
Market Dynamics
ANVISA's accelerated re-evaluation framework under Resolution RDC 294/2019 is systematically retiring legacy chemistries while fast-tracking novel-mode-of-action registrations, compressing product lifecycles and forcing reformulation investments before patent cliffs erode margins.
Growth Catalysts
- Asian Soybean Rust Pressure:Pathogen resistance to single-site fungicides across Brazil's Cerrado and Pampas regions is driving stacked application programs and premium strobilurin-triazole combinations.
- Resolution RDC 294/2019:ANVISA's streamlined novel molecule pathway is reducing registration timelines for biological-and-chemical combination products, opening replacement demand windows.
- No-Till Expansion:Soil treatment formulations embedded at planting are displacing foliar-only programs across Argentina's Pampas, creating structural volume growth in seed-applied fungicide segments.
Market Restraints
- Active Ingredient Concentration:Three manufacturers control over 70% of strobilurin technical production globally, exposing Brazilian formulators to supply allocation risk and input cost volatility.
- Residue Chemistry Burden:ANVISA's tolerance protocols require extensive field residue trials, adding 18-24 months to registration timelines for reformulated products.
- Biological Substitution Threat:Bacillus-based biocontrol products are capturing share in preventive soybean applications where rust pressure remains moderate, pressuring chemical fungicide pricing.
Strategic Opportunities
- Chilean Specialty Crop Segment:Vineyard and berry operations in Chile's Central Valley remain underpenetrated by systemic fungicide programs, offering premium pricing potential for targeted formulations.
- Biological-Chemical Convergence:Integration of Trichoderma spp. with reduced-rate triazoles is opening hybrid product categories that command price premiums over standalone chemistries.
- SENASA Import Equivalence:Argentina's streamlined equivalence recognition for Brazilian-registered products enables cross-border formulation supply without full re-registration.
Industry Challenges
- Regulatory Affairs Talent Scarcity:ANVISA's evolving toxicology requirements have created acute shortages of residue chemists and field trial coordinators capable of managing complex dossier submissions.
- Channel Inventory Reconfiguration:The shift from foliar to soil-applied formulations is forcing distributors to retool storage infrastructure for seed-treatment handling and precision application equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Fungicide Market |
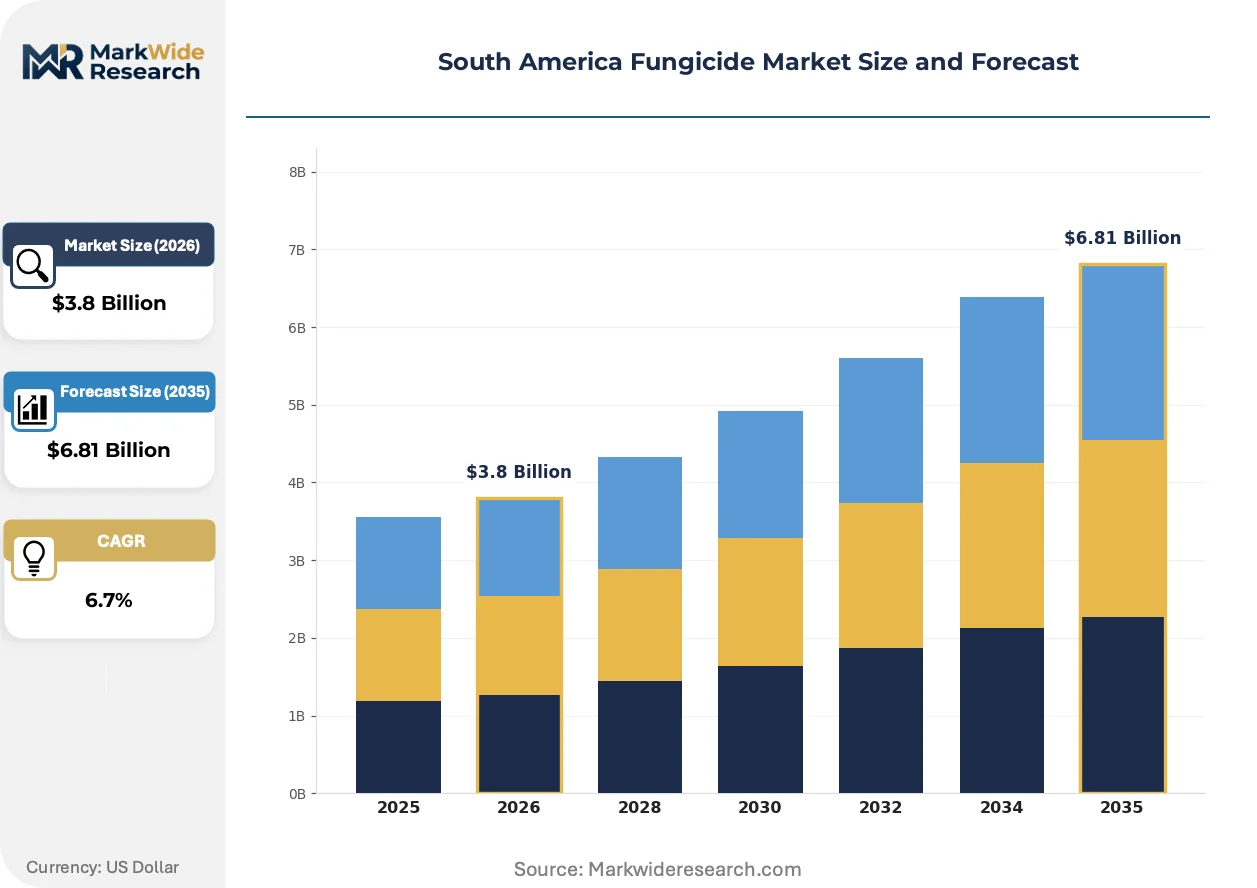
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Azoles, Strobilurins, Triazoles, Chloronitriles Crop Type: Cereals, Fruits, Vegetables, Oilseeds Application Method: Soil Treatment, Foliar Spray, Seed Treatment, Post-Harvest Formulation: Granules, Liquids, Wets, Powders |
| Companies Covered | Syngenta Group, BASF SE, Bayer AG, Corteva Agriscience, UPL Limited, FMC Corporation, ADAMA Agricultural Solutions Ltd, Sumitomo Chemical Co Ltd, American Vanguard Corporation, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Fungicide Market Trends and Innovations
Formulation chemistry and application technology are converging to address resistance management while regulatory pressure accelerates the obsolescence of single-site modes of action across South American soybean belts.
RNA interference fungicides targeting specific fungal mRNA sequences are supplanting broad-spectrum azoles in high-value seed treatment applications. Large-scale cooperatives in Mato Grosso are piloting these precision biocontrol agents for early-season protection. The technology is compressing the addressable market for conventional protectant fungicides in premium soybean segments.
ANVISA's 2023 update to residue monitoring protocols is expanding mandatory multi-residue testing for imported grain shipments. This regulatory tightening is forcing exporters to document complete fungicide application histories. Brazilian bulk grain handlers are now requiring supplier certification of pre-harvest intervals for all contracted soybean volumes.
Cooperative procurement consortia are consolidating input purchasing across Paraná and Rio Grande do Sul, displacing traditional distributor relationships with direct manufacturer negotiations. These buyer aggregations are extracting volume-based pricing concessions and technical service commitments previously reserved for national distributors. The concentration is most visible in southern Brazil's large-scale farming operations exceeding 10,000 hectares.
South America Fungicide Market Segmentation
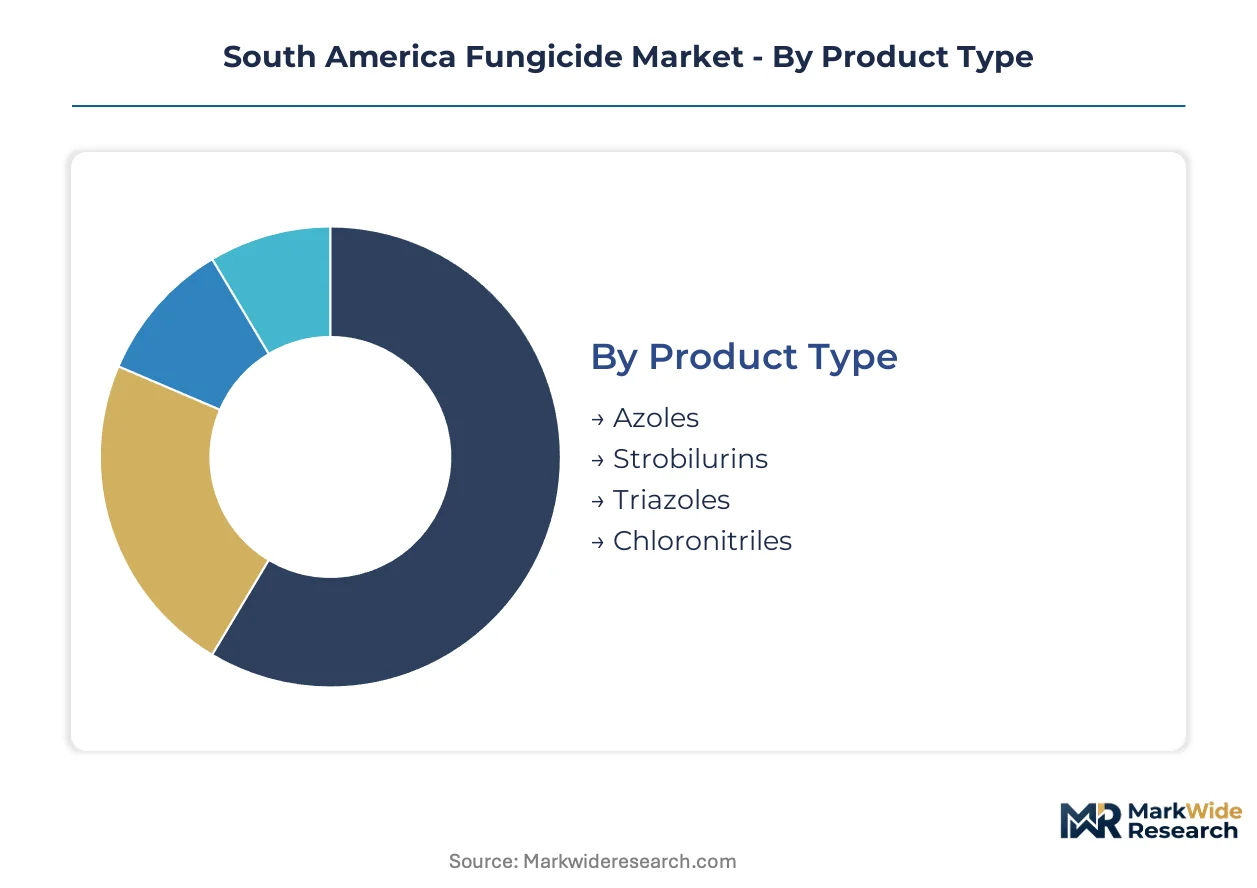
Fungicide segmentation across South America reveals distinct procurement patterns tied to crop value chains and regulatory exposure. Channel configurations vary sharply between bulk commodity soybean belts and high-value specialty crop clusters, with formulation choices driven by application infrastructure and residue compliance requirements.
Product Type:
Channel flow for active ingredient categories splits between direct manufacturer contracts for volume strobilurin-triazole combinations and distributor-led procurement for legacy azoles and chloronitriles.
- Strobilurins:Systemic compounds derived from fungal metabolites that inhibit mitochondrial respiration through Qo site binding. Brazilian Mato Grosso cooperatives specify these for stacked rust management programs where resistance rotation is mandatory. ANVISA's residue protocols favor their favorable toxicology profiles over older chemistries.
- Triazoles:Ergosterol biosynthesis inhibitors with broad-spectrum activity against Ascomycetes and Basidiomycetes. Demand concentrates across Paraná and Rio Grande do Sul cereal operations where cost-per-hectare governs procurement decisions and foliar spray infrastructure is universal.
- Azoles:Earlier-generation DMI fungicides facing accelerated phase-out under Resolution RDC 294/2019. Remaining volumes flow through clearance channels for non-export grain.
- Chloronitriles:Protectant contact fungicides with multi-site activity. Argentina's SENASA-registered formulations maintain niche demand in potato and vegetable sectors where resistance pressure is lower.
Strobilurins dominate installed base in premium soybean belts. Triazoles are where expansion concentrates as generic sourcing reduces unit costs.
Crop Type:
Customer type and margin structure vary dramatically across crop categories, with oilseed procurement consolidating through cooperative aggregators while specialty crops retain fragmented distributor relationships.
- Oilseeds:Soybean cultivation across Brazil's Cerrado and Argentina's Pampas generates the dominant volume flow. Asian rust pressure forces multiple applications per season, with large-scale operators negotiating direct supply agreements bypassing traditional distribution.
- Cereals:Wheat and corn operations in southern Brazil and Argentina's Buenos Aires province. Application windows are narrower than oilseeds, favoring pre-mix formulations with built-in resistance management.
- Fruits:Grape, citrus, and apple production in Chile's Central Valley and Brazil's São Paulo state. Premium pricing supports targeted systemic programs with documented residue compliance for export certification.
- Vegetables:Potato, tomato, and onion cultivation with concentrated demand in Argentina's Mendoza and Brazil's Minas Gerais. Smaller plot sizes sustain distributor technical service relationships.
Oilseeds anchor volume procurement scale. Fruits represent the steepest expansion trajectory for premium formulation development.
Application Method:
Supply concentration and infrastructure investment requirements reshape competitive access depending on whether protection is embedded at planting, applied in-season, or delivered post-harvest.
- Soil Treatment:Granular or liquid formulations applied at planting in no-till systems prevalent across Argentina's Pampas. Equipment integration with precision planters creates high switching costs for farmers.
- Foliar Spray:Aerial and ground-based application of liquid formulations across Brazilian soybean belts. Mato Grosso's aerial spray contractor networks handle the majority of volume.
- Seed Treatment:Early-season protection embedded through film coatings or pelleting. Growing share in Brazil as farmers seek to defer first foliar application.
- Post-Harvest:Storage protection for grain and fruit export quality preservation. Limited to high-value export corridors with certified cold chain infrastructure.
Foliar spray retains the largest installed application base. Seed treatment is gaining share fastest as planting-embedded protection reduces operational complexity.
Formulation:
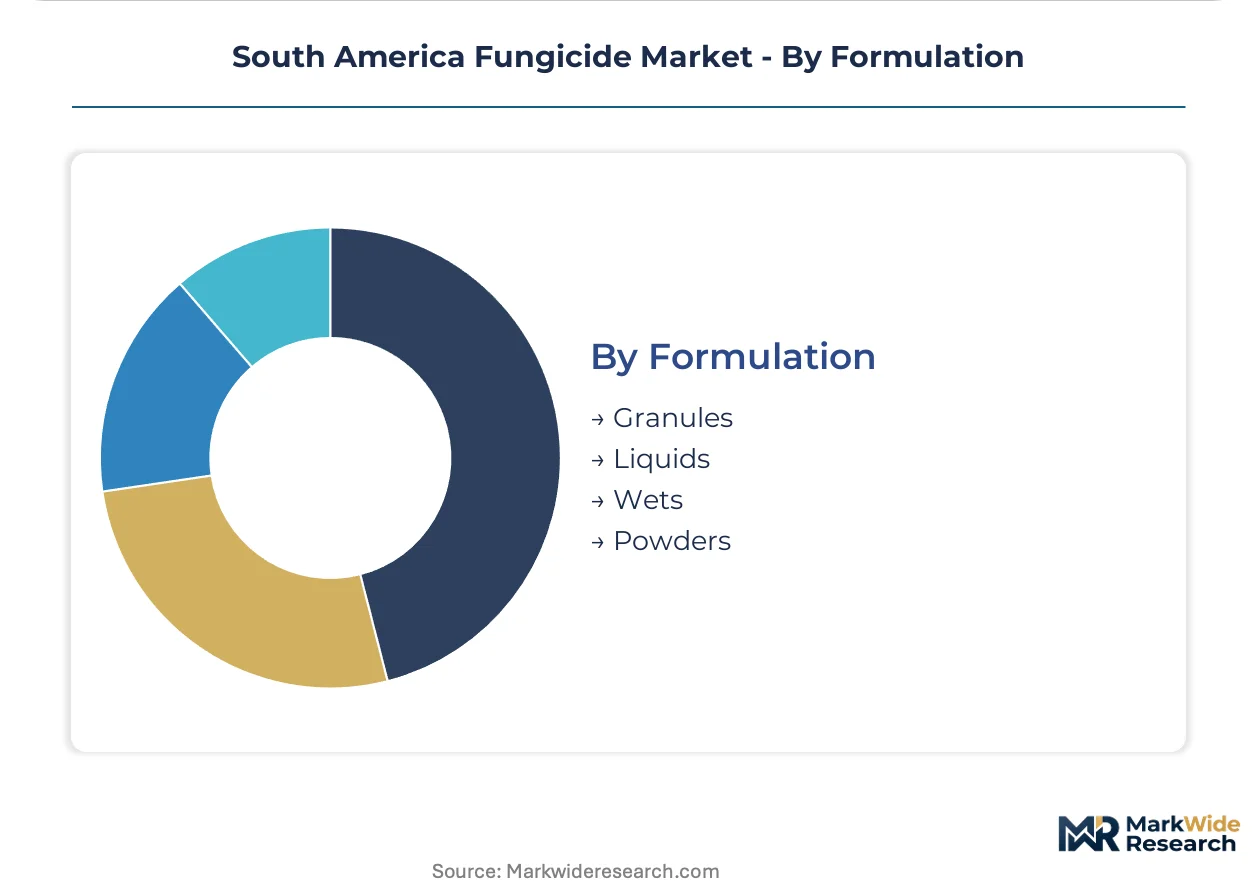
Cost tier and handling infrastructure requirements segment procurement, with liquid concentrates dominating broad-acre operations and solids retaining position where water access or mixing equipment is constrained.
- Liquids:Suspension concentrates and emulsifiable concentrates optimized for foliar spray systems. Brazilian cooperatives specify these for aerial application compatibility and rapid tank mixing.
- Granules:Controlled-release formulations for soil treatment in no-till corn and soybean planting. Argentina's precision agriculture adoption drives specification.
- Wets:Wettable powders requiring agitation during tank mixing. Declining share except in smallholder vegetable sectors with limited equipment investment.
- Powders:Dust formulations for seed treatment and specialized post-harvest applications. Niche demand concentrated in Chilean fruit export packing operations.
Liquids dominate commercial farming procurement. Granules are where formulation R&D investment concentrates for planting-embedded delivery systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Santos grain terminal anchors Brazil's fungicide distribution infrastructure, handling over 150 million tonnes of agricultural commodities annually and channeling crop protection inputs into the interior soybean belt.
Brazil
Asian soybean rust pressure across Mato Grosso and Paraná drives multiple fungicide applications per growing season. ANVISA's Resolution RDC 294/2019 accelerates phase-out of legacy azoles while fast-tracking novel molecule registrations. São Paulo state's formulation plants supply blended strobilurin-triazole products to the Cerrado expansion zone.
Argentina
No-till soybean and corn systems across the Pampas generate structural demand for soil-applied fungicide formulations. SENASA's import-equivalence rules enable Brazilian-registered products to cross without full re-registration. Buenos Aires province cooperatives negotiate direct supply contracts bypassing traditional distribution channels.
Chile
Vineyard and berry operations in the Central Valley remain underpenetrated by systemic fungicide programs compared to commodity crop benchmarks. SAG phytosanitary certification requirements shape residue compliance protocols for export-oriented fruit packers. Maule Region's wine cooperatives are piloting precision application technologies for downy mildew management.
Colombia
High-altitude coffee zones in Antioquia and Cauca require specialized fungicide programs against leaf rust pathogens. The country's national agricultural regulator enforces residue tolerance protocols aligned with EU export market access requirements. Coffee federation procurement consortia aggregate input purchasing across the Eje Cafetero region.
Uruguay
Intensive soybean and wheat rotations across the Litoral region mirror Argentine application patterns at smaller scale. MGAP's pesticide registration timelines lag regional peers, creating reliance on Brazilian formulation imports. Paysandú and Colonia departments concentrate commercial farming operations with direct manufacturer relationships.
South America Fungicide Market Competitive Landscape
Listed leaders compete with private specialists across regulatory affairs capabilities, with public company R&D budgets clashing against private capital's speed-to-market advantages in novel biological registrations. The sector exhibits tiered concentration: integrated agrochemical conglomerates control active ingredient synthesis, mid-scale formulators serve regional cooperatives, and biological specialists capture preventive application niches. Dominant competitive moves include backward integration into technical production and cross-border registration arbitrage exploiting SENASA-ANVISA equivalence pathways.
Within the integrated conglomerate tier, Syngenta Group, BASF SE, and Bayer AG exemplify archetypes of channel dominance, backward integration, and portfolio diversification respectively. Syngenta's Swiss-registered structure represents seed-and-crop-protection platform consolidation. BASF SE anchors German chemical industry positioning through captive active ingredient supply. Bayer AG occupies the biological-chemical convergence space with combination product development pipelines.
| Leading Market Players |
|---|
| Syngenta Group |
| BASF SE |
| Bayer AG |
| Corteva Agriscience |
| UPL Limited |
| FMC Corporation |
| ADAMA Agricultural Solutions Ltd |
| Sumitomo Chemical Co Ltd |
| American Vanguard Corporation |
| Others |
Pricing and Supply Chain Analysis
Seed treatment fungicides displacing foliar applications across Argentina's Pampas and Brazil's Cerrado simultaneously redistribute manufacturing capacity toward São Paulo formulation plants and compress per-hectare pricing economics for aerial spray contractors. This substitution dynamic concentrates procurement leverage with cooperatives specifying planting-embedded protection while eroding margins for legacy foliar distribution networks.
Pricing Analysis
Volume-discount tiering structures separate national cooperative consortia from regional distributor networks from smallholder clearance channels. Price differentiation rests on application timing flexibility, residue documentation depth for ANVISA export certification, and bundled technical service commitments. Cost compression in generic triazole segments is intensifying because Brazilian formulators source technical material from concentrated Asian suppliers. Regional distributors serving vegetable sectors in Minas Gerais exhibit highest price sensitivity, while Mato Grosso cooperatives negotiating direct manufacturer contracts demonstrate lowest sensitivity due to yield-risk transfer requirements.
Supply Chain Analysis
China and India anchor strobilurin and triazole technical production, while Brazil's São Paulo state concentrates formulation blending for South American distribution. Active ingredient synthesis draws from concentrated overseas supply, with Brazilian plants dependent on imported technical material for local formulation. Single-source vulnerability concentrates in strobilurin technical production where three manufacturers control majority global capacity. Distribution runs through Port of Santos grain terminal infrastructure channeling inputs into interior soybean belts, with cooperative procurement consortia increasingly bypassing traditional distributor tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized residue chemistry capabilities and ANVISA dossier management expertise constitute the critical scarcity layer determining competitive survival as Resolution RDC 294/2019 accelerates product turnover cycles.
For Market Incumbents: Fortify backward integration into active ingredient synthesis to secure supply allocation priority during technical material shortages. Deepen regulatory affairs capabilities in toxicology and residue chemistry to compress ANVISA registration timelines before patent cliffs erode proprietary product margins. Channel control through integrated seed-and-crop-protection platforms offers defensive positioning against biological substitution threats in preventive soybean applications. For New Entrants and Emerging Players: Differentiate on biological-chemical combination formulations targeting ANVISA's accelerated novel-mode-of-action review pathway. Chilean vineyard and berry operations in the Central Valley represent the most penetrable white-space segment, with systemic fungicide programs remaining underdeveloped relative to commodity crop benchmarks. SENASA import-equivalence arbitrage enables cross-border supply from Brazilian-registered formulations without full Argentina re-registration. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private-equity-backed mid-scale formulators possessing established ANVISA registration portfolios but lacking integrated technical production. Long-term viability hinges on replacement demand capture from phased-out legacy chemistries over the medium-term regulatory transition. Monitor convergence velocity between biological fungicide efficacy data and ANVISA's novel-mode-of-action review pathway as the primary inflection signal for technology portfolio valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Active Ingredient Synthesis | Captive technical production insulates Brazilian formulators from supply allocation risk during Asian manufacturer capacity constraints. |
| Biological-Chemical Combination Product Development | Hybrid formulations command price premiums over standalone chemistries while qualifying for ANVISA's accelerated registration pathway. |
| Cooperative Procurement Consortium Participation | Direct manufacturer relationships with Mato Grosso and Paraná cooperatives displace traditional distributor margin capture. |
| Residue Chemistry Capability Buildout | Dedicated toxicology and field trial coordination teams compress ANVISA registration timelines for reformulated products. |
| Chilean Specialty Crop Market Entry | Central Valley vineyard and berry operations offer premium pricing potential with limited incumbent systemic fungicide penetration. |
Research Methodology
Operator-level perspectives from crop protection distributors, cooperative procurement managers, ANVISA regulatory consultants, and formulation plant technical directors anchored the qualitative base. Secondary validation drew from customs trade data, MAPA registration databases, ANVISA resolution filings, and SEC 10-K disclosures of listed agrochemical conglomerates. Bottom-up volume estimates from state-level application rate surveys triangulated against top-down market value reconstructions.
Sensitivity analysis around Asian soybean rust pressure severity, ANVISA re-evaluation acceleration timelines, and biological substitution rates tested forecast robustness across the projection horizon. Segmentation modeling incorporated product type, crop category, application method, and formulation chemistry dimensions. CAGRs derived from regression analysis of historical volume trends against planted area expansion and application intensity trajectories. Industry-specific inputs included ANVISA registration pipeline data and cooperative procurement consortium formation rates.
Material uncertainties — regulatory timeline delays, pathogen resistance evolution, and technical material supply disruptions — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding resolution implementation velocity and farmer adoption patterns for novel application technologies. Recalibration cycles align with material shifts in ANVISA regulatory pronouncements and Asian soybean rust epidemiological monitoring.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
North America Insecticide Market
Crop Protection
Global Acephate Market
Crop Protection
US Pest Control Market
Crop Protection
France Crop Protection Chemicals Market
Crop Protection
Indonesia Insecticide Market
Crop Protection
Soil Sterilizers Market
Crop Protection
Captan Fungicide Market
Crop Protection
Herbicide Safeners Market
Crop Protection
Azoxystrobin Market
Crop Protection
Pest Control Products Market
Crop Protection
Fosthiazate Market
Crop Protection
Indoor Vertical Farm Safe Crop Protection Chemistry Market
Crop Protection
North America Acaricides Market
Crop Protection
Europe Herbicide Market
Crop Protection
Vietnam Crop Protection Chemicals Market
Crop Protection
Low-Odor, Enclosed-Greenhouse Foliar Protection Market