
 South America Feed Anti-Caking Agents Market | 2026-2036
South America Feed Anti-Caking Agents Market Size, Share, and Industry Trends Forecast 2026-2036
South America Feed Anti-Caking Agents Market Analytics
Market Dynamics
Specialized formulation chemists with expertise in hygroscopic mineral stabilization is collapsing across Argentina and Uruguay, forcing feed compounders to source pre-blended anti-caking systems rather than customize in-house. BASF SE leverages its Montevideo technical service center to sustain direct relationships with Brazilian integrators. Cargill Inc. anchors regional supply through its captive distribution network spanning Paraguay to Colombia. Kemin Industries Inc. differentiates via precision-milled organic additive grades targeting premium pet food contracts.
Product Landscape
Feed anti-caking agents comprise inorganic and organic compounds engineered to absorb moisture, reduce particle cohesion, and maintain free-flow characteristics in finished feed matrices; silicate grades typically achieve bulk density below 0.4 g/cm³ and moisture absorption capacity exceeding 25% by weight to prevent bridge formation in storage silos. Silicates dominate volume throughput across the region due to cost efficiency in bulk poultry rations, while organic additives capture margin concentration in pet food and aquaculture formulations where label-friendly positioning commands premium positioning. Clays retain stable demand from ruminant feed manufacturers seeking pH buffering alongside flow control.
Regulatory Environment
Brazil's MAPA and Argentina's SENASA enforce divergent additive registration pathways, with SENASA requiring full toxicological dossiers for novel silicate sources while MAPA permits provisional commercialization pending parallel safety studies. ANVISA's overlapping jurisdiction over feed-contact substances in Brazil creates dual compliance obligations for imported organic additives. Stakeholders must monitor pending Mercosur harmonization negotiations that could unify maximum permissible levels for carbonates and clays across member states.
Market Dynamics
Specialized formulation chemists with expertise in hygroscopic mineral stabilization are collapsing across Argentina and Uruguay, forcing feed compounders to source pre-blended anti-caking systems rather than customize in-house formulations.
Growth Catalysts
- Brazil's MAPA registration enforcement:Tightening quality documentation for imported silicates and carbonates is filtering out low-grade suppliers and consolidating demand around certified additive producers.
- Poultry feed pellet flowability requirements:Humid storage conditions across Brazil's southern livestock corridor are mandating moisture absorption capacity exceeding 25% by weight in finished feed matrices.
- Precision-milled organic additive grades:Pet food manufacturers in São Paulo and Buenos Aires are specifying label-friendly positioning that commands premium contract structures.
Market Restraints
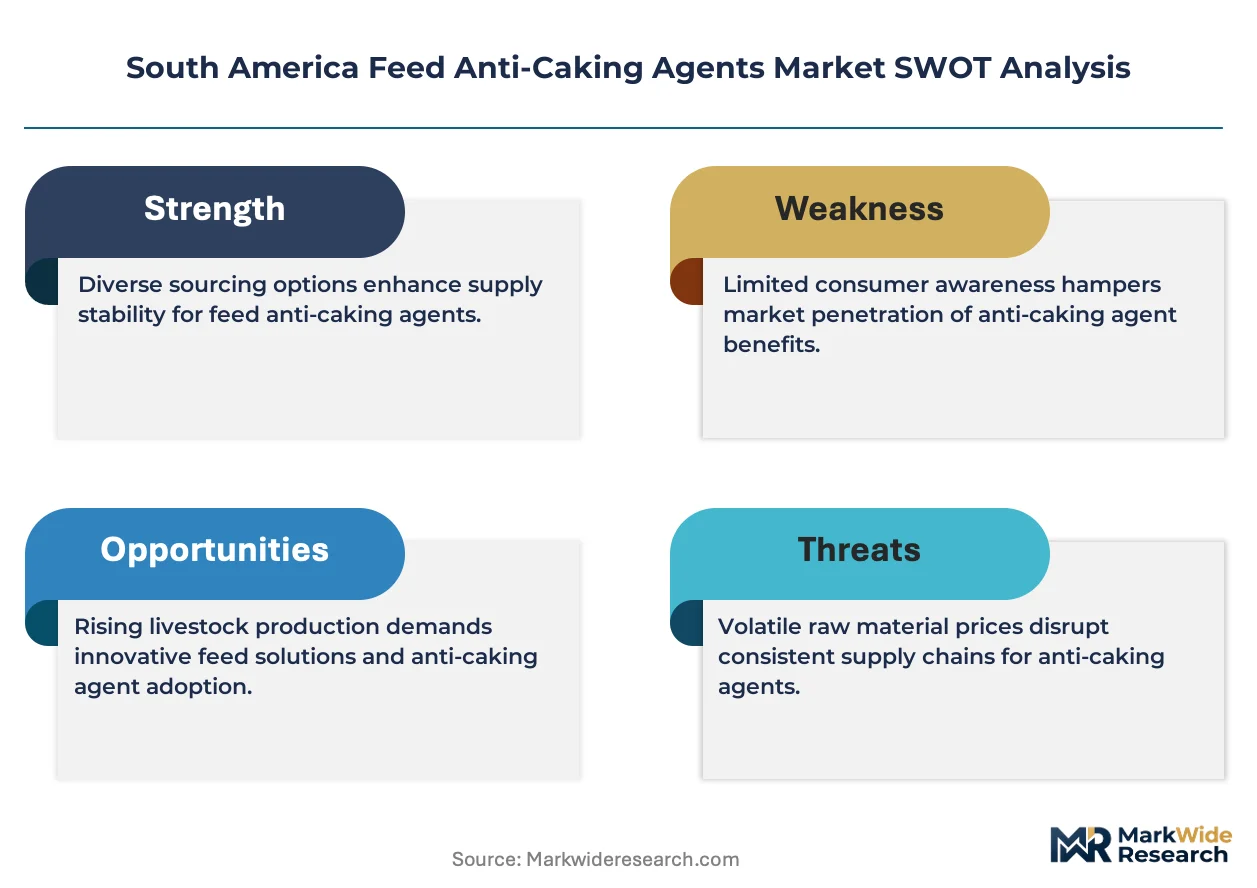
- Input cost volatility in mineral feedstocks:Silicate and clay raw material prices fluctuate with Brazilian mining royalty adjustments and Argentine export tariff instability.
- Supply concentration in Montevideo technical services:Regional formulation expertise clusters in Uruguay, creating single-point vulnerability for Brazilian integrators requiring rapid troubleshooting.
- Divergent SENASA toxicological dossier requirements:Argentina's full safety study mandates for novel silicate sources delay commercialization timelines versus Brazil's provisional approval pathway.
Strategic Opportunities
- Underpenetrated Paraguayan poultry integration:Emerging feed mill construction near Asunción lacks established anti-caking supplier relationships, creating first-mover positioning for technical service providers.
- Mercosur harmonization negotiations:Pending unified maximum permissible levels for carbonates and clays would eliminate dual compliance costs for cross-border compounders.
- Aquaculture formulation premiumization:Shrimp and tilapia feed producers in Ecuador and Colombia are specifying organic additive grades previously reserved for pet food applications.
Industry Challenges
- Formulation chemistry skill scarcity:The collapse of specialized mineral stabilization expertise in Argentina and Uruguay forces reliance on pre-blended systems with limited customization flexibility.
- Dual ANVISA-MAPA compliance timelines:Brazil's overlapping jurisdiction over feed-contact substances creates parallel documentation requirements that extend product registration cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Feed Anti-Caking Agents Market |
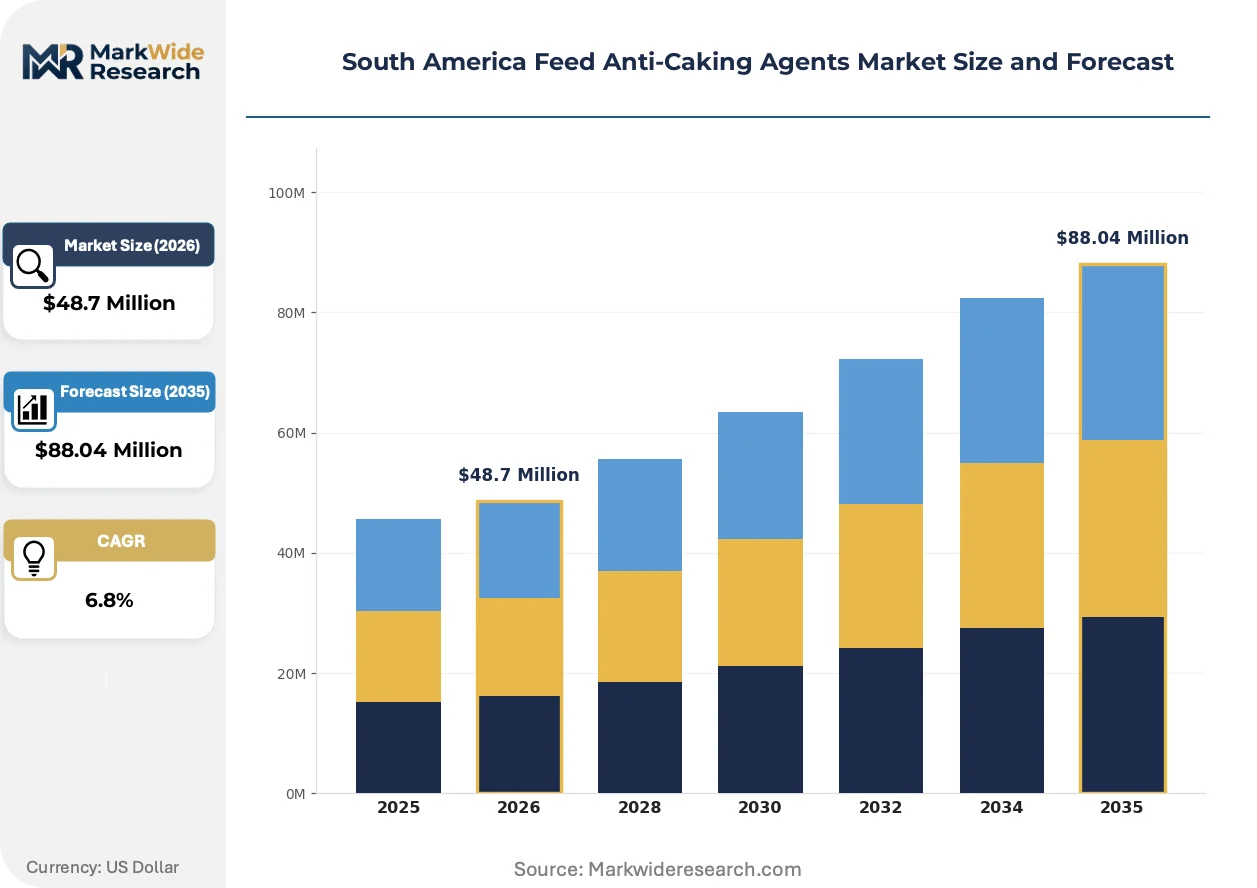
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $88.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clays, Silicates, Carbonates, Organic Additives Application: Animal Feed, Pet Food, Aquaculture Feed, Nutritional Supplements End User: Livestock Farmers, Pet Owners, Aquaculture Enterprises, Feed Manufacturers Delivery Mode: Bulk, Bags, Transport Tanks, Others |
| Companies Covered | BASF SE, Cargill Inc., Kemin Industries Inc., Huber Engineered Materials, Evonik Industries, Novus International, Solvay, Roquette Freres SA, Sasol Ltd., Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Feed Anti-Caking Agents Market Evolving Landscape
Moisture control technologies are fragmenting across cost-sensitive bulk applications and precision-grade specialty formulations, with regulatory divergence between Brazil and Argentina accelerating supplier specialization.
Surface-modified silicate grades engineered for sub-0.4 g/cm³ bulk density are bifurcating the additive landscape. Poultry integrators in Paraná and Santa Catarina are adopting these materials at accelerated procurement cycles. The technology is compressing margins on unmodified mineral grades while enabling premium positioning for precision-milled alternatives.
MAPA's provisional commercialization pathway for imported additives is diverging from SENASA's full toxicological dossier requirements. Brazilian compounders are exploiting this asymmetry to accelerate novel silicate introductions ahead of Argentine competitors. Pet food manufacturers with cross-border formulations face the steepest compliance cost differentials.
Direct technical service relationships are displacing distributor-mediated procurement for large Brazilian integrators. BASF SE's Montevideo center and captive distribution networks are capturing volume from traditional channel intermediaries. This pattern concentrates most visibly among poultry producers in Rio Grande do Sul with annual additive procurement exceeding 500 metric tons.
South America Feed Anti-Caking Agents Market Segmentation
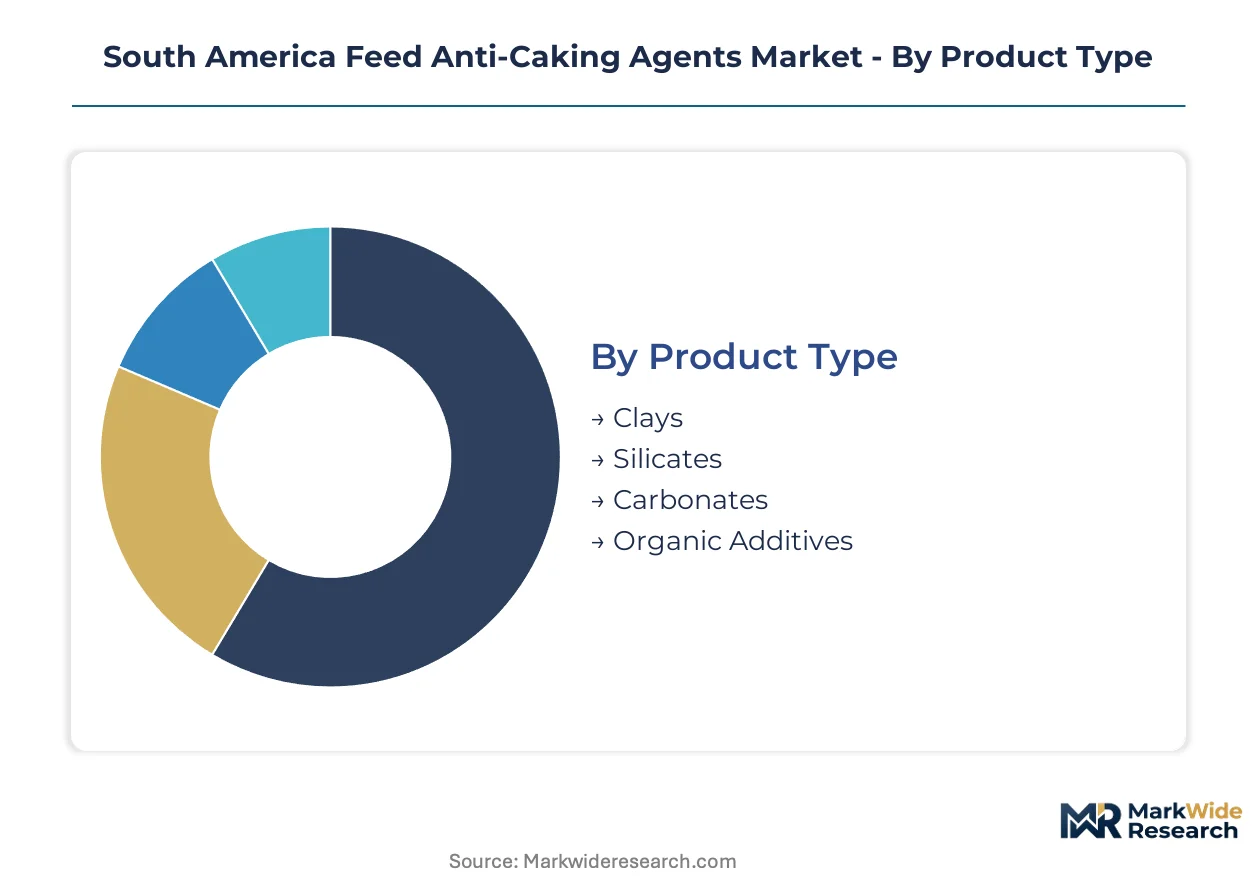
Feed anti-caking agents flow through distinct procurement channels shaped by volume scale, formulation complexity, and regulatory documentation burden. Understanding these segment boundaries clarifies where margin concentrates versus where commodity competition dominates.
Product Type:
Silicates and clays move predominantly through bulk mineral distributors serving poultry integrators, while organic additives route through specialty chemical channels requiring technical service support.
- Silicates:Synthetic and natural silicate grades achieve bulk density below 0.4 g/cm³ with moisture absorption exceeding 25% by weight. Demand concentrates in Brazil's southern livestock corridor where humid storage conditions mandate high-capacity moisture control for poultry pellet flowability.
- Organic Additives:Precision-milled plant-derived and synthetic organic compounds engineered for label-friendly positioning. Pet food manufacturers in São Paulo and Buenos Aires specify these grades for premium contract structures where clean-label claims command price premiums.
- Clays:Bentonite and kaolin-based materials serve ruminant feed manufacturers seeking dual-function pH buffering alongside flow control.
- Carbonates:Calcium and magnesium carbonate grades provide cost-efficient moisture absorption for bulk compound feed applications with lower performance specifications.
By volume, silicates lead. By growth pace, organic additives are expanding most quickly.
Application:
Cost tier stratification separates commodity bulk feed applications from precision-formulated specialty nutrition where additive specifications tighten.
- Animal Feed:Poultry, swine, and ruminant formulations represent the volume anchor, with Brazilian integrators in Paraná and Santa Catarina specifying surface-modified silicate grades at accelerated procurement cycles.
- Pet Food:Premium dry kibble and extruded treats demand organic additive grades with documented absence of synthetic anti-caking agents. São Paulo-based contract manufacturers drive specification tightening.
- Aquaculture Feed:Shrimp and tilapia producers in Ecuador and Colombia are migrating toward organic additive grades previously reserved for pet food, creating specification spillover.
- Nutritional Supplements:Vitamin and mineral premixes require anti-caking integration to maintain blend homogeneity through extended shelf life.
Animal feed dominates absolute volume. Pet food carries the steepest margin expansion trajectory.
End User:
Customer type determines whether procurement flows through distributor intermediaries or direct technical service relationships.
- Feed Manufacturers:Large Brazilian integrators with annual additive procurement exceeding 500 metric tons are displacing distributor channels in favor of direct technical service relationships anchored by Montevideo-based formulation support.
- Livestock Farmers:Smaller-scale operations in Argentina's Entre Ríos and Córdoba provinces rely on pre-blended anti-caking systems from regional compounders due to collapsed in-house formulation expertise.
- Aquaculture Enterprises:Ecuadorian shrimp operations and Colombian tilapia producers specify imported organic grades with full toxicological dossiers to meet export market requirements.
- Pet Owners:Indirect demand driver through contract manufacturers; no direct procurement channel exists for this segment.
Feed manufacturers command procurement volume leadership. Aquaculture enterprises are gaining share fastest as regional protein production shifts toward marine species.
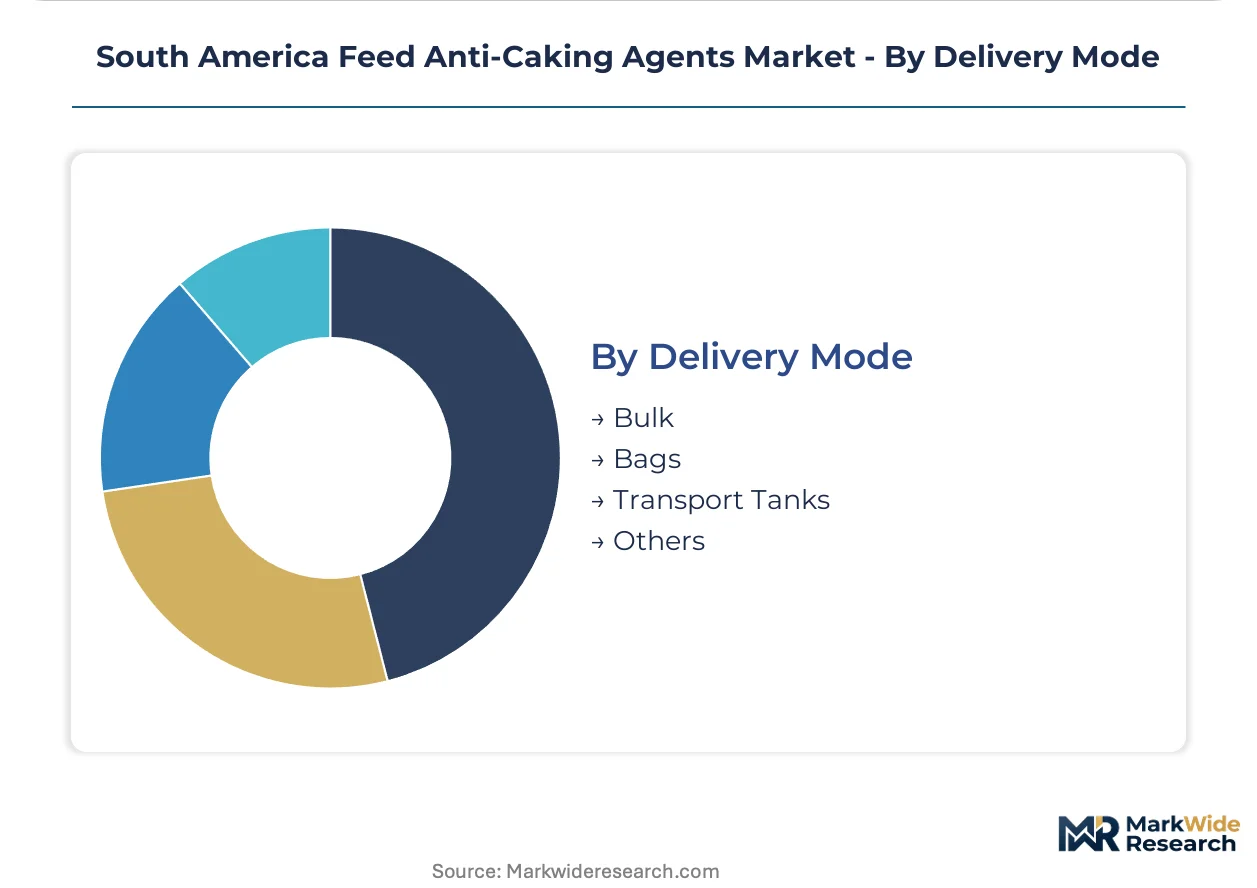
Delivery Mode:
Supply concentration in Brazilian mineral processing and Argentine import logistics shapes how physical product reaches compounders.
- Bulk:Pneumatic delivery of silicate and clay powders to mill-side storage silos serves large poultry integrators in Rio Grande do Sul with continuous production schedules.
- Bags:25kg and 50kg woven polypropylene packaging dominates organic additive distribution where batch-scale precision dosing requires measured dispensing.
- Transport Tanks:Liquid suspension concentrates of modified silicates for automated dosing systems at high-throughput feed mills.
- Others:Intermediate bulk containers and custom packaging for specialty premix manufacturers with unique handling requirements.
Bulk delivery leads by tonnage. Bagged formats are climbing the fastest as specialty additive share expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil commands pricing leverage over Argentine suppliers due to MAPA's provisional approval pathway, while SENASA's full toxicological dossier requirements compress margins for cross-border compounders. This regulatory asymmetry reshapes procurement patterns across the southern livestock corridor.
Brazil
Poultry integrators in Paraná and Santa Catarina specify surface-modified silicate grades with sub-0.4 g/cm³ bulk density for humid storage conditions. MAPA enforcement of additive registration requirements filters low-grade imports and consolidates demand around certified producers. The southern livestock corridor spanning Rio Grande do Sul anchors regional volume, with mills procuring additives exceeding 500 metric tons annually.
Argentina
Collapsed formulation chemistry expertise in Buenos Aires and Córdoba forces feed compounders toward pre-blended anti-caking systems. SENASA mandates complete toxicological dossiers for novel silicate sources, delaying commercialization versus Brazilian competitors. The Entre Ríos province relies on regional compounders for anti-caking integration as in-house customization capacity vanishes.
Uruguay
Montevideo technical service clusters create single-point vulnerability for Brazilian integrators requiring rapid troubleshooting support. BASF SE anchors regional formulation expertise through its captive service center. The capital's concentration of hygroscopic mineral stabilization knowledge draws procurement decisions from cross-border poultry producers.
Paraguay
Emerging feed mill construction near Asunción lacks established anti-caking supplier relationships, creating first-mover positioning for technical service providers. The country's poultry integration expansion outpaces local additive sourcing infrastructure. Brazilian distributors are extending captive networks northward to capture unpenetrated demand.
Colombia and Ecuador
Shrimp and tilapia feed producers specify organic additive grades previously reserved for pet food applications, creating specification spillover from premium nutrition segments. Aquaculture enterprises demand full toxicological dossiers to meet export market requirements. Colombian integrators bypass traditional mineral distributors for direct technical service relationships.
South America Feed Anti-Caking Agents Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with precision-milled organic additive specialists commanding premium positioning while bulk mineral processors dominate volume throughput. The market structures around three tiers: multinational chemical conglomerates with integrated technical service networks, regional distributors with captive logistics infrastructure, and specialty additive pure-plays targeting label-friendly nutrition segments. Consolidation pressure concentrates among mid-scale compounders lacking backward integration into mineral feedstocks. Strategic moves bifurcate between direct technical service relationships displacing distributor channels and geographic expansion into underpenetrated Andean markets.
Among multinational chemical conglomerates, BASF SE and Evonik Industries occupy positions exemplifying technology-forward archetypes with Montevideo-based formulation support. Cargill Inc. anchors the distributor-integrated tier through captive networks spanning Paraguay to Colombia. Kemin Industries Inc. sits within the specialty pure-play segment, representing precision-grade positioning for premium contract structures. These three company types illustrate how competitive advantage fragments across service intensity, scale economies, and formulation expertise rather than converging on a single dominant model.
| Leading Market Players |
|---|
| BASF SE |
| Cargill Inc. |
| Kemin Industries Inc. |
| Huber Engineered Materials |
| Evonik Industries |
| Novus International |
| Solvay |
| Roquette Freres SA |
| Sasol Ltd. |
| Others |
Value Network & Pricing Analysis
Surface-modified silicate grades displacing unmodified mineral alternatives are simultaneously redrawing procurement geography toward Montevideo technical clusters and compressing margins on commodity bulk grades. Brazilian integrators exploit this substitution to extract price concessions from traditional mineral distributors while premium-positioning precision-milled alternatives.
Pricing Analysis
The customization-premium spread separates configured-to-order organic additive formulations from standard silicate bulk deliveries. Three-tier pricing structure across premium, standard, and economy levels dominates, with differentiation driven by certification grade under MAPA registration and volume scale of annual procurement. Cost compression in unmodified mineral grades is intensifying because surface-modified alternatives capture specification share from poultry integrators in Paraná. Large Brazilian compounders with procurement exceeding 500 metric tons exhibit lowest price sensitivity, while Argentine regional compounders dependent on pre-blended systems face acute margin pressure.
Supply Chain Analysis
Strategic stockpile preferences among Brazilian poultry integrators contrast with just-in-time mineral sourcing from Argentine compounders facing collapsed formulation expertise. Supply concentrates in Brazil, Uruguay, and Paraguay, with raw material dependencies on mined silicates, processed clays, and imported organic feedstocks. Single-source vulnerability clusters in Montevideo technical service centers, creating bottleneck risk for cross-border troubleshooting. Distribution runs through captive networks anchored by multinational chemical conglomerates, displacing traditional distributor intermediaries for volume accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in a cyclical recovery phase driven by livestock feed demand normalization following herd rebuilding cycles across Brazil's southern corridor.
For Market Incumbents: Fortify technical service relationships with Brazilian integrators through expanded Montevideo formulation support capacity, countering emerging distributor networks from Paraguay. Deepen backward integration into mineral feedstock processing to offset Argentine export tariff instability and secure margin control against low-grade import competition filtered by MAPA enforcement. For New Entrants and Emerging Players: Differentiate on precision-milled organic additive grades targeting Ecuadorian shrimp and Colombian tilapia producers migrating from pet food specifications. Paraguayan poultry integration near Asunción offers the most penetrable white space, accessible through technical service partnerships with feed mill construction projects lacking established supplier relationships. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors specialty additive pure-plays with label-friendly certification portfolios. Long-term viability hinges on regulatory harmonization execution across Mercosur negotiations. Acquisition targets should demonstrate MAPA-registered product lines and direct technical service infrastructure. The signal to watch is SENASA toxicological dossier requirement relaxation, which would unlock cross-border margin compression recovery.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mineral Processing | Captive silicate sourcing insulates Brazilian integrators from Argentine export tariff volatility. |
| MAPA Registration Certification Program | Full dossier compliance unlocks provisional commercialization pathway acceleration versus SENASA delays. |
| Technical Service Center Expansion | Montevideo formulation clusters capture procurement decisions from Rio Grande do Sul poultry producers. |
| Organic Additive Grade Development | Precision-milled plant-derived compounds command premium positioning in São Paulo pet food contracts. |
| Cross-Border Distribution Network Extension | Paraguayan feed mill construction creates first-mover positioning for established Brazilian distributors. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with feed formulation chemists, procurement leads at Brazilian poultry integrators, MAPA regulatory affairs specialists, and distribution channel partners across Paraguay to Colombia. Secondary validation drew from customs trade data, MAPA additive registration filings, SENASA toxicological dossier records, and SEC disclosures from multinational chemical conglomerates. Bottom-up volume triangulation across product grades and top-down macroeconomic anchoring ensured convergence.
Across the analysis window, projections model demand evolution through product type segmentation, application tier stratification, end-user procurement scale, and delivery mode logistics configuration. CAGRs were derived from regression analysis against livestock production indices and feed mill capacity expansion schedules, incorporating mineral feedstock price elasticity and regulatory approval timeline differentials between Brazil and Argentina.
The analysis sits within stated boundaries; outcomes outside sustained MAPA enforcement intensity or Mercosur harmonization progress would require recalibration. Forecasts reflect assumptions regarding mineral processing capacity expansion and poultry integration consolidation patterns. Revision becomes warranted when SENASA dossier requirements diverge further from MAPA provisional pathways or when Argentine formulation expertise collapse accelerates beyond pre-blended system substitution rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
India Anti Caking Market
Food Additives and Ingredients
Europe Leavening Agents Market
Food Additives and Ingredients
Filling Fat Market
Food Additives and Ingredients
China Monosodium Glutamate (MSG) Market
Food Additives and Ingredients
Lake Food Colors Market
Food Additives and Ingredients
Meat Tenderizing Agents Market
Food Additives and Ingredients
Potassium Propionate Market
Food Additives and Ingredients
Food Grade Glycerin Market
Food Additives and Ingredients
Food Supplement Ingredients Market
Food Additives and Ingredients
Natural Food Color Additives Market
Food Additives and Ingredients
United States Food Preservatives Market
Food Additives and Ingredients
Fish-Free Omega-3 Ingredients Market
Food Additives and Ingredients
Sustained Release Excipients Market
Food Additives and Ingredients
Beverages Additives Market
Food Additives and Ingredients
North America Food Coating Ingredients Market
Food Additives and Ingredients
Egypt Food Enzymes Market