
 United States Food Preservatives Market | 2026-2036
United States Food Preservatives Market Size, Share, and Industry Trends Forecast 2026-2036
United States Food Preservatives Market Analytics
Plant-based meat alternatives and extended-shelf-life dairy are recalibrating preservative demand across the United States. Cargill, Incorporated leverages its integrated fermentation infrastructure to supply propionates at scale for bakery clients. Kerry Group plc differentiates through clean-label vinegar-based preservation systems targeting natural-positioned brands. Kemin Industries, Inc. specializes in rosemary extract and buffered vinegar blends that occupy the premium natural preservative tier.
Food preservatives comprise chemical and natural substances added to food matrices at concentrations typically ranging from 0.05% to 0.3% by weight to inhibit microbial spoilage, oxidative rancidity, and enzymatic degradation. Sorbates dominate volume demand in dairy and beverage applications where pH conditions optimize potassium sorbate efficacy against yeast and mold. Propionates command structural importance in bakery supply chains due to their specific activity against rope-forming bacteria in bread matrices. Benzoates face formulation pressure in beverage applications as manufacturers navigate consumer preference shifts toward preservative-free positioning.
The FDA governs preservative safety through 21 CFR regulations and GRAS notification programs, while USDA FSIS oversees antimicrobial interventions in meat and poultry processing facilities. California's Proposition 65 warning requirements and New York's sodium reduction targets in processed foods create state-level compliance layers that shape regional formulation strategies. Stakeholders must monitor emerging FDA guidance on revised exposure assessments for traditional preservatives and evaluate natural alternative portfolios against cost-performance benchmarks.
Market Dynamics
Clean-label formulation mandates from major retailers are compressing synthetic preservative demand while accelerating natural alternative qualification cycles across US food manufacturing.
Growth Catalysts
- California Proposition 65 enforcement:Warning-label litigation against synthetic preservative users is pushing reformulation toward rosemary extract and buffered vinegar systems in snack and beverage categories.
- Extended-shelf-life dairy:Ultra-high-temperature processing adoption in fluid milk and plant-based alternatives is expanding potassium sorbate and natamycin demand for mold control in refrigerated distribution.
- Midwest meat processing clusters:Concentrated slaughter and further-processing capacity in Iowa, Nebraska, and Kansas drives bulk antimicrobial procurement for cured and ready-to-eat protein applications.
Market Restraints
- Propionic acid feedstock volatility:Petroleum-derived acetic acid and ethylene price swings compress propionate manufacturer margins and destabilize bakery sector contract pricing.
- China-dominant sorbic acid supply:Concentration of fermentation-grade sorbic acid production in Shandong Province creates import-dependency exposure for US potassium sorbate formulators.
- Benzoate beverage substitution:Aseptic packaging and cold-chain infrastructure investments enable preservative-free positioning in premium juice and ready-to-drink tea segments.
Strategic Opportunities
- Southeast baked goods expansion:Georgia and Tennessee production facility investments by national bread manufacturers create regional propionate blending and distribution hub demand.
- Fermentation-derived natural preservatives:Precision-fermentation platforms producing nisin and natamycin analogs offer label-friendly alternatives to synthetic antimicrobials in clean-positioned brands.
- USDA FSIS Listeria control mandates:Post-processing lethality requirements for deli meats and hot dogs drive antimicrobial intervention adoption in small and mid-sized ready-to-eat protein processors.
Industry Challenges
- Natural preservative efficacy validation:Shelf-life testing protocols for vinegar-based and plant-extract systems require 12-18 month qualification timelines that conflict with accelerated product launch cycles.
- GRAS self-determination liability:FDA notification withdrawal risks and class-action exposure around undisclosed preservative function claims elevate legal review costs for novel natural ingredient introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Food Preservatives Market |
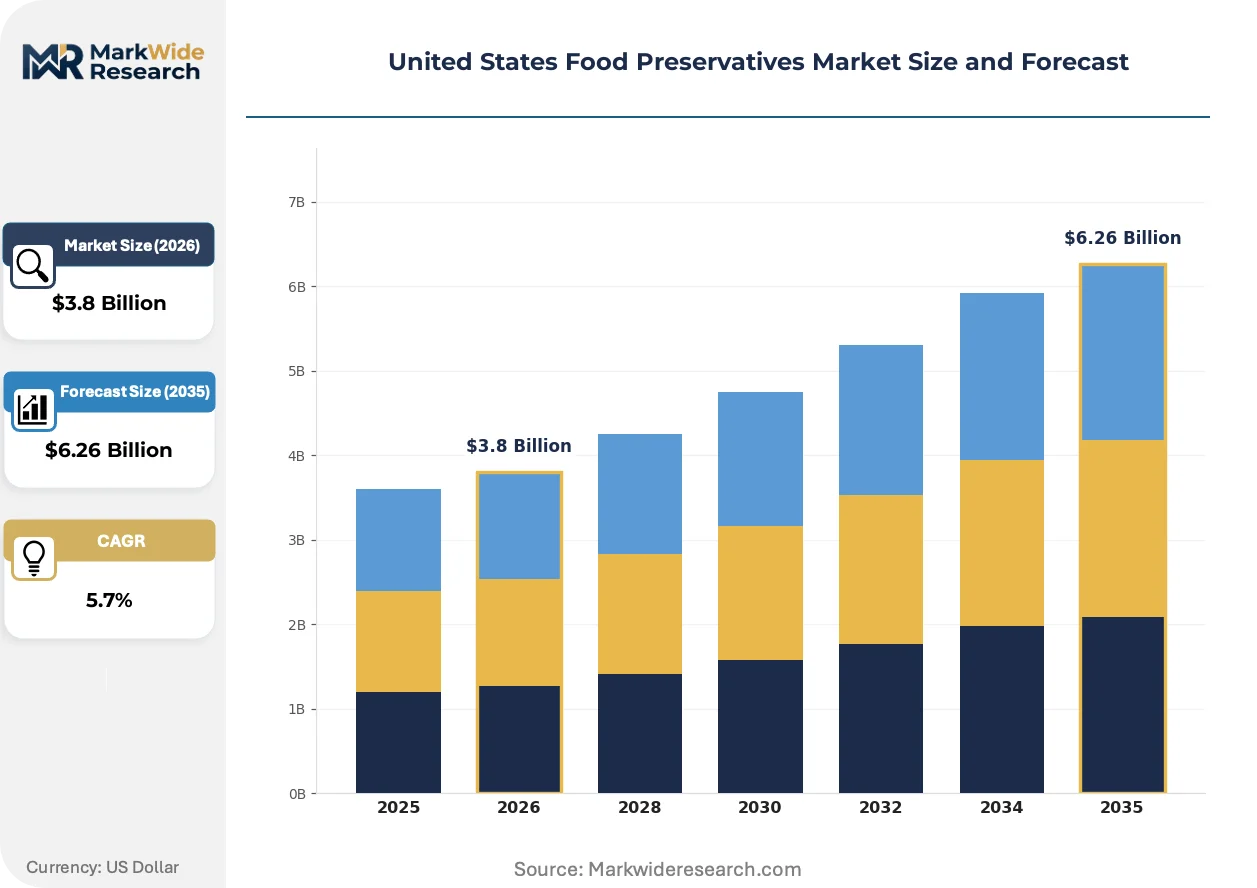
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sorbates, Benzoates, Nitrates, Propionates Application: Beverages, Meat Products, Dairy Products, Bakery Products End User: Food Manufacturers, Retail Chains, Restaurants, Food Service Providers Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Archer Daniels Midland Company, Cargill, Incorporated, Kerry Group plc, Kemin Industries, Inc., Koninklijke DSM N.V., BASF SE, Tate & Lyle, Corbion N.V., Celanese Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Food Preservatives Market Evolving Landscape
Active and intelligent packaging integration is redefining preservative deployment strategies, with controlled-release systems and oxygen-scavenging films reducing direct additive dependence in sensitive food matrices.
Fermentation-based biosynthetic production of natamycin and nisin is electrifying natural antimicrobial supply chains. Dairy and plant-based cheese manufacturers are adopting these precision-fermentation inputs at triple-digit annual procurement growth rates. This biotechnology transition is compressing traditional extraction-dependent natural preservative cost structures and enabling price parity with synthetic alternatives in mid-tier formulations.
FDA's updated GRAS exposure assessment methodology is tightening safety substantiation requirements for legacy preservatives. The revised guidance demands cumulative dietary exposure modeling across all food categories, elevating toxicological review costs for benzoate and sulfite suppliers. Beverage and condiment manufacturers are responding with accelerated clean-label transition roadmaps to preempt regulatory vulnerability.
Direct-procurement contracts between preservative suppliers and retail private-label programs are displacing traditional distributor-mediated purchasing in the natural and organic channel. Kroger, Whole Foods Market, and regional cooperative banners are consolidating supplier qualification and auditing functions internally. This consolidation is most visible in the Pacific Northwest and Northeast metropolitan corridors where private-label penetration in natural-positioned categories exceeds national averages.
United States Food Preservatives Market Segmentation
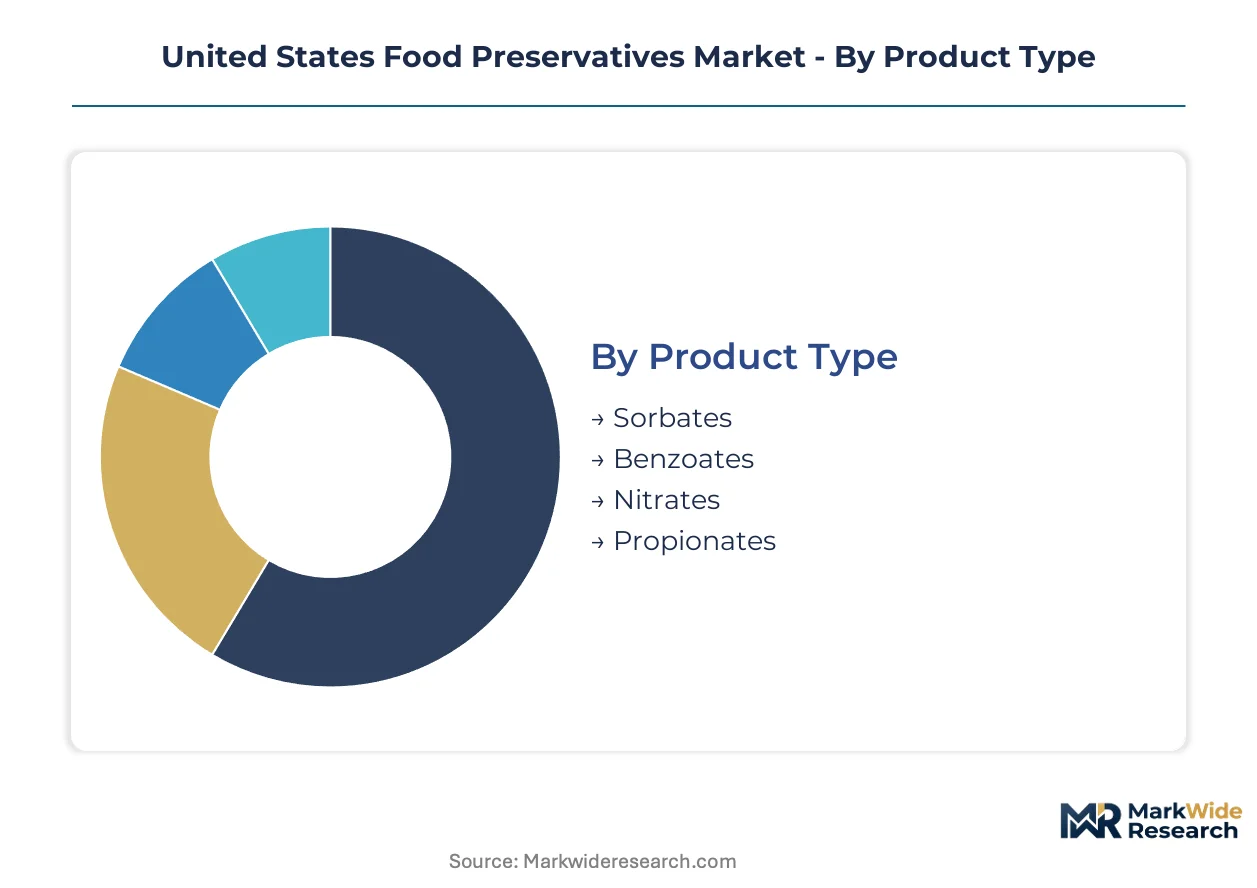
Food preservative procurement patterns diverge sharply across product chemistry, application matrix, and customer operational scale. Understanding these segment boundaries clarifies where formulation standardization yields economies of scale versus where customization commands premium positioning.
Product Type:
Standardization dominates commodity synthetics while natural-derived alternatives require bespoke specification negotiation with each manufacturing client.
- Sorbates:Potassium sorbate and calcium sorbate function as broad-spectrum yeast and mold inhibitors effective across pH ranges below 6.5. Demand concentrates in Midwest dairy processing corridors where extended-shelf-life fluid milk and plant-based cheese alternatives require post-pasteurization mold control. Potassium sorbate procurement volumes track directly with refrigerated distribution network expansion.
- Propionates:Sodium and calcium propionate salts deliver targeted suppression of rope-forming Bacillus species in bread matrices. Bakery manufacturing clusters in Georgia and Tennessee drive regional blending facility investments. Propionic acid feedstock volatility compresses contract pricing stability for national bread manufacturers.
- Benzoates:Sodium benzoate remains cost-effective for acidic beverage preservation below pH 4.5, though aseptic packaging substitution erodes volume in premium juice segments.
- Nitrates:Sodium nitrite and potassium nitrate serve essential antimicrobial and color-fixing functions in cured meat applications regulated by USDA FSIS residual limits.
Leading the category by volume: Sorbates. Growing fastest: Propionates.
Application:
Application-driven segmentation reveals divergent technical requirements between ambient-stable and refrigerated food matrices.
- Beverages:Acidic liquid matrices favor benzoate-sorbate blends, though cold-chain infrastructure investments enable preservative-free positioning in premium ready-to-drink tea. FDA GRAS exposure assessment revisions accelerate clean-label transition timelines.
- Meat Products:Cured, smoked, and ready-to-eat protein applications combine nitrate-based color stabilization with lactate-diacetate antimicrobial interventions. Iowa and Nebraska processing clusters drive bulk antimicrobial procurement for deli meat and hot dog applications.
- Dairy Products:Fluid milk, cheese, and plant-based alternatives deploy potassium sorbate and natamycin against post-process mold contamination. Ultra-high-temperature processing adoption expands preservative demand for ambient-stable creamers.
- Bakery Products:Sliced bread, tortillas, and sweet goods rely on propionate-based rope bacteria control. Clean-label vinegar-based alternatives gain traction in natural-positioned artisan segments.
Volume concentration: Meat Products. Steepest expansion trajectory: Dairy Products.
End User:
End-user scale determines procurement channel preference and technical service intensity.
- Food Manufacturers:National and regional processors specify preservative blends through direct supplier contracts with integrated fermentation houses. Technical service teams co-develop shelf-life protocols for reformulation projects.
- Retail Chains:Private-label programs consolidate supplier qualification functions internally, displacing traditional distributor relationships in natural and organic channels.
- Restaurants:Limited-service and fast-casual operators prioritize cost-minimization in bulk sauce and dressing procurement.
- Food Service Providers:Institutional and contract catering distributors manage preservative specification through broadline procurement contracts.
Dominant procurement scale: Food Manufacturers. Fastest channel growth: Retail Chains.
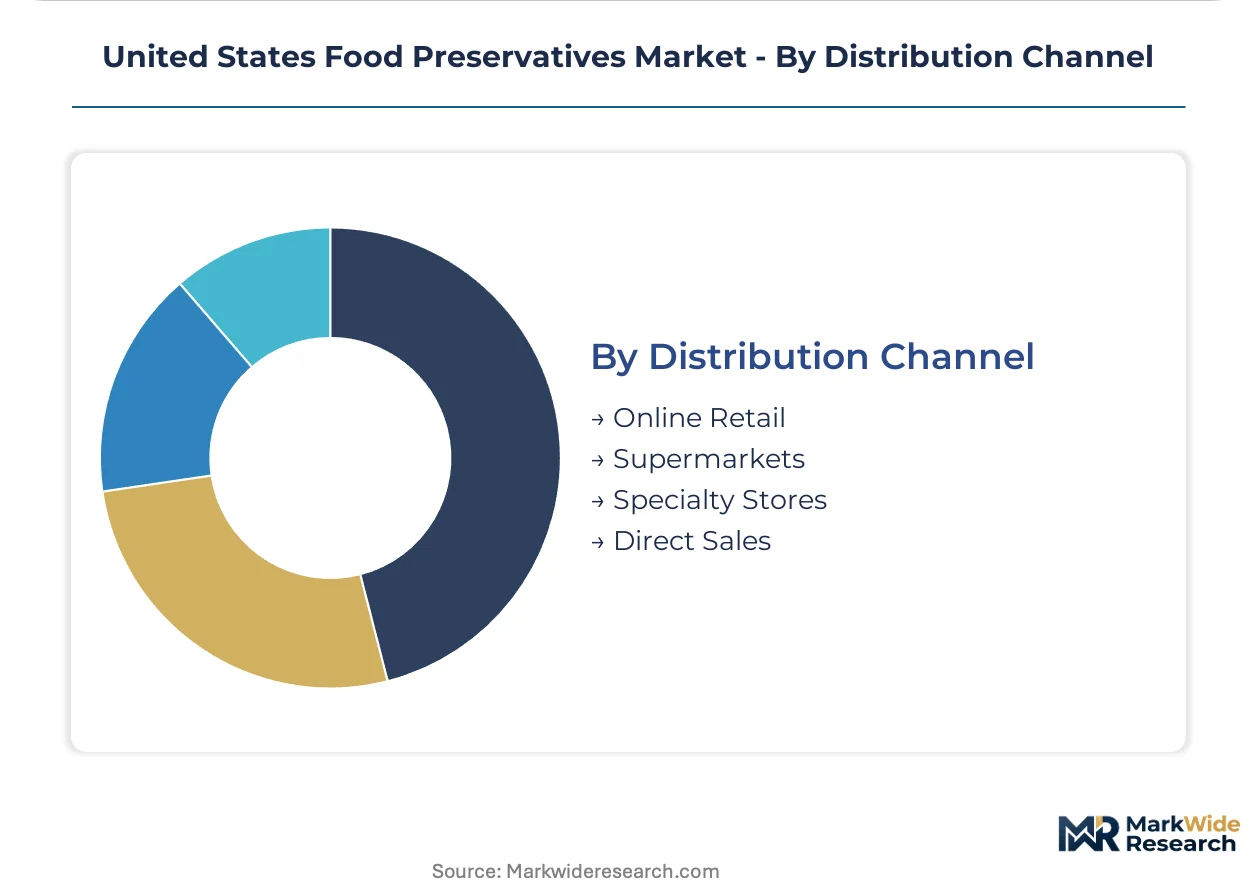
Distribution Channel:
Channel structure reflects customer scale, geographic concentration, and technical support requirements.
- Direct Sales:Large-volume food manufacturers negotiate multi-year supply agreements with integrated propionate and sorbate producers. Cargill and Kerry Group field technical service teams for co-development partnerships.
- Online Retail:Small-batch and artisan food producers source natural preservative blends through specialty ingredient marketplaces with rapid fulfillment.
- Supermarkets:Limited preservative SKUs target home preservers and small commercial kitchens.
- Specialty Stores:Natural and organic channel distributors curate clean-label vinegar and rosemary extract portfolios for reformulation projects.
Primary volume channel: Direct Sales. Fastest digital growth: Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Opportunity Zones in Georgia and Tennessee concentrate new bakery manufacturing investment, drawing propionate blending capacity toward the Southeast. State-level sodium reduction mandates in California and New York reshape preservative formulation requirements across coastal markets. Midwest meat processing corridors anchor bulk antimicrobial demand for cured and ready-to-eat protein applications.
California
Proposition 65 warning-label litigation accelerates reformulation toward rosemary extract and buffered vinegar systems in snack and beverage categories. The state's Office of Environmental Health Hazard Assessment maintains active enforcement against synthetic preservative users in processed foods. Los Angeles and San Francisco metropolitan areas concentrate clean-label brand headquarters and natural channel distribution infrastructure.
Midwest Corridor
Iowa, Nebraska, and Kansas slaughter and further-processing capacity drives bulk antimicrobial procurement for cured meat and hot dog applications. USDA FSIS post-processing lethality mandates elevate adoption of lactate-diacetate interventions in small and mid-sized ready-to-eat protein processors. Omaha and Des Moines processing clusters negotiate multi-year supply agreements with integrated fermentation houses for nitrate and antimicrobial blends.
Southeast
Georgia and Tennessee bread manufacturing facility investments create regional propionate blending and distribution hub demand. Tennessee's Jobs4TN incentive program supports food manufacturing expansion in the Nashville and Chattanooga corridors. Atlanta anchors national bread manufacturer headquarters and technical service co-development partnerships with preservative suppliers.
New York
State sodium reduction targets in processed foods compel reformulation of cured meat and cheese applications away from traditional salt-based preservation. The Department of Health's voluntary sodium benchmarks pressure manufacturers to qualify alternative antimicrobial systems. Buffalo and Rochester dairy processing clusters expand potassium sorbate and natamycin demand for extended-shelf-life fluid milk distribution.
Pacific Northwest
Private-label penetration in natural-positioned categories exceeds national averages, consolidating supplier qualification functions within retail banners. Oregon and Washington clean-label brand density accelerates vinegar-based and fermentation-derived natural preservative procurement. Seattle and Portland metropolitan areas concentrate direct-procurement contracts between preservative suppliers and retail cooperative programs.
United States Food Preservatives Market Competitive Landscape
Top-tier vendors anchor integrated fermentation infrastructure, while mid-scale specialists occupy clean-label natural preservation niches. The market exhibits tiered concentration with commodity synthetic suppliers facing margin compression from petroleum feedstock volatility. Three archetypes dominate: integrated fermentation houses supplying propionates and sorbates at scale; clean-label specialists commercializing vinegar and plant-extract systems; and precision-fermentation platforms producing biosynthetic natamycin analogs. Competitive moves center on backward integration into fermentation capacity and strategic partnerships with retail private-label programs.
Within the integrated fermentation tier, Cargill, Incorporated and Kerry Group plc represent scale-driven supply archetypes. Kerry Group plc exemplifies the clean-label transition specialist, while Kemin Industries, Inc. occupies a position in the premium natural preservative segment. These three entities anchor the competitive structure, with Cargill leveraging captive supply of propionic acid feedstocks, Kerry Group plc representing the technical service-intensive co-development model, and Kemin Industries, Inc. sitting within the botanical extraction and buffered vinegar formulation niche.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Cargill, Incorporated |
| Kerry Group plc |
| Kemin Industries, Inc. |
| Koninklijke DSM N.V. |
| BASF SE |
| Tate & Lyle |
| Corbion N.V. |
| Celanese Corporation |
| Others |
Value Network & Pricing Analysis
California's Proposition 65 warning-label mandates gate qualified supply for preservative suppliers serving West Coast food manufacturers, with compliance certification becoming the threshold for premium-tier pricing access in natural-positioned retail channels.
Pricing Analysis
Lead-time-driven pricing stratification rewards rapid fulfillment: synthetic propionate and sorbate buyers pay premiums for 48-hour turnaround from Midwest blending facilities, while spot inventory of fermentation-derived natural alternatives trades at discounts due to shelf-life limitations. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale, with FDA GRAS notification status commanding substantial markups. Pricing pressure stems from petroleum-derived acetic acid feedstock volatility compressing propionate margins. National bread manufacturers exhibit lowest price sensitivity due to contract security needs, while small-batch artisan producers demonstrate highest sensitivity to per-kilogram differentials.
Supply Chain Analysis
Domestic-content preferences embedded in USDA FSIS procurement guidelines and retailer supplier qualification programs are reshaping sourcing toward North American fermentation capacity. Geographic supply concentrates in China for fermentation-grade sorbic acid, the United States for propionic acid derivatives, and India for botanical extract precursors. Raw material dependencies encompass petroleum-derived ethylene, corn-derived dextrose feedstocks, and Shandong Province-sourced sorbic acid intermediates. Single-source vulnerability from China-dominant sorbic acid production creates tariff exposure and logistics chokepoint risk. Distribution runs through direct sales contracts with integrated fermentation houses for national food manufacturers, supplemented by specialty ingredient distributors serving regional processors and natural channel retailers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
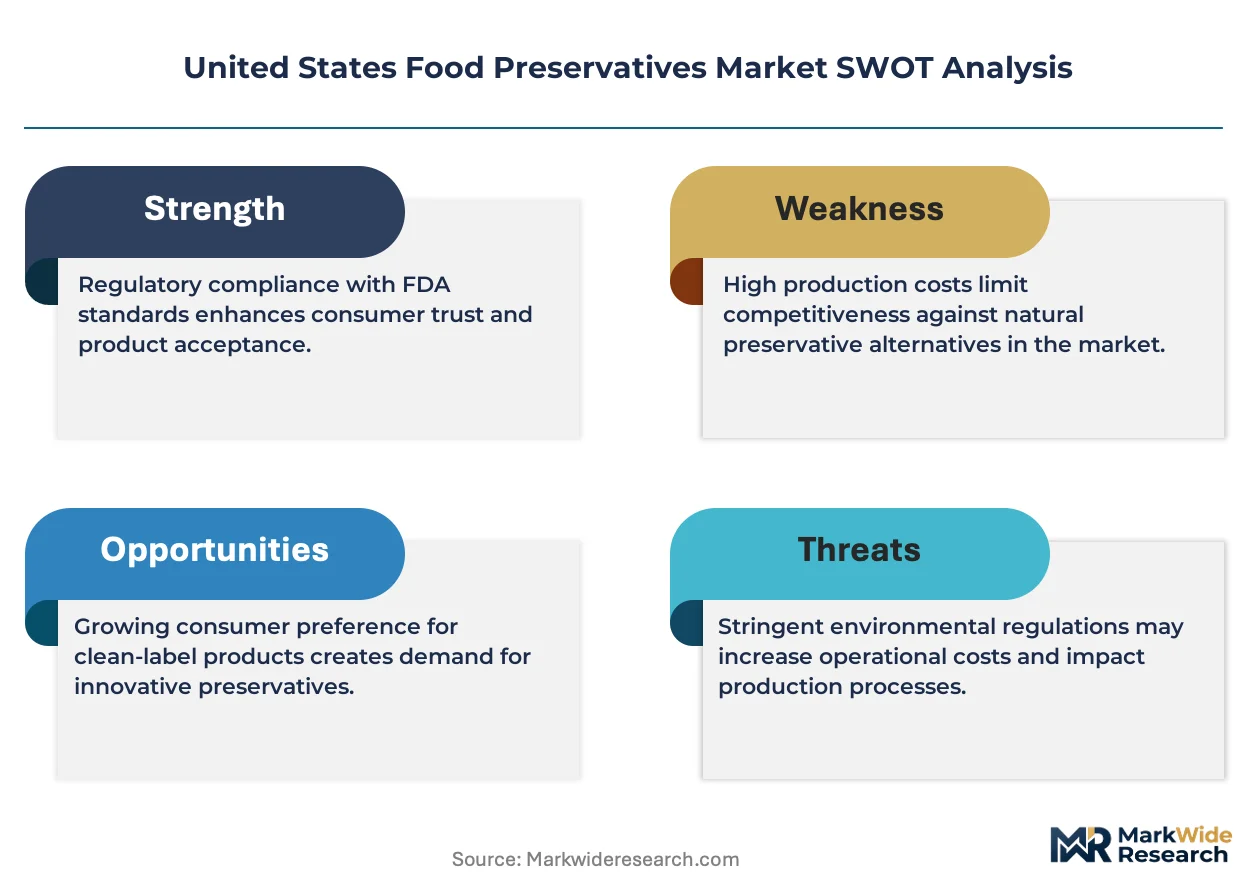
This market functions as a cost-of-compliance story where FDA's revised GRAS exposure assessment methodology erects a barrier-to-entry moat favoring incumbents with established toxicological review infrastructure and notification track records.
For Market Incumbents: Anchor defensive positioning through backward integration into propionic acid fermentation capacity in Iowa and Nebraska corridor, securing captive supply against petroleum feedstock volatility. Invest in precision-fermentation platforms for biosynthetic natamycin production to preempt emerging biotechnology entrants. Prioritize certification maintenance for California Proposition 65 compliance to defend premium-channel access against reformulation service competitors.
For New Entrants and Emerging Players: The price-point gap between premium rosemary extract systems and economy synthetic benzoates creates entry space for mid-tier buffered vinegar blends targeting Southeast bakery expansion. Target Georgia and Tennessee regional bread manufacturers with technical service-intensive co-development partnerships as the most penetrable segment. Pursue direct-procurement relationships with retail private-label programs in Pacific Northwest cooperative banners as the primary go-to-market angle.
For Investors and Strategic Acquirers: FDA notification withdrawal petitions against legacy preservatives are the leading indicator that clean-label transition timelines are compressing, signaling accelerated M&A windows for natural preservative specialists. Frame long-term viability around fermentation-derived biosynthetic production platforms achieving cost parity with synthetics. Target acquisition archetypes of precision-fermentation startups with validated nisin or natamycin analog production. Monitor California Office of Environmental Health Hazard Assessment enforcement actions as the critical inflection signal for synthetic preservative demand erosion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Capacity | Cargill's captive propionic acid supply secures margin stability against petroleum feedstock swings. |
| Precision-Fermentation Platform Development | Biosynthetic natamycin production enables price parity with synthetic alternatives in mid-tier dairy formulations. |
| Direct Procurement Partnership with Retail Chains | Kroger's consolidated supplier qualification displaces distributor intermediaries in natural channel preservative sourcing. |
| Clean-Label Technical Service Co-Development | Kerry Group's vinegar-based preservation systems command premium positioning through formulation partnership depth. |
| Regional Blending Hub Expansion | Southeast propionate facility investments align with Georgia and Tennessee bread manufacturing cluster growth. |
Research Methodology
Independent corroboration across FDA GRAS notification databases, USDA FSIS regulatory filings, and state-level environmental health enforcement records underwrites the qualitative findings in this study. Primary interviews with food manufacturing R&D directors, retail private-label program managers, fermentation plant operations heads, and specialty ingredient distribution channel partners combined with secondary validation from SEC 10-K disclosures, customs import records, and American Bakers Association technical bulletins. Bottom-up volume triangulation from application-specific consumption rates and top-down value reconciliation from producer revenue disclosures anchored the analytical framework.
Rate-of-change decomposition across the analysis window segmented volume and value trajectories by product chemistry, application matrix, end-user operational scale, and regional regulatory cluster intensity. Modeled dimensions encompassed synthetic versus natural preservative chemistry tiers, meat-dairy-bakery-beverage application splits, national processor versus regional artisan customer scale, and California-Midwest-Southeast-New York regulatory framework differentiation. CAGRs derived from weighted average of historical trajectory elasticity and forward-looking policy impact assessment, with fermentation capacity expansion timelines and retail private-label penetration curves as key industry-specific forecast inputs.
Inputs from FDA guidance document releases and state enforcement action databases were available through the study window; gaps in real-time proprietary formulation data from confidential supplier-manufacturer contracts introduce uncertainty bands around natural preservative substitution rate assumptions. Forecasts reflect documented regulatory trajectory assumptions with revision risk from accelerated GRAS exposure assessment implementation or unforeseen Proposition 65 chemical listing actions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Microencapsulated Food Ingredient Market
Food Additives and Ingredients
North America Fermented Ingredient Market
Food Additives and Ingredients
North America Dehydrated Onion Market
Food Additives and Ingredients
Sugar Reduction Technology Market
Food Additives and Ingredients
Food Encapsulation Market
Food Additives and Ingredients
Pyranose Oxidase Market
Food Additives and Ingredients
Mexico Food Acidulants Market
Food Additives and Ingredients
Anti-Caking Agents Market
Food Additives and Ingredients
India Anti Caking Market
Food Additives and Ingredients
India Food Enzymes Market
Food Additives and Ingredients
Food Protein Ingredient Market
Food Additives and Ingredients
Mexico Food Enzymes Market
Food Additives and Ingredients
Wheat & Rice Flour Substitute-Resistant Starch Market
Food Additives and Ingredients
Food Texturing Agents Market
Food Additives and Ingredients
United Kingdom Food Preservatives Market
Food Additives and Ingredients
Powdered Fats Market