
 Lake Food Colors Market | 2026-2036
Lake Food Colors Market Size, Share, and Industry Trends Forecast 2026-2036
Lake Food Colors Market Analytics
Asset-light toll manufacturing and third-party blending arrangements is reconfiguring competitive entry barriers in lake food colors, allowing regional specialists to scale without captive pigment synthesis. Sensient Technologies Corporation leverages backward integration into botanical extraction to secure supply continuity for natural lake lines. DDW anchors its position through proprietary encapsulation technologies that improve light stability in confectionery applications. Alliance Organics LLP competes on custom blend agility, serving mid-tier bakery and dairy accounts with rapid turnaround formulations.
Lake food colors are insoluble pigment complexes produced by precipitating water-soluble dyes onto aluminum hydrate substrates, yielding particles with controlled particle size distributions and oil-dispersible properties essential for fat-based food matrices. The natural colors segment leads volume as reformulation mandates from North American and European retailers push manufacturers away from azo-based synthetics. Synthetic colors retain margin concentration in emerging-market confectionery where cost sensitivity dominates and regulatory thresholds remain permissive. Powder form dominates industrial procurement due to extended shelf stability and lower freight costs, though liquid dispersions gain traction in automated beverage dosing systems.
FDA color additive regulations under 21 CFR 73 and 74 govern batch certification requirements for synthetic lakes in the United States, while EFSA re-evaluations of aluminum-containing pigments under the EU food improvement agent framework are elevating compliance costs for European suppliers. India's FSSAI notification on maximum permissible synthetic colors in sweets and savories is tightening enforcement at state-level manufacturing clusters, redirecting domestic demand toward BIS-certified natural alternatives. Stakeholders must monitor evolving maximum residue limits for heavy metal contaminants and invest in dual-certification capacity to maintain access across divergent regulatory zones.
Market Dynamics
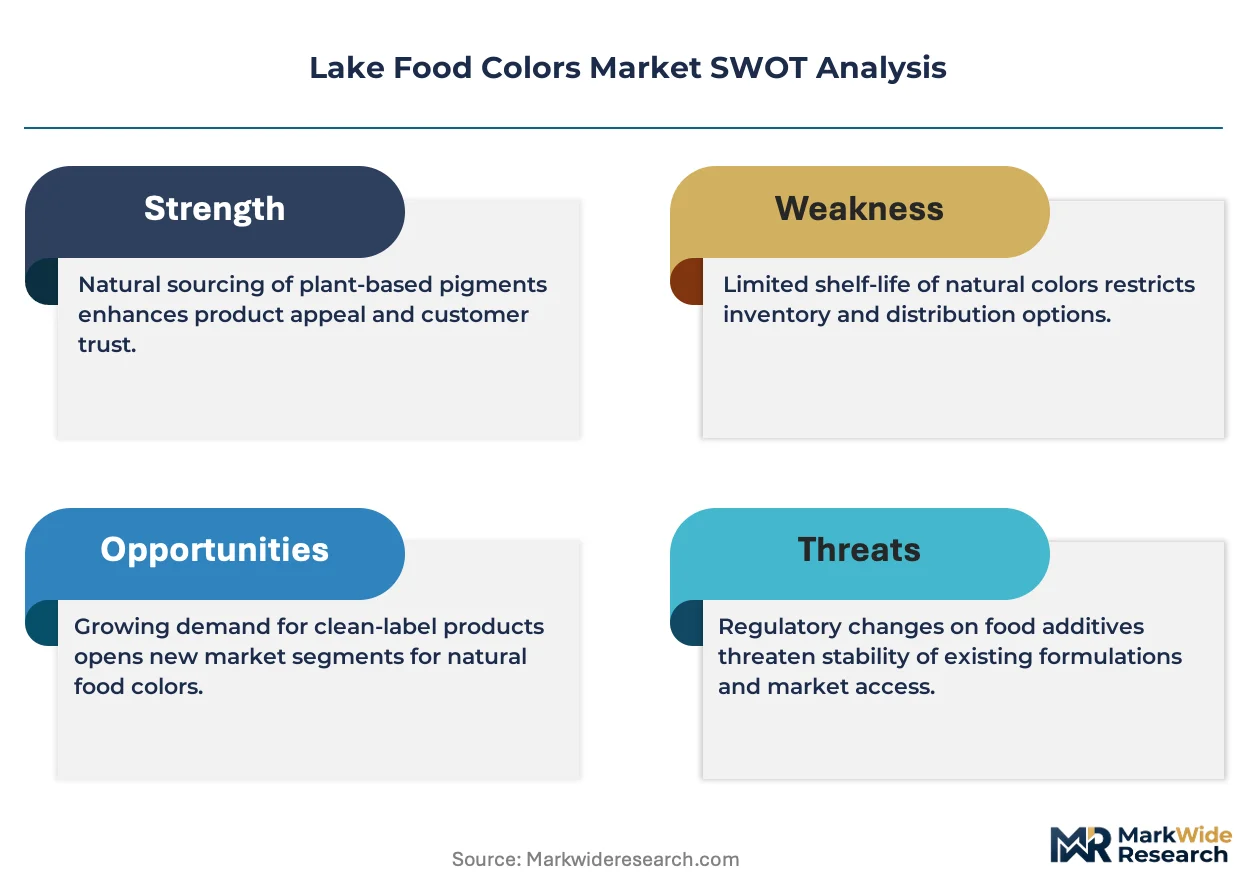
Clean-label reformulation mandates from major retailers and tightening aluminum-based pigment scrutiny by EFSA are forcing lake color suppliers to reconfigure extraction and precipitation processes. This regulatory compression is accelerating capital deployment toward botanical sourcing infrastructure and dual-certification manufacturing lines.
Growth Catalysts
- EFSA Aluminum Re-evaluation:The EU food improvement agent framework is elevating compliance costs for synthetic lakes, redirecting formulation budgets toward certified natural alternatives in German and French confectionery clusters.
- Confectionery Export Hubs:Large-scale food processing clusters in India and the United States are generating concentrated procurement volumes for certified color suppliers serving panned candy and coated chocolate production.
- Encapsulation Technology:Proprietary microencapsulation methods are improving light stability in fat-based matrices, enabling natural lake pigments to match synthetic performance in high-exposure retail environments.
Market Restraints
- Aluminum Substrate Volatility:Input cost fluctuations for aluminum hydrate precursors are compressing margins for precipitation-based lake production, particularly affecting mid-tier suppliers without long-term chemical supply contracts.
- Extraction Concentration:Botanical raw material sourcing concentrates in specific climatic zones, creating geographic supply vulnerability for natural lake lines dependent on seasonal harvest cycles.
- Batch Certification Bottlenecks:FDA 21 CFR 74 certification timelines for new synthetic lake variants extend 18-24 months, delaying product launches and freezing formulation innovation in U.S.-bound applications.
Strategic Opportunities
- Indian Natural Color Transition:FSSAI enforcement tightening on synthetic dye limits in sweets and savories is redirecting domestic demand toward BIS-certified natural lake alternatives in Maharashtra and Gujarat processing clusters.
- Liquid Dispersion Automation:Automated beverage dosing systems are creating new demand for liquid lake dispersions, opening channel access beyond traditional powder procurement relationships.
- Dual-Certification Capacity:Investment in simultaneous FDA-EFSA compliant production lines enables suppliers to capture cross-Atlantic procurement consolidation among multinational confectionery accounts.
Industry Challenges
- Natural Pigment Stability Expertise:Shortage of formulation chemists experienced in botanical lake stabilization is slowing clean-label product development cycles and extending client onboarding timelines.
- Heavy Metal Testing Infrastructure:CapEx requirements for in-house ICP-MS heavy metal screening to meet evolving maximum residue limits are straining regional specialist balance sheets.
- Legacy Dye Integration:Reformulation of established product lines requires precise particle size matching between synthetic and natural lakes to maintain visual consistency without process revalidation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lake Food Colors Market |
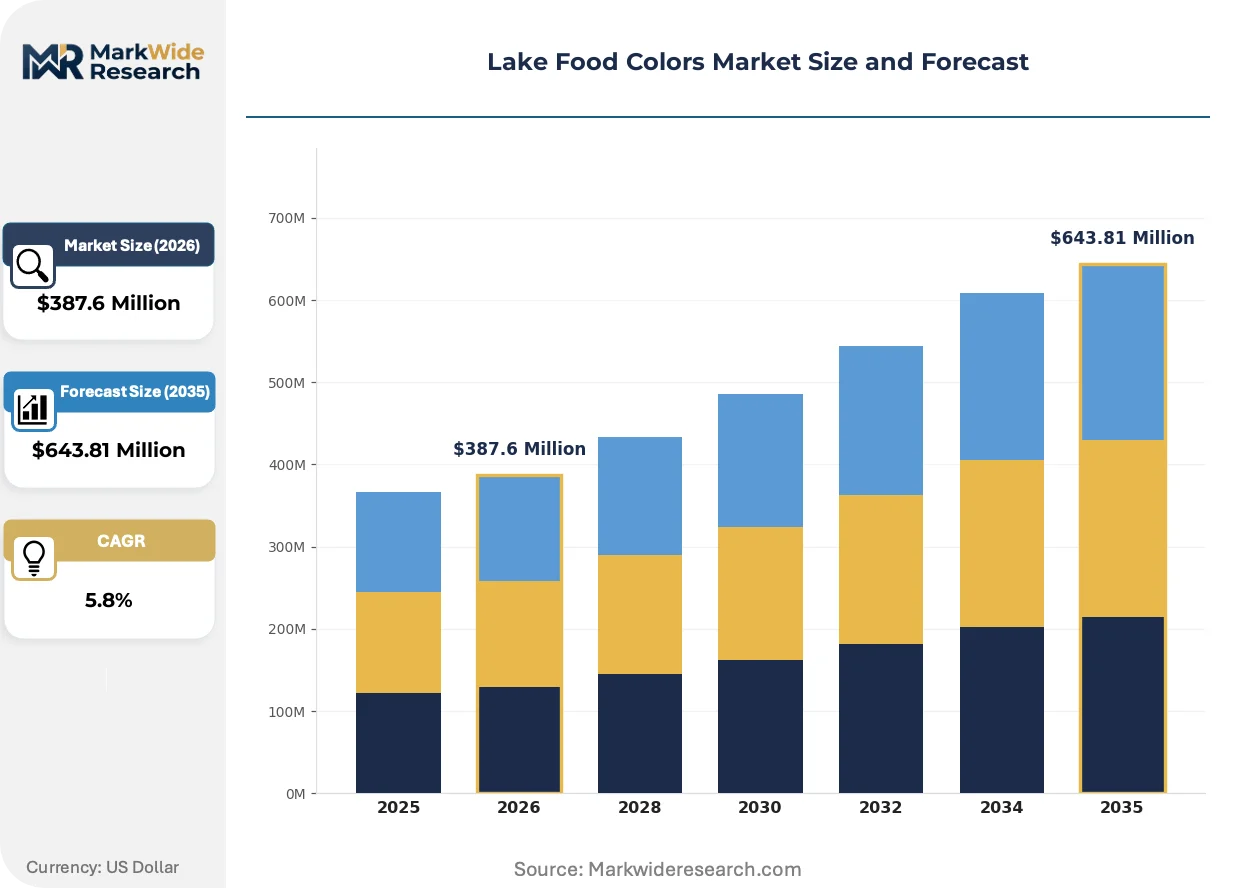
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $643.81 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Colors, Synthetic Colors, Organic Colors, Custom Blends Application: Bakery, Confectionery, Dairy Products, Beverages End User: Food Manufacturers, Beverage Producers, Retail Chains, Catering Services Form: Powder, Liquid, Gel, Granule |
| Companies Covered | Sensient Technologies Corporation, DDW, Alliance Organics LLP, NACTAROME S.P.A., LycoRed, Kalsec Inc., Horizon Specialities Ltd., BIOCONCOLORS, Sunfoodtech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lake Food Colors Market Evolving Landscape
Digital formulation platforms and AI-driven color matching are compressing development cycles for custom lake blends. These tools are enabling regional specialists to compete with integrated majors on specification agility.
Computational pigment formulation is virtualizing traditional laboratory trial-and-error methods. Mid-tier bakery and dairy manufacturers are adopting cloud-based color prediction tools to reduce sample iteration counts. This technology is virtualizing the specification relationship between buyers and suppliers, compressing the competitive advantage of legacy technical service teams.
REACH authorization requirements for aluminum-containing substances are expanding disclosure obligations across EU supply chains. The industrial consequence is accelerated substitution investment by pan-European confectionery groups. Natural lake lines with EFSA-approved carrier systems are capturing reformulation budgets previously allocated to certified synthetic alternatives.
Retailer-driven certification requirements are restructuring procurement evaluation criteria. Clean-label mandates from North American grocery chains are displacing cost-per-kilogram sourcing models with total-compliance-cost frameworks. This shift is most visible in United States private-label confectionery, where dual-certified natural lakes command specification preference despite unit price premiums.
Lake Food Colors Market Segmentation
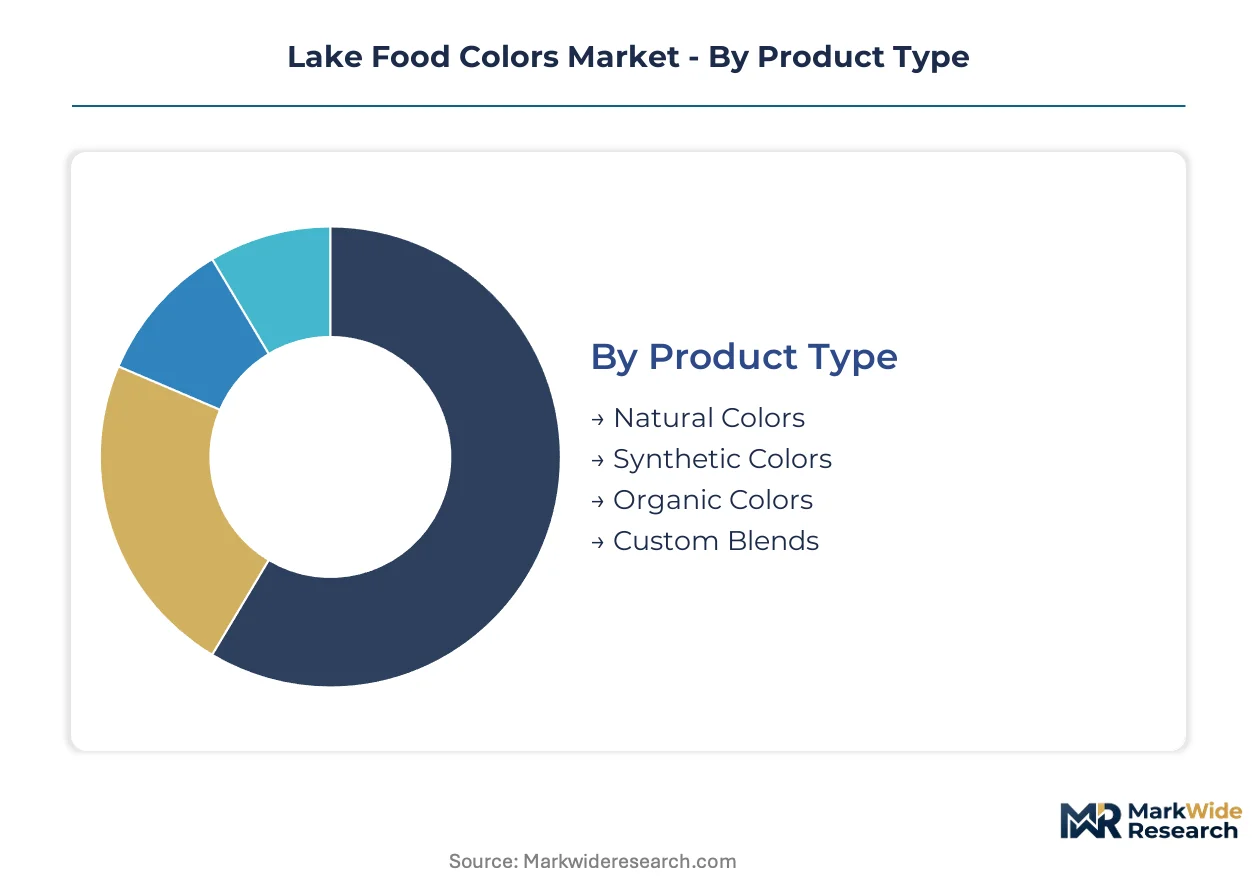
Lake food colors serve radically different performance requirements across fat-based confectionery, water-based beverages, and neutral-pH dairy matrices. Segmentation reveals how precipitation chemistry, dispersion physics, and regulatory certification create distinct procurement criteria for each application cluster.
Product Type:
Use-case spectrum spans certified synthetic lakes for cost-sensitive emerging-market confectionery to botanical-derived natural lakes commanding premium positioning in clean-label North American and European retail.
- Natural Colors:Botanical extracts precipitated onto aluminum hydrate substrates deliver oil-dispersible pigments with EFSA and FDA certification pathways. Demand concentrates in United States and German private-label confectionery where retailer mandates exclude azo-based synthetics.
- Synthetic Colors:Certified FD&C and EU-listed dyes precipitated as insoluble complexes provide maximum tinctorial strength and batch-to-batch consistency. Procurement concentrates in Indian and Brazilian export-oriented candy production where cost-per-kilogram dominates specification decisions.
- Organic Colors:USDA and EU organic-certified lake lines meet 95%+ organic formulation requirements in premium chocolate and artisan bakery segments.
- Custom Blends:Proprietary pigment combinations matched to specific fat-content matrices and process temperature profiles serve mid-tier dairy and bakery accounts requiring rapid reformulation support.
The dominant share belongs to Natural Colors, while Custom Blends are closing the gap fastest as regional specialists leverage digital color-matching platforms to compress development timelines.
Application:
Cost tier stratification separates commodity-scale beverage dosing from precision confectionery coating where particle size distribution directly impacts surface finish quality.
- Confectionery:Panned candy and chocolate coating applications demand narrow particle size distributions for uniform surface coverage without streaking. United States and Indian export hubs generate concentrated procurement volumes for certified lake suppliers.
- Bakery:Heat-stable lake pigments withstand proofing and baking temperatures while maintaining color integrity in fondants, icings, and filled products. German and French industrial bakery clusters drive specification innovation for natural alternatives.
- Dairy Products:pH-sensitive lake formulations prevent color migration in yogurt coatings and processed cheese applications.
- Beverages:Automated dosing systems favor liquid lake dispersions over traditional powder forms, opening new channel relationships beyond industrial procurement.
Volume concentration sits with Confectionery, though Beverages are expanding most quickly as liquid dispersion technology penetrates carbonated soft drink and functional beverage production lines.
End User:
Customer type determines whether procurement prioritizes technical service intensity, certification documentation depth, or logistics integration with just-in-time manufacturing schedules.
- Food Manufacturers:Integrated confectionery and bakery operations with captive R&D facilities demand dual-certified natural lakes and custom formulation support. Maharashtra and Gujarat processing clusters in India represent high-volume accounts transitioning from synthetic to natural lines under FSSAI enforcement.
- Beverage Producers:Automated production lines require liquid dispersion formats with validated dosing accuracy and extended ambient stability.
- Retail Chains:Private-label specification power is displacing traditional supplier relationships with total-compliance-cost frameworks prioritizing clean-label certification over unit pricing.
- Catering Services:Small-batch procurement favors powder formats with extended shelf stability and minimal minimum order quantities.
Procurement scale concentrates with Food Manufacturers, while Retail Chains are gaining specification influence fastest through mandated certification requirements.
Form:
Supply concentration reflects freight economics and shelf stability requirements, with powder dominating long-distance procurement and liquid formats capturing automated manufacturing integration.
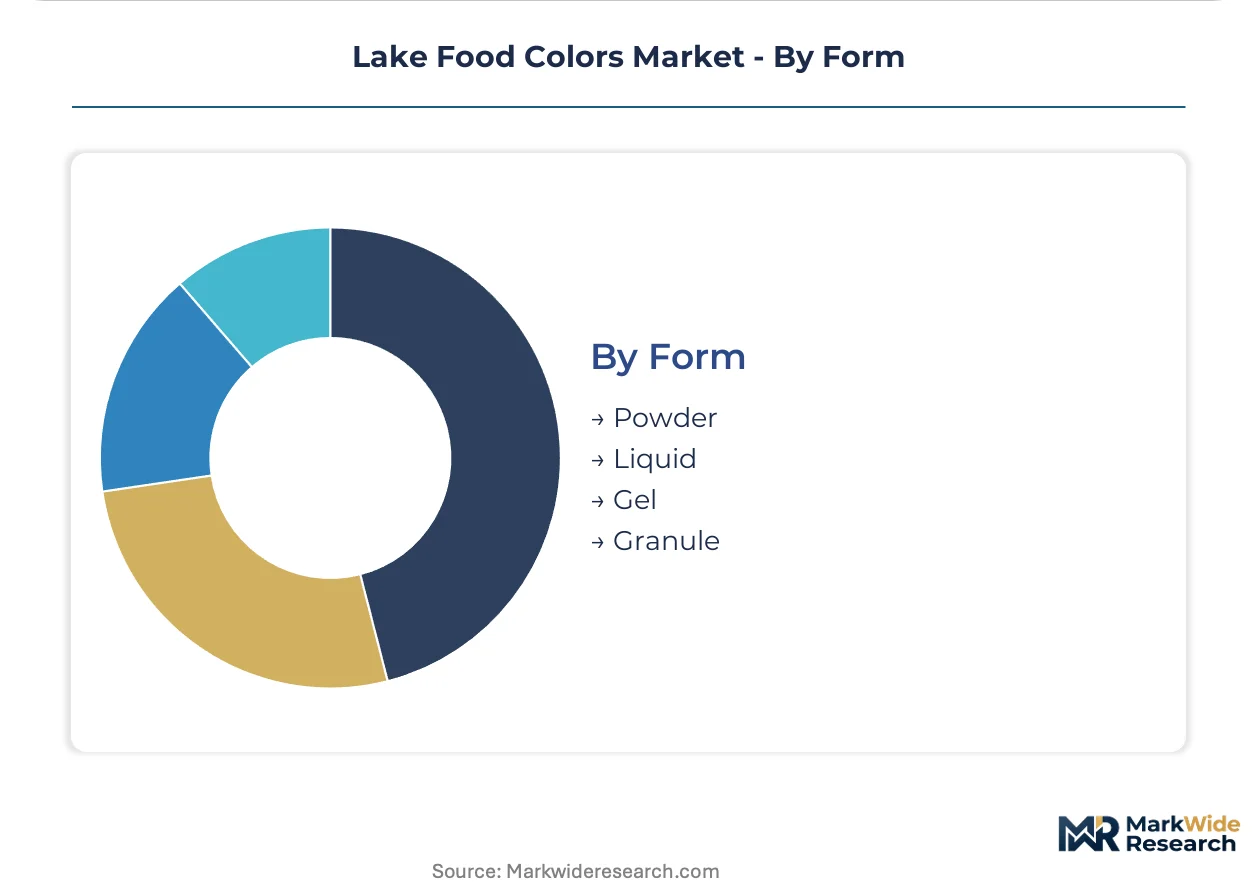
- Powder:Extended shelf stability and lower freight costs make this the default for industrial procurement across all geographies. German and United States confectionery clusters maintain large powder inventories with validated aluminum hydrate substrate specifications.
- Liquid:Pre-dispersed lake concentrates eliminate dust exposure and enable precision dosing in high-speed beverage filling lines. Adoption concentrates in automated North American and Western European manufacturing facilities.
- Gel:High-viscosity formats serve artisan bakery and small-batch confectionery requiring manual incorporation without specialized dispersion equipment.
- Granule:Low-dust handling properties address occupational safety requirements in high-volume powder processing environments.
Procurement volume belongs to Powder, while Liquid is climbing the fastest as beverage automation investments accelerate across United States and European manufacturing footprints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German and United States confectionery clusters where retailer-driven clean-label mandates command premium positioning, while Indian and Brazilian export hubs compete on volume scale with thinner margin structures.
United States
Private-label confectionery procurement from Walmart and Kroger enforces dual-certified natural lake specifications. FDA 21 CFR 73 and 74 batch certification timelines extend 18-24 months for new synthetic variants. Chicago and New Jersey processing corridors host concentrated panned candy and chocolate coating operations transitioning from azo-based synthetics.
Germany
Industrial bakery clusters in Bavaria and North Rhine-Westphalia drive specification innovation for heat-stable natural alternatives. EFSA re-evaluations of aluminum-containing pigments under the EU food improvement agent framework elevate compliance costs. Stuttgart and Hamburg harbor specialized lake pigment distributors serving pan-European reformulation mandates.
India
Maharashtra and Gujarat confectionery export hubs generate concentrated procurement volumes for certified color suppliers. FSSAI notification on maximum permissible synthetic colors in sweets and savories tightens enforcement at state-level manufacturing clusters. Mumbai and Ahmedabad processing facilities redirect domestic demand toward BIS-certified natural lake alternatives.
Brazil
Cost-sensitive candy production for Latin American and African export markets sustains demand for certified synthetic lakes. ANVISA color additive regulations maintain permissive thresholds relative to FDA and EFSA standards. São Paulo state industrial corridors concentrate toll manufacturing and third-party blending arrangements for regional confectionery accounts.
China
Yangtze River Delta food processing clusters integrate lake pigments into coated snack and chocolate production for domestic and Southeast Asian markets. SAMR and GB standards govern food additive safety assessments with accelerating alignment toward international certification benchmarks. Shanghai and Suzhou manufacturing zones attract multinational confectionery joint ventures requiring dual-source pigment supply security.
Lake Food Colors Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with formulation agility and regional certification expertise. The vendor base stratifies across three tiers: multinational pigment houses with captive botanical extraction, mid-scale regional blenders with custom formulation platforms, and commodity-scale precipitators serving emerging-market cost floors. Strategic archetypes include backward-integrated natural extractors, encapsulation technology licensors, and toll-manufacturing aggregators. Competitive moves center on dual-certification capacity investments and digital color-matching platform deployment.
Within the backward-integrated tier, Sensient Technologies Corporation exemplifies upstream control over botanical sourcing infrastructure. DDW occupies a position anchored in proprietary encapsulation methods for light-stability performance. Alliance Organics LLP represents the custom-blend agility archetype, serving mid-tier accounts with rapid-turnaround specification support.
| Leading Market Players |
|---|
| Sensient Technologies Corporation |
| DDW |
| Alliance Organics LLP |
| NACTAROME S.P.A. |
| LycoRed |
| Kalsec Inc. |
| Horizon Specialities Ltd. |
| BIOCONCOLORS |
| Sunfoodtech |
| Others |
Value Network & Pricing Analysis
Aluminum hydrate precursor volatility determines both pricing tier spreads and supply chain configuration across lake pigment production. Input cost fluctuations compress margins for precipitation-based manufacturers while redirecting procurement budgets toward backward-integrated suppliers with captive chemical supply.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the lake food colors market. Premium natural lakes with dual FDA-EFSA certification command substantial premiums over uncertified synthetic alternatives, while price differentiation hinges on certification grade and volume scale. Cost compression in economy-tier synthetic lakes is intensifying because Brazilian and Indian export confectionery buyers prioritize unit economics over compliance documentation. Emerging-market food manufacturers exhibit highest price sensitivity; North American private-label retail chains show lowest sensitivity due to mandated clean-label specifications.
Supply Chain Analysis
Tariff exposure between China and Western confectionery markets dominates supply chain risk planning for aluminum-containing pigment substrates. Botanical raw material sourcing concentrates in India, Peru, and Morocco, while synthetic dye precursor production rests on Chinese and German chemical manufacturing. Single-source vulnerability in aluminum hydrate supply creates concentration risk for mid-tier precipitators without long-term offtake agreements. Distribution runs through specialized pigment distributors in Stuttgart and Hamburg serving pan-European reformulation demand, alongside direct procurement relationships with Maharashtra and Gujarat processing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face sustained substitution pressure from botanical lake alternatives as EFSA aluminum re-evaluations and retailer clean-label mandates erode synthetic pigment demand. Defense requires repositioning around certification assets and extraction infrastructure that emerging competitors cannot rapidly replicate.
For Market Incumbents: Insulate core confectionery accounts by accelerating dual-certification capacity investments in FDA-EFSA compliant production lines. Secure captive botanical sourcing infrastructure to defend margin position against toll-manufacturing aggregators entering natural lake segments. Prioritize encapsulation technology licensing to maintain performance differentiation as synthetic-to-natural reformulation accelerates.
For New Entrants and Emerging Players: Brazilian domestic confectionery production represents underpenetrated white space where ANVISA's permissive regulatory thresholds sustain synthetic lake demand absent in North America and Europe. Target liquid dispersion automation opportunities in automated North American beverage manufacturing facilities where incumbent relationships remain underdeveloped. Pursue rapid-turnaround custom blend capabilities serving mid-tier dairy and bakery accounts with specification agility.
For Investors and Strategic Acquirers: EFSA's aluminum-containing pigment re-evaluation under the EU food improvement agent framework reshapes the acquisition landscape toward natural extraction infrastructure. Long-term viability favors targets with backward-integrated botanical sourcing and dual-certification manufacturing footprints. Monitor FSSAI enforcement intensity across Maharashtra and Gujarat as the signal indicating acceleration of India's synthetic-to-natural transition.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Botanical Extraction | Sensient Technologies' upstream control over supply continuity secures natural lake line expansion against seasonal harvest volatility. |
| Dual-Certification Manufacturing Investment | Simultaneous FDA-EFSA compliant production lines enable cross-Atlantic procurement consolidation among multinational confectionery accounts. |
| Encapsulation Technology Licensing | DDW's proprietary microencapsulation methods improve light stability in fat-based matrices, matching synthetic performance in retail environments. |
| Digital Color-Matching Platform Deployment | Cloud-based formulation tools compress development cycles for regional specialists competing with integrated majors on specification agility. |
| Long-Term Aluminum Hydrate Supply Agreement | Fixed-price chemical precursor contracts protect margin structures against input cost volatility affecting precipitation-based production. |
Research Methodology
The analysis maps natural lake extraction, synthetic pigment precipitation, encapsulation technology, and custom blending sub-sectors, each validated through formulation chemists, confectionery procurement directors, and regulatory affairs specialists. Primary interviews with plant managers at Maharashtra and Gujarat processing facilities, technical R&D directors at German industrial bakery clusters, and distribution channel partners in Stuttgart and Hamburg were cross-referenced against secondary sources including FDA 21 CFR batch certification records, EFSA food improvement agent framework documentation, FSSAI enforcement notifications, and customs trade data for aluminum hydrate and botanical raw material flows. Bottom-up procurement volume estimates and top-down market sizing were triangulated to resolve segment-level allocations.
The forecast framework holds regulatory trajectory assumptions constant across the projection horizon while varying adoption rate scenarios for clean-label reformulation. Segmentation dimensions modeled include product type certification tier, application matrix requirements, end-user procurement scale, and geographic regulatory cluster. CAGRs were derived from trend extrapolation of procurement volume shifts and price trajectory analysis. Industry-specific inputs incorporated EFSA re-evaluation timelines, FSSAI enforcement intensity gradients, and encapsulation technology penetration curves in confectionery applications.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by backward-integrated botanical extractors or accelerated aluminum substrate substitution would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Food Grade Calcium Phosphate Market
Food Additives and Ingredients
Bread Preservatives Market
Food Additives and Ingredients
Food Grade Potassium Sorbate Market
Food Additives and Ingredients
Annatto Food Colors Market
Food Additives and Ingredients
Sodium Propionate Market
Food Additives and Ingredients
Spain Food Acidulants Market
Food Additives and Ingredients
India Food Preservatives Market
Food Additives and Ingredients
Clean Labelled Food Additives Market
Food Additives and Ingredients
Flour Whiteners Market
Food Additives and Ingredients
Global Natamycin Market
Food Additives and Ingredients
Food Protein Ingredient Market
Food Additives and Ingredients
Argentina Food Enzymes Market
Food Additives and Ingredients
Meat Tenderizing Agents Market
Food Additives and Ingredients
Asia-Pacific Food Additives Market
Food Additives and Ingredients
South America Feed Anti-Caking Agents Market
Food Additives and Ingredients
Bread Emulsifier Market