
 Filling Fat Market | 2026-2036
Filling Fat Market Size, Share, and Industry Trends Forecast 2026-2036
Filling Fat Market Insights
Multi-source procurement from Southeast Asian palm processors is decoupling from traditional single-origin supply contracts. Cargill leverages integrated oilseed crushing networks across multiple continents to secure base stock flexibility. Bunge Limited anchors its filling fat portfolio through backward integration into tropical oil refining. AAK competes via specialized emulsifier-blend formulations tailored to confectionery viscosity requirements.
Filling fats are lipid-based shortening systems formulated with triglyceride blends, emulsifiers, and crystallization modifiers to deliver specific plasticity ranges and melting profiles for industrial food production. Their primary function is to provide structure, mouthfeel, and moisture barrier properties in processed foods where solid fat functionality remains essential. Powder and paste forms command margin premiums due to handling efficiency and dosing precision in automated bakery lines. Confectionery applications represent the fastest-growing application segment as chocolate compound coatings require tailored fat compatibility. Emulsifier components sit at the center of formulation differentiation, with lecithin and monoglyceride blends determining shelf stability and texture control.
EFSA evaluates emulsifier safety under renewed food additive authorization protocols, while FDA maintains GRAS self-affirmation pathways that create divergent compliance burdens for exporters. BIS certification requirements in India mandate specific melting point declarations for imported filling fat consignments. Stakeholders must monitor evolving trans-fat labeling mandates and crystallization technology advances that could reshape formulation economics without warning.
Market Dynamics
Clean-label mandates from EFSA are forcing food manufacturers to reformulate emulsifier systems while crystallization technology advances reshape formulation economics across industrial bakery and confectionery supply chains.
Growth Catalysts
- EFSA Additive Re-evaluation:Tightened safety protocols for food contact materials are accelerating demand for palm-derived alternatives with documented traceability in European processed food manufacturing.
- Chocolate Compound Coatings:Confectionery processors require tailored fat compatibility for compound coatings that maintain snap and gloss without cocoa butter, driving specialized formulation development.
- Indonesia's Processing Corridor:Concentrated palm oil refining infrastructure in Sumatra and Kalimantan provides integrated supply security for multinational food manufacturers seeking backward integration.
Market Restraints
- Palm Oil Price Volatility:Crude palm oil futures on Bursa Malaysia Derivatives exchange transmit immediate cost pressure to filling fat processors with limited hedging capacity.
- Single-Origin Supply Risk:Traditional procurement from Malaysian plantation networks creates concentration exposure that multi-source strategies only partially mitigate during El Niño weather events.
- Trans-Fat Labeling Mandates:FDA disclosure requirements and WHO elimination targets restrict formulation flexibility for plasticity ranges previously achieved through partial hydrogenation.
Strategic Opportunities
- India's Bakery Ingredient Sector:Organized retail expansion and quick-service restaurant penetration in tier-2 cities create underexploited demand for automated dosing-compatible paste formats.
- Emulsifier-Blend Convergence:Combination of enzymatic interesterification with structured lipid technology enables custom melting profiles without hydrogenation for premium confectionery tiers.
- BIS Certification Pathway:Mandatory melting point declarations for imported consignments create compliance-as-a-service revenue streams for testing laboratories and certification consultants.
Industry Challenges
- Crystallization Modification Expertise:Formulation chemists capable of balancing polymorphic stability with mouthfeel requirements remain scarce relative to expanding clean-label development pipelines.
- Legacy Equipment Retrofit Costs:Automated bakery lines designed for solid block fats require capital-intensive reconfiguration to handle powder and paste formats efficiently.
- GRAS Self-Affirmation Complexity:Divergent FDA notification pathways versus EFSA pre-authorization create dual-track compliance burdens for exporters serving both regulatory jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Filling Fat Market |
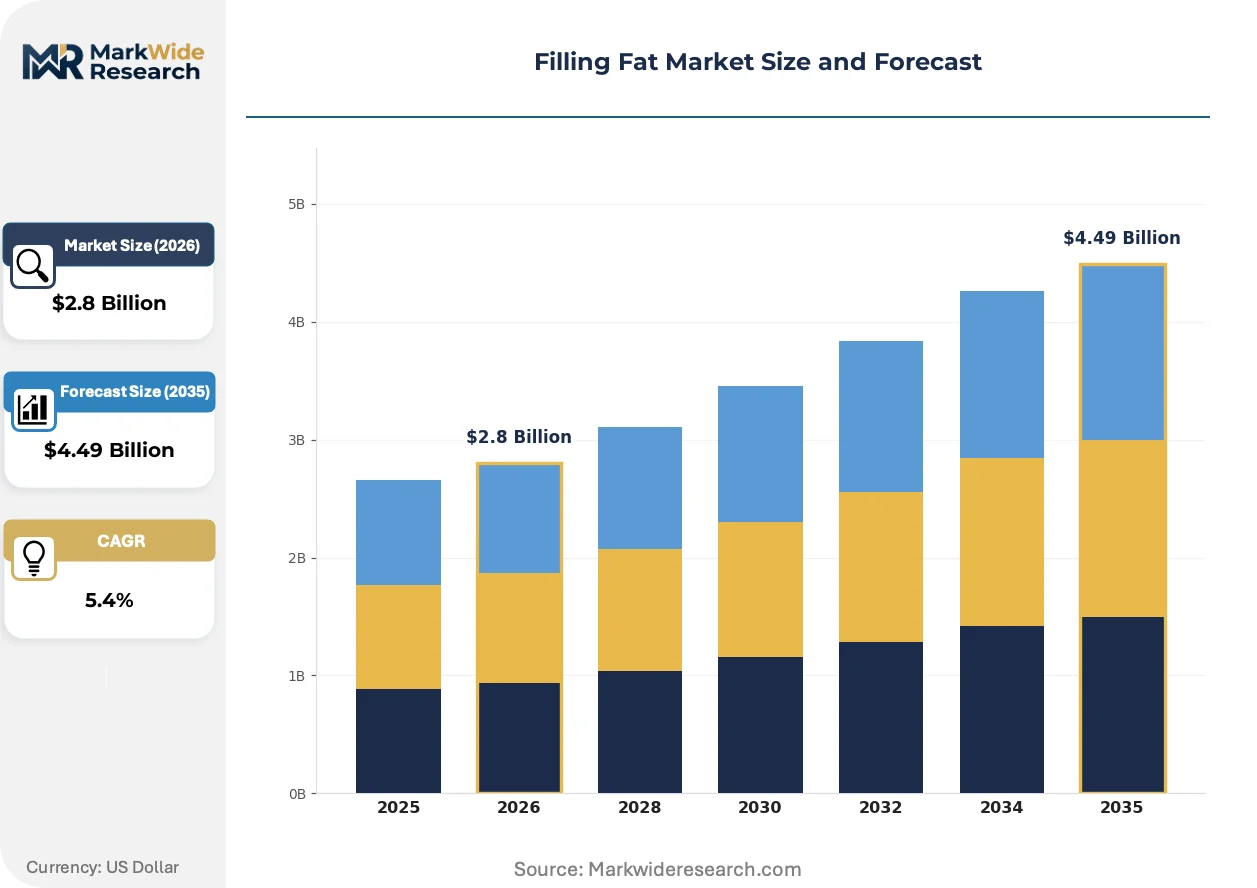
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.49 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component: Emulsifiers, Stabilizers, Texture Agents, Colorants Application: Baked Goods, Dairy Products, Confectionery, Sauces Form: Liquid, Powder, Granular, Paste End User: Food Manufacturers, Restaurants, Retailers, Catering Services |
| Companies Covered | Cargill, Bunge Limited, AAK, Wilmar International, IOI Group, Fuji Oil Holdings, Mewah International, Manorama Industries, Sime Darby Plantation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Filling Fat Market Trends and Innovations
Interesterification technology is displacing partial hydrogenation as the dominant modification pathway, while digital traceability platforms and enzymatic processing converge to reshape how filling fat specifications are verified and contracted.
Enzymatic interesterification is consolidating market share among premium confectionery formulators seeking precise control over triglyceride positioning without trans-fat generation. Chocolate compound manufacturers in Western Europe have adopted this technology at scale since 2019. The process is consolidating supplier margins by reducing chemical catalyst waste and enabling smaller-batch customization that hydrogenation cannot achieve.
REACH registration requirements for food contact substances are tightening documentary obligations for emulsifier imports into European Union member states. Industrial food manufacturers must now submit extended safety data sheets for lecithin and monoglyceride derivatives. The confectionery segment bears the heaviest compliance burden, with mid-tier processors delaying new product launches to complete substance volume tracking.
Direct contracting between food manufacturers and plantation-level processors is compressing traditional trader intermediation in Southeast Asian supply chains. Large bakery conglomerates in Indonesia and Malaysia now negotiate base stock supply agreements spanning multiple harvest cycles. This pattern is most visible in the quick-service restaurant supply chain, where specified melting point ranges are locked into multi-year procurement contracts with price-adjustment clauses tied to crude palm oil futures.
Filling Fat Market Segmentation
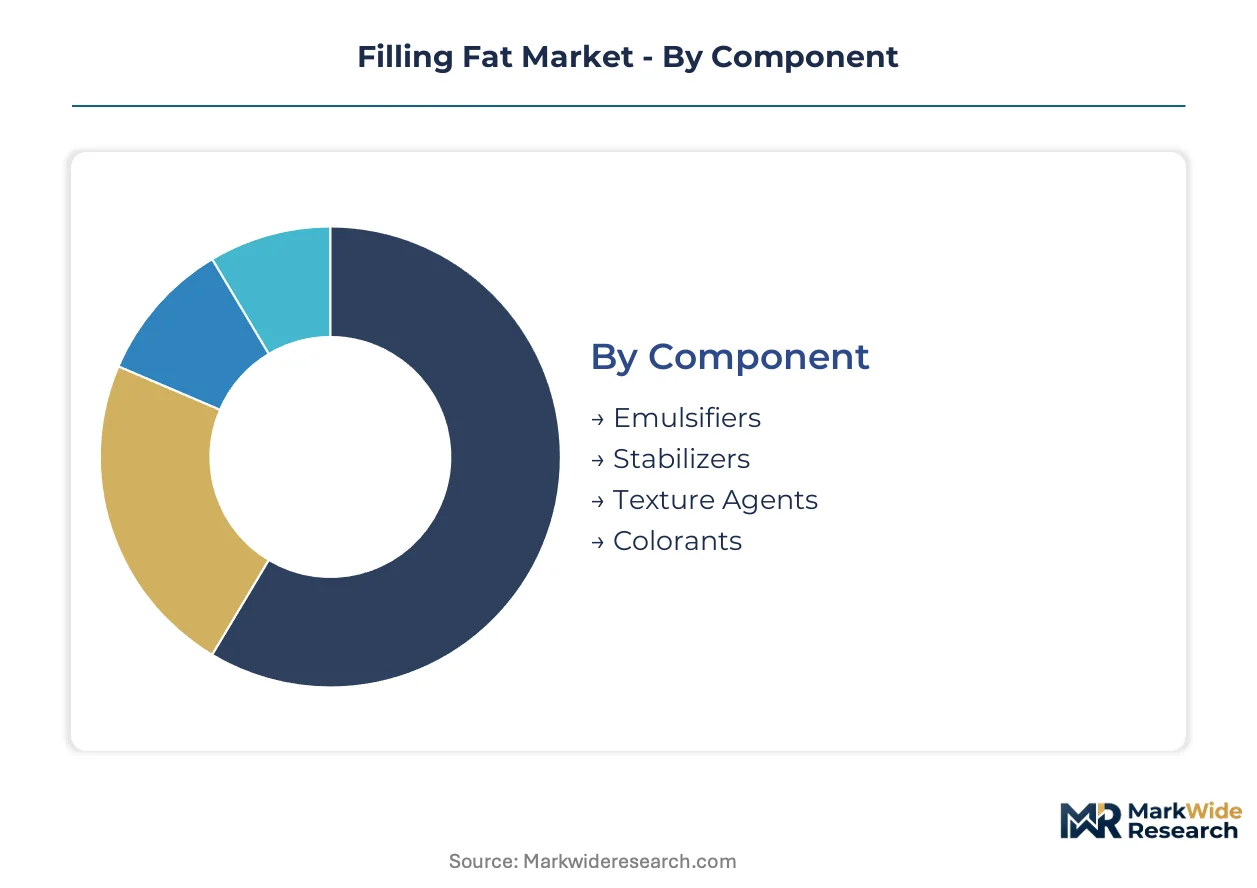
Filling fat formulations derive commercial value from precise component engineering and physical state optimization. Each segmentation dimension reveals distinct margin structures and procurement patterns that determine competitive positioning across industrial food manufacturing.
Component:
Volume concentrates in commodity emulsifier grades while premium formulation value migrates toward enzymatic stabilizer systems with documented traceability chains.
- Emulsifiers:Lecithin and monoglyceride blends determine shelf stability and texture control in industrial bakery applications. European confectionery processors under EFSA's renewed additive authorization protocols are accelerating procurement of palm-derived lecithin with batch-level documentation. This segment anchors baseline formulation economics across all major food manufacturing geographies.
- Stabilizers:Crystallization modifiers including sorbitan esters and polyglycerol polyricinoleate manage polymorphic stability in chocolate compound coatings. Indonesian palm processors in Sumatra and Kalimantan now integrate stabilizer pre-blending into their refined oil output streams, compressing traditional trader margins. Demand concentrates where clean-label mandates restrict synthetic additive use.
- Texture Agents:Hydrophilic colloids and modified starches extend plasticity ranges in automated dosing systems.
- Colorants:Carotenoid and annatto extracts provide visual differentiation in premium confectionery tiers.
Today's leader: Emulsifiers. Tomorrow's challenger: Stabilizers.
Application:
Application-driven procurement separates high-throughput commodity buyers from specialized formulators seeking custom melting profile engineering.
- Baked Goods:Industrial bread and pastry manufacturing consumes powder and paste formats optimized for automated line integration. India's organized retail expansion and quick-service restaurant penetration in tier-2 cities is expanding demand for dosing-compatible paste specifications with defined melting point ranges. EFSA's tightened food contact material rules are forcing reformulation of emulsifier systems in European bakery operations.
- Confectionery:Chocolate compound coatings require tailored fat compatibility to maintain snap and gloss without cocoa butter. Enzymatic interesterification technology enables precise triglyceride positioning for premium tiers. This application is expanding most quickly as Western European processors adopt clean-label modification pathways at scale.
- Dairy Products:Whipped topping and ice cream systems demand specific aeration stability and freeze-thaw resistance.
- Sauces:Emulsion stability in ambient and chilled dressings determines mouthfeel consistency across shelf life.
Volume dominance: Baked Goods. Margin expansion: Confectionery.
Form:
Physical state selection reflects automation compatibility requirements and handling cost trade-offs across supply chain configurations.
- Powder:Spray-dried and plated fat systems enable precise dosing in high-speed bakery lines with minimal handling losses. Powder formats command margin premiums due to dosing precision and reduced labor requirements in automated production environments. Indian food manufacturers upgrading legacy equipment are prioritizing powder compatibility in procurement specifications.
- Paste:Pumpable fat systems with controlled plasticity ranges suit continuous mixing operations in industrial confectionery. Paste demand concentrates in facilities with heated transfer infrastructure capable of maintaining specified viscosity parameters. Indonesia's integrated processing corridor is expanding paste output capacity to serve multinational quick-service restaurant supply chains.
- Liquid:Fluid shortening systems serve frying and coating applications where solid fat functionality is not required.
- Granular:Intermediate physical state offers compromise between powder flowability and paste plasticity control.
Automation preference: Powder. Processing flexibility: Paste.
End User:
Customer type determines specification stringency, contract structure, and technical service intensity across the procurement relationship.
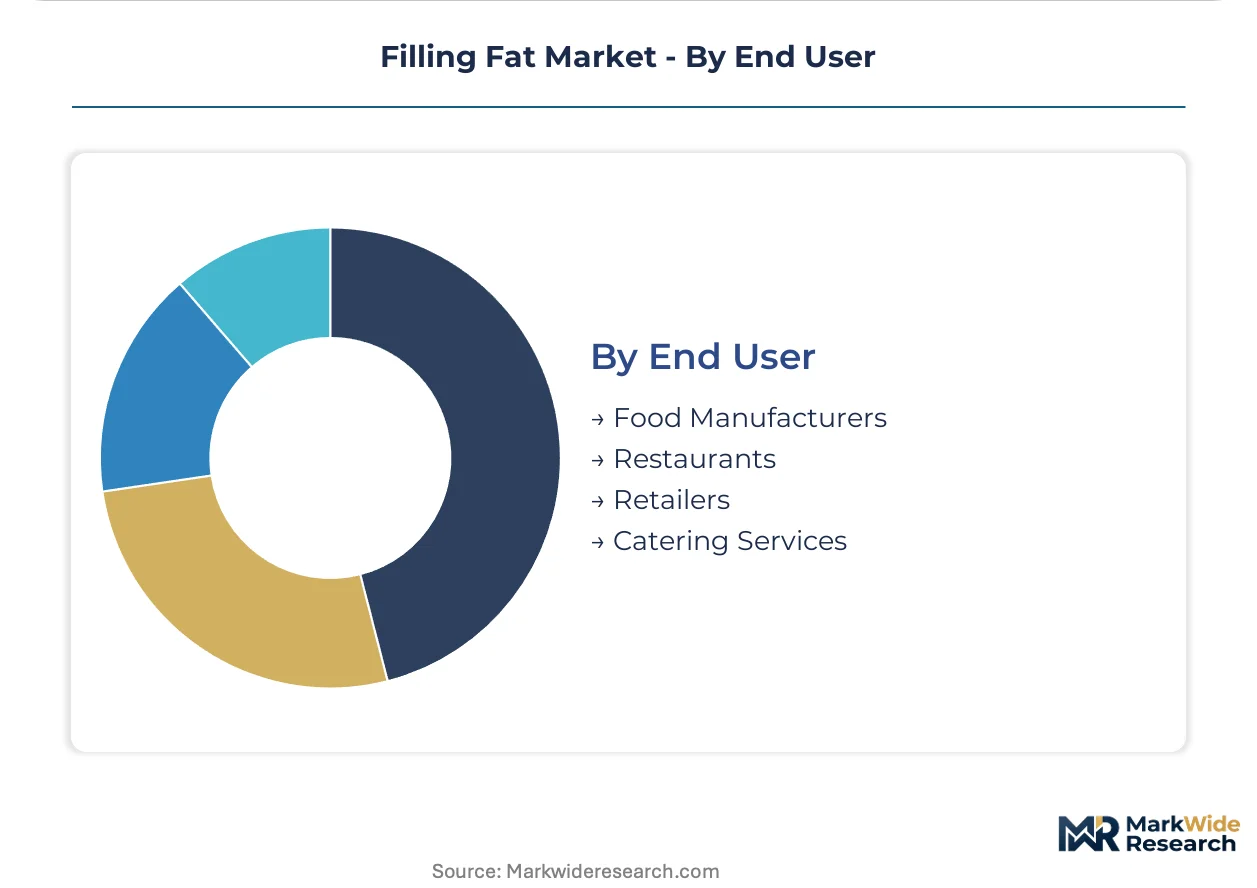
- Food Manufacturers:Industrial processors with captive R&D capabilities negotiate direct supply agreements spanning multiple harvest cycles. Large bakery conglomerates in Indonesia and Malaysia now lock specified melting point ranges into multi-year contracts with crude palm oil price-adjustment clauses. BIS certification requirements in India mandate specific documentation for imported filling fat consignments.
- Restaurants:Quick-service restaurant chains require consistent performance specifications across distributed kitchen networks with varying equipment ages. Procurement concentrates through approved supplier programs with stringent quality audit protocols. Central kitchen models in Southeast Asia are consolidating filling fat demand toward standardized paste formats.
- Retailers:Private-label bakery and confectionery programs drive specification development for contract manufacturers.
- Catering Services:Institutional foodservice operations prioritize cost stability and supply security over formulation sophistication.
Contract sophistication: Food Manufacturers. Volume consolidation: Restaurants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia's palm oil processing corridor in Sumatra and Kalimantan anchors global filling fat supply security, with multinational food manufacturers negotiating multi-year procurement contracts that lock specified melting point ranges with crude palm oil price-adjustment clauses.
Indonesia
Integrated refining infrastructure in Sumatra and Kalimantan serves multinational quick-service restaurant chains requiring standardized paste formats with documented traceability. BIS certification requirements for Indian imports are prompting Indonesian processors to pre-certify melting point declarations. Direct contracting between plantation-level processors and food manufacturers is compressing traditional trader intermediation across Southeast Asian supply chains.
India
Organized retail expansion and quick-service restaurant penetration in tier-2 cities is expanding demand for automated dosing-compatible paste formats with defined melting point ranges. FSSAI mandates specific documentation standards for imported filling fat consignments under BIS certification pathways. Maharashtra and Gujarat host the densest concentrations of industrial bakery operations upgrading legacy equipment for powder compatibility.
Germany
Western European confectionery processors under EFSA's renewed additive authorization protocols are accelerating procurement of palm-derived lecithin with batch-level documentation. REACH registration requirements for food contact substances are tightening documentary obligations for emulsifier imports into EU member states. The Rhine-Ruhr industrial corridor concentrates chocolate compound manufacturing facilities adopting enzymatic interesterification at scale.
United States
FDA disclosure requirements and WHO trans-fat elimination targets are restricting formulation flexibility for plasticity ranges previously achieved through partial hydrogenation. GRAS self-affirmation pathways create divergent compliance burdens for exporters serving both US and European jurisdictions. Midwest bakery conglomerates are prioritizing powder format procurement to minimize handling losses in automated production environments.
Brazil
Domestic soybean crushing capacity provides alternative base stock flexibility for filling fat processors seeking to reduce palm oil price volatility exposure. ANVISA maintains alignment with CODEX standards for emulsifier safety evaluations while preserving formulation flexibility absent in European jurisdictions. São Paulo state concentrates industrial bakery and confectionery manufacturing demanding consistent performance specifications across distributed production networks.
Filling Fat Market Competitive Landscape
Global majors compete with regional champions across integrated oilseed crushing networks and specialized emulsifier-blend formulation capabilities. The market structure fragments between multinational traders with backward integration into tropical oil refining and mid-tier specialists competing via enzymatic processing technology. Three archetypes dominate: integrated agribusiness conglomerates with captive palm processing assets, emulsifier-specialist formulators serving premium confectionery tiers, and plantation-linked processors leveraging direct supply agreements. Competitive moves concentrate on multi-source procurement strategies and crystallization technology licensing to secure formulation flexibility without hydrogenation.
Within the integrated agribusiness tier, Cargill and Bunge Limited exemplify multinational scale advantages through oilseed crushing networks spanning multiple continents. AAK occupies a specialist position focused on emulsifier-blend formulations tailored to viscosity requirements in premium confectionery applications. These three entities represent distinct competitive vectors: trading and logistics integration, upstream refining control, and formulation chemistry specialization respectively.
| Leading Market Players |
|---|
| Cargill |
| Bunge Limited |
| AAK |
| Wilmar International |
| IOI Group |
| Fuji Oil Holdings |
| Mewah International |
| Manorama Industries |
| Sime Darby Plantation |
| Others |
Pricing and Supply Chain Analysis
EFSA's tightened food contact material rules gate qualified supply access and premium-tier pricing for European confectionery processors seeking batch-documented palm-derived emulsifiers. Clean-label procurement mandates compress margins for non-compliant traders while enzymatic interesterification capabilities command formulation premiums.
Pricing Analysis
Crude palm oil futures on Bursa Malaysia Derivatives transmit immediate cost pressure through contract-based long-term offtake agreements with crude palm oil price-adjustment clauses. Price differentiation separates enzymatic interesterification-enabled premium tiers from chemically modified standard grades, with certification grade and volume scale as secondary drivers. Cost compression in commodity emulsifier tiers is intensifying because Indonesian processors integrate pre-blending capabilities that displace traditional trader margins. Quick-service restaurant chains exhibit highest price sensitivity due to standardized specification requirements, while premium confectionery formulators prioritize melting profile precision over unit cost.
Supply Chain Analysis
Regional distribution centers in Jakarta and Surabaya consolidate output from Sumatra and Kalimantan processing corridors before onward shipment to Indian and European manufacturing hubs. Supply concentrates in Indonesia, Malaysia, and India, with raw material dependencies on crude palm oil, lecithin feedstocks, and crystallization modifier chemicals. Single-source vulnerability from El Niño weather events disrupts harvest cycles and refining capacity allocation. Distribution runs through direct contracting between plantation-level processors and multinational food manufacturers, compressing traditional trader intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The filling fat market compounds steadily as clean-label reformulation mandates perpetually refresh demand for enzymatic processing capabilities and documented traceability systems.
For Market Incumbents: Lock in multi-year procurement contracts spanning multiple harvest cycles with price-adjustment clauses tied to crude palm oil futures to defend against emerging processor competition from integrated Indonesian refining networks. Prioritize crystallization technology licensing to preserve formulation flexibility as EFSA additive re-evaluations restrict hydrogenation pathways.
For New Entrants and Emerging Players: Quick-service restaurant chains represent the most penetrable buyer segment due to centralized procurement consolidation and specification standardization across distributed kitchen networks. Target India's tier-2 city expansion through automated dosing-compatible paste formats with defined melting point ranges and BIS pre-certification to accelerate market access.
For Investors and Strategic Acquirers: Roll-up economics work for mid-tier enzymatic processing specialists because formulation chemistry expertise remains scarce relative to expanding clean-label development pipelines across European confectionery tiers. Monitor EFSA authorization protocol timelines as the inflection signal for premium-tier margin expansion or compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tropical Oil Refining | Bunge Limited anchors portfolio control through captive palm processing assets in Sumatra. |
| Emulsifier-Blend Convergence R&D | AAK develops specialized formulations for confectionery viscosity requirements under EFSA protocols. |
| Multi-Source Procurement Networks | Cargill leverages oilseed crushing across continents to secure base stock flexibility against El Niño disruption. |
| Digital Traceability Platform Deployment | Indonesian processors implement batch-level documentation systems for European lecithin procurement compliance. |
| Legacy Equipment Retrofit for Powder Compatibility | Indian bakery conglomerates upgrade Maharashtra and Gujarat facilities to capture dosing precision premiums. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with palm oil procurement directors, confectionery formulation chemists, bakery operations managers, and emulsifier supply chain coordinators with secondary validation from Bursa Malaysia Derivatives exchange data, EFSA additive authorization filings, FSSAI BIS certification records, and customs trade documentation. Bottom-up volume modeling and top-down value triangulation anchored segment-level outputs.
Comparable-period anchoring tied projection assumptions to historical reference patterns across the analysis window, with segmentation modeling across component type, application, physical form, and end-user archetype. CAGRs derived from regression-weighted trend extrapolation incorporating crude palm oil price volatility indices, enzymatic processing adoption curves, and regulatory authorization timeline probabilities.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EFSA emulsifier safety re-evaluations, El Niño weather cycle intensity, and crystallization technology licensing diffusion rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Beverages Additives Market
Food Additives and Ingredients
Argentina Food Preservatives Market
Food Additives and Ingredients
Fermented Chymosin Market
Food Additives and Ingredients
Cetyl Palmitate Market
Food Additives and Ingredients
Beverage Clouding Agent Market
Food Additives and Ingredients
Tapioca Starch Market
Food Additives and Ingredients
Africa Food Stabilizers Market
Food Additives and Ingredients
Australia Food Emulsifiers Market
Food Additives and Ingredients
Locust Bean Gum Market
Food Additives and Ingredients
Amaranth (E123) Market
Food Additives and Ingredients
France Anti Caking Market
Food Additives and Ingredients
Food Grade Phosphates Market
Food Additives and Ingredients
Japan Food Acidulants Market
Food Additives and Ingredients
Natural Food and Beverage Preservatives Market
Food Additives and Ingredients
US Food Emulsifiers Market
Food Additives and Ingredients
Hydrocolloids Market