
 Beverages Additives Market | 2026-2036
Beverages Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Beverages Additives Market Analysis
Food chemist and formulation scientist shortages in emerging markets is reorganizing how multinational suppliers deploy technical resources. Cargill, Incorporated leverages its integrated sweetener supply chain to dominate bulk high-intensity sweetener procurement. Kerry Group anchors its position through specialized beverage application labs in key consumption zones. Tate & Lyle differentiates via deep expertise in texturant systems for reduced-sugar formulations.
Beverage additives comprise functional ingredients—encompassing flavorings, sweeteners, preservatives, and colorants—that modify sensory properties, extend shelf stability, or enhance nutritional profiles in drinkable products, typically dosed at parts-per-million to low-percentage concentrations depending on functional class. Their primary commercial purpose centers on enabling product differentiation, cost optimization, and compliance with evolving consumer health expectations in liquid consumables. Sweeteners command the largest absolute value pool within product type segmentation, driven by sugar reduction mandates across formulated beverages, while flavorings represent the fastest-expanding category as botanical and exotic fruit profiles proliferate in premium positioning. Within application segmentation, energy drinks outpace sodas in additive intensity per liter, creating concentrated margin opportunities for suppliers with stimulant-compatible formulation expertise.
The FDA governs color additive certification and GRAS self-determination pathways in the United States, while the EMA and EFSA jointly influence preservative safety thresholds and labeling requirements across European markets, directly constraining permissible ingredient portfolios and reformulation cycles. China's SAMR enforces GB standards for food additive usage limits, creating divergent compliance burdens for suppliers operating across multiple regulatory jurisdictions. Stakeholders must monitor pending revisions to clean-label definitions in major economies, as regulatory ambiguity around natural versus artificial classifications threatens to invalidate existing product positioning strategies and force accelerated reformulation investments.
Market Dynamics
Clean-label mandates from the EU's Farm to Fork Strategy are compressing permissible additive portfolios and forcing accelerated reformulation cycles across functional beverage manufacturing.
Growth Catalysts
- Sugar Reduction Mandates:National health frameworks in Mexico, the United Kingdom, and South Africa impose beverage sugar caps that expand demand for high-intensity sweeteners and bulking agents in reformulated products.
- Functional Positioning:Energy drink and sports hydration categories drive additive intensity per liter, creating concentrated procurement pull for stimulant-compatible and electrolyte-delivery systems.
- Botanical Extraction Advances:Supercritical CO2 and membrane filtration technologies reduce off-notes in natural flavorings, enabling broader replacement of synthetic alternatives in premium positioning.
Market Restraints
- Regulatory Divergence:China's SAMR enforces GB standards with usage limits divergent from FDA GRAS determinations and EFSA safety thresholds, multiplying compliance burdens for multinational portfolios.
- Input Concentration:Stevia glycoside supply concentrates in Paraguay and China's Yunnan province, exposing sweetener procurement to climate volatility and single-origin risk.
- Clean-Label Ambiguity:Absence of harmonized natural-versus-artificial definitions across major economies threatens to invalidate existing product positioning without warning.
Strategic Opportunities
- Fermentation-Derived Ingredients:Precision fermentation platforms produce nature-identical compounds with supply security advantages over agricultural extraction, opening positioning in markets with strict additive ceilings.
- India's Beverage Manufacturing:FSSAI modernization and PLI scheme incentives for food processing attract additive suppliers to underpenetrated formulation services in Maharashtra and Karnataka.
- Postbiotic Integration:Heat-inactivated microbial preparations bypass live-culture stability challenges in ambient beverages, creating new functional claim territory beyond traditional probiotics.
Industry Challenges
- Formulation Talent Scarcity:Food chemist shortages in Brazil's southeastern manufacturing corridor force suppliers to deploy centralized technical resources rather than embedded field support.
- Reformulation Cycle Compression:Pending EFSA revisions to preservative safety assessments demand accelerated stability testing timelines that strain application laboratory capacity.
- Intellectual Property Fragmentation:Patent thickets around novel sweetener molecules and encapsulation technologies complicate freedom-to-operate analyses for new product development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beverages Additives Market |
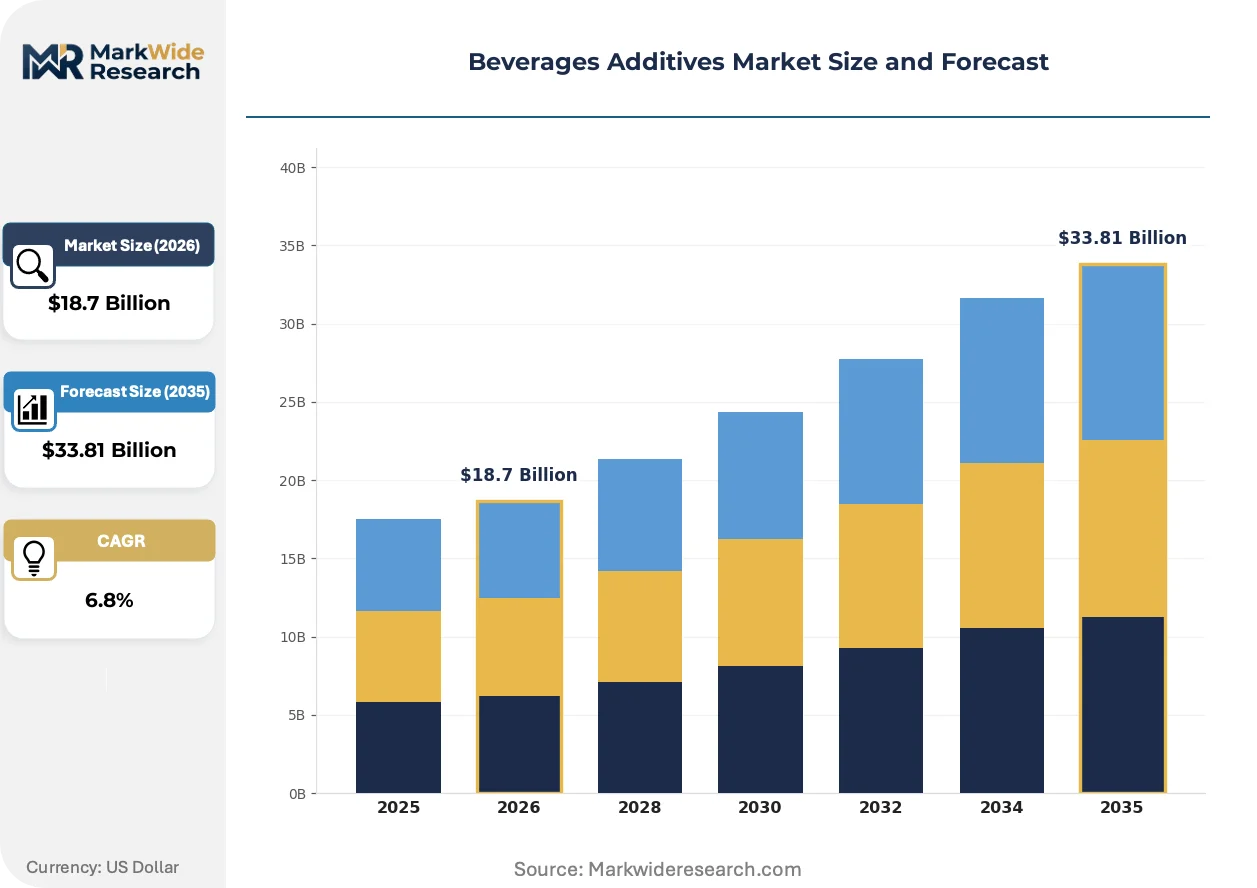
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flavorings, Sweeteners, Preservatives, Colorants Application: Sodas, Energy Drinks, Juices, Alcoholic Beverages Form: Liquid, Powder, Capsule, Granule End User: Food Manufacturers, Beverage Companies, Retailers, Food Service Providers |
| Companies Covered | Cargill, Incorporated, Archer Daniels Midland Company, DuPont, Tate & Lyle, International Flavors & Fragrances Inc., Ingredion Incorporated, Kerry Group, Givaudan, Chr. Hansen Holding A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beverages Additives Market Emerging Trajectories
Biotechnology and regulatory stringency are restructuring how beverage additives are sourced, validated, and integrated into finished products.
Precision fermentation for nature-identical compounds is bifurcating supply strategies. Major sweetener and flavoring houses now operate parallel agricultural and biomanufacturing supply lines. Energy drink manufacturers in the United States and Germany prioritize fermentation-derived sources for supply security and ESG positioning.
REACH authorization requirements and the EU Green Deal's chemical sustainability criteria are tightening preservative and colorant approval pathways. ECHA substance evaluation timelines now extend eighteen to thirty-six months for novel additives. Botanical extract suppliers accelerate dossier preparation for substances under regulatory scrutiny.
Beverage brand technical buyers now require full supply chain transparency to ingredient origin rather than certificate-of-analysis compliance alone. Direct supplier-manufacturer relationships displace distributor-mediated procurement for strategic additive categories. This pattern concentrates in Western European and North American premium beverage segments where clean-label claims command shelf price premiums.
Beverages Additives Market Segmentation
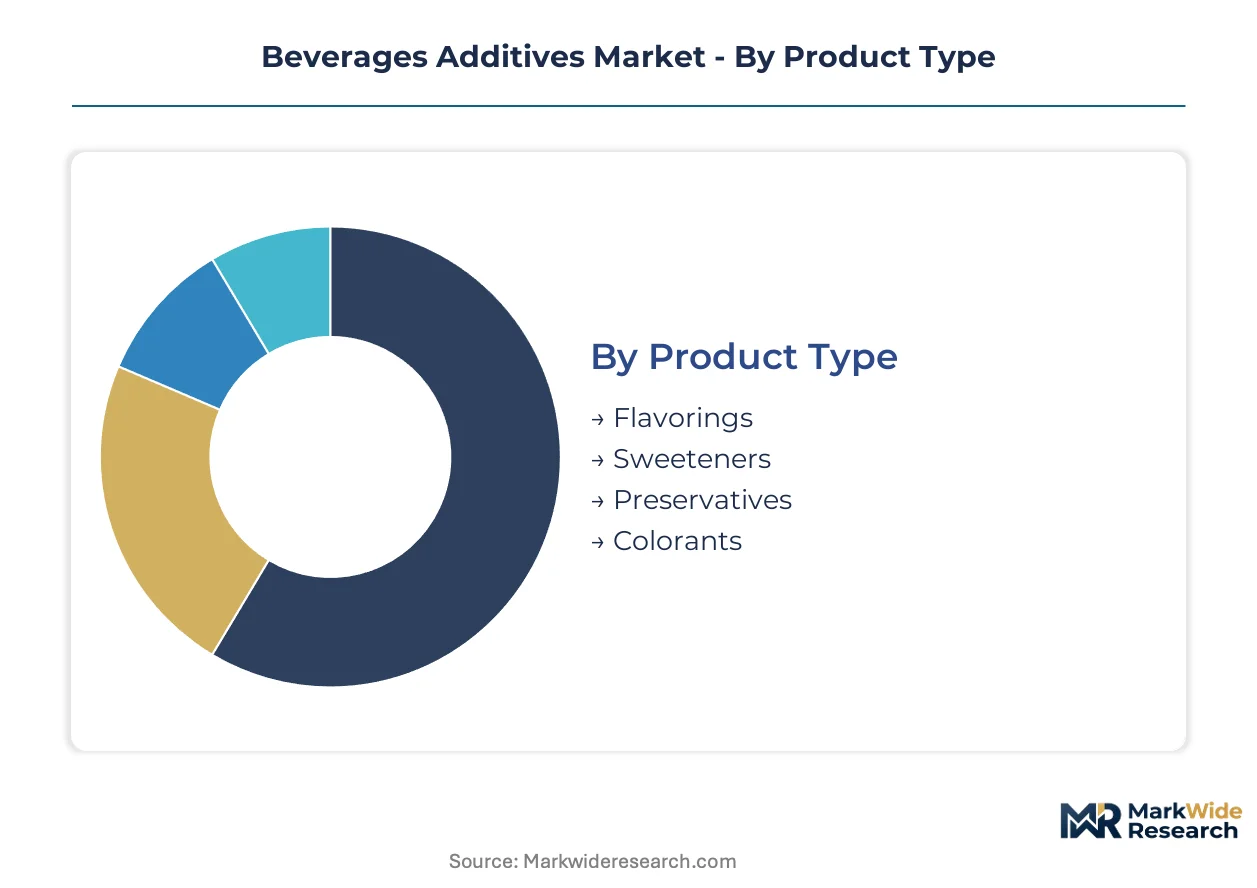
Additive selection in beverages follows distinct procurement pathways. Product type determines formulation complexity. Application dictates regulatory scrutiny intensity. Form and end-user channels shape margin structures and technical service requirements.
Product Type:
Channel mix varies sharply across additive categories. Sweeteners and flavorings flow predominantly through direct supplier-manufacturer relationships in premium beverage segments. Preservatives and colorants retain more distributor-mediated procurement in cost-sensitive applications.
- Flavorings:Botanical and exotic fruit extracts delivered via supercritical CO2 processing. Demand concentrates in energy drink formulation labs across Germany and the United States, where clean-label mandates accelerate synthetic replacement timelines.
- Sweeteners:High-intensity compounds including stevia glycosides and fermentation-derived alternatives. Procurement concentrates around sugar reduction mandates in Mexico, the United Kingdom, and South Africa, with supply security driving biomanufacturing adoption.
- Preservatives:Chemical and natural shelf-life extenders subject to REACH authorization delays.
- Colorants:Certified and exempt categories governed by divergent FDA and EFSA approval pathways.
Sweeteners dominate installed base value. Flavorings are where expansion concentrates.
Application:
Cost tier stratification separates premium positioning from commodity volume play. Energy drinks and premium juices command formulation service premiums. Sodas and mass-market alcoholic beverages prioritize procurement efficiency.
- Energy Drinks:Highest additive intensity per liter across all beverage categories. Formulation demands stimulant-compatible systems and electrolyte-delivery expertise, creating concentrated margin pools for specialized suppliers in the United States and Germany.
- Sodas:Volume-driven procurement with sugar reduction reformulation as the primary technical challenge. Mexico's national sugar caps and the United Kingdom's soft drinks levy reshape ingredient specifications.
- Juices:Natural positioning constraints limit permissible additive categories.
- Alcoholic Beverages:Flavor modulation and stability systems for RTD cocktails and flavored beers.
Sodas retain the largest installed production base. Energy drinks represent the steepest expansion trajectory.
Form:
Volume concentration favors liquid and powder formats for industrial-scale beverage manufacturing. Capsule and granule forms serve niche applications with dosing precision requirements.
- Liquid:Preferred for high-throughput continuous processing. Dominates sweetener and flavoring delivery in Brazil's southeastern manufacturing corridor around São Paulo state.
- Powder:Dry-blend compatibility and extended shelf stability. Concentrates in sports hydration and instant beverage applications.
- Capsule:Precision dosing for small-batch premium production.
- Granule:Controlled dissolution profiles for specific mouthfeel targets.
Liquid forms anchor current manufacturing infrastructure. Powder formats are climbing the fastest in functional beverage expansion.
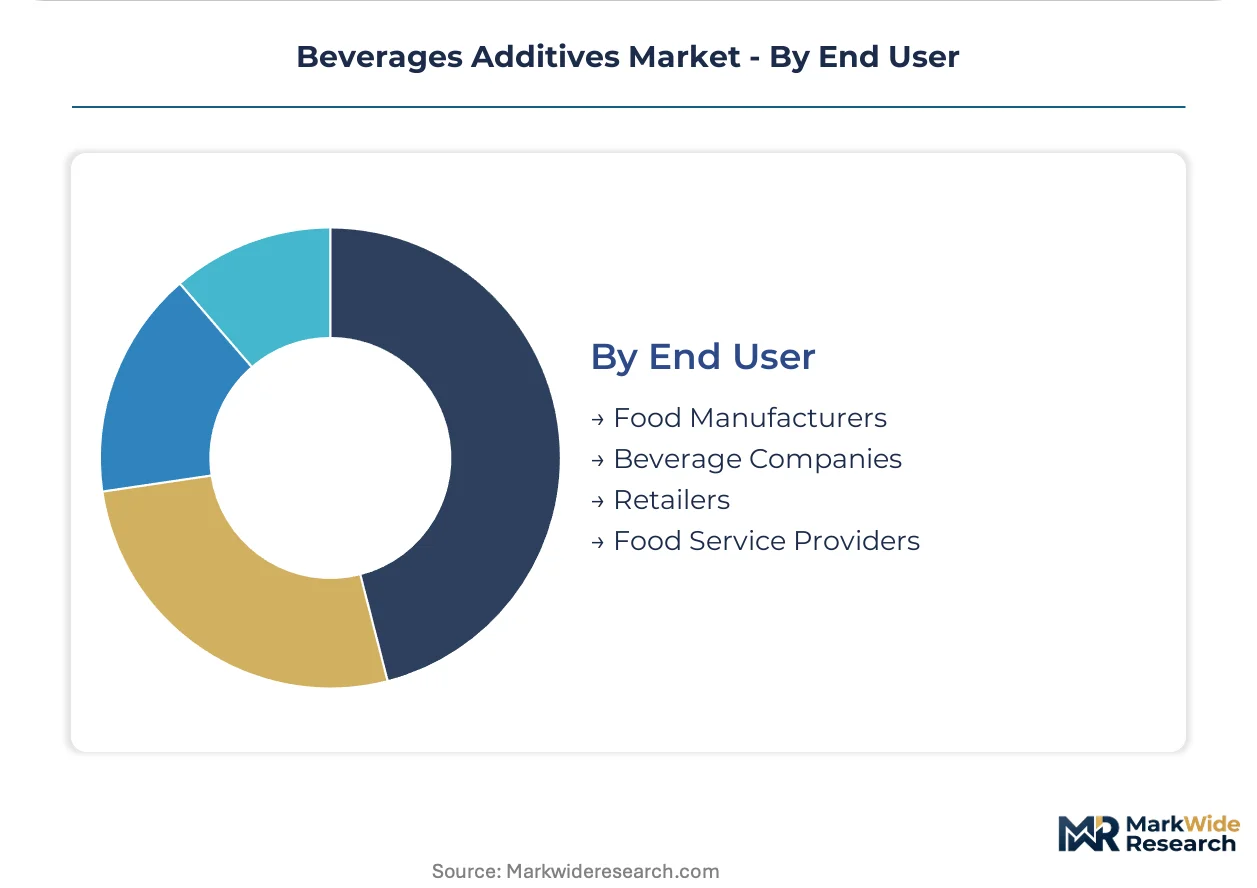
End User:
Customer type determines technical service intensity and contract structure. Beverage companies demand embedded formulation support. Retailers and food service providers prioritize supply reliability over innovation partnership.
- Beverage Companies:Direct technical collaboration with additive suppliers. Kerry Group's application labs and Cargill's integrated supply chains target this segment with specialized service models.
- Food Manufacturers:Cross-category procurement leverage across beverage and solid food portfolios.
- Retailers:Private-label formulation with cost-optimized additive specifications.
- Food Service Providers:Dispensing system compatibility and portion control requirements.
Beverage companies command the deepest supplier relationships. Food manufacturers are where cross-selling expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and the United States drive premium formulation demand with clean-label mandates, while Brazil and China concentrate volume manufacturing with distinct regulatory compliance burdens.
Germany
Energy drink manufacturers in Bavaria and North Rhine-Westphalia accelerate botanical flavoring procurement for stimulant-compatible systems. ECHA's REACH authorization timelines now stretch eighteen to thirty-six months for novel preservatives. The Cologne-Düsseldorf corridor anchors reformulation service demand as brands navigate EU Green Deal chemical sustainability criteria.
United States
Sugar reduction mandates across California and New York Metro expand high-intensity sweetener procurement for reformulated sodas. FDA GRAS self-determination pathways diverge from EFSA thresholds, forcing parallel compliance documentation. Chicago and Atlanta formulation labs concentrate technical resources to serve beverage company direct-supplier relationships.
Brazil
São Paulo state's southeastern manufacturing corridor dominates liquid additive consumption for high-throughput beverage processing. ANVISA enforcement of Mercosur additive harmonization creates reformulation pressure distinct from FDA or EMA frameworks. Campinas and Ribeirão Preto clusters face food chemist shortages that force centralized technical support deployment.
China
Yunnan province stevia glycoside extraction supplies global sweetener demand amid climate volatility exposure. SAMR's GB standards enforce usage limits divergent from Western regulatory determinations, multiplying compliance architecture for multinational portfolios. Shanghai and Guangzhou formulation centers navigate dual carbon goals while scaling fermentation-derived ingredient platforms.
India
Maharashtra and Karnataka beverage manufacturing attracts additive suppliers through FSSAI modernization and PLI scheme incentives. The country's food processing expansion targets underpenetrated formulation services for functional beverage categories. Mumbai and Bengaluru technical facilities bridge agricultural extraction expertise with precision fermentation adoption timelines.
Beverages Additives Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with the former commanding captive supply chains and the latter anchoring application-specific expertise. The market structure favors players with dual capabilities in agricultural sourcing and biomanufacturing platforms. Three archetypes dominate: integrated agribusiness conglomerates, specialized flavor and texture houses, and fermentation-technology platforms. Competitive moves concentrate on backward integration into raw material supply and geographic expansion of application laboratory networks.
Within the integrated agribusiness tier, Cargill, Incorporated and Archer Daniels Midland Company exemplify supply chain control strategies that span sweetener procurement through finished additive delivery. Tate & Lyle occupies a position among texture and stabilization specialists, representing the formulation-science archetype that beverage manufacturers engage for reduced-sugar system development. Kerry Group anchors the service-intensive segment, with its application lab model exemplifying how technical embedding secures procurement relationships in premium beverage segments.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| Archer Daniels Midland Company |
| DuPont |
| Tate & Lyle |
| International Flavors & Fragrances Inc. |
| Ingredion Incorporated |
| Kerry Group |
| Givaudan |
| Chr. Hansen Holding A/S |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at Paraguayan stevia extraction facilities and Yunnan province glycoside processing plants anchors price floors for high-intensity sweeteners, concentrating procurement leverage among buyers with long-term offtake agreements while squeezing spot-market participants facing climate-driven supply volatility.
Pricing Analysis
Long-term offtake contracts dominate procurement for fermentation-derived sweeteners and botanical extracts, locking in volume commitments that insulate buyers from spot-price swings in agricultural inputs. Price differentiation rests on certification tier—FDA GRAS self-determination versus EFSA safety dossier—and geographic delivery cost from Yunnan or Paraguay to formulation centers in Germany or the United States. Pricing pressure stems from REACH authorization delays extending ECHA evaluation timelines, compressing margins for novel preservative introductions. Mass-market soda manufacturers exhibit highest price sensitivity, while energy drink formulators in Bavaria and North Rhine-Westphalia absorb premiums for stimulant-compatible clean-label systems.
Supply Chain Analysis
Inventory lead times for stevia glycosides now stretch eighteen to twenty-four months from Yunnan province harvest through extraction, purification, and global distribution, forcing beverage manufacturers to carry working capital buffers against climate volatility. Supply concentrates in Paraguay for natural extraction and China for both agricultural sourcing and fermentation platforms, with Germany anchoring European formulation services. Raw material dependencies span stevia leaf supply, fermentation feedstocks, and supercritical CO2 for botanical processing. Single-source vulnerability in Yunnan glycoside extraction exposes procurement to drought-induced crop failure. Distribution runs through direct supplier-manufacturer relationships in premium segments, retaining distributor mediation for cost-sensitive preservative and colorant categories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense as precision fermentation platforms displace agricultural extraction for nature-identical compounds, threatening incumbent positioning built on captive leaf supply and regional processing assets.
For Market Incumbents: Shield formulation service relationships by embedding application laboratories in Maharashtra and Karnataka before FSSAI modernization attracts competitor technical facilities. Backward integration into fermentation capacity secures supply continuity against Yunnan climate exposure, while accelerating dossier preparation for EFSA preservative safety revisions defends existing product registrations from regulatory invalidation. For New Entrants and Emerging Players: FDA GRAS self-determination fast-tracks market entry for fermentation-derived sweeteners targeting soda reformulation in California and New York Metro, bypassing EFSA's eighteen-to-thirty-six-month evaluation windows. India's underpenetrated formulation services for functional beverages offer white-space expansion, with technical partnerships in Mumbai bridging agricultural extraction heritage to precision fermentation adoption timelines. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors fermentation-technology platforms with dual agricultural and biomanufacturing supply lines over pure-play extraction specialists tethered to single-origin leaf supply. Long-term viability hinges on regulatory arbitrage capabilities across FDA, EFSA, and SAMR frameworks. Monitor EFSA clean-label definition revisions as inflection indicator for accelerated reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Capacity Buildout | Biomanufacturing platforms in Shanghai and Guangzhou bypass Yunnan climate volatility for supply security. |
| Application Laboratory Geographic Expansion | Technical embedding in Campinas and Ribeirão Preto clusters addresses Brazil's food chemist scarcity. |
| Regulatory Dossier Acceleration | Early EFSA submission for novel preservatives compresses eighteen-to-thirty-six-month REACH authorization timelines. |
| Direct Supplier-Manufacturer Relationships | Displacing distributor mediation captures shelf-price premiums in Western European clean-label segments. |
| Postbiotic Platform Development | Heat-inactivated microbial preparations unlock ambient beverage functional claims beyond live-culture stability constraints. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with beverage formulation scientists, procurement directors at multinational soda and energy drink manufacturers, FSSAI regulatory affairs specialists, and technical directors at sweetener extraction facilities; and secondary validation through FDA GRAS notices, EFSA scientific opinions, SAMR GB standard publications, and customs trade data for stevia glycoside flows. Bottom-up triangulation across ingredient-level procurement patterns and top-down reconciliation against national sugar reduction mandate implementation timelines anchored volume and value estimates.
Across the analysis window, the forecasting framework modeled additive demand by product type, application intensity, form factor, and end-user technical service requirements, with CAGRs derived from regulatory-driven reformulation cycle compression and clean-label adoption curves. Segment-level projections incorporated EFSA preservative safety reassessment timelines, Mercosur harmonization enforcement by ANVISA, and PLI scheme incentive uptake in Maharashtra and Karnataka.
Decision-makers should treat outputs as directional under assumptions of continued sugar reduction mandate expansion and stable fermentation technology cost curves; material deviation in regulatory ambiguity resolution or climate-induced crop failure would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Africa Food Hydrocolloids Market
Food Additives and Ingredients
Beverage Clouding Agent Market
Food Additives and Ingredients
Argentina Food Enzymes Market
Food Additives and Ingredients
Acetylated Monoglycerides (AMG) Market
Food Additives and Ingredients
Global Wood-Derived Food Additives Market
Food Additives and Ingredients
Europe Food Enzymes Market
Food Additives and Ingredients
Gardenia Food Color Market
Food Additives and Ingredients
Bakery Stabilizers Market
Food Additives and Ingredients
Asia- Pacific Food Micronized Salt Market
Food Additives and Ingredients
Food Clarifiers Market
Food Additives and Ingredients
China Food Additives Market
Food Additives and Ingredients
Clean Label Ingredients Market
Food Additives and Ingredients
Plant Based Preservatives Market
Food Additives and Ingredients
Food Binders Market
Food Additives and Ingredients
Lecithin Market
Food Additives and Ingredients
Africa Anti Caking Agent Market