
 Europe Leavening Agents Market | 2026-2036
Europe Leavening Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Leavening Agents Market Insights
Asset-light contract manufacturing and third-party fermentation leasing is reconfiguring capital deployment across the European leavening agents sector. Cargill Incorporated leverages its integrated grain processing network to secure upstream glucose supply for yeast cultivation. Kerry Group PLC anchors its position through specialized enzyme blends that reduce proofing time in industrial bakery settings.
Leavening agents are chemical or biological compounds that generate carbon dioxide gas within dough or batter matrices, typically functioning through acid-base reactions or microbial fermentation at controlled temperature and pH parameters to achieve specific crumb structure and volume expansion in baked goods. Baking powder maintains volume leadership across Western European retail channels due to its convenience in home baking applications, while yeast segments capture premium margins from artisan and industrial bakeries demanding extended fermentation flavor profiles. Liquid enzyme formulations are gaining traction among large-scale bread manufacturers seeking precise dosing control and reduced dust exposure in automated production lines.
EFSA's enzyme safety evaluations, EU Green Deal agricultural emission targets, and REACH chemical registration requirements collectively constrain novel ingredient introduction timelines while accelerating reformulation toward biodegradable processing aids. ECHA's classification criteria for respiratory sensitizers directly influence powder handling protocols in commercial baking facilities. Stakeholders must monitor pending amendments to the EU F-Gas Regulation that could alter industrial fermentation cooling economics.
Market Dynamics
Artisan bakery chains across Germany and France are consolidating procurement power, forcing leavening agent suppliers to reconfigure formulation services around clean-label specifications and extended fermentation protocols rather than commodity volume plays.
Growth Catalysts
- EFSA Enzyme Authorization Pathways:Streamlined safety evaluations for novel fermentation enzymes are accelerating product registration timelines for industrial bakeries seeking reduced-proofing solutions.
- Southern European Commercial Baking Clusters:Concentrated demand from Spain and Italy's industrial bread manufacturers is pulling powdered yeast volumes upward through centralized purchasing cooperatives.
- Clean-Label Sourcing Mandates:German and French retail chains are specifying additive-free leavening systems, creating formulation pull-through for minimally processed yeast derivatives and natural acidulants.
Market Restraints
- Molasses Supply Concentration:Upstream glucose feedstock for yeast cultivation depends on beet sugar processing capacity concentrated in northern France and eastern Germany, exposing margins to agricultural yield volatility.
- REACH Chemical Registration:Novel acid-base leavening compounds face extended toxicity testing timelines and registration fees that freeze SME innovation budgets.
- Compressed Air Refrigeration Economics:Pending EU F-Gas Regulation amendments threaten to raise cooling costs for industrial fermentation tanks, squeezing bulk yeast production margins.
Strategic Opportunities
- Polish and Romanian Industrial Bakery Expansion:Underpenetrated central European markets present volume growth potential as pan-European retailers localize bread production in lower-cost manufacturing zones.
- Liquid Enzyme Dosing Systems:Automated precision-delivery technology is opening retrofit opportunities in aging Northern European bread plants seeking dust exposure reduction and labor cost compression.
- EU Green Deal Agricultural Emissions Targets:Biodegradable processing aid mandates are creating preferential procurement pathways for fermentation-derived leavening agents over synthetic chemical alternatives.
Industry Challenges
- Fermentation Microbiology Talent Scarcity:Industrial yeast strain optimization requires specialized phD-level expertise that bakery ingredient suppliers struggle to retain against pharmaceutical and biotech poaching.
- Legacy Powder Handling Infrastructure:Retrofitting commercial baking facilities for liquid enzyme delivery demands capital-intensive pneumatic system overhauls that mid-sized cooperatives defer.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Leavening Agents Market |
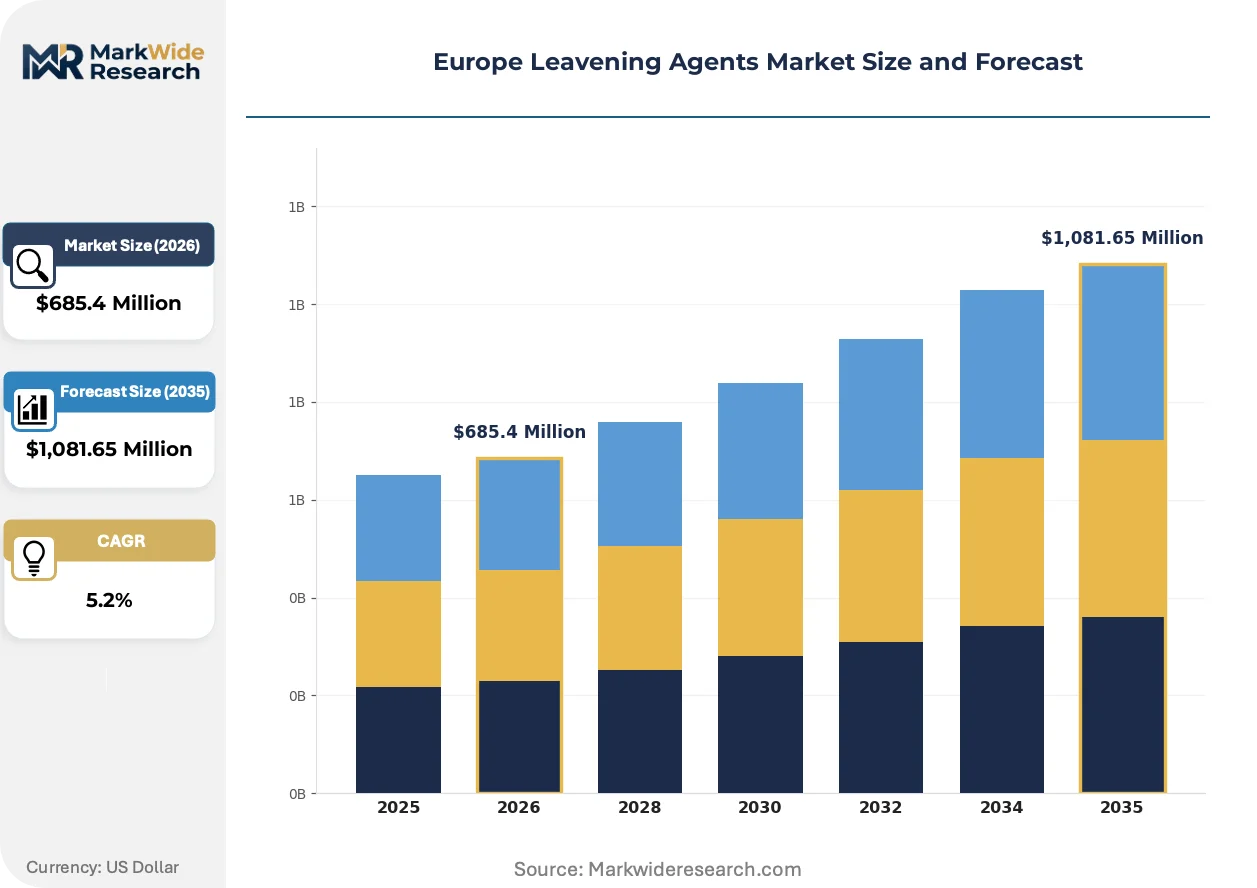
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,081.65 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Baking Powder, Yeast, Baking Soda, Cream of Tartar Application: Bread, Cakes, Pastries, Cookies Form: Powder, Liquid, Granular, Paste Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Wholesale |
| Companies Covered | Cargill Incorporated, Kerry Group PLC, Associated British Foods PLC, Puratos Group NV, Koninklijke DSM NV, Archer Daniels Midland Company, Novozymes A/S, Lesaffre Group, Corbion NV, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Leavening Agents Market Trends and Innovations
Biotechnology convergence with traditional baking science is compressing product development cycles and blurring boundaries between commodity yeast supply and specialized enzyme services across European industrial bakery procurement.
Targeted enzyme cocktails combining amylases, xylanases, and lipases are hybridizing conventional yeast fermentation with accelerated proofing control. Large-scale bread manufacturers in the Netherlands and Belgium are adopting these systems at pilot scale. The technology is hybridizing the historical separation between chemical leavening speed and biological flavor development into unified processing platforms.
REACH registration requirements for respiratory sensitizers are forcing reformulation of powdered baking aids across commercial facilities. ECHA classification criteria now mandate enclosed handling systems for high-dust leavening products. Industrial bakeries in northern Germany are responding by accelerating liquid enzyme conversion timelines and suspending powder line expansions.
Consolidated procurement by pan-European retail chains is compressing supplier negotiation cycles from annual to quarterly frameworks. Category managers at centralized buying desks in Paris and Munich are unbundling technical service contracts from ingredient supply agreements. This pattern is most visible in the German discount retail channel, where private-label bread programs now specify dedicated fermentation technical support as a separate line item.
Europe Leavening Agents Market Segmentation
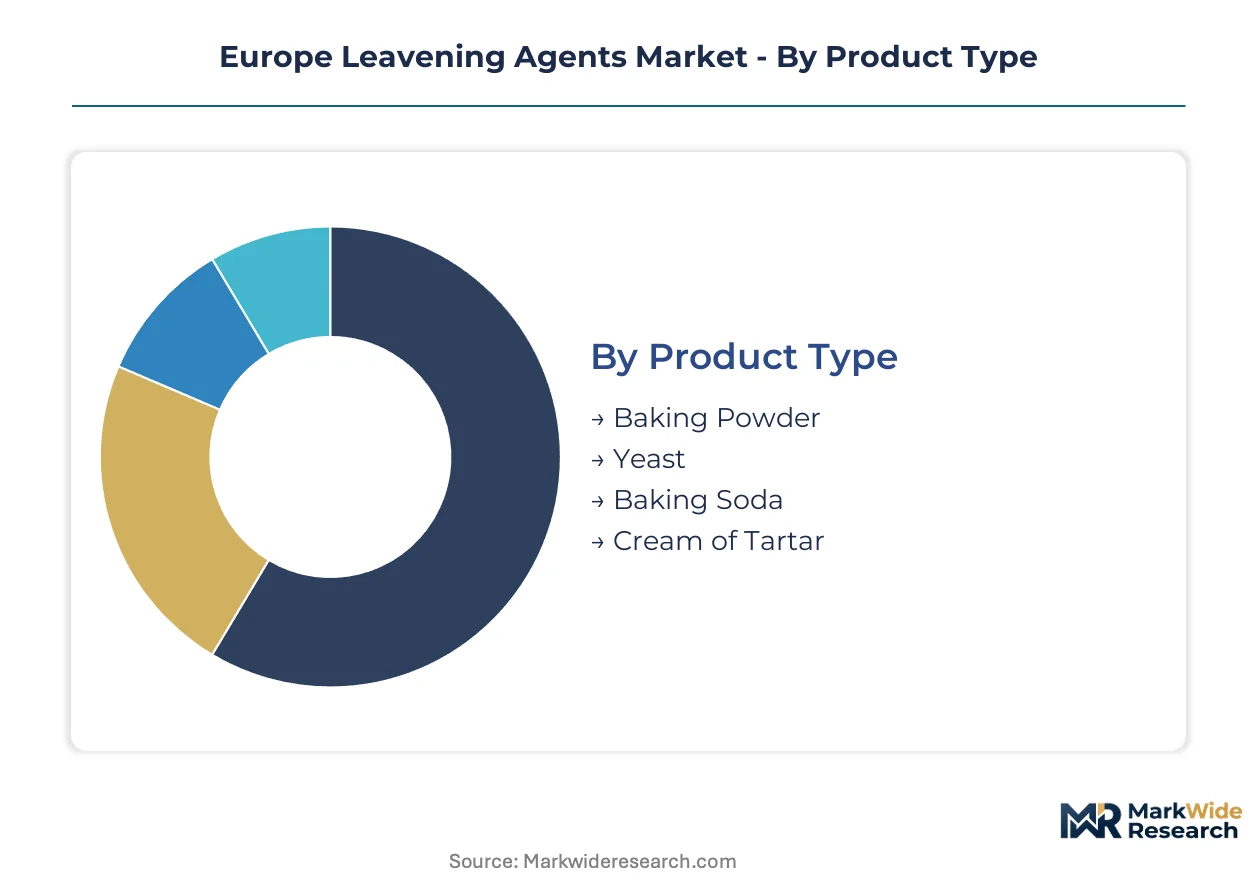
Leavening agent procurement patterns diverge sharply between industrial bakeries optimizing for throughput and artisan producers prioritizing fermentation complexity. Segment boundaries increasingly blur as enzyme-enhanced yeast hybrids and liquid dosing systems reshape traditional category definitions across European commercial baking.
Product Type:
Cost tier stratification separates commodity chemical leaveners from premium biological fermentation systems, with procurement budgets allocating disproportionately to yeast derivatives in high-margin applications.
- Yeast:Living Saccharomyces cerevisiae cultures generate carbon dioxide through controlled glucose metabolism, producing extended fermentation flavor profiles prized by German and French artisan bakery chains. Clean-label mandates from centralized retail buyers in Paris and Munich are accelerating demand for minimally processed yeast derivatives over chemical alternatives.
- Baking Powder:Dual-action sodium bicarbonate and acid phosphate compounds release carbon dioxide through moisture-activated and heat-triggered reactions. Western European retail channels favor this format for home baking convenience, though ECHA respiratory sensitizer classifications are forcing enclosed handling investments in commercial facilities.
- Baking Soda:Single-acting sodium bicarbonate requires acidulants for gas release, limiting standalone utility in neutral batters.
- Cream of Tartar:Potassium bitartrate acidulant stabilizes egg whites and activates baking soda in specialty confectionery applications.
Yeast commands the established base. The steepest expansion runs through enzyme-enhanced yeast hybrids compressing proofing timelines.
Application:
Volume concentration maps directly to per-capita bread consumption patterns and industrial bakery infrastructure density across the continent.
- Bread:Industrial pan bread manufacturing in the Netherlands and Belgium consumes bulk yeast volumes through automated fermentation systems. Spanish and Italian commercial baking clusters are consolidating procurement through centralized purchasing cooperatives, pulling powdered yeast demand upward.
- Cakes:Chemical leavening dominates sponge and layer cake production where rapid gas release and neutral flavor profiles prove essential.
- Pastries:Laminated dough applications demand precise leavening control to preserve butter layer integrity during thermal expansion.
- Cookies:Minimal leavening requirements in dense, short-textured formats limit per-unit ingredient intensity despite high production volumes.
Bread anchors volume procurement. The steepest expansion trajectory belongs to laminated pastries as premium viennoiserie consumption climbs in urban Polish and Romanian markets.
Form:
Supply concentration in Northern European production hubs shapes format availability and handling infrastructure investments downstream.
- Powder:Standardized particle-size distributions enable precise dosing in high-throughput bread plants, though REACH registration requirements for respiratory sensitizers are accelerating conversion timelines.
- Liquid:Enzyme suspensions and yeast creams enable automated precision delivery with reduced dust exposure. Northern German industrial bakeries are retrofitting pneumatic systems to accommodate liquid dosing as ECHA classification criteria tighten.
- Granular:Intermediate moisture formats bridge powder convenience with liquid stability for mid-scale cooperatives deferring capital-intensive infrastructure overhauls.
- Paste:Compressed yeast blocks serve artisan bakers requiring extended fermentation control unavailable in dried alternatives.
Powder formats retain the installed base. The steepest expansion runs through liquid enzyme systems as labor cost compression and safety compliance converge.
Distribution Channel:
Customer type fragmentation separates consolidated industrial procurement from fragmented retail and foodservice purchasing patterns.
- Wholesale:Direct supply agreements with industrial bakery conglomerates in Germany and France concentrate volume through annual framework contracts with embedded technical service provisions.
- Supermarkets:Private-label bread programs at German discount retailers now unbundle fermentation technical support from ingredient supply, compressing supplier negotiation cycles to quarterly frameworks.
- Online Retail:Specialty yeast strains and clean-label baking powders reach home bakers and small artisan producers outside concentrated industrial supply networks.
- Specialty Stores:Professional bakery supply outlets serve artisan producers requiring technical consultation and small-batch format flexibility.
Wholesale channels command the established base. The steepest expansion runs through supermarket private-label programs as pan-European retail chains localize bread production in lower-cost manufacturing zones.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial bakery procurement desks in Germany and France concentrate buying power, while commercial baking clusters in Southern and Central Europe pull differentiated format demand through specialized distribution channels.
Germany
Discount retail chains in Munich and Berlin unbundle fermentation technical support from ingredient supply agreements. EFSA enzyme authorization protocols streamline novel product registrations for industrial bakeries seeking reduced-proofing systems. The North Rhine-Westphalia corridor hosts concentrated yeast cultivation capacity serving pan-European wholesale channels.
France
Artisan bakery chains in Paris specify clean-label sourcing mandates that favor minimally processed yeast derivatives over chemical alternatives. REACH registration requirements for respiratory sensitizers accelerate liquid enzyme conversion timelines in commercial facilities. The Grand Est region anchors beet sugar processing capacity supplying upstream glucose feedstock for fermentation operations.
Italy
Centralized purchasing cooperatives in Milan and Bologna consolidate powdered yeast procurement for industrial bread manufacturers. EU Green Deal agricultural emission targets favor biodegradable processing aids in large-scale baking operations. The Po Valley commercial baking cluster drives volume demand through automated fermentation systems.
Spain
Industrial bread producers in Barcelona and Madrid expand capacity to serve localized production for pan-European retail chains. ECHA classification criteria for powder handling tighten safety protocols in aging commercial facilities. The Mediterranean corridor concentrates demand for extended-fermentation flavor profiles in artisan applications.
Poland
Underpenetrated industrial bakery infrastructure in Warsaw and Łódź presents volume growth potential as retailers localize bread production. Pending EU F-Gas Regulation amendments threaten cooling cost economics for fermentation tank operations. Lower-cost manufacturing zones attract pan-European bakery conglomerates seeking procurement efficiency.
Europe Leavening Agents Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered procurement frameworks. The supplier base concentrates around integrated grain processors, specialized enzyme houses, and fermentation biotechnology firms. Three archetypes dominate: upstream-integrated agricultural conglomerates, enzyme technology specialists, and dedicated yeast cultivation enterprises. Competitive moves center on backward integration into glucose feedstock supply and portfolio diversification toward liquid enzyme delivery systems.
Among upstream-integrated processors, Cargill Incorporated and Archer Daniels Midland Company represent the agricultural conglomerate archetype with captive grain processing networks. Kerry Group PLC and Novozymes A/S exemplify the enzyme technology specialist tier, while Lesaffre Group anchors the dedicated fermentation segment. These named entities occupy positions that reflect broader structural patterns in European leavening agent supply rather than discrete strategic postures.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Kerry Group PLC |
| Associated British Foods PLC |
| Puratos Group NV |
| Koninklijke DSM NV |
| Archer Daniels Midland Company |
| Novozymes A/S |
| Lesaffre Group |
| Corbion NV |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Northern European yeast cultivation facilities is compressing spot pricing for bulk fermentation products while forcing suppliers toward long-term offtake commitments with industrial bakery conglomerates. This utilization dynamic rewards backward-integrated grain processors with captive glucose supply and squeezes standalone fermentation houses exposed to volatile beet sugar feedstock costs.
Pricing Analysis
Cost-plus contracts indexed to EU beet sugar futures dominate bulk yeast procurement between Northern European suppliers and industrial bakery conglomerates. Three-tier pricing structure across premium enzyme-enhanced, standard active-dried, and economy compressed yeast formats reflects fermentation complexity and proofing performance differentiation. Pricing pressure stems from consolidated retail procurement desks in Germany and France unbundling technical service fees from ingredient supply. Small artisan cooperatives exhibit highest price sensitivity, while pan-European industrial bakeries prioritize supply security over unit cost optimization.
Supply Chain Analysis
Contract-manufacturing concentration among dedicated fermentation houses in France, Germany, and the Netherlands controls active yeast capacity for European industrial baking. Upstream glucose feedstock draws from beet sugar processing clusters in northern France and eastern Germany, with molasses supply tethered to agricultural yield cycles. Single-source vulnerability runs through concentrated beet sugar processing capacity exposed to climate-driven harvest volatility. Distribution runs through wholesale channels serving industrial bakery conglomerates alongside specialty stores supplying artisan producers requiring technical consultation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from a cyclical trough driven by post-pandemic artisan bakery expansion and reformulation demand from clean-label retail mandates. The recovery trajectory hinges on sustained investment in liquid enzyme delivery infrastructure and fermentation biotechnology talent retention.
For Market Incumbents: Harden supply security through backward integration into beet sugar processing capacity or long-term molasses offtake agreements with Grand Est and eastern German agricultural cooperatives. Deepen technical service capabilities to defend against unbundling pressure from centralized retail procurement desks in Paris and Munich. Prioritize liquid enzyme dosing system investments to capture retrofit demand from Northern European industrial bakeries facing ECHA respiratory sensitizer compliance deadlines.
For New Entrants and Emerging Players: Establish a beachhead in Polish and Romanian industrial bakery markets where localized production for pan-European retail chains is expanding fastest. Target enzyme-enhanced yeast hybrid formulations for mid-scale cooperatives seeking proofing acceleration without full liquid infrastructure overhaul. Lead with automated precision-delivery technology partnerships to differentiate from incumbent commodity suppliers.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across liquid enzyme production and automated dosing system manufacturing, favoring asset-light fermentation biotechnology specialists over heavy infrastructure plays. Over a five-to-ten-year horizon, acquisition value concentrates in specialized enzyme houses with strain optimization IP and established industrial bakery technical service relationships. Monitor quarterly EFSA enzyme authorization timelines as the critical signal for product registration velocity and competitive positioning shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Glucose Feedstock | Cargill's captive grain processing network secures upstream supply against beet sugar volatility. |
| Liquid Enzyme Dosing System Deployment | Automated precision delivery reduces dust exposure and labor costs in Northern German industrial bakeries. |
| Clean-Label Yeast Derivative Development | Minimally processed fermentation products align with EFSA authorization pathways and retail chain mandates. |
| Central European Manufacturing Localization | Polish and Romanian production expansion captures pan-European retailer procurement efficiency drives. |
| Enzyme-Enhanced Hybrid Formulation Launch | Targeted amylase-xylanase cocktails compress proofing timelines while preserving biological flavor development. |
Research Methodology
The analysis maps yeast cultivation, enzyme formulation, and chemical leavening sub-sectors, each validated through primary interviews with industrial bakery procurement directors, fermentation plant managers, and retail category buyers. Secondary validation draws from EFSA enzyme authorization databases, EU customs trade statistics for molasses and active yeast, SEC filings of listed ingredient suppliers, and Cefic chemical industry reports. Bottom-up volume modeling from individual production facilities triangulates against top-down expenditure analysis from pan-European retail chain procurement disclosures.
Assumptions held fixed across the projection horizon include EFSA regulatory frameworks, EU Green Deal agricultural emission targets, and REACH chemical registration requirements. Segmentation dimensions modeled encompass product type, application, form, and distribution channel, with additional granularity on enzyme-enhanced versus conventional fermentation systems. CAGRs derive from regression analysis of historical procurement patterns and elasticity estimates from industrial bakery capacity expansion announcements. Forecast inputs incorporate beet sugar yield projections and pan-European retail chain localization timelines.
Sensitivities concentrate around EFSA enzyme authorization delays, EU F-Gas Regulation amendments affecting fermentation cooling economics, and climate-driven beet sugar harvest volatility. Forecasts reflect documented assumptions subject to revision from regulatory shifts or agricultural supply disruptions. Quarterly review of EFSA authorization timelines, EU agricultural emission compliance deadlines, and industrial bakery capacity utilization indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Agar Agar Gum Market
Food Additives and Ingredients
Argentina Food Enzymes Market
Food Additives and Ingredients
Food Grade Potassium Sorbate Market
Food Additives and Ingredients
China Food Enzymes Market
Food Additives and Ingredients
Fruit and Vegetable Processing Enzymes Market
Food Additives and Ingredients
Mexico Food Preservatives Market
Food Additives and Ingredients
Natural Food Preservatives Market
Food Additives and Ingredients
Italy Food Acidulants Market
Food Additives and Ingredients
Russia Food Acidulants Market
Food Additives and Ingredients
Plant-Based Emulsifiers Market
Food Additives and Ingredients
Flour Treatment Agent Market
Food Additives and Ingredients
Italy Sodium Reduction Ingredients Market
Food Additives and Ingredients
United States Food Acidulants Market
Food Additives and Ingredients
Argentina Gellan Gum Market
Food Additives and Ingredients
PVPP Beer Stabilizer Market
Food Additives and Ingredients
Leavening Acids Market