
 United States Soy Beverages Market | 2026-2036
United States Soy Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
United States Soy Beverages Market Analytics
Buyer concentration among health food retailers is repositioning procurement power toward specialty grocers and direct-to-consumer channels. Danone leverages its refrigerated distribution network to dominate conventional retail placement. The Hain Celestial Group sustains shelf presence through organic certification depth. Eden Foods specializes in aseptic packaging formats that extend shelf stability without preservatives.
Soy beverages comprise aqueous extracts of whole soybeans or soy protein isolates, typically fortified with calcium, vitamin D, and B12 to match dairy nutritional profiles, produced through enzymatic hydrolysis and ultra-high temperature processing for microbial safety. Their primary commercial purpose is delivering complete plant protein for consumers excluding animal products. Unflavored varieties anchor volume due to formulation flexibility in cooking applications, while chocolate and vanilla segments capture premium positioning through indulgence positioning. Cartons and Tetra Packs control ambient distribution economics, though bottle formats compete in refrigerated premium tiers where visual differentiation commands attention.
FDA enforces allergen labeling under FALCPA, compelling prominent soy disclosure that shapes consumer trust architecture. USDA organic standards govern ingredient sourcing for certified products, creating tiered market access based on farm-level compliance investment. State-level nutrition procurement policies in California and New York schools expand institutional volume channels. Stakeholders must monitor evolving plant protein health claims litigation and clean label certification proliferation as determinants of competitive positioning.
Market Dynamics
FDA allergen labeling mandates under FALCPA have reconfigured how soy beverage manufacturers architect consumer trust, forcing prominent soy disclosure that shapes formulation transparency and retail placement negotiations with conventional grocers.
Growth Catalysts
- USDA Organic Certification:Farm-level compliance investment creates tiered market access, with certified products commanding shelf priority in specialty retail channels across California and the Pacific Northwest.
- Fitness and Wellness Programs:Health-conscious consumers in structured exercise regimens drive adoption of complete plant protein formats, particularly unflavored varieties with formulation flexibility.
- Enzymatic Hydrolysis:This processing technology enables ultra-high temperature treatment for microbial safety while preserving nutritional integrity, supporting ambient distribution economics.
Market Restraints
- Soy Protein Isolate Input Volatility:Concentrated supply of high-purity protein inputs exposes manufacturers to agricultural commodity price swings and crop yield uncertainty.
- Pacific Northwest Production Clustering:Geographic concentration of plant-based food manufacturing creates regional supply vulnerability to climate disruption and logistics congestion.
- Almond and Oat Substitution:Alternative plant milks with milder flavor profiles and lower allergen concerns erode soy beverage share in premium refrigerated tiers.
Strategic Opportunities
- California and New York School Nutrition Procurement:State-level institutional volume channels expand through mandated plant-based options in public education foodservice programs.
- Aseptic Packaging Convergence:Tetra Pak and carton format innovation combined with extended shelf stability technology opens ambient distribution into convenience retail and foodservice.
- Direct-to-Consumer Subscription:Bypassing conventional retail slotting fees through refrigerated delivery networks captures margin and builds brand loyalty among urban health-conscious households.
Industry Challenges
- Clean Label Certification Timeline:Multiple overlapping third-party verification programs create compliance complexity and extended product launch cycles.
- Refrigerated Distribution Infrastructure:Cold chain capital requirements constrain regional expansion for premium bottle formats competing in visual differentiation tiers.
- Plant Protein Health Claims Litigation Risk:Evolving judicial interpretation of nutritional equivalence statements demands legal review of all marketing copy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Soy Beverages Market |
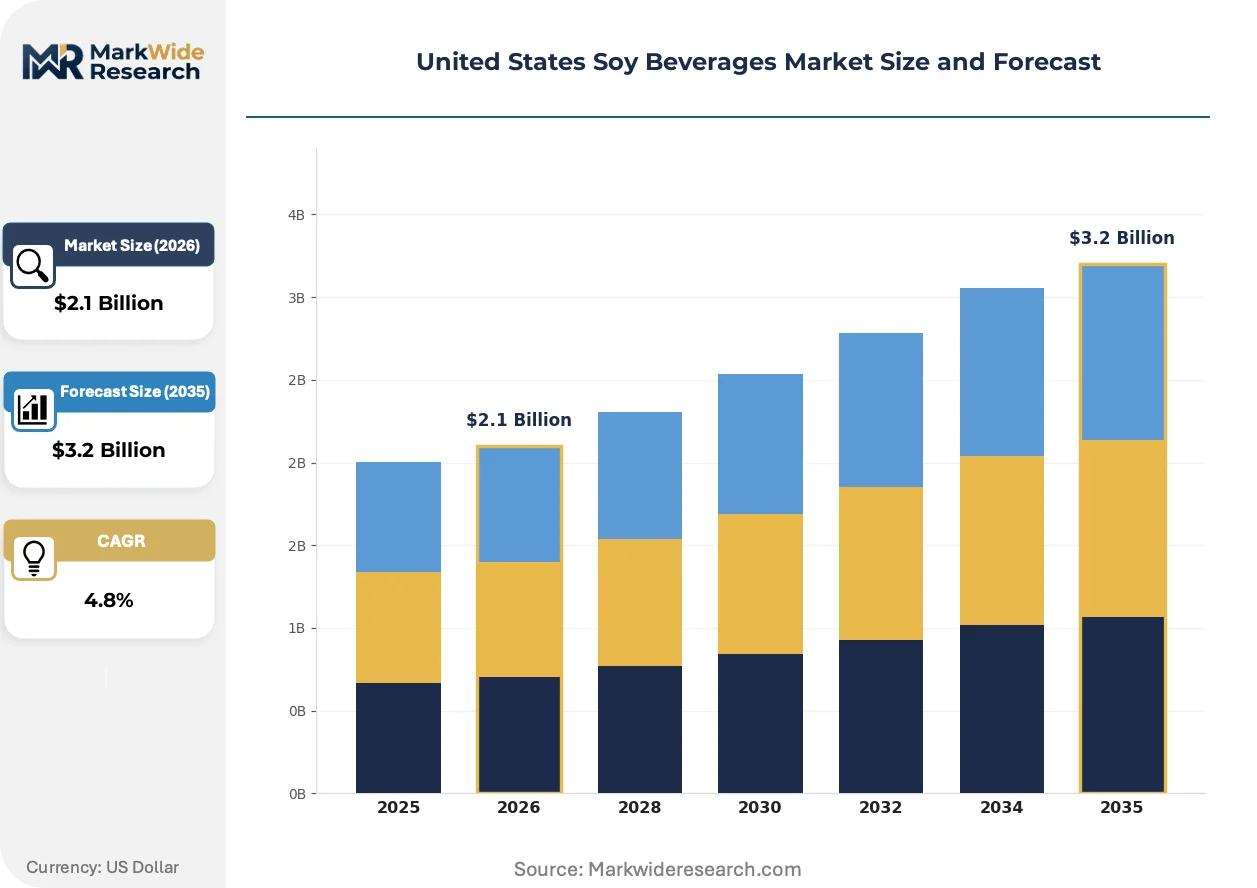
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.2 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Unflavored, Vanilla, Chocolate, Sweetened End User: Health-conscious Consumers, Vegans, Lactose-intolerant Individuals, Athletes Packaging Type: Cartons, Bottles, Tetra Packs, Pouches Distribution Channel: Supermarkets, Health Food Stores, Online Retailers, Convenience Stores |
| Companies Covered | Danone, The Hain Celestial Group, Eden Foods, Pacific Foods of Oregon, Kikkoman, Stremicks Heritage Foods, SunOpta, Earth's Own Food Company, Alpro, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Soy Beverages Market Evolving Landscape
Processing technology and packaging format innovation are compressing the boundary between ambient and refrigerated distribution economics, while regulatory pressure on transparency accelerates clean label proliferation.
Enzymatic hydrolysis paired with ultra-high temperature processing is absorbing the technical trade-off between nutritional retention and shelf stability. Mid-sized manufacturers in the Pacific Northwest are adopting these systems at accelerated pace to compete with established refrigerated networks. The technology is absorbing capital that previously flowed into conventional pasteurization equipment, reshaping facility investment priorities.
FDA enforcement of FALCPA allergen disclosure requirements has tightened labeling specifications for soy-derived products. This regulatory pressure forces reformulation of legacy packaging designs and renegotiation of retail placement agreements. Conventional grocery chains in California are responding by consolidating shelf space toward brands with pre-compliant labeling architectures.
Buyer concentration among health food retailers has compressed procurement cycles and shifted volume toward specialty grocers with dedicated plant-based sets. Direct sourcing agreements are displacing traditional distributor relationships in metropolitan markets. This pattern is most visible in Los Angeles and Seattle, where regional chains have built captive refrigerated logistics for ambient-to-cold product transitions.
United States Soy Beverages Market Segmentation
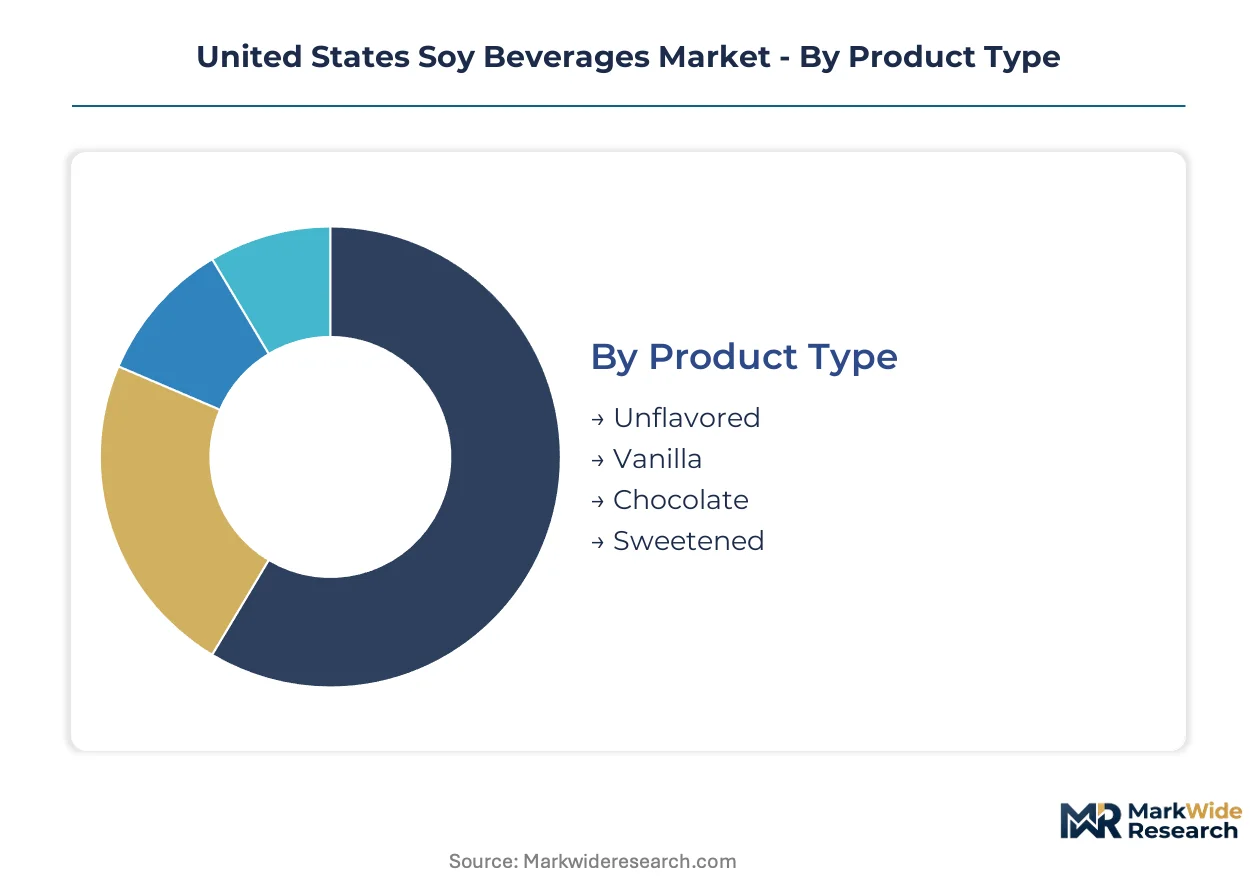
Segmentation in the United States soy beverages market reveals how FDA allergen labeling and USDA organic certification create divergent compliance burdens across product tiers. Manufacturers must architect formulations and packaging strategies around these regulatory fault lines to secure shelf placement in California's specialty retail clusters and conventional grocery channels.
Product Type:
USDA organic certification requirements and FDA FALCPA allergen disclosure mandates reshape formulation economics differently across flavor profiles, with unflavored varieties facing simpler additive compliance while flavored segments navigate compounded ingredient verification.
- Unflavored:Aqueous soy extract without added flavoring agents, typically fortified with calcium and vitamins D and B12 to match dairy nutritional equivalence. Demand concentrates in Pacific Northwest metropolitan households with formulation flexibility for cooking applications, driven by clean label preferences and institutional procurement specifications in California and New York school nutrition programs.
- Vanilla:Soy base with natural or artificial vanilla flavoring, often carrying higher organic certification costs due to multi-ingredient supply chain verification. Premium positioning in refrigerated retail tiers commands visual differentiation through bottle formats, though ambient cartons capture volume in conventional grocery ambient sets.
- Chocolate:Cocoa-infused formulation targeting indulgence positioning with elevated sugar content and corresponding nutritional panel complexity.
- Sweetened:Added sugar variants requiring enhanced FDA labeling compliance around total sugars disclosure under updated nutrition facts requirements.
Unflavored sits at the top of the volume ranking, with vanilla climbing the fastest.
End User:
Customer archetypes distribute across distinct channel preferences and price sensitivity thresholds, with institutional buyers and direct-to-consumer households creating divergent margin structures.
- Health-conscious Consumers:Fitness-oriented households prioritizing complete plant protein intake, concentrated in urban coastal markets with subscription delivery adoption.
- Vegans:Strict plant-based diet adherents requiring B12 fortification verification and ethical sourcing transparency, driving certified organic premiumization.
- Lactose-intolerant Individuals:Dairy-averse consumers seeking nutritional equivalence without allergen concerns, representing stable baseline demand in conventional retail.
- Athletes:Structured exercise participants in protein-targeted regimens, expanding most quickly through specialty sports nutrition channels and direct-to-consumer platforms.
Health-conscious consumers anchor current volume, while athletes gain share fastest.
Packaging Type:
Format selection determines cold chain capital requirements and shelf stability technology investments, compressing margin profiles across ambient and refrigerated distribution economics.
- Cartons:Paperboard-based containers with polyethylene lining, dominating ambient distribution economics through conventional grocery supply chains.
- Bottles:PET or HDPE formats requiring refrigerated infrastructure, commanding premium positioning through visual transparency and brand differentiation in Los Angeles and Seattle metropolitan retail.
- Tetra Packs:Aseptic laminated carton systems enabling extended shelf stability without preservatives, opening foodservice and convenience retail penetration.
- Pouches:Flexible film formats emerging in single-serve and on-the-go consumption occasions, constrained by limited retail slotting acceptance.
Cartons maintain volume leadership, with Tetra Packs expanding most rapidly.
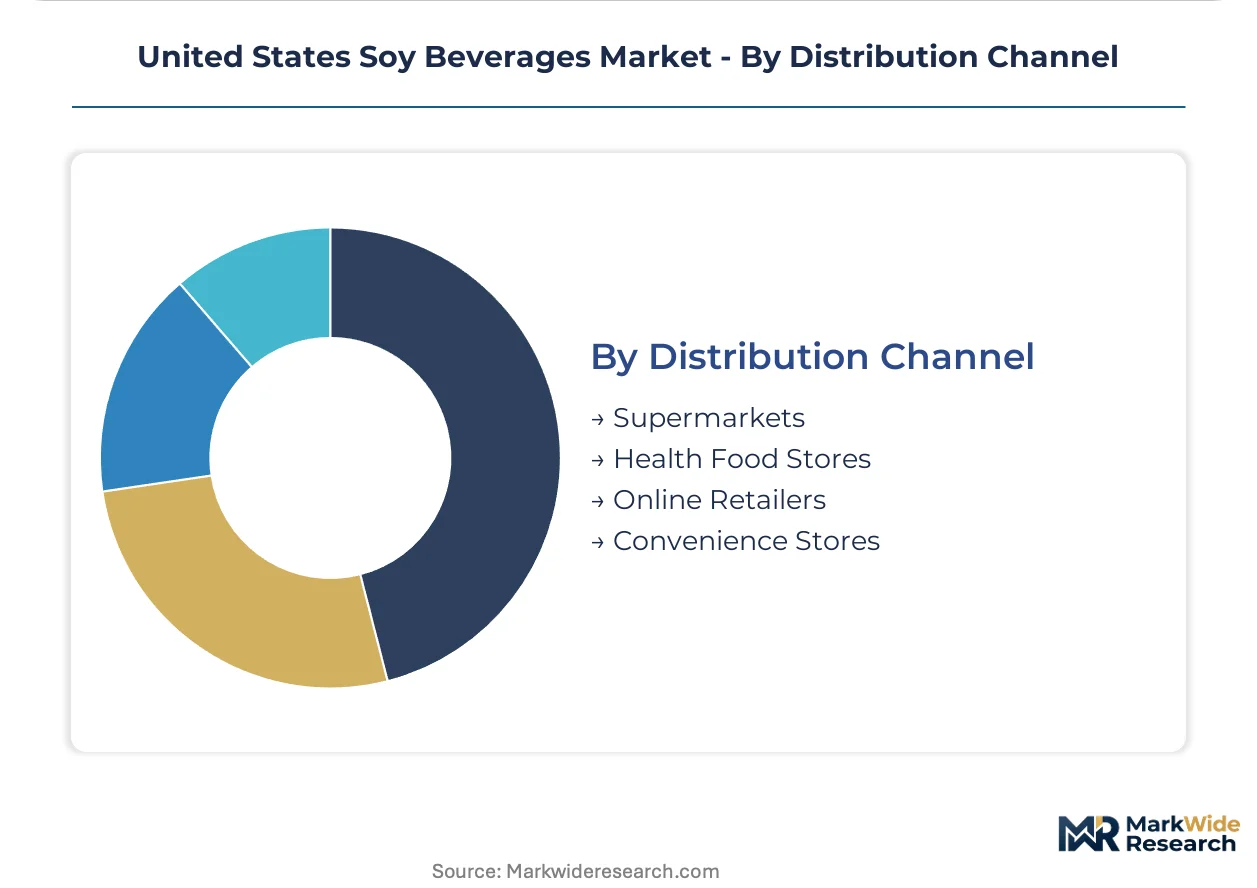
Distribution Channel:
Channel concentration patterns reflect procurement power shifts, with specialty retail consolidation and direct sourcing agreements displacing traditional distributor relationships in metropolitan markets.
- Supermarkets:Conventional grocery chains with consolidated shelf space toward FALCPA-pre-compliant labeling architectures, particularly in California retail consolidation.
- Health Food Stores:Specialty retailers with dedicated plant-based sets and captive refrigerated logistics, concentrated in Pacific Northwest urban clusters.
- Online Retailers:E-commerce platforms enabling direct-to-consumer subscription bypassing slotting fees, capturing margin in urban health-conscious households.
- Convenience Stores:Ambient-focused channels leveraging Tetra Pack shelf stability for grab-and-go positioning, constrained by refrigerated infrastructure limitations.
Supermarkets dominate volume, with online retailers climbing fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California commands disproportionate shelf space allocation compared to Texas, where refrigerated infrastructure gaps constrain premium format penetration despite comparable population density.
California
Los Angeles and San Francisco metropolitan clusters anchor institutional procurement through state-mandated school nutrition programs expanding plant-based options. FDA FALCPA allergen disclosure requirements shape retail consolidation toward pre-compliant labeling architectures. The Central Valley soy processing corridor supplies ingredient inputs to Sacramento-area formulation facilities.
Pacific Northwest
Seattle and Portland urban households drive subscription delivery adoption for unflavored varieties with cooking flexibility. USDA organic certification standards govern sourcing from Willamette Valley farm cooperatives. Regional specialty grocers have built captive refrigerated logistics enabling ambient-to-cold product transitions.
New York
New York City metro health-conscious consumers anchor direct-to-consumer channel growth bypassing conventional slotting fees. State-level school nutrition procurement policies expand institutional volume channels through mandated plant-based options. Brooklyn-based formulation startups compete with established distributors for refrigerated warehouse access.
Texas
Dallas and Houston metropolitan markets show emerging demand from fitness-oriented households in structured exercise regimens. Limited cold chain capital investment constrains premium bottle format distribution compared to coastal markets. Austin's plant-based food startup cluster sources aseptic packaging formats from out-of-state suppliers.
Midwest
Chicago anchors conventional grocery volume through carton-format ambient distribution economics. Illinois and Ohio school districts pilot USDA-compliant organic certification programs for institutional procurement. Detroit-area manufacturing facilities face refrigerated infrastructure gaps limiting premium tier competition with coastal markets.
United States Soy Beverages Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered shelf placement negotiations. Danone leverages refrigerated distribution networks to dominate conventional retail placement, while mid-sized organic specialists sustain presence through certification depth. The vendor base organizes around three strategic archetypes: multinational beverage conglomerates with cold chain assets, organic-certified regional specialists with aseptic packaging capabilities, and direct-to-consumer subscription operators bypassing slotting fees. Capacity expansion in enzymatic hydrolysis systems and strategic partnerships for Tetra Pak format access represent dominant competitive moves.
Within the multinational conglomerate tier, Danone occupies a position exemplifying refrigerated network leverage, while The Hain Celestial Group represents organic certification depth. Among Pacific Northwest-based specialists, Eden Foods and Pacific Foods of Oregon exemplify aseptic packaging format specialization. These anchors illustrate how geographic concentration of plant-based food manufacturing creates regional competitive dynamics distinct from national distribution scale advantages.
| Leading Market Players |
|---|
| Danone |
| The Hain Celestial Group |
| Eden Foods |
| Pacific Foods of Oregon |
| Kikkoman |
| Stremicks Heritage Foods |
| SunOpta |
| Earth's Own Food Company |
| Alpro |
| Others |
Value Network & Pricing Analysis
USDA organic certification requirements gate both qualified soy supply and premium-tier pricing access, with farm-level compliance investment creating a bifurcated market where certified organic inputs command shelf priority in California specialty retail while conventional formulations compete on ambient distribution economics.
Pricing Analysis
Capacity additions in the Pacific Northwest are reshaping price floors for aseptic packaging formats, compressing margins for legacy refrigerated bottle producers. Three-tier pricing structure across premium organic, standard conventional, and economy private-label levels stratifies the market, with certification grade and cold chain delivery cost as primary differentiation drivers. Pricing pressure stems from almond and oat milk substitution in premium refrigerated tiers, eroding soy's share and forcing cost compression. Institutional buyers in school nutrition programs exhibit highest price sensitivity, while direct-to-consumer subscription households show lowest sensitivity due to convenience premium acceptance.
Supply Chain Analysis
Workforce availability constraints in California's Central Valley soy processing corridor and the Pacific Northwest formulation cluster are tightening production scheduling flexibility. Supply concentrates in the United States, with secondary dependencies on Canadian organic soybean imports and Brazilian conventional inputs. Raw material sourcing draws from Willamette Valley farm cooperatives, Illinois commodity processors, and imported organic certifiers. Single-source vulnerability in Tetra Pak aseptic packaging equipment creates supply chain risk. Distribution runs through conventional grocery chains with consolidated shelf space, specialty retailers with captive refrigerated logistics, and direct-to-consumer platforms bypassing traditional distributor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
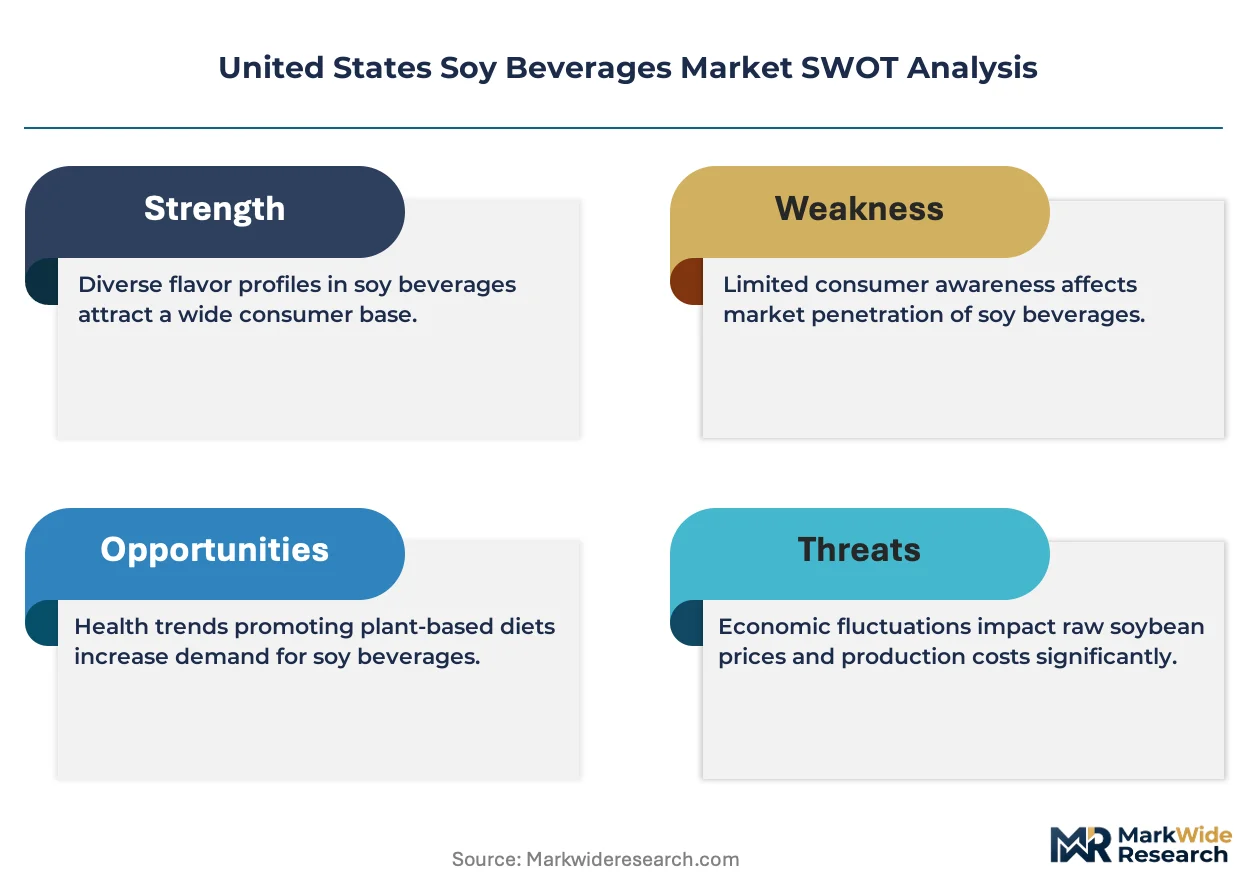
Margin expansion in United States soy beverages rests on enzymatic hydrolysis technology cost-down curves and the shift toward direct-to-consumer subscription tiers capturing full retail margin.
For Market Incumbents: Cement refrigerated network dominance by accelerating enzymatic hydrolysis capacity additions in the Pacific Northwest, defending against oat and almond substitution through formulation transparency investments. Prioritize USDA organic certification depth to maintain shelf priority in California specialty retail consolidation. Channel control through direct sourcing agreements with Los Angeles and Seattle metropolitan chains reinforces placement security against emerging aseptic packaging specialists. For New Entrants and Emerging Players: Direct-to-consumer subscription platforms offer the lowest barrier entry path, bypassing conventional retail slotting fees and capturing margin in urban health-conscious households. Target Texas metropolitan markets where refrigerated infrastructure gaps constrain incumbent premium format penetration. White-space exists in single-serve pouch formats for convenience retail, and in institutional procurement channels for USDA-compliant school nutrition programs. Aseptic packaging format specialization enables ambient distribution without cold chain capital requirements. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap organic-certified specialists because buyer concentration among health food retailers compresses procurement cycles and rewards scale in certification compliance. Long-term viability over the next decade hinges on enzymatic processing technology adoption and Tetra Pak format access. Acquisition target archetype: Pacific Northwest-based aseptic packaging specialists with Willamette Valley organic supply agreements. Watch plant protein health claims litigation resolution as inflection indicator for marketing copy risk and premium positioning stability.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Hydrolysis Capacity Expansion | Ultra-high temperature processing adoption preserves nutritional integrity while enabling ambient shelf stability without preservatives. |
| USDA Organic Certification Investment | Farm-level compliance creates tiered market access with shelf priority in California and Pacific Northwest specialty retail clusters. |
| Direct-to-Consumer Subscription Launch | Refrigerated delivery networks bypass conventional slotting fees and capture margin in urban health-conscious households. |
| Aseptic Packaging Format Development | Tetra Pak and carton innovation opens foodservice and convenience retail penetration without cold chain infrastructure. |
| State School Nutrition Procurement Capture | California and New York mandated plant-based options expand institutional volume channels through compliant formulation. |
Research Methodology
Bottom-up end-user modeling reconciled against top-down supply-side tracking forms the analytical core of this study. Primary interviews with brand managers at diversified beverage conglomerates, category buyers at specialty grocers, supply planners at organic certifiers, and channel sales heads at refrigerated distributors combined with secondary validation from FDA FALCPA filings, USDA organic certification databases, Nielsen retail audit data, and SEC 10-K disclosures from publicly traded parent companies. Triangulation across these sources ensures segmentation integrity.
Historical trendline analysis of volume and value trajectories across unflavored, vanilla, chocolate, and sweetened product types, combined with packaging format evolution and distribution channel shift patterns, established baseline growth parameters. Segmentation dimensions modeled include flavor profile, end-user archetype, packaging technology, and distribution channel, with regional regulatory cluster effects from California and New York school nutrition policies. CAGRs derive from fitted trend analysis adjusted for input cost volatility and substitution elasticity from alternative plant milks.
The model assumes a particular technology adoption path for enzymatic hydrolysis and aseptic packaging; alternative pathways for UHT processing equipment or cold chain infrastructure investment would alter the outlook. Forecasts reflect documented assumptions around organic certification penetration rates and school procurement policy implementation timelines. Material deviation in FDA allergen labeling enforcement intensity or Pacific Northwest climate disruption warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Asia-Pacific Probiotic Drinks Market
Beverages
Electrolyte Mixes Market
Beverages
Ready to Drink Margarita Market
Beverages
Coconut Water Market
Beverages
Plant-Based Energy Drink Market
Beverages
Cactus Water Market
Beverages
Fruit Juices and Nectars Market
Beverages
Europe Probiotic Drinks Market
Beverages
Blackstrap Molasses Market
Beverages
Carbonated Soft Drinks Market
Beverages
Herb Infused Water Market
Beverages
Hot Cocoa Mix Market
Beverages
Carbonated Beverages Market
Beverages
Bottled Beverages Market
Beverages
Europe Bottled Water Market
Beverages
Ginger Beer Market