
 Latin America Sports and Energy Drinks Market | 2026-2036
Latin America Sports and Energy Drinks Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Sports and Energy Drinks Market Intelligence
Bottling line technician shortages across Brazil and Mexico is redrawing where production capacity expands. PepsiCo leverages its corn syrup supply chain and captive distribution networks to anchor shelf presence in Mexican convenience channels. The Coca-Cola Company sustains formulation R&D through its Latin American innovation center in São Paulo, developing region-specific flavor profiles. Grupo Petrópolis competes on price in Brazil's Northeast, where per-capita energy drink consumption remains below Southeast levels but climbs fastest.
Sports and energy drinks comprise formulated beverages delivering caffeine, electrolytes, B-vitamins, or amino acids through carbonated or still matrices, typically packaged in aluminum cans or PET bottles with shelf stability engineered for tropical climates. Their primary commercial purpose centers on hydration, mental alertness, or physical performance support during work, exercise, or social occasions. Energy Drinks dominate value contribution due to higher per-liter pricing and youth brand loyalty, while Natural Drinks expand fastest as health-conscious consumers reject synthetic colorants and high-fructose formulations. Distribution through Fitness Centers captures premium margins but remains structurally limited by geographic concentration in wealthy urban districts.
ANVISA governs caffeine limits and health claim prohibitions in Brazil, while COFEPRIS enforces front-of-package warning labels in Mexico; both regulators tighten scrutiny on sugar content and adolescent-targeted marketing. Brazil's CONAR self-regulatory code and Mexico's NOM-051 standard collectively pressure reformulation toward reduced-sugar variants or stevia blends. Stakeholders must monitor whether pending tax proposals on sugar-sweetened beverages spread from Chile's existing framework into Colombia and Peru, reshaping portfolio architecture before implementation.
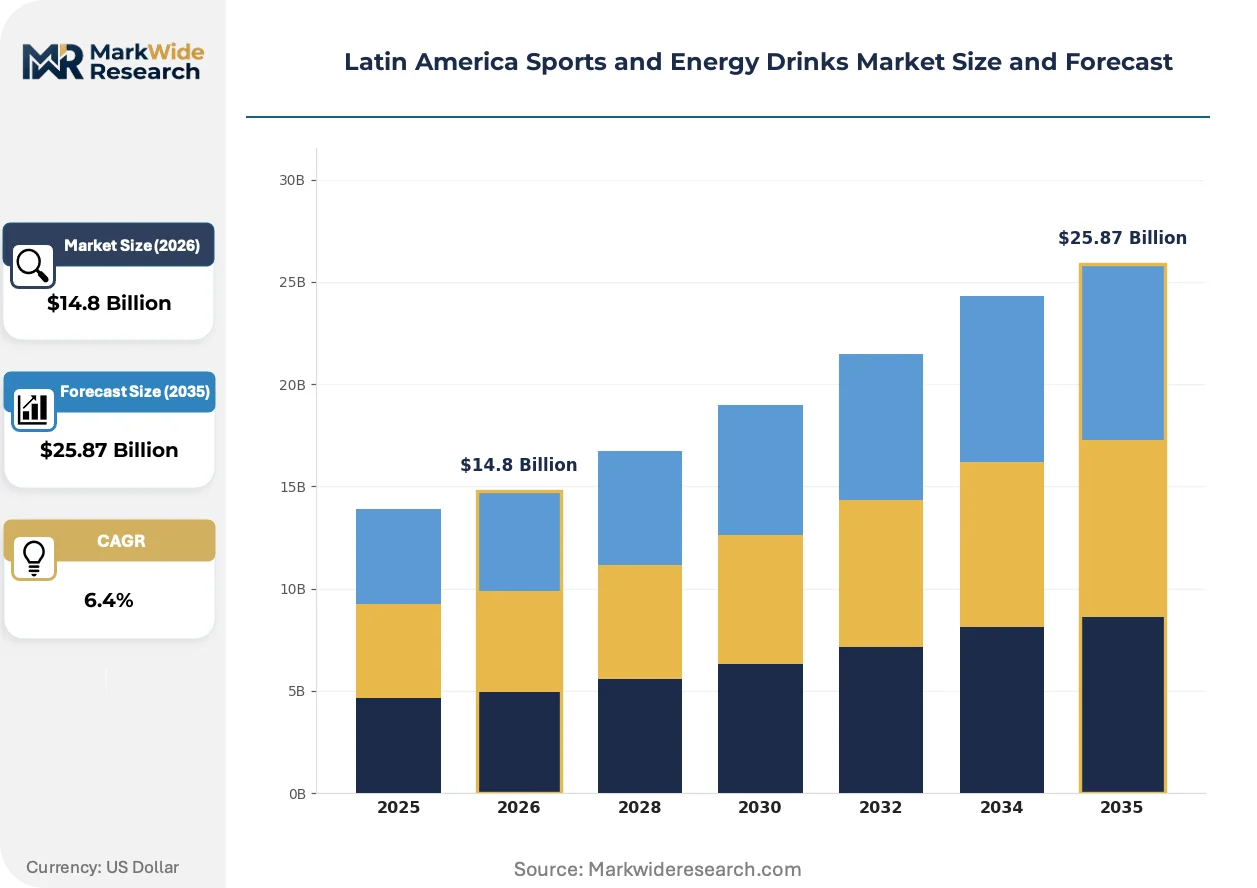
Market Dynamics
Brazil's ANVISA and Mexico's COFEPRIS are tightening caffeine limits and front-of-package warning mandates simultaneously, forcing simultaneous reformulation across portfolios while corn syrup and natural stevia supply chains adjust pricing power.
Growth Catalysts
- Urban fitness culture:São Paulo and Rio de Janeiro metropolitan zones host expanding gym networks where functional beverage consumption clusters around pre-workout and recovery occasions.
- COFEPRIS front-of-package rules:Mexico's NOM-051 standard is accelerating manufacturer migration toward reduced-sugar stevia blends that command shelf space in OXXO and 7-Eleven channels.
- Electrolyte formulation advances:Tropical climate engineering for shelf-stable potassium and magnesium delivery is opening convenience-store distribution in Colombia's Caribbean coastal cities.
Market Restraints
- Aluminum can input volatility:Brazil's primary aluminum smelter concentration around São Paulo state exposes producers to energy-cost pass-through from hydroelectric grid fluctuations.
- ANVISA adolescent marketing prohibitions:Brazil's CONAR self-regulatory code restricts sponsorship activation at music festivals and gaming tournaments where core demographics concentrate.
- Natural caffeine sourcing concentration:Guarana extract supply from Amazonas state faces climate variability that compresses formulation consistency for energy drink producers.
Strategic Opportunities
- Brazil's Northeast corridor:Pernambuco and Ceará states show per-capita consumption gaps against Southeast levels but climbing fastest among price-sensitive demographics.
- Fitness center direct distribution:Premium-margin capture through refrigerated vending at SmartFit and Bodytech locations bypasses traditional retail slotting fees.
- Chilean sugar-tax precedent:Pending fiscal proposals in Colombia and Peru create first-mover advantage for stevia-forward portfolios before implementation spreads.
Industry Challenges
- Bottling line technician scarcity:Brazil's SENAI vocational pipeline produces insufficient mechatronics specialists for high-speed aseptic filling equipment maintenance.
- Refrigerated last-mile fragmentation:Mexico's informal tienda network lacks cold-chain consistency, forcing producers to absorb spoilage risk in Guadalajara and Monterrey distribution zones.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Sports and Energy Drinks Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $25.87 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Energy Drinks, Sports Drinks, Functional Beverages, Natural Drinks Target Audience: Fitness Enthusiasts, Athletes, Casual Consumers, Health-Conscious Individuals Distribution Channel: Supermarkets, Convenience Stores, E-Commerce, Fitness Centers Flavor Profile: Citrus, Berry, Tropical, Herbal |
| Companies Covered | Red Bull, Monster Beverage, PepsiCo, Grupo Petrópolis, Rockstar, The Coca-Cola Company, Electrolit, Grupo Jumex, AJE Group, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Sports and Energy Drinks Market Strategic Shifts & Innovations
Formulation science and regulatory architecture are diverging simultaneously across Latin America, with natural ingredient substitution running ahead of labeling harmonization and creating competitive advantage for producers with flexible R&D infrastructure.
Cold-aseptic filling technology is fragmenting production scale requirements across the region. Mid-size Brazilian producers in Minas Gerais state are adopting modular Tetra Pak lines previously reserved for dairy, enabling 10,000-unit batch runs of functional shots. This capability is compressing minimum viable scale for regional brand entry and enabling flavor experimentation cycles that outpace multinational portfolio refresh rates.
COFEPRIS is expanding NOM-051 octagon warning label requirements to all sugar-sweetened beverages above 5% caloric density by 2025. Mexican manufacturers are accelerating stevia-rebaudioside M formulation trials to maintain palatability thresholds. The energy drink segment faces disproportionate impact as its core consumer base remains price-sensitive while reformulation costs concentrate in concentrated syrup production.
Subscription-based replenishment is displacing single-unit convenience purchasing among affluent Brazilian consumers. Rio de Janeiro's Zona Sul district shows strongest adoption of monthly functional beverage boxes delivered through logistics partnerships with Mercado Libre. This channel rotation is visible among 25-34 year-old remote workers who consolidate grocery purchasing through app-based platforms.
Latin America Sports and Energy Drinks Market Segmentation
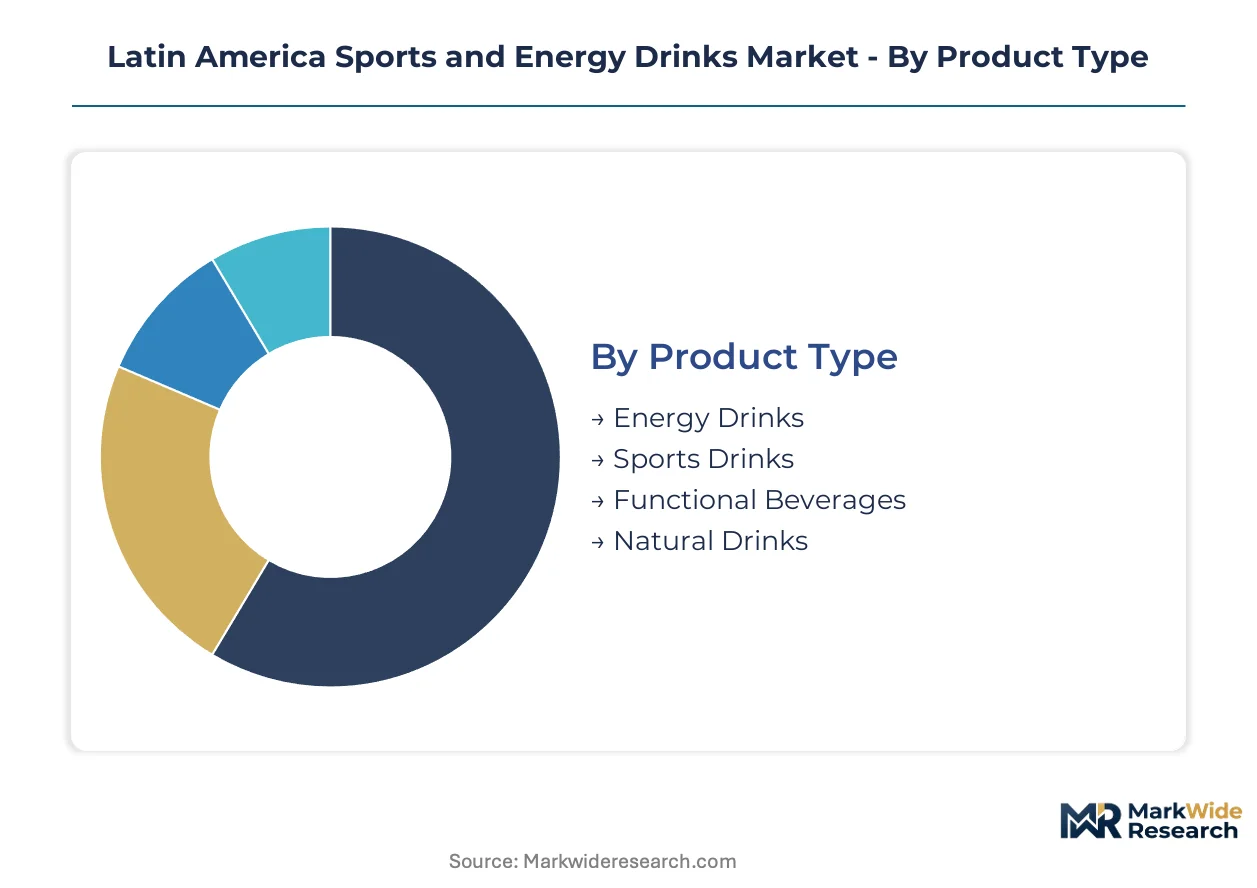
Segmentation reveals how formulation science, channel architecture, and consumer occasion mapping diverge across Latin America's tropical climate belt. Manufacturers must align R&D investment with distinct hydration and alertness use cases while navigating ANVISA and COFEPRIS compliance per segment.
Product Type:
Brazil dominates domestic consumption across all four categories, while Natural Drinks show emerging export traction toward North American wellness channels.
- Energy Drinks:Carbonated matrices delivering 80-160mg caffeine per serving through synthetic or guarana-derived sources. São Paulo's metropolitan corridor concentrates pre-workout and late-work-shift consumption among 18-29 year-olds. ANVISA's 400mg daily caffeine limit and adolescent marketing prohibitions constrain sponsorship activation at music festivals.
- Natural Drinks:Stevia-sweetened or unsweetened formulations with botanical extracts and no synthetic colorants. Colombia's Caribbean coastal cities and Rio de Janeiro's Zona Sul show fastest adoption as health-conscious consumers reject high-fructose corn syrup. Subscription replenishment through Mercado Libre partnerships is displacing single-unit convenience purchasing.
- Sports Drinks:Electrolyte-replenishment formulations with sodium, potassium, and magnesium engineered for tropical shelf stability. Demand clusters around gym networks in Brazil's southeastern urban corridor.
- Functional Beverages:Amino acid or adaptogen-infused still beverages targeting recovery and cognitive performance. Niche positioning commands premium pricing in fitness center vending.
Energy Drinks command the established base. The steepest expansion runs through Natural Drinks.
Target Audience:
Cost tier stratification separates premium formulation seekers from price-sensitive mass market entry points.
- Fitness Enthusiasts:High-frequency consumers purchasing 4-8 liters weekly through gym direct distribution. SmartFit and Bodytech locations in São Paulo and Mexico City bypass traditional retail slotting fees. Pre-workout caffeine loading and post-session electrolyte recovery drive dual-occasion purchasing.
- Casual Consumers:Occasion-based purchasers selecting single-serve aluminum cans from OXXO and 7-Eleven channels. Mexico's informal tienda network fragmentation forces producers to absorb spoilage risk in Guadalajara distribution zones.
- Athletes:Performance-verified formulations with batch-tested electrolyte ratios. Limited to sponsored professional tiers and competitive amateur segments.
- Health-Conscious Individuals:Sugar-content scrutinizers migrating toward stevia blends under COFEPRIS NOM-051 warning label pressure. Colombia and Peru show pending tax proposal anticipation driving early portfolio shifts.
Fitness Enthusiasts anchor volume concentration. The steepest expansion trajectory belongs to Health-Conscious Individuals.
Distribution Channel:
Volume scale concentrates in traditional retail, while margin capture accelerates through direct and digital routes.
- Convenience Stores:OXXO's 20,000-plus Mexican locations and Brazil's AmPm network dominate impulse purchasing. Refrigerated last-mile constraints in Monterrey and Recife force ambient-stable formulation priorities.
- Fitness Centers:Premium-margin refrigerated vending at Bodytech and SmartFit locations. Geographic concentration in wealthy urban districts limits structural scale but captures highest per-liter profitability.
- Supermarkets:Multi-pack and family-format purchasing with highest absolute volume throughput. São Paulo and Rio de Janeiro metropolitan zones show strongest weekly basket incorporation.
- E-Commerce:Monthly subscription boxes through Mercado Libre logistics partnerships. Rio de Janeiro's Zona Sul district leads adoption among 25-34 year-old remote workers consolidating grocery purchasing through app-based platforms.
Supermarkets maintain the volume base. The steepest expansion runs through E-Commerce.
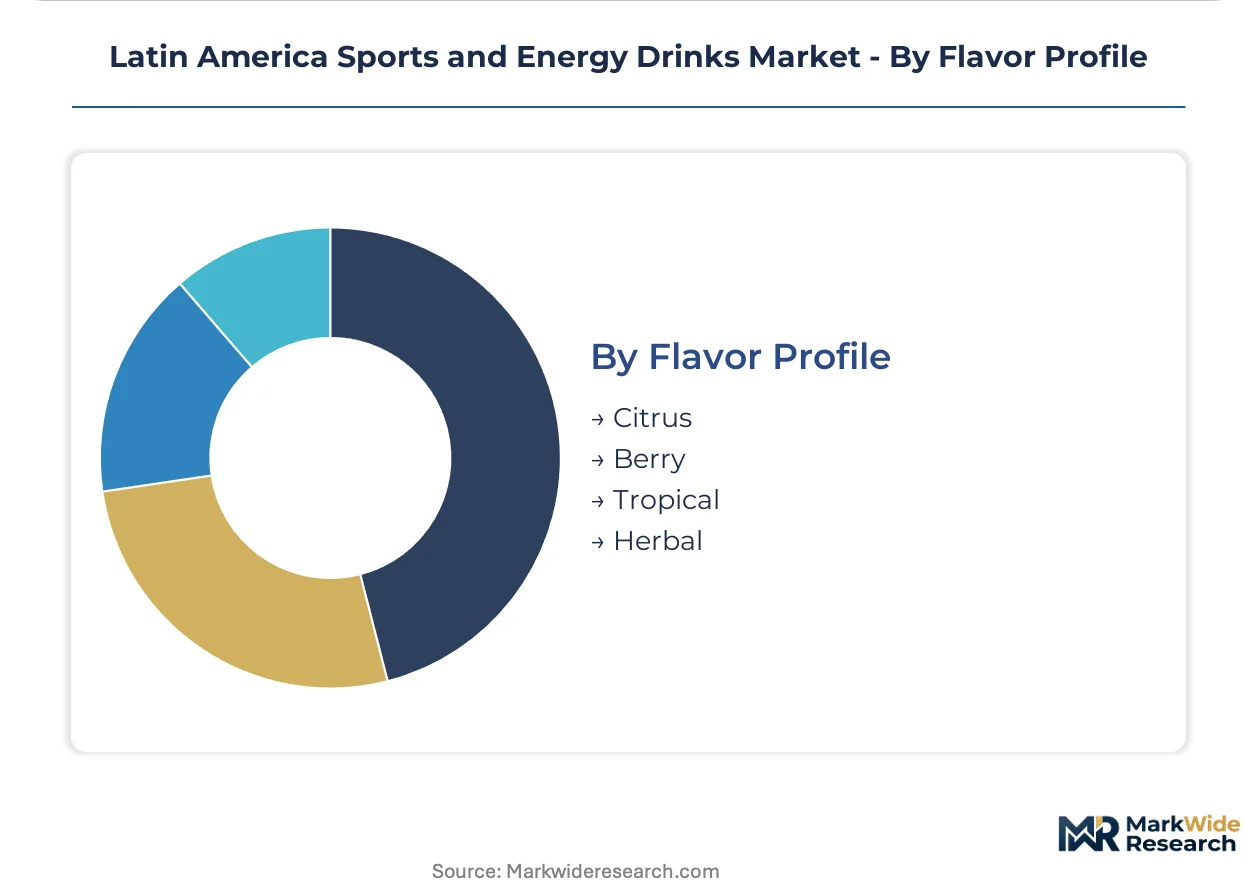
Flavor Profile:
Application occasion dictates preference: citrus for refreshment, tropical for energy, herbal for wellness positioning.
- Tropical:Guava, passion fruit, and açaí formulations developed at Coca-Cola's São Paulo innovation center. Brazil's Northeast corridor shows strongest per-capita preference alignment.
- Citrus:Lemon-lime and orange variants optimized for electrolyte masking. Standard sports drink base across all four countries.
- Berry:Blueberry and mixed-berry positioning for antioxidant health claims. ANVISA health claim prohibitions limit explicit marketing.
- Herbal:Yerba mate and guarana botanical extracts leveraging regional ingredient heritage. Amazonas state guarana supply faces climate variability compressing formulation consistency.
Citrus commands the established base. The steepest expansion runs through Tropical.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
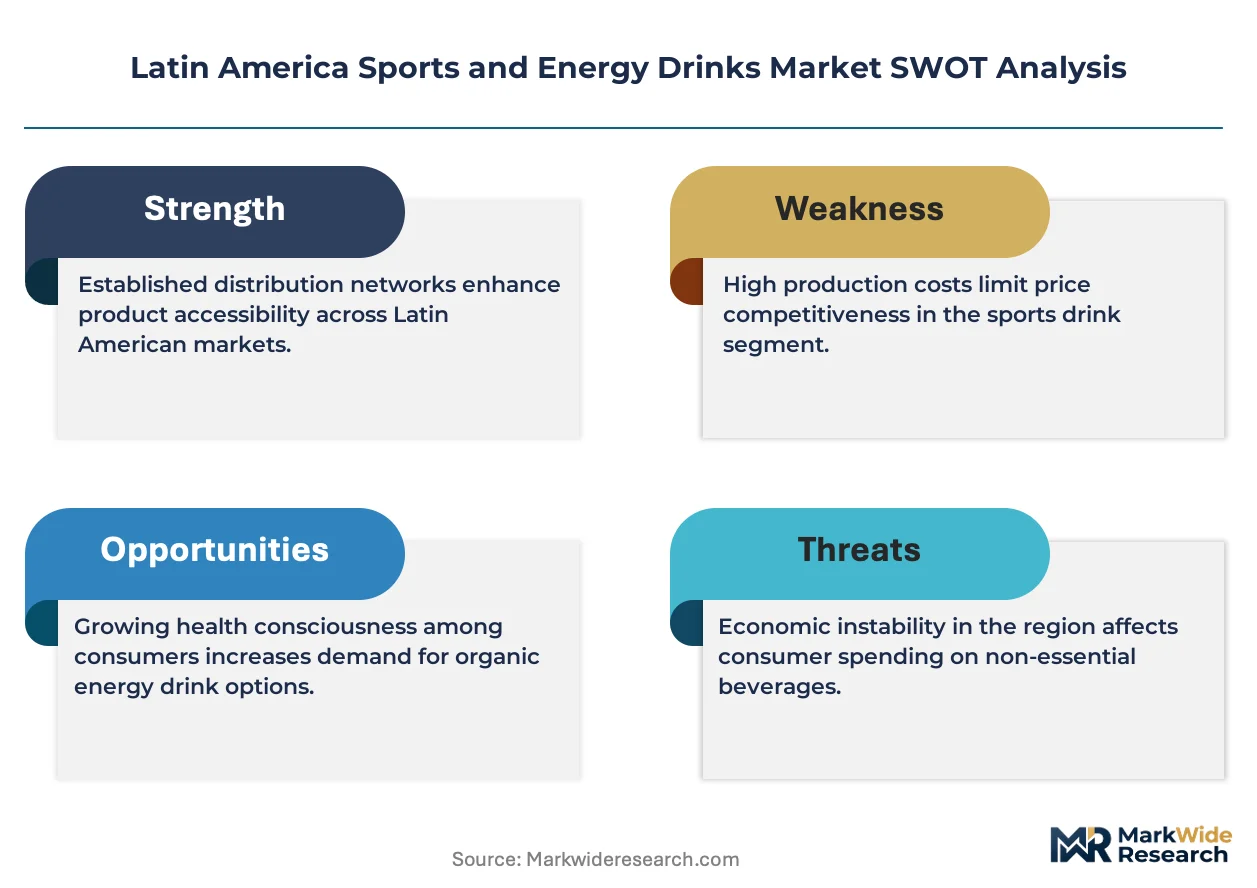
ANVISA enforces caffeine limits and adolescent marketing prohibitions across Brazil, anchoring regulatory gravity for the Latin American market. Mexico's COFEPRIS front-of-package warning mandates under NOM-051 accelerate reformulation timelines. Colombia and Chile introduce sugar-tax precedents that reshape portfolio architecture.
Brazil
Fitness culture expansion in São Paulo and Rio de Janeiro metropolitan zones drives pre-workout and recovery beverage consumption. ANVISA's 400mg daily caffeine ceiling and CONAR self-regulatory code restrict sponsorship activation at music festivals and gaming tournaments. The southeastern urban corridor concentrates gym network density and refrigerated vending infrastructure.
Mexico
OXXO's 20,000-plus convenience locations dominate impulse purchasing across urban and semi-urban zones. COFEPRIS mandates octagon warning labels on sugar-sweetened beverages above 5% caloric density, forcing stevia-rebaudioside M formulation trials. Monterrey and Guadalajara distribution zones suffer refrigerated last-mile fragmentation in informal tienda networks.
Colombia
Caribbean coastal cities adopt electrolyte formulations engineered for tropical shelf stability. Pending fiscal proposals on sugar-sweetened beverages create first-mover advantage for stevia-forward portfolios before implementation. Barranquilla and Cartagena clusters show fastest convenience-store channel expansion.
Chile
Existing sugar-tax framework pressures reduced-sugar variant development across imported and domestic portfolios. Health-conscious consumers in Santiago metropolitan area migrate toward unsweetened botanical extracts. Regulatory precedent influences adjacent Andean markets considering similar fiscal instruments.
Argentina
Economic volatility compresses purchasing power toward price-sensitive entry points in energy drink categories. Buenos Aires and Córdoba metropolitan zones maintain highest per-capita consumption despite currency fluctuation impacts. Informal import channels from neighboring markets complicate formal distribution margin structures.
Latin America Sports and Energy Drinks Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with multinational beverage conglomerates leveraging captive corn syrup supply chains and distribution networks against regional price competitors. The market structure concentrates around formulation R&D capabilities and cold-chain logistics scale. Two strategic archetypes dominate: vertically integrated syrup-to-shelf operators with tropical climate engineering expertise, and agile regional challengers competing on price in underserved corridors. Competitive moves center on portfolio diversification toward stevia blends and geographic expansion into Brazil's Northeast.
Among multinational operators, The Coca-Cola Company and PepsiCo exemplify the integrated leader archetype through São Paulo innovation center activity and Mexican convenience channel anchoring respectively. Grupo Petrópolis occupies a position within the regional challenger tier, competing on price in Brazil's Northeast where per-capita consumption climbs fastest among price-sensitive demographics.
| Leading Market Players |
|---|
| Red Bull |
| Monster Beverage |
| PepsiCo |
| Grupo Petrópolis |
| Rockstar |
| The Coca-Cola Company |
| Electrolit |
| Grupo Jumex |
| AJE Group |
| Others |
Cost & Logistics Intelligence
ANVISA's caffeine content ceilings and COFEPRIS front-of-package warning mandates simultaneously gate supply qualification and price differentiation, forcing manufacturers to absorb reformulation costs while premium-positioned stevia blends capture shelf space in Mexican OXXO and Brazilian AmPm channels.
Pricing Analysis
Brazil's Southeast corridor commands 15-20% price premiums over Northeast states for identical SKUs, with São Paulo metropolitan zones showing highest per-liter acceptance for functional beverage subscriptions. Three-tier pricing structure across premium, standard, and economy levels separates fitness-center direct distribution from supermarket multi-packs and informal tienda single-serve. Price differentiation hinges on cold-chain reliability and brand heritage, with health-conscious segments least sensitive and price-driven Northeast consumers most responsive to promotional elasticity. Cost compression in economy-tier aluminum can production is intensifying because energy-price pass-through from São Paulo state hydroelectric grid fluctuations.
Supply Chain Analysis
Brazil and Mexico anchor Latin American beverage formulation and filling infrastructure, with Colombia emerging as Caribbean coastal distribution hub. Raw material flows draw from Amazonas state guarana extract, US Gulf Coast high-fructose corn syrup, and Chinese stevia-rebaudioside M concentrate. Single-source vulnerability concentrates in tropical-climate engineering expertise for shelf-stable electrolyte matrices. Distribution runs through captive wholesaler networks in southeastern Brazil and OXXO's vertically integrated convenience chain in Mexico.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards regulatory entrenchment as a defensive moat, with ANVISA and COFEPRIS compliance timelines creating switching costs that lock in shelf presence for established portfolios.
For Market Incumbents: Shield market position by accelerating stevia-rebaudioside M formulation R&D ahead of pending sugar-tax proposals in Colombia and Peru. Deepen backward integration into Amazonas state guarana sourcing to compress climate-variability exposure. Lock in multi-year refrigerated logistics contracts with Mercado Libre to defend subscription-channel margins against emerging direct-to-consumer entrants.
For New Entrants and Emerging Players: Anchor in Brazil's Northeast corridor where per-capita consumption gaps against Southeast levels offer white-space expansion among price-sensitive demographics. Target Pernambuco and Ceará states with ambient-stable PET formats bypassing cold-chain infrastructure deficits. Pursue private-label partnerships with regional supermarket chains to bypass slotting-fee barriers in saturated southeastern markets.
For Investors and Strategic Acquirers: Carve-out targets emerge from multinational beverage conglomerates seeking portfolio streamlining, particularly stevia-forward regional brands with ANVISA-approved formulations. Mid-term viability rests on regulatory compliance infrastructure as a scarce asset. Monitor COFEPRIS NOM-051 implementation velocity as inflection signal for reformulation cost curves and margin compression timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Stevia-Rebaudioside M Formulation Migration | COFEPRIS NOM-051 compliance preserves shelf access in OXXO's 20,000-plus Mexican locations. |
| Fitness Center Direct Distribution Expansion | Bodytech and SmartFit refrigerated vending captures premium margins bypassing traditional retail slotting fees. |
| Amazonas Guarana Supply Integration | Backward integration into botanical extract sourcing compresses climate-variability risk for energy drink consistency. |
| Subscription Replenishment Platform Launch | Mercado Libre logistics partnerships in Rio de Janeiro's Zona Sul consolidate remote-worker purchasing patterns. |
| Northeast Brazil Manufacturing Footprint | Pernambuco and Ceará production placement aligns with fastest-climbing per-capita consumption corridors. |
Research Approach
The analysis maps energy drinks, natural drinks, sports drinks, and functional beverages, each validated through bottling line technicians, category buyers at OXXO and AmPm, ANVISA regulatory affairs specialists, and Coca-Cola São Paulo innovation center formulation scientists. Secondary sources include ANVISA caffeine-limit filings, COFEPRIS NOM-051 regulatory texts, Nielsen retail audit data for Latin American convenience channels, and customs records for stevia and guarana raw material flows. Bottom-up volume builds triangulate against top-down category spend estimates.
Consistency checks validated outputs against external benchmarks across the projection horizon. Segmentation dimensions modeled include product type, target audience archetype, distribution channel, and flavor profile. CAGRs derive from trend-line extrapolation of per-capita consumption intensity correlated with gym network density and urban income distribution. Industry-specific forecast inputs incorporate ANVISA enforcement velocity indices and COFEPRIS warning-label rollout timelines.
Underlying assumptions cover regulatory implementation schedules, raw material price stability, and consumer preference migration toward reduced-sugar formulations, with deviation risk concentrated in pending sugar-tax legislative passage in Colombia and Peru. Recalibration cycles align with material shifts in ANVISA caffeine-limit enforcement patterns and COFEPRIS NOM-051 expansion scope.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Drinking Water Market
Beverages
Spring Water Market
Beverages
Apple Juice Concentrate Market
Beverages
Alternative Waters (Plant Based Waters) Market
Beverages
Sports Drink Market
Beverages
China Orange Juice Market
Beverages
Drinking Bottled Mineral Water Market
Beverages
Packaged Cactus Water Market
Beverages
Chocolate Powdered Drinks Market
Beverages
Sports and Energy Drinks Market
Beverages
North America Sugar Free Energy Drinks Market
Beverages
Italy Probiotic Drinks Market
Beverages
Growlers Market
Beverages
Fusion Beverages Market
Beverages
Fiber Fortified Beverages Market
Beverages
South America Mate Market