
 HVAC Pumps Market | 2026-2036
HVAC Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
HVAC Pumps Market Intelligence
ISO 9906 hydraulic performance testing is redrawing competitive boundaries for pump manufacturers seeking project-specification approvals. Grundfos leverages its vertical integration into permanent-magnet motor production to command premium positioning in European hydronic retrofits. Xylem sustains R&D intensity around digital twin-enabled pump diagnostics, while KSB anchors its position through foundry-to-final-assembly control in German industrial heating applications.
HVAC pumps are pressure-raising machines designed to circulate water, glycol solutions, or refrigerants through closed-loop thermal distribution networks, with operational envelopes typically spanning 0.5 to 500 kilowatts of hydraulic power and efficiency targets governed by ISO 5198 test protocols. Centrifugal pumps occupy the volume core across commercial and institutional installations where constant-pressure variable-flow architecture dominates new construction specifications. Inline pumps represent the fastest-growing product configuration, driven by spatial constraints in urban mechanical rooms and the retrofit imperative within aging European building stock. The replacement installation channel now commands disproportionate margin attention as facility managers prioritize drop-in efficiency upgrades over full-system redesigns.
The US Department of Energy enforces minimum efficiency standards under 10 CFR 431 that disqualify single-speed circulators from federal procurement channels, while the EU Ecodesign Directive mandates tiered efficiency indexing for glandless pumps in residential and commercial service. China's GB 19762 standard for centrifugal pump energy consumption is tightening import eligibility for non-domestic manufacturers serving state-funded infrastructure projects. Stakeholders must calibrate product roadmaps against divergent regional certification timelines rather than assuming harmonized efficiency benchmarks will emerge.
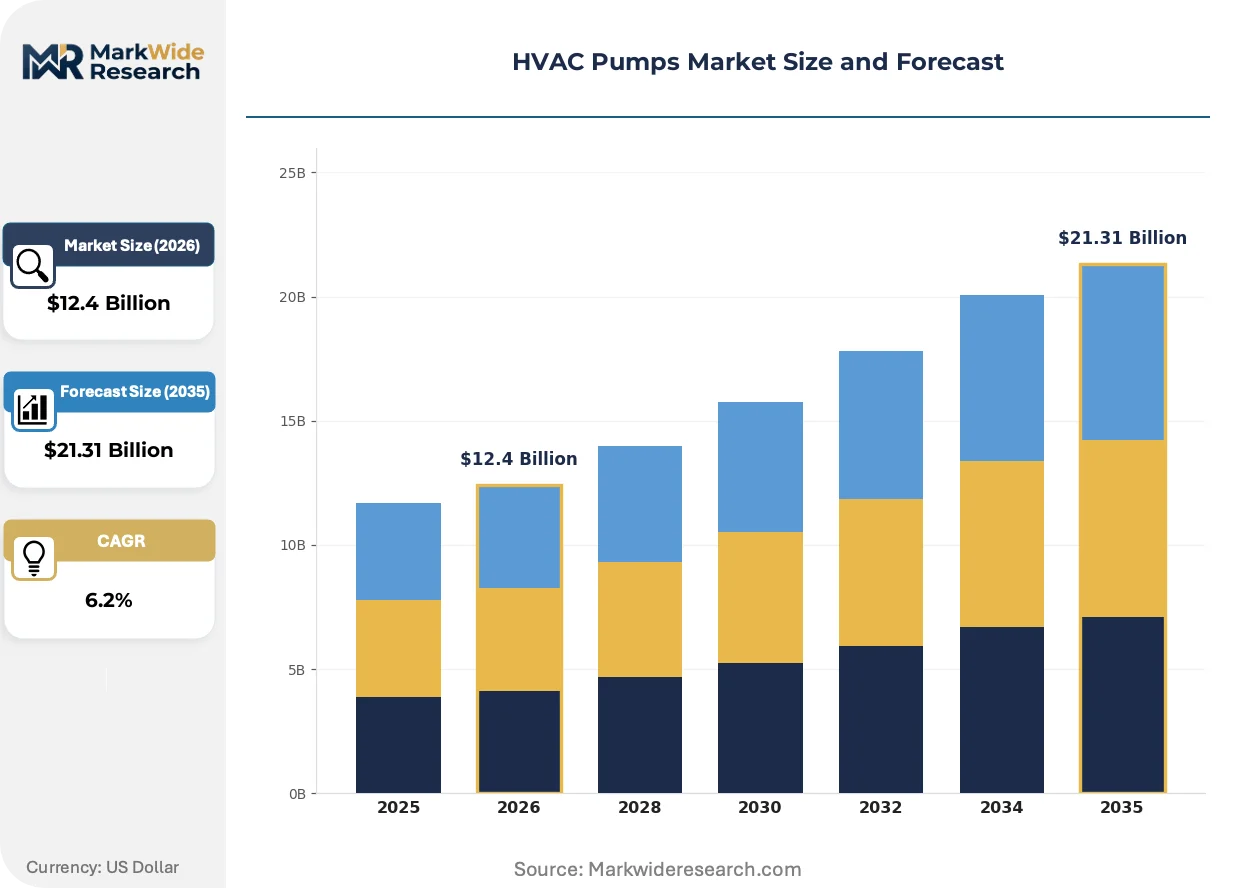
Market Dynamics
The EU F-Gas Regulation's phase-down schedule is compressing replacement cycles for fixed-speed circulators across European commercial building stock, while permanent-magnet motor adoption reconfigures supplier power toward vertically integrated manufacturers.
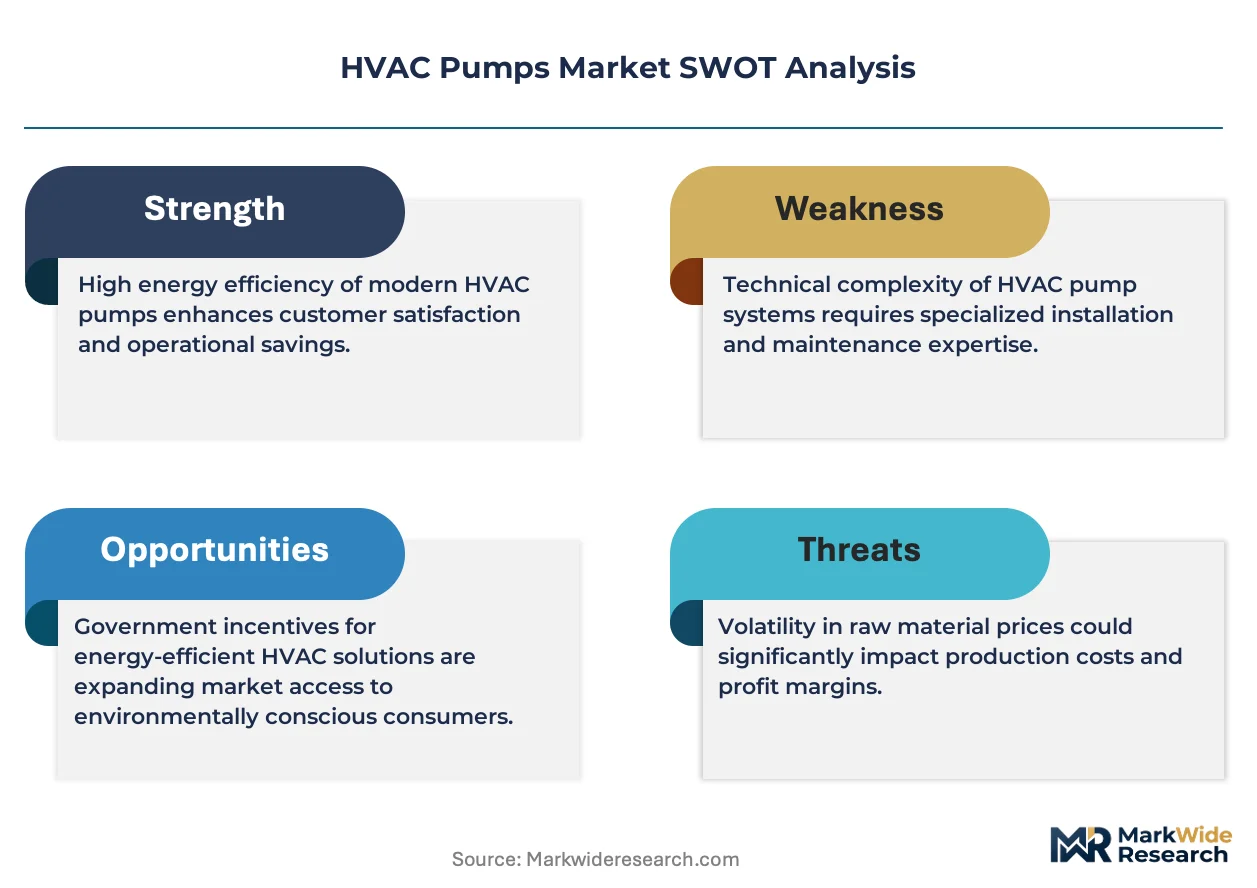
Growth Catalysts
- Permanent-magnet synchronous motors:These motors deliver efficiency gains that satisfy EU Ecodesign Directive tiered indexing for glandless pumps in commercial service. Building operators in Germany's industrial corridor prioritize drop-in retrofits that avoid full-system redesign.
- US Department of Energy 10 CFR 431 enforcement:Federal procurement disqualification of single-speed circulators is accelerating municipal and institutional upgrade schedules. Facility managers in the US Sun Belt face converging cooling load growth and decarbonization mandates.
- Inline pump configuration demand:Spatial constraints in urban mechanical rooms favor compact installation footprints. Aging hydronic infrastructure across North America and Europe requires solutions that minimize piping modification.
Market Restraints
- Rare-earth magnet supply concentration:Neodymium and dysprosium processing concentrates in China's upstream refining capacity, exposing permanent-motor manufacturers to export control volatility and price swings.
- Foundry capacity bottlenecks:Ductile iron casting for pump housings faces constrained European supplier bases, with lead times extending for ISO 9906-certified component sourcing.
- Refrigerant pump material incompatibility:Low-GWP alternatives to R-410A require stainless steel or specialized elastomer seals that inflate bill-of-material costs versus traditional bronze-alloy construction.
Strategic Opportunities
- Digital twin-enabled predictive maintenance:Sensor-integrated pumps with cloud-connected diagnostics create recurring revenue streams. Equipment-as-a-service models penetrate German industrial heating applications where uptime guarantees command premium positioning.
- China's GB 19762 standard tightening:Import eligibility restrictions for non-domestic manufacturers serving state-funded infrastructure projects favor joint-venture production localization. Domestic certification accelerates access to municipal district heating tenders.
- Hybrid heat pump hydronic integration:Dual-source systems combining air-source and geothermal loops require variable-speed distribution pumps with expanded operational envelopes. Nordic residential markets demonstrate early specification adoption.
Industry Challenges
- ISO 9906 testing capacity scarcity:Accredited hydraulic performance laboratories face backlog queues that extend product qualification timelines, delaying project-specification approvals for new pump platforms.
- Legacy building automation protocol fragmentation:BACnet, Modbus, and proprietary OEM communication standards create integration friction for smart pump deployments in retrofit environments. Interoperability middleware adds commissioning cost and complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | HVAC Pumps Market |
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $21.31 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Centrifugal Pumps, Reciprocating Pumps, Submersible Pumps, Inline Pumps End User: Residential, Commercial, Industrial, Institutional Installation: New, Replacement, Upgrade, Retrofit Application: Heating, Cooling, Refrigeration, Hydronic Systems |
| Companies Covered | Grundfos, Xylem, KSB, Wilo, Circulator Pumpen, Ebara Corporation, Sulzer, Flowserve, ITT Goulds Pumps, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
HVAC Pumps Market Strategic Shifts & Innovations
Electrification of thermal distribution networks is accelerating specification shifts toward intelligent pumping systems that modulate hydraulic power against real-time load profiles rather than constant-speed operation.
Permanent-magnet motor technology is supplanting induction motor architectures in commercial circulator specifications above 5 kilowatts hydraulic power. German industrial heating operators now mandate IE5 efficiency classifications for new installations. This motor transition compresses operating energy consumption by fifteen to twenty-five percentage points versus premium-efficiency induction equivalents, repositioning lifecycle cost calculations against first-cost procurement preferences.
REACH regulation amendments restricting per- and polyfluoroalkyl substances are eliminating traditional PTFE-based pump seal materials from European supply chains. Manufacturers pivot toward advanced thermoplastic elastomers and graphite-composite alternatives that satisfy chemical resistance requirements without SVHC classification. Glandless pump categories in residential and light commercial service face accelerated material qualification timelines to maintain CE marking compliance.
After-sales service unbundling is fragmenting traditional OEM-captive maintenance relationships. Third-party predictive analytics platforms integrate sensor data across multi-brand pump installations, displacing manufacturer-proprietary diagnostic tools. Facility management consolidators in North American commercial real estate portfolios favor vendor-agnostic monitoring solutions that standardize maintenance workflows across heterogeneous mechanical equipment bases.
HVAC Pumps Market Segmentation
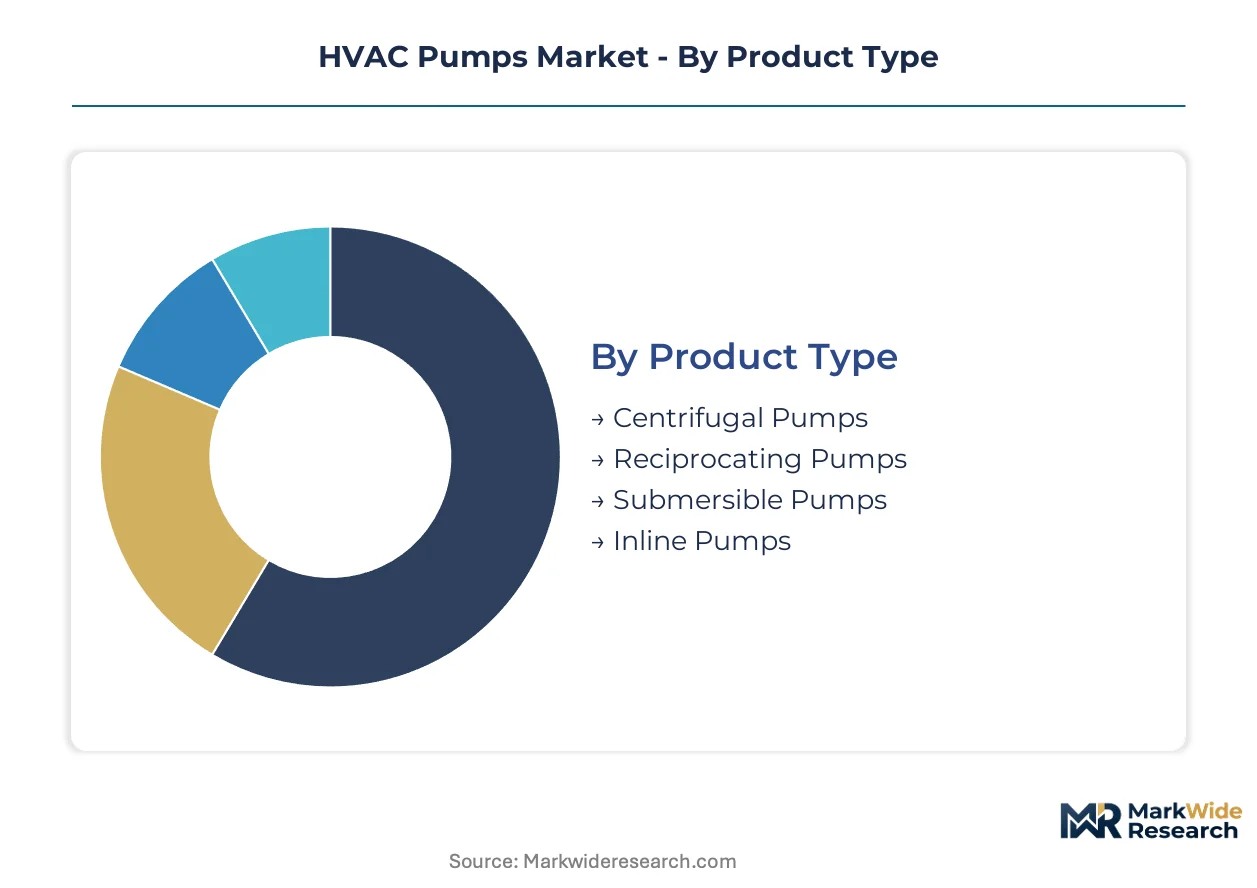
HVAC pump procurement splits across four dimensions that determine specification authority and margin structure. Regulatory pressure on minimum efficiency performance standards drives divergence between product architectures, while installation channel dynamics reshape supplier engagement models.
Product Type:
EU Ecodesign Directive tiered indexing and US DOE 10 CFR 431 enforcement create divergent compliance burdens across pump architectures, favoring configurations that accommodate permanent-magnet motor integration.
- Centrifugal Pumps:These pressure-raising machines dominate commercial and institutional specifications through constant-pressure variable-flow architecture. Demand concentrates in Germany's industrial corridor where IE5 efficiency classifications are now mandatory for new installations above 5 kilowatts hydraulic power.
- Inline Pumps:Compact footprint configurations address spatial constraints in urban mechanical rooms across aging European building stock. Facility managers in the US Sun Belt prioritize drop-in retrofits that avoid full-system redesign while satisfying decarbonization mandates.
- Reciprocating Pumps:Positive-displacement architectures serve specialized high-pressure hydronic applications in district heating networks.
- Submersible Pumps:Immersed motor designs target geothermal loop circulation and below-grade sump installations in Nordic residential markets.
Centrifugal pumps handle the majority of throughput; inline pumps are gaining share fastest on retrofit-driven specification shifts.
End User:
Customer type determines procurement authority, with consolidated facility management portfolios commanding standardized multi-site contracts that displace single-project specifications.
- Commercial:Building operators across North American and European portfolios accelerate replacement schedules for aging hydronic infrastructure. The EU F-Gas Regulation compresses replacement cycles for fixed-speed circulators while permanent-magnet motor adoption reconfigures supplier power.
- Industrial:Process heating and cooling applications in Germany's industrial corridor require expanded operational envelopes for dual-source hybrid heat pump integration. Uptime guarantees command premium positioning through equipment-as-a-service models.
- Residential:Glandless pump categories face accelerated material qualification timelines as REACH amendments eliminate PTFE-based seals from European supply chains.
- Institutional:Municipal and federal procurement channels disqualify single-speed circulators under US DOE enforcement, accelerating upgrade schedules in educational and healthcare facilities.
Commercial installations generate the dominant revenue base; industrial applications show the steepest expansion trajectory on hybrid system integration.
Installation:
Channel dynamics reflect capital cycle positioning, with deferred maintenance backlogs now converting to efficiency-focused upgrade commitments.
- Replacement:Drop-in efficiency upgrades command disproportionate margin attention as facility managers prioritize ISO 9906-certified component sourcing over full-system redesign. Aging hydronic infrastructure across North America and Europe requires solutions that minimize piping modification.
- Retrofit:Legacy building automation protocol fragmentation creates integration friction for smart pump deployments. BACnet, Modbus, and proprietary OEM communication standards add commissioning cost and complexity in urban mechanical rooms.
- New:Greenfield specifications incorporate digital twin-enabled diagnostics from commissioning, creating recurring revenue streams through sensor-integrated pumps.
- Upgrade:Partial system modernization targets efficiency thresholds for state-funded infrastructure project eligibility under tightening certification standards.
Replacement channels capture the dominant share of current procurement volume; retrofit activity is climbing the fastest as deferred maintenance converts to capital deployment.
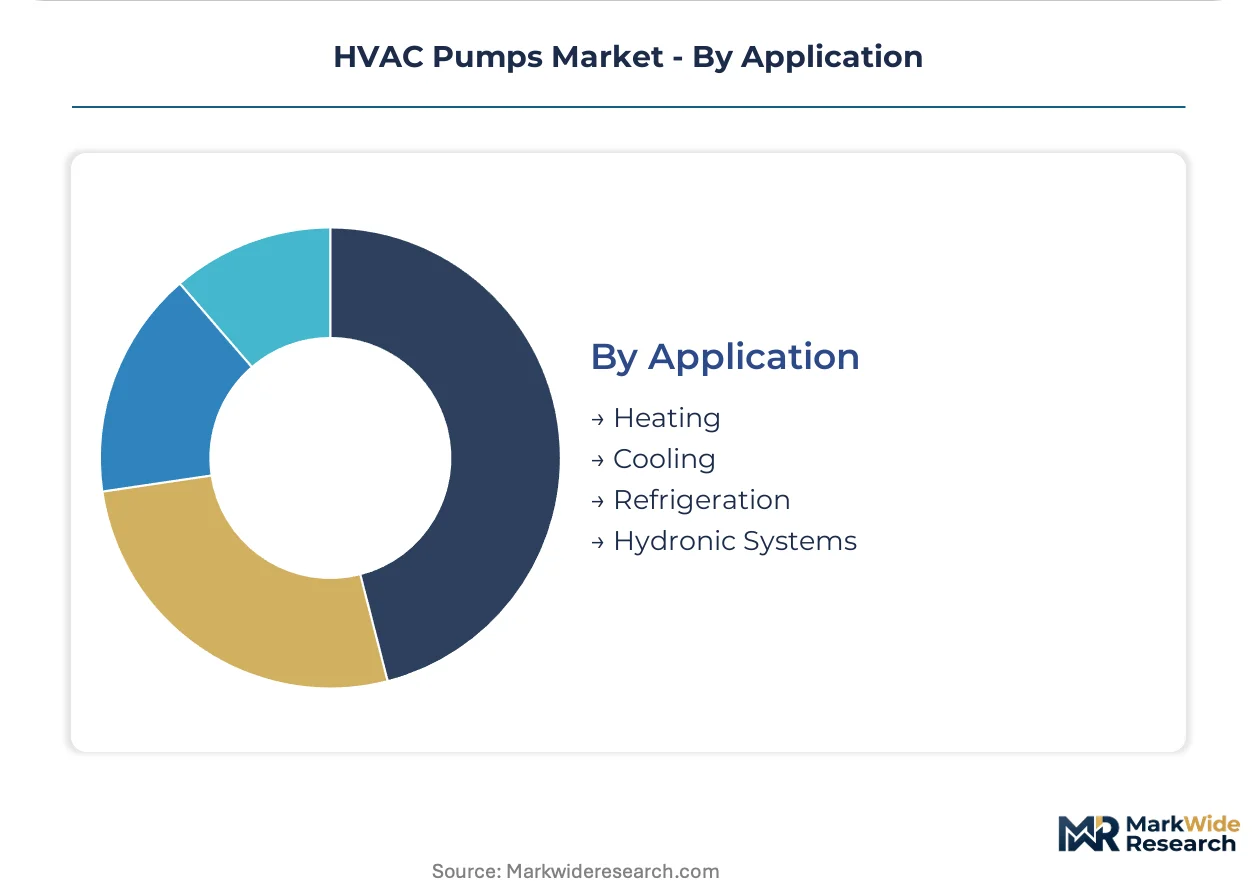
Application:
Functional use case determines material compatibility requirements, with refrigerant pump specifications facing accelerated qualification timelines for low-GWP alternatives.
- Cooling:Variable-speed distribution pumps with expanded operational envelopes serve air-source and geothermal loop combinations in Nordic residential markets. Cooling load growth in the US Sun Belt converges with decarbonization mandates to accelerate specification shifts.
- Hydronic Systems:Closed-loop thermal distribution networks circulate water and glycol solutions through commercial and institutional installations. ISO 5198 test protocols govern efficiency targets across 0.5 to 500 kilowatt operational envelopes.
- Heating:German industrial heating operators mandate IE5 efficiency classifications for new installations, compressing operating energy consumption versus premium-efficiency induction equivalents.
- Refrigeration:Low-GWP alternatives to R-410A require stainless steel or specialized elastomer seals that inflate bill-of-material costs versus traditional bronze-alloy construction.
Cooling applications anchor current volume; hydronic systems are expanding most quickly on electrification of thermal distribution networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU F-Gas Regulation and US DOE efficiency mandates are compressing replacement cycles across mature building stocks, while China's GB 19762 standard redirects procurement toward certified domestic production.
United States
Cooling load growth in the Sun Belt converges with municipal decarbonization mandates to accelerate specification shifts. DOE 10 CFR 431 enforcement disqualifies single-speed circulators from federal procurement channels. Facility managers in Texas and Florida prioritize drop-in retrofits that minimize piping modification.
Germany
Industrial heating operators in the Ruhr corridor mandate IE5 efficiency classifications for new installations above 5 kilowatts hydraulic power. The EU Ecodesign Directive's tiered indexing compels glandless pump upgrades in commercial service. Foundry-to-final-assembly control anchors supplier positioning in Baden-Württemberg's manufacturing belt.
China
State-funded infrastructure projects tighten import eligibility under GB 19762 centrifugal pump energy standards. Dual carbon goals accelerate municipal district heating tenders in the Yangtze River Delta. Joint-venture production localization secures access to northern industrial corridor specifications.
India
Commercial real estate expansion in Mumbai and Delhi-NCR drives demand for compact inline configurations in constrained mechanical rooms. BIS efficiency labeling for circulating pumps pressures importers toward certified product lines. Western Maharashtra's industrial clusters demonstrate early adoption of variable-speed distribution architecture.
Japan
Hybrid heat pump hydronic integration expands operational envelope requirements in residential and light commercial applications. METI efficiency standards for glandless pumps align with JIS certification protocols. Osaka-Kansai manufacturing bases supply sensor-integrated pumps for predictive maintenance deployment.
HVAC Pumps Market Key Industry Players
Player mix skews toward vertically integrated European specialists with captive motor production and foundry control. The supplier base concentrates around three strategic tiers: premium-positioned full-line manufacturers, mid-scale regional fabricators with certification depth, and emerging Asian producers leveraging cost-advantaged component sourcing. Competitive dynamics center on permanent-magnet motor integration and ISO 9906 testing capacity acquisition rather than price-based displacement.
Among European-headquartered manufacturers, Grundfos and KSB occupy positions defined by upstream control over critical components, while Xylem represents the digital services archetype. These three exemplify divergent strategic vectors: backward integration into motor manufacturing, foundry-to-assembly vertical control, and cloud-connected diagnostics platform development. Each anchors a distinct competitive posture without overlapping core capabilities.
| Leading Market Players |
|---|
| Grundfos |
| Xylem |
| KSB |
| Wilo |
| Circulator Pumpen |
| Ebara Corporation |
| Sulzer |
| Flowserve |
| ITT Goulds Pumps |
| Others |
Cost & Logistics Intelligence
Permanent-magnet synchronous motors replacing induction architectures in commercial circulators above 5 kilowatts are redrawing supply geography toward rare-earth processing clusters while compressing lifecycle cost calculations against first-cost procurement preferences. This substitution dynamic concentrates pricing power among manufacturers with captive motor production and exposes price-sensitive buyers to neodymium price volatility.
Pricing Analysis
IE5 efficiency certification creates the primary spread between premium and standard tiers, with German industrial buyers accepting twenty to twenty-five percentage point operating cost premiums against first-cost discounts. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 9906 testing depth and foundry-to-assembly control. Pricing pressure stems from REACH-compliant seal material qualification timelines inflating bill-of-material costs. Municipal procurement channels show highest price sensitivity; uptime-guaranteed industrial heating contracts show lowest.
Supply Chain Analysis
China anchors upstream rare-earth magnet refining, with neodymium and dysprosium processing concentration creating single-source vulnerability for permanent-motor manufacturers. Germany and Italy supply ISO 9906-certified foundry capacity for pump housings, while Taiwan and South Korea feed precision electronics for sensor-integrated diagnostics. Supply chain risk centers on export control volatility from China's upstream refining capacity. Distribution runs through OEM-direct specification channels for large industrial projects and wholesale distribution for replacement aftermarket.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ISO 9906 testing laboratory scarcity and foundry capacity bottlenecks are concentrating competitive advantage among manufacturers with in-house certification assets and backward integration into critical components.
For Market Incumbents: Compound defensive positioning by acquiring accredited hydraulic performance testing capacity to compress qualification timelines for new pump platforms. Deepen backward integration into permanent-magnet motor production to secure supply against rare-earth export volatility. Prioritize foundry-to-final-assembly control in German industrial corridor specifications where IE5 mandates command premium positioning. For New Entrants and Emerging Players: Fast-track GB 19762 certification for China's state-funded infrastructure tenders offers the most penetrable entry point for non-domestic manufacturers. Target India's BIS efficiency labeling compliance for circulating pump import eligibility in Mumbai and Delhi-NCR commercial real estate expansion. Lead with compact inline configurations addressing spatial constraints in urban mechanical rooms across aging European building stock. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European pump specialists lacking digital twin-enabled predictive maintenance capabilities. Long-term viability favors manufacturers bridging cloud-connected diagnostics with equipment-as-a-service revenue models. Watch for ISO 9906 testing backlog resolution as inflection indicator for new platform qualification velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Permanent-Magnet Motor Production | Captive rare-earth magnet supply secures pricing power against Chinese export volatility. |
| ISO 9906 Testing Capacity Acquisition | Accredited hydraulic performance laboratories compress project-specification approval timelines. |
| Digital Twin-Enabled Predictive Maintenance Platform | Cloud-connected diagnostics create recurring revenue streams in German industrial heating. |
| Joint-Venture Production Localization in China | Domestic GB 19762 certification accelerates access to Yangtze River Delta district heating tenders. |
| REACH-Compliant Seal Material Qualification | Advanced thermoplastic elastomers maintain CE marking as PTFE-based alternatives face SVHC classification. |
Research Approach
Initial hypotheses were tested against primary input from plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads and refined through secondary validation. Bottom-up and top-down triangulation combined facility-level equipment audits with customs trade data, SEC 10-K filings, and national efficiency standard regulatory texts. Field intelligence from German industrial corridor operators and US Sun Belt facility managers grounded competitive positioning assessments.
Variance decomposition across product type, end user, installation channel, and application dimensions structured the analytical framework over the projection horizon. CAGRs derived from segment-level volume and value build-ups calibrated against macroeconomic indicators and regulatory enforcement timelines. Forecast inputs incorporated EU F-Gas Regulation phase-down schedules, US DOE 10 CFR 431 procurement disqualification impacts, and China's GB 19762 tightening trajectories.
Underlying assumptions cover steady regulatory enforcement intensity and stable rare-earth magnet supply availability, with deviation risk concentrated in export control volatility and foundry capacity constraints. Forecasts reflect these assumptions with acknowledgment that accelerated REACH amendments or ISO 9906 laboratory accreditation delays would require model recalibration. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Industrial Condensing Units Market
HVAC Equipment
Steam Heat Exchanger Market
HVAC Equipment
Heat Moisture Exchanger Market
HVAC Equipment
Global HVAC Linesets Market
HVAC Equipment
Air Conditioning Systems Market
HVAC Equipment
France Commercial HVAC Market
HVAC Equipment
US Residential Heat Pump Market
HVAC Equipment
Air Conditioner Quilt Market
HVAC Equipment
Global Variable Refrigerant Flow (VRF) Market
HVAC Equipment
Brazed Plate Heat Exchangers Market
HVAC Equipment
Middle East and Africa Commercial HVAC Market
HVAC Equipment
Residential Furnaces Market
HVAC Equipment
Heating and Cooling Market
HVAC Equipment
United Kingdom District Heating Market
HVAC Equipment
Europe Bus HVAC Market
HVAC Equipment
Asia Pacific Commercial HVAC Market