
 Europe Dehumidifier Market | 2026-2036
Europe Dehumidifier Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Dehumidifier Market Insights
Poland is narrowing its production gap in compressor-based dehumidifier assembly through expanded manufacturing corridors near Wrocław. Munters Group anchors its industrial portfolio with desiccant rotor technology for pharmaceutical and food processing clients across Northern Europe. De'Longhi Appliances S.r.l. dominates the Mediterranean residential segment through brand recognition in Italy and Spain. Meaco (U.K.) Limited specializes in compact refrigerant units for heritage building conservation across British estates.
Europe dehumidifiers are electromechanical systems that extract atmospheric moisture through refrigeration cycles, desiccant absorption, or thermoelectric cooling, typically operating between 30% and 80% relative humidity setpoints with capacities ranging from 0.5 to 1,000 liters per day depending on configuration. These systems protect industrial processes, preserve building fabric, and maintain health-compliant indoor air quality in climates where seasonal humidity exceeds thermal comfort thresholds. Refrigerant dehumidifiers occupy the largest installed base across European residential and light commercial buildings due to mature supply chains and service infrastructure. Desiccant dehumidifiers represent the fastest-growing product category in industrial and pharmaceutical applications where sub-40% relative humidity control is mandatory. The distribution channel structure shows online retail gaining share in homeowner segments while wholesalers and specialty stores retain control over contractor and facility manager procurement flows.
The EU F-Gas Regulation and Ecodesign Directive shape refrigerant selection and minimum energy performance standards, compelling manufacturers to redesign compressor systems around lower-global-warming-potential working fluids. CE marking requirements under the Machinery Directive govern electrical safety and electromagnetic compatibility for all units sold within the European Economic Area. Stakeholders must monitor upcoming revisions to ecodesign thresholds and prepare supply chain transitions ahead of phased refrigerant phase-down schedules.
Market Dynamics
The EU F-Gas Regulation is forcing refrigerant transitions across compressor-based systems while Nordic building retrofits and pharmaceutical cleanroom expansions pull desiccant technology into industrial dominance.
Growth Catalysts
- Cleanroom humidity mandates:Pharmaceutical manufacturing in Germany and the Netherlands requires sub-40% relative humidity control, expanding desiccant rotor installations.
- F-Gas refrigerant phase-down:The EU F-Gas Regulation compels manufacturers to redesign compressor systems around lower-GWP working fluids, accelerating technology refresh cycles.
- Nordic building efficiency retrofits:Sweden and Finland are installing advanced humidity management systems to meet passive house standards and prevent moisture damage in super-insulated envelopes.
Market Restraints
- Copper and aluminum input volatility:Refrigerant dehumidifier production depends on commodity heat exchanger materials subject to energy-intensive processing cost swings.
- Compressor supply concentration:European assembly relies on imported rotary and scroll compressor cores from concentrated East Asian manufacturing bases.
- Desiccant rotor technical ceiling:Silica gel and molecular sieve media face regeneration energy penalties that limit efficiency gains below 0.5 kWh per liter removed.
Strategic Opportunities
- Polish manufacturing corridor expansion:Wrocław-area assembly plants are narrowing the production gap for compressor-based units serving Central European demand.
- Heritage building conservation:British estates and museums require compact refrigerant units with precise setpoint control, creating specialized service contracts.
- Ecodesign Directive tailwinds:Upcoming minimum energy performance standard revisions will disqualify legacy units, forcing replacement demand across residential channels.
Industry Challenges
- Refrigerant handling certification gaps:Service technician pools with F-Gas Category I certification are insufficient for projected installation and maintenance volumes.
- CE marking compliance timelines:Machinery Directive electromagnetic compatibility testing creates bottlenecks for new product introductions.
- Legacy building integration friction:Historic structures with solid masonry walls resist standard vapor barrier approaches, requiring customized psychrometric engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Dehumidifier Market |
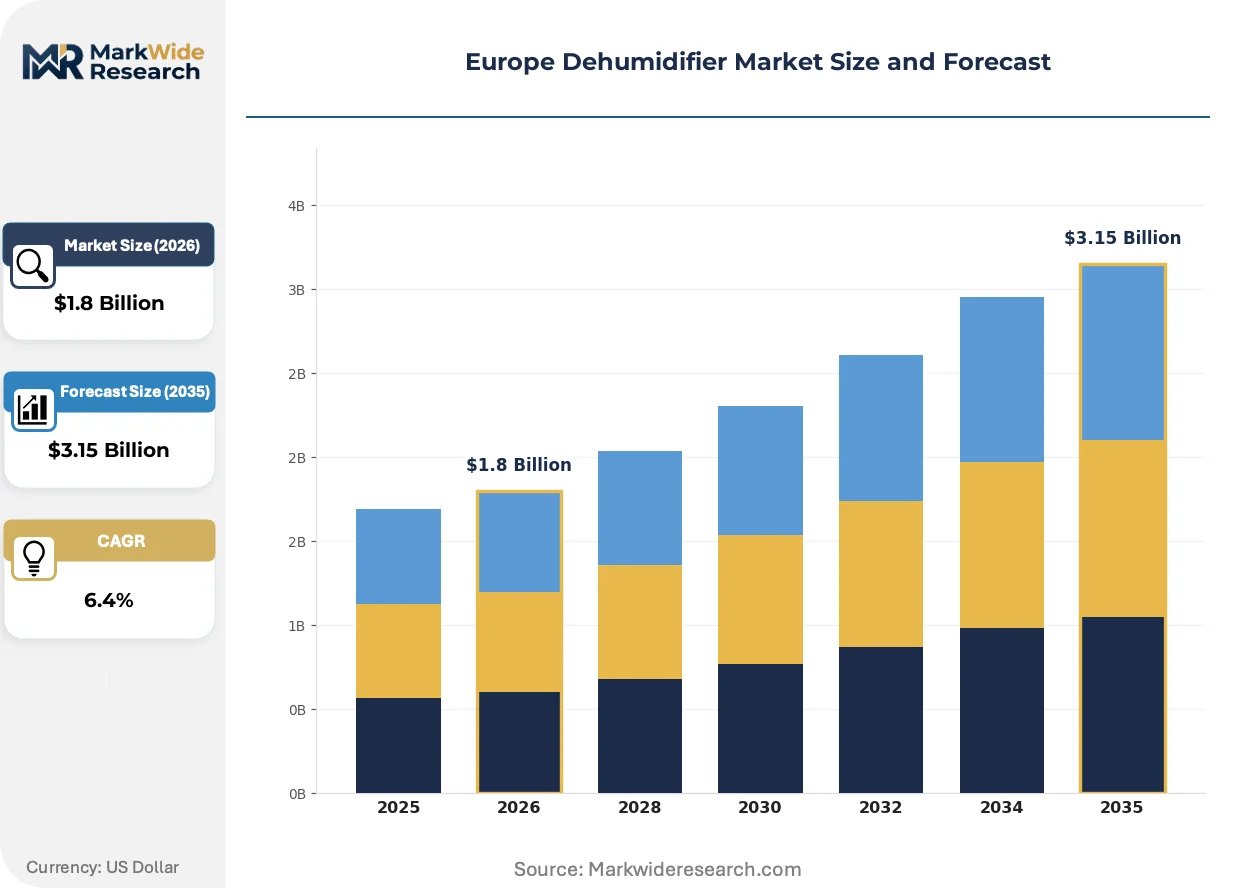
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Desiccant Dehumidifiers, Refrigerant Dehumidifiers, Thermoelectric Dehumidifiers, Ingress Protection Dehumidifiers Application: Residential, Commercial, Industrial, Automotive End User: Homeowners, Contractors, Facility Managers, Automotive Manufacturers Distribution Channel: Online Retail, Specialty Stores, DIY Stores, wholesalers |
| Companies Covered | Whirlpool Corporation, Honeywell International Inc., De’Longhi Appliances S.r.l., AB Electrolux, Munters Group, Desiccant Technologies Group, Condair Group, LG Electronics, Meaco (U.K.) Limited, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Dehumidifier Market Trends and Innovations
Refrigeration and desiccant technologies are converging into hybrid architectures while regulatory pressure on working fluids intensifies and procurement channels fragment between digital platforms and specialized distributors.
Hybrid dehumidification technology is hybridizing refrigerant compression with desiccant rotor stages to capture latent loads across wider temperature ranges. Pharmaceutical cleanroom operators in the Netherlands are piloting these systems for year-round stability without seasonal efficiency collapse. This convergence is compressing the performance gap between single-technology units and premium engineered solutions.
The EU F-Gas Regulation's phasedown schedule is eliminating R-410A and R-134a from new equipment, compelling manufacturers to validate R-32 and R-290 alternatives through redesigned compressor maps and safety enclosures. Industrial refrigeration suppliers are absorbing the largest compliance burden due to higher charge sizes and stricter leak detection mandates. German engineering firms are responding by accelerating in-house testing capacity for flammable refrigerant compatibility.
Facility managers are unbundling equipment purchase from service contracts, preferring separate negotiations for installation, commissioning, and multi-year maintenance. Wholesalers retain contractor procurement flows while online platforms capture homeowner segments with transparent pricing and direct delivery. This channel bifurcation is most pronounced in France and Italy where distributor networks remain entrenched in commercial construction supply chains.
Europe Dehumidifier Market Segmentation
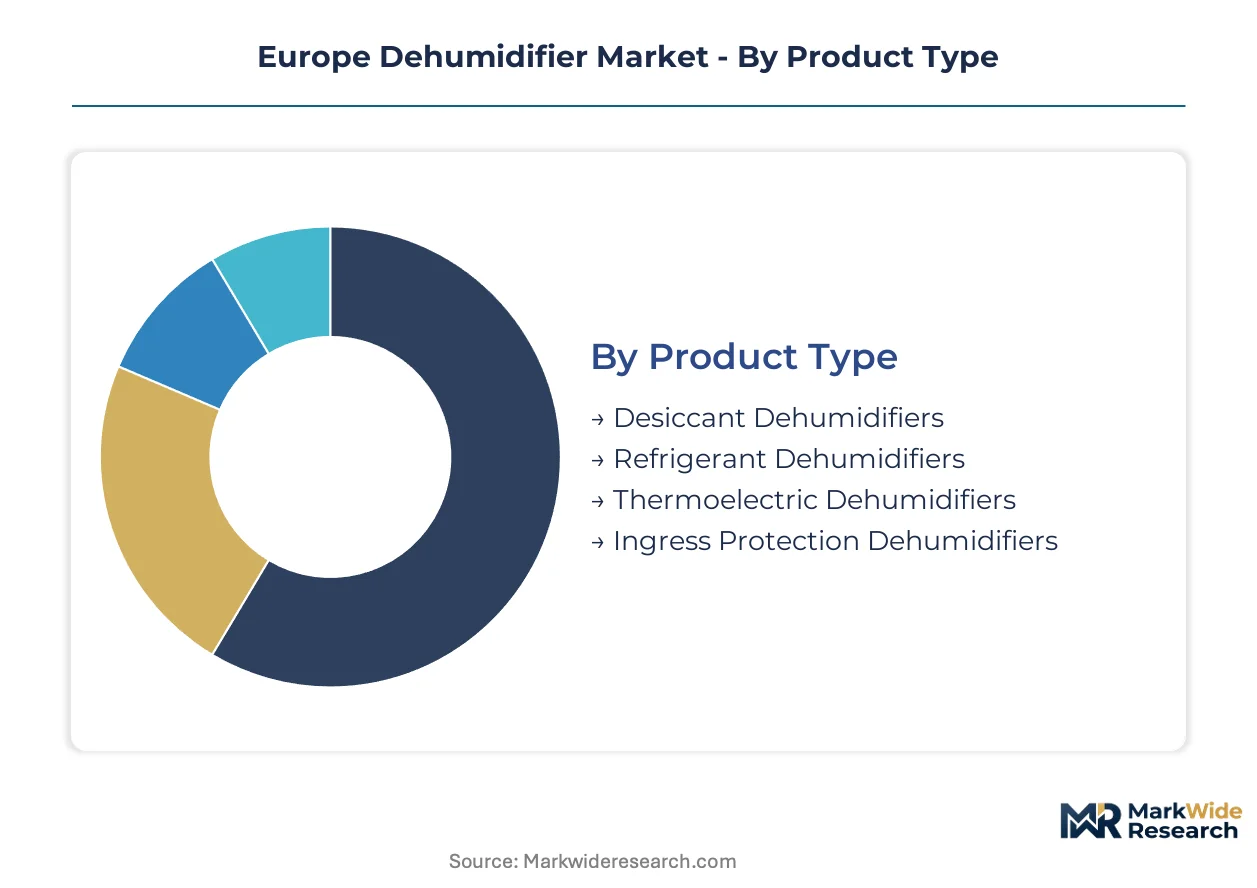
Dehumidifier segmentation in Europe reflects divergent technology maturities, from entrenched refrigerant compression to emerging desiccant rotor systems. Each category channels distinct procurement behaviors, regulatory exposures, and margin structures across residential, commercial, and industrial demand pools.
Product Type:
Mature refrigerant systems dominate installed capacity while desiccant technology accelerates in specialized industrial niches requiring extreme dryness control.
- Desiccant Dehumidifiers:Silica gel or molecular sieve media adsorb moisture through rotating rotor assemblies, achieving relative humidity below 40% impossible for refrigeration cycles. Pharmaceutical cleanrooms in the Netherlands and Germany mandate these systems for powder processing stability, though regeneration energy penalties constrain efficiency gains.
- Refrigerant Dehumidifiers:Vapor-compression cycles condense atmospheric moisture on cooled coils, operating efficiently above 15°C ambient. Sweden and Finland deploy these units extensively in residential retrofits where mature service infrastructure and F-Gas-certified technician pools support maintenance continuity.
- Thermoelectric Dehumidifiers:Peltier-effect solid-state cooling suits compact, low-capacity applications in British heritage properties where compressor noise and vibration threaten artifact preservation.
- Ingress Protection Dehumidifiers:Sealed enclosures rated IP54 and above protect electronics in Nordic offshore wind turbine nacelles and Baltic marine environments.
Refrigerant dehumidifiers retain volume leadership across European residential channels; desiccant systems hold the steepest expansion curve in pharmaceutical and food processing verticals.
Application:
Application segmentation tracks building stock age, industrial process intensity, and regulatory compliance burdens across the continent.
- Residential:Single-family and multifamily dwellings in coastal Mediterranean zones and Northern European basements drive replacement cycles. Ecodesign Directive thresholds disqualify legacy units, forcing upgrade demand in France and Italy.
- Commercial:Hotels, retail, and office buildings in German city centers integrate humidity control with HVAC modernization. CE marking under the Machinery Directive governs electrical safety for all commercial installations.
- Industrial:Food processing, electronics assembly, and battery manufacturing require precision moisture management. Polish manufacturing corridors near Wrocław supply compressor-based units serving Central European industrial demand.
- Automotive:Electric vehicle battery production facilities in Germany and Hungary deploy cleanroom-grade dehumidification to prevent lithium cell contamination during assembly.
Residential applications anchor procurement volumes through replacement cycles; industrial segments climb fastest on pharmaceutical and battery manufacturing expansion.
End User:
End-user categories reveal procurement sophistication gradients, from price-sensitive homeowners to specification-driven facility managers.
- Homeowners:Digital-native buyers in France and Italy favor online retail with transparent pricing and direct delivery, bypassing traditional distributor networks.
- Contractors:Installation professionals source through entrenched wholesaler relationships in commercial construction supply chains, particularly in Italy and Spain.
- Facility Managers:Industrial and institutional buyers unbundle equipment purchase from service contracts, negotiating separate commissioning and multi-year maintenance agreements in the Netherlands and Germany.
- Automotive Manufacturers:Tier-1 suppliers and OEMs specify integrated humidity management systems for battery gigafactories, with procurement centralized at engineering headquarters.
Facility managers command the highest specification intensity; homeowners represent the largest addressable population but lowest per-unit margins.
Distribution Channel:
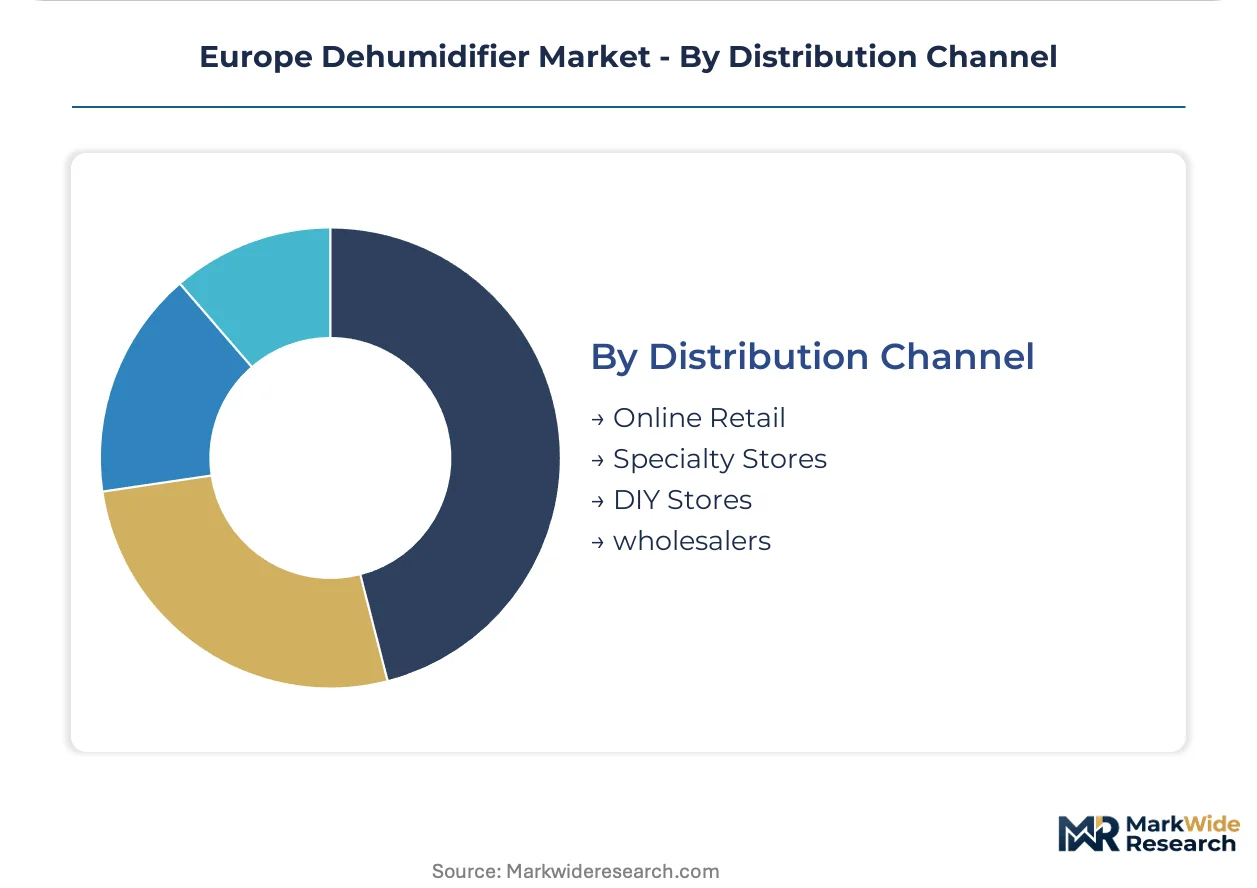
Channel structure bifurcates between digital platforms capturing convenience-driven demand and specialty distributors retaining technical specification control.
- Online Retail:Amazon, manufacturer direct sites, and specialized HVAC platforms aggregate homeowner demand with price transparency and rapid fulfillment across Northern Europe.
- Specialty Stores:Climate control showrooms and HVAC trade counters in Germany and the Netherlands serve contractors requiring technical consultation and immediate availability.
- DIY Stores:Leroy Merlin, B&Q, and regional chains stock residential units for self-installation in France, Spain, and the United Kingdom.
- Wholesalers:Rexel, Sonepar, and regional electrical distributors retain contractor procurement flows with project pricing and credit terms in commercial construction.
Wholesalers retain grip on commercial and industrial procurement; online retail gains fastest in residential replacement markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North Sea-Baltic Corridor rail freight network underpins Central European supply chain integration for dehumidifier component flows.
Germany
Pharmaceutical cleanroom expansions in Ludwigshafen and Leverkusen drive desiccant rotor demand for sub-40% relative humidity control. The EU F-Gas Regulation mandates refrigerant transitions for compressor-based systems sold nationwide. Stuttgart's automotive battery gigafactories deploy industrial-grade humidity management for lithium cell assembly lines.
Netherlands
Rotterdam's port logistics hub channels imported compressor cores to assembly plants across the Benelux region. ECHA chemical safety protocols govern desiccant media handling in food processing applications. Eindhoven's high-tech campus hosts pilot installations of hybrid refrigerant-desiccant systems for semiconductor cleanrooms.
Sweden
Passive house retrofits in Stockholm and Gothenburg require advanced vapor management in super-insulated building envelopes. The country's national building code mandates moisture risk assessments for all deep energy renovations. Malmö's sustainable construction cluster integrates humidity control with district heating recovery systems.
Poland
Wrocław-area manufacturing corridors narrow the production gap for compressor-based units serving Central European demand. CE marking requirements under the Machinery Directive govern electrical safety for all domestically assembled equipment. Katowice's logistics hubs distribute finished units to contractor networks across the Visegrád region.
United Kingdom
British heritage estates and museums require compact refrigerant units with precise psychrometric control for artifact preservation. The UK's building regulations Part L sets minimum efficiency standards for residential humidity management systems. London's commercial property refurbishment sector integrates dehumidification with HVAC modernization in Grade II listed buildings.
Europe Dehumidifier Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in rotor media and compressor supply. The European dehumidifier market structures around three tiers: multinational appliance conglomerates with residential portfolios, industrial engineering groups with desiccant expertise, and regional assemblers serving contractor channels. Strategic archetypes include refrigerant technology platform owners, desiccant rotor specialists, and contract manufacturing aggregators. Competitive moves concentrate on F-Gas compliance transitions and Polish manufacturing corridor expansion.
Within the industrial engineering tier, Munters Group and Condair Group exemplify desiccant-focused platform integrators with European headquarters. De'Longhi Appliances S.r.l. represents the residential appliance conglomerate archetype with Mediterranean market anchoring. These three entities occupy distinct competitive positions without overlapping core technology portfolios.
| Leading Market Players |
|---|
| Whirlpool Corporation |
| Honeywell International Inc. |
| De'Longhi Appliances S.r.l. |
| AB Electrolux |
| Munters Group |
| Desiccant Technologies Group |
| Condair Group |
| LG Electronics |
| Meaco (U.K.) Limited |
| Others |
Pricing and Supply Chain Analysis
The North Sea-Baltic Corridor rail freight network shapes cost dynamics across compressor core imports and desiccant media flows, concentrating supply leverage with East Asian manufacturers while fragmenting downstream price tiers between contractor wholesale and direct-to-homeowner retail channels.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates CE-marked industrial units with F-Gas certification from basic residential models and unbranded contractor-grade equipment. Price differentiation hinges on energy efficiency grade under the Ecodesign Directive and after-sales service bundling for multi-year maintenance contracts. Cost compression in economy tiers is intensifying because Polish manufacturing corridors are narrowing assembly cost gaps with East Asian sources. Homeowners in France and Italy exhibit highest price sensitivity through online retail price comparison, while facility managers in Germany and the Netherlands prioritize specification compliance over unit cost.
Supply Chain Analysis
Copper and aluminum feedstock draws from energy-intensive smelting operations in China, Russia, and Chile, exposing heat exchanger production to electricity cost volatility and carbon border adjustment mechanisms. Compressor cores rest on concentrated rotary and scroll manufacturing in China, South Korea, and Japan, creating single-source vulnerability for European assemblers dependent on maritime container routes. Silica gel and molecular sieve desiccant media sources from specialized chemical processors in Germany and the United States. Distribution runs through Rexel and Sonepar wholesaler networks for contractor procurement, while Amazon and manufacturer direct sites capture residential replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics in Europe dehumidifiers are shifting toward unbundled equipment-service procurement and interoperability between building management systems, creating winner-take-most dynamics for integrators who control both hardware specification and commissioning protocols.
For Market Incumbents: Pre-empt refrigerant technology obsolescence by accelerating in-house R-32 and R-290 validation capacity before F-Gas phase-down deadlines disqualify legacy compressor platforms. Secure backward integration into desiccant rotor media production to defend margin position against silica gel supply concentration. Anchor channel control through captive service technician certification programs that lock contractor loyalty beyond equipment replacement cycles. For New Entrants and Emerging Players: Pursue heritage building conservation contracts across British estates and Nordic museums, where compact thermoelectric units with precision psychrometric control command premium pricing and resist commoditization. Target Polish manufacturing corridor expansion for compressor-based assembly serving Central European industrial demand. Lead with direct digital sales to bypass entrenched wholesaler relationships in France and Italy residential markets. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with neglected climate control divisions lacking standalone scale to absorb F-Gas compliance R&D burdens. Long-term viability favors platform integrators with hybrid refrigerant-desiccant technology portfolios and certified service networks rather than pure equipment manufacturers. Monitor Ecodesign Directive threshold revision announcements as inflection indicators for forced replacement demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| F-Gas Refrigerant Transition | R-32 and R-290 validation capacity determines compressor platform survival under EU phasedown schedules. |
| Desiccant Rotor Media Backward Integration | In-house silica gel production insulates margin from chemical supply concentration and ECHA regulatory exposure. |
| Service Technician Certification Programs | F-Gas Category I training pipelines lock contractor loyalty and create recurring revenue beyond equipment sales. |
| Hybrid System Development | Refrigerant-desiccant convergence captures pharmaceutical cleanroom demand for year-round sub-40% relative humidity stability. |
| Polish Manufacturing Corridor Expansion | Wrocław-area assembly narrows cost gaps with East Asian sources for Central European industrial procurement flows. |
Research Methodology
Operator-level perspectives from facility managers at pharmaceutical cleanrooms, HVAC contractors in commercial construction, procurement leads at industrial distributors, and aftermarket service technicians anchored the qualitative base for this study. Primary interviews combined with secondary validation from EU F-Gas Regulation implementation reports, Ecodesign Directive compliance databases, customs trade records for compressor core imports, and Machinery Directive CE marking registries. Bottom-up unit shipment estimates by product type and application triangulated against top-down market sizing from manufacturer revenue disclosures.
Scenario-bracketing around refrigerant transition timelines and Ecodesign threshold revision schedules shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type technology, application vertical, end-user procurement sophistication, and distribution channel structure. CAGRs derived from regression analysis of historical replacement cycles, building stock renovation rates, and industrial capacity expansion announcements. Forecast inputs incorporated F-Gas phase-down compliance cost absorption assumptions and Nordic passive house retrofit penetration curves.
Sensitivities concentrate around Ecodesign Directive threshold revision timing, copper and aluminum commodity price volatility, and maritime logistics disruption affecting East Asian compressor core deliveries. Forecasts reflect documented assumptions about technician certification pool expansion rates and hybrid technology adoption curves in pharmaceutical applications. Cross-checking against national building code renovation mandate databases and ECHA chemical safety protocol evolution is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Wall Hung Boilers Market
HVAC Equipment
Hydronic Radiators Market
HVAC Equipment
Steam Operated Condensate Pump Market
HVAC Equipment
Germany Commercial HVAC Market
HVAC Equipment
Wall Fan Coil Market
HVAC Equipment
Industrial Refrigeration Equipment Market
HVAC Equipment
United States Residential Heating Equipment Market
HVAC Equipment
Global Air Duct Market
HVAC Equipment
Louver Dampers Market
HVAC Equipment
US Compressed Air Treatment Equipment Market
HVAC Equipment
China Commercial HVAC Market
HVAC Equipment
North America Industrial Air Chiller Market
HVAC Equipment
Warm Air Furnaces Market
HVAC Equipment
Industrial Heating Equipment Market
HVAC Equipment
Steam Humidifiers Market
HVAC Equipment
Europe Ventilation Equipment Market