
 Digital Patient Monitoring Devices Market | 2026-2036
Digital Patient Monitoring Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Patient Monitoring Devices Market Intelligence
Digital patient monitoring hardware is decoupling into FDA-cleared clinical-grade systems and consumer wellness trackers with divergent validation protocols and reimbursement pathways. GE Healthcare anchors its position through deep hospital integration and regulatory engineering capacity. Koninklijke Philips N.V. differentiates via its HealthSuite digital platform that spans acute and ambulatory settings. Medtronic leverages its cardiac implant heritage to dominate connected cardiac monitoring with embedded sensors.
Digital patient monitoring devices encompass sensor-enabled systems that capture, transmit, and analyze physiological parameters such as ECG waveforms, blood oxygen saturation, and continuous glucose levels through wireless protocols for clinical decision support. Bluetooth-enabled wearable monitors lead volume deployment for ambulatory cardiac and glucose tracking, while bedside monitors retain the highest installed-base value in intensive care units. Cellular-connected portable monitors represent the fastest-expanding segment as rural health networks adopt LTE-based remote patient monitoring to extend specialist reach beyond hospital walls.
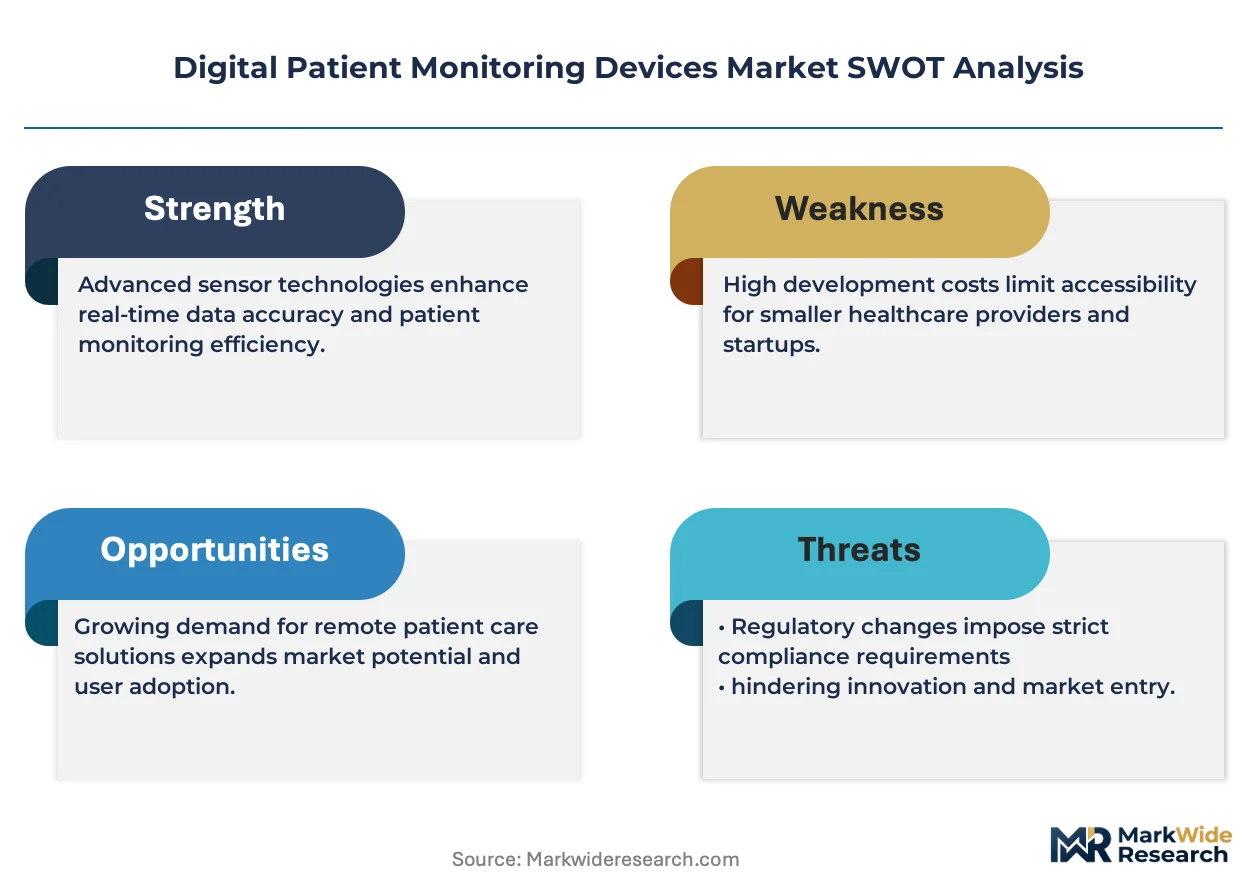
FDA 510(k) clearance timelines and EMA Medical Device Regulation conformity assessments shape product development cadences and market access costs for connected monitoring systems. HIPAA data governance requirements and GDPR health data provisions enforce encryption standards that influence cloud architecture choices across vendor roadmaps. Stakeholders must weigh the capital intensity of multi-jurisdiction regulatory compliance against the margin compression from consumer electronics firms entering preventive monitoring segments.
Market Dynamics
The central structural force reshaping digital patient monitoring is the divergence between clinical-grade validation requirements and consumer wellness accessibility, creating parallel product architectures with incompatible reimbursement pathways and software lifecycle protocols.
Growth Catalysts
- Remote Patient Monitoring Reimbursement:CMS expanded CPT codes for chronic care management in the United States, reimbursing physicians for data review from connected devices. This payment infrastructure accelerates hospital-at-home program adoption.
- Bluetooth Low Energy 5.3:The protocol's improved power efficiency and range enable multi-day cardiac patch monitors with continuous streaming. Device manufacturers are migrating legacy proprietary radio designs to this standard.
- Japan's Super-Aged Society:METI targets 75% of elderly chronic disease management through remote monitoring by 2030. Municipal health cooperatives in rural prefectures deploy cellular-enabled glucose monitors to reduce clinic visits.
Market Restraints
- Semiconductor Supply Concentration:Advanced biosensors and edge AI processors depend on TSMC and Samsung foundry capacity concentrated in Taiwan and South Korea. Geopolitical friction threatens component availability for multi-channel ECG systems.
- FDA 510(k) Cybersecurity Burden:The 2023 guidance requiring SBOM documentation and pre-market penetration testing adds 8-14 months to clearance timelines. Smaller device developers lack security engineering bandwidth to comply.
- Consumer Wearable Substitution:Apple Watch and Samsung Galaxy Watch ECG functions capture wellness-oriented users who might otherwise adopt prescribed monitors. This price-compression limits addressable market expansion for clinical-grade ambulatory devices.
Strategic Opportunities
- Rural India Connectivity Gap:The PLI scheme for medical electronics and expanding 4G coverage in Bihar and Uttar Pradesh create first-mover potential for low-cost cellular pulse oximeters. State governments pilot RPM for maternal health.
- EU AI Act Medical Device Classification:The regulation's risk-based framework for machine-learning diagnostic algorithms creates compliance consulting demand. Vendors with pre-validated MDR technical documentation can accelerate market entry.
- Continuous Glucose Monitor-Pump Convergence:Integration of real-time glucose data with closed-loop insulin delivery represents unclaimed white space beyond Medtronic and Dexcom core territories. Diabetes technology startups target hybrid closed-loop systems.
Industry Challenges
- Embedded Security Engineering Talent:FDA and EMA cybersecurity mandates require firmware developers with medical device and cryptography expertise. This skill intersection commands premium compensation and extends hiring cycles.
- Legacy Hospital IT Integration:HL7 FHIR adoption varies across health systems, forcing device vendors to maintain multiple API connectors. Epic and Cerner EHR interoperability testing consumes product engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Patient Monitoring Devices Market |
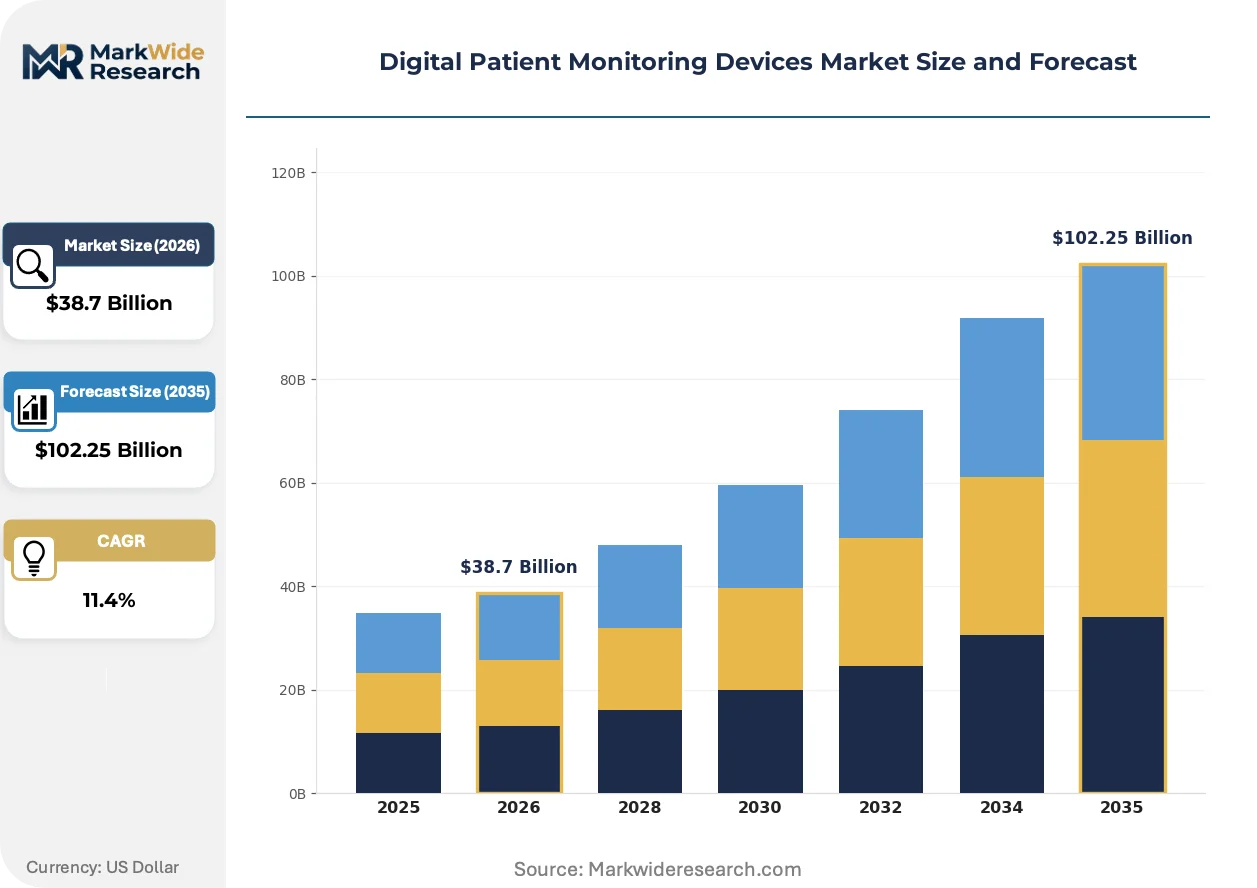
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $102.25 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Wearable Monitors, Bedside Monitors, Portable Monitors, Smartphone Applications Technology: Bluetooth, Wi-Fi, Cellular, Radio Frequency End User: Hospitals, Home Care, Clinics, Rehabilitation Centers Application: Cardiac Monitoring, Blood Glucose Monitoring, Respiratory Monitoring, Temperature Monitoring |
| Companies Covered | GE Healthcare, Koninklijke Philips N.V., Medtronic, Abbott, Athenahealth, OMRON Healthcare, Inc., Fitbit, Inc., Garmin Ltd., VitalConnect, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Patient Monitoring Devices Market Strategic Shifts & Innovations
Edge computing architectures are redistributing analytical workloads from cloud data centers to device-local processors, altering power budgets, form factors, and regulatory validation scope for connected monitors.
Photoplethysmography is absorbing multi-parameter sensing responsibilities previously requiring discrete hardware modules. Advanced signal processing algorithms extract blood pressure, respiratory rate, and atrial fibrillation indicators from optical heart rate sensors. Cardiology practices in Germany and Japan are validating these integrated approaches against catheter-based reference standards. The technology is absorbing market share from traditional cuff-based ambulatory blood pressure monitors by reducing patient burden and eliminating inflation artifacts.
EMA Medical Device Regulation Article 10.4 post-market surveillance requirements are forcing manufacturers to implement automated vigilance reporting systems. The mandate obligates systematic analysis of serious incidents and trend reporting across distributed device fleets. Intensive care monitor vendors with European installed bases are restructuring quality management systems to handle real-time adverse event triage. This regulatory architecture is compressing product update cycles and favoring vendors with mature software-as-a-medical-device capabilities.
Hospital procurement committees are unbundling device hardware from data analytics subscriptions, reversing decade-long bundled service contracts. Acute care facilities in the United States negotiate separate agreements for monitor capital expenditure and cloud platform access. This disaggregation exposes pure-play hardware manufacturers to margin pressure while enabling software-native entrants to compete without manufacturing assets. The pattern is most pronounced in IDN consolidations where centralized IT governance overrides traditional vendor relationships.
Digital Patient Monitoring Devices Market Segmentation
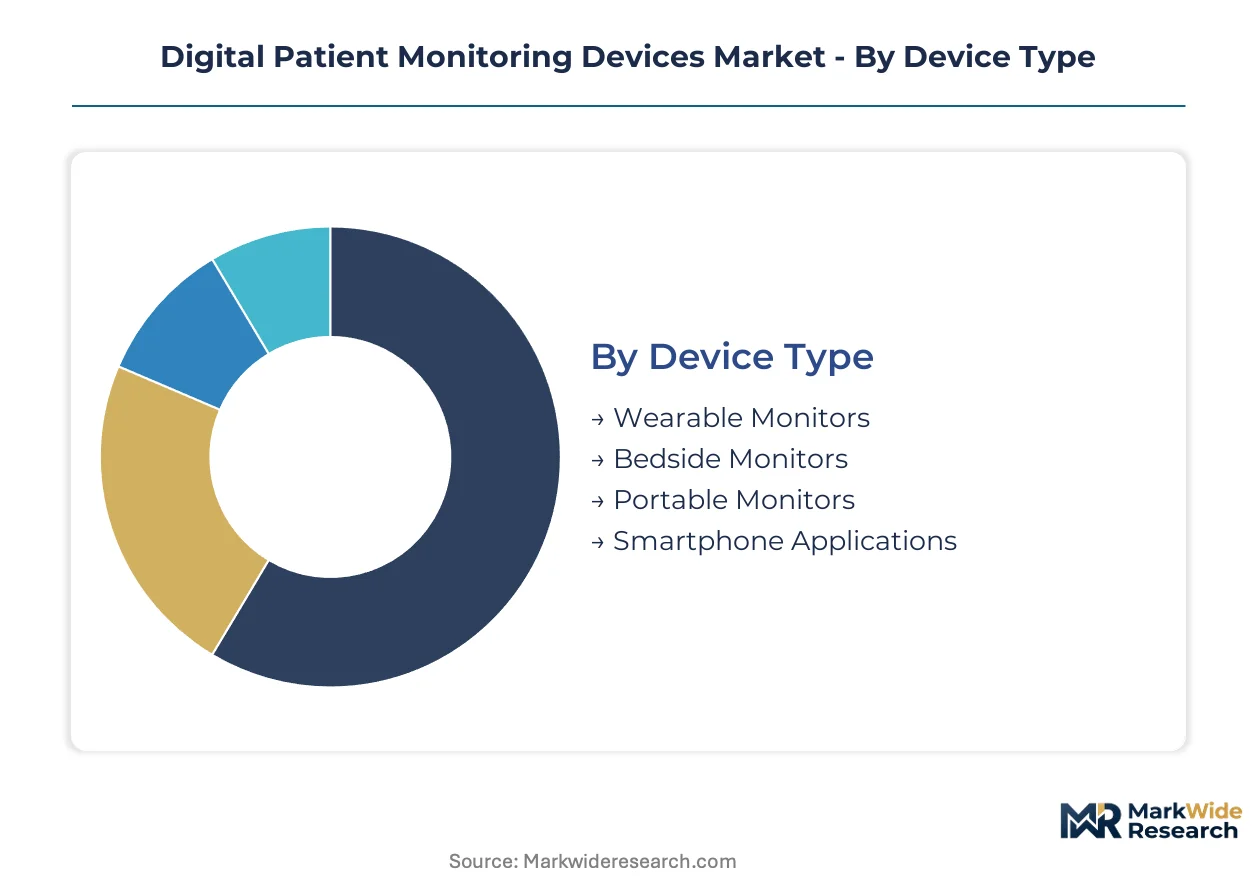
Device architectures in digital patient monitoring diverge sharply based on validation protocols, power budgets, and reimbursement eligibility. Each segment category reflects distinct upgrade cycles—from hospital capital equipment refresh timelines to consumer electronics replacement rates—that reshape vendor competitive positioning.
Device Type:
Wearable monitors command the shortest replacement cycles as battery degradation and sensor drift drive 18-24 month refresh rates among ambulatory cardiac users. Bedside monitors follow hospital capital planning cycles with 7-10 year service intervals, while portable monitors occupy an intermediate position shaped by rural health network expansion schedules.
- Wearable Monitors:Continuous glucose patches and multi-lead ECG chest straps integrate flexible printed circuit substrates with skin-conformable adhesives. Demand concentrates among Medicare-enrolled chronic disease patients in Florida and Arizona where CMS reimbursement for remote patient monitoring has achieved full operational scale.
- Bedside Monitors:Multi-parameter intensive care systems combine invasive blood pressure transducers, pulse oximetry, and capnography in modular rack configurations. Academic medical centers in Massachusetts and California anchor procurement volume as these institutions prioritize FDA-cleared alarm integration with Epic EHR systems.
- Portable Monitors:Cellular-enabled devices with LTE-M connectivity extend specialist monitoring to homebound populations. Rural health cooperatives in Japan's Tottori and Shimane prefectures deploy these for elderly diabetes management.
- Smartphone Applications:Software-only solutions leveraging device camera and accelerometer sensors for heart rate variability and respiratory rate estimation. Wellness-oriented consumers in Germany's private insurance market adopt these as supplementary tracking tools.
Wearable monitors sit at the top of the volume ranking, with portable monitors climbing the fastest as cellular coverage expands into underserved regions.
Technology:
Wireless protocol selection determines power autonomy, transmission range, and regulatory classification burden for connected monitoring systems. Cost tiers separate clinical-grade validated radios from consumer wellness implementations with divergent cybersecurity documentation requirements.
- Bluetooth:Low Energy 5.3 implementations enable 72-hour continuous cardiac patch monitoring with sub-10mW power draw. Ambulatory monitoring services in the United States standardize on this protocol for Medicare-reimbursed remote patient monitoring programs.
- Wi-Fi:Hospital-grade 802.11ac/ax connectivity supports high-frequency waveform transmission for intensive care central station displays. German university hospitals in Berlin and Munich prioritize Wi-Fi 6E implementations to reduce 2.4GHz spectrum congestion from legacy medical devices.
- Cellular:LTE-M and NB-IoT modules enable standalone operation without smartphone tethering. India's expanding 4G infrastructure in Bihar and Uttar Pradesh creates first-mover deployment opportunities for maternal health monitoring.
- Radio Frequency:Proprietary sub-GHz designs persist in legacy implantable cardiac device communication. Replacement demand concentrates among health systems with substantial Medtronic pacemaker installed bases.
Bluetooth dominates current shipment volume, with cellular protocols gaining share fastest as standalone rural deployments multiply.
End User:
Customer type segmentation maps directly to purchasing authority structures and total cost of ownership calculation methods. Hospital procurement committees evaluate 10-year lifecycle costs against home care settings where out-of-pocket sensitivity shapes device selection.
- Hospitals:Integrated delivery networks negotiate enterprise agreements spanning bedside monitors, central stations, and middleware analytics. IDN consolidations in Texas and Pennsylvania are unbundling hardware from software subscriptions.
- Home Care:Skilled nursing facilities and private duty agencies deploy cellular-enabled devices for post-acute transition management. Japan's municipal health cooperatives drive volume as METI targets 75% elderly chronic disease management through remote monitoring.
- Clinics:Federally qualified health centers in the United States leverage HRSA funding for remote patient monitoring expansion. Cardiology and endocrinology practices prioritize Bluetooth-enabled devices with streamlined CMS documentation workflows.
- Rehabilitation Centers:Post-stroke and cardiac rehabilitation programs integrate wearable monitors for supervised home exercise programs. German rehabilitation clinics (Reha-Kliniken) in Bavaria lead adoption of integrated physical therapy monitoring systems.
Hospitals retain the highest installed-base value, with home care expanding most quickly as hospital-at-home reimbursement matures.
Application:
Clinical indication determines sensor modality, algorithm validation requirements, and regulatory pathway complexity. Maturity gradients separate decades-established cardiac monitoring from emerging multi-parameter optical sensing applications.
- Cardiac Monitoring:Multi-lead ECG systems, implantable loop recorders, and photoplethysmography-based atrial fibrillation detection. The United States dominates volume through CMS reimbursement for ambulatory arrhythmia detection.
- Blood Glucose Monitoring:Factory-calibrated continuous glucose monitors with 10-14 day sensor wear times. Integration with closed-loop insulin delivery systems represents the steepest expansion trajectory beyond incumbent vendor territories.
- Respiratory Monitoring:Capnography, pulse oximetry, and acoustic respiratory rate sensing for sleep apnea and COPD management. German pulmonology practices validate optical multi-parameter approaches against polysomnography reference standards.
- Temperature Monitoring:Continuous wearable thermometers for infection detection and fertility tracking. Consumer wellness channels in Japan's aging prefectures drive volume for non-clinical applications.
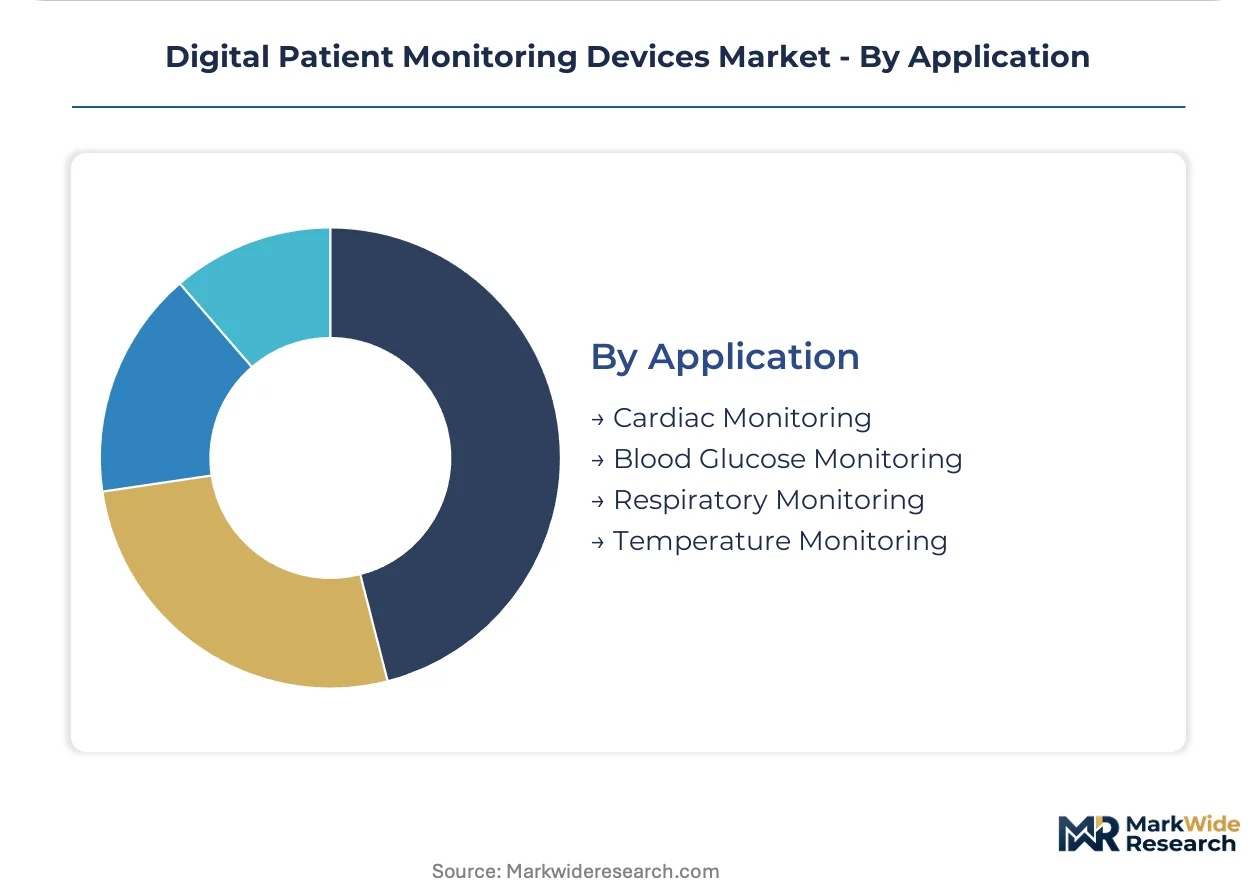
Cardiac monitoring commands the largest revenue base, with blood glucose monitoring climbing fastest as closed-loop diabetes technology converges.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biomedical engineering talent clusters in Boston, Basel, and Tokyo anchor the geographic distribution of digital patient monitoring innovation. Regulatory science expertise concentrates near FDA headquarters in Maryland and EMA offices in Amsterdam. Manufacturing scale advantages favor established medtech corridors with mature supplier ecosystems.
United States
Medicare reimbursement infrastructure for remote patient monitoring drives hospital-at-home program expansion across Florida and Arizona retirement corridors. FDA 510(k) clearance timelines shape product development cadences for connected cardiac monitors. Greater Boston hosts the highest density of venture-backed digital health startups focused on ambulatory glucose tracking.
Germany
Reimbursement pathways through statutory health insurance funds enable broad adoption of prescribed wearable monitors. EMA Medical Device Regulation conformity assessments enforce rigorous post-market surveillance obligations on intensive care monitor vendors. Berlin and Munich university hospitals prioritize Wi-Fi 6E implementations to reduce spectrum congestion in crowded clinical environments.
Japan
METI targets 75% of elderly chronic disease management through remote monitoring by 2030, driving municipal procurement of cellular-enabled glucose devices. PMDA consultation procedures for software-as-a-medical-device accelerate validation timelines for algorithm-driven diagnostic tools. Tottori and Shimane prefectures deploy portable monitors to reduce clinic visits among dispersed rural populations.
India
The PLI scheme for medical electronics attracts domestic manufacturing investment for low-cost pulse oximeters targeting maternal health programs. CDSCO medical device rules create regulatory clarity for imported Bluetooth-enabled cardiac patches. Expanding 4G infrastructure in Bihar and Uttar Pradesh enables first-mover deployment of standalone cellular monitors.
Digital Patient Monitoring Devices Market Key Industry Players
Capital-heavy producers compete with asset-light designers across divergent validation protocols and reimbursement pathways. The market structure separates into FDA-cleared clinical-grade systems requiring multi-year regulatory investment and consumer wellness trackers with compressed development cycles. Three archetypes dominate: diversified medtech conglomerates with hospital integration depth, cardiac-focused specialists leveraging implant heritage, and consumer electronics entrants exploiting retail distribution scale. Competitive moves concentrate on unbundling hardware from analytics subscriptions and securing EHR interoperability certifications.
Among diversified health technology conglomerates, GE Healthcare and Koninklijke Philips N.V. occupy positions spanning acute and ambulatory care settings. Medtronic represents the cardiac-specialist archetype with embedded sensor expertise. These three entities exemplify the tier of vendors capable of sustaining multi-jurisdiction regulatory compliance engineering and enterprise-scale hospital IT integration.
| Leading Market Players |
|---|
| GE Healthcare |
| Koninklijke Philips N.V. |
| Medtronic |
| Abbott |
| Athenahealth |
| OMRON Healthcare, Inc. |
| Fitbit, Inc. |
| Garmin Ltd. |
| VitalConnect |
| Others |
Cost & Logistics Intelligence
Hospital procurement committee unbundling of hardware from analytics subscriptions forces device vendors to restructure revenue models and compress manufacturing cost bases across Bluetooth-enabled cardiac patches and cellular glucose monitors.
Pricing Analysis
The bundled-versus-unbundled service split now defines competitive positioning as IDN consolidations in Texas and Pennsylvania negotiate separate capital expenditure and cloud platform agreements. Pricing stratifies across FDA-cleared clinical systems, CE-marked hospital-grade devices, and consumer wellness tiers with divergent cybersecurity documentation burdens. Cost compression in ambulatory cardiac monitors intensifies because Apple Watch ECG substitution limits premium capture for prescribed devices. Home care settings exhibit highest price sensitivity due to out-of-pocket exposure, while academic medical centers prioritize 10-year lifecycle cost certainty over unit economics.
Supply Chain Analysis
India's PLI scheme for medical electronics and domestic-content mandates in Japan's municipal health cooperatives are reshaping sourcing patterns for low-cost pulse oximeters and cellular-enabled glucose devices. Advanced biosensors and edge AI processors draw from Taiwan, South Korea, and United States foundry capacity. Single-source vulnerability concentrates in TSMC advanced node production for multi-channel ECG systems. Distribution runs through GPO contracts for hospital systems and direct-to-clinic arrangements for ambulatory monitoring services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion trajectories favor vendors capturing software-as-a-medical-device recurring revenue as hardware commoditization accelerates across Bluetooth cardiac patch segments.
For Market Incumbents: Cement EHR interoperability certifications with Epic and Cerner systems as defensive moats against consumer electronics entrants. Deepen firmware security engineering capabilities to absorb FDA 510(k) cybersecurity burden without timeline extension. Capacity addition in India's PLI-eligible manufacturing zones offsets semiconductor supply concentration risk. For New Entrants and Emerging Players: Rural health cooperatives in Japan's Tottori prefecture and India's Bihar state represent the most penetrable geography for standalone cellular monitors without smartphone tethering. Federally qualified health centers in the United States offer white-space access through HRSA-funded remote patient monitoring expansion. Go-to-market execution should prioritize streamlined CMS documentation workflows for Medicare reimbursement eligibility. For Investors and Strategic Acquirers: Asymmetric upside sits with software-native monitoring platforms unburdened by manufacturing asset intensity across the 5-10 year viability window. Acquisition target archetypes include validated algorithm developers with pre-cleared MDR technical documentation and established hospital IT integration pathways. The signal to watch is EU AI Act medical device classification enforcement creating compliance consulting demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Epic EHR interoperability certification locks in bedside monitor procurement at academic medical centers in Massachusetts. |
| Software Companion Development | Edge AI algorithm validation for photoplethysmography blood pressure estimation displaces traditional cuff-based ambulatory monitors. |
| Reimbursement Strategy | CMS CPT code expansion for chronic care management data review accelerates hospital-at-home program adoption in Florida. |
| CE Marking Pathway | EMA MDR Article 10.4 post-market surveillance compliance enables European intensive care monitor fleet expansion. |
| FDA Submission | 510(k) clearance with pre-market SBOM documentation and penetration testing secures Medicare-reimbursed remote patient monitoring eligibility. |
Research Approach
Multiple input streams — primary interviews with hospital purchasing committees, biomedical engineers, and GPO contracts managers, alongside secondary validation against FDA 510(k) filings, CMS Medicare reimbursement databases, and EMA MDR conformity assessments — were reconciled through bottom-up shipment modeling and top-down market sizing triangulation.
Data-stream reconciliation across device type, wireless protocol, end user, and clinical application dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from installed base refresh cycle analysis and reimbursement pathway maturity curves. Forecast inputs incorporated cellular coverage expansion trajectories in rural India and Japan's METI remote monitoring penetration targets.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA cybersecurity guidance evolution, TSMC foundry capacity allocation, and consumer wearable clinical feature expansion. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Europe Remote Patient Monitoring Systems Market
Patient Monitoring
United States Cardiac Holter Monitor Market
Patient Monitoring
Italy Patient Monitoring Market
Patient Monitoring
North America Body Temperature Monitoring Market
Patient Monitoring
Blood Pressure Monitors Market
Patient Monitoring
Pain Monitoring Devices Market
Patient Monitoring
Global Ambulatory Blood Pressure Monitoring (ABPM) Devices Market
Patient Monitoring
Heart Beat Monitor and Sensor Market
Patient Monitoring
Brain Tissue Oxygen Monitoring Systems Market
Patient Monitoring
US Remote Patient Monitoring and Care Market
Patient Monitoring
South America Patient Monitoring Market
Patient Monitoring
Oman Blood Glucose Monitoring Market
Patient Monitoring
MRI Compatible Patient Monitoring Systems Market
Patient Monitoring
ECG Monitoring System Market
Patient Monitoring
Multi-Item Patient Monitor Market
Patient Monitoring
Global Smart Pulse Oximeters Market