
 No.4 Fuel Oil Market | 2026-2036
No.4 Fuel Oil Market Size, Share, and Industry Trends Forecast 2026-2036
No.4 Fuel Oil Market Analytics
Market Context with Strategic Players
India's refining capacity expansion is reconfiguring residual fuel export flows across the Indian Ocean basin. ExxonMobil leverages its integrated Gulf Coast refining network to sustain heavy fuel oil blending dominance in the Americas. Indian Oil Corporation Ltd anchors domestic supply security through its Paradip and Vadinar refinery complexes. Vitol competes aggressively in spot arbitrage between Singapore and Rotterdam pricing hubs.
Technical Definition and Structural Segments
No.4 fuel oil denotes a medium-viscosity residual fuel blend with a maximum viscosity of 5.8 cSt at 40°C and sulfur content typically ranging from 0.5% to 2.0%, produced through vacuum distillation and catalytic cracking of heavier crude fractions. The product serves primarily as a commercial and industrial heating fuel where combustion equipment tolerates moderate ash and sediment levels. Residual fuel oil occupies the mature volume core of the product type split, while marine fuel oil carries the fastest structural growth as dual-fuel engine retrofits expand compliant bunker demand. Power generation end users concentrate margin pools in long-term utility contracts, whereas maritime buyers fragment procurement across spot and term structures.
Regulatory Frame and Forward-Looking Close
The International Maritime Organization enforces sulfur caps through MARPOL Annex VI, while the US EPA administers stationary source emissions standards under Clean Air Act provisions; both frameworks directly constrain allowable sulfur and particulate levels in residual fuel formulations. India's Central Pollution Control Board and China's Ministry of Ecology and Environment impose parallel regional limits on industrial boiler emissions, shaping refinery upgrading investments and product slate decisions. Stakeholders must monitor scrubber installation rates versus LNG dual-fuel adoption curves to calibrate residual fuel demand assumptions for maritime applications.
Market Dynamics
Maritime fuel sulfur regulations are compressing residual fuel demand curves while forcing refinery upgrading investments across the US Gulf Coast, Indian Ocean basin, and East Asian manufacturing corridors.
Growth Catalysts
- IMO 2020 sulfur caps:MARPOL Annex VI enforcement continues to drive compliant bunker fuel blending demand as dual-fuel engine retrofits expand across container and bulk carrier fleets.
- Industrial heating fuel baseload:Commercial boiler operators in northern US states and Northeast Asian manufacturing zones maintain residual fuel procurement for cost-competitive thermal energy.
- Vacuum distillation capacity additions:Indian and Chinese refiners are expanding residual fuel processing units to capture arbitrage between heavy crude discounts and compliant product premiums.
Market Restraints
- Crude sulfur price volatility:Heavy sour crude differentials swing with OPEC+ production decisions, compressing refinery margin predictability for residual fuel slate optimization.
- LNG bunkering infrastructure buildout:Singapore, Rotterdam, and Shanghai port authorities are expanding liquefied natural gas refueling capacity that substitutes residual fuel demand in deep-sea shipping.
- US EPA stationary source standards:Clean Air Act provisions tightening particulate limits are forcing industrial boiler operators toward natural gas or distillate fuel switching.
Strategic Opportunities
- Scrubber-equipped vessel refueling hubs:Panama Canal, Gibraltar, and Fujairah port operators can capture high-sulfur residual fuel demand from scrubber-retrofitted bulk carriers.
- Carbon border adjustment mechanisms:EU Green Deal implementation creates compliance fuel blending opportunities for low-carbon residual formulations entering European industrial markets.
- Refinery residue upcycling technologies:Solvent deasphalting and delayed coking integration enables higher-value product extraction from vacuum residuum streams.
Industry Challenges
- Marine fuel quality testing capability gaps:Bunker fuel suppliers face ISO 8217 specification verification delays at secondary ports lacking onboard mass spectrometry equipment.
- Residual fuel-chemical feedstock integration:Refinery operators struggle to balance asphalt, carbon black feedstock, and fuel oil slate decisions against volatile construction and tire manufacturing demand.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | No.4 Fuel Oil Market |
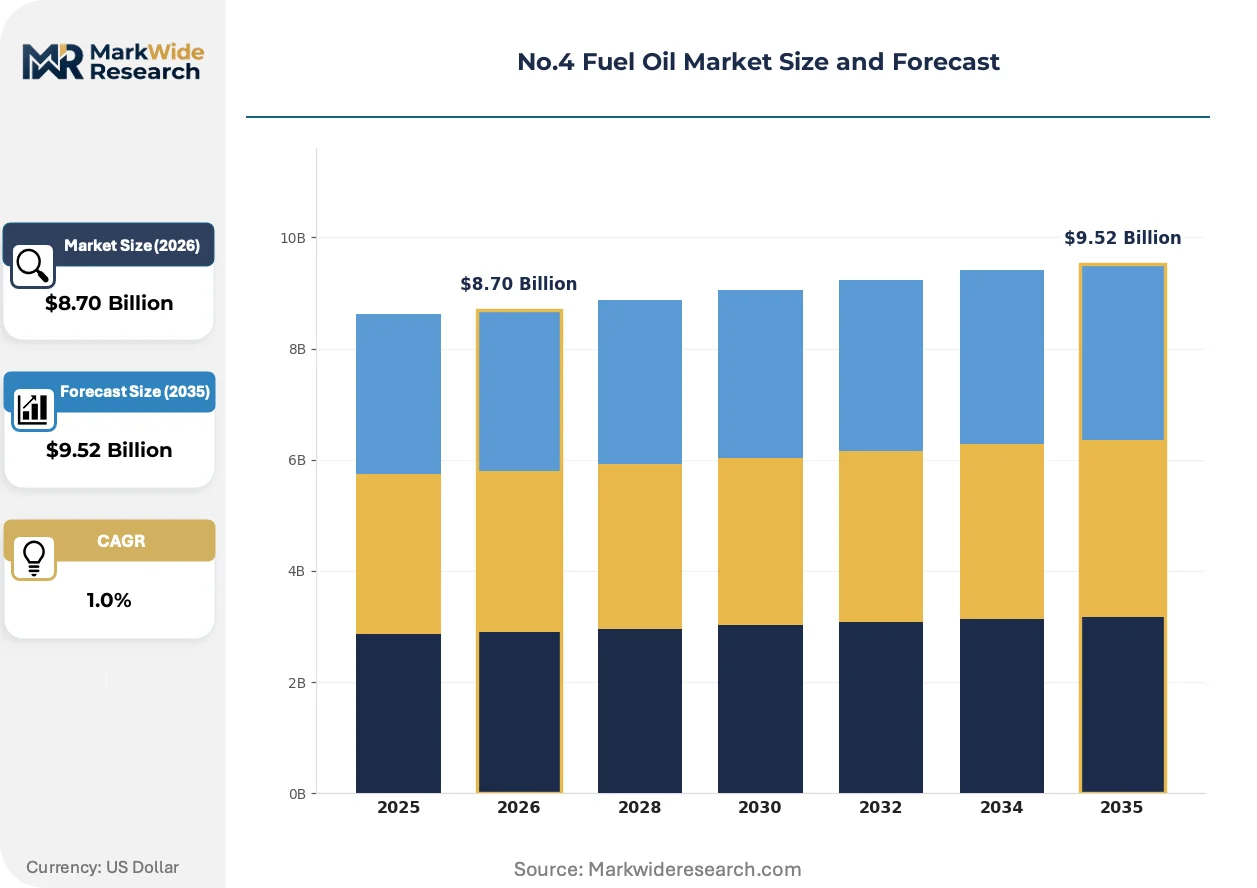
| Market Size in 2026 | $8.70 Billion |
| Market Size in 2035 | $9.52 Billion |
| CAGR (2026 – 2036) | 1.0% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Residual Fuel Oil, Marine Fuel Oil, Industrial Fuel Oil, Heating Oil End User: Power Generation, Maritime, Manufacturing, Commercial Heating Application: Combustion Engines, Boilers, Turbines, Space Heating Distribution Channel: Direct Sales, Wholesalers, Retailers, Online Platforms |
| Companies Covered | Chevron, Indian Oil Corporation Ltd, ExxonMobil, Shell, Vitol, Lukoil, Bharat Petroleum Corporation Limited, Neste, Crown Oil Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
No.4 Fuel Oil Market Evolving Landscape
Refinery configuration decisions and maritime engine technology trajectories are fragmenting residual fuel demand into sulfur-specification tiers while compressing traditional heavy fuel oil volume pools.
Exhaust gas cleaning systems (scrubbers) are rendering obsolete the assumption that IMO 2020 would eliminate high-sulfur residual fuel demand. Bulk carrier and tanker operators with scrubber retrofits continue procuring 3.5% sulfur bunkers at port hubs including Singapore, Rotterdam, and Houston. This bifurcation is preserving residual fuel refining economics while splitting the marine market into parallel specification tracks.
REACH authorization requirements for polycyclic aromatic hydrocarbons in residual fuel formulations are tightening European industrial supply chains. German and Dutch refinery operators face reformulation costs for heating fuel sold to commercial boiler segments. The compliance burden concentrates on small-scale industrial distributors lacking in-house blending capabilities.
Long-term utility contracts are fragmenting into index-linked shorter tenors as power generators seek fuel oil procurement flexibility against renewable dispatch volatility. US Northeast grid operators and Japanese regional utilities now layer residual fuel purchases across quarterly rather than annual commitments. This compression is visible in New York Harbor and Chiba inventory positioning strategies.
No.4 Fuel Oil Market Segmentation
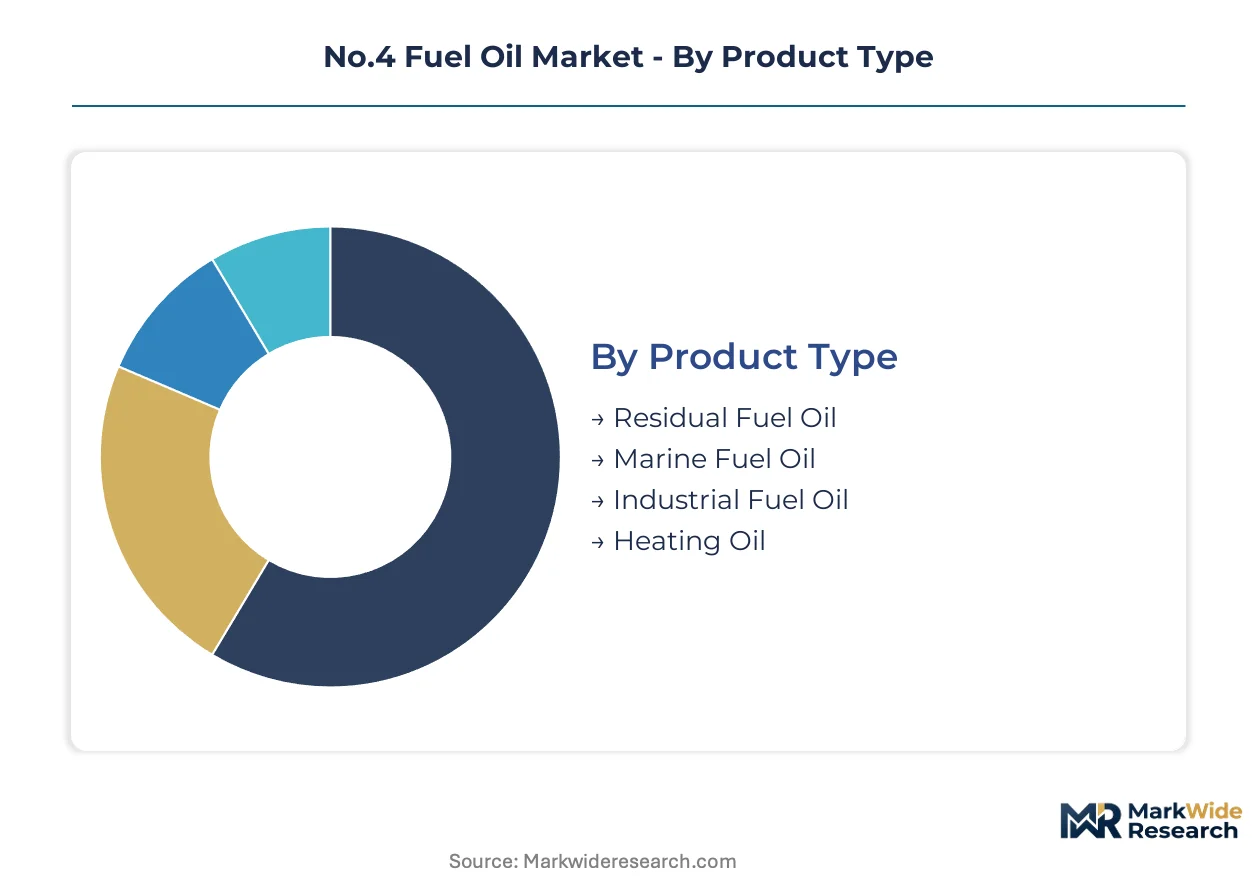
No.4 fuel oil demand fragments across sulfur specifications, end-use equipment tolerances, and procurement contract structures. Refiners configure vacuum distillation and catalytic cracking units to serve these parallel demand tracks with distinct margin profiles.
Product Type:
Combustion equipment tolerances and regulatory sulfur caps determine which residual fuel grade operators can burn without engine damage or compliance violations.
- Residual Fuel Oil:Heavy vacuum residuum blended with cutter stock to achieve viscosity specifications up to 5.8 cSt at 40°C. US Gulf Coast refiners and Indian Oil Corporation's Paradip complex dominate supply for industrial boiler operators in northern US states and Indian manufacturing zones. Established volume favors this segment; emerging adoption favors marine fuel oil.
- Marine Fuel Oil:IMO 2020-compliant formulations with sulfur content capped at 0.5% for open-ocean burning, or 3.5% high-sulfur grades for scrubber-equipped vessels. Singapore and Rotterdam bunkering hubs see the steepest expansion trajectory as dual-fuel engine retrofits accelerate across container fleets.
- Industrial Fuel Oil:Medium-viscosity grades tailored to stationary combustion equipment in cement kilns and steel reheating furnaces.
- Heating Oil:Light residual cuts optimized for commercial building space heating in Northeast Asian and US Northeast markets.
Residual fuel oil commands the mature volume core; marine fuel oil gains share fastest from regulatory-driven fleet renewal.
End User:
Procurement scale and contract duration vary sharply across these demand pools, from fragmented spot bunkering to decade-long utility supply agreements.
- Power Generation:Grid operators in Japan and the US Northeast layer residual fuel purchases across quarterly index-linked contracts rather than annual commitments, seeking flexibility against renewable dispatch volatility.
- Maritime:Bulk carrier and tanker operators fragment procurement across spot Singapore-Rotterdam arbitrage and term contracts with integrated trading houses. Scrubber retrofits preserve high-sulfur demand at Panama Canal and Fujairah refueling hubs.
- Manufacturing:Cement and steel producers in China and India anchor residual fuel consumption for process heat where natural gas infrastructure remains underdeveloped.
- Commercial Heating:Building operators in Germany and the Netherlands face REACH-driven reformulation costs as polycyclic aromatic hydrocarbon limits tighten.
Power generation concentrates margin in long-tenor contracts; maritime procurement fragments across pricing hubs and sulfur specifications.
Application:
Equipment metallurgy and emission control systems dictate fuel viscosity and ash tolerance across these combustion modes.
- Combustion Engines:Low-speed marine diesel engines and stationary power units require fuel treatment systems to handle residual fuel sediment and cat fines.
- Boilers:Industrial steam generators in US manufacturing corridors and Indian chemical parks tolerate higher ash content than turbine applications.
- Turbines:Power utilities in Japan specify lower viscosity cuts to prevent fuel nozzle coking and hot corrosion of turbine blades.
- Space Heating:Commercial building operators in the US Northeast prioritize pour point specifications for cold-weather handling.
Boiler applications retain the broadest equipment base; turbine specifications command premium blending precision.
Distribution Channel:
Logistics infrastructure and credit risk allocation shape how fuel moves from refinery gate to end-use burner tip.
- Direct Sales:Integrated refiners like ExxonMobil supply utility and maritime accounts through captive terminal networks, capturing margin from blending to delivery.
- Wholesalers:Regional distributors aggregate volumes for industrial clusters lacking direct refinery access, particularly in secondary Indian and Chinese manufacturing zones.
- Retailers:Small-scale commercial heating suppliers in European markets face REACH compliance burdens without in-house blending capabilities.
- Online Platforms:Digital procurement tools penetrate maritime bunkering first, with platforms offering real-time Singapore-Rotterdam price transparency to vessel operators.
Direct sales lock in utility and maritime volume; wholesaler networks retain relevance for fragmented industrial demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Refinery capacity clusters along the US Gulf Coast, Indian Ocean rim, and East Asian manufacturing corridors concentrate residual fuel supply. Demand fragmentation follows maritime bunkering routes and industrial heating load centers. Regulatory sulfur caps in each jurisdiction reshape product specifications and trade flows.
United States
US Gulf Coast refiners process heavy sour crude into residual fuel blends for domestic industrial boilers and export bunkering. EPA stationary source standards under the Clean Air Act tighten particulate limits for commercial heating applications. Houston and New Orleans anchor spot trading liquidity, with inventory positioning strategies visible in New York Harbor storage terminals.
India
Indian Oil Corporation's Paradip and Vadinar complexes expand vacuum distillation capacity to capture residual fuel export demand. The Central Pollution Control Board imposes regional limits on industrial boiler emissions, shaping refinery upgrading investments. Gujarat's manufacturing zones and Mumbai's port infrastructure concentrate domestic consumption and bunkering supply.
China
Coastal refiners upgrade residual fuel processing units to serve IMO 2020-compliant marine demand from Shanghai and Ningbo-Zhoushan bunkering hubs. The Ministry of Ecology and Environment enforces sulfur caps on industrial emissions, forcing reformulation of heating fuel grades. Yangtze River Delta chemical parks and Pearl River Delta manufacturing corridors anchor process heat consumption.
Singapore
The city-state's bunkering infrastructure handles the largest residual fuel throughput in Asia-Pacific, blending compliant marine grades for container and bulk carrier fleets. Maritime Port Authority regulations align with MARPOL Annex VI enforcement, preserving high-sulfur demand from scrubber-equipped vessels. Jurong Island refineries and terminal networks concentrate supply logistics for regional arbitrage.
Netherlands
Rotterdam's bunkering hub competes with Singapore on spot pricing transparency for marine fuel procurement. ECHA REACH authorization requirements for polycyclic aromatic hydrocarbons tighten residual fuel formulations for European industrial markets. The port's storage and blending facilities serve German and Dutch commercial heating demand while arbitraging between Brent-linked and Dubai-linked crude slates.
No.4 Fuel Oil Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with narrower scope. The residual fuel market structures around integrated refining majors, national oil companies, and independent trading houses. Three archetypes dominate: vertically integrated majors with captive terminal networks, state-owned refiners securing domestic supply security, and commodity traders arbitraging between regional pricing hubs. Competitive moves concentrate on refinery residue upgrading investments and bunkering hub capacity expansions.
Among integrated majors, ExxonMobil and Shell occupy positions defined by Gulf Coast and global terminal network control. Indian Oil Corporation Ltd exemplifies the state-owned archetype, anchoring domestic supply through refinery complex ownership. Vitol represents the trading house vector, capturing margin from spot arbitrage between Singapore and Rotterdam pricing hubs.
| Leading Market Players |
|---|
| Chevron |
| Indian Oil Corporation Ltd |
| ExxonMobil |
| Shell |
| Vitol |
| Lukoil |
| Bharat Petroleum Corporation Limited |
| Neste |
| Crown Oil Ltd |
| Others |
Value Network & Pricing Analysis
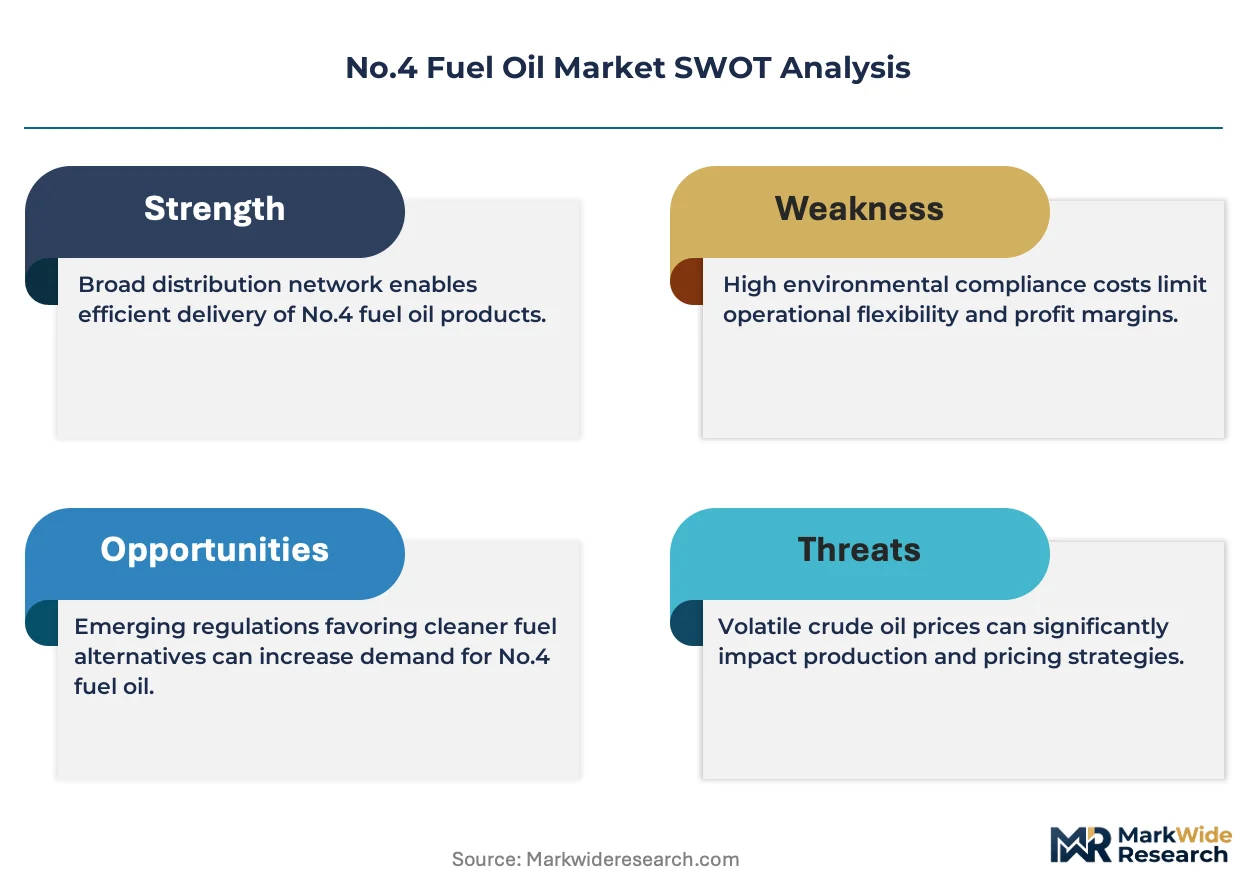
Singapore-Rotterdam freight differentials compress refinery margin capture while concentrating pricing power among integrated Gulf Coast and Indian Ocean rim operators capable of blending to IMO 2020 sulfur tiers. This corridor cost structure feeds directly into how marine fuel oil premiums detach from residual fuel oil baselines at bunkering hubs.
Pricing Analysis
MARPOL Annex VI dictates the pricing tier structure across the marine segment, separating 0.5% sulfur compliant grades from 3.5% high-sulfur residual for scrubber-equipped vessels. Price differentiation hinges on sulfur certification grade and volume scale, with bulk carrier fleets securing term discounts unavailable to spot-trading tramp operators. Cost compression in high-sulfur bunkers is intensifying because scrubber installation rates lag fleet renewal timelines. Small-scale industrial distributors in European heating markets exhibit the highest price sensitivity, while integrated maritime buyers with captive terminal access show the least.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculus for residual fuel feedstock flows. Geographic concentration centers on the US Gulf Coast, India, and Singapore, with vacuum residuum sourcing from Venezuelan, Mexican, and Middle Eastern heavy crude streams. The supply chain draws from cutter stock availability, catalytic cracking capacity, and marine logistics scheduling. Single-source vulnerability persists at the Panama Canal and Strait of Malacca chokepoints. Distribution runs through integrated refiner terminal networks, wholesaler aggregators, and digital bunkering platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized vacuum distillation and residue upgrading capabilities remain scarce outside the integrated major and national oil company archetypes, creating defensive moats for incumbent operators while constraining new entrant replication speed.
For Market Incumbents: Harden refinery residue processing capabilities through solvent deasphalting and delayed coking integration to capture margin from vacuum residuum upcycling. Secure term offtake agreements with scrubber-retrofitted bulk carrier operators at Fujairah and Gibraltar before LNG dual-fuel adoption curves accelerate. LNG bunkering infrastructure buildout in Shanghai and Rotterdam represents the primary substitution threat to residual fuel demand. For New Entrants and Emerging Players: Build out digital procurement platforms targeting fragmented maritime spot buyers seeking real-time Singapore-Rotterdam price transparency. Secondary Indian manufacturing zones and Chinese Yangtze River Delta chemical parks offer the most penetrable industrial demand pools, lacking direct refinery access. Partner with regional wholesalers to aggregate volumes for cement and steel producers where natural gas infrastructure remains underdeveloped. For Investors and Strategic Acquirers: EU Green Deal carbon border adjustment implementation reshapes the acquisition landscape toward low-carbon residual formulation capabilities and European industrial heating fuel distributors. Long-term viability centers on refinery operators with integrated carbon capture or hydrogen co-processing pathways. Monitor scrubber installation rates versus LNG dual-fuel engine order books as the critical inflection signal for residual fuel demand trajectory.| Strategic Initiative | Industry Significance |
|---|---|
| Refinery Residue Upgrading Investment | Solvent deasphalting and delayed coking integration captures higher-value product extraction from vacuum residuum streams. |
| Scrubber-Equipped Vessel Refueling Hub Development | Panama Canal and Fujairah port operators secure high-sulfur residual fuel demand from retrofitted bulk carriers. |
| Digital Bunkering Platform Launch | Real-time Singapore-Rotterdam price transparency reduces procurement friction for fragmented maritime spot buyers. |
| Low-Carbon Residual Formulation Program | EU Green Deal compliance creates blending opportunities for carbon-adjusted fuel oil entering European industrial markets. |
| Long-Term Utility Supply Agreement | Quarterly index-linked contracts with US Northeast and Japanese grid operators secure power generation margin pools. |
Research Methodology
Initial hypotheses were tested against primary input from refinery operations managers, maritime procurement officers, and industrial fuel buyers and refined through secondary validation. Refinery configuration databases, customs trade flow records, and MARPOL compliance filings anchored supply-side assessment. Demand-side triangulation drew from utility fuel procurement contracts, bunkering port throughput statistics, and EPA stationary source emission reports. Bottom-up refinery capacity modeling and top-down maritime fuel consumption estimates were cross-referenced for convergence.
Demand-supply-balance framing structured the analytical approach across the projection horizon, with segmentation modeled by sulfur specification tier, end-use equipment type, procurement contract structure, and regional regulatory cluster. CAGRs were derived from iterative convergence of capacity expansion schedules and fleet renewal trajectories. Scrubber retrofit penetration curves and LNG bunkering infrastructure buildout timelines served as primary demand-shifting inputs.
Practitioners should monitor OPEC+ heavy sour crude production decisions and IMO marine fuel sulfur enforcement amendments for early signals of forecast revision. Forecasts reflect assumptions about scrubber economics, dual-fuel engine capital costs, and regional emission regulation stringency. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Refuse Derived Fuel Market
Fuels
Saudi Arabia Fuel Station Market
Fuels
Coal Briquette Box Market
Fuels
North America Oil and Gas Lubricants Market
Fuels
Solid Recovered Fuel Market
Fuels
Hydrogen Cylinder Market
Fuels
LPG Tanker Market
Fuels
Renewable Heating Fuels Market
Fuels
United Kingdom Bunker Fuel Market
Fuels
Bituminous Coal Market
Fuels
Palm Methyl Ester Market
Fuels
UAE Chemical Logistics Market
Fuels
Heavy Fuel Oil Market
Fuels
Fuel Oxygenate Market
Fuels
India Petrol Station Market
Fuels
Global Chemical Logistics Market