
 Global Artificial Joints Market | 2026-2036
Global Artificial Joints Market Size, Share, and Industry Trends Forecast 2026-2036
Global Artificial Joints Market Foresight
Subscription-based remote monitoring and predictive maintenance software is repositioning artificial joint value propositions from hardware-only sales to lifetime patient management contracts. Stryker Corporation leverages its Mako robotic surgery platform to anchor premium positioning in computer-assisted arthroplasty. Zimmer Biomet sustains manufacturing scale across titanium alloy and ceramic bearing portfolios. Johnson & Johnson navigates regulatory complexity through DePuy Synthes by controlling vertically integrated supply chains from raw material forging to sterile packaging.
Artificial joints are biomechanical prostheses engineered to replace diseased or damaged synovial joints, typically fabricated from cobalt-chromium alloys, ultra-high molecular weight polyethylene, or alumina ceramic composites with surface roughness tolerances below 0.05 micrometers to minimize wear debris generation. Knee implants and hip implants occupy the dominant revenue share due to procedural volume concentration among patients over sixty-five. Ceramic-on-polyethylene bearing surfaces represent the fastest-growing material configuration as orthopedic clinics prioritize reduced osteolysis risk. Ambulatory surgical centers are capturing disproportionate growth in joint replacement volume as reimbursement shifts favor same-day discharge protocols.
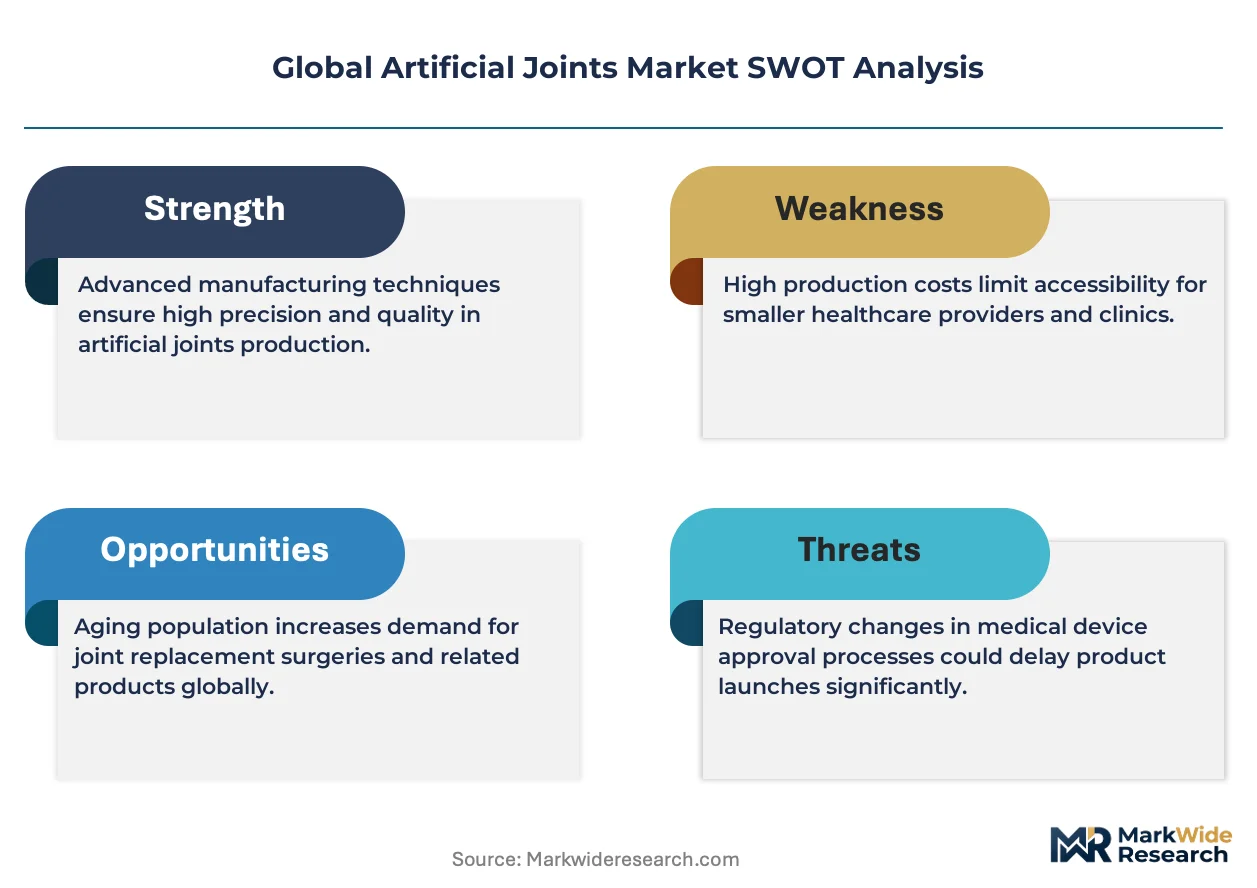
The FDA's 510(k) premarket notification framework governs device clearance in the United States, while the EU Medical Device Regulation imposes stricter clinical evidence requirements for hip and knee implant classes. Japan's PMDA mandates post-market surveillance studies that extend manufacturer accountability through decade-long follow-up obligations. Stakeholders must monitor evolving reimbursement thresholds for outpatient arthroplasty and ceramic bearing longevity data before committing capital to capacity expansion or geographic market entry decisions.
Market Dynamics
Robotic-assisted surgical platforms are compressing the skill gap between high-volume arthroplasty centers and community hospitals, redistributing procedural capacity across tiered healthcare networks while elevating precision benchmarks for implant positioning.
Growth Catalysts
- Japan's PMDA post-market surveillance mandate:Manufacturers now embed decade-long tracking infrastructure into implant distribution, creating recurring revenue streams from follow-up services and data analytics subscriptions.
- Ceramic-on-polyethylene bearing surfaces:Orthopedic clinics in Germany and the United States are prioritizing this material configuration to reduce osteolysis risk and revision surgery rates among patients over sixty-five.
- Ambulatory surgical center expansion:Medicare reimbursement shifts favoring same-day discharge protocols are capturing disproportionate joint replacement volume outside traditional hospital settings.
Market Restraints
- Cobalt-chromium alloy supply concentration:Raw material forging capacity clusters in a limited set of specialized metallurgical suppliers, exposing manufacturers to input price volatility and allocation risk.
- EU Medical Device Regulation clinical evidence requirements:Stricter documentation burdens for hip and knee implant classes are extending time-to-market and elevating regulatory compliance costs for mid-tier manufacturers.
- Revision surgery burden:Polyethylene wear debris and implant loosening necessitate costly secondary procedures that strain payer budgets and limit addressable market expansion.
Strategic Opportunities
- Remote monitoring software integration:Subscription-based predictive maintenance platforms are repositioning artificial joint value propositions from hardware-only sales toward lifetime patient management contracts.
- India's underserved arthroplasty market:Underpenetrated elective joint replacement access among aging urban populations creates whitespace for cost-optimized implant portfolios and localized manufacturing partnerships.
- 3D-printed patient-specific implants:Additive manufacturing convergence with preoperative planning software enables anatomically matched components that reduce operative time and improve fit accuracy.
Industry Challenges
- Orthopedic surgeon training bottlenecks:Robotic platform proficiency requires substantial proctored case volumes, constraining deployment speed and limiting addressable provider networks.
- Sterile packaging validation timelines:Extended qualification protocols for barrier systems and terminal sterilization processes compress product launch windows and elevate working capital requirements.
- Legacy electronic health record integration:Implant tracking databases must interface with fragmented hospital information systems, complicating post-market surveillance data capture and regulatory reporting automation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Artificial Joints Market |
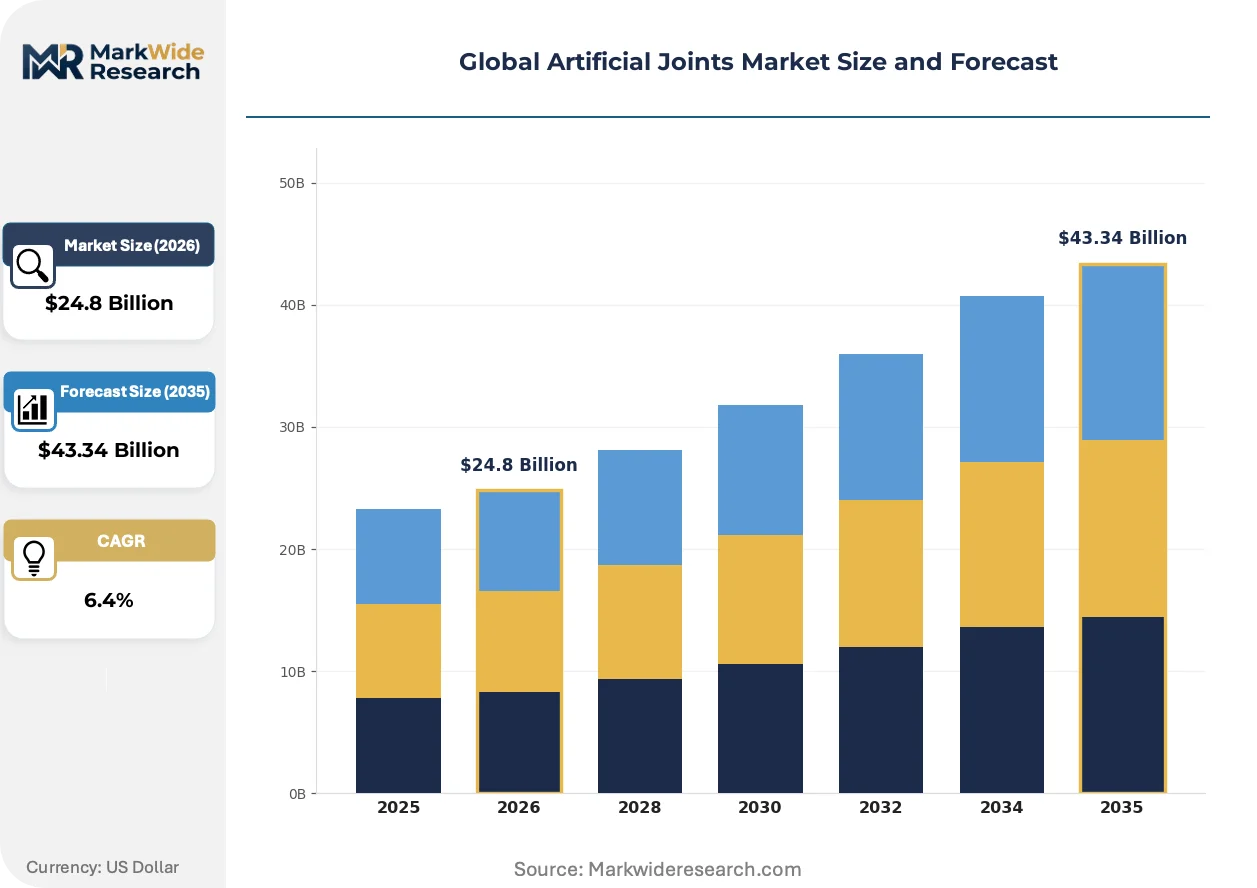
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $43.34 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Knee Implants, Hip Implants, Shoulder Implants, Elbow Implants, Ankle Implants Material Type: Titanium Alloys, Cobalt-Chromium, Polyethylene, Ceramic, Stainless Steel Application: Osteoarthritis, Rheumatoid Arthritis, Fracture Repair, Joint Degeneration, Avascular Necrosis End User: Orthopedic Clinics, Rehabilitation Centers, Specialty Hospitals, Ambulatory Surgical Centers |
| Companies Covered | Zimmer Biomet, Stryker Corporation, DePuy Synthes, Smith & Nephew, Exactech, Medtronic, Johnson & Johnson, United Orthopedic Corporation, MicroPort Scientific Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Artificial Joints Market Shifts & Advancements
Digital thread technologies are threading through implant lifecycles from design to explant, creating closed-loop feedback systems that compress innovation cycles and elevate performance accountability across manufacturer-payer-patient relationships.
Additive manufacturing of porous titanium lattice structures is decentralizing production geography for acetabular cups and tibial trays. Regional hospital networks in the United States and Germany are installing point-of-care printing capabilities that compress supply lead times from weeks to days. This distributed fabrication model is enabling same-day implant customization while reducing finished goods inventory carrying costs for healthcare systems.
The EU Medical Device Regulation's Unique Device Identification mandate is forcing systemic traceability investments across orthopedic supply chains. Manufacturers must now maintain device history records accessible across fifteen-year lifecycles, elevating data architecture requirements and favoring enterprises with captive cloud infrastructure. Knee implant product lines face the steepest compliance burden due to higher procedural volumes and component complexity.
Patients are demanding accelerated recovery protocols that compress postoperative rehabilitation timelines. Ambulatory surgical centers in the United States are responding with multimodal anesthesia regimens and preoperative optimization clinics that enable same-day discharge for select hip replacement candidates. This behavioral shift is reallocating physical therapy spend toward prehabilitation services and home-based monitoring technologies rather than institutional rehabilitation facilities.
Global Artificial Joints Market Segmentation
Artificial joint segmentation reveals how procedural specialization, bearing surface innovation, and site-of-care economics reshape procurement patterns across orthopedic supply chains. Manufacturers calibrate portfolio depth against revision surgery risk profiles and ambulatory migration trends.
Product Type:
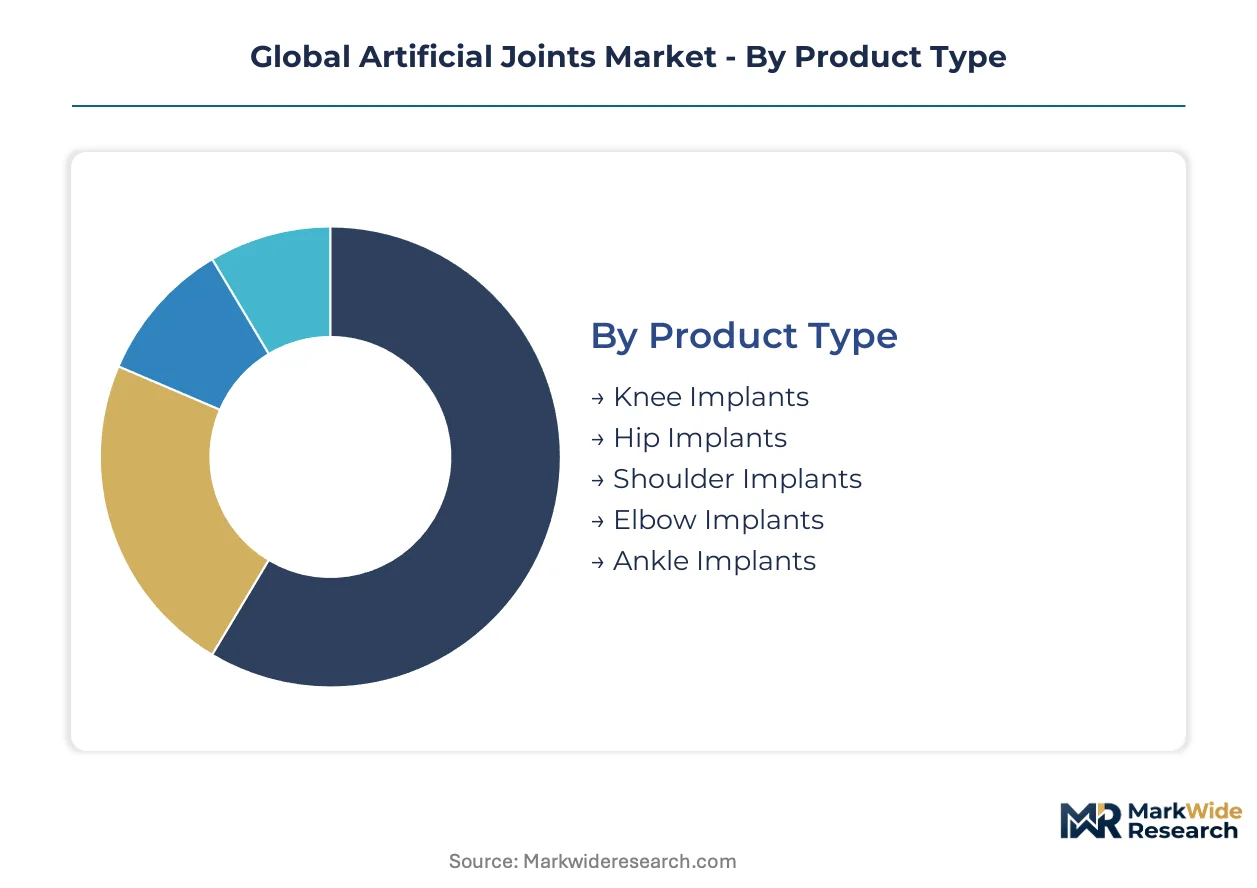
Replacement cycle frequency varies dramatically by anatomical site, with weight-bearing joints demanding earlier intervention and more durable bearing configurations.
- Knee Implants:These tibial and femoral component systems incorporate ultra-high molecular weight polyethylene inserts with cobalt-chromium or oxidized zirconium femoral runners. German and United States orthopedic clinics prioritize cruciate-retaining designs for patients under seventy to preserve native ligament function and accelerate ambulation.
- Hip Implants:Acetabular cups and femoral stems fabricated from titanium alloy or cobalt-chromium substrates accommodate ceramic or polyethylene bearing couples. Japan's aging demographic concentrates demand for dual-mobility constructs that reduce dislocation risk in elderly patients with compromised soft tissue integrity.
- Shoulder Implants:Reverse total shoulder arthroplasty systems address rotator cuff-deficient pathology through medialized center-of-rotation mechanics.
- Elbow Implants:Linked and unlinked designs serve post-traumatic arthritis and rheumatoid destruction with constrained motion envelopes.
- Ankle Implants:Three-component mobile-bearing systems address end-stage tibiotalar degeneration with bone-preserving talar dome resurfacing.
Volume placements concentrate in Knee Implants; the faster expansion belongs to Shoulder Implants.
Material Type:
Cost tier stratification separates premium ceramic-bearing portfolios from standard metal-polyethylene configurations and economy stainless steel options.
- Titanium Alloys:Ti-6Al-4V ELI substrates enable osseointegration through surface-modified porous coatings with 300-500 micrometer pore architectures. United States ambulatory surgical centers specify titanium femoral stems for younger patients anticipating longer implant survival horizons.
- Ceramic:Alumina and zirconia-toughened alumina bearing surfaces generate sub-micron wear debris volumes that minimize periprosthetic osteolysis. German reimbursement authorities now favor ceramic-on-polyethylene constructs for Medicare-equivalent populations to reduce revision surgery incidence.
- Cobalt-Chromium:Cast and wrought alloys dominate femoral head production with superior hardness and scratch resistance.
- Polyethylene:Highly cross-linked UHMWPE liners with vitamin E stabilization dominate bearing surface volume.
- Stainless Steel:Austenitic 316L variants persist in provisional trauma implants and cost-constrained markets.
Procurement volume tilts toward Polyethylene; Ceramic commands the steepest expansion trajectory.
Application:
Clinical indication severity determines implant complexity tier and bearing surface selection protocols.
- Osteoarthritis:Degenerative cartilage loss drives primary arthroplasty volume through progressive joint space narrowing and subchondral sclerosis. United States Medicare claims data shows osteoarthritis procedures dominate hip and knee replacement volume among patients over sixty-five.
- Avascular Necrosis:Femoral head collapse from vascular compromise demands urgent intervention with ceramic-bearing constructs to preserve acetabular bone stock. Japanese orthopedic centers report rising avascular necrosis incidence linked to corticosteroid utilization patterns.
- Rheumatoid Arthritis:Systemic inflammatory destruction requires cemented fixation in osteoporotic bone.
- Fracture Repair:Acute trauma necessitates hemiarthroplasty or total joint conversion for displaced femoral neck fractures.
- Joint Degeneration:Post-traumatic and metabolic arthropathies drive revision surgery volume.
Procedure volume clusters in Osteoarthritis; Avascular Necrosis generates the fastest-growing surgical indication profile.
End User:
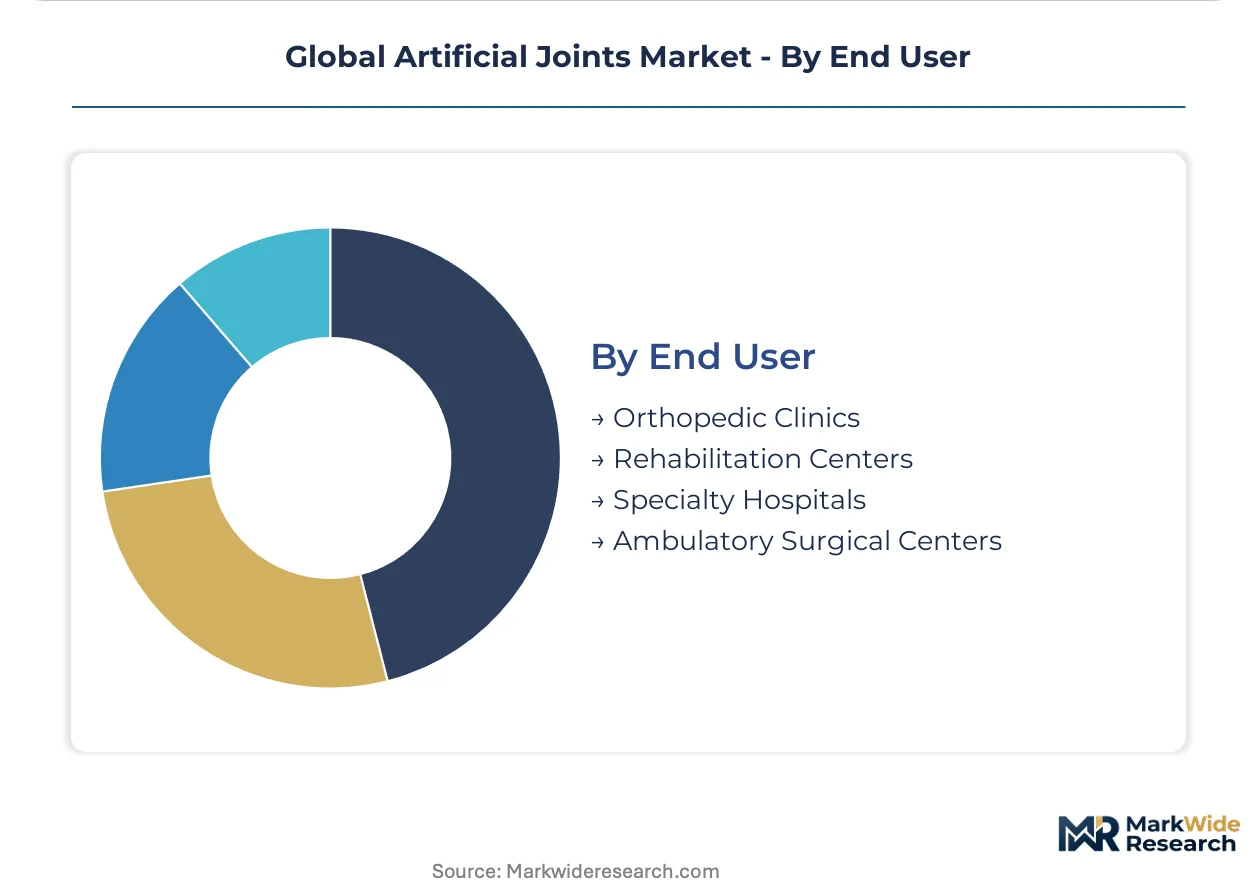
Customer type fragmentation separates high-acuity hospital-based practice from decentralized ambulatory delivery models.
- Ambulatory Surgical Centers:Same-day discharge protocols demand streamlined instrumentation sets and rapid-recovery anesthesia pathways. United States CMS reimbursement shifts have concentrated elective joint replacement volume in freestanding ASCs with lower infection rates and faster throughput metrics.
- Specialty Hospitals:Dedicated orthopedic facilities in Germany and Japan maintain robotics programs and complex revision capabilities. These centers capture high-margin bilateral procedures and infected implant exchanges requiring extended operative time.
- Orthopedic Clinics:Office-based practices drive preoperative optimization and postoperative surveillance.
- Rehabilitation Centers:Post-acute facilities manage functional recovery protocols.
Patient volume concentrates in Specialty Hospitals; Ambulatory Surgical Centers gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Warsaw's emerging medical technology corridor anchors Central Europe's orthopedic manufacturing expansion, with specialized metallurgical foundries supplying cobalt-chromium alloy forgings to implant fabricators across the continent.
United States
Medicare reimbursement shifts favoring outpatient joint replacement procedures concentrate demand in ambulatory surgical centers across Florida and Texas. The FDA's 510(k) clearance pathway accelerates commercialization timelines for ceramic-bearing portfolios. Greater Minneapolis hosts the densest cluster of orthopedic device headquarters, where manufacturers coordinate vertically integrated supply chains from raw material sourcing to sterile packaging operations.
Germany
Aging demographics in Bavaria and North Rhine-Westphalia expand the patient pool for elective knee and hip arthroplasty beyond historical volumes. The EU Medical Device Regulation imposes stricter clinical evidence requirements for implant classes, elevating compliance costs for mid-tier manufacturers. The Stuttgart industrial corridor maintains specialized titanium alloy forging capacity serving premium implant producers with surface-modified porous coating specifications.
Japan
Post-market surveillance mandates from PMDA extend manufacturer accountability through decade-long follow-up obligations, embedding tracking infrastructure into implant distribution networks. Japan's aging population concentrates demand for dual-mobility hip constructs reducing dislocation risk in elderly patients. The Kansai region around Osaka maintains specialized ceramic bearing production facilities supplying domestic orthopedic clinics with alumina and zirconia-toughened alumina components.
India
Underpenetrated elective joint replacement access among aging urban populations in Maharashtra and Karnataka creates whitespace for cost-optimized implant portfolios. CDSCO regulatory pathways for orthopedic devices remain less burdensome than EU or US equivalents, attracting manufacturing partnerships from multinational firms. The Delhi-NCR corridor hosts emerging domestic producers targeting tier-2 city hospital networks with stainless steel and standard polyethylene configurations.
China
Rising osteoarthritis prevalence among urban populations over sixty drives procedural volume expansion in Shanghai and Beijing hospital networks. NMPA regulatory harmonization efforts with international standards accelerate approval timelines for imported ceramic-bearing systems. The Yangtze River Delta maintains concentrated additive manufacturing capabilities for patient-specific implant production serving regional orthopedic centers with compressed lead times.
Global Artificial Joints Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the artificial joints sector, with integrated metallurgical operations commanding premium positioning against contract-manufacturing-dependent specialists. The vendor base fragments across three tiers: multinational conglomerates with captive forging capacity, mid-scale regional fabricators leveraging distributed manufacturing partnerships, and emerging point-of-care printing specialists. Strategic archetypes separate scale-driven portfolio breadth from ceramic-bearing material specialization and robotic surgery platform integration. Dominant competitive moves include backward integration into cobalt-chromium alloy supply and subscription-based remote monitoring software deployment.
Within the multinational tier, Zimmer Biomet, Stryker Corporation, and Johnson & Johnson exemplify divergent strategic positioning. Zimmer Biomet represents manufacturing scale concentration across titanium alloy and ceramic bearing portfolios. Stryker Corporation anchors computer-assisted arthroplasty positioning through robotic surgery platform integration. Johnson & Johnson occupies vertical supply chain control from raw material forging through sterile packaging operations. These three entities collectively illustrate the spectrum from hardware-centric sales models toward lifetime patient management contract structures.
| Leading Market Players |
|---|
| Zimmer Biomet |
| Stryker Corporation |
| DePuy Synthes |
| Smith & Nephew |
| Exactech |
| Medtronic |
| Johnson & Johnson |
| United Orthopedic Corporation |
| MicroPort Scientific Corporation |
| Others |
Supply & Pricing Matrix
EU MDR's Unique Device Identification mandate gates qualified supply access and premium-tier pricing power by forcing manufacturers to maintain fifteen-year device history records, elevating data infrastructure costs that only scale players absorb without margin compression.
Pricing Analysis
Outcome-linked reimbursement contracts anchor value-based pricing for ceramic-bearing portfolios in German and United States orthopedic clinics. Three-tier pricing structure across premium, standard, and economy levels separates ceramic-on-polyethylene constructs from metal-polyethylene configurations and stainless steel alternatives. Cost compression in economy tiers intensifies because CDSCO-registered Indian manufacturers flood tier-2 city hospital networks with undifferentiated implants. Ambulatory surgical centers exhibit highest price sensitivity due to CMS reimbursement caps, while specialty hospitals in Japan tolerate premium positioning for dual-mobility hip systems.
Supply Chain Analysis
Dual-sourcing requirements from United States orthopedic OEMs mandate qualified suppliers in Germany, Japan, and the United States for cobalt-chromium alloy forgings. Raw material dependencies center on titanium sponge from Japan, alumina ceramic powders from Germany, and vitamin E-stabilized UHMWPE resin from the United States. Single-source vulnerability concentrates in specialized metallurgical foundries around Stuttgart and Warsaw. Distribution runs through GPO contracts with hospital systems and direct-to-ASC consignment models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around manufacturers with captive forging capacity and FDA 510(k) clearance velocity, as EU MDR compliance costs force mid-tier players toward exit or acquisition.
For Market Incumbents: Cement market position by backward integration into cobalt-chromium alloy supply and deploying subscription-based remote monitoring software to capture lifetime patient management contracts. Stryker's Mako platform demonstrates how robotic surgery anchoring defends against point-of-care 3D printing entrants. Prioritize ceramic-bearing certification investments to maintain German reimbursement preference. For New Entrants and Emerging Players: Additive manufacturing convergence with preoperative planning software offers a technology-first wedge into patient-specific implant niches underserved by multinational scale players. India's Maharashtra and Karnataka urban corridors present the most penetrable geography for cost-optimized portfolios. Pursue CDSCO registration pathways and localized manufacturing partnerships rather than direct FDA or EU MDR confrontation. For Investors and Strategic Acquirers: FDA 510(k) clearance velocity for ceramic-bearing systems is the leading indicator that mid-tier manufacturers possess viable acquisition infrastructure worth premium multiples. Long-term viability favors targets with vertically integrated supply chains from raw material forging to sterile packaging. Monitor PMDA post-market surveillance compliance as the signal for Japanese market access durability.| Strategic Initiative | Industry Significance |
|---|---|
| Robotic Surgery Platform Integration | Stryker's Mako system demonstrates how computer-assisted arthroplasty commands premium hospital contracts. |
| Ceramic-Bearing Portfolio Expansion | German reimbursement authorities now favor alumina constructs for Medicare-equivalent populations. |
| Point-of-Care 3D Printing Deployment | Regional hospital networks in the United States and Germany compress supply lead times from weeks to days. |
| Remote Monitoring Software Launch | Subscription-based predictive maintenance platforms reposition value propositions toward lifetime contracts. |
| CDSCO Manufacturing Partnership | Delhi-NCR corridor producers target tier-2 Indian cities with stainless steel configurations. |
Research Methodology
Multi-period observation of FDA 510(k) clearance timelines, PMDA post-market surveillance compliance rates, and CMS reimbursement policy shifts anchored the trend analysis, supplemented by interviews with orthopedic surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. Secondary validation drew from FDA MAUDE database entries, EUDAMED device registration records, hospital procurement databases, and CMS Medicare claims data. Bottom-up implant volume modeling triangulated against top-down market size estimates.
Segment-weighting across product type, material configuration, application indication, and end-user site-of-care dimensions structured the analytical framework across the analysis window. CAGRs derived from procedure volume trajectories, demographic aging curves, and reimbursement policy elasticity assumptions. Ceramic-bearing longevity data and ambulatory surgical center migration rates served as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including unforeseen regulatory harmonization between NMPA and FDA standards, abrupt cobalt-chromium alloy supply disruptions, and revolutionary biomaterial substitutions displacing current bearing surfaces. Deviation in EU MDR enforcement intensity or Medicare outpatient reimbursement thresholds would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Cartilage Repair Market
Orthopedic Devices
Europe Orthopedic Devices Market
Orthopedic Devices
India Orthopedic Braces and Supports Market
Orthopedic Devices
Orthopedic Splints and Casts Market
Orthopedic Devices
US Orthopedic Devices Market
Orthopedic Devices
Global Orthopedic Splints Market
Orthopedic Devices
Hip Reconstruction Devices Market
Orthopedic Devices
3D Medical Implant Market
Orthopedic Devices
Medical Traction Devices Market
Orthopedic Devices
Shoulder Arthroplasty Market
Orthopedic Devices
Vertebroplasty and Kyphoplasty Needles Market
Orthopedic Devices
Asia-Pacific Kyphoplasty Market
Orthopedic Devices
Global Joint Replacement Market
Orthopedic Devices
Orthobiologics Market
Orthopedic Devices
Orthopedic Contract Manufacturing Market
Orthopedic Devices
France Neurology Devices Market