
 Motorcycle Aluminum Casting Market | 2026-2036
Motorcycle Aluminum Casting Market Size, Share, and Industry Trends Forecast 2026-2036
Motorcycle Aluminum Casting Market Insights
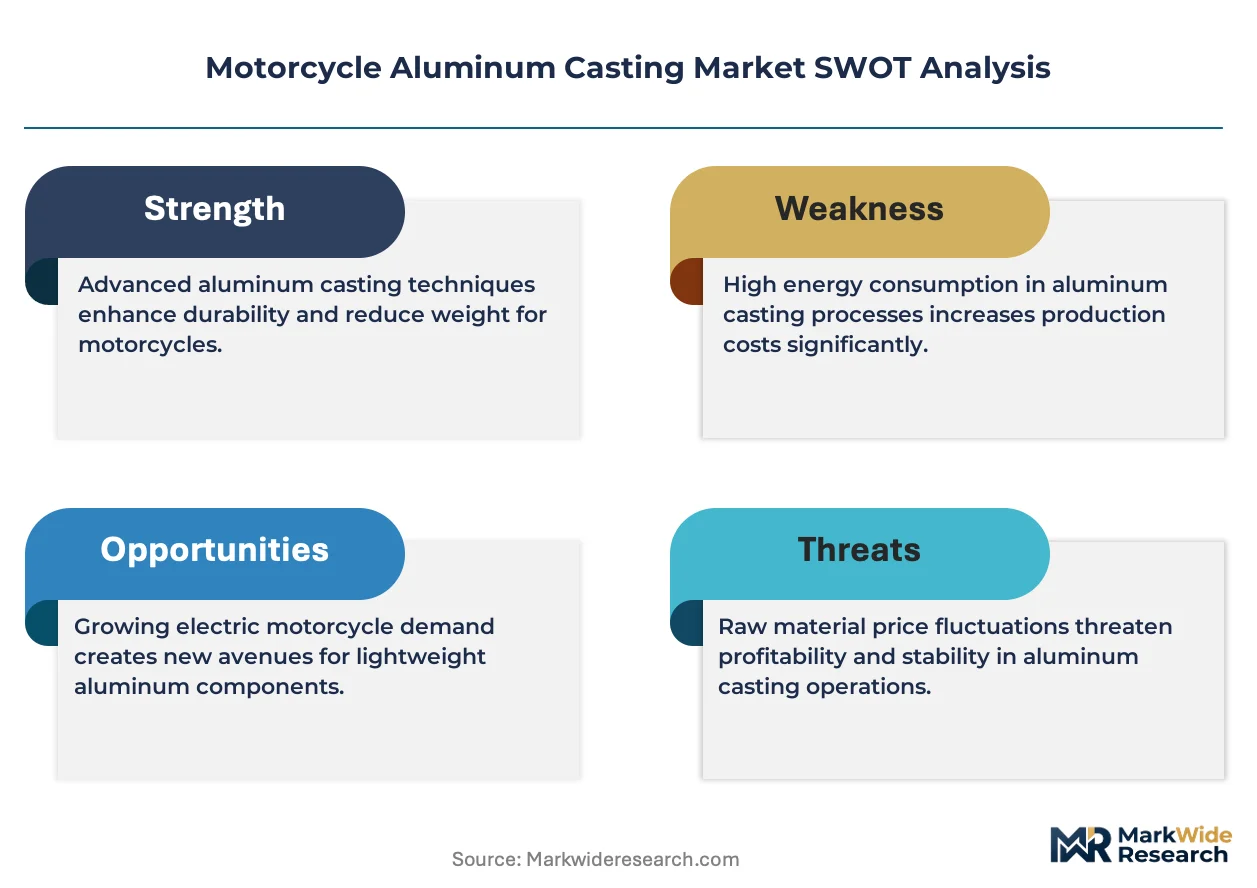
Electric motorcycle manufacturing is pivoting toward aluminum-intensive chassis and powertrain housings as OEMs chase weight reduction targets. Nemak leverages its high-pressure die-casting footprint to supply structural battery trays and motor housings for emerging EV two-wheeler platforms. Ryobi sustains dominance in precision cylinder head casting through advanced thermal management designs that serve both ICE and hybrid motorcycle architectures.
Motorcycle aluminum casting encompasses gravity die, low-pressure die, and high-pressure die-casting processes that shape aluminum-silicon alloys into structural and powertrain components with wall thicknesses typically ranging from 2.5 mm to 12 mm. These castings deliver strength-to-weight ratios critical for fuel efficiency, handling dynamics, and thermal dissipation in motorcycle engines and frames. Cylinder heads and engine crankcases occupy mature volume positions with established tooling amortization cycles, while wheel rims and frame components capture expanding margin pools as styling customization and electric-platform structural integration intensify. Electric motorcycles represent the fastest-growing application segment as casting houses retool for larger-format housings that accommodate battery enclosures and hub motors.
The US EPA and California Air Resources Board enforce evaporative emissions standards that dictate alloy permeability specifications for fuel-system castings, while EU REACH restrictions on heavy-metal additives reshape foundry chemistry across European supply chains. India's BIS certification mandates material traceability for OEM-sourced cast components, tightening market access for unqualified suppliers. Stakeholders must monitor how China's dual carbon goals and evolving GB standards for recycled aluminum content recast sourcing strategies for export-oriented foundries.
Market Dynamics
Electric motorcycle OEM procurement of structural battery housings and motor casings is compressing traditional ICE component demand while forcing foundries to retool for larger-format, thinner-wall castings with tighter dimensional tolerances.
Growth Catalysts
- EU REACH compliance mandates:Heavy-metal restrictions in aluminum alloys are accelerating foundry investment in clean chemistry processes that serve premium export markets.
- India BIS certification expansion:Material traceability requirements for OEM-sourced cast components are formalizing supply relationships and squeezing informal competitors from the value chain.
- High-pressure die-casting scale-up:Structural battery tray demand from electric two-wheeler platforms is pulling capacity expansion across South and Southeast Asian manufacturing clusters.
Market Restraints
- Primary aluminum price volatility:Energy-intensive smelting costs in China and Russia create input cost instability that squeezes margin pools for independent foundries.
- Gravity die-casting equipment obsolescence:Legacy tooling cycles for cylinder heads and crankcases face stranded asset risk as OEMs pivot to low-pressure and high-pressure processes.
- Silicon carbide composite substitution:Advanced ceramics in high-heat powertrain applications threaten traditional aluminum-silicon alloy penetration in performance motorcycle segments.
Strategic Opportunities
- Vietnam manufacturing cluster emergence:Motorcycle assembly migration into northern industrial zones creates captive demand for localized aluminum casting capacity.
- China dual carbon goals:Recycled aluminum content mandates under evolving GB standards create first-mover advantage for foundries with verified scrap-to-ingot traceability systems.
- Hub motor housing integration:Convergence of casting and motor assembly expertise opens white space for tier suppliers capable of delivering finished powertrain modules rather than raw castings.
Industry Challenges
- Thin-wall casting process engineering:Battery enclosure specifications below 3 mm wall thickness demand rare combinations of thermal management simulation and rapid solidification control that outstrip current workforce capabilities.
- Multi-certification timeline compression:Simultaneous pursuit of EPA evaporative emissions compliance, EU REACH material declarations, and India BIS lot traceability stretches quality assurance bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Motorcycle Aluminum Casting Market |
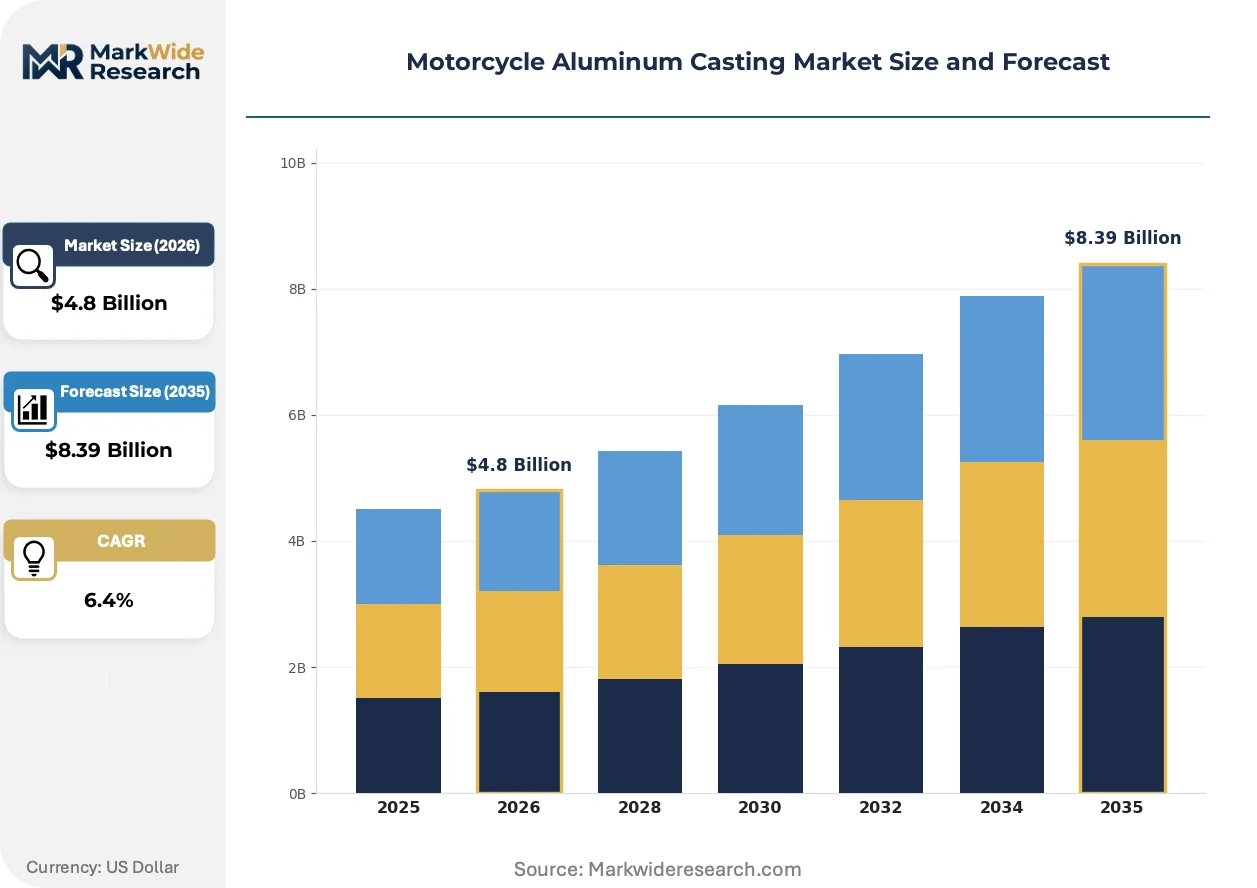
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cylinder Heads, Engine Crankcases, Wheel Rims, Frame Components Application: Motorbikes, Scooters, Dirt Bikes, Electric Motorcycles End User: OEMs, Aftermarket Suppliers, Custom Builders, Enthusiasts Distribution Channel: Direct Sales, Online Retail, Distributors, Exporters |
| Companies Covered | Nemak, Ryobi, Ahresty, Georg Fischer Ltd, Alcoa, Dynacast International, Gibbs Die Casting, Rockman Industries, Endurance, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Motorcycle Aluminum Casting Market Trends and Innovations
Aluminum casting for motorcycles is pivoting from standalone component supply toward integrated structural systems, with process technology and regulatory chemistry commanding equal attention to alloy formulation.
Thin-wall high-pressure die-casting is integrating thermal management channels directly into battery tray and motor housing geometries. Tier-one suppliers serving electric motorcycle OEMs in India and Vietnam are adopting this capability to eliminate secondary machining operations. The technology is integrating formerly separate cooling circuit fabrication into single-shot casting cycles that compress total cost structures.
EU REACH restrictions on cadmium and lead additives in aluminum alloys are forcing reformulation of traditional Al-Si-Cu compositions used in fuel-system castings. Foundries serving European export markets are qualifying alternative grain refiners and modifying melt practices to maintain mechanical properties. Cylinder head suppliers face the steepest requalification burden as permeability specifications intersect with new chemistry constraints.
Fleet operators and shared mobility platforms are consolidating procurement around certified casting suppliers with documented carbon footprints. Large-format buyers in Southeast Asia are unbundling component sourcing from assembly contracts and establishing direct foundry relationships. This pattern is most visible in Indonesia and Thailand where ride-hail motorcycle electrification programs demand volume-scale, traceable supply chains.
Motorcycle Aluminum Casting Market Segmentation
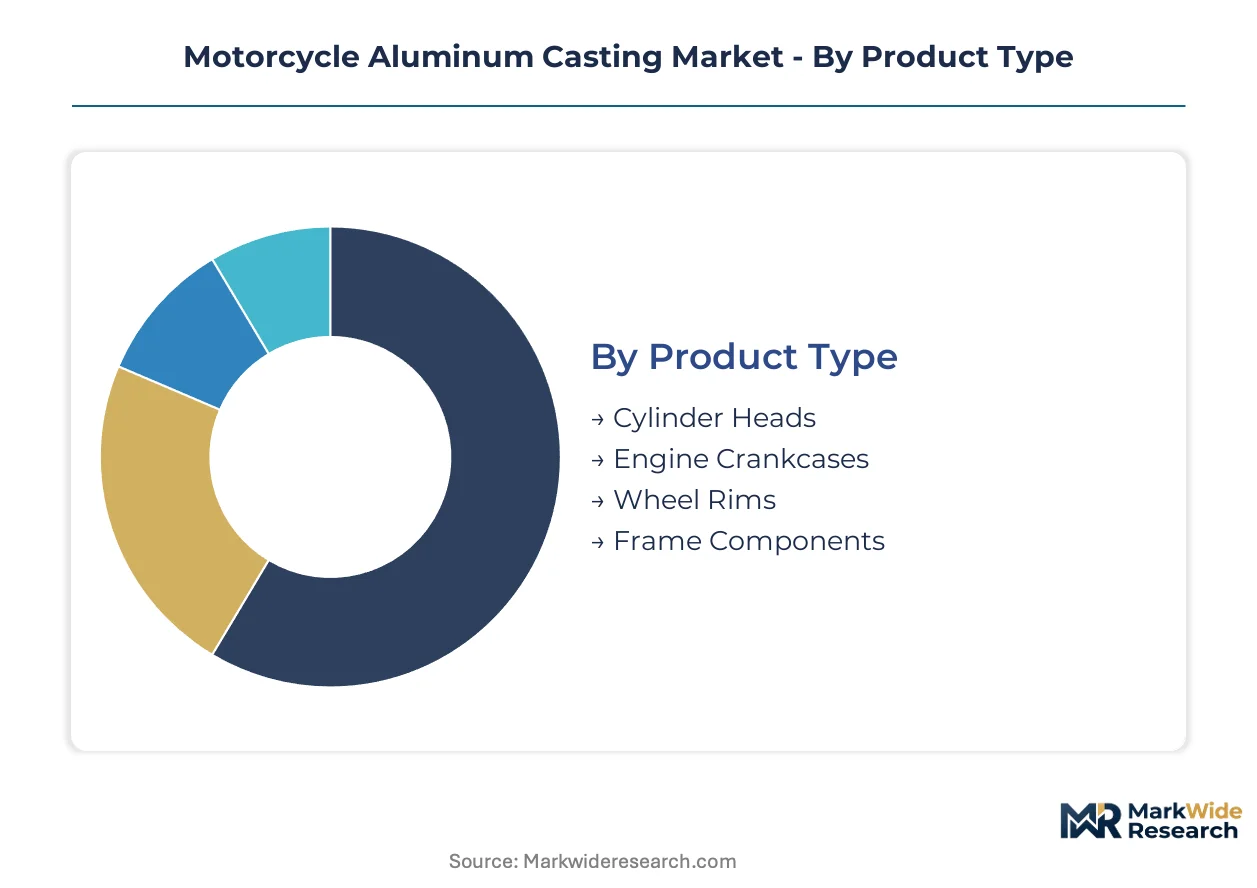
Motorcycle aluminum casting procurement splits across process technology, vehicle architecture, and supply chain configuration. Foundries align capability investments with specific segment margin profiles and certification requirements.
Product Type:
High-pressure die-casting and gravity die-casting technologies map to distinct wall thickness and structural load specifications.
- Cylinder Heads:Al-Si-Cu alloys with integrated cooling passages dominate thermal management in combustion architectures. Demand concentrates in India and Vietnam as ICE motorcycle assembly expands, though EPA evaporative emissions compliance tightens alloy permeability specifications for fuel-system interfaces.
- Engine Crankcases:High-pressure die-cast housings with 3-5 mm wall thickness deliver structural rigidity for powertrain mounting. OEM procurement in China and India drives volume, with BIS certification mandates formalizing supplier qualification timelines.
- Wheel Rims:Low-pressure die-cast Al-Si-Mg alloys balance fatigue resistance with styling flexibility.
- Frame Components:Thin-wall high-pressure die-casting below 3 mm enables battery tray integration for electric platforms.
Mature deployment sits with cylinder heads and crankcases. Newer deployment is concentrated in frame components.
Application:
Vehicle electrification intensity reshapes casting format requirements across two-wheeler categories.
- Motorbikes:Traditional ICE architectures sustain demand for cylinder heads and crankcases with established tooling amortization. Procurement concentrates in Indian and Vietnamese OEM supply chains facing simultaneous EPA, EU REACH, and BIS compliance burdens.
- Electric Motorcycles:Structural battery housings and hub motor casings demand larger-format, thinner-wall castings with integrated thermal channels. Foundry investment in South and Southeast Asian clusters accelerates to capture OEM platform launches.
- Scooters:Compact wheel rim and frame casting specifications serve urban mobility density.
- Dirt Bikes:High-stress suspension mounting points require gravity die-cast alloy formulations with enhanced fracture toughness.
Scooters and motorbikes anchor current volume. Electric motorcycles are gaining share fastest.
End User:
Procurement authority concentration determines contract scale and technical specification stringency.
- OEMs:Direct foundry relationships with documented carbon footprint traceability serve platform-scale battery tray and motor housing programs. EU REACH compliance and BIS certification requirements filter supplier bases toward qualified tier-one casting houses.
- Aftermarket Suppliers:Wheel rim and cylinder head replacement demand flows through distributor networks with shorter qualification cycles.
- Custom Builders:Low-volume frame and wheel casting procurement emphasizes styling differentiation over structural certification.
- Enthusiasts:Direct online purchasing of replacement components bypasses traditional distribution markups.
Volume concentration rests with OEMs. Margin expansion is concentrating in aftermarket suppliers.
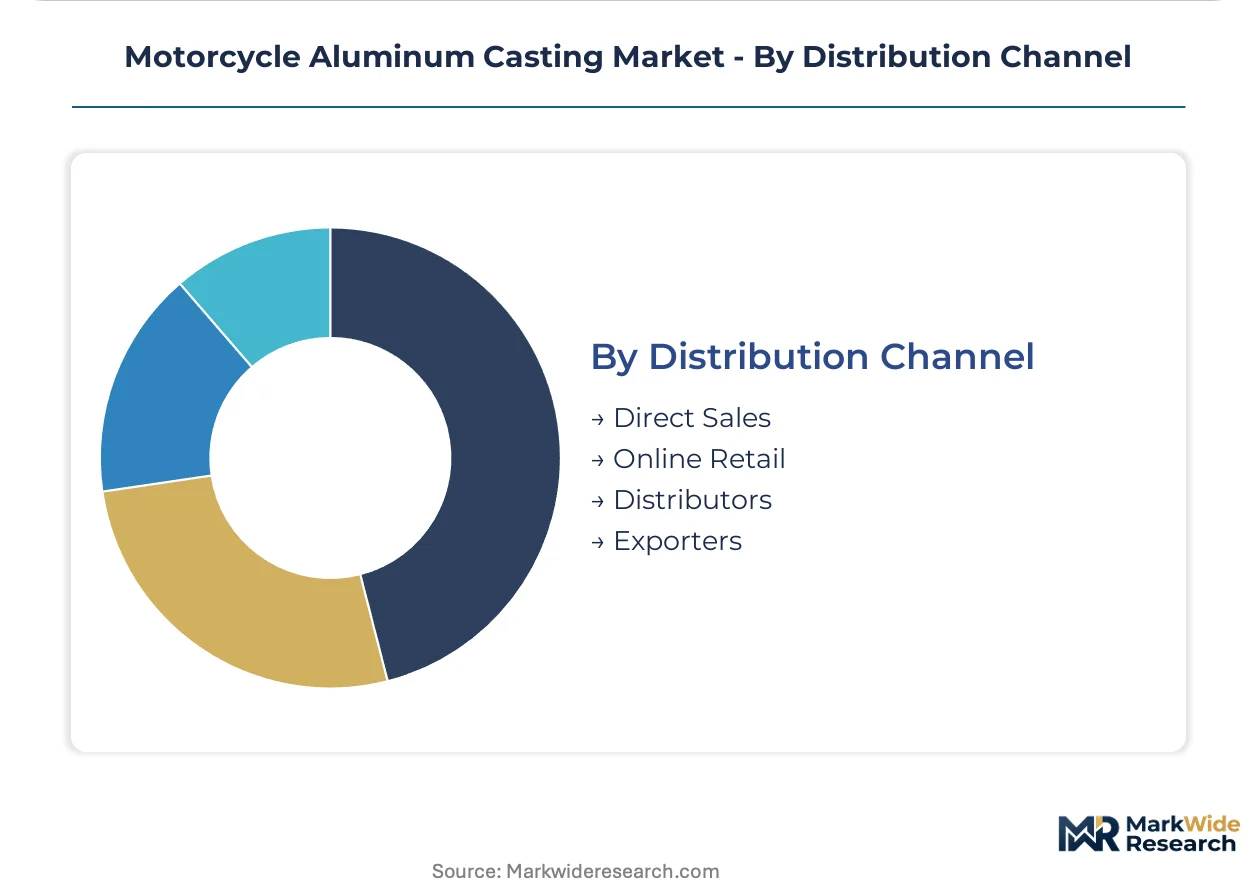
Distribution Channel:
Channel selection reflects order scale, certification documentation requirements, and geographic reach.
- Direct Sales:OEM and tier-one supplier contracts with embedded quality assurance protocols dominate structural component procurement. Foundries in India, China, and Vietnam cultivate direct relationships to secure platform-scale battery tray programs.
- Distributors:Aftermarket cylinder heads and wheel rims move through regional inventory networks serving independent repair channels.
- Online Retail:Custom builders and enthusiasts source replacement castings through digital marketplaces with compressed delivery timelines.
- Exporters:Foundries with EU REACH and EPA compliance documentation serve cross-border OEM supply chains.
Established volume flows through direct sales. Channel expansion is accelerating in online retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China dominates aluminum casting production capacity while India and Vietnam absorb the fastest OEM assembly migration. Consumption patterns diverge as electric motorcycle adoption accelerates in Europe and Southeast Asia strains legacy supply chains.
China
Domestic OEMs and export foundries drive structural battery tray demand for electric two-wheeler platforms. GB standards for recycled aluminum content tighten under dual carbon goals, forcing scrap-to-ingot traceability upgrades. The Yangtze River Delta concentrates high-pressure die-casting investment serving battery enclosure programs.
India
ICE motorcycle assembly expansion sustains cylinder head and crankcase procurement from foundries in Pune and Chennai. BIS certification mandates now require material lot traceability for all OEM-sourced cast components. The Tamil Nadu industrial corridor attracts capacity expansion for both domestic supply and re-export to Southeast Asian assembly plants.
Vietnam
Japanese and Korean OEM assembly migration into northern industrial zones creates captive demand for localized aluminum casting. Foundries near Hanoi and Hai Phong retool for larger-format battery housings as domestic electric motorcycle platforms launch. The Red River Delta emerges as a high-pressure die-casting cluster serving regional EV supply chains.
Germany
Premium motorcycle OEMs source precision cylinder heads and structural frame components from domestic foundries. EU REACH restrictions on cadmium and lead additives force reformulation of traditional Al-Si-Cu alloys for fuel-system castings. The Baden-Württemberg supplier belt maintains dominance in thermal management casting for performance motorcycle architectures.
United States
Custom builders and aftermarket distributors sustain demand for wheel rims and replacement cylinder heads. EPA evaporative emissions standards dictate alloy permeability specifications for fuel-system interfaces. The Midwest manufacturing belt retains gravity die-casting capacity for heritage motorcycle restoration and niche performance applications.
Motorcycle Aluminum Casting Market Competitive Landscape
Top-tier vendors anchor OEM platform-scale contracts, while mid-tier foundries serve aftermarket and regional assembly demand. The market structure stratifies across three tiers: multinational die-casting specialists with integrated thermal management capabilities, regional foundry groups with BIS or REACH certification, and independent operators concentrated in cylinder head replacement. Capacity expansion and certification acquisition represent the dominant competitive moves as electric motorcycle programs consolidate procurement authority.
Within the multinational specialist tier, Nemak and Ryobi exemplify scale-driven positions serving structural battery tray and precision powertrain casting demand. Ahresty occupies a position among Japanese-origin fabricators with established OEM relationships. These three companies represent the archetype of integrated thermal management capability that electric motorcycle platforms now require.
| Leading Market Players |
|---|
| Nemak |
| Ryobi |
| Ahresty |
| Georg Fischer Ltd |
| Alcoa |
| Dynacast International |
| Gibbs Die Casting |
| Rockman Industries |
| Endurance |
| Others |
Pricing and Supply Chain Analysis
Electric motorcycle OEM procurement of structural battery housings with sub-3 mm wall thickness specifications is forcing foundries to absorb retooling costs that compress margin pools across the supply base.
Pricing Analysis
Lead-time-driven pricing tiers separate OEM platform-scale contracts from spot aftermarket orders. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume commitment, with BIS-traceable, REACH-compliant castings commanding sustained premiums. Cost compression in standard-tier cylinder head supply is intensifying because gravity die-casting equipment obsolescence strands legacy capacity. Aftermarket distributors exhibit highest price sensitivity, while OEM direct procurement prioritizes technical qualification over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale battery tray demand from Indian and Vietnamese electric motorcycle platforms. Primary aluminum feedstock draws from Chinese smelters and Russian producers, with secondary scrap-to-ingot flows resting on Yangtze River Delta recycling infrastructure. Single-source vulnerability concentrates in high-purity silicon supply for Al-Si alloy formulations. Distribution runs through tier-one foundry-direct relationships for structural components, while aftermarket castings move via regional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where foundries capturing in-house thermal management simulation and rapid solidification control secure platform-scale OEM contracts.
For Market Incumbents:Cement platform-scale relationships by acquiring thin-wall high-pressure die-casting capacity in Tamil Nadu and Red River Delta clusters before emerging entrants qualify. Silicon carbide composite substitution in performance powertrain applications threatens traditional Al-Si-Cu penetration; counter by deepening backward integration into verified scrap-to-ingot traceability systems that satisfy China's dual carbon mandates.
For New Entrants and Emerging Players:Custom builders seeking styling-differentiated frame castings with compressed certification cycles represent an underserved buyer archetype with accessible entry economics. Hub motor housing integration—combining casting and motor assembly expertise—offers white space in Vietnam's northern industrial zones. Pursue direct online channels to bypass incumbent distributor markups and establish brand recognition before scaling into OEM qualification.
For Investors and Strategic Acquirers:The window for entry favors foundries with demonstrated EU REACH compliance and active BIS certification pipelines. Long-term viability hinges on exposure to electric motorcycle platform launches rather than ICE replacement cycles. Watch for OEM unbundling of component sourcing from assembly contracts in Indonesia and Thailand as the inflection signal for direct foundry relationship formation.
| Strategic Initiative | Industry Significance |
|---|---|
| High-Pressure Die-Casting Capacity Expansion | Captures structural battery tray demand from Indian and Vietnamese EV platforms. |
| Backward Integration into Scrap Traceability | Secures first-mover advantage under China's evolving GB recycled content standards. |
| EU REACH Compliance Certification | Unlocks premium export markets with cadmium-free Al-Si-Cu alloy formulations. |
| Hub Motor Housing Integration | Delivers finished powertrain modules rather than commodity raw castings. |
| Direct OEM Relationship Formation | Bypasses distributor markups as fleet operators consolidate procurement authority. |
Research Methodology
Document review covered SEC filings from listed foundry groups, EPA evaporative emissions guidance, EU REACH substance restriction updates, and India BIS certification protocols, complemented by interviews with foundry operations directors, OEM platform engineers, Tier 1 supplier procurement leads, and aftermarket distribution channel managers. Secondary validation drew from customs trade data, aluminum alloy pricing benchmarks, and vehicle production registration databases. Bottom-up capacity assessments and top-down demand modeling were triangulated against primary field intelligence.
Segment-level outputs across process technology, vehicle architecture, and supply chain configuration were generated over the projection horizon. Modeled dimensions encompassed casting process type, propulsion architecture, wall thickness specification tier, and regional regulatory cluster. CAGRs were derived from installation base growth, replacement cycle analysis, and content-per-vehicle trajectories for electric platforms. Forecast inputs incorporated primary aluminum price volatility scenarios and OEM platform launch timelines.
Revisions become necessary when EPA emissions benchmarks tighten alloy permeability specifications, EU REACH expands heavy-metal restrictions, or China's dual carbon goals accelerate recycled content mandates beyond current GB standards. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Canada Automotive Parts Die Casting Market
Automotive Parts
Car Phone Holder Market
Automotive Parts
France Automotive Pneumatic Actuators Market
Automotive Parts
Power Liftgate Market
Automotive Parts
Accelerator Pedal Module Market
Automotive Parts
Engine Piston Ring Set Market
Automotive Parts
Global Automotive Gasoline Particulate Filter (GPF) Market
Automotive Parts
Automotive Piston Engine System Market
Automotive Parts
Automotive Adaptive Engine Mounts Market
Automotive Parts
Oil Catch Cans Market
Automotive Parts
Mexico Automotive Parts Zinc Die Casting Market
Automotive Parts
Electric Power Steering System (EPS) Market
Automotive Parts
Automotive Crankshaft Materials Market
Automotive Parts
Global Passenger Vehicles Lubricants Market
Automotive Parts
Europe Ball Bearings Market
Automotive Parts
Wiper Systems Market