
 Philippines Automotive Lubricants Market | 2026-2036
Philippines Automotive Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Philippines Automotive Lubricants Market Analytics
A capital-intensity divergence between integrated refiners and blenders is unwinding competitive stability in the Philippines. Petron Corporation leverages its Bataan refinery to control base stock supply, while Royal Dutch Shell Plc sustains premium positioning through branded service station networks. Chevron Corporation competes via Caltex retail presence, and BP Plc (Castrol) differentiates through motorcycle-specific formulations.
Automotive lubricants are formulated mixtures of base oils and performance additives designed to reduce friction, dissipate heat, and prevent wear in internal combustion engines and drivetrains, with viscosity grades such as SAE 5W-30 and 10W-40 calibrated to operating temperature ranges. Engine oil dominates volume demand across the Philippines, while synthetic formulations capture expanding margin pools as OEM service intervals lengthen. Motorcycle end users represent the fastest-growing consumption segment, driven by two-wheeler density in urban and rural areas. Distribution through service stations retains channel control, though online platforms are gaining traction in aftermarket replenishment.
The Department of Energy enforces fuel quality standards that indirectly shape lubricant additive chemistry, while the Bureau of Product Standards mandates compliance with Philippine National Standards for petroleum products. The Department of Environment and Natural Resources implements hazardous waste regulations affecting used oil collection and re-refining economics. Stakeholders must monitor how emission compliance timelines for Euro 4 and Euro 5 vehicle standards will redirect formulation investments toward lower-viscosity and extended-drain products.
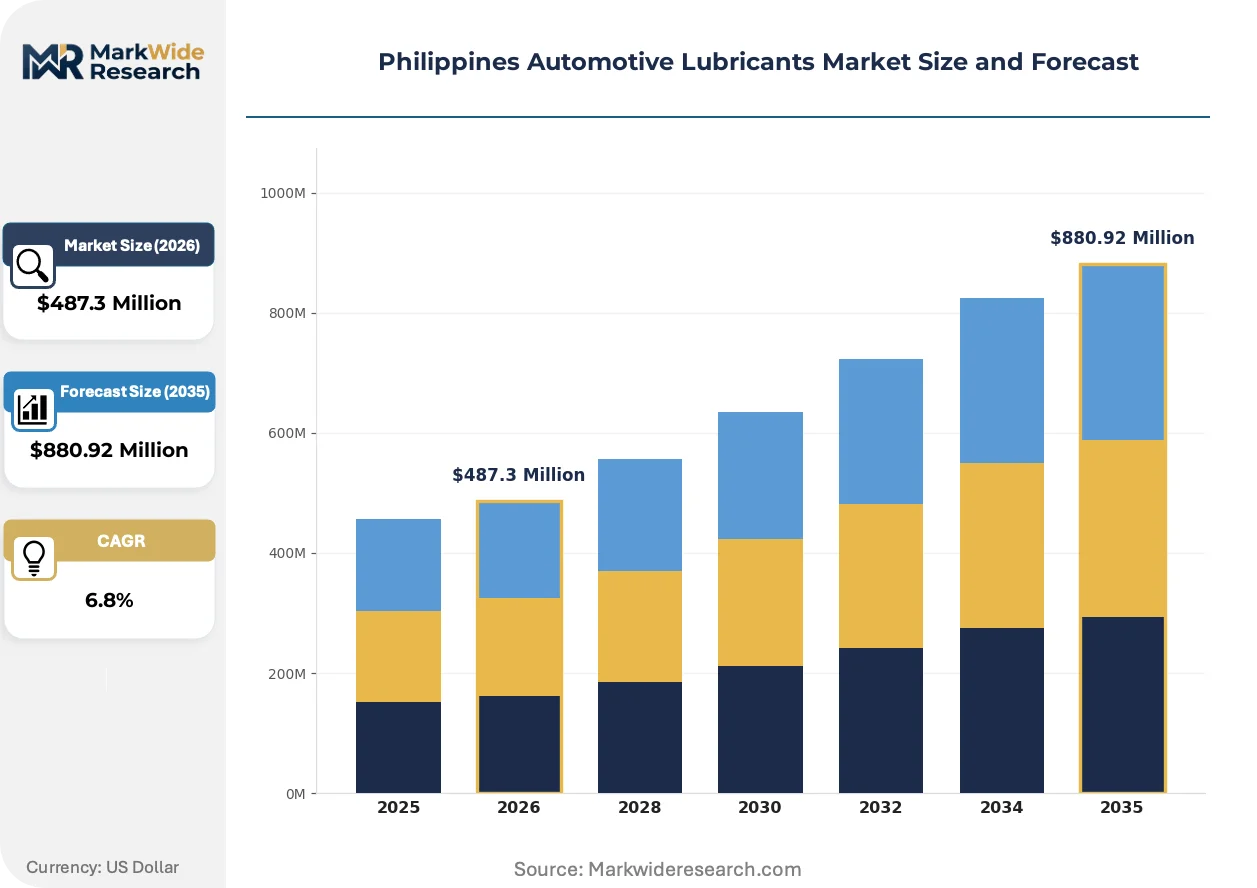
Market Dynamics
The Philippines automotive lubricants market is experiencing structural pressure from the Department of Energy's fuel economy mandates, which are compressing formulation cycles as blenders race to certify products against tightening API SP and ILSAC GF-6 specifications before older stocks become obsolete.
Growth Catalysts
- Motorcycle Fleet Density:Two-wheeler registrations across Luzon, Visayas, and Mindanao continue climbing, with rural last-mile delivery and urban gig-economy transport creating sustained drain-interval demand for 10W-40 and 20W-50 grades.
- Euro 5 Alignment:The Department of Environment and Natural Resources emission compliance timelines are forcing lubricant reformulation toward lower-viscosity 0W-20 and 5W-30 products that reduce cold-start friction and extend catalyst life.
- CALABARZON Manufacturing:Industrial zones in Cavite, Laguna, Batangas, Rizal, and Quezon concentrate commercial vehicle servicing, creating dense corridors where fleet operators negotiate volume-based supply contracts with integrated refiners.
Market Restraints
- Base Oil Import Dependency:The Philippines lacks domestic Group II/III base stock production, leaving blenders exposed to freight volatility from Singapore and South Korean supply hubs.
- API Certification Costs:Third-party testing and licensing fees for ILSAC GF-6 and API SP claims impose fixed cost burdens that disadvantage smaller independent blenders without captive laboratory infrastructure.
- Re-refining Infrastructure Gap:Used oil collection networks remain underdeveloped outside Metro Manila, limiting circular economy participation and keeping feedstock costs elevated for sustainability-positioned products.
Strategic Opportunities
- Mindanao Logistics Corridors:Davao and Cagayan de Oro present underpenetrated aftermarket terrain where early-mover lubricant distributors can secure service station exclusivity before national brands complete retail networks.
- E-commerce Replenishment Channels:Lazada and Shopee logistics hubs enable direct-to-garage delivery, bypassing traditional jobber intermediaries and capturing margin from time-constrained motorcycle repair shops in secondary cities.
- Extended-Drain Formulations:OEM service interval lengthening for Toyota, Mitsubishi, and Isuzu commercial vehicles creates demand for synthetic and synthetic-blend products with 15,000-kilometer certification claims.
Industry Challenges
- Additive Chemist Shortage:Formulation expertise for friction modifier and dispersant packages remains concentrated with multinational suppliers, constraining local product development timelines.
- Used Oil Collection Compliance:Hazardous waste regulations under the Department of Environment and Natural Resources require documented chain-of-custody systems that small service stations struggle to implement without aggregator partnerships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Philippines Automotive Lubricants Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Transmission Fluid, Gear Oil, Grease End User: Passenger Vehicles, Commercial Vehicles, Heavy-Duty Trucks, Motorcycles Distribution Channel: Retail Stores, Online Platforms, Service Stations, Distributors Formulation: Mineral Oil, Synthetic Oil, Semi-Synthetic Oil, Bio-Based Lubricants |
| Companies Covered | Petron Corporation, Royal Dutch Shell Plc, Chevron Corporation, BP Plc (Castrol), TotalEnergies, SEAOIL Philippines Inc., Phoenix Petroleum, Gulf Oil International, PTT Lubricants, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Philippines Automotive Lubricants Market Evolving Landscape
Formulation chemistry and distribution architecture in the Philippines are diverging sharply between premium synthetic segments and commodity mineral oil volumes, with regulatory pressure and buyer sophistication widening the gap between product tiers.
Synthetic base stocks derived from Group III and PAO technologies are bifurcating the market. Fleet operators in Metro Manila and CALABARZON are accelerating adoption of 0W-20 and 5W-30 grades to meet OEM warranty requirements and reduce fuel consumption. This technology compression is squeezing mid-tier semi-synthetic positioning, forcing blenders to choose between premium certification investments or commodity volume plays.
The Department of Energy's fuel quality standards are indirectly reshaping additive chemistry by mandating cleaner-burning fuels that reduce soot loading but increase combustion chamber temperatures. Lubricant formulators must recalibrate antioxidant and detergent packages to maintain deposit control under these conditions. Motorcycle oils face the tightest reformulation windows given their higher power density and air-cooled thermal stress profiles.
Independent motorcycle repair shops are consolidating purchasing through digital platforms rather than traditional jobber networks. Shop owners in Cebu, Iloilo, and Davao now compare specifications and pricing through mobile applications before placing orders, compressing brand loyalty cycles and rewarding transparent technical documentation. This behavioral shift is most visible in the 200cc-400cc motorcycle service segment where owner-operators demand OEM-matching viscosity certifications.
Philippines Automotive Lubricants Market Segmentation
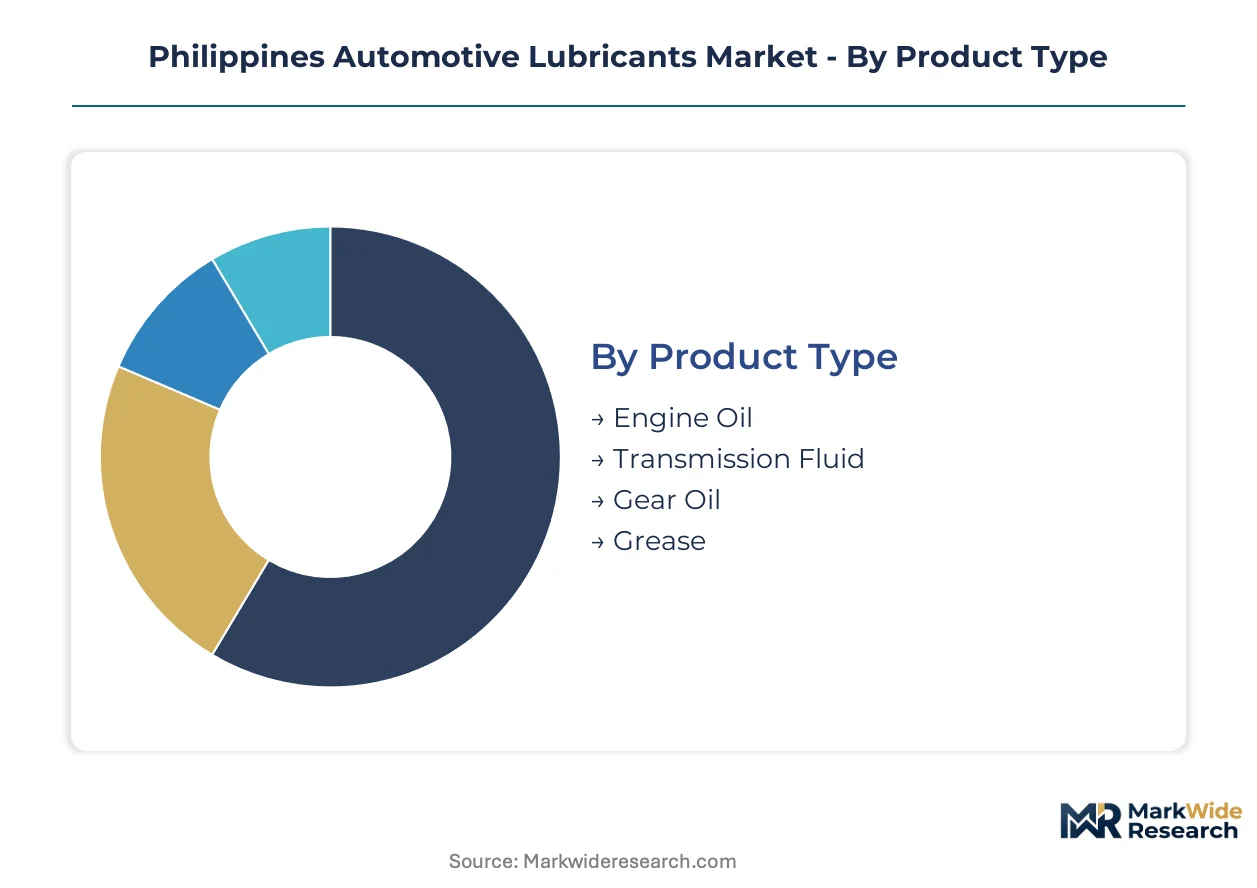
Segmentation in the Philippines automotive lubricants market reveals how regulatory pressure and fleet composition redirect purchasing power across incompatible product tiers. Each dimension exposes different vulnerability to substitution, import dependency, and channel disruption.
Product Type:
Engine oil faces the most acute substitution pressure from extended-drain synthetics that compress replacement frequency, while greases and gear oils defend their positions through application-specific performance barriers.
- Engine Oil:Formulated from Group I-III base stocks with detergent-dispersant additive packages calibrated to API SP and ILSAC GF-6 specifications. Demand concentrates in Metro Manila's commercial servicing corridors where fleet operators negotiate volume contracts for 5W-30 and 10W-40 grades, constrained by Euro 5 emission timelines forcing lower-viscosity adoption.
- Transmission Fluid:Specialized friction-modified formulations for automatic and continuously variable transmissions requiring OEM-specific certification. CALABARZON manufacturing zones drive consumption as Japanese and Korean vehicle assemblers mandate proprietary ATF and CVTF specifications for warranty compliance, limiting cross-brand substitution.
- Gear Oil:Extreme-pressure lubricants for differential and transmission applications with SAE 80W-90 and 75W-140 viscosity grades. Heavy-duty commercial fleets in Mindanao logistics corridors generate concentrated demand.
- Grease:Thickened lubricants for chassis, wheel bearings, and industrial coupling applications. Mining and construction equipment operators in Visayas represent the core customer base.
Engine oil retains volume leadership; transmission fluid holds the steepest expansion curve.
End User:
Cost tier stratification separates premium synthetic demand in fleet-managed commercial segments from price-sensitive mineral oil consumption in owner-operated motorcycle workshops.
- Motorcycles:Two-wheeler density across Luzon, Visayas, and Mindanao creates sustained demand for 10W-40 and 20W-50 grades in air-cooled engines. Rural last-mile delivery and urban gig-economy transport in Davao and Cagayan de Oro drive drain-interval frequency, with independent repair shops consolidating purchases through Lazada and Shopee platforms.
- Commercial Vehicles:Fleet operators in Cavite, Laguna, Batangas, Rizal, and Quezon industrial zones negotiate direct supply contracts with integrated refiners. Extended service intervals for Toyota, Mitsubishi, and Isuzu commercial vehicles accelerate synthetic and synthetic-blend adoption with 15,000-kilometer certification requirements.
- Passenger Vehicles:Private owner maintenance patterns concentrate in Metro Manila service station networks, with OEM warranty compliance driving 0W-20 and 5W-30 specification adherence.
- Heavy-Duty Trucks:Long-haul logistics operators require high-temperature stability and soot-handling capacity in diesel engine oils, with demand clustering along North Luzon Expressway and South Luzon Expressway corridors.
Commercial vehicles command the highest per-account revenue; motorcycles deliver the broadest addressable base.
Distribution Channel:
Geographic coverage gaps in Mindanao and Eastern Visayas create vulnerability for traditional jobber networks as digital platforms capture secondary city aftermarket replenishment.
- Service Stations:Branded retail networks controlled by integrated refiners and multinational oil companies retain channel dominance in Metro Manila and CALABARZON. Petron, Shell, and Caltex service stations combine fuel sales with lubricant bundling, capturing fleet operator loyalty through volume rebate programs.
- Online Platforms:Lazada and Shopee logistics hubs enable direct-to-garage delivery, bypassing traditional intermediaries. Motorcycle repair shops in Cebu, Iloilo, and Davao now compare specifications through mobile applications before ordering, compressing brand loyalty cycles.
- Distributors:Regional jobbers maintain inventory positions in secondary cities where service station density remains insufficient, though margin pressure from platform competition threatens their viability.
- Retail Stores:Hardware and automotive parts outlets serve DIY maintenance segments in provincial areas, with limited technical consultation capability constraining premium product penetration.
Service stations defend the highest transaction values; online platforms are climbing the fastest.
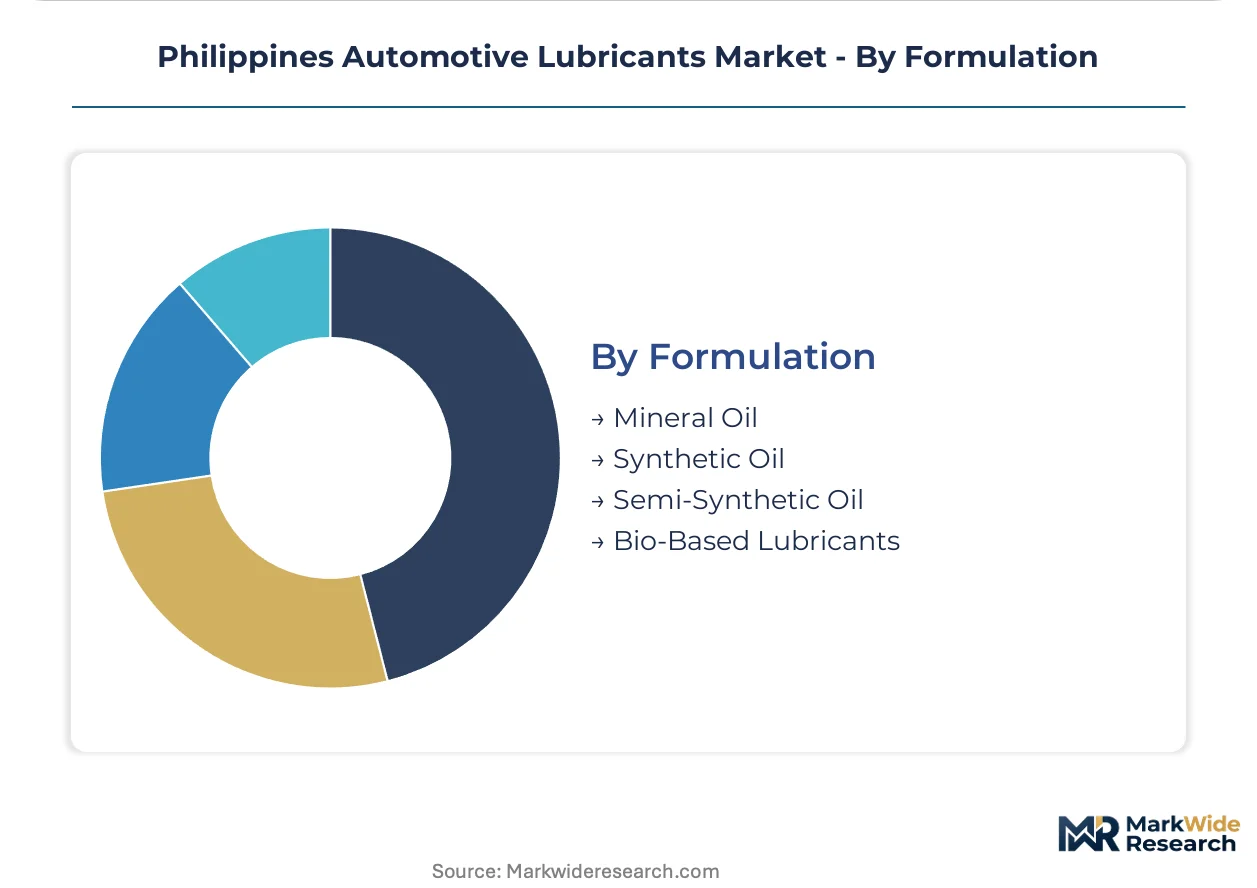
Formulation:
Supply concentration in Singapore and South Korean base oil hubs fragments cost structures across formulation tiers, with import dependency elevating working capital requirements for synthetic positioning.
- Synthetic Oil:Group III and PAO-derived base stocks deliver thermal stability and extended drain intervals required by Euro 5-aligned OEM specifications. Fleet operators in Metro Manila and CALABARZON accelerate adoption of 0W-20 and 5W-30 grades to meet warranty requirements and reduce fuel consumption.
- Semi-Synthetic Oil:Blended formulations targeting mid-market positioning face compression as buyers polarize toward premium synthetics or commodity mineral alternatives. This tier loses share fastest as technology bifurcation accelerates.
- Mineral Oil:Group I base stock formulations dominate rural motorcycle servicing and aging vehicle populations where drain intervals remain short and price sensitivity is acute.
- Bio-Based Lubricants:Vegetable oil-derived formulations with biodegradable additive packages serve niche environmental compliance applications in ecotourism zones and marine protected areas under Department of Environment and Natural Resources oversight.
Mineral oil retains volume leadership; synthetic oil holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity for automotive lubricants varies sharply across Philippine sub-regions. Metro Manila and CALABARZON fleet operators absorb premium synthetic pricing for warranty compliance, while Mindanao and Eastern Visayas motorcycle workshops remain acutely price-sensitive to mineral oil fluctuations.
Metro Manila
Commercial vehicle fleet density along EDSA and North Luzon Expressway corridors sustains volume demand for 5W-30 and 10W-40 synthetic formulations. The Department of Energy's fuel economy programs mandate cleaner-burning fuel standards that indirectly reshape lubricant additive chemistry requirements. Makati and Quezon City service station networks concentrate national brand retail presence where Petron, Shell, and Caltex compete for fleet operator loyalty through volume rebate structures.
CALABARZON
Industrial zones in Cavite, Laguna, Batangas, Rizal, and Quezon generate concentrated commercial vehicle servicing demand as Japanese and Korean automotive assemblers operate manufacturing facilities. The Department of Environment and Natural Resources enforces Euro 5 emission compliance timelines that force lubricant reformulation toward lower-viscosity 0W-20 and 5W-30 products. Toyota, Mitsubishi, and Isuzu fleet operators in Santa Rosa and Calamba negotiate direct supply contracts with integrated refiners for extended-drain synthetic products.
Central Visayas
Cebu and Iloilo anchor motorcycle lubricant consumption as two-wheeler density supports independent repair shop networks. The Bureau of Product Standards mandates Philippine National Standards compliance for petroleum products distributed through regional jobber networks. Digital platform adoption accelerates in Cebu City where shop owners compare specifications through mobile applications before placing Lazada and Shopee orders, compressing traditional brand loyalty cycles.
Davao Region
Mindanao's logistics corridors present underpenetrated aftermarket terrain where national lubricant brands have incomplete retail network coverage. The Department of Environment and Natural Resources hazardous waste regulations require documented chain-of-custody systems for used oil collection that small service stations struggle to implement. Davao City and Cagayan de Oro concentrate commercial fleet activity where early-mover distributors can secure service station exclusivity before dominant brands complete geographic expansion.
Philippines Automotive Lubricants Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes in the Philippines automotive lubricants market. Integrated refiners with captive base stock supply command formulation flexibility and margin control, while independent blenders compete on price accessibility in mineral oil segments. The competitive structure bifurcates between premium synthetic positioning backed by OEM certification investments and commodity volume plays serving rural motorcycle servicing. Dominant competitive moves include backward integration into base oil supply and digital platform partnerships that bypass traditional jobber intermediaries.
Within the integrated refiner archetype, Petron Corporation and Royal Dutch Shell Plc occupy positions that exemplify divergent strategic approaches to the Philippine market. Petron's Bataan-based refining infrastructure represents captive supply control over base stock availability. Shell's branded service station network anchors premium positioning through retail density in Metro Manila and CALABARZON corridors. Chevron Corporation, operating through its Caltex retail presence, sits within the multinational oil company tier competing on distribution reach. BP Plc's Castrol subsidiary exemplifies specialization in motorcycle-specific formulations that target the fastest-growing consumption segment.
| Leading Market Players |
|---|
| Petron Corporation |
| Royal Dutch Shell Plc |
| Chevron Corporation |
| BP Plc (Castrol) |
| TotalEnergies |
| SEAOIL Philippines Inc. |
| Phoenix Petroleum |
| Gulf Oil International |
| PTT Lubricants |
| Others |
Value Network & Pricing Analysis
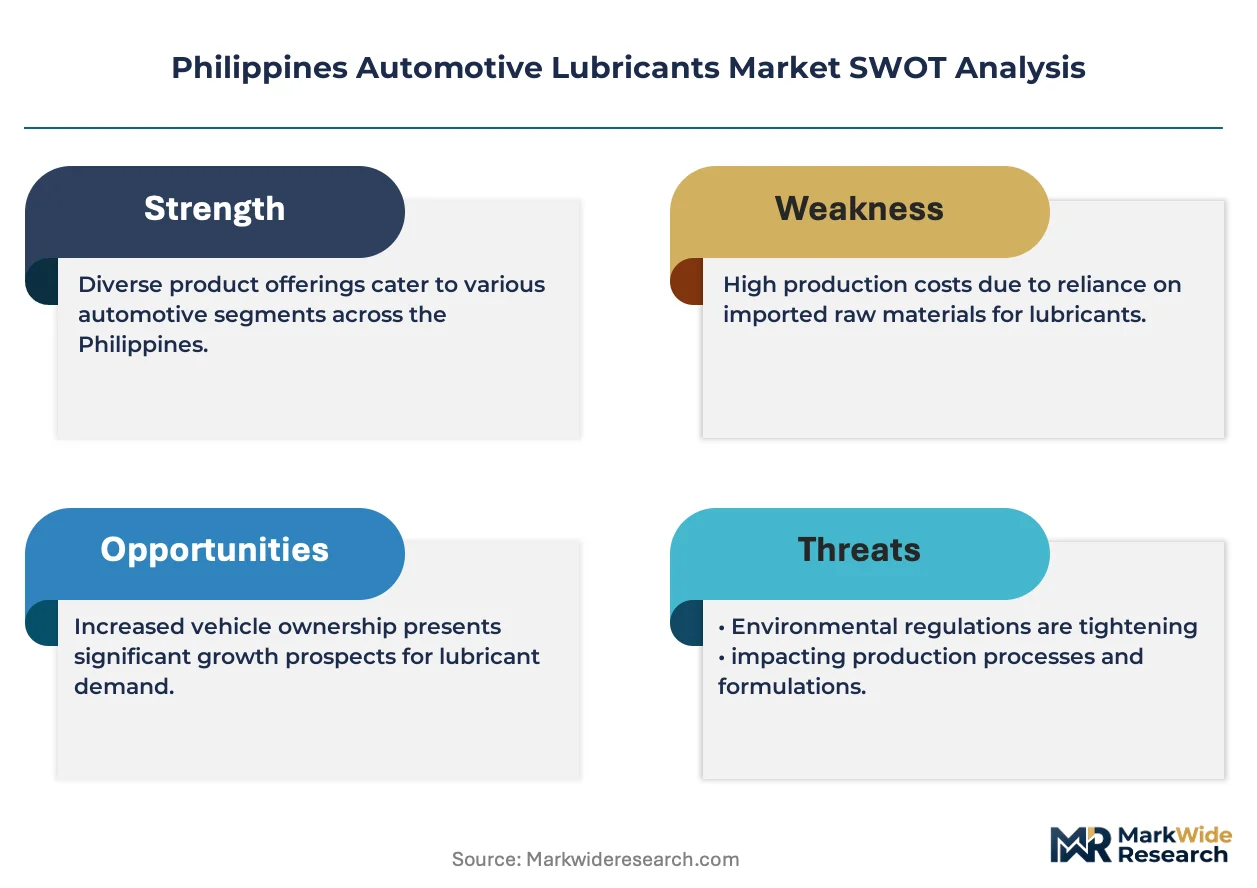
Forty-five to sixty-day base oil lead times from Singapore and South Korean supply hubs compress working capital cycles for Philippine blenders while amplifying pricing volatility during freight spikes. This inventory-to-pricing linkage forces formulation decisions that trade margin stability against product availability in a market where import dependency concentrates cost control with integrated refiners.
Pricing Analysis
After-sales service bundling through branded station networks drives lifetime value capture for integrated refiners competing against jobber-distributed alternatives. Three-tier pricing structure across premium synthetic, semi-synthetic, and mineral oil levels stratifies by API certification grade and volume commitment scale, with synthetic positioning commanding premium spreads justified by extended-drain warranty compliance. Cost compression in mineral oil tiers is intensifying because motorcycle repair shops in secondary cities consolidate purchasing through digital platforms that expose price transparency. Fleet operators in CALABARZON industrial zones exhibit lowest price sensitivity due to OEM-mandated specification adherence, while rural owner-operated workshops in Mindanao remain most responsive to per-liter differentials.
Supply Chain Analysis
Strategic stockpile preferences dominate among integrated refiners with captive Bataan storage, while independent blenders run lean just-in-time positions exposed to Singapore and South Korean supply disruptions. Group II and Group III base stocks draw from Singaporean and South Korean refining complexes, with additive packages sourced from multinational chemical suppliers in Japan and the USA. Single-source vulnerability concentrates in API SP certification testing infrastructure, where third-party laboratory access creates bottlenecks for product launch timelines. Distribution runs through service station networks in Metro Manila and CALABARZON, with digital platforms capturing secondary city replenishment in Central Visayas and Mindanao.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Philippines automotive lubricants market represents early-cycle expansion anchored in motorcycle fleet density growth across underpenetrated Mindanao logistics corridors. CALABARZON manufacturing zone concentration and Euro 5 emission alignment create sustained formulation upgrade demand that rewards early positioning in synthetic product tiers.
For Market Incumbents: Shield margin pools in Metro Manila and CALABARZON fleet corridors by securing exclusive service station supply contracts before national brands complete retail network expansion. Deepen backward integration into additive package formulation capabilities to reduce dependency on multinational chemical suppliers. Channel control through volume rebate structures remains the critical defensive lever against digital platform disintermediation threatening traditional jobber networks.
For New Entrants and Emerging Players: Lead with e-commerce direct-to-garage delivery models targeting motorcycle repair shops in Davao and Cagayan de Oro where service station density remains insufficient. Mindanao logistics corridors present the most penetrable geography for early-mover exclusivity arrangements. Capture share through transparent technical documentation and mobile application-enabled specification comparison that compresses incumbent brand loyalty cycles among independent workshop owners.
For Investors and Strategic Acquirers: Carve-out targets emerge from multinational oil companies repositioning portfolio focus away from downstream Philippine retail operations. Long-term viability hinges on synthetic formulation capability and API certification infrastructure that sustains premium positioning through OEM warranty compliance cycles. Watch for inflection when Department of Environment and Natural Resources accelerates Euro 5 enforcement timelines, forcing accelerated reformulation investment that disadvantages capital-constrained independents.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Oil Supply | Captive Bataan refinery operations insulate Petron from Singapore freight volatility and secure formulation flexibility. |
| Digital Platform Partnership Development | Lazada and Shopee logistics hubs enable direct-to-garage delivery bypassing traditional jobber intermediaries in secondary cities. |
| API SP Certification Investment | Third-party testing infrastructure access accelerates product launch timelines against ILSAC GF-6 specification deadlines. |
| Mindanao Service Station Exclusivity | Early-mover arrangements in Davao and Cagayan de Oro secure geographic moats before national brands complete retail expansion. |
| Extended-Drain Formulation Development | Synthetic and synthetic-blend products with 15,000-kilometer claims capture OEM service interval lengthening for Toyota and Mitsubishi fleets. |
Research Methodology
A standing panel of refinery operations managers, lubricant formulation chemists, fleet procurement officers, and aftermarket distributor principals provided ongoing calibration against market developments. Primary interview insights triangulated with secondary validation from Department of Energy fuel quality bulletins, Bureau of Product Standards regulatory filings, vehicle registration databases, and customs import records for base oil and additive shipments. Bottom-up volume modeling across product type, end user, and formulation segments converged with top-down market sizing derived from integrated refiner revenue disclosures.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including product type, end user category, distribution channel, and formulation technology tier. CAGRs were derived from trend extrapolation adjusted for regulatory compliance timelines and OEM specification evolution. Industry-specific forecast inputs incorporated motorcycle fleet registration trajectories and commercial vehicle production schedules from CALABARZON assembly operations.
Forecasts assume regulatory continuity in Department of Environment and Natural Resources emission compliance and Department of Energy fuel economy programs; material policy shifts would require re-modeling. Forecasts reflect assumptions regarding base oil import cost stability and API certification infrastructure access. Revision becomes warranted when Euro 5 enforcement acceleration or base oil supply disruption crosses thresholds that alter blender cost structures or product availability timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Nigeria Automotive Lubricants Market
Automotive Parts
Automotive Filter Paper Market
Automotive Parts
Electromagnetic Clutch System Market
Automotive Parts
Automotive Belts Market
Automotive Parts
Europe Automotive Aftermarket Spare Parts Market
Automotive Parts
Automotive Vents Market
Automotive Parts
Global Automotive Damper Market
Automotive Parts
Automotive Trim Part Market
Automotive Parts
Rammer Market
Automotive Parts
Automotive Cylinder Head Gasket Market
Automotive Parts
Air Springs Market
Automotive Parts
Automotive Hoses Market
Automotive Parts
Commercial Vehicle Brake Chambers Market
Automotive Parts
Global Automotive Gas Charged Shock Absorbers Market
Automotive Parts
Global Truck Refrigeration Unit Market
Automotive Parts
Industrial Shock Absorbers Market