
 Artificial Spine Discs Market | 2026-2036
Artificial Spine Discs Market Size, Share, and Industry Trends Forecast 2026-2036
Artificial Spine Discs Market Intelligence
The ISO 13485 quality management standard is bifurcating the competitive landscape, separating manufacturers with certified production systems from smaller entrants. Medtronic leverages its extensive clinical trial data and global distribution network to maintain a leading position. Johnson & Johnson (DePuy Synthes) differentiates through its focus on biocompatible materials and surgeon training programs. Centinel Spine specializes in innovative cervical and lumbar disc replacement technologies, targeting specific patient populations.
An artificial spine disc is a prosthetic device designed to replace a damaged intervertebral disc in the spine, aiming to preserve motion. These devices often feature a core made of ultra-high-molecular-weight polyethylene sliding between two endplates constructed from titanium alloy. Cervical discs command the largest share due to higher procedural volumes for degenerative conditions in the neck. In terms of materials, PEEK composites are gaining traction for their radiolucency and modulus of elasticity.
Market access hinges on navigating stringent regulatory pathways, including the FDA's PMA process in the United States and CE marking under the MDR in Europe. These frameworks mandate extensive clinical evidence to prove both safety and efficacy. In parallel, bodies like Japan's PMDA and China's NMPA impose their own rigorous testing and approval requirements. The critical decision for device makers revolves around balancing investment in next-generation materials against the long timelines for regulatory approval.
Market Dynamics
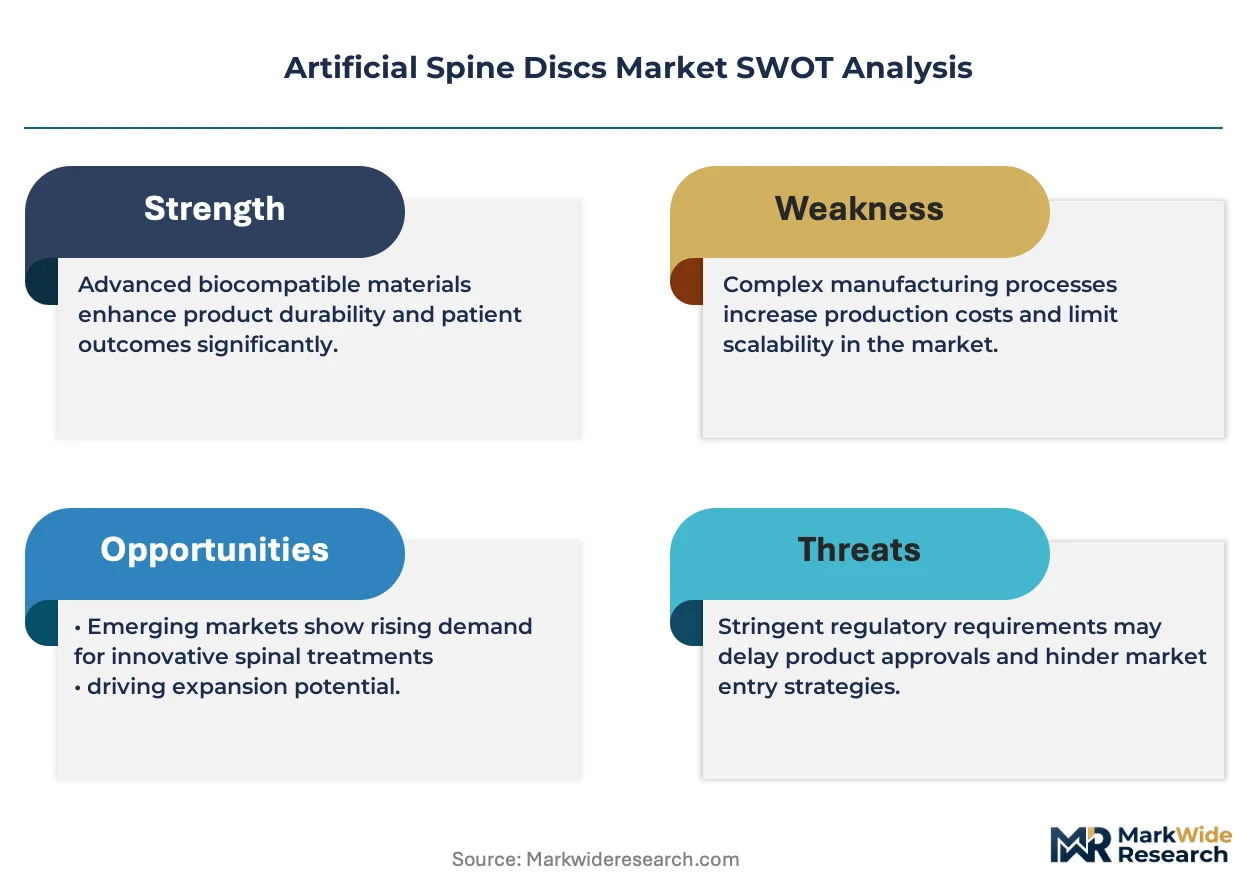
The market's trajectory is defined by the core tension between rapid material science advancements and the protracted timelines of global regulatory bodies. This dynamic forces manufacturers to balance investment in next-generation composites against the lengthy clinical evidence requirements for market approval.
Growth Catalysts
- Favorable Reimbursement:Comprehensive coverage policies, particularly in Germany, lower the financial barrier for patients and encourage adoption of advanced spinal prosthetics in Specialized Hospitals.
- Aging Demographics:An increasing prevalence of degenerative disc disease in aging populations, especially in countries like Japan, expands the addressable patient base for motion-preserving spinal surgery.
- Material Innovation:The adoption of PEEK composites enhances device radiolucency, allowing for clearer post-operative imaging and assessment, which is a significant clinical advantage over traditional metals.
Market Restraints
- High Procedural Costs:The combined expense of the artificial disc and the complex surgical procedure limits accessibility in healthcare systems without robust, specific reimbursement codes for disc arthroplasty.
- Stringent Regulatory Hurdles:The FDA's Premarket Approval (PMA) process in the United States mandates extensive and costly clinical trials, significantly delaying the introduction of new devices.
- Dominance of Spinal Fusion:Spinal fusion remains a well-established, widely practiced, and often lower-cost surgical alternative, representing a significant substitution threat for potential disc replacement candidates.
Strategic Opportunities
- Geographic Expansion:Entering markets such as Brazil, where medical device regulators like ANVISA are clarifying approval pathways, presents an opportunity to reach new patient populations.
- Patient-Specific Devices:Leveraging 3D printing technology to create customized endplates tailored to individual patient anatomy offers a pathway for improved device fit and potentially better clinical outcomes.
- Focus on Younger Patients:Targeting younger, more active patients who place a high value on preserving spinal motion post-surgery can create a distinct market segment where the benefits over fusion are most pronounced.
Industry Challenges
- Surgical Skill Scarcity:A limited pool of orthopedic and neurosurgeons possess the specialized training required for artificial disc replacement, constraining procedural volume growth compared to conventional techniques.
- Compliance Overhead:Maintaining ISO 13485 quality management certification while navigating the evolving post-market surveillance demands of Europe's MDR creates a significant and ongoing operational burden.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Artificial Spine Discs Market |
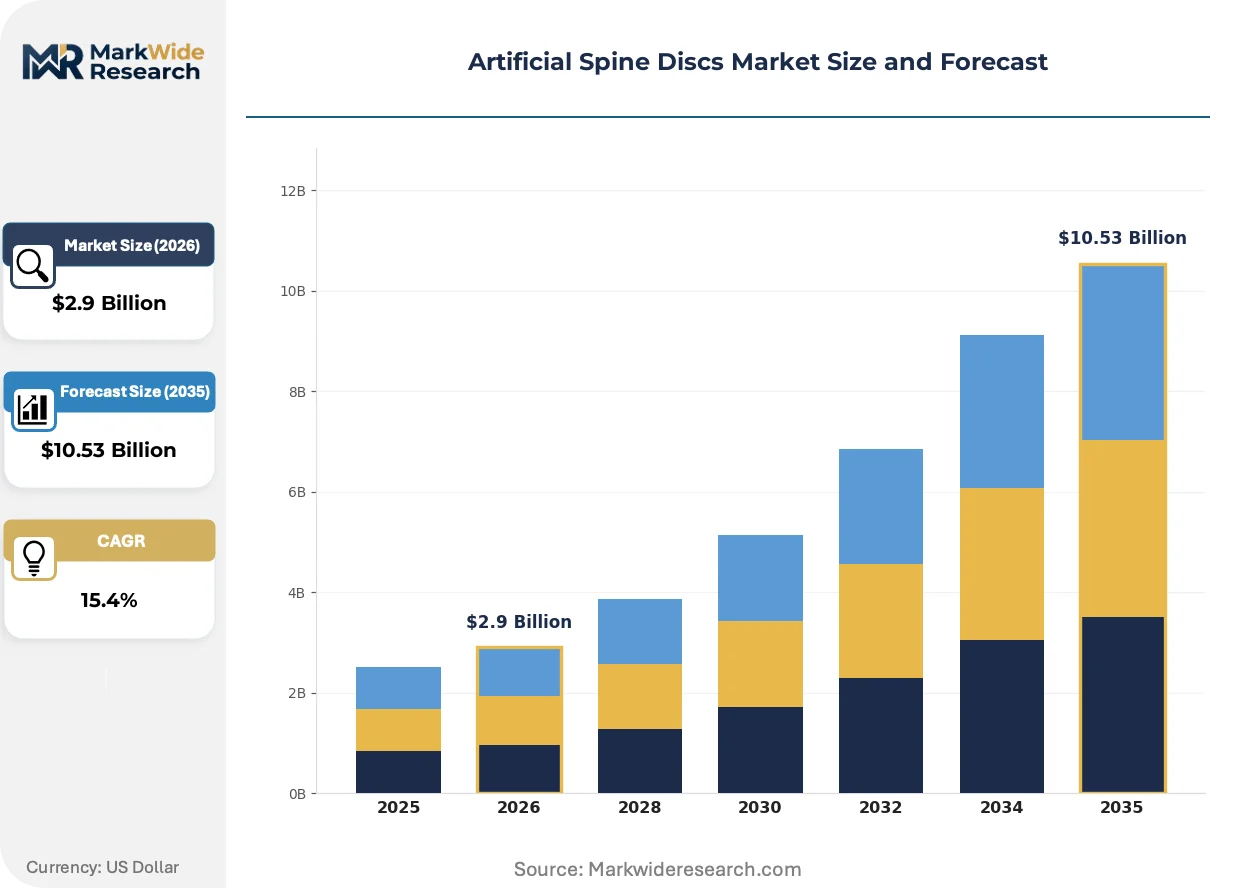
| Market Size in 2026 | $2.9 Billion |
| Market Size in 2035 | $10.53 Billion |
| CAGR (2026 – 2036) | 15.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cervical Discs, Lumbar Discs, Thoracic Discs, Hybrid Discs Material: Titanium Alloy, Polyethylene, Stainless Steel, Ceramic Composite, PEEK Application: Degenerative Disc Disease, Spinal Stenosis, Herniated Disc, Spondylolisthesis, Traumatic Injury End User: Orthopedic Clinics, Neurospinal Centers, Rehabilitation Facilities, Ambulatory Surgery, Specialized Hospitals |
| Companies Covered | Medtronic, Zimmer Biomet, Johnson & Johnson (DePuy Synthes), Centinel Spine, Globus Medical, NuVasive, B. Braun Melsungen AG (Aesculap), Orthofix Medical, Stryker Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Artificial Spine Discs Market Strategic Shifts & Innovations
An evolution in material science is fundamentally altering device design and performance characteristics. These innovations are developing within a strict global regulatory environment that prioritizes long-term patient safety and proven clinical efficacy over speed to market.
The use of PEEK composites as a core material is a key product evolution. These polymers offer a modulus of elasticity closer to natural bone than titanium, alongside complete radiolucency for unimpeded post-operative imaging. Adoption by surgeons in specialized orthopedic centers is steady, particularly for complex cervical cases. This trend is bifurcating the market between devices offering advanced material benefits and established prosthetics based on titanium alloys.
Regulatory harmonization is creating more efficient global market access strategies. Japan's PMDA, for instance, is increasingly aligning its requirements with data packages used for FDA approval or CE marking. This shift reduces the need for duplicative, country-specific clinical trials, saving significant time and expense for manufacturers. Cervical disc prosthetics, which have a deep well of existing clinical evidence, are best positioned to benefit from this streamlined pathway into the Japanese market.
A clear preference for evidence-based purchasing is changing how hospitals select spinal implants. Decision-making authority is migrating from individual surgeons to multidisciplinary value analysis committees that rigorously evaluate long-term clinical outcomes and cost-effectiveness data. This shift away from relationship-based selling favors devices with strong, published multi-year trial results. The trend is most visible within large, integrated hospital networks in the United States and parts of Europe.
Artificial Spine Discs Market Segmentation
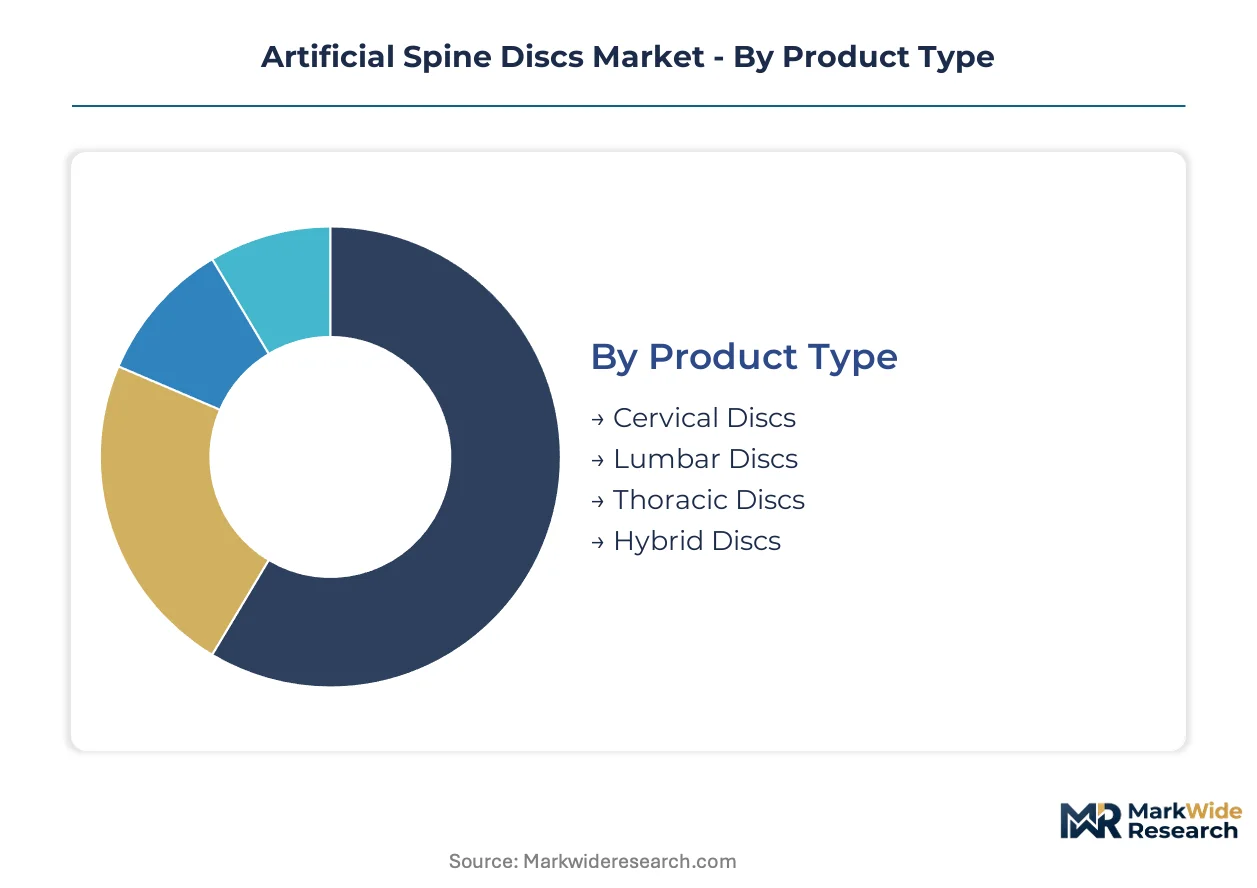
The Artificial Spine Discs Market is diverse, shaped by distinct product designs, material innovations, clinical applications, and end-user preferences. Understanding these segments is crucial for manufacturers to align product development with specific patient needs and healthcare provider capabilities.
Product Type:
Product type segmentation distinguishes between devices primarily used in domestic markets and those with broader international export appeal. Procedural volumes vary by region.
- Cervical Discs:These prosthetics replace damaged intervertebral discs in the neck, restoring motion. Cervical discs hold the largest market share due to high incidence of degenerative conditions, particularly in Japan.
- Lumbar Discs:Designed for the lower back, these devices address disc degeneration. Lumbar disc procedures are common in the United States and Europe, driven by patient desire for motion preservation.
- Thoracic Discs:Specialized implants for the less common replacement of discs in the mid-back region. Surgical complexity limits procedural volume.
- Hybrid Discs:Combining fusion and motion preservation elements, hybrid discs offer tailored solutions for complex spinal pathologies.
Cervical Discs commands the established base. The steepest expansion runs through Lumbar Discs.
Material:
Material segmentation often reflects varying cost tiers, with advanced composites commanding higher prices due to specialized manufacturing and enhanced biomechanical properties.
- PEEK:Polyether ether ketone (PEEK) composites offer radiolucency for clear post-operative imaging. Their modulus of elasticity matches natural bone, reducing stress shielding. PEEK gains traction in European orthopedic centers.
- Titanium Alloy:This metal is a traditional material for endplates due to its biocompatibility and mechanical strength. Titanium alloy devices are widely used globally, offering a proven track record.
- Polyethylene:Ultra-high-molecular-weight polyethylene (UHMWPE) is used as the core sliding component, providing low friction articulation.
- Stainless Steel:Less common than titanium, stainless steel is sometimes used for endplates in older disc designs.
- Ceramic Composite:These materials offer wear resistance and biocompatibility, but brittleness limits widespread spinal application.
Titanium Alloy maintains broad market penetration. PEEK composites are rapidly expanding their footprint.
Application:
Application segmentation illustrates varying procedural volumes associated with different spinal pathologies, influencing device demand and manufacturer focus. High-volume indications attract significant investment.
- Degenerative Disc Disease:This condition, the breakdown of intervertebral discs, is the primary indication for artificial disc replacement. An aging global demographic drives high prevalence, particularly in Europe.
- Herniated Disc:Occurring when disc material pushes through its outer layer, herniated discs cause pain. Disc replacement is a common treatment, especially for cervical herniations.
- Spinal Stenosis:Narrowing of the spinal canal compresses nerves. Disc replacement is less common for this condition.
- Spondylolisthesis:One vertebra slips forward over another. Disc replacement is considered for specific, low-grade cases.
- Traumatic Injury:Disc replacement for traumatic injuries is rare, reserved for severe cases where motion preservation is feasible.
Degenerative Disc Disease represents the largest patient population. Herniated Disc procedures maintain consistent demand.
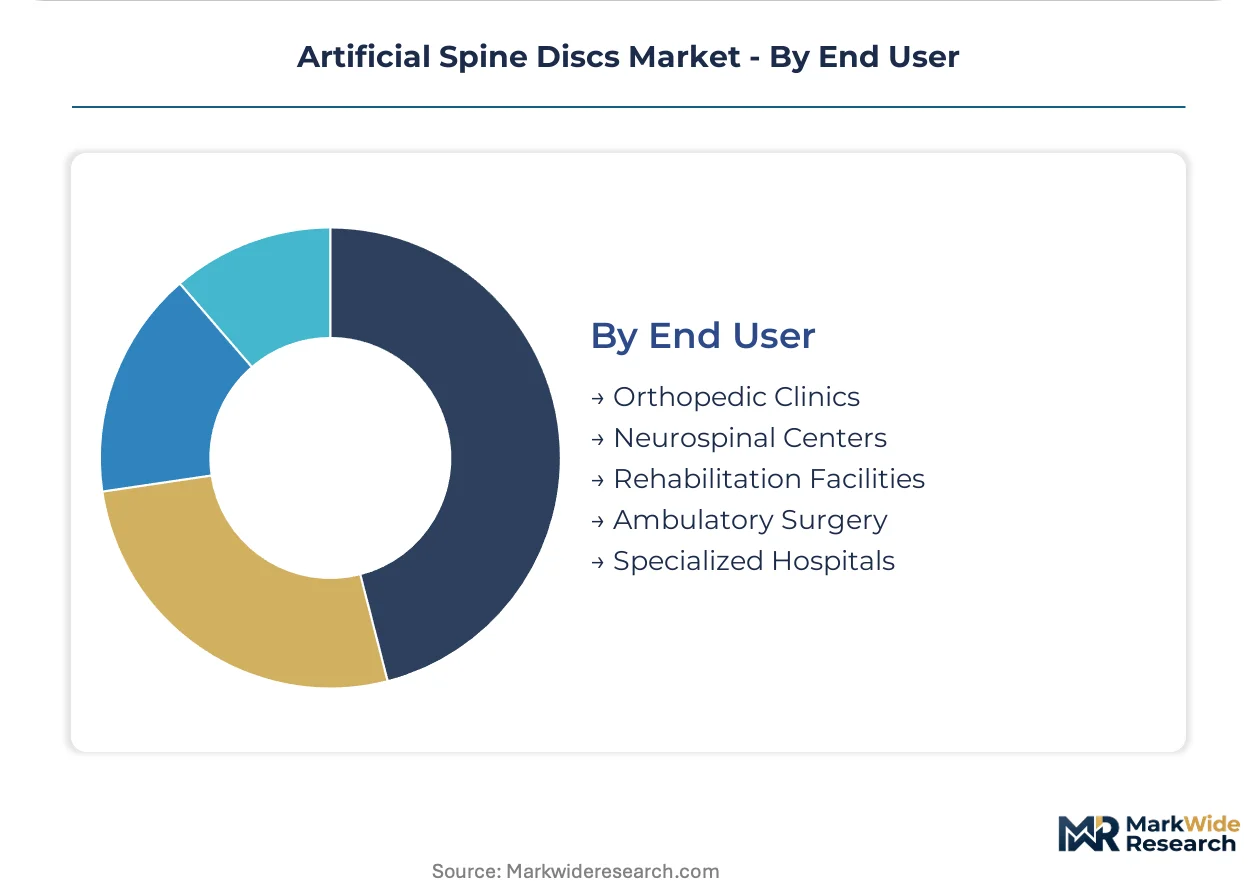
End User:
End-user segmentation reflects the maturity of surgical infrastructure and specialized care capabilities across different healthcare settings. Facilities with advanced surgical suites drive higher procedural volumes.
- Specialized Hospitals:These facilities are equipped with advanced surgical technology and multidisciplinary teams, making them primary centers for complex artificial disc replacement. Adoption accelerates in Germany.
- Neurospinal Centers:Highly specialized centers focusing on neurological and spinal conditions perform significant disc replacement surgeries. They attract patients seeking expert care.
- Orthopedic Clinics:Many orthopedic clinics refer complex cases, but some larger clinics with surgical capabilities perform less intricate procedures.
- Rehabilitation Facilities:These facilities focus on post-operative care and physical therapy, crucial for patient recovery.
- Ambulatory Surgery:Disc replacement in ambulatory surgery centers is limited due to procedural complexity and need for overnight monitoring.
Specialized Hospitals remain the dominant end-user. Neurospinal Centers are expanding their procedural capacity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized Hospitals, equipped with advanced surgical technology, concentrate the demand for artificial spine discs globally. These facilities, particularly in developed economies, drive the adoption of complex spinal prosthetics due to their capacity for intricate procedures and post-operative care. Understanding regional nuances in regulation and healthcare infrastructure is crucial for market penetration.
United States
The United States drives significant demand for artificial spine discs, fueled by a high prevalence of degenerative disc disease and patient preference for motion preservation. The FDA's Premarket Approval (PMA) process sets a rigorous standard for device safety and efficacy before market entry. Major medical device manufacturing and research hubs in states like California and Massachusetts lead in clinical trial initiation and product development.
Germany
Germany represents a strong market for artificial spine discs, benefiting from comprehensive reimbursement policies that lower patient financial barriers. Compliance with the EU's Medical Device Regulation (MDR) is essential for manufacturers seeking market access within the European Union. Specialized orthopedic centers across cities like Berlin and Munich accelerate the adoption of advanced spinal prosthetics.
Japan
Japan's aging demographics contribute to a rising patient base for artificial spine disc replacement, particularly for cervical conditions. The PMDA is increasingly aligning its regulatory requirements with international standards, streamlining the approval process for well-documented devices. Major metropolitan areas like Tokyo and Osaka host numerous neurospinal centers focusing on advanced surgical techniques.
China
A growing middle class and expanding healthcare infrastructure are increasing the addressable market for artificial spine discs in China. The NMPA imposes its own rigorous testing and approval requirements for medical devices, influencing local manufacturing and import strategies. Medical device industrial parks in regions such as Shanghai and Suzhou are becoming centers for both domestic production and international collaboration.
Brazil
Brazil presents a strategic opportunity for geographic expansion, as its medical device regulator, ANVISA, clarifies approval pathways for advanced prosthetics. The rising incidence of spinal conditions among its large population creates a substantial patient pool. Major healthcare centers in São Paulo and Rio de Janeiro are expanding their capabilities in complex spinal surgeries, including disc arthroplasty.
Artificial Spine Discs Market Key Industry Players
Player mix skews toward established medical device conglomerates with diversified portfolios. The market structure exhibits a tiered consolidation, with a few large players dominating the premium segment and smaller innovators focusing on niche applications. Strategic archetypes include global diversified players, specialized spinal implant manufacturers, and material science innovators. Dominant competitive moves involve strategic partnerships for technology development and geographic expansion into emerging markets.
On the premium-tier vector, Medtronic and Johnson & Johnson (DePuy Synthes) occupy a significant position, leveraging extensive clinical data and established distribution networks. These companies exemplify the global diversified player archetype, offering a broad range of spinal solutions. Centinel Spine exemplifies specialization, focusing on innovative cervical and lumbar disc replacement technologies for specific patient populations and maintaining a strong market presence in its niche.
| Leading Market Players |
|---|
| Medtronic |
| Zimmer Biomet |
| Johnson & Johnson (DePuy Synthes) |
| Centinel Spine |
| Globus Medical |
| NuVasive |
| B. Braun Melsungen AG (Aesculap) |
| Orthofix Medical |
| Stryker Corporation |
| Others |
Cost & Logistics Intelligence
Long-term procurement agreements for specialized hospitals lock in supply access and provide price visibility for advanced artificial spine discs.
Pricing Analysis
Cost-plus contracts, often indexed to material costs like titanium alloy and PEEK composites, define pricing for artificial spine discs. Price differentiation stems from extensive clinical trial data demonstrating long-term efficacy and the level of customization offered, such as patient-specific 3D printed endplates. Pricing softness emerges from stringent reimbursement policies in some regions and the established, lower-cost alternative of spinal fusion. Specialized Hospitals with comprehensive coverage are less price-sensitive than smaller orthopedic clinics operating under tighter budgets.
Supply Chain Analysis
Inbound logistics costs, particularly for specialized medical-grade materials, influence the supply chain for artificial spine discs. Manufacturing concentrates in the United States, Germany, and China, drawing from specialized suppliers for titanium alloy, PEEK composites, and UHMWPE. Regulatory approval delays, especially for novel materials, represent a significant structural risk for new device introduction. Distribution primarily flows through direct sales forces and specialized medical device distributors to Specialized Hospitals and Neurospinal Centers globally.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market exhibits a buyer-power shift, driven by the consolidation of purchasing decisions within large integrated hospital networks and value analysis committees.
For Market Incumbents:Compound investment in long-term clinical trial data to reinforce device efficacy against the ongoing threat of spinal fusion. Secure preferred vendor status with large hospital systems through comprehensive product portfolios and robust surgeon training programs. Leverage extensive global distribution networks to accelerate market penetration in emerging economies like Brazil, offsetting slower growth in mature markets.
For New Entrants and Emerging Players:Differentiate on patient-specific device customization, utilizing 3D printing technology to target complex anatomical challenges. Focus on the younger, active patient segment in developed markets where motion preservation benefits over fusion are highly valued. Penetrate markets with clarifying regulatory pathways, such as Brazil, by demonstrating superior material innovation like PEEK composites for specific cervical applications.
For Investors and Strategic Acquirers:The market sits at a growth phase that favors specialized spinal implant manufacturers with strong intellectual property in next-generation materials. Long-term viability depends on sustained material advancements and streamlined regulatory approvals over the next decade. Acquisition targets include agile innovators focusing on patient-specific solutions; watch for accelerated reimbursement codes in new geographies.
| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Material R&D | Developing PEEK composites with enhanced biomechanical properties improves device performance and patient outcomes. |
| Regulatory Pathway Acceleration | Streamlining FDA PMA submissions and CE marking under MDR reduces time-to-market for novel disc designs. |
| 3D Printing Investment | Creating patient-specific endplates via additive manufacturing offers improved fit and reduces surgical complexity. |
| Hospital System Partnerships | Collaborating with Specialized Hospitals for clinical trials generates crucial long-term efficacy data. |
| Geographic Market Entry | Entering markets like Brazil, with clarifying ANVISA regulations, expands the addressable patient population. |
Research Approach
Initial hypotheses were tested against primary input from orthopedic surgeons, neurosurgeons, and hospital procurement committees, then refined through iterative processes. This involved combining insights from these industry stakeholders with secondary validation from FDA filings, PMDA reports, and clinical trial registries. Bottom-up market sizing and top-down validation ensured comprehensive data triangulation.
Variance decomposition identified key drivers impacting artificial spine disc adoption across the analysis window. The framework modeled market dynamics across product type, material, application, end user, and surgical approach. Compound Annual Growth Rates were derived from historical trends and projected procedural volumes, informed by aging demographics and regulatory shifts.
The analysis sits within stated boundaries; outcomes outside major shifts in reimbursement or disruptive surgical techniques necessitate recalibration. Forecasts reflect documented assumptions on material innovation and clinical evidence. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Saudi Arabia Minimally Invasive Surgery Devices Market
Medical Devices
Global Portable Ultrasound Equipment Market
Medical Devices
Biomedical Temperature Sensors Market
Medical Devices
Global Tumor Tracking Systems Market
Medical Devices
Capsule Endoscope and Workstations Market
Medical Devices
Global Adult and Pediatric Hemoconcentrators Market
Medical Devices
Implantable Neurostimulation Device EMI and Safety Test Systems Market
Medical Devices
Global Female Sterilization Devices Market
Medical Devices
Middle East and Africa Orthotic Devices Market
Medical Devices
Global Peripheral Vascular Devices and Accessories Market
Medical Devices
US Thrombectomy Devices Market
Medical Devices
MRI Guided Drug Delivery Market
Medical Devices
United States Implantable Medical Devices Market
Medical Devices
Brazil Artificial Organs and Bionic Implants Market
Medical Devices
Interspinous Process Decompression Devices Market
Medical Devices
Single-Lead ECG Monitors Market