
 Europe Electric Vegetable Chopper Market | 2026-2036
Europe Electric Vegetable Chopper Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Electric Vegetable Chopper Market Insights
Appliance engineering talent shortages across Central Europe is unwinding production capacity expansion plans for several manufacturers. Braun GmbH leverages its deep R&D heritage in precision motor systems to sustain premium positioning across German-speaking markets. SEVERIN Elektrogerate GmbH anchors its competitive stance through manufacturing scale at its Sundern facility, while Philips N.V. differentiates via channel control across Benelux and Nordic retail networks.
Europe electric vegetable choppers are motor-driven food preparation appliances employing stainless steel or BPA-free plastic housings with rotary blade assemblies rated between 100W and 700W, designed to reduce manual cutting labor in domestic and commercial kitchens. Countertop units dominate value contribution due to higher power ratings and multi-function attachments, whereas handheld segments capture volume through entry-price positioning in Southern and Eastern European markets. Stainless steel material grades command margin premiums over plastic variants, particularly in restaurant and catering service procurement where durability requirements override initial cost considerations.
CE marking obligations under the EU Machinery Directive and Ecodesign framework mandate energy efficiency thresholds and electrical safety testing for all units sold within the region, while REACH restricts hazardous substances in blade coatings and housing polymers. The EU Green Deal's circular economy requirements are pressuring manufacturers to redesign for disassembly and establish take-back programs across member states. Stakeholders must monitor evolving ECHA substance restrictions and national transposition timelines to anticipate compliance cost impacts on sourcing and pricing structures.
Market Dynamics
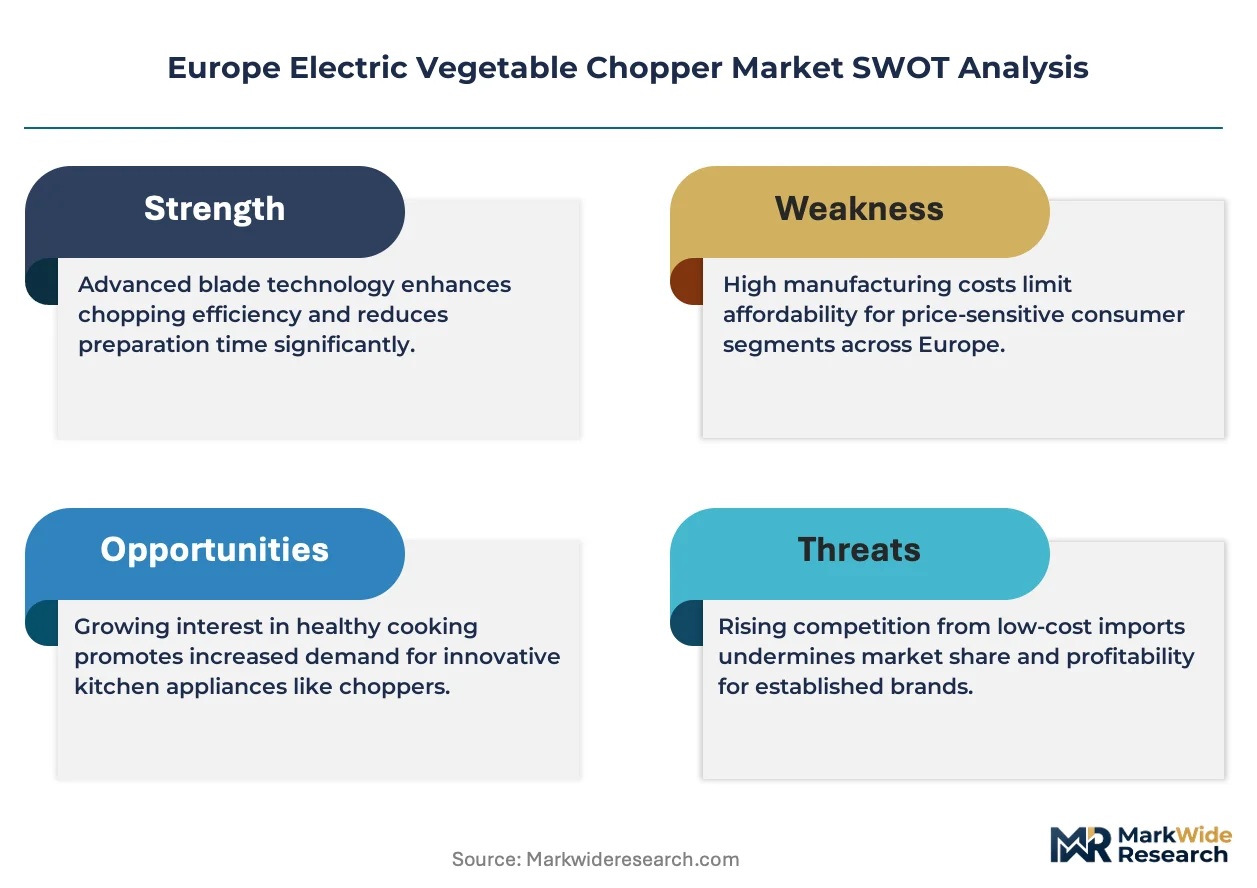
The EU Green Deal's circular economy mandates are forcing manufacturers to redesign blade housings and motor assemblies for end-of-life disassembly, compressing margins while opening compliance-based differentiation pathways for early movers.
Growth Catalysts
- REACH substance restrictions:ECHA's evolving restrictions on blade coatings and housing polymers are accelerating R&D investment in BPA-free thermoplastics and ceramic-coated cutting assemblies across German and French supply chains.
- Small-format food service:Urban ghost kitchens and delivery-only operations in London, Paris, and Berlin are standardizing countertop multi-function units to reduce prep labor and footprint constraints.
- Rental housing penetration:Compact appliance demand from millennial tenants in Barcelona, Amsterdam, and Milan is driving volume through entry-price handheld segments with sub-200W power ratings.
Market Restraints
- Copper and rare-earth magnet costs:Motor assembly input volatility from Chinese processing concentration is compressing gross margins for mid-tier manufacturers without captive sourcing arrangements.
- CE marking complexity:Divergent national transposition timelines for the EU Machinery Directive's 2023 amendments are extending certification cycles by four to eight months for new product launches.
- Manual knife substitution:Cultural preference for traditional cutting methods in Southern European domestic kitchens limits electric chopper penetration in price-sensitive segments.
Strategic Opportunities
- Polish and Romanian retail expansion:Underpenetrated modern trade channels in Warsaw and Bucharest offer first-mover advantage for brands establishing localized service networks.
- Take-back program mandates:The EU Green Deal's extended producer responsibility requirements create competitive moat for manufacturers with established reverse logistics infrastructure.
- Smart kitchen integration:Convergence of Bluetooth-enabled motor controls with recipe-app ecosystems is opening premium positioning for connected countertop units in Nordic markets.
Industry Challenges
- Precision motor engineering talent:Central European technical universities produce insufficient graduates with small-appliance electromagnetic design expertise, constraining R&D pipeline velocity.
- Multi-jurisdiction compliance:Simultaneous navigation of ECHA substance reviews, national WEEE transpositions, and evolving energy efficiency tiers fragments product management bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Electric Vegetable Chopper Market |
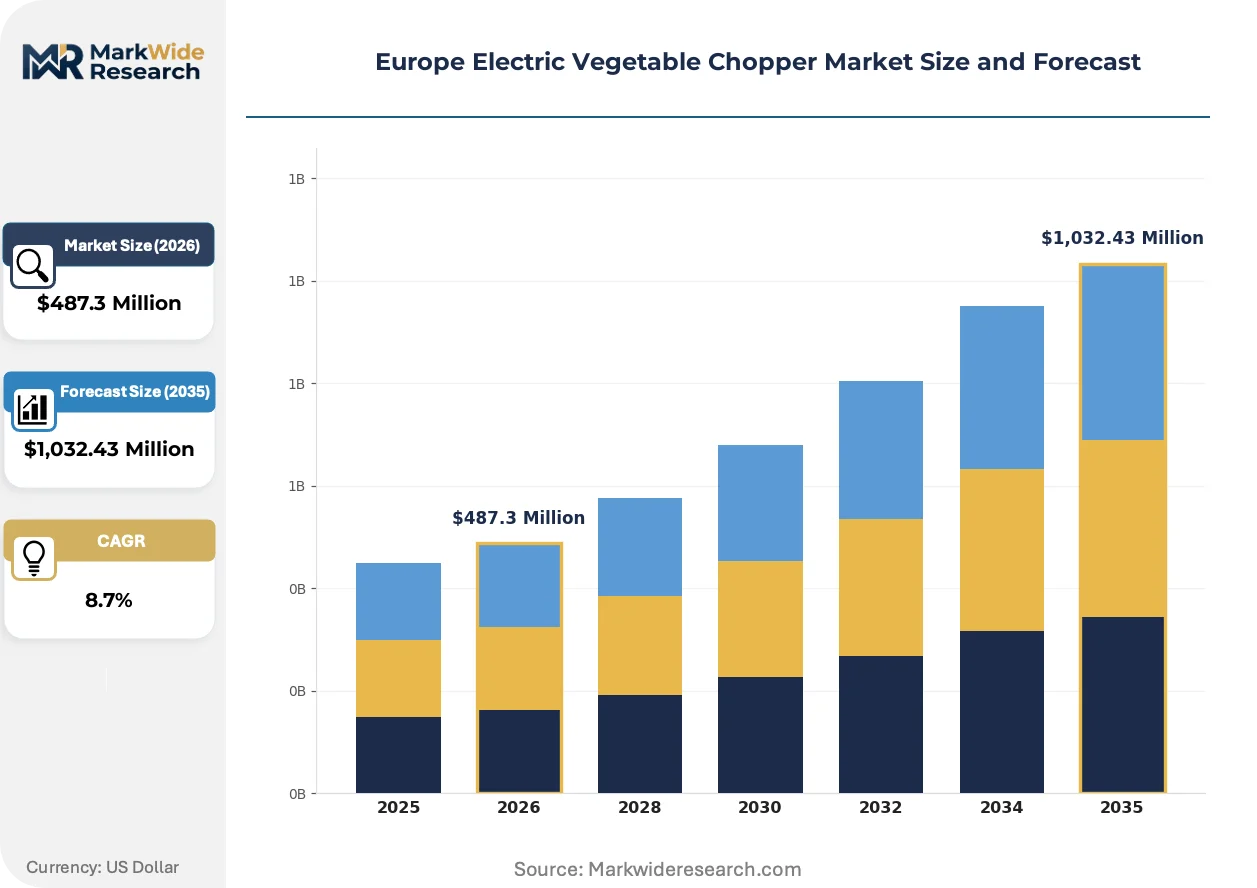
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld, Countertop, Multi-Function, Mini Power Rating: 100-300W, 301-500W, 501-700W, Above 700W Material: Plastic, Stainless Steel, Glass, BPA-Free End User: Households, Restaurants, Catering Services, Food Trucks |
| Companies Covered | Braun GmbH, SEVERIN Elektrogerate GmbH, Philips N.V., Kenwood, Bosch, Ninja, ADE, Prestige, Geepas, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Electric Vegetable Chopper Market Trends and Innovations
Material science advances and connectivity integration are reshaping competitive positioning across the European electric vegetable chopper landscape, with sustainability compliance and user experience convergence driving differentiation.
Brushless DC motor architectures are supplanting traditional universal motor designs in mid-premium countertop units. German and Austrian commercial kitchen operators are adopting these systems for reduced noise signatures and extended duty cycles. The technology is supplanting legacy motor suppliers in the 300W-500W power band, compressing maintenance revenue streams while enabling longer warranty terms as a competitive lever.
The EU Ecodesign Directive's 2025 energy efficiency thresholds are mandating standby power consumption below 0.5W and minimum active-mode efficiency ratings. Manufacturers are redesigning power supply units and motor control circuits to meet these specifications ahead of enforcement deadlines. Countertop multi-function units with heating or blending attachments face the steepest redesign costs, with Italian and Spanish producers accelerating compliance investments to avoid market exclusion.
Direct-to-consumer subscription models bundling blade replacement and descaling services are displacing traditional retail warranty structures. Urban millennials in Copenhagen, Stockholm, and Hamburg are adopting these plans for predictable maintenance costs and sustainability alignment. This shift is most visible in Benelux markets where Philips and established domestic brands have piloted integrated app-based service platforms with quarterly consumable deliveries.
Europe Electric Vegetable Chopper Market Segmentation
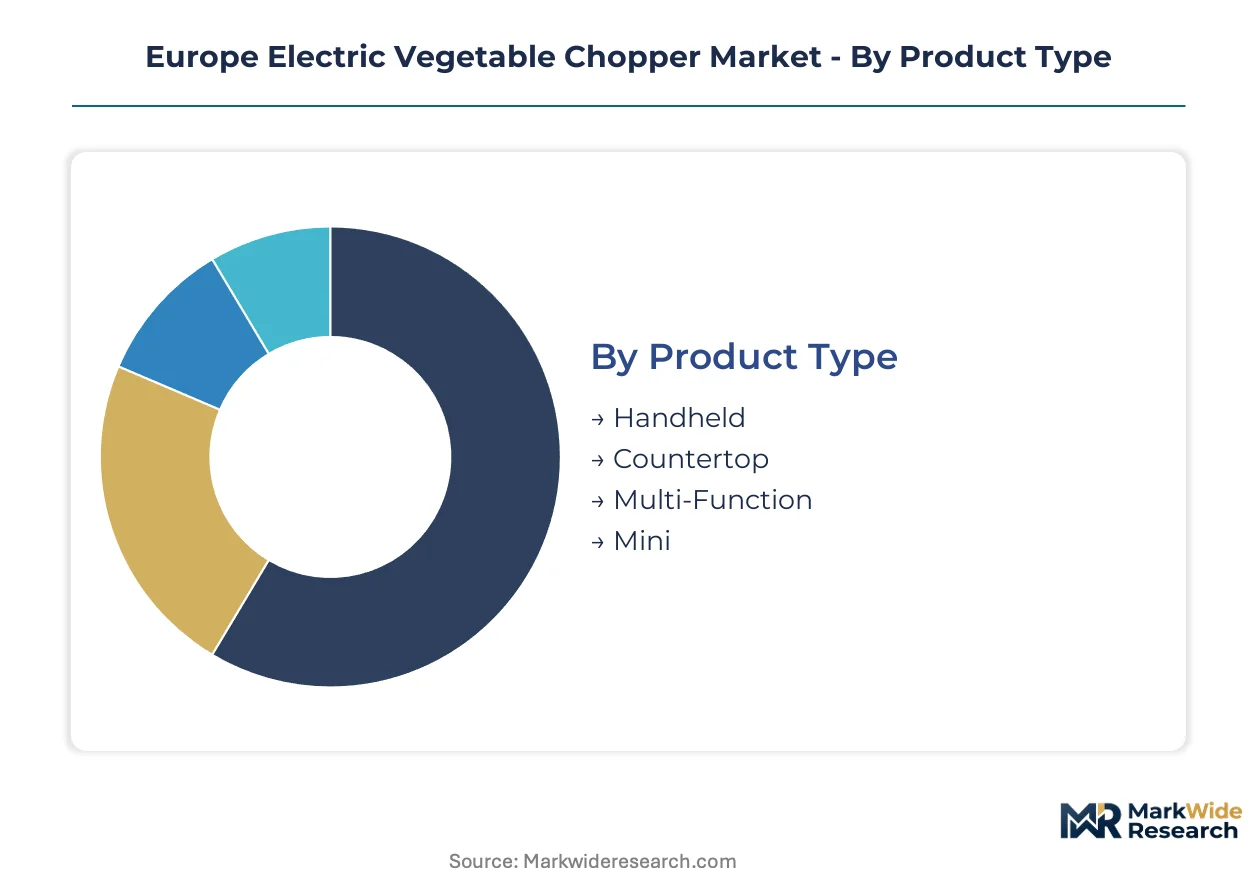
Segmentation in the Europe electric vegetable chopper market reveals divergent growth vectors across power classes and material specifications. Understanding these fault lines enables targeted positioning against REACH compliance costs and varying durability expectations across domestic and commercial use cases.
Product Type:
Domestic consumption concentrates in handheld and mini formats across Southern European rental markets, while export-oriented production from German and Polish facilities favors countertop and multi-function units bound for Benelux and Nordic retail networks.
- Handheld:Battery-operated or corded units with sub-300W motors and single-blade assemblies, optimized for intermittent use. Demand clusters in Barcelona, Milan, and Lisbon rental housing where storage constraints override power requirements. REACH substance restrictions on housing polymers compress margins for entry-price manufacturers sourcing from non-EU molders.
- Countertop:Stationary bases with 300W-700W induction motors and interchangeable bowl systems. German and Austrian households anchor volume, with commercial adoption spreading through Berlin and Paris ghost kitchens seeking labor reduction without ventilation infrastructure. CE marking complexity extends certification cycles for new launches.
- Multi-Function:Integrated chopping, blending, and heating modules requiring modular blade attachments. Premium positioning in Copenhagen and Stockholm reflects Nordic appetite for connected kitchen ecosystems.
- Mini:Compact single-serve units under 200W targeting solo-occupant urban apartments. Warsaw and Bucharest retail channels show underpenetrated expansion potential.
Countertop units command the established base. The steepest expansion runs through multi-function systems integrating smart kitchen connectivity.
Power Rating:
Cost tier stratification aligns with end-use intensity, with higher wattage segments capturing commercial margin premiums while lower bands compete on volume throughput in price-sensitive Southern markets.
- 100-300W:Entry-motor handheld and mini formats with brushed universal motor designs. Italian and Spanish domestic kitchens favor these units for occasional use, though cultural preference for manual cutting methods limits penetration depth.
- 301-500W:Mid-range countertop units with emerging brushless DC architectures. German commercial operators adopt these for reduced noise signatures in open-kitchen formats.
- 501-700W:Heavy-duty induction motor systems with thermal overload protection. French catering services and London delivery-only operations standardize here for continuous duty cycles. Copper and rare-earth magnet cost volatility squeezes mid-tier manufacturers without captive sourcing.
- Above 700W:Industrial-grade asynchronous motors for central prep facilities. Limited household penetration due to countertop footprint and energy consumption.
The 301-500W band captures the most rapid share gain. Above 700W systems remain confined to centralized food production.
Material:
Application context dictates material selection, with durability requirements in commercial settings overriding initial cost considerations that dominate household procurement.
- Plastic:ABS and polypropylene housings in entry-price handheld units. Ecodesign Directive pressure toward recyclable polymers accelerates R&D investment in bio-based alternatives across Italian supply chains.
- Stainless Steel:304 and 316 grade housings and blade assemblies for commercial durability. Restaurant and catering procurement in France and Germany specifies these grades for hygiene audit compliance. Margin premiums over plastic variants sustain specialized fabricators in Solingen and Sheffield.
- Glass:Borosilicate chopping bowls for chemical resistance and aesthetic positioning. Nordic markets show disproportionate adoption for sustainability alignment.
- BPA-Free:Tritan copolyester and other non-bisphenol thermoplastics mandated by ECHA restrictions. All segments face conversion pressure as substance restrictions tighten.
Stainless steel anchors commercial procurement standards. BPA-free materials are climbing the fastest as regulatory deadlines approach.
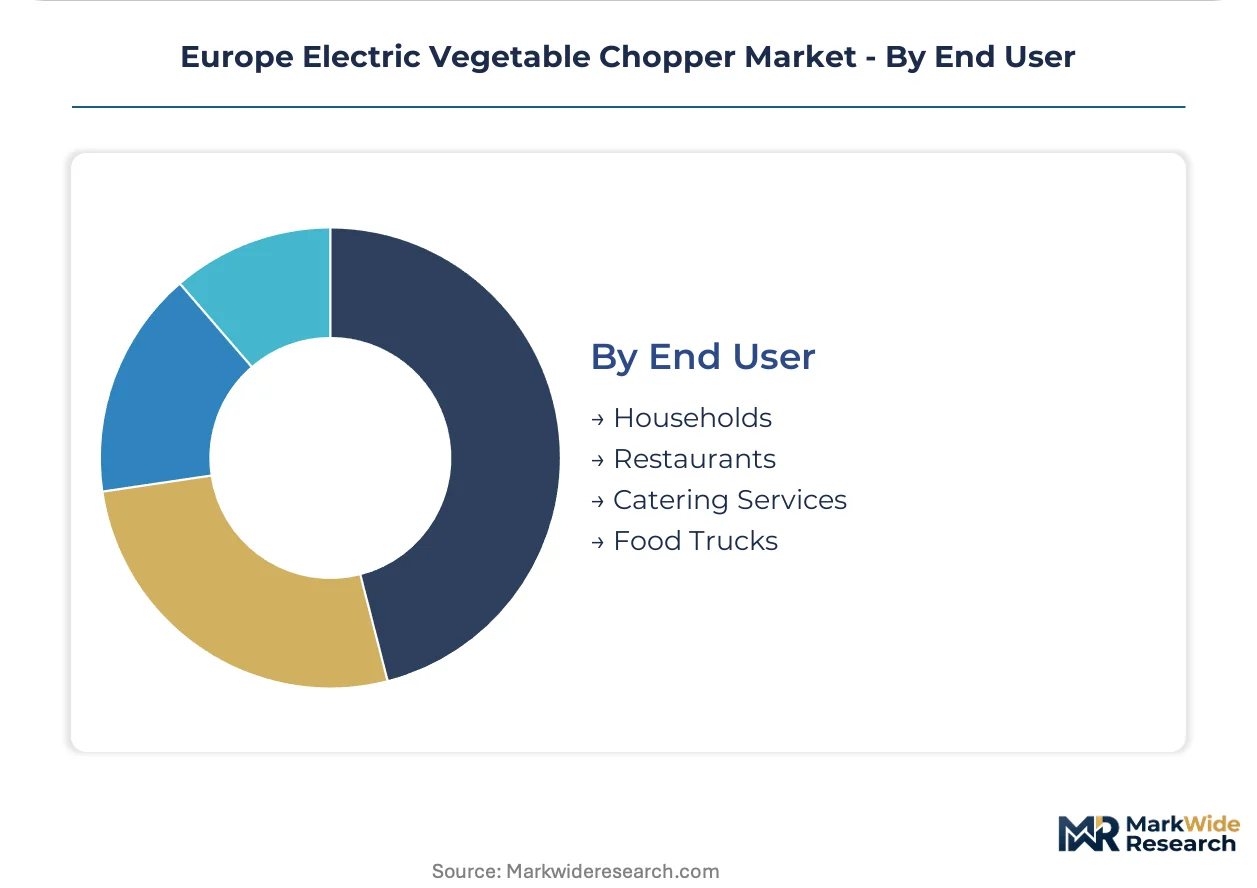
End User:
Customer type segmentation maps directly to performance tier and service infrastructure requirements, with commercial accounts demanding warranty terms and spare part availability that reshape manufacturer economics.
- Households:Individual and family units across urban and suburban geographies. Millennial tenants in Amsterdam and Hamburg drive subscription-model adoption for blade replacement services.
- Restaurants:Full-service and fast-casual operators with high-frequency daily use. Brussels and Vienna establishments prioritize noise reduction and compact footprint for front-of-house visibility.
- Catering Services:Event and institutional food providers with seasonal demand spikes. Polish and Romanian market entry targets this segment for equipment financing partnerships.
- Food Trucks:Mobile operators with severe power and space constraints. Battery-compatible 100-300W handheld units dominate, with solar charging integration emerging in Portuguese and Spanish coastal markets.
Households represent the volume foundation. Food trucks are gaining share fastest as mobile food service expands across Mediterranean urban centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German-speaking markets favor high-wattage countertop units with extended warranties, while Southern European households prefer entry-price handheld formats for intermittent use. This consumption-mix differential shapes inventory allocation and service infrastructure requirements across distribution networks.
Germany
Commercial ghost kitchens in Berlin and Hamburg drive demand for 301-500W brushless DC systems with noise-reduction engineering. The EU Ecodesign Directive's 2025 energy efficiency thresholds are accelerating power supply redesigns ahead of enforcement deadlines. Precision motor manufacturing clusters in Baden-Württemberg supply blade assembly components to countertop producers.
United Kingdom
London's delivery-only operations standardize multi-function units to compress prep labor in footprint-constrained facilities. REACH substance restrictions on blade coatings are forcing housing polymer conversions across UK-based molders. The Midlands manufacturing corridor hosts assembly facilities serving Benelux export channels.
France
Parisian fast-casual operators prioritize stainless steel grade 304 housings for front-of-house visibility and hygiene audit compliance. ECHA's evolving restrictions on BPA-containing thermoplastics are redirecting procurement toward Tritan copolyester alternatives. Lyon-based catering equipment distributors are expanding service networks into underpenetrated Romanian markets.
Italy
Domestic kitchens in Milan and Rome show persistent cultural attachment to manual cutting methods, limiting electric chopper penetration in price-sensitive segments. The EU Green Deal's extended producer responsibility requirements are pressuring manufacturers to establish take-back programs. Emilia-Romagna's appliance fabricators are piloting bio-based polymer R&D to meet recyclable component mandates.
Poland
Warsaw's modern trade channels remain underpenetrated, offering first-mover advantage for brands establishing localized service networks. National transposition timelines for the EU Machinery Directive's 2023 amendments are extending certification cycles for new entrants. The Silesian industrial basin hosts contract manufacturers producing entry-price handheld units for Southern European markets.
Europe Electric Vegetable Chopper Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with premium positioning sustained through motor engineering heritage and channel control rather than manufacturing scale alone. The competitive terrain divides between precision-motor specialists with deep R&D legacies and scale-oriented fabricators leveraging centralized production. Two dominant archetypes prevail: heritage engineering houses with electromagnetic design expertise, and volume manufacturers optimizing cost structures through captive sourcing arrangements. Competitive moves concentrate on geographic expansion into underpenetrated Central European retail networks and compliance-based differentiation through early REACH adaptation.
Among German-based engineering houses, Braun GmbH and SEVERIN Elektrogerate GmbH exemplify divergent strategic postures within the same national market. Braun occupies a position anchored in precision motor heritage, while SEVERIN represents scale-driven manufacturing concentration. Philips N.V., organized as a Dutch limited liability company, sits within the channel-control archetype through retail network penetration across Benelux and Nordic markets. These three entities collectively illustrate how geographic origin and corporate structure map to distinct competitive vectors in a market where technical specification and distribution reach operate as separable sources of advantage.
| Leading Market Players |
|---|
| Braun GmbH |
| SEVERIN Elektrogerate GmbH |
| Philips N.V. |
| Kenwood |
| Bosch |
| Ninja |
| ADE |
| Prestige |
| Geepas |
| Others |
Pricing and Supply Chain Analysis
Brushless DC motor architectures replacing brushed universal designs in mid-premium countertop units are simultaneously relocating sourcing patterns toward German and Austrian precision engineering clusters while compressing margin structures for manufacturers locked into legacy motor supply contracts.
Pricing Analysis
Long-term offtake agreements between countertop producers and copper winding suppliers dominate procurement structures across German and Polish assembly facilities. Three-tier pricing structure across premium, standard, and economy levels separates brushless DC-equipped units with extended warranties from entry-price handheld formats with sub-200W ratings. Cost compression in the 100-300W segment is intensifying because REACH compliance investments in BPA-free housing polymers fall disproportionately on entry-price manufacturers. Food truck operators and Southern European rental tenants exhibit the highest price sensitivity, while Parisian fast-casual establishments prioritize noise-reduction specifications over unit economics.
Supply Chain Analysis
Rare-earth magnet processing concentration in Chinese refining facilities creates single-source vulnerability for motor assembly inputs across European chopper manufacturers. Supply draws from German precision motor clusters, Polish contract assembly basins, and Chinese rare-earth processing infrastructure. Blade-grade stainless steel sourcing rests on Sheffield and Solingen metallurgical suppliers, with borosilicate glass bowl production concentrated in Czech and Slovak glassworks. Tariff exposure on Chinese-processed neodymium magnets threatens margin stability for mid-tier producers without captive sourcing arrangements. Distribution runs through Benelux retail networks and Nordic direct-to-consumer platforms with subscription service integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across EU member state transposition timelines creates white-space openings for specialists who can navigate multi-jurisdiction compliance faster than scale incumbents.
For Market Incumbents: Consolidate precision motor engineering capabilities through targeted hiring in Baden-Württemberg technical clusters to defend against brushless DC technology substitution threatening legacy universal motor product lines. Deepen channel control across Benelux retail networks before REACH substance restriction deadlines force simultaneous compliance investments that favor scale players with established reverse logistics infrastructure. For New Entrants and Emerging Players: After-sales blade replacement and descaling subscription gaps in Warsaw and Bucharest modern trade channels offer service-layer entry points where incumbents under-serve with traditional warranty structures. Target Polish catering services and Romanian food truck operators through equipment financing partnerships that incumbent scale players have not localized. Establish app-based service platforms with quarterly consumable deliveries mirroring Benelux pilot programs. For Investors and Strategic Acquirers: The market sits at a compliance-transition phase that favors mid-cap specialists with early REACH adaptation and established take-back program infrastructure. Five-to-ten year viability hinges on circular economy mandate navigation rather than manufacturing scale alone. Monitor ECHA substance review timelines as the critical inflection signal for margin compression or differentiation opening.| Strategic Initiative | Industry Significance |
|---|---|
| Brushless DC Motor Transition | Reduces noise signatures for Berlin ghost kitchens while extending warranty terms as competitive lever. |
| REACH Compliance Acceleration | Early BPA-free polymer conversion captures differentiation ahead of ECHA enforcement deadlines. |
| Take-Back Program Establishment | Creates competitive moat under EU Green Deal extended producer responsibility requirements. |
| Smart Kitchen Connectivity Integration | Bluetooth-enabled motor controls open premium positioning in Copenhagen and Stockholm connected ecosystems. |
| Central European Retail Expansion | Localized service networks in Warsaw and Bucharest exploit underpenetrated modern trade channels. |
Research Methodology
A standing panel of appliance engineering directors, category buyers at Benelux retail chains, ghost kitchen operations managers, and ECHA regulatory affairs specialists provided ongoing calibration across primary interview cycles. Secondary validation drew from EU Ecodesign Directive amendment filings, REACH substance restriction proposals, customs records for small-appliance imports, and SEC disclosures from listed parent companies of major chopper manufacturers. Bottom-up unit shipment estimates triangulated against top-down household appliance expenditure data from national statistical offices.
Consistency checks against external benchmarks validated volume and value outputs across the analysis window. The analytical framework modeled power rating tiers, material specifications, end-user segments, and regional adoption patterns throughout the forecast period. CAGRs derived from regression analysis of historical penetration rates against urban rental housing growth and food service labor cost indices. Industry-specific inputs included ECHA substance review timelines and national WEEE transposition schedules.
Forecasts assume regulatory continuity in EU Ecodesign and REACH enforcement regimes; material policy shifts would require re-modeling of compliance cost assumptions and product redesign timelines. Practitioners should keep alternative scenarios live as rare-earth magnet supply volatility and CE marking complexity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
Europe Built-In Coffee Machine Market
Kitchen Appliances
Cake Pans Market
Kitchen Appliances
Toast Maker Market
Kitchen Appliances
Electric Hobs Market
Kitchen Appliances
Outdoor Commercial Grills Market
Kitchen Appliances
Europe Air Fryers Market
Kitchen Appliances
Ceramic Coated Cookware Market
Kitchen Appliances
India Kitchen Appliances Market
Kitchen Appliances
Heavy Duty Mixer Grinder Market
Kitchen Appliances
Germany Kitchen Appliances Market
Kitchen Appliances
Middle East Electric Vegetable Chopper Market
Kitchen Appliances
Egg Boiler/Cooker Market
Kitchen Appliances
Italy Kitchen Appliances Market
Kitchen Appliances
Europe Kitchen Appliances Market
Kitchen Appliances
Capsule Coffee Machines Market
Kitchen Appliances
Electric Pizza Oven Market