
 US Food Hydrocolloids Market | 2026-2036
US Food Hydrocolloids Market Size, Share, and Industry Trends Forecast 2026-2036
US Food Hydrocolloids Market Analytics
Asset-light toll manufacturing and third-party fermentation leasing is reshaping competitive entry in US food hydrocolloids, lowering capital barriers for mid-tier producers. CP Kelco leverages captive biomass fermentation capacity to sustain kelp-derived alginate supply. Ingredion anchors its position through backward integration into waxy maize and tapioca starch streams. Tate & Lyle differentiates via specialty texturant portfolios targeting reduced-sugar bakery applications.
Food hydrocolloids comprise high-molecular-weight polysaccharides and proteins that hydrate in aqueous systems to modify rheology, typically functioning at concentrations between 0.1% and 2.0% by weight. These biopolymers serve primarily as viscosity builders, water binders, and phase stabilizers across formulated food matrices. Gums occupy the dominant value position due to premium pricing for locust bean and guar derivatives in clean-label applications. Xanthan gum represents the fastest-expanding product category, driven by gluten-free bakery and extended-shelf-life beverage demand. Starch-based hydrocolloids retain volume leadership but face margin compression from commodity pricing cycles.
FDA GRAS notification procedures and USDA organic certification requirements govern hydrocolloid deployment in US food systems, with the former dictating novel ingredient market access timelines. EPA effluent guidelines for fermentation facilities constrain brownfield expansion, particularly for xanthan and gellan gum production. State-level California Proposition 65 enforcement adds labeling complexity for certain seaweed-derived extracts. Stakeholders must monitor emerging FDA guidance on precision-fermented hydrocolloids and their regulatory classification relative to traditional extraction methods.
Market Dynamics
Clean-label formulation mandates from FDA and USDA are forcing hydrocolloid suppliers to abandon synthetic stabilizers in favor of minimally processed seaweed and plant-derived alternatives. This regulatory pivot is compressing traditional supply chains while elevating fermentation-based biopolymers.
Growth Catalysts
- Plant-based dairy acceleration:Oat, almond, and pea protein beverages require hydrocolloid stabilizers to prevent phase separation and deliver creamy mouthfeel. California's food technology corridor anchors formulation R&D for these applications.
- FDA GRAS self-determination pathways:Streamlined novel ingredient approvals are shortening time-to-market for precision-fermented hydrocolloids. This regulatory flexibility benefits startups developing next-generation texturants.
- Gluten-free bakery expansion:Xanthan gum and hydroxypropyl methylcellulose replace gluten's viscoelastic properties in bread and pastry systems. Midwest processing facilities scale these specialty ingredients for national distribution.
Market Restraints
- Seaweed supply concentration:Carrageenan and alginate raw material dependence on Southeast Asian harvesting regions exposes processors to climate volatility and trade friction.
- EPA effluent constraints:Fermentation facility wastewater discharge limits restrict brownfield capacity expansion for xanthan and gellan gum production in legacy manufacturing zones.
- Commodity starch margin compression:Waxy maize and tapioca price cycles erode profitability for modified starch hydrocolloids against premium-priced gum alternatives.
Strategic Opportunities
- Precision fermentation scale-up:Biosynthetic collagen and elastin alternatives target clean-label meat analog applications. Third-party fermentation leasing lowers capital barriers for mid-tier entrants.
- California Proposition 65 compliance services:Seaweed extract heavy metal testing and labeling support creates adjacent revenue streams for analytical laboratories serving hydrocolloid importers.
- Reduced-sugar bakery texturants:Specialty hydrocolloid blends restore structural integrity and moisture retention in low-calorie formulations. Tate & Lyle's portfolio addresses this functional gap.
Industry Challenges
- Fermentation talent scarcity:Industrial microbiology and downstream processing expertise concentrates in pharmaceutical biologics, creating recruitment competition for food-grade biopolymer facilities.
- Organic certification timelines:USDA National Organic Program compliance for hydrocolloid supply chains extends 18-24 months, delaying premium positioning for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Food Hydrocolloids Market |
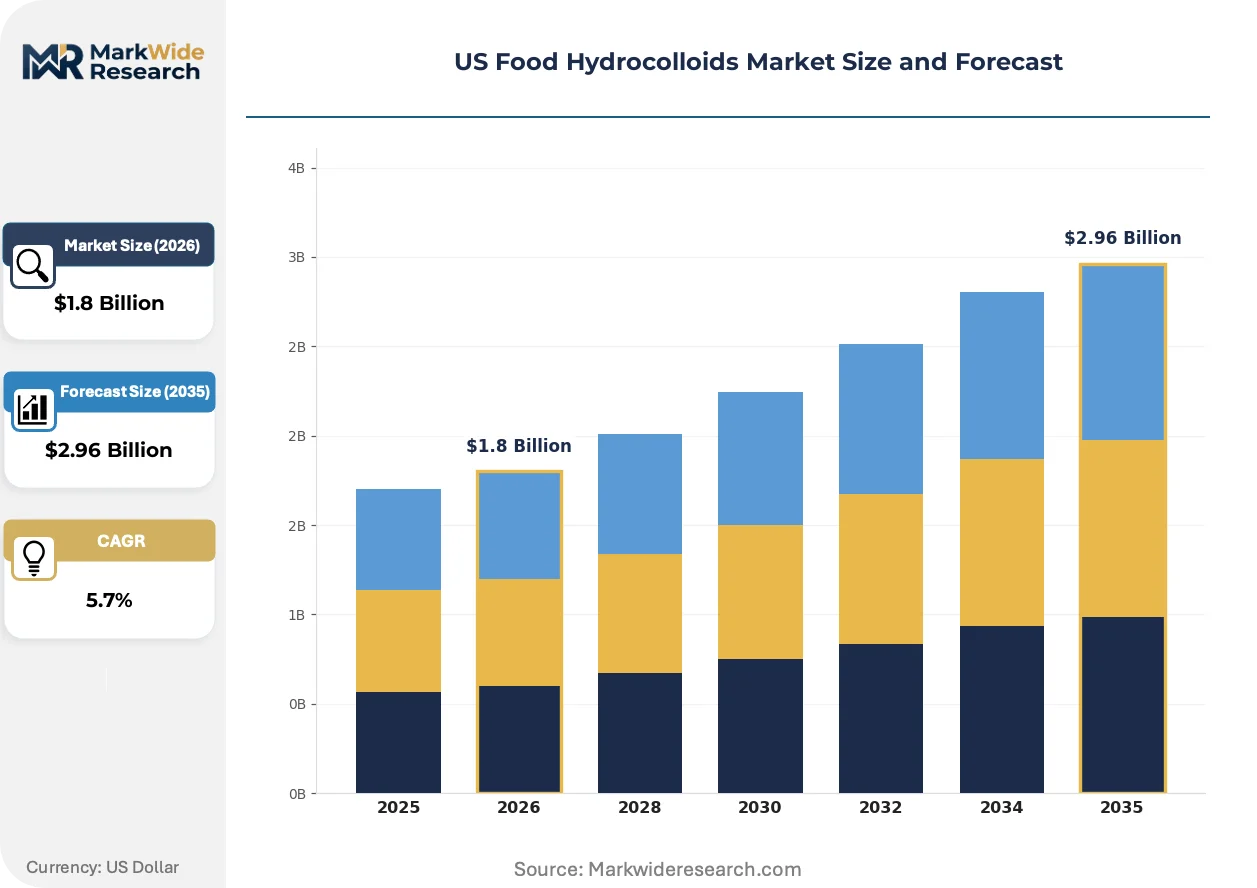
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gums, Pectins, Starches, Xanthan Gum Application: Dairy Products, Sauces, Bakery, Beverages End User: Food Manufacturers, Restaurants, Retailers, Consumers Functionality: Thickening Agent, Stabilizer, Emulsifier, Gelling Agent |
| Companies Covered | Archer Daniels Midland Company, Ingredion, CP Kelco, Darling Ingredients, Tate & Lyle, Cargill, DuPont de Nemours, J.M. Huber Corporation, Ashland, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Food Hydrocolloids Market Evolving Landscape
Bioprocess engineering advances are collapsing cost curves for fermentation-derived hydrocolloids while digital formulation tools compress development cycles. These shifts are redistributing competitive advantage toward technology-integrated suppliers.
Precision fermentation is collapsing the traditional extraction economics of seaweed and plant-derived hydrocolloids. Startups in California's food technology corridor deploy biosynthetic platforms to produce collagen, elastin, and polysaccharide mimics at commercial scale. Bakery and alternative protein manufacturers adopt these ingredients within 12-18 month qualification windows, compressing supplier selection timelines and favoring agile biotech entrants over legacy extractors.
USDA organic certification requirements and FDA guidance on precision-fermented ingredients are creating dual-track compliance frameworks. Hydrocolloid suppliers must maintain parallel documentation for extraction-based and biomanufactured product lines. The organic segment faces the strictest documentation burden, with certifiers demanding full supply chain segregation and non-GMO verification for fermentation feedstocks.
Direct supplier relationships with co-manufacturers are displacing traditional distributor intermediaries in hydrocolloid procurement. Large food brands in the Midwest processing belt negotiate toll manufacturing agreements that embed technical service and application development. This channel compression is most pronounced in plant-based dairy, where formulation complexity demands embedded R&D support rather than commodity trading relationships.
US Food Hydrocolloids Market Segmentation
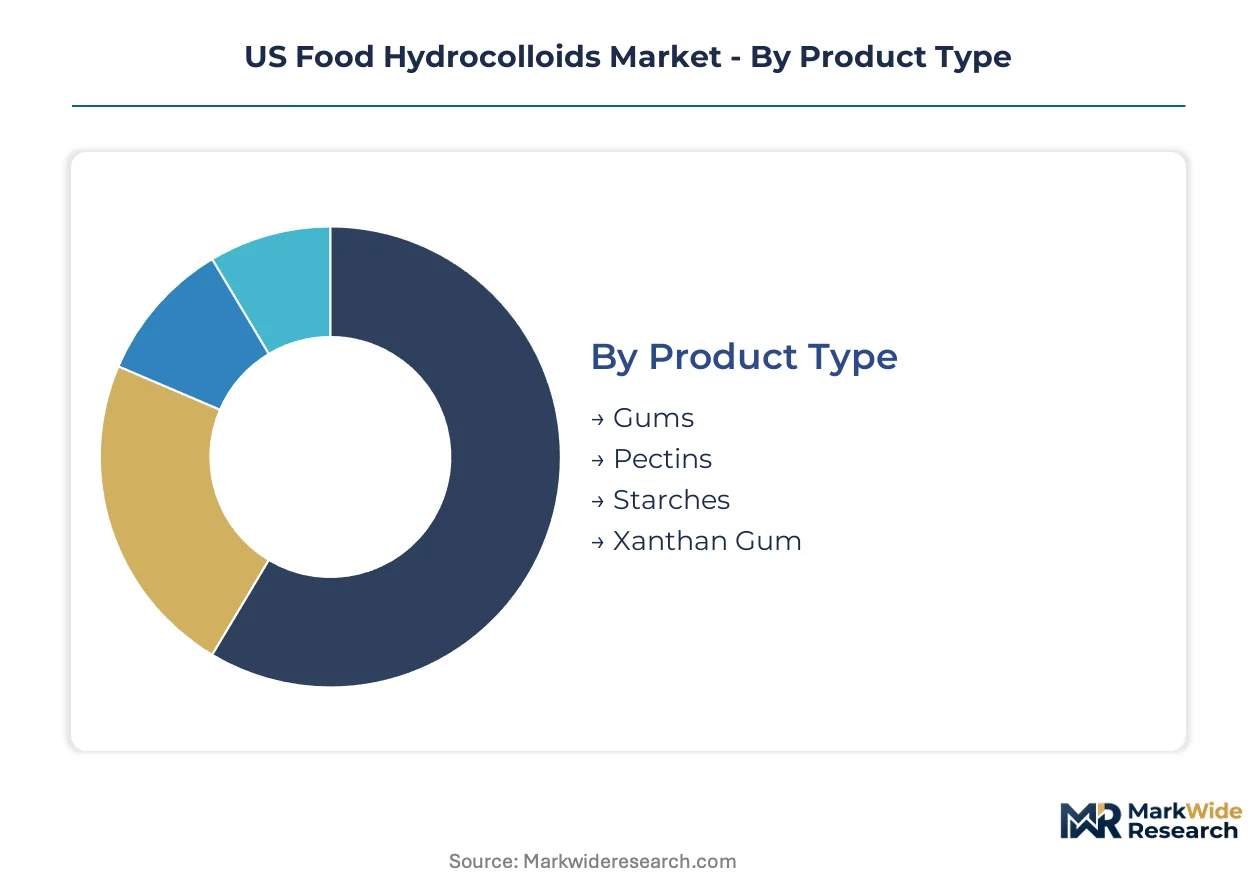
US food hydrocolloids demand fragments across four distinct segmentation axes. Product type determines raw material sourcing strategies and margin profiles. Application specificity drives formulation complexity and technical service requirements. End-user channel dictates procurement scale and relationship structures. Functional role shapes competitive positioning against synthetic alternatives.
Product Type:
Cost tier differentiation separates premium fermentation-derived biopolymers from commodity extraction-based alternatives.
- Gums:High-molecular-weight polysaccharides from seaweed and plant exudates command premium positioning in clean-label applications. Locust bean and guar derivatives concentrate demand in California's plant-based dairy formulation labs where texture modulation justifies ingredient cost.
- Xanthan Gum:Microbial fermentation of Xanthomonas campestris produces this anionic polysaccharide with exceptional shear-thinning rheology. Gluten-free bakery applications in Midwest processing facilities absorb expanding output as wheat alternatives proliferate.
- Pectins:Citrus peel and apple pomace extraction yields these galacturonic acid polymers for high-solids gel systems.
- Starches:Waxy maize and tapioca modification dominates volume throughput despite margin compression from commodity pricing cycles.
Gums hold installed capacity. Xanthan gum is rotating up the share rankings.
Application:
Volume concentration varies dramatically by formulation complexity and shelf-life requirements across food matrices.
- Dairy Products:Plant-based oat, almond, and pea protein beverages require hydrocolloid stabilizers to prevent phase separation and deliver creamy mouthfeel. California's food technology corridor anchors R&D for these applications as clean-label mandates intensify.
- Bakery:Gluten-free bread and pastry systems replace wheat viscoelasticity with xanthan gum and hydroxypropyl methylcellulose. Midwest co-manufacturing facilities scale these specialty ingredients for national distribution networks.
- Beverages:Extended-shelf-life formulations demand suspension stability in pulp-containing and protein-fortified drinks.
- Sauces:Emulsion stability and pour viscosity control dominate functional requirements in pourable and spoonable formats.
Dairy applications absorb the most technical service resources. Bakery is climbing the fastest as gluten-free penetration deepens.
End User:
Customer type determines procurement scale, technical support intensity, and contract structure preferences.
- Food Manufacturers:Large-scale processors in the Midwest belt negotiate direct supplier relationships embedding application development and toll manufacturing agreements. Plant-based dairy complexity demands embedded R&D support rather than commodity trading.
- Restaurants:Foodservice operators prioritize consistent hydration performance and simplified inventory through blended hydrocolloid systems.
- Retailers:Private-label brands drive specification standardization and dual-sourcing requirements for supply security.
- Consumers:Direct purchasing remains minimal, concentrated in specialty baking and molecular gastronomy enthusiast segments.
Food manufacturers hold installed capacity. Restaurants are gaining share fastest as prepared sauce and beverage concentrate adoption accelerates.
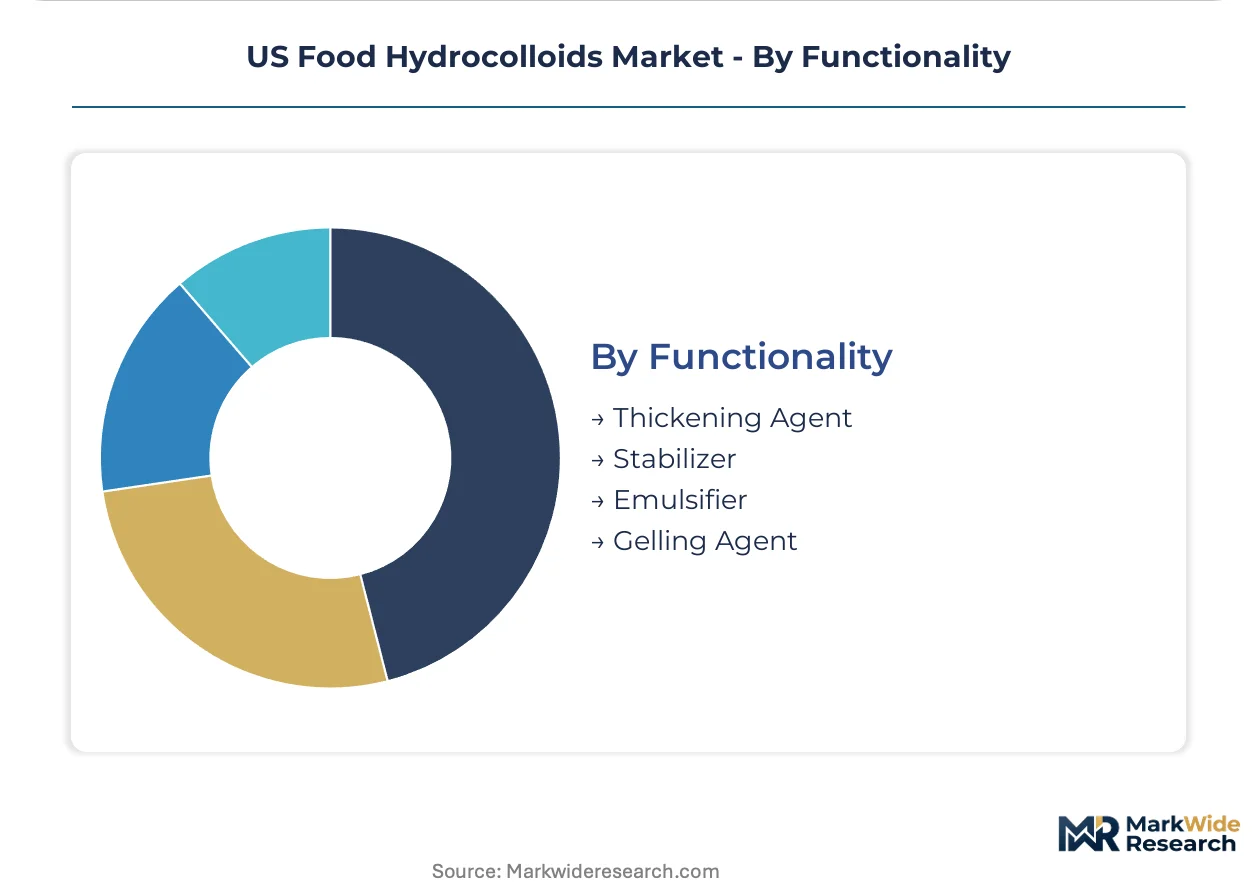
Functionality:
Functional role shapes competitive dynamics against synthetic stabilizers and determines regulatory scrutiny intensity.
- Stabilizer:Phase separation prevention in emulsions and suspensions represents the highest-value functional application. FDA clean-label guidance is forcing abandonment of synthetic alternatives in favor of minimally processed seaweed and plant-derived options.
- Thickening Agent:Viscosity building at low concentrations defines performance in pourable sauces and beverage systems. Cost-pressure from modified starch alternatives constrains pricing power in commodity segments.
- Gelling Agent:Thermoreversible and thermoirreversible gel networks structure water and oil phases in confectionery and dessert applications.
- Emulsifier:Surface-active hydrocolloids reduce interfacial tension in oil-water systems where synthetic lecithin alternatives face clean-label displacement.
Stabilizer functionality holds installed capacity. Emulsifier applications are rotating up the share rankings as label-friendly alternatives to synthetic surfactants proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in food hydrocolloids reveal a net import dependence for specialty gums alongside robust domestic fermentation capacity. The United States sources significant alginate and carrageenan feedstocks from overseas harvesting regions while maintaining xanthan gum production leadership. Regional demand concentrates in coastal formulation hubs and Midwest processing corridors.
California
Plant-based dairy innovation drives hydrocolloid consumption across oat, almond, and pea protein beverage applications. FDA GRAS self-determination pathways accelerate novel ingredient approvals for precision-fermented texturants developed in San Francisco and Los Angeles food technology clusters. The state's Proposition 65 enforcement creates labeling complexity for seaweed-derived extracts imported through Long Beach and Oakland ports.
Midwest Processing Belt
Gluten-free bakery expansion absorbs expanding xanthan gum and hydroxypropyl methylcellulose volumes across Illinois, Michigan, and Ohio co-manufacturing facilities. USDA organic certification requirements extend supply chain timelines for regional starch processors seeking premium positioning. Chicago anchors distribution networks linking fermentation facilities to national retail and foodservice channels.
Texas Gulf Coast
Petrochemical adjacency supports specialty cellulose derivative production for food-grade applications. EPA effluent guidelines constrain brownfield expansion for fermentation-based hydrocolloid manufacturing in legacy chemical processing zones. Houston serves as an import gateway for Latin American tapioca starch feedstocks.
Northeast Corridor
Precision fermentation startups concentrate in Greater Boston and New York Metro biotech corridors. FDA guidance on novel biomanufactured ingredients shapes regulatory strategy for collagen and elastin alternative developers. Philadelphia and Baltimore harbor facilities handle carrageenan imports for regional dairy processors.
Pacific Northwest
Kelp cultivation initiatives in Washington and Oregon explore domestic alginate sourcing alternatives to Southeast Asian imports. State-level environmental review processes extend permitting timelines for seaweed processing infrastructure. Seattle anchors clean-label formulation R&D for Pacific Rim export markets.
US Food Hydrocolloids Market Competitive Landscape
On the supply side, the industry is consolidating around three structural tiers: integrated agricultural processors, specialized fermentation operators, and toll manufacturing platforms. Large-scale starch and protein conglomerates control upstream feedstock access. Niche biopolymer specialists leverage captive fermentation technology. Asset-light service providers fill capacity gaps for mid-tier brands. Dominant competitive moves include backward integration into raw material streams and strategic partnerships embedding technical service capabilities.
Among integrated agricultural processors, Archer Daniels Midland Company and Cargill exemplify scale-driven feedstock dominance through captive corn and tapioca supply chains. Ingredion occupies a position within the specialty texturant tier, representing backward integration into waxy maize streams. CP Kelco anchors the fermentation-specialist segment, exemplifying kelp-derived biopolymer production through captive biomass capacity. Tate & Lyle sits within the premium application tier, representing reduced-sugar bakery formulation expertise.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Ingredion |
| CP Kelco |
| Darling Ingredients |
| Tate & Lyle |
| Cargill |
| DuPont de Nemours |
| J.M. Huber Corporation |
| Ashland |
| Others |
Value Network & Pricing Analysis
Undercapacity in domestic alginate extraction capacity drives suppliers toward premium positioning for seaweed-derived gums while forcing fermentation-based alternatives into cost-competitive slots. This utilization imbalance rewards CP Kelco's captive kelp processing with pricing power while compressing margins for modified starch processors competing on commodity cycles.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that lock in volume commitments against raw material volatility. Price differentiation rests on USDA organic certification tier and vertical integration depth, with fully integrated processors commanding premiums over toll-dependent competitors. Cost compression in modified starches is intensifying because tapioca and waxy maize price cycles erode profitability against gum alternatives. Food manufacturers with direct supplier relationships exhibit lowest price sensitivity, while restaurants and foodservice operators buying blended systems show highest elasticity.
Supply Chain Analysis
Tariff exposure between Southeast Asian harvesting regions and US West Coast ports dominates supply chain risk calculus for carrageenan and alginate feedstocks. Raw material sourcing draws from Indonesian seaweed farms, Philippine carrageenan processors, and domestic fermentation facilities in Illinois and California. Single-source vulnerability concentrates in Southeast Asian alginate supply, with climate volatility and trade friction threatening continuity. Distribution runs through Chicago-based national networks linking Midwest co-manufacturing to coastal formulation hubs, with direct supplier relationships displacing traditional distributor intermediaries in plant-based dairy procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among large food manufacturers negotiating embedded R&D support, fragmenting pricing leverage across mid-tier brands unable to secure direct supplier relationships.
For Market Incumbents: Pre-empt precision fermentation scale-up by securing toll manufacturing partnerships with California biotech clusters before capacity constraints harden. Defend margin position through backward integration into waxy maize and tapioca starch streams, mirroring Ingredion's feedstock control. Channel control over Midwest co-manufacturing facilities represents the priority defensive lever against emerging biosynthetic collagen alternatives. For New Entrants and Emerging Players: Reduced-sugar bakery texturants in Midwest processing facilities represent the most penetrable entry point, with Tate & Lyle's portfolio gap indicating unmet functional demand. Third-party fermentation leasing in California's food technology corridor lowers capital barriers for precision-fermented hydrocolloid development. Go-to-market execution should embed technical service capabilities within toll manufacturing agreements rather than commodity trading relationships. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among fermentation-specialist platforms with captive biomass capacity and long-term supply contracts to plant-based dairy formulators. Long-term viability over the next decade hinges on regulatory navigation of FDA precision-fermentation guidance and USDA organic certification timelines. Acquisition target archetype: mid-tier biopolymer specialists with California Proposition 65 compliance infrastructure and embedded R&D service models. The signal to watch is EPA effluent guideline enforcement intensity constraining brownfield fermentation expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Starch Feedstocks | Ingredion's waxy maize control secures margin insulation against commodity pricing cycles. |
| Precision Fermentation Scale-Up | CP Kelco's captive biomass capacity sustains kelp-derived alginate supply dominance. |
| Third-Party Fermentation Leasing | Asset-light toll manufacturing lowers capital barriers for mid-tier biopolymer entrants. |
| California Proposition 65 Compliance Services | Seaweed extract heavy metal testing creates adjacent revenue for analytical laboratories. |
| Direct Supplier Relationship Embedding | Midwest food manufacturers negotiate technical service integration replacing distributor intermediaries. |
Research Methodology
Initial hypotheses were tested against primary input from hydrocolloid procurement managers at Midwest food manufacturers, fermentation facility operations directors, California formulation R&D leads, and USDA organic certification specialists, then refined through secondary validation. Bottom-up triangulation combined FDA GRAS notification databases, EPA effluent compliance records, SEC 10-K filings from integrated agricultural processors, and customs trade data on Southeast Asian seaweed imports. Top-down cross-checks applied macro consumption patterns across plant-based dairy and gluten-free bakery categories.
Demand-supply balance framing anchored the analytical approach across the analysis window, modeling volume and value outputs through product type, application specificity, end-user channel, and functional role segmentation dimensions. CAGRs were derived from iterative reconciliation of bottom-up capacity expansion plans and top-down category consumption elasticity. Industry-specific forecast inputs incorporated EPA effluent constraint scenarios and FDA guidance timelines on precision-fermented ingredient classification.
Macroeconomic conditions sit as an overlay; deviation in agricultural commodity price cycles, trade policy friction with Southeast Asian suppliers, or fermentation feedstock cost volatility would shift the trajectory. Forecasts reflect documented assumptions on regulatory approval timelines and organic certification throughput. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Components and Additives
North America Food Antimicrobial and Antioxidants Market
Food Components and Additives
Brazil Food Hydrocolloids Market
Food Components and Additives
Edible Films and Coating Market
Food Components and Additives
Europe Fat Replacers Market
Food Components and Additives
Edible Oil Co-Products and by-Products Market
Food Components and Additives
Soybean by-Products Market
Food Components and Additives
Horseradish Peroxidase Market
Food Components and Additives
Polydextrose Market
Food Components and Additives
Modified Starch Market
Food Components and Additives
Canada Food Hydrocolloids Market
Food Components and Additives
Europe Food Preservatives Market
Food Components and Additives
Japan Food Hydrocolloids Market
Food Components and Additives
France Food Preservatives Market
Food Components and Additives
Argentina Food Hydrocolloids Market
Food Components and Additives
Food Grade Antifoams Market
Food Components and Additives
Food Grade Polyvinyl Acetate Market