
 Malaysia Data Center Cooling Market | 2026-2036
Malaysia Data Center Cooling Market Size, Share, and Industry Trends Forecast 2026-2036
Malaysia Data Center Cooling Market Insights
Tier-III and Tier-IV reliability specifications is rotating toward dominance as hyperscale operators demand uninterrupted thermal management. Schneider Electric SE anchors its position through integrated power and cooling architectures across Greater Kuala Lumpur deployments. Vertiv Group Corp competes with precision air conditioning systems designed for tropical humidity loads. Huawei Digital Power Technologies Co Ltd leverages liquid-cooled rack solutions tailored to high-density GPU clusters.
Data center cooling encompasses mechanical and thermal systems engineered to maintain ambient temperatures between 18°C and 27°C with humidity control, utilizing refrigerants, chilled water loops, or direct liquid contact with server components to prevent thermal throttling and hardware degradation. Liquid cooling configurations are capturing margin pools as AI training workloads push rack densities past 30 kW per cabinet. Chilled water systems still dominate legacy enterprise facilities, though evaporative cooling variants gain traction in Malaysia's equatorial climate where wet-bulb temperatures favor adiabatic approaches. Cloud service providers and telecommunications operators represent the fastest-growing end-user cohorts, with colocation and hybrid deployment models absorbing the majority of new cooling capacity installations.
Malaysia's Green Building Index and the Sustainable Energy Development Authority's building energy efficiency codes shape equipment selection by mandating minimum energy performance thresholds for mechanical cooling systems. The Department of Standards Malaysia enforces MS 1525 compliance for building energy efficiency, directly influencing chiller and air handler specifications. Stakeholders must monitor how Putrajaya's renewable energy tariff structures and carbon disclosure requirements for data center operators will reshape total cost-of-ownership calculations for cooling infrastructure investments.
Market Dynamics
Hyperscale cloud operators are compressing deployment timelines for Tier-III and Tier-IV facilities across Johor and Selangor, forcing cooling infrastructure procurement to synchronize with 18-to-24-month data center construction cycles rather than traditional equipment replacement schedules.
Growth Catalysts
- Green Building Index mandates:Malaysia's certification framework requires minimum energy performance thresholds for mechanical cooling systems in new commercial buildings, directly accelerating chiller and air handler upgrades in data center developments.
- AI training workload density:GPU clusters exceeding 30 kW per cabinet are proliferating in Iskandar Malaysia, creating immediate demand for liquid-cooled rack architectures that conventional precision air conditioning cannot support.
- Johor-Selangor corridor concentration:Cloud service providers are anchoring capacity expansions in the Klang Valley and Iskandar zones, concentrating procurement volumes that justify localized supply chain investments by cooling equipment vendors.
Market Restraints
- Refrigerant cost volatility:Hydrofluorocarbon phase-down schedules under the Kigali Amendment are compressing supply availability for conventional chillers, inflating replacement part costs for legacy facilities in Penang and Kuala Lumpur.
- Specialized contractor scarcity:Malaysia's pool of technicians certified for direct liquid cooling installation and maintenance remains shallow relative to deployment timelines, extending commissioning periods for high-density racks.
- Grid interconnection delays:Tenaga Nasional Berhad's queue for new substations in Cyberjaya and Nusajaya stretches 24 to 36 months, freezing cooling capacity expansion until power infrastructure catches demand.
Strategic Opportunities
- Evaporative cooling in equatorial climates:Adiabatic and wet-bulb-dependent designs are capturing efficiency advantages in Malaysia's high-humidity environment where wet-bulb temperatures favor water-based heat rejection over mechanical refrigeration cycles.
- Sustainable Energy Development Authority incentives:Building energy efficiency codes administered by SEDA Malaysia offer accelerated depreciation for high-efficiency cooling equipment, improving project IRRs for colocation operators.
- East Malaysia latency arbitrage:Kota Kinabalu and Kuching remain undersupplied relative to West Malaysia demand density, creating first-mover positioning for cooling infrastructure targeting disaster recovery and content distribution nodes.
Industry Challenges
- Thermal-fluid engineering talent gap:Direct-to-chip and immersion cooling deployments require expertise in dielectric fluid chemistry and two-phase heat transfer that Malaysia's vocational pipeline has not yet scaled to match deployment velocity.
- MS 1525 compliance integration:The Department of Standards Malaysia's building energy efficiency standard mandates documentation workflows that extend equipment specification cycles by 8 to 12 weeks, compressing installation windows for time-bound facility launches.
- Legacy chilled water retrofit complexity:Enterprise facilities built on 1990s-era central plant architectures face structural constraints—pipe sizing, floor loading, and spatial clearance—that obstruct direct replacement with modular in-row cooling units.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Malaysia Data Center Cooling Market |
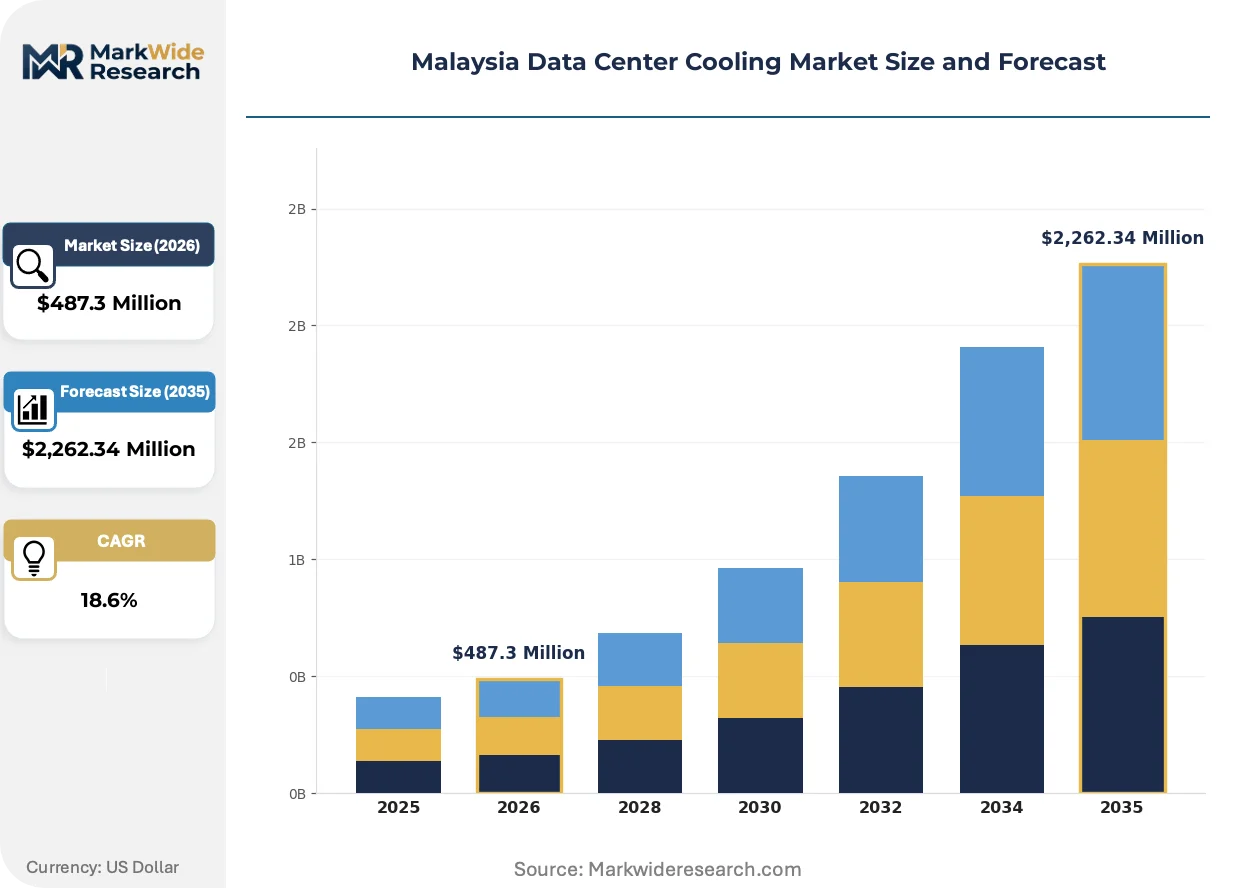
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $2,262.34 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Cooling Type: Chilled Water, Direct Expansion, Evaporative Cooling, Liquid Cooling End User: Telecommunications, Cloud Service Providers, Financial Institutions, Enterprises Product Type: CRAC Units, CRAH Units, Cooling Towers, Air Handlers Deployment Model: On-Premises, Managed Services, Hybrid, Colocation |
| Companies Covered | Schneider Electric SE, Vertiv Group Corp, Johnson Controls Inc, Rittal GmbH & Co. KG, Carrier Global Corporation, Eaton Corporation PLC, Huawei Digital Power Technologies Co Ltd, Right Power Technology Sdn Bhd, GIGA-BYTE Technology Co Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Malaysia Data Center Cooling Market Trends and Innovations
Liquid cooling architectures are compressing the technology adoption cycle from niche HPC deployments to mainstream AI infrastructure, while regulatory pressure on energy efficiency and water usage reshapes equipment specification priorities across Malaysian data center developments.
Direct-to-chip liquid cooling is displacing conventional raised-floor precision air conditioning in high-density racks. Hyperscale operators in Cyberjaya and Nusajaya are specifying cold-plate systems for GPU clusters above 25 kW per cabinet, with deployment timelines compressing from 18 months to 9 months. This transition is displacing margin pools historically captured by CRAC unit manufacturers and redirecting procurement toward thermal-fluid engineering specialists.
Malaysia's Green Building Index and SEDA's building energy efficiency codes are tightening operational efficiency thresholds for mechanical cooling systems. The regulations now mandate minimum coefficient-of-performance ratings for chillers above 500 kW capacity, with compliance documentation required for certificate of completion issuance. Colocation operators in the Klang Valley are responding by pre-specifying magnetic-bearing chillers and variable-primary chilled water loops to secure GBI Gold certification.
Cloud service providers are consolidating cooling infrastructure procurement under master service agreements with integrated power and thermal vendors. This pattern concentrates specification authority with hyperscale engineering teams rather than distributing decisions across general contractors and MEP consultants. The shift is most visible in Johor's Iskandar Puteri zone, where Meta and Microsoft direct-award contracts are compressing vendor qualification cycles and unbundling traditional equipment distributor margins.
Malaysia Data Center Cooling Market Segmentation
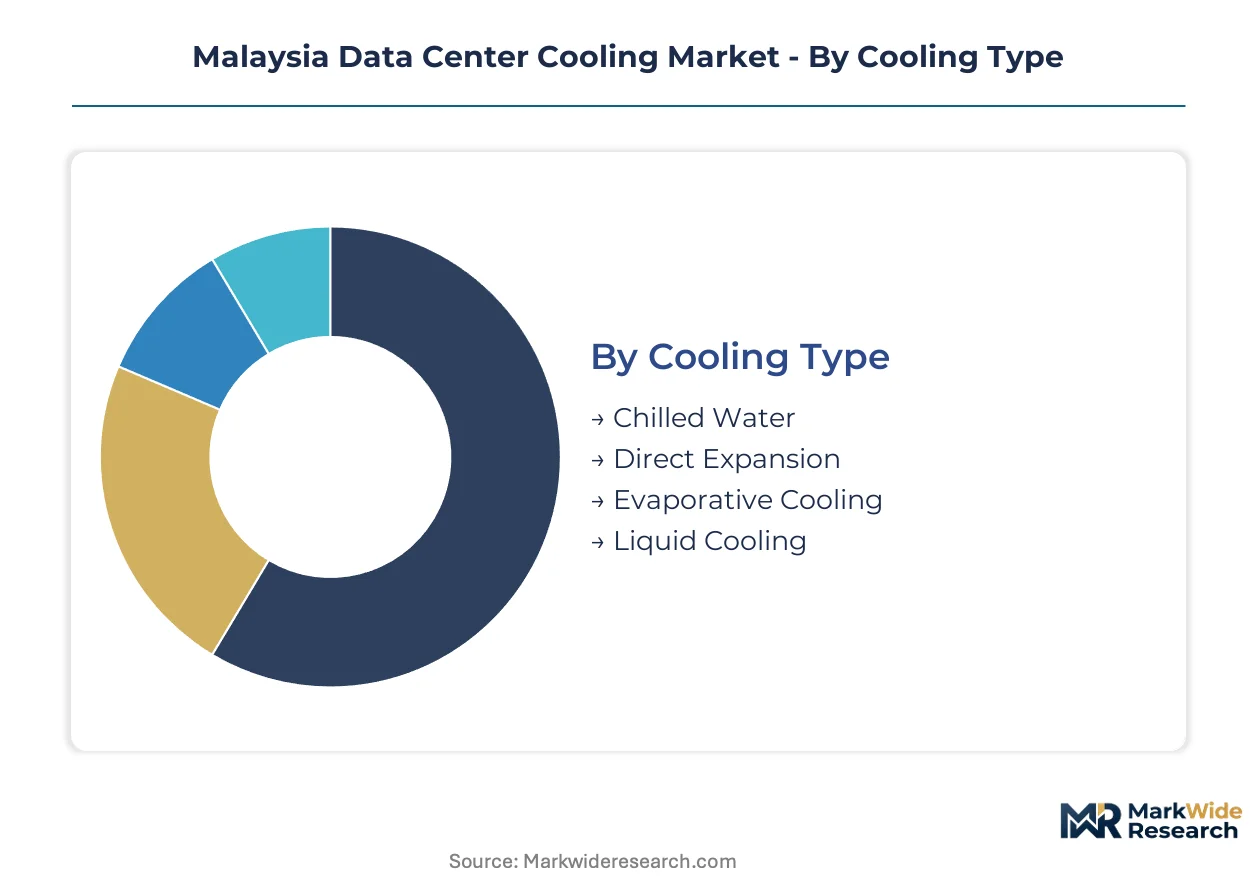
Cooling technology selection in Malaysia's data center market hinges on rack density requirements, tropical humidity conditions, and compliance with the Green Building Index. Segmentation reveals how procurement patterns diverge between legacy enterprise facilities in Kuala Lumpur and hyperscale deployments in Johor.
Cooling Type:
Domestic demand concentrates in technologies adapted to Malaysia's equatorial climate, while liquid cooling imports scale with AI infrastructure investments.
- Liquid Cooling:Direct-to-chip and immersion configurations handle GPU clusters exceeding 30 kW per cabinet. Cloud operators in Iskandar Malaysia specify cold-plate systems for AI training workloads that conventional air conditioning cannot support.
- Chilled Water:Central plant architectures with magnetic-bearing chillers dominate legacy Tier-II and Tier-III facilities. The Klang Valley corridor retains installed base advantages, though retrofit complexity obstructs efficiency upgrades in 1990s-era buildings.
- Evaporative Cooling:Adiabatic designs exploit Malaysia's high wet-bulb temperatures to reduce mechanical refrigeration cycles. SEDA Malaysia incentives accelerate specification for new colocation builds seeking operational cost advantages.
- Direct Expansion:DX precision air conditioning serves smaller enterprise data centers with sub-500 kW loads. Penang and Cyberjaya deployments favor these units for rapid commissioning without chilled water infrastructure.
Chilled water holds the largest share; momentum sits with liquid cooling.
End User:
Customer concentration varies by deployment scale, with hyperscale operators driving specification authority and enterprises following procurement cycles.
- Cloud Service Providers:Meta, Microsoft, and regional hyperscalers anchor capacity expansions in Johor and Selangor. These operators compress vendor qualification cycles and consolidate cooling procurement under master service agreements.
- Telecommunications:Mobile network operators deploy edge cooling for 5G infrastructure and central offices. CelcomDigi and Maxis drive demand for modular precision air conditioning across Peninsular Malaysia.
- Financial Institutions:Banks and insurers in Kuala Lumpur prioritize Tier-III reliability for trading platforms and core banking systems. Cooling procurement synchronizes with BNM risk management guidelines for operational resilience.
- Enterprises:Manufacturing and logistics firms operate smaller server rooms with CRAC-dependent architectures. Johor's industrial zones generate replacement demand as legacy equipment reaches end-of-life.
Cloud service providers command specification authority; telecommunications delivers volume scale.
Product Type:
Equipment selection tracks facility vintage, with newer installations favoring modular architectures over central plant designs.
- CRAH Units:Computer room air handlers integrate with chilled water loops in large-scale facilities. Variable-speed fan arrays and coil configurations adapt to Malaysia's tropical humidity loads.
- CRAC Units:Self-contained direct expansion systems serve legacy raised-floor environments. Replacement cycles in Penang and Kuala Lumpur sustain aftermarket revenue for compressor and refrigerant components.
- Cooling Towers:Open-cell and closed-cell configurations reject heat for central plant architectures. Iskandar Malaysia deployments specify corrosion-resistant materials for coastal humidity exposure.
- Air Handlers:Custom-built units serve hyperscale halls with specific airflow and filtration requirements. Cyberjaya facilities demand low-velocity designs to minimize acoustic interference with adjacent operations.
CRAH units dominate new construction; CRAH and liquid cooling hybrids gain share fastest.
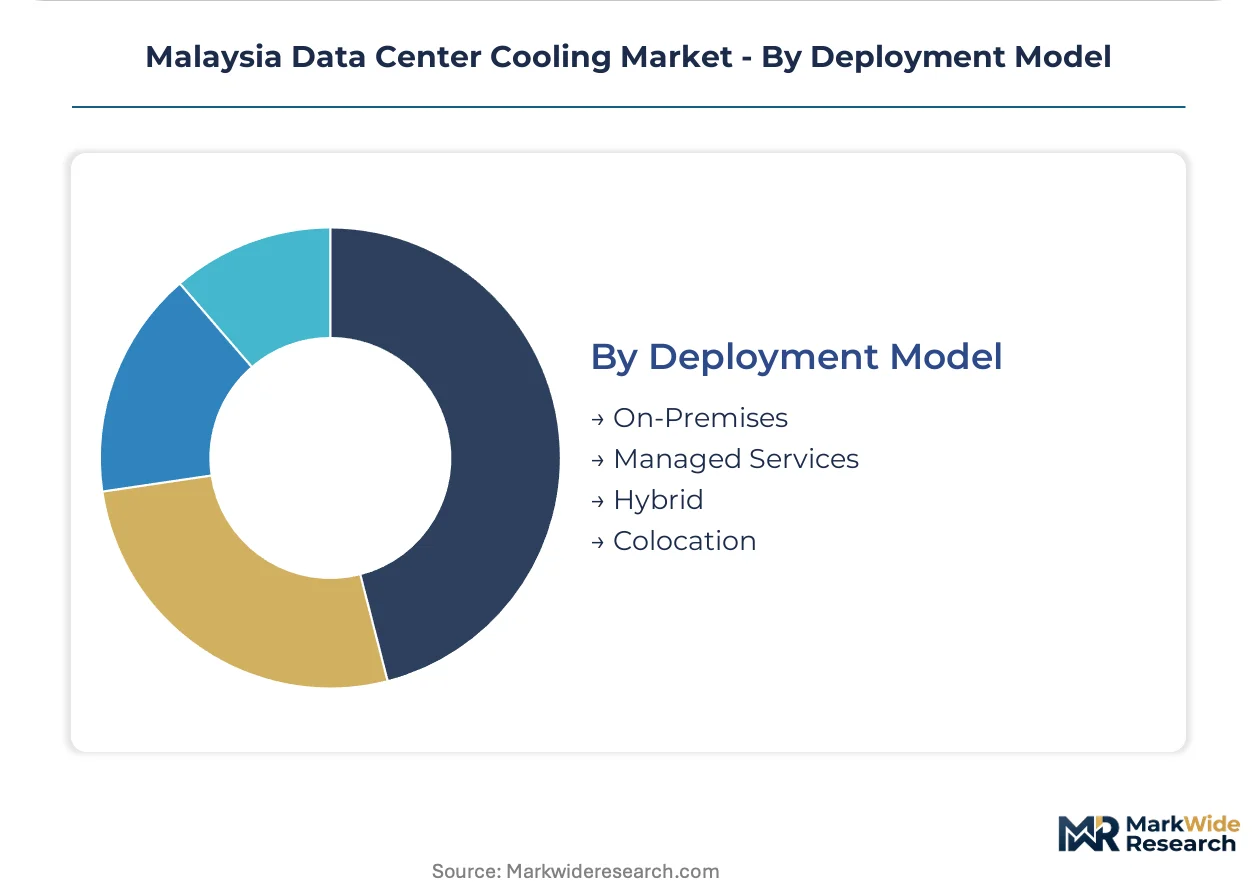
Deployment Model:
Facility operating models determine cooling capital allocation and operational responsibility structures.
- Colocation:Third-party operators provision cooling as a metered utility. Klang Valley providers compete on Power Usage Effectiveness ratios certified under the Green Building Index.
- On-Premises:Enterprise-owned facilities retain full capital burden for cooling infrastructure. Financial institutions in Kuala Lumpur maintain these models for data sovereignty compliance.
- Hybrid:Split workloads between owned and leased capacity create mixed cooling procurement. Enterprises deploy edge cooling on-premises while bursting to colocation for peak loads.
- Managed Services:Outsourced operations transfer cooling maintenance to specialist contractors. Scarcity of direct liquid cooling technicians constrains this model's expansion in high-density segments.
Colocation captures the majority of new cooling capacity; hybrid deployments show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore's data center construction moratorium is redirecting capacity investment flows into Johor's Iskandar Malaysia zone, with cross-border fiber links and power interconnections tightening integration between the two markets.
Selangor
Hyperscale operators anchor cooling procurement in Cyberjaya and the Klang Valley corridor. The Green Building Index mandates minimum energy performance thresholds for mechanical systems in new commercial buildings. Cyberjaya facilities demand low-velocity air handler designs to minimize acoustic interference with adjacent operations.
Johor
Cloud service providers compress deployment timelines for Tier-III and Tier-IV facilities across Iskandar Puteri and Nusajaya. The Sustainable Energy Development Authority's building energy efficiency codes offer accelerated depreciation for high-efficiency cooling equipment. Meta and Microsoft direct-award contracts are consolidating procurement under master service agreements in this zone.
Kuala Lumpur
Financial institutions prioritize Tier-III reliability specifications for trading platforms and core banking systems. Bank Negara Malaysia risk management guidelines for operational resilience shape cooling procurement cycles. Legacy enterprise facilities in the city center face retrofit complexity from 1990s-era central plant architectures.
Penang
Manufacturing and logistics firms generate replacement demand as legacy CRAC-dependent equipment reaches end-of-life. The Department of Standards Malaysia enforces MS 1525 compliance for building energy efficiency. Industrial zones sustain aftermarket revenue for compressor and refrigerant components in smaller enterprise server rooms.
Sabah and Sarawak
Kota Kinabalu and Kuching remain undersupplied relative to West Malaysia demand density. The national renewable energy tariff structures reshape total cost-of-ownership calculations for cooling infrastructure investments. First-mover positioning targets disaster recovery and content distribution nodes in these East Malaysia markets.
Malaysia Data Center Cooling Market Competitive Landscape
Listed leaders compete with private specialists across integrated power and thermal system architectures. The vendor base clusters around three tiers: multinational conglomerates with full-stack portfolios, regional specialists in tropical climate adaptations, and component fabricators serving retrofit replacement cycles. Consolidation pressures favor integrated vendors who can synchronize cooling procurement with 18-to-24-month data center construction timelines. Dominant competitive moves include strategic partnerships with hyperscale operators and geographic expansion into the Johor-Selangor corridor.
Among France-based conglomerates, Schneider Electric SE anchors the integrated architecture tier. Vertiv Group Corp represents US-listed specialists in precision environmental control. Huawei Digital Power Technologies Co Ltd exemplifies China-based technology groups leveraging liquid-cooled rack solutions. These three occupy positions across the competitive spectrum from full-stack integration to high-density thermal specialization.
| Leading Market Players |
|---|
| Schneider Electric SE |
| Vertiv Group Corp |
| Johnson Controls Inc |
| Rittal GmbH & Co. KG |
| Carrier Global Corporation |
| Eaton Corporation PLC |
| Huawei Digital Power Technologies Co Ltd |
| Right Power Technology Sdn Bhd |
| GIGA-BYTE Technology Co Ltd |
| Others |
Pricing and Supply Chain Analysis
Dielectric fluid substitution for conventional refrigerants is simultaneously relocating procurement toward chemical specialists in Germany and Japan while compressing margins for legacy chiller manufacturers serving Penang's enterprise retrofit market. This input transition rewards vendors with captive fluid chemistry capabilities and penalizes pure-play mechanical equipment providers.
Pricing Analysis
Next-generation liquid cooling systems command substantial premiums over conventional chilled water architectures, while direct-expansion precision units face price erosion from commoditized compressor supply. Pricing stratifies across Tier-IV certified premium configurations, Tier-III standard reliability tiers, and economy-grade DX units for sub-500 kW loads. Cost compression in the standard tier intensifies as Chinese manufacturers expand magnetic-bearing chiller production. Cloud service providers exhibit lowest price sensitivity due to master service agreement structures, while Johor manufacturing firms drive hardest bargain on replacement CRAH units.
Supply Chain Analysis
Inventory buffers for specialized cooling towers and corrosion-resistant heat exchangers stretch 16 to 20 weeks as Iskandar Malaysia deployment timelines compress. Manufacturing concentrates in China, Germany, and the United States for precision air handlers and control systems. Supply chains draw from copper processing in Chile, rare-earth magnets for high-efficiency motors from China, and specialty steel alloys from Japan. Single-source vulnerability around direct-to-chip cold plates sourced from Taiwanese fabricators poses concentration risk. Distribution runs through integrated power and thermal vendors with direct hyperscale relationships, bypassing traditional MEP distributor networks in the Klang Valley.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acute shortage of technicians certified for dielectric fluid handling and two-phase heat transfer engineering constrains deployment velocity across Johor's AI infrastructure buildouts, creating asymmetric returns for stakeholders who resolve this bottleneck.
For Market Incumbents: Shield installed base relationships in Kuala Lumpur's financial district by embedding predictive maintenance contracts that lock out modular replacement vendors. Accelerate backward integration into dielectric fluid chemistry to capture margin pools escaping to chemical specialists. The Kigali Amendment refrigerant phase-down threatens aftermarket revenue for legacy DX equipment. For New Entrants and Emerging Players: Green Building Index certification fast-tracks for evaporative cooling designs open immediate positioning in Cyberjaya colocation builds seeking Gold ratings. East Malaysia's disaster recovery node gap in Kota Kinabalu offers penetrable white space with limited incumbent presence. Lead with SEDA incentive optimization consulting to differentiate from equipment-only competitors. For Investors and Strategic Acquirers: The market sits at an infrastructure buildout phase that favors thermal-fluid engineering specialists with proven hyperscale referenceability. Long-term viability hinges on liquid cooling capability depth rather than legacy air conditioning scale. Watch for Tenaga Nasional Berhad substation queue clearance as the signal that cooling demand will outstrip power-constrained supply.| Strategic Initiative | Industry Significance |
|---|---|
| Direct Liquid Cooling Partnership | Secures hyperscale qualification with Meta and Microsoft in Iskandar Puteri. |
| SEDA Incentive Structuring Service | Differentiates colocation operators competing on Power Usage Effectiveness certification. |
| Dielectric Fluid Chemistry Acquisition | Captures margin pools migrating from mechanical equipment to thermal-fluid engineering. |
| East Malaysia First-Mover Deployment | Establishes disaster recovery positioning in Kota Kinabalu ahead of incumbent expansion. |
| GBI Gold Pre-Certification Program | Accelerates Cyberjaya facility completion timelines by 8 to 12 weeks. |
Research Methodology
A spread of perspectives from data center engineering directors, MEP procurement leads at colocation operators, thermal-fluid specialists, and SEDA Malaysia compliance officers converged on the working assumptions. Primary fieldwork combined structured interviews with facility operators in Cyberjaya and Johor with secondary validation through Department of Standards Malaysia MS 1525 documentation, Green Building Index certification databases, Tenaga Nasional Berhad interconnection queue records, and hyperscaler capex disclosures. Bottom-up equipment shipment tracking triangulated against top-down cooling capacity buildout estimates.
Segmentation dimensions modeled span cooling technology type, end-user archetype, product category, and deployment model across the projection horizon. CAGRs derive from equipment procurement cycle analysis synchronized with data center construction timelines. Forecast inputs incorporate wet-bulb temperature distributions for evaporative cooling efficiency modeling and GPU cluster density trajectories for liquid cooling penetration assumptions.
Decision-makers should treat outputs as directional under base assumptions of sustained AI training workload expansion and stable SEDA incentive structures; material deviation in refrigerant regulation timelines or grid interconnection clearance rates would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Cooling
Data Center Liquid Immersion Cooling Market
Data Center Cooling
Japan Data Center Cooling Market
Data Center Cooling
Italy Data Center Cooling Market
Data Center Cooling
Brazil Data Center Cooling Market
Data Center Cooling
Saudi Arabia Data Center Cooling Market
Data Center Cooling
Uk Data Center Cooling Market
Data Center Cooling
United Arab Emirates Data Center Cooling Market
Data Center Cooling
Philippines Data Center Cooling Market
Data Center Cooling
Canada Data Center Cooling Market
Data Center Cooling
New Zealand Data Center Cooling Market
Data Center Cooling
Nigeria Data Center Cooling Market
Data Center Cooling
North America Data Center Cooling Market
Data Center Cooling
Austria Data Center Cooling Market
Data Center Cooling
United States Data Center Cooling Market
Data Center Cooling
Chile Data Center Cooling Market
Data Center Cooling
Europe District Cooling Market