
 Canada Data Center Cooling Market | 2026-2036
Canada Data Center Cooling Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Data Center Cooling Market Insights
Canadian data center infrastructure deployment is decoupling from legacy cooling architectures as power densities climb past twenty kilowatts per rack. Vertiv Holdings Co. leverages its local manufacturing footprint to anchor projects in Ontario and British Columbia. Schneider Electric SE sustains technology leadership through integrated microgrid and thermal management platforms. Johnson Controls International plc competes on chiller efficiency ratings and building automation integration.
Canada Data Center Cooling encompasses engineered thermal management systems—precision air handlers, liquid coolant distribution units, and evaporative heat rejection equipment—designed to maintain server inlet temperatures between eighteen and twenty-seven degrees Celsius while minimizing energy use effectiveness ratios. These systems protect computational uptime for cloud, colocation, and enterprise workloads across Canada's northern climate zones. Liquid cooling systems represent the fastest-expanding segment as GPU-intensive AI training loads overwhelm traditional air handlers. Colocation providers occupy the most concentrated margin pool, locking in long-term service contracts with cooling infrastructure bundled into lease structures.
Health Canada and Environment and Climate Change Canada shape equipment efficiency standards and refrigerant phase-down timelines, while provincial regulators in Quebec and Ontario enforce carbon intensity thresholds for grid-connected facilities. The Canadian Standards Association certifies electrical and mechanical safety compliance, creating a layered approval pathway for imported cooling equipment. Stakeholders must weigh liquid cooling capital commitments against the operational flexibility of modular retrofit designs as workload densities continue climbing.
Market Dynamics
Power density thresholds above twenty kilowatts per rack are forcing Canadian operators to abandon air-cooled architectures in favor of liquid cooling systems, compressing deployment timelines and capital planning cycles across Ontario and Quebec.
Growth Catalysts
- Provincial carbon mandates:Quebec's hydroelectric grid and Ontario's carbon intensity thresholds create competitive pressure for facilities to adopt energy-efficient thermal management, accelerating liquid cooling procurement.
- AI training clusters:GPU-intensive workloads in Toronto's digital corridor and Montreal's AI research hubs generate sustained demand for direct-to-chip cooling systems that traditional precision air handlers cannot satisfy.
- Hyperscale facility construction:Cloud service providers are expanding multi-hundred-megawatt campuses across the Greater Toronto Area and Beauharnois, locking in long-term cooling infrastructure commitments.
Market Restraints
- Refrigerant phase-down timelines:Environment and Climate Change Canada's restrictions on high-global-warming-potential refrigerants compress retrofit windows for existing chiller fleets, stranding some air-cooled assets.
- Copper and aluminum price volatility:Liquid cooling distribution networks rely on commodity-intensive heat exchangers and piping, exposing project economics to raw material cost swings.
- Specialized contractor scarcity:Qualified technicians for dielectric fluid installation and leak detection concentrate in southern Ontario, creating installation bottlenecks for remote Quebec deployments.
Strategic Opportunities
- Western Canada expansion:British Columbia's clean electricity profile and Vancouver's subsea cable connectivity position the province as an underpenetrated destination for sustainable data center cooling.
- Heat reuse integration:District heating partnerships with municipal utilities in Toronto and Montreal allow operators to monetize waste heat, transforming thermal management from cost center to revenue stream.
- Modular retrofit architectures:Hybrid cooling designs that preserve air-handling infrastructure while adding liquid loops enable colocation providers to serve mixed-density client bases without full facility overhauls.
Industry Challenges
- Fluid chemistry certification:Canadian Standards Association approval pathways for new dielectric coolants extend product launch timelines, delaying deployment of next-generation thermal transfer fluids.
- Legacy facility constraints:Raised-floor data centers built for sub-ten-kilowatt racks lack structural load capacity and clearance for liquid cooling manifolds, forcing expensive slab reinforcement or greenfield construction.
- Cross-provincial regulatory fragmentation:Divergent electrical safety interpretations between Ontario's Electrical Safety Authority and Quebec's Régie du bâtiment du Québec complicate multi-site operator standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Data Center Cooling Market |
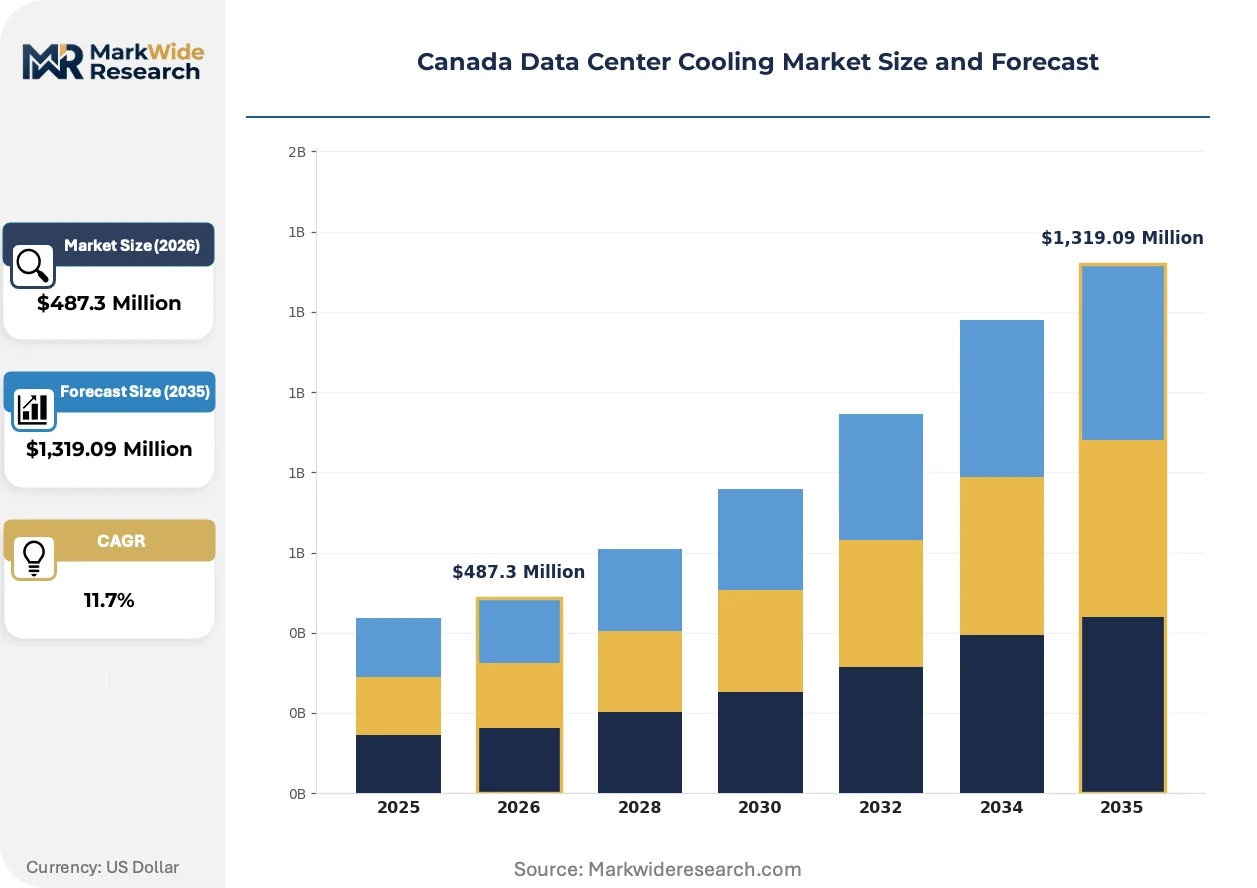
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,319.09 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Cooling Type: Aired Coolers, Liquid Cooling Systems, Evaporative Cooling, Chilled Beams End User: Cloud Service Providers, Colocation Providers, Enterprises, Government Agencies Technology: Traditional Cooling, Modular Cooling, Smart Cooling, Passive Cooling Installation Type: New Installations, Retrofitting, Upgrades, Maintenance Services |
| Companies Covered | Vertiv Holdings Co., Schneider Electric SE, Johnson Controls International plc, CoolIT Systems Inc., Nortek Air Solutions LLC, STULZ GmbH, Rittal GmbH & Co. KG, Emerson Electric Co., Asetek A/S, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Data Center Cooling Market Trends and Innovations
Liquid cooling architectures are compressing the traditional boundary between facility infrastructure and IT equipment, blurring procurement responsibilities and reshaping vendor relationships across Canadian data center construction.
Direct-to-chip liquid cooling is rewriting thermal management economics for high-density AI clusters. Cold plates attached to GPU and CPU packages capture heat at the source, eliminating the intermediate air loop. Hyperscale operators in Ontario and Quebec are deploying these systems at rack densities exceeding fifty kilowatts, compressing facility footprints and reducing energy use effectiveness ratios below industry benchmarks.
Health Canada's refrigerant management regulations and provincial carbon reporting mandates are accelerating equipment replacement cycles. Facilities must document lifecycle emissions for cooling systems and demonstrate compliance with phasedown schedules for hydrofluorocarbon-based refrigerants. Colocation providers face the steepest compliance burden, as multi-tenant contracts require transparent carbon accounting that legacy chiller fleets cannot support.
Service contract unbundling is fragmenting the traditional integrated procurement model. Enterprise buyers are separating cooling infrastructure from facility leases, negotiating directly with thermal management specialists rather than accepting bundled offerings from real estate operators. This pattern concentrates in Toronto's financial services vertical, where risk management departments demand direct vendor relationships for critical uptime systems.
Canada Data Center Cooling Market Segmentation
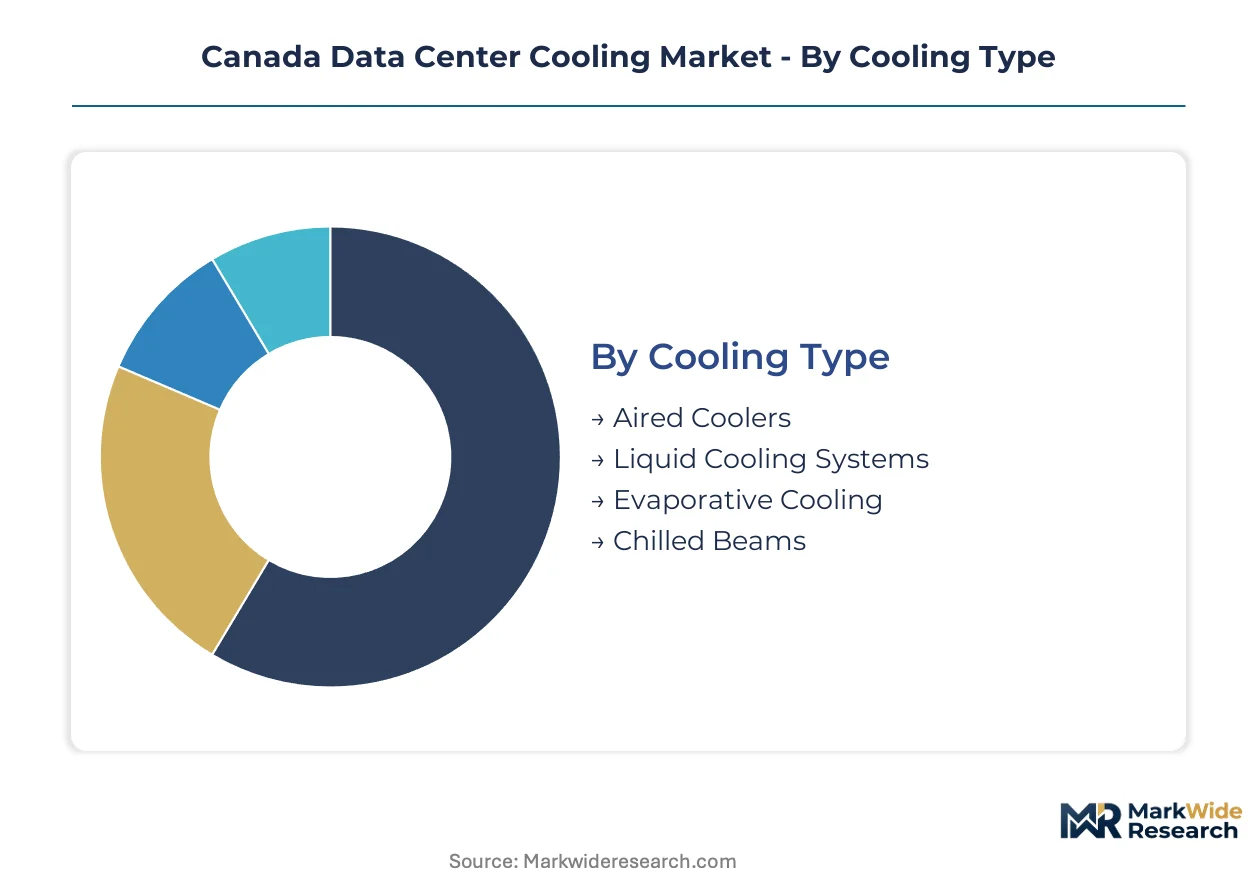
Segmentation reveals how thermal management procurement diverges across Canadian data center operators. Cooling type selection tracks directly to rack power density, while end-user category determines contract structure and capital commitment horizons.
Cooling Type:
Supply concentration for advanced thermal systems clusters in southern Ontario manufacturing corridors and Quebec's industrial zones near Montreal.
- Liquid Cooling Systems:Direct-to-chip and immersion architectures circulate dielectric fluids through cold plates or tanks, capturing heat at the source. Demand concentrates in Toronto's AI training clusters and Montreal's hyperscale campuses where GPU densities exceed fifty kilowatts per rack. Health Canada's refrigerant phase-down timelines accelerate displacement of legacy chiller fleets.
- Aired Coolers:Precision air handlers and computer room air conditioning units maintain server inlet temperatures through conditioned air distribution. Ontario's enterprise colocation facilities and government data centers in Ottawa continue deploying these systems for sub-twenty-kilowatt workloads despite efficiency limitations.
- Evaporative Cooling:Adiabatic cooling towers and swamp coolers leverage low wet-bulb temperatures in Canada's northern climate zones to reject heat without mechanical compression. British Columbia's temperate coastal conditions support deployment in Vancouver's emerging data center cluster.
- Chilled Beams:Passive or active beam systems circulate chilled water through ceiling-mounted heat exchangers, delivering cooling without forced air distribution. Quebec's hydroelectric grid advantage supports these systems in low-density administrative computing environments.
Liquid cooling systems absorb the bulk of installed capacity in new hyperscale construction; evaporative cooling is expanding most quickly in western provinces with favorable climate profiles.
End User:
Customer type determines procurement scale, with cloud operators driving standardization while enterprises prioritize operational flexibility.
- Cloud Service Providers:Hyperscale operators design custom thermal architectures for multi-hundred-megawatt campuses, negotiating directly with cooling system manufacturers rather than through intermediaries. Their procurement volumes shape supplier R&D priorities across Ontario and Quebec.
- Colocation Providers:Multi-tenant facilities bundle cooling infrastructure into lease structures, requiring modular designs that accommodate mixed-density client bases. Toronto's financial services vertical demands transparent carbon accounting that pressures equipment refresh cycles.
- Enterprises:Corporate data centers in Calgary's energy sector and Vancouver's technology vertical pursue hybrid cooling retrofits that preserve existing air-handling investments while adding liquid loops for AI workloads.
- Government Agencies:Federal and provincial facilities in Ottawa and Quebec City prioritize reliability certifications and domestic content requirements, extending procurement timelines but reducing supply chain risk exposure.
Cloud service providers absorb the bulk of installed capacity; colocation providers are climbing the fastest as multi-tenant demand fragments procurement across smaller-scale deployments.
Technology:
Technology maturity curves diverge sharply, with smart systems requiring integration expertise that concentrates in Ontario's contractor base.
- Smart Cooling:Machine learning algorithms optimize chiller staging, fan speeds, and coolant flows based on real-time workload telemetry. These systems gain traction in Toronto's financial services data centers where uptime guarantees justify premium automation investments.
- Modular Cooling:Factory-integrated cooling units deploy as standardized blocks, compressing installation timelines for rapid capacity expansion. Quebec's Beauharnois cluster leverages these systems for phased campus buildouts.
- Traditional Cooling:Fixed-capacity chillers and precision air handlers dominate legacy facility maintenance and budget-constrained government deployments.
- Passive Cooling:Free cooling and thermal mass systems exploit Canada's seasonal temperature variation, with Calgary and Edmonton operators maximizing economizer hours.
Traditional cooling absorbs the bulk of installed capacity; smart cooling is gaining share fastest as AI workload unpredictability demands dynamic thermal response.
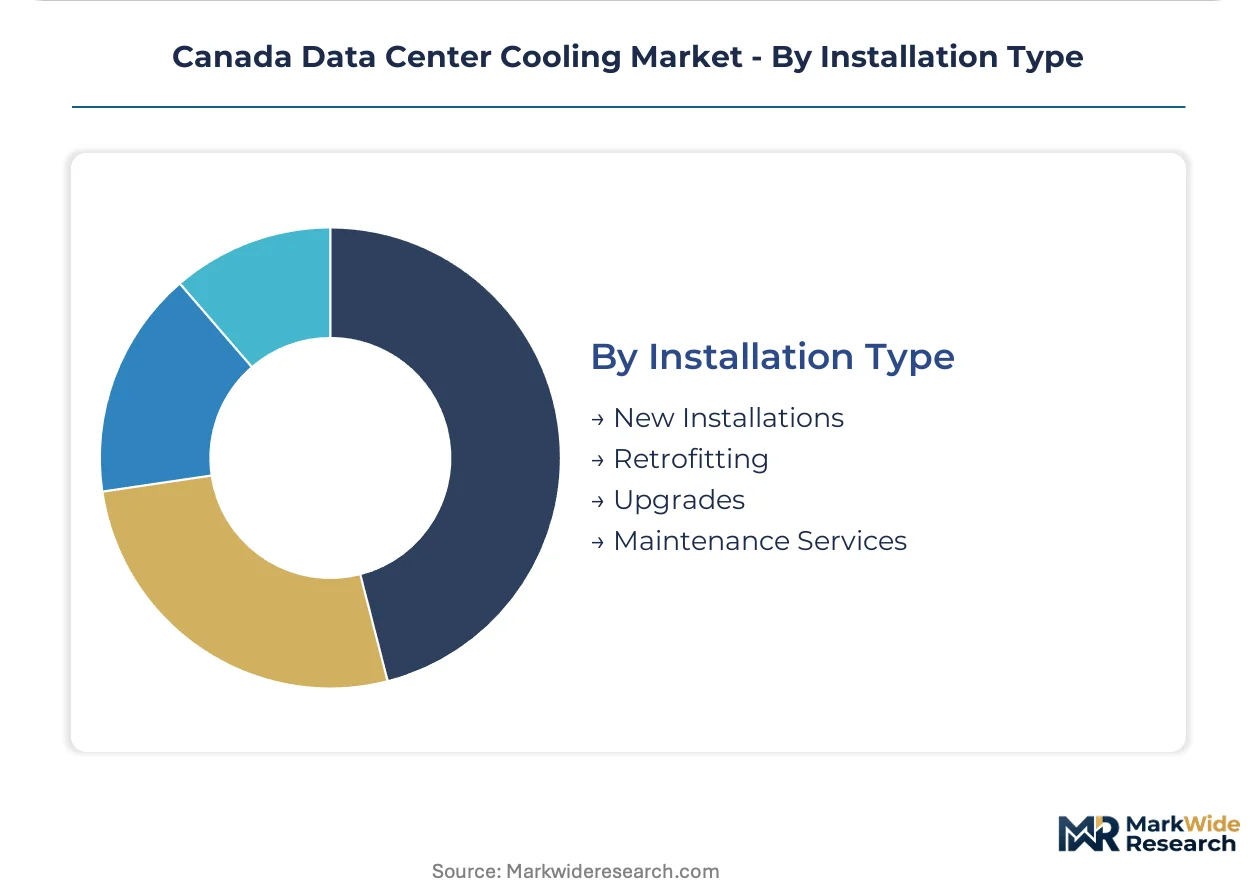
Installation Type:
Project type distribution reflects the tension between greenfield hyperscale construction and legacy facility constraints in established markets.
- New Installations:Greenfield data centers in Greater Toronto Area suburbs and Quebec's Montérégie region specify liquid cooling from initial design, avoiding retrofit complexity. These projects lock in twenty-year infrastructure commitments.
- Retrofitting:Raised-floor facilities built for sub-ten-kilowatt racks require structural reinforcement and clearance modifications to accommodate liquid cooling manifolds. Vancouver's aging enterprise data centers face slab load capacity constraints.
- Upgrades:Chiller replacements and controls modernization address Health Canada refrigerant phase-down deadlines while extending facility lifespans.
- Maintenance Services:Predictive maintenance contracts and fluid chemistry monitoring sustain dielectric cooling system performance, with technician scarcity in remote Quebec markets inflating service premiums.
New installations absorb the bulk of installed capacity; retrofitting is expanding most quickly as AI density requirements overwhelm legacy air-cooled architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Quebec's hydroelectric reservoirs and Ontario's nuclear baseload anchor Canadian data center cooling infrastructure. Provincial electricity profiles dictate thermal technology selection across the country's four dominant deployment zones.
Ontario
Toronto's digital corridor generates concentrated demand for liquid cooling systems serving GPU-intensive AI training clusters. The Independent Electricity System Operator enforces carbon intensity thresholds that accelerate displacement of legacy chiller fleets. Greater Toronto Area suburbs host multi-hundred-megawatt hyperscale campuses specifying direct-to-chip cooling from initial design.
Quebec
Montreal's Beauharnois cluster leverages hydroelectric grid advantages to attract carbon-conscious cloud operators. The Régie du bâtiment du Québec imposes electrical safety interpretations that complicate standardization for multi-site operators. The Montérégie region hosts phased campus buildouts utilizing modular cooling blocks for rapid capacity expansion.
British Columbia
Vancouver's subsea cable connectivity positions the province for sustainable data center cooling expansion. Clean electricity profiles from BC Hydro support evaporative cooling deployment in temperate coastal conditions. Aging enterprise facilities in Vancouver face slab load constraints blocking liquid cooling retrofits.
Alberta
Calgary's energy sector maintains enterprise data centers pursuing hybrid cooling architectures for mixed-density workloads. Provincial regulators emphasize reliability certifications for critical infrastructure serving oil and gas computational demands. Edmonton operators maximize economizer hours through passive free cooling systems exploiting seasonal temperature variation.
Canada Data Center Cooling Market Competitive Landscape
Global majors compete with regional champions across thermal technology integration, creating a tiered structure where scale-driven hyperscale specialists face off against modular retrofit specialists. The vendor base splits between consolidated integrated platform providers and focused component specialists. Three archetypes dominate: full-stack infrastructure integrators, precision cooling component fabricators, and dielectric fluid distribution specialists. Capacity expansion in Ontario manufacturing corridors and strategic partnerships for heat reuse integration represent the dominant competitive moves.
Within the integrated infrastructure tier, Vertiv Holdings Co. and Schneider Electric SE occupy positions exemplifying full-stack thermal and power integration. Johnson Controls International plc anchors the building automation convergence archetype, representing chiller efficiency optimization. Among liquid cooling specialists, CoolIT Systems Inc. exemplifies the direct-to-chip component fabricator model serving density-constrained AI clusters.
| Leading Market Players |
|---|
| Vertiv Holdings Co. |
| Schneider Electric SE |
| Johnson Controls International plc |
| CoolIT Systems Inc. |
| Nortek Air Solutions LLC |
| STULZ GmbH |
| Rittal GmbH & Co. KG |
| Emerson Electric Co. |
| Asetek A/S |
| Others |
Pricing and Supply Chain Analysis
Health Canada's refrigerant phase-down mandates gate qualified supplier access and premium-tier pricing power, compressing procurement windows for facilities seeking compliant cooling systems while elevating certified equipment premiums across Ontario and Quebec deployment corridors.
Pricing Analysis
Service contract unbundling separates cooling infrastructure warranties from facility leases, forcing direct vendor negotiations in Toronto's financial services vertical. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and fluid chemistry compliance, with Health Canada-certified dielectric coolants commanding substantial premiums. Cost compression in standard-tier air-cooled systems intensifies because of stranded asset risk from refrigerant restrictions. Cloud service providers exhibit lowest price sensitivity due to long-term infrastructure lock-ins, while government agencies face acute budget constraints extending procurement cycles.
Supply Chain Analysis
Warehouse-distribution layers concentrate in southern Ontario manufacturing corridors and Quebec's industrial zones near Montreal, creating hub-and-spoke patterns serving western provinces. Supply draws from USA, Germany, and China for precision pumps, heat exchangers, and dielectric fluids. Single-source vulnerability concentrates in specialized dielectric fluid chemistry from limited CSA-approved suppliers. Distribution runs through direct manufacturer relationships for hyperscale operators and regional HVAC distributors serving retrofit markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
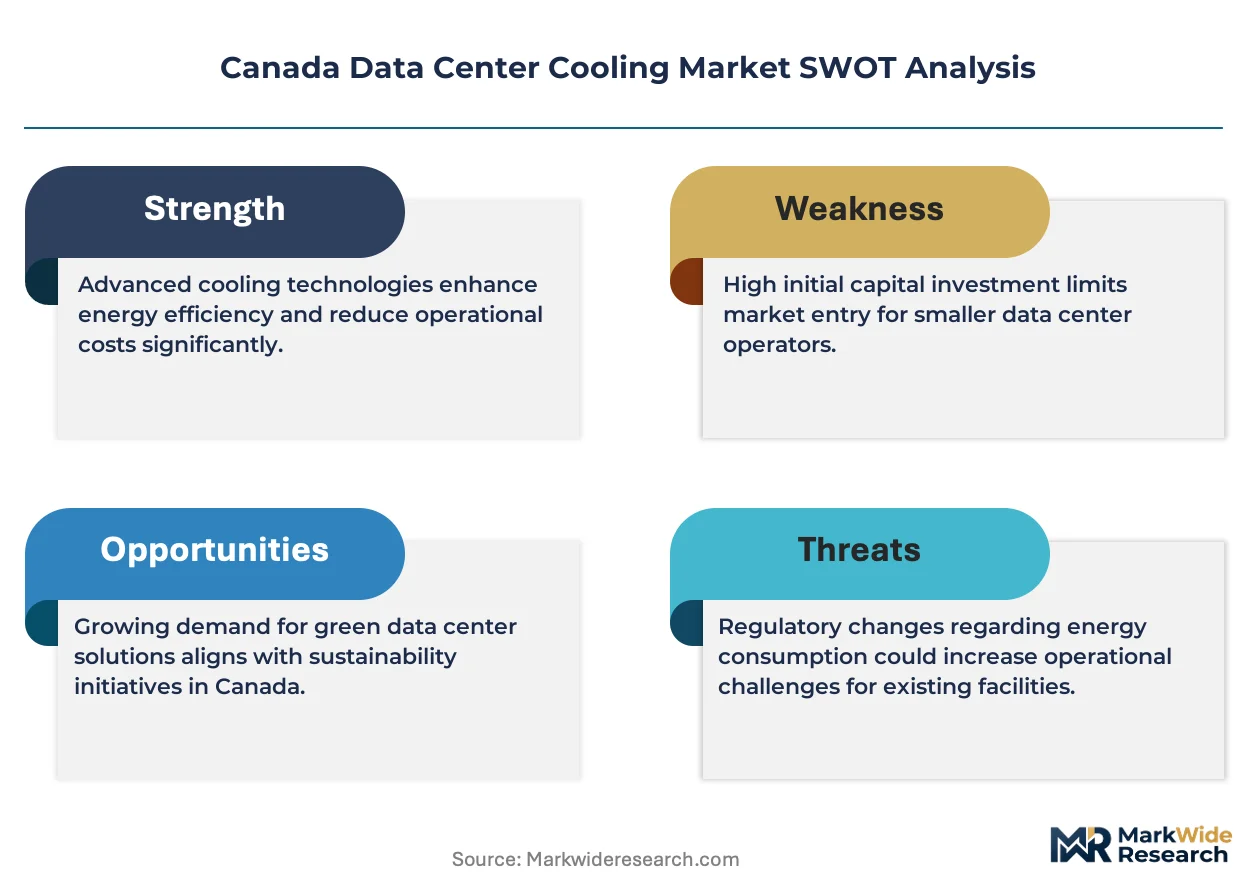
This market operates as a vertical-integration race where upstream control over dielectric fluid supply and downstream heat reuse partnerships determine margin capture across Ontario and Quebec deployment zones.
For Market Incumbents: Anticipate displacement pressure from modular cooling specialists by securing exclusive fluid chemistry partnerships with CSA-certified suppliers. Backward integration into dielectric coolant blending capacity anchors margin control as refrigerant phase-downs accelerate equipment refresh cycles. Vertiv Holdings Co. and Schneider Electric SE exemplify platform consolidation strategies that colocation providers increasingly favor for bundled thermal and power solutions.
For New Entrants and Emerging Players: Western Canada's enterprise retrofit segment offers the most penetrable white-space target, with Vancouver's aging facilities facing slab load constraints blocking liquid cooling adoption. Hybrid cooling architectures that preserve air-handling infrastructure while adding liquid loops address this constraint without full facility overhauls. Partnership positioning with British Columbia's municipal utilities for district heating integration provides differentiated entry against established Ontario-Quebec incumbents.
For Investors and Strategic Acquirers: Multi-hundred-megawatt hyperscale campus announcements in the Greater Toronto Area are the leading indicator that liquid cooling procurement volumes are approaching inflection thresholds. Long-term viability rests on supplier scale advantages in direct-to-chip component fabrication and fluid chemistry certification expertise. Acquisition targets should demonstrate CSA approval pathways for next-generation dielectric coolants and established contractor relationships in southern Ontario's technician-concentrated markets.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dielectric Fluid Supply | Captures margin from CSA-certified coolant chemistry bottlenecks affecting Quebec deployment timelines. |
| Heat Reuse Partnership with Municipal Utilities | Transforms thermal management from cost center to revenue stream in Toronto's district heating network. |
| Modular Cooling Block Manufacturing Scale-Up | Compresses installation timelines for phased Beauharnois campus expansions attracting carbon-conscious operators. |
| Direct-to-Chip Cold Plate Certification Investment | Secures Health Canada compliance pathways ahead of GPU density thresholds exceeding fifty kilowatts per rack. |
| Western Canada Distribution Hub Establishment | Reduces logistics exposure for British Columbia's emerging sustainable data center cooling demand. |
Research Methodology
Document review covered equipment manufacturer technical specifications, Health Canada regulatory filings, provincial electricity system operator reports, and hyperscale facility development announcements, complemented by interviews with data center engineering directors, thermal management procurement leads at colocation providers, facility construction contractors, and dielectric fluid chemistry specialists. Secondary validation drew from Environment and Climate Change Canada emissions databases, Canadian Standards Association certification registries, and utility interconnection disclosure filings. Bottom-up installation and capacity estimates triangulated against top-down provincial electricity demand projections for data center load growth.
Installed capacity and revenue outputs reflect integrated modeling across cooling type, end-user category, technology tier, and installation format segmentation throughout the forecast period. The analytical framework incorporated rack power density trajectories, refrigerant phase-down compliance deadlines, and provincial carbon intensity threshold enforcement patterns. CAGRs were derived from facility construction pipeline tracking and equipment procurement cycle analysis, with sensitivity testing around AI workload adoption curves and hyperscale campus completion schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to copper and aluminum commodity volatility, CSA approval timeline extensions for novel dielectric fluids, and cross-provincial regulatory interpretation divergences between Ontario's Electrical Safety Authority and Quebec's Régie du bâtiment du Québec. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Cooling
Saudi Arabia Study of Data Center Water Consumption Market
Data Center Cooling
Singapore Data Center Cooling Market
Data Center Cooling
India Data Center Cooling Market
Data Center Cooling
Netherlands Data Center Cooling Market
Data Center Cooling
Australia Data Center Cooling Market
Data Center Cooling
Indonesia Data Center Cooling Market
Data Center Cooling
South Korea Data Center Cooling Market
Data Center Cooling
Germany Data Center Cooling Market
Data Center Cooling
Data Center Liquid Cooling Market
Data Center Cooling
Latin America Data Center Cooling Market
Data Center Cooling
Chile Data Center Cooling Market
Data Center Cooling
United States Data Center Cooling Market
Data Center Cooling
Hong Kong Data Center Cooling Market
Data Center Cooling
Europe District Cooling Market
Data Center Cooling
CPU Water Cooling Radiator Market
Data Center Cooling
High-purity Data Center Thermal Management Fluids Market